
 Industrial Automation Spares Market | 2026-2036
Industrial Automation Spares Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Automation Spares Market Intelligence
The European Union's Machinery Regulation is broadening the compliance requirements for component manufacturers, impacting market entry and product design. Siemens leverages its extensive portfolio of PLCs and drives to address these complex standards across its industrial customer base. Concurrently, Rockwell Automation sustains its strong position in the North American market by specializing in integrated control systems for sectors like food and beverage and automotive. ABB competes with a comprehensive offering that combines robotics, electrification, and automation spares, targeting large-scale industrial projects.
Industrial automation spares are the individual, replaceable components used for the maintenance, repair, and operational continuity of automated systems. These parts, from sensors with microsecond response times to high-torque servo drives, ensure minimal production downtime. Their primary purpose is to restore or maintain the original performance and safety specifications of machinery. Controllers and drives constitute a large share of market value, while the sensor segment represents the fastest-growing category, fueled by data collection for predictive maintenance algorithms in automotive and aerospace applications.
Compliance with regional and international standards is non-negotiable for market access. The CE marking in Europe, GB standards in China, and specific OSHA safety requirements in the United States all dictate component specifications. These regulatory frameworks directly influence material selection, testing protocols, and documentation for all spares. Success for suppliers depends on managing a complex portfolio of certified products and navigating the shift from transactional part sales to more integrated maintenance and support service models.
Market Dynamics
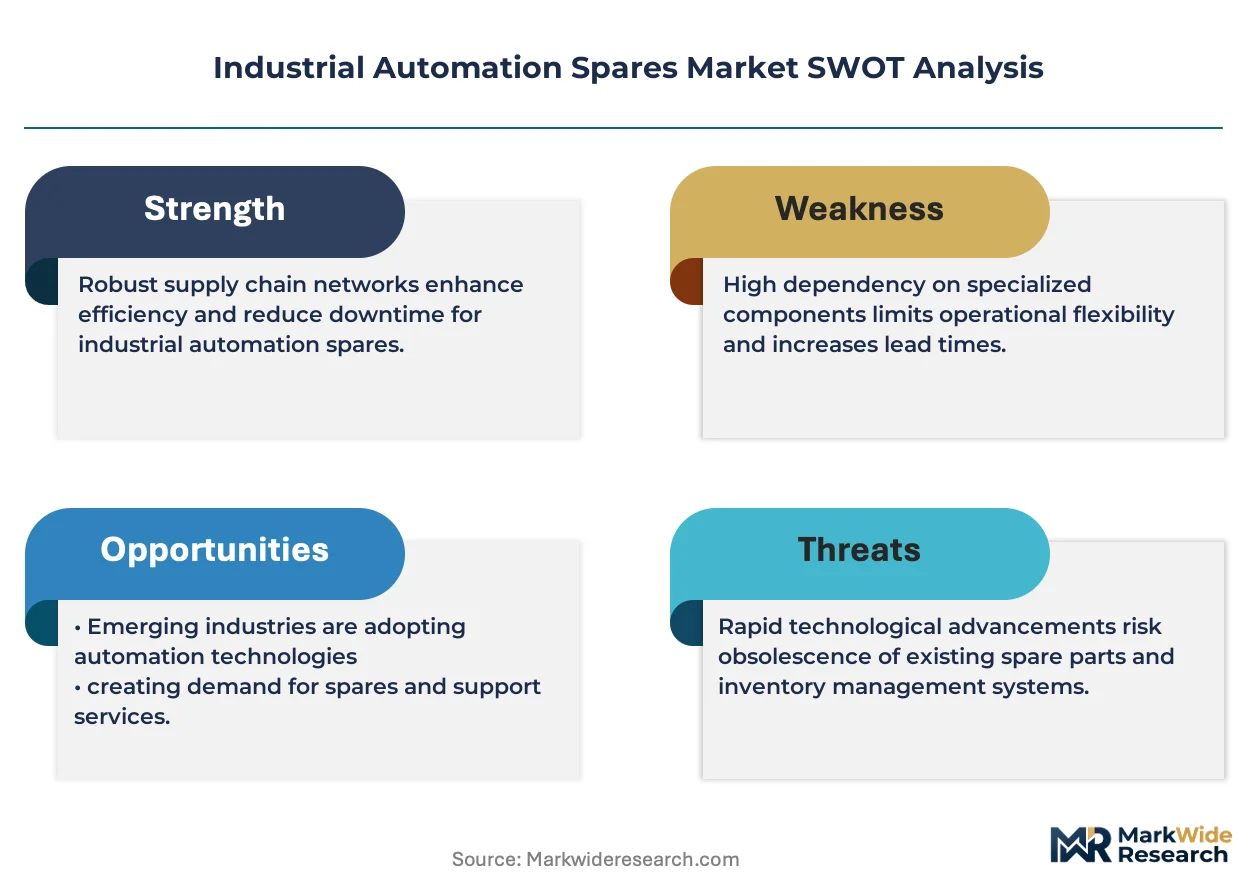
The industrial automation spares market is shaped by the fundamental tension between the need for maximum operational uptime in manufacturing and the increasing complexity of regulatory compliance. Stricter safety and cybersecurity rules, such as the EU's Machinery Regulation, dictate component design, forcing a continuous cycle of product redevelopment and certification.
Growth Catalysts
- Predictive Maintenance Adoption:The integration of IIoT sensors and analytics platforms in automotive and aerospace manufacturing creates persistent demand for smart components that can provide data for uptime optimization algorithms.
- Regulatory Mandates:Tightening functional safety and cybersecurity standards, including the CE marking framework in Europe and specific OSHA requirements in the US, compel manufacturers to upgrade to compliant spares.
- Advanced Manufacturing in Asia:Rapid automation within China's industrial sector and the development of smart factories across Southeast Asia generate significant new demand for a full spectrum of automation spares.
Market Restraints
- Semiconductor Supply Volatility:The reliance on a concentrated number of semiconductor foundries for microcontrollers and processors creates a structural bottleneck, leading to long lead times and price instability for critical electronic spares.
- Legacy System Integration:Integrating modern, networked spares with older, proprietary automation systems on factory floors presents significant technical hurdles, often requiring costly custom engineering and extensive validation.
- Multi-Regional Certification Costs:The expense and time required to certify a single component against divergent regional standards, such as Europe's CE marking and China's GB standards, act as a barrier to entry for smaller suppliers.
Strategic Opportunities
- Service-Based Models:A transition from transactional part sales to subscription-based services, offering parts-as-a-service (PaaS) and integrated predictive maintenance support, provides a recurring revenue opportunity.
- AI-Enhanced Diagnostics:Developing spares with embedded AI capabilities for self-diagnosis and failure prediction offers a path to higher-margin products that reduce troubleshooting time for end-users.
- Circular Economy Initiatives:Establishing certified remanufacturing and refurbishment programs for high-value components like drives and robotic arms can capture value and appeal to customers with sustainability mandates.
Industry Challenges
- Cybersecurity Skill Gaps:A shortage of maintenance technicians with dual expertise in both mechanical systems and the network security protocols required for modern IIoT-enabled spares complicates deployment and support.
- Component Traceability:Implementing robust traceability systems to track components from manufacturing through their operational lifecycle is a complex logistical challenge, yet essential for meeting regulatory demands.
- Standardization of Communication Protocols:The lack of a universal communication standard across different automation vendors complicates the interoperability of spares, forcing customers into single-vendor ecosystems or expensive integration projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Automation Spares Market |
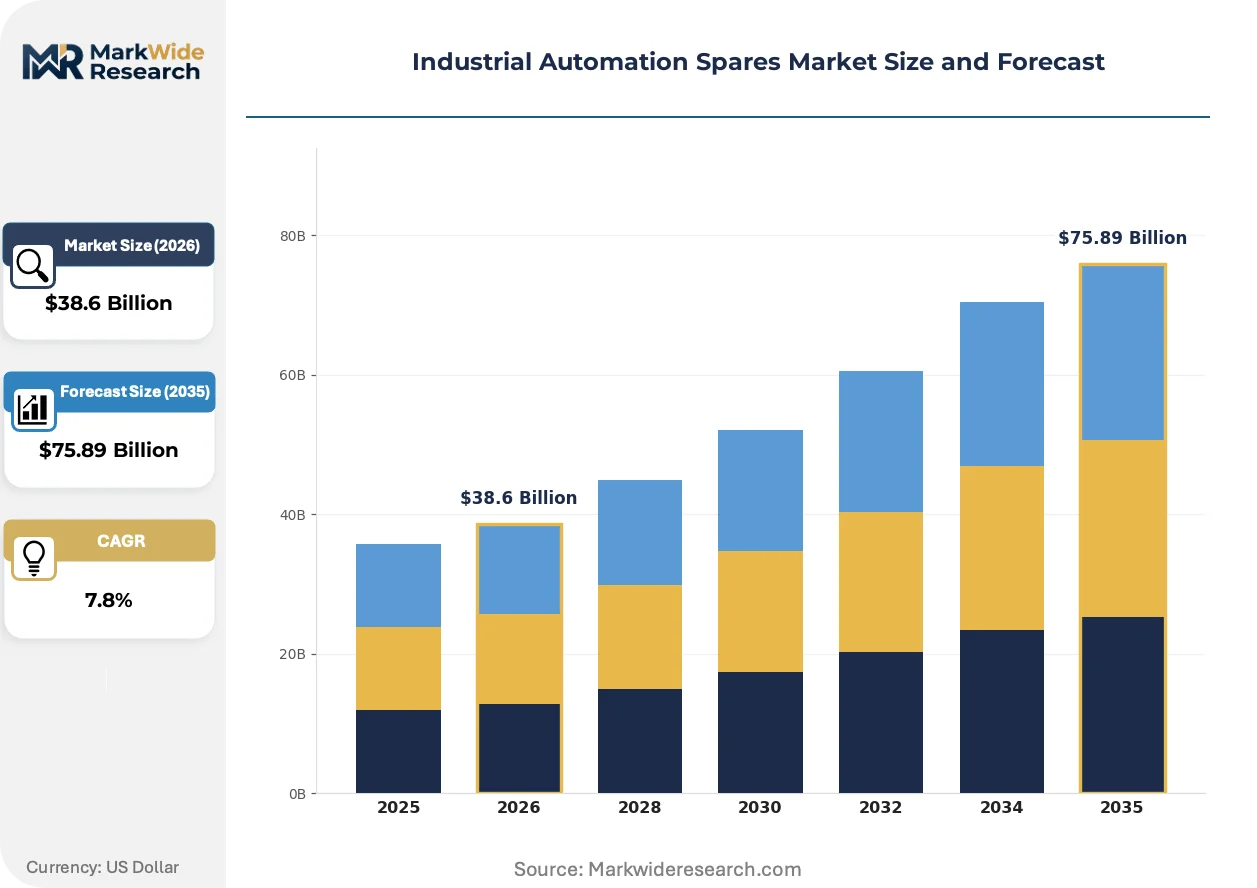
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $75.89 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensors, Actuators, Controllers, Drives Technology: PLC, SCADA, DCS, HMI End User: Manufacturing, Oil & Gas, Automotive, Aerospace Service Type: Maintenance, Support, Installation, Consulting |
| Companies Covered | FANUC, Yaskawa, Siemens, Honeywell, Schneider Electric, Rockwell Automation, Emerson Automation Solutions, Mitsubishi Electric, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Automation Spares Market Strategic Shifts & Innovations
A fundamental shift from reactive replacement to proactive, data-driven maintenance is redefining the value proposition in the industrial automation spares market. This evolution transforms components from passive parts into active participants in system health monitoring, driven by embedded intelligence and connectivity.
Advanced servo drives with high-torque density are a key product evolution. These components provide precise, high-speed motion control essential for modern robotics and multi-axis CNC machinery. Adoption is accelerating in the automotive and electronics assembly sectors, where speed and accuracy directly impact production throughput. The technology is electrifying legacy motion systems, replacing less efficient and less precise hydraulic and pneumatic actuators in heavy industrial applications.
The European Union's updated Machinery Regulation introduces stringent cybersecurity requirements for industrial components. This policy forces manufacturers to build security into the design of parts like PLCs and network gateways, treating them as potential entry points for cyber threats. Suppliers to critical infrastructure and advanced manufacturing are most affected, now needing to provide verifiable security documentation and software integrity checks to maintain market access in Europe.
Customer buying behavior is moving away from simple transactional purchases toward more holistic asset management partnerships. This disrupts the traditional model where end-users or distributors hold large physical inventories of spares. The trend is most prominent in capital-intensive industries like semiconductor manufacturing, where factories engage suppliers in service-level agreements that guarantee uptime and parts availability for a fixed fee, shifting the inventory risk to the component vendor.
Industrial Automation Spares Market Segmentation
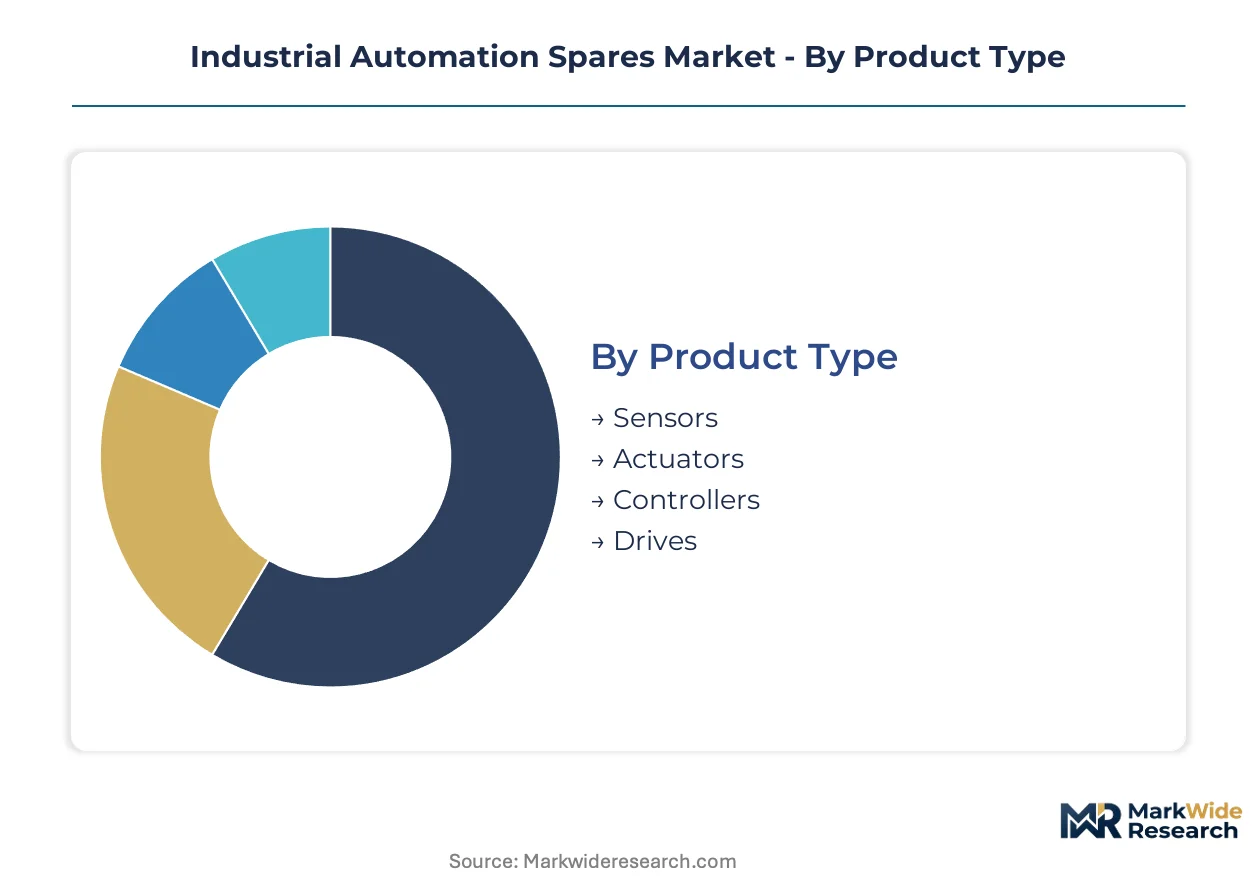
Understanding the segmentation within the industrial automation spares market reveals distinct demand patterns and supplier specialization. Component lifecycles and technological advancements drive purchasing decisions for manufacturers. Analyzing these segments helps identify where investments in product development and service infrastructure yield the highest returns.
Product Type:
The imperative for continuous operational uptime frequently triggers the replacement cycle for specific product types within industrial automation.
- Controllers:These are the programmable logic controllers (PLCs) and distributed control systems (DCS) that execute automation sequences. Demand for advanced controllers is concentrating in Germany's automotive plants, driven by the need for complex, high-speed process orchestration and adherence to updated EU Machinery Regulation standards.
- Sensors:Devices that detect physical parameters like temperature, pressure, and position, often with microsecond response times. The aerospace sector in the United States requires highly precise, data-rich sensors for predictive maintenance algorithms, ensuring flight-critical system reliability and reducing unscheduled downtime.
- Actuators:Components that convert energy into mechanical motion, such as pneumatic, hydraulic, or electric servo drives. These are critical for robotic arms and precision machinery.
- Drives:Electronic devices that control the speed and torque of electric motors, ranging from variable frequency drives to servo drives. Their performance directly impacts machine efficiency.
Volume placements concentrate in Controllers; the faster expansion belongs to Sensors.
Technology:
Market concentration for specific automation technologies often dictates the spares landscape, influencing procurement strategies and vendor relationships.
- PLC:Programmable Logic Controllers are robust industrial computers that automate specific processes. Siemens maintains a strong position in European manufacturing, supplying PLCs that meet stringent CE marking requirements for functional safety.
- SCADA:Supervisory Control and Data Acquisition systems monitor and control industrial processes remotely. China's rapidly expanding smart factories frequently integrate advanced SCADA spares to manage complex, distributed production lines.
- DCS:Distributed Control Systems manage large, complex, and continuous process industries like chemical plants or power generation. These systems require specialized spares for long operational lifecycles.
- HMI:Human-Machine Interfaces provide graphical user interfaces for operators to interact with machines. Spares for HMIs are critical for maintaining intuitive control and data visualization.
The highest volume of spares moves through PLC channels; SCADA components are gaining share due to increased connectivity.
End User:
Specific application demands from various end-user industries shape the design and availability of industrial automation spares.
- Automotive:This sector requires high-performance spares for robotics, assembly lines, and paint shops, prioritizing uptime and precision. Manufacturers in Michigan frequently upgrade automation spares to maintain competitive production speeds and adapt to new electric vehicle platforms.
- Manufacturing:A broad category encompassing discrete and process manufacturing, requiring a diverse range of spares for general machinery. German industrial firms invest in advanced spares to comply with Industry 4.0 initiatives and maintain high-efficiency production.
- Oil & Gas:This industry demands rugged, explosion-proof, and corrosion-resistant spares for harsh operating environments. Specialized sensors and controllers are essential for safety and regulatory compliance.
- Aerospace:Precision engineering and stringent quality control drive demand for highly reliable and certified spares for automated assembly and testing. Components must often meet specific FAA or EASA standards.
Manufacturing accounts for the largest share of spare parts consumption; the Automotive sector shows the steepest expansion trajectory.
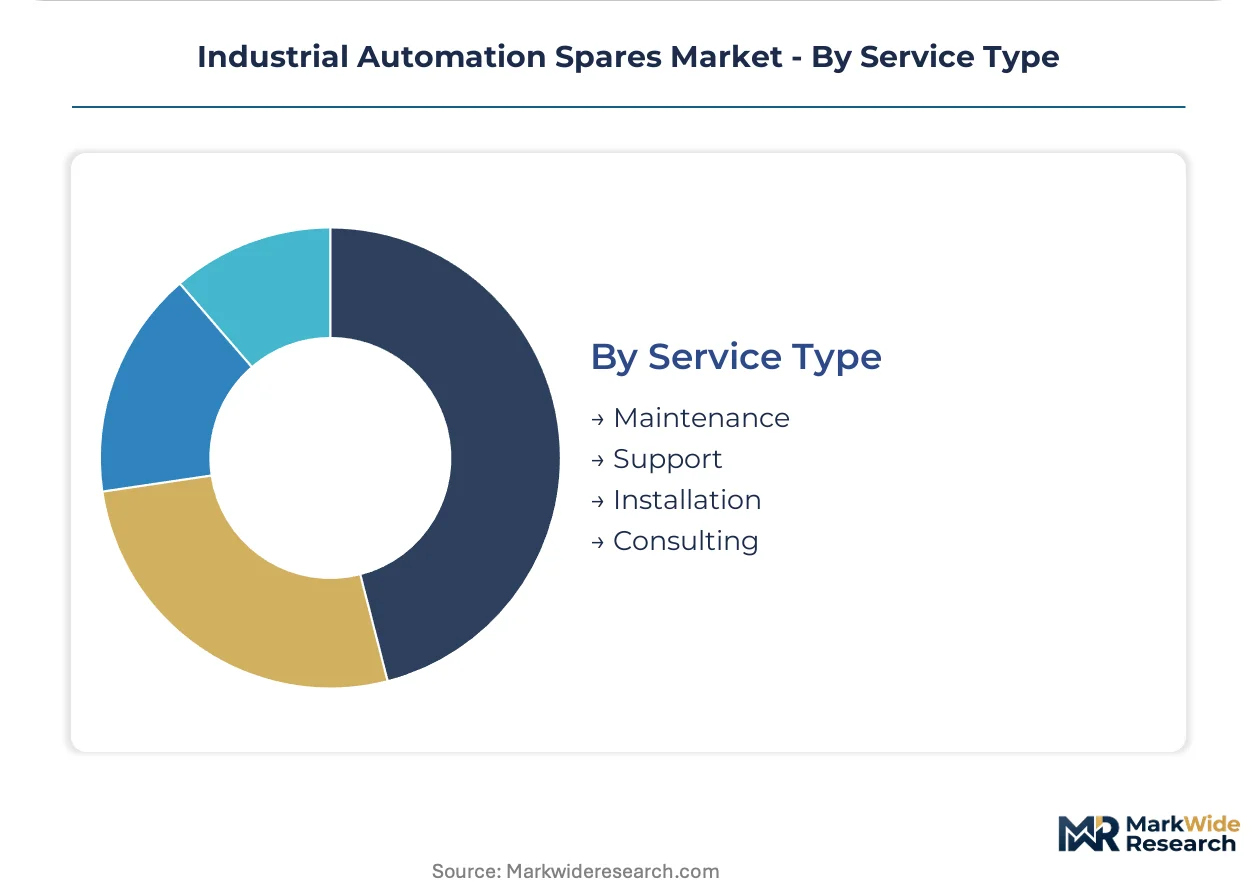
Service Type:
Customer type and their operational models significantly influence the demand for various service types accompanying industrial automation spares.
- Maintenance:Services focused on routine inspections, repairs, and preventative measures to ensure equipment longevity and performance. Many US food and beverage companies outsource maintenance to specialized providers to ensure compliance with OSHA safety protocols and minimize downtime.
- Support:Technical assistance, troubleshooting, and remote diagnostics for automation systems and their components. European manufacturers increasingly rely on remote support services to address complex software and hardware integration challenges quickly.
- Installation:The professional setup and integration of new automation spares into existing or new systems. Proper installation is critical for optimal performance and warranty validity.
- Consulting:Expert advice on system optimization, regulatory compliance, and technology upgrades related to automation spares. This service helps end-users make informed investment decisions.
Maintenance services generate the most consistent revenue; Support services are expanding most quickly as systems become more complex.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Within Germany's advanced manufacturing ecosystem, the concentration of industrial automation spares demand is particularly pronounced, driven by high-efficiency production mandates. China's rapidly automating production facilities also represent a significant hub for these critical components. These regions exemplify the global shift towards sophisticated, compliant industrial operations.
United States
United States demand for industrial automation spares is propelled by the aerospace sector's need for precise sensors and Michigan's automotive production upgrades. OSHA safety requirements dictate component specifications, ensuring workplace safety across industries. Major industrial hubs like Detroit and Seattle focus on integrating advanced spares for high-reliability applications.
Germany
German manufacturing drives significant demand for controllers and drives, supporting complex, high-speed process orchestration in automotive plants. The updated EU Machinery Regulation tightens safety and cybersecurity requirements, influencing product design. Industrial centers in Bavaria and Baden-Württemberg lead in adopting advanced spares for Industry 4.0 initiatives.
China
China's rapidly automating production facilities generate substantial demand for SCADA and PLC spares, managing complex, distributed production lines. GB standards in China dictate component specifications and market access for suppliers. The Yangtze River Delta region, including Shanghai, sees significant investment in smart factory spares.
Japan
Japanese industrial automation spares demand stems from precision engineering in robotics and advanced manufacturing. JIS standards ensure high quality and reliability for components in critical applications. The Kanto region, including Tokyo, remains a hub for high-tech industrial automation development and consumption.
South Korea
South Korea's high-tech manufacturing, especially in semiconductors and electronics assembly, fuels demand for advanced sensors and drives. National quality certifications influence component selection for critical production processes. The Seoul Capital Area and Gyeonggi Province are major centers for integrating cutting-edge automation spares.
Industrial Automation Spares Market Key Industry Players
European producers anchor one tier of the industrial automation spares market, often characterized by comprehensive portfolios and adherence to stringent regional standards. North American specialists hold strong positions in integrated control systems, focusing on specific industry verticals like food and beverage. The market structure is moderately consolidated, with a few large multinational corporations dominating key segments. Competitive moves often involve strategic partnerships for technology integration and geographic expansion into rapidly industrializing economies.
On the global scale, Siemens AG, a German industrial conglomerate, exemplifies companies offering extensive PLC and drive portfolios that address complex compliance standards. Rockwell Automation, an American corporation, sustains a strong position in North America by specializing in integrated control systems for sectors like automotive. Japanese manufacturer FANUC Corporation anchors the precision robotics and motion control segment, providing critical spares for high-speed assembly lines worldwide.
| Leading Market Players |
|---|
| FANUC |
| Yaskawa |
| Siemens |
| Honeywell |
| Schneider Electric |
| Rockwell Automation |
| Emerson Automation Solutions |
| Mitsubishi Electric |
| ABB |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps often anchor specialized component production, influencing supply stability and enabling premium pricing for niche industrial automation spares. Their long-term investment horizons shape controlled supply behaviors, impacting market pricing discipline.
Pricing Analysis
Premium pricing for short lead times characterizes the industrial automation spares market, reflecting the critical need for operational uptime. The dominant pricing model is per-unit transactional, with emerging subscription-based services differentiating offerings. Price differentiation stems from component certification levels, such as CE marking compliance, and brand premium for established manufacturers like Siemens. Pricing softness reflects semiconductor supply volatility, particularly for electronic spares, while automotive manufacturers are least price-sensitive due to uptime criticality.
Supply Chain Analysis
Single-source vulnerability sits with specialized semiconductor foundries, concentrated in Taiwan and South Korea, which produce microcontrollers and processors for critical electronic spares. The supply chain relies heavily on rare earth minerals and advanced composite materials, sourced primarily from China. Logistics chokepoints, particularly for air freight, represent a significant structural risk. Distribution runs through a dual model, with direct sales to large OEMs and a network of specialized industrial distributors serving smaller end-users globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial automation spares market remains a supply-constrained story, where limited specialized manufacturing capacity for advanced components props up pricing power. Persistent semiconductor shortages create a critical bottleneck for electronic spares.
For Market Incumbents: Extend long-term service agreements with key industrial customers to guarantee parts availability and deepen customer relationships. Invest in localized manufacturing capacity within Europe to mitigate geopolitical supply risks and meet EU Machinery Regulation compliance. The threat of new entrants offering AI-enhanced diagnostics necessitates continuous R&D in embedded intelligence. Leverage certification investment, particularly for CE marking, as a competitive barrier.
For New Entrants and Emerging Players: Capture market share by specializing in cybersecurity-compliant components for critical infrastructure, a white space driven by new EU regulations. Develop modular, open-architecture spares that integrate seamlessly with legacy systems, targeting the integration challenge in general manufacturing. The most penetrable segment lies in advanced sensors for predictive maintenance in aerospace applications. A go-to-market angle involves offering performance-guaranteed parts-as-a-service models.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with strong intellectual property in functional safety components within Germany. The long-term viability of the market is underpinned by the continuous need for operational uptime across manufacturing sectors over the next decade. Acquisition targets should be firms with certified product portfolios and established service networks. The signal to watch is the consolidation of smaller component manufacturers by larger players seeking to expand their compliance capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Localized Manufacturing Capacity Expansion | Reduces lead times for critical components in Europe, enhancing supply chain resilience against geopolitical disruptions. |
| Parts-as-a-Service (PaaS) Model Launch | Shifts inventory risk to vendors and provides recurring revenue streams for Siemens and Rockwell Automation. |
| Cybersecurity-by-Design Integration | Ensures compliance with EU Machinery Regulation, preventing cyber threats in critical infrastructure components. |
| Certified Remanufacturing Programs | Appeals to sustainability mandates from German industrial firms and creates a circular economy for high-value spares. |
| Strategic Technology Partnerships | Accelerates the development of AI-enhanced diagnostics for sensors, improving predictive maintenance capabilities for end-users. |
Research Approach
Independent corroboration across industry reports, regulatory filings, and trade association publications underwrites the qualitative findings of this study. Primary interviews with plant engineers, procurement leads, and aftermarket service heads provided crucial insights. Secondary validation included analysis of customs data for component flows and technical specifications from standards bodies like ISO. This approach combined bottom-up market sizing with top-down validation.
The forecast window was anchored to historical reference periods, ensuring consistent data comparability across the analysis window. This analytical framework modeled segmentation dimensions including product type, technology, end-user industry, and regional regulatory frameworks. Compound annual growth rates were derived from a multi-factor regression analysis, incorporating industrial production indices. Automation adoption rates in emerging economies served as a key forecast input.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply stability and geopolitical trade policies. Forecasts reflect assumptions regarding regulatory enforcement and industrial investment cycles. Deviation in global economic growth would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Middle East and Africa Process Automation Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
United States SCADA Market
Industrial Automation
Global Motion Controller Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
Industry 4.0 Market
Industrial Automation
Latin America Laboratory Automation Market
Industrial Automation
Global Industrial Control and Factory Automation Market
Industrial Automation
North America Human Machine Interface Market
Industrial Automation
Smart Warehouse System Market
Industrial Automation
Asia Industry 4.0 Market
Industrial Automation
Geosteering Technology Market
Industrial Automation
Modular High-Bay Solutions Market
Industrial Automation
Smart Factory Market
Industrial Automation
Asia Pacific Industrial Communication Market
Industrial Automation
Industrial Internet Connectivity Tracker Market