
 Industrial Automation Device Manager Software Market | 2026-2036
Industrial Automation Device Manager Software Market Size, Share, and Industry Trends Forecast 2026-2036
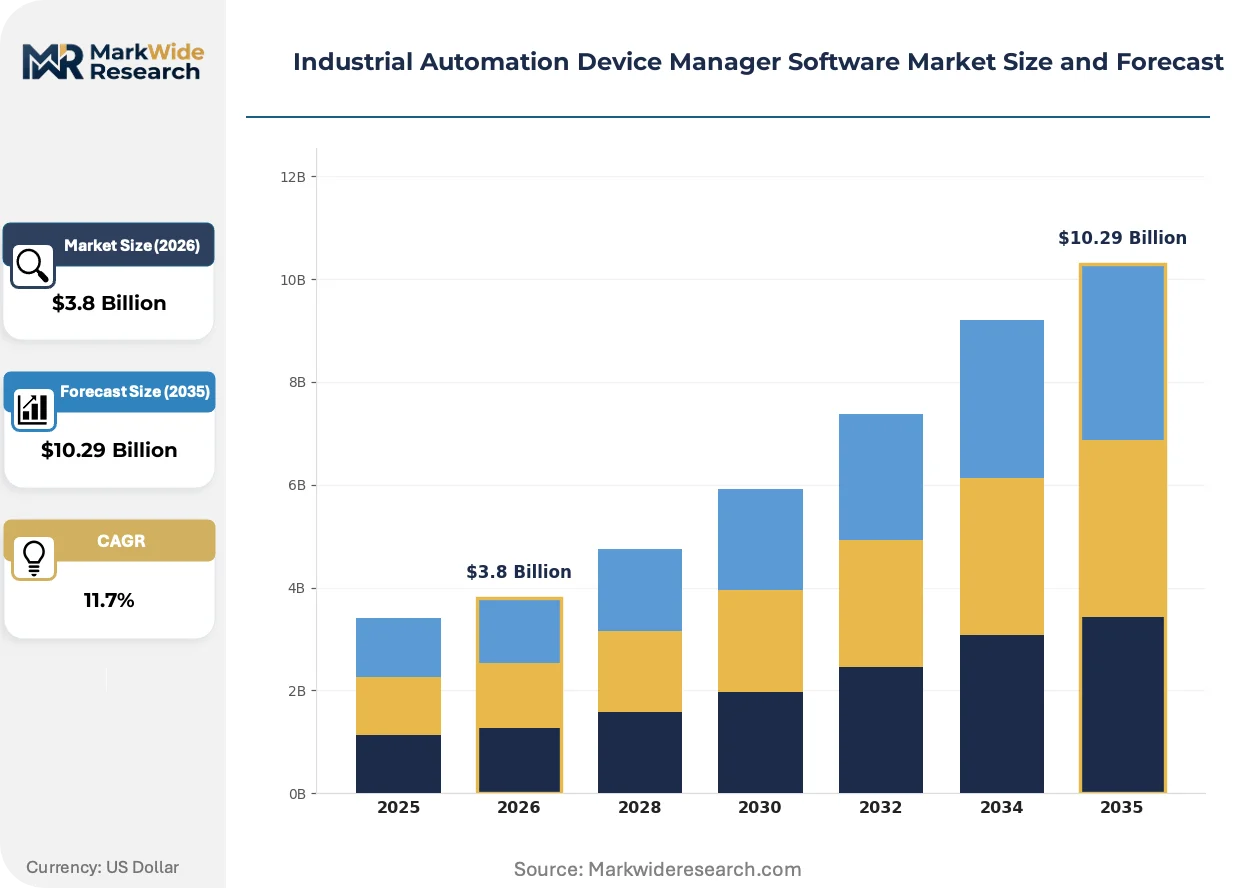
Industrial Automation Device Manager Software Market Foresight
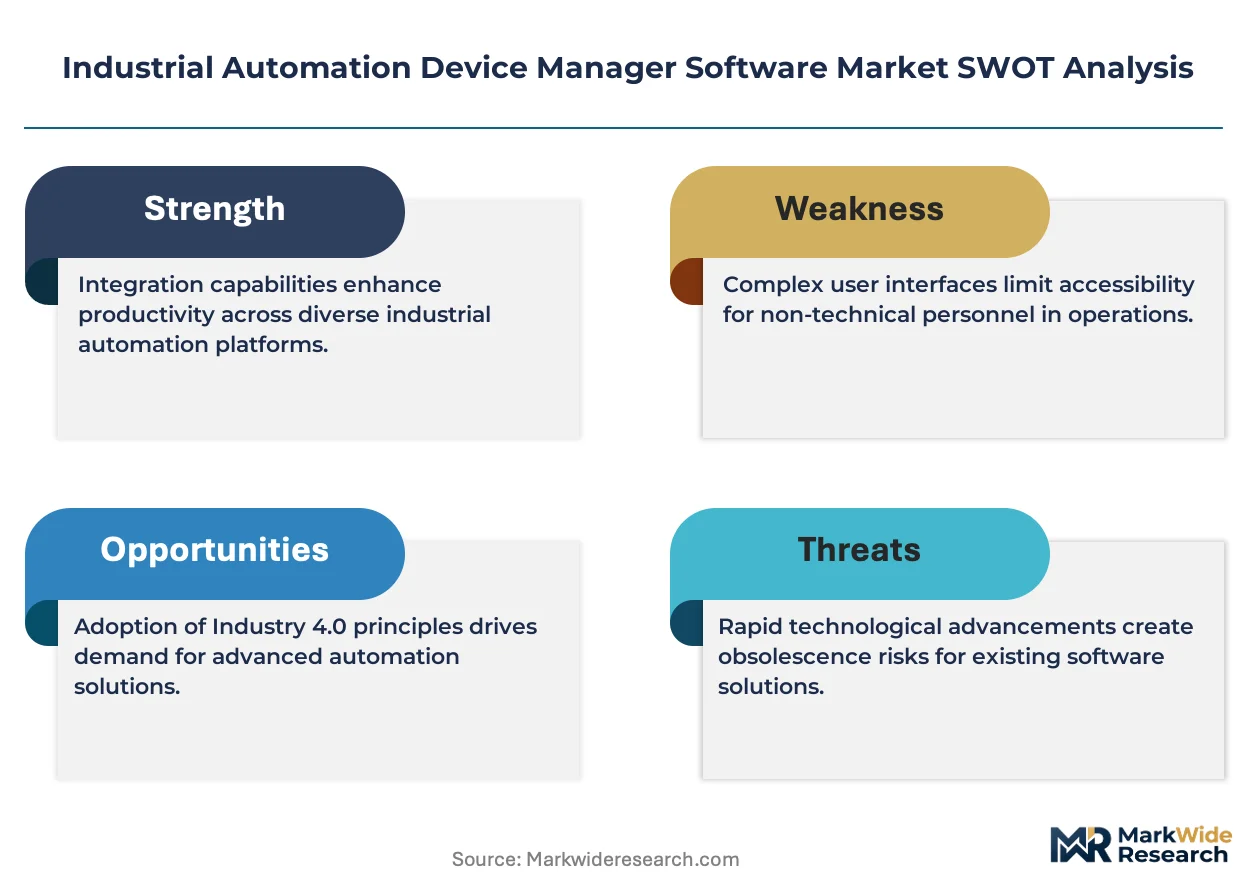
The widening capability gap between premium device manager suites and commodity configuration tools is repositioning how industrial buyers evaluate total cost of ownership. Siemens leverages deep vertical integration across PLC and SCADA stacks to sustain pricing power in process-heavy sectors. Rockwell Automation anchors its competitive stance through FactoryTalk ecosystems that dominate North American discrete manufacturing.
Industrial Automation Device Manager Software comprises applications that discover, configure, monitor, and maintain programmable logic controllers, distributed control systems, and human-machine interfaces through centralized dashboards with real-time diagnostic protocols. These platforms serve to reduce unplanned downtime by enabling remote firmware updates, asset inventory tracking, and security policy enforcement across heterogeneous device fleets. Cloud-based deployment models are capturing the fastest expansion as manufacturers seek to offload infrastructure capital while edge computing configurations retain dominance in latency-sensitive safety systems. The oil and gas end-user segment concentrates margin pools where explosion-proof certification requirements and hazardous area compliance sustain premium pricing for specialized device manager modules.
The EU Cyber Resilience Act and IEC 62443 standards are reshaping product development roadmaps by mandating secure-by-design architectures and documented vulnerability management across connected automation devices. NIST's Cybersecurity Framework and FDA's software validation guidance for manufacturing systems are similarly tightening procurement specifications in the United States. Stakeholders must weigh the trade-off between cloud agility and operational technology isolation as regulatory scrutiny of software supply chains intensifies across jurisdictions.
Market Dynamics
The EU Cyber Resilience Act is forcing device manager vendors to rearchitect software supply chains around mandatory software bill of materials and patch transparency requirements, compressing development timelines while elevating compliance costs.
Growth Catalysts
- EU Cyber Resilience Act:Mandated SBOM disclosure and vulnerability tracking for connected industrial products is pulling manufacturers toward certified device manager platforms with built-in compliance tooling.
- Automotive heterogeneous control unification:Electric vehicle and battery assembly lines require device managers that bridge PLC, SCADA, and robotic controller protocols through single-pane dashboards.
- Cloud deployment acceleration:Capital-constrained manufacturers are offloading on-premise infrastructure to SaaS device manager configurations, reducing IT headcount and hardware refresh cycles.
Market Restraints
- OT-IT convergence friction:Operational technology networks with decades-old legacy protocols resist seamless integration with cloud-native device manager architectures, extending deployment timelines.
- Semiconductor supply concentration:Industrial controller chip shortages concentrated in Taiwanese foundries create hardware availability bottlenecks that stall device manager fleet expansions.
- Specialized certification costs:IEC 62443-3-3 SL3 compliance for safety instrumented systems demands expensive third-party validation, pricing out mid-tier manufacturers.
Strategic Opportunities
- India manufacturing digitization:PLI scheme incentives for electronics and automotive production are creating first-time device manager demand among domestic contract manufacturers.
- Digital twin convergence:Integration of device manager telemetry with physics-based simulation models enables predictive maintenance revenue streams in process industries.
- Edge-cloud hybrid architectures:Latency-sensitive safety systems retain edge computing while non-critical monitoring shifts to cloud, opening dual-deployment licensing models.
Industry Challenges
- Cybersecurity-operations skill scarcity:Cross-functional teams fluent in both IEC 62443 standards and legacy PLC programming command premium wages, constraining vendor implementation capacity.
- Multi-vendor protocol fragmentation:Proprietary fieldbus standards from incumbent automation suppliers complicate unified device discovery and configuration workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Automation Device Manager Software Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLC, SCADA, DCS, HMI Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Manufacturing, Oil & Gas, Utilities, Automotive Integration Level: Full Automation, Semi-Automation, Manual Integration, Legacy Systems |
| Companies Covered | Siemens, Rockwell Automation, ABB, Schneider Electric, Emerson Electric, Honeywell International, Mitsubishi Electric, Yokogawa Electric, Advantech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Automation Device Manager Software Market Shifts & Advancements
Device manager architectures are fragmenting along latency and security fault lines, with vendors racing to deliver unified platforms that span cloud, edge, and air-gapped deployments without compromising either agility or isolation.
Containerized device manager software is modularizing deployment topologies across manufacturing environments. Automotive battery gigafactories in Germany and South Korea are adopting Kubernetes-orchestrated device agents that standardize firmware update pipelines across heterogeneous controller fleets. This modularization is compressing the traditional divide between process and discrete manufacturing software stacks, enabling vendors to serve both sectors with shared codebases.
The EU Cyber Resilience Act's software supply chain disclosure mandates are accelerating SBOM tooling integration into device manager platforms. Industrial buyers now require documented vulnerability management workflows before procurement approval, particularly for safety instrumented systems in oil and gas applications. German automation clusters are responding fastest, embedding automated patch verification into continuous integration pipelines.
Buying patterns are consolidating around outcome-based maintenance contracts that bundle device manager licenses with uptime guarantees. North American discrete manufacturers are displacing perpetual software licenses with subscription models tied to connected asset counts, transferring operational risk to vendors. This shift is most visible in automotive tier-one supplier networks, where procurement teams negotiate fleet-wide pricing rather than site-by-site deployments.
Industrial Automation Device Manager Software Market Segmentation
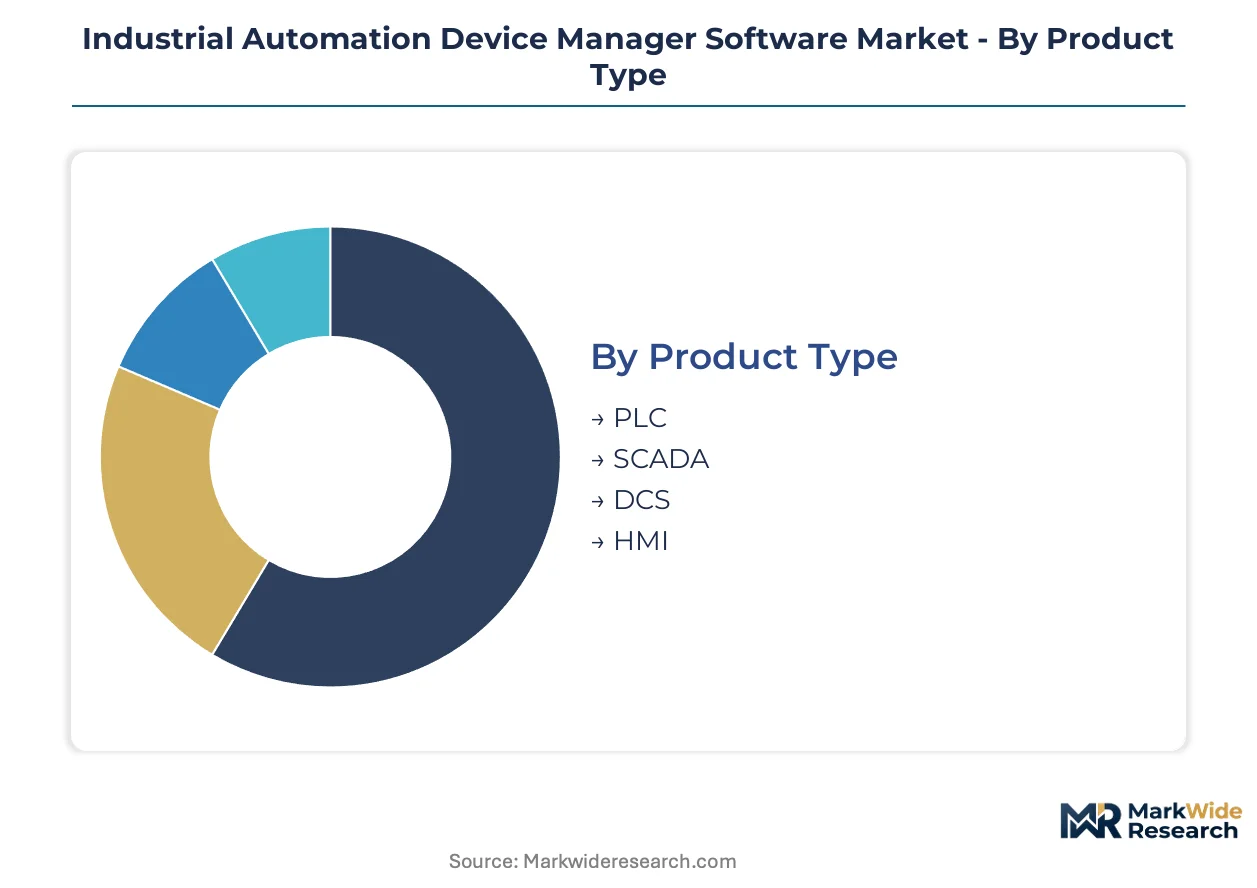
Segmentation in device manager software reveals how upgrade cycles and integration complexity fragment procurement decisions across industrial verticals. Buyers weigh legacy protocol compatibility against cloud-native agility when selecting deployment architectures.
Product Type:
Replacement timelines vary sharply across controller categories, with PLC refresh cycles averaging shorter intervals than process-heavy DCS installations.
- PLC:Programmable logic controllers dominate discrete manufacturing floors with modular I/O configurations and ladder logic programming environments. German automotive battery plants drive concentrated demand as Siemens and Rockwell Automation compete for gigafactory standardization contracts.
- SCADA:Supervisory control and data acquisition systems layer visualization and historical trending atop field-level controllers. North American water utilities and oil pipeline operators anchor procurement volumes where IEC 62443 cybersecurity certification filters vendor selection.
- DCS:Distributed control systems govern continuous process loops in chemical and refining operations with redundant controller architectures.
- HMI:Human-machine interfaces provide operator visualization panels ranging from embedded touchscreens to centralized control room displays.
Volume placements concentrate in PLC; the faster expansion belongs to SCADA as cloud-native visualization layers displace traditional historian architectures.
Deployment Model:
Cost tier stratification separates capital-intensive on-premise installations from operational-expense cloud subscriptions favored by mid-tier manufacturers.
- Cloud-Based:SaaS device manager configurations offload server infrastructure and reduce IT headcount through browser-accessible dashboards. Indian contract manufacturers under PLI scheme incentives adopt these models fastest to minimize upfront capital deployment.
- Edge Computing:Localized processing nodes execute latency-critical control loops within 10-millisecond response windows. South Korean automotive battery lines mandate edge deployments for safety instrumented systems where cloud latency violates functional safety requirements.
- On-Premises:Air-gapped server installations persist in defense and nuclear applications with strict network segmentation requirements.
- Hybrid:Split architectures retain edge control for safety systems while streaming non-critical telemetry to cloud analytics platforms.
On-premises retains margin concentration in regulated industries; hybrid architectures are climbing fastest as vendors dual-license edge and cloud modules.
End User:
Application severity and certification burdens create distinct margin tiers across industrial verticals.
- Oil & Gas:Explosion-proof certification requirements and IEC 62443-3-3 SL3 compliance sustain premium pricing for hazardous area device manager modules. North Sea and Gulf of Mexico offshore platforms anchor this segment's procurement volumes.
- Automotive:Electric vehicle assembly lines require protocol bridges across robotic controllers, PLCs, and battery management systems through unified dashboards. German OEM supplier networks standardize on Siemens and ABB platforms for heterogeneous control unification.
- Manufacturing:Discrete production facilities span food packaging to electronics assembly with varying automation maturity levels.
- Utilities:Power generation and water treatment operations prioritize SCADA integration with legacy fieldbus protocols.
Oil and gas commands the steepest pricing tier; automotive is gaining share fastest as battery gigafactory construction accelerates across Germany and South Korea.
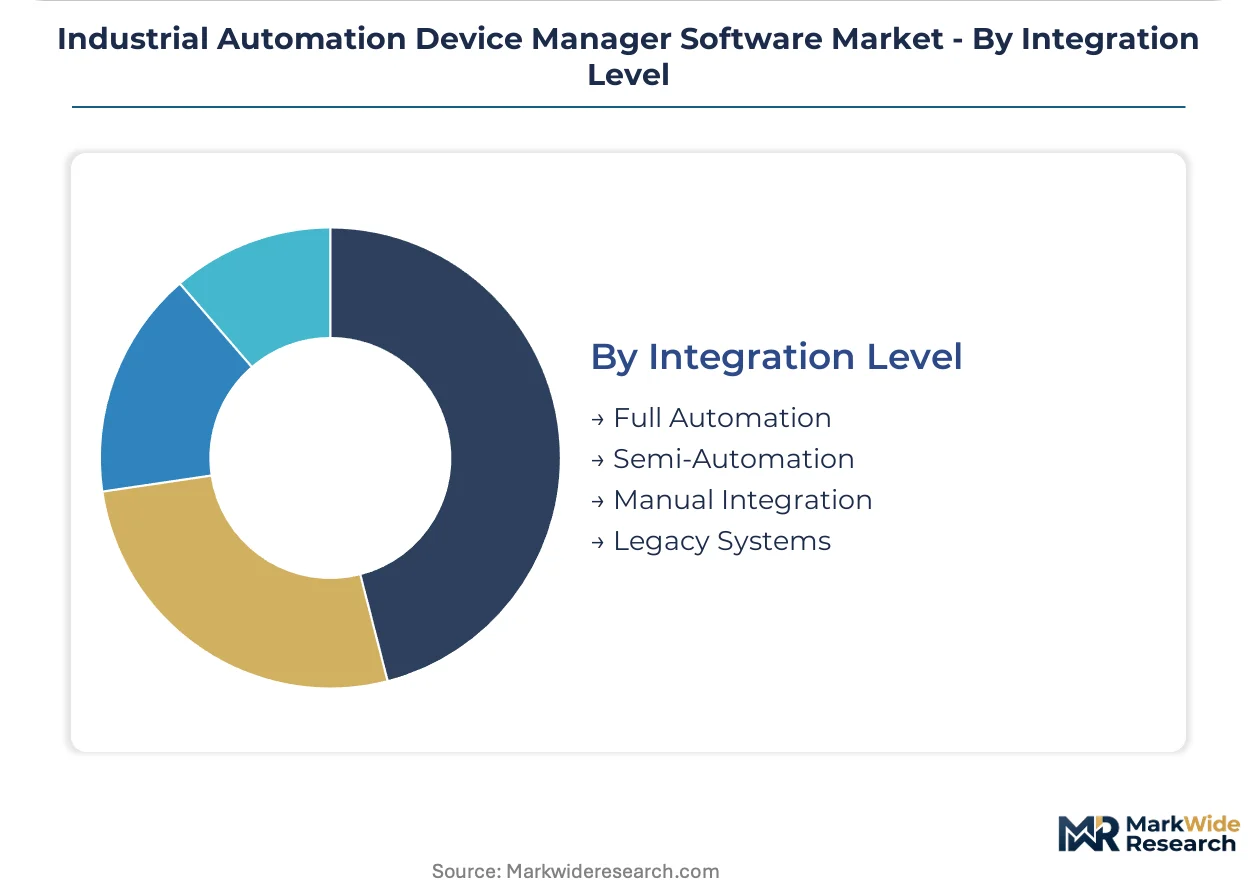
Integration Level:
Customer automation maturity and legacy asset bases determine implementation complexity and service attach rates.
- Full Automation:Greenfield facilities with unified vendor stacks enable plug-and-play device discovery and centralized policy enforcement. New German automotive plants exemplify this tier with single-source Siemens ecosystems.
- Legacy Systems:Decades-old proprietary fieldbus installations require protocol gateways and custom integration services to connect modern device managers. North American process industries anchor this segment with Honeywell TDC and Yokogawa CENTUM retrofits.
- Semi-Automation:Partially integrated environments mix automated cells with manual workstations and islanded controllers.
- Manual Integration:Operator-driven device configuration persists in small-batch job shops and developing market facilities.
Full automation captures the premium implementation pipeline; legacy system retrofits represent the largest addressable base by connected device count.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nuremberg anchors the densest concentration of automation software engineering in Europe, hosting Siemens' digital industries headquarters and a cluster of PLC programming specialists that supply device manager modules across German automotive plants.
Germany
Automotive battery gigafactories in Lower Saxony and Bavaria drive concentrated demand for heterogeneous control unification. The EU Cyber Resilience Act mandates software bill of materials disclosure for all connected industrial products sold in member states. Siemens anchors Nuremberg's automation software cluster while ABB maintains substantial engineering presence in Mannheim for process industry device management.
United States
Discrete manufacturing hubs in Michigan and Ohio require device managers bridging legacy Rockwell PLC installations with cloud-native monitoring layers. NIST's Cybersecurity Framework tightens procurement specifications for critical infrastructure operators. Houston's oil and gas engineering corridor sustains premium pricing for IEC 62443-certified device manager modules serving offshore platform retrofits.
China
Electric vehicle assembly lines in Shanghai's Jiading District and Shenzhen's Pingshan New Area create demand for protocol bridges across robotic controller fleets. MIIT's industrial internet platform standards push domestic manufacturers toward centralized device management architectures. Suzhou's industrial park hosts localized device manager development for semiconductor fabrication equipment.
South Korea
Battery cell production complexes in Gwangju and Ulsan mandate edge-computing device managers for sub-10-millisecond safety system response. The country's national cybersecurity framework for critical infrastructure elevates procurement scrutiny of software supply chains. Pangyo's technology corridor hosts Hyundai and SK Innovation engineering centers standardizing device management across gigafactory deployments.
India
Electronics contract manufacturers in Tamil Nadu's Sriperumbudur belt and Karnataka's Bangalore Rural district adopt cloud-based device managers under PLI scheme incentives. The Bureau of Indian Standards drafts certification requirements for industrial automation software security. Gujarat's Sanand automotive cluster generates first-time demand as Tata Motors and Suzuki expand EV assembly capacity.
Industrial Automation Device Manager Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and vertical integration breadth, with IEC 62443 SL3 validation and captive PLC hardware ecosystems sustaining pricing power. The vendor base stratifies into three tiers: diversified automation conglomerates with full-stack control, specialized software houses with protocol-agnostic architectures, and regional system integrators with customization capabilities. M&A activity concentrates on cybersecurity tooling acquisitions and edge computing module rollups. Geographic expansion into Indian PLI beneficiary zones and battery gigafactory corridors represents the dominant competitive vector.
Within the diversified automation tier, Siemens and Rockwell Automation exemplify contrasting geographic anchoring strategies. The German conglomerate occupies a position spanning European process industries and Asian automotive electrification, while the Milwaukee-based manufacturer anchors North American discrete manufacturing through ecosystem-centric platform architectures. ABB represents the Swiss-Swedish specialist archetype with concentrated strength in heavy process automation and robotics integration.
| Leading Market Players |
|---|
| Siemens |
| Rockwell Automation |
| ABB |
| Schneider Electric |
| Emerson Electric |
| Honeywell International |
| Mitsubishi Electric |
| Yokogawa Electric |
| Advantech |
| Others |
Supply & Pricing Matrix
The EU Cyber Resilience Act's software bill of materials mandates gate qualified supply access for device manager vendors while elevating premium-tier pricing for IEC 62443-certified platforms. German automotive battery manufacturers now demand documented vulnerability management workflows before procurement approval, compressing margins for non-compliant suppliers and concentrating pricing power among validated ecosystem providers.
Pricing Analysis
Outcome-based contracts tied to uptime guarantees anchor value-based pricing for device manager software in automotive and oil and gas verticals. Three-tier pricing structure across premium, standard, and economy levels stratifies by IEC 62443 certification grade and after-sales service bundling, with SL3-validated platforms commanding substantial premiums over commodity configuration tools. Pricing pressure stems from cloud-native SaaS entrants undercutting perpetual license models in mid-tier manufacturing segments. Small-batch job shops exhibit highest price sensitivity; hazardous area operators in offshore oil platforms demonstrate lowest.
Supply Chain Analysis
Automation software engineering talent scarcity in Nuremberg, Mannheim, and Milwaukee constrains development velocity for device manager platforms. Taiwan, South Korea, and Germany anchor semiconductor controller chip supply and specialized firmware development capacity. Supply chains draw from Taiwanese foundries for industrial controller silicon, German automotive clusters for protocol integration expertise, and Indian PLI beneficiary zones for cloud deployment engineering. Single-source vulnerability in Taiwanese semiconductor fabrication creates hardware availability bottlenecks. Distribution runs through direct OEM partnerships and systems integrator channels serving plant-level deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Containerized Kubernetes-orchestrated device agents are displacing monolithic SCADA architectures, compressing deployment timelines and reshaping competitive positioning across heterogeneous controller environments.
For Market Incumbents: Acquire cybersecurity tooling specialists with automated SBOM verification capabilities to satisfy EU Cyber Resilience Act mandates and defend against cloud-native entrants. Deepen backward integration into edge computing hardware to capture hybrid deployment margins. Prioritize IEC 62443-3-3 SL3 certification investment for oil and gas safety instrumented system modules. For New Entrants and Emerging Players: Cloud-native SaaS routes through Indian electronics contract manufacturers under PLI scheme incentives offer lowest competitive density for first-time device manager adoption. Target semi-automated facilities with protocol-agnostic discovery tools bridging legacy fieldbus installations. Pursue outcome-based maintenance contracts with uptime guarantees to displace perpetual license incumbents. For Investors and Strategic Acquirers: Accelerated battery gigafactory construction in Lower Saxony and Gwangju is the leading indicator that automotive electrification will sustain device manager demand across the projection horizon. Target protocol-agnostic software houses with Kubernetes-native architectures and established SI channel relationships. Watch for IEC 62443 certification backlogs as signal of vendor implementation capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| SBOM Tooling Acquisition | Automated software supply chain disclosure satisfies EU Cyber Resilience Act procurement gates. |
| Edge-Cloud Hybrid Platform Launch | Dual-deployment licensing captures latency-sensitive safety systems and cloud analytics simultaneously. |
| IEC 62443-3-3 SL3 Certification Investment | Safety integrity validation unlocks premium pricing in North Sea offshore platform retrofits. |
| Indian PLI Zone Partnership | Electronics contract manufacturer relationships establish first-mover position in cloud-native adoption. |
| Digital Twin Integration Development | Physics-based simulation convergence enables predictive maintenance revenue streams in chemical processing. |
Research Methodology
SEC filings, IEC 62443 certification registries, and automotive production databases formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with plant engineers, OEM procurement teams, automation systems integrators, and aftermarket service heads validated deployment model preferences and pricing sensitivity thresholds. Bottom-up connected device counts and top-down software spend estimates were triangulated against disclosed platform revenues.
Bottom-up segmentation across deployment model, integration complexity, vertical application, and regional adoption pattern drove volume and value outputs throughout the forecast period. CAGRs were derived from regression analysis against industrial capital expenditure cycles and electrification investment trajectories. Forecast inputs incorporated battery gigafactory construction pipelines, EU regulatory compliance deadlines, and semiconductor availability indicators.
The model holds under sustained industrial electrification investment and stable semiconductor supply; deviation in Taiwanese foundry capacity or EU Cyber Resilience Act enforcement intensity would shift vendor competitive positioning and pricing trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Industrial Networking Solutions Market
Industrial Automation
North America Process Automation Market
Industrial Automation
France Factory Automation and Industrial Controls Market
Industrial Automation
Warehousing Automation Equipment Market
Industrial Automation
Geosteering Technology Market
Industrial Automation
Industrial Automation Spares Market
Industrial Automation
United States Factory Automation and Industrial Controls Market
Industrial Automation
Global Programmable Logical Controllers Automation Market
Industrial Automation
Asia Pacific Process Automation Market
Industrial Automation
United States SCADA Market
Industrial Automation
Motion Control Centers Market
Industrial Automation
Industrial Internet Connectivity Tracker Market
Industrial Automation
Global Blasting Automation Services Market
Industrial Automation
Asia Pacific Factory Automation and Industrial Controls Market
Industrial Automation
Rotary Vector (RV) Reducer Market
Industrial Automation
Distribution Feeder Automation Market