
 Digital Transformation in Manufacturing Market | 2026-2036
Digital Transformation in Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Transformation in Manufacturing Market Analysis
Automotive OEM demand for digital thread integration is hardening as electrification programs multiply factory complexity. Siemens Digital Industries leverages its digital twin portfolio to anchor European automotive automation programs. GE Digital competes through Predix-based asset performance management in energy-intensive process industries. Rockwell Automation controls North American discrete manufacturing with FactoryTalk-aligned channel partnerships.
Digital transformation in manufacturing denotes the systematic integration of cyber-physical systems, industrial IoT sensors, and AI-driven analytics platforms into production environments, typically operating at sub-50-millisecond latency for real-time control loops. Its primary purpose is to convert operational data into actionable production intelligence that reduces unplanned downtime and material waste. IoT deployment currently leads installed technology bases across heavy process sectors where sensor density governs throughput visibility. Predictive Maintenance application segments capture disproportionate margin pools as asset-intensive buyers prioritize uptime guarantees over capex reduction. Cloud-Based deployment architectures are displacing legacy on-premises SCADA in mid-market electronics and pharmaceutical facilities seeking elastic compute without facility expansion.
The EU AI Act classifies certain manufacturing AI systems as high-risk, mandating conformity assessments before CE marking for automated quality control installations. FDA computer system validation requirements under 21 CFR Part 11 constrain digital record-keeping in pharmaceutical manufacturing, directly shaping software procurement specifications for batch release automation. China's MIIT dual carbon goals are accelerating GB-standard energy monitoring mandates in steel and cement plants, forcing retrofit demand for connected metering infrastructure. Stakeholders must monitor whether emerging AI liability frameworks in the European Union and United States will shift insurance costs onto system integrators or remain with end-user operators.
Market Dynamics
Automotive electrification programs are hardening demand for digital thread integration across assembly lines, forcing OEMs to synchronize design-to-production data flows at sub-50-millisecond latency thresholds.
Growth Catalysts
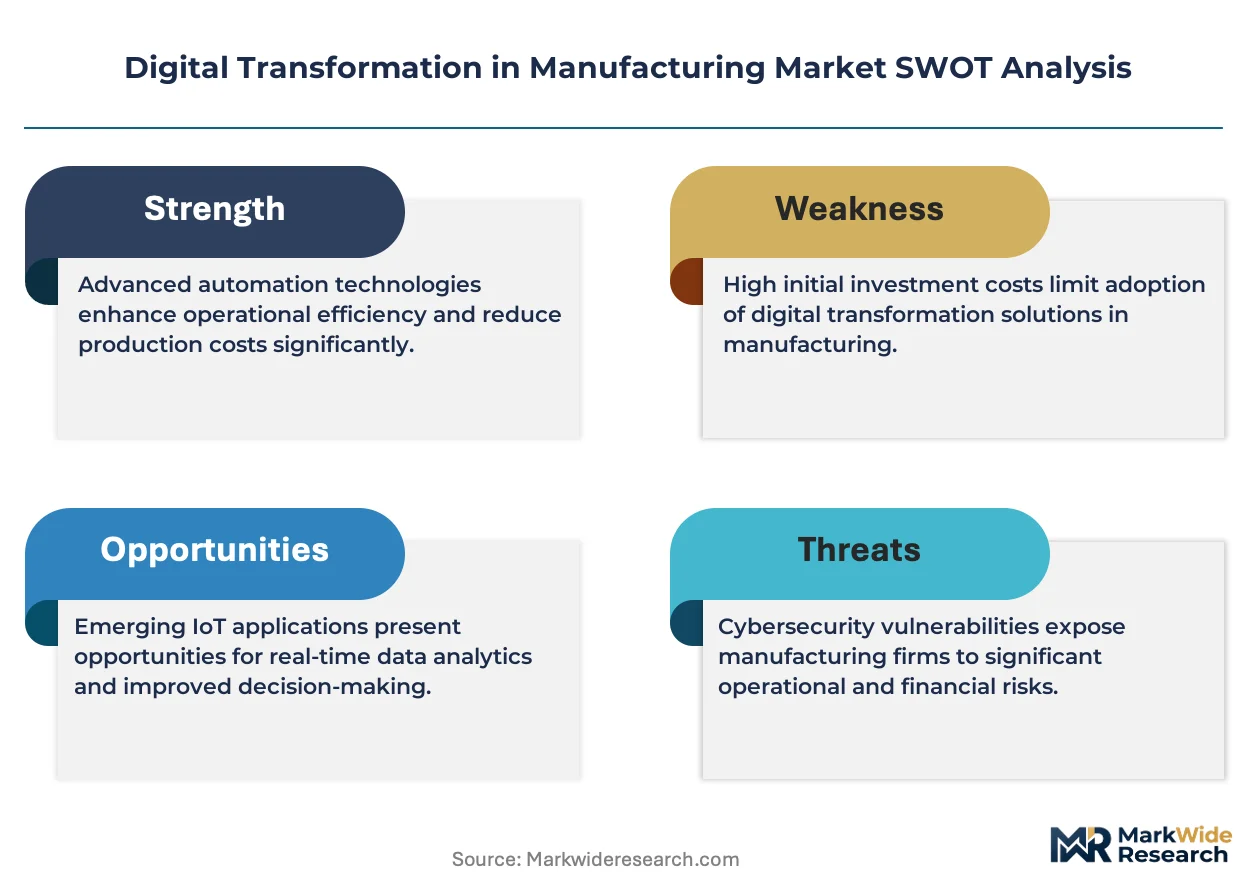
- EU AI Act high-risk classification:Automated quality control installations now require conformity assessments before CE marking, accelerating certified vendor consolidation among system integrators.
- China MIIT dual carbon mandates:GB-standard energy monitoring retrofit requirements in steel and cement plants are forcing connected metering infrastructure upgrades.
- Predictive Maintenance adoption:Asset-intensive process industries prioritize uptime guarantees over capex reduction, concentrating margin pools in condition-monitoring analytics.
Market Restraints
- Legacy SCADA replacement costs:Mid-market electronics and pharmaceutical facilities face facility expansion avoidance expenses when migrating from on-premises architectures.
- FDA 21 CFR Part 11 validation:Pharmaceutical batch release automation software procurement specifications carry 18-24 month compliance timelines.
- Edge compute hardware shortages:Industrial IoT sensor density requirements in heavy process sectors strain semiconductor supply chains.
Strategic Opportunities
- Cloud-Based deployment elasticity:Pharmaceutical and electronics mid-market buyers seek elastic compute without physical facility expansion.
- Digital twin convergence:Cyber-physical system integration with AI-driven analytics platforms creates new system integrator service revenue.
- Germany automotive automation:European OEM electrification programs multiply factory complexity, expanding digital twin portfolio demand.
Industry Challenges
- OT-IT cybersecurity skill scarcity:Smart factory deployments require cross-functional talent capable of bridging operational technology and information security domains.
- Interoperability standard fragmentation:Multiple industrial IoT protocols complicate sensor-to-platform integration across vendor ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Transformation in Manufacturing Market |
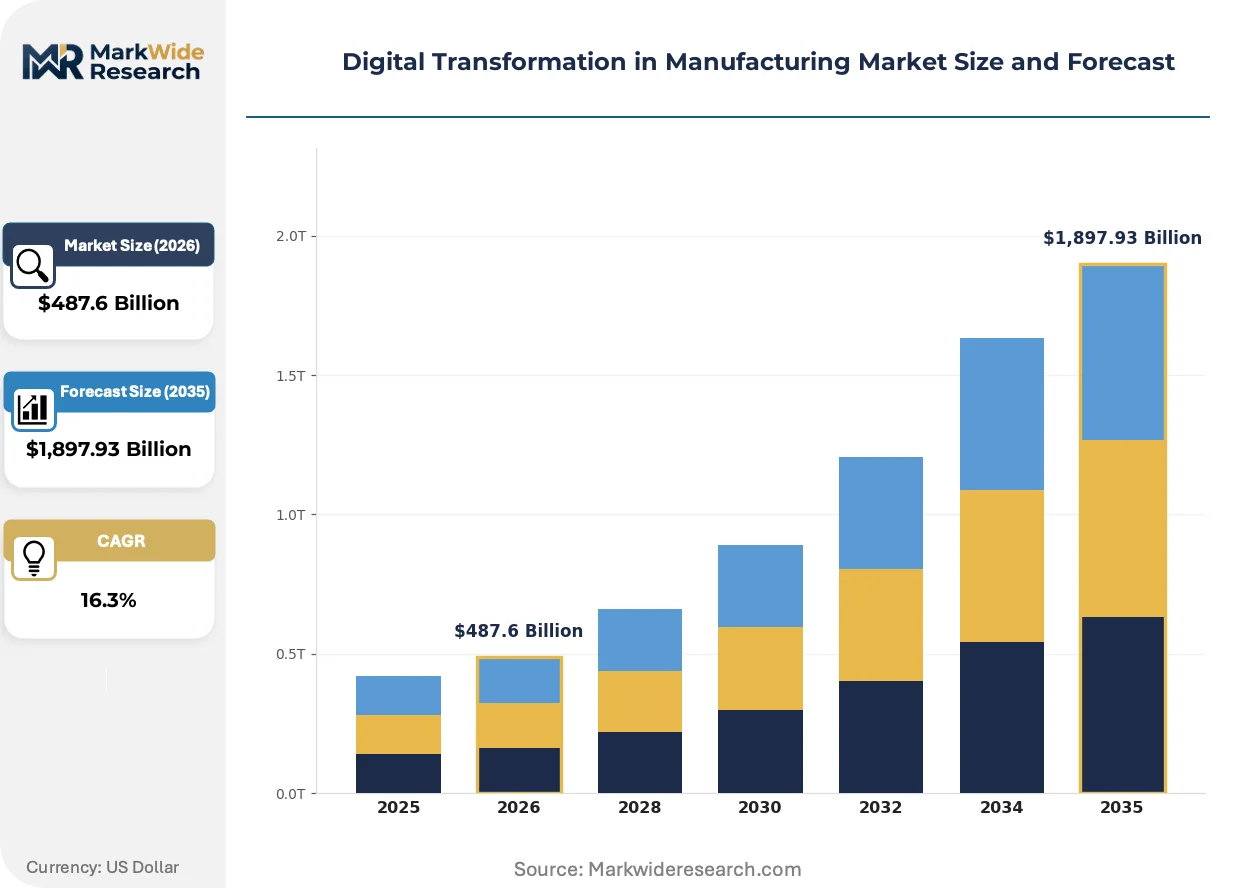
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $1,897.93 Billion |
| CAGR (2026 – 2036) | 16.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, AI, Robotics, Big Data Application: Production Optimization, Supply Chain Management, Predictive Maintenance, Quality Control End User: Aerospace, Automotive OEMs, Electronics, Pharmaceuticals Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Siemens Digital Industries, GE Digital, Schneider Electric, Honeywell Connected Enterprise, IBM, SAP, PTC, Rockwell Automation, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Transformation in Manufacturing Market Emerging Trajectories
Real-time control architectures are compressing decision latencies from minutes to milliseconds, eliminating batch-oriented production planning in favor of continuous optimization loops.
Edge-native AI inference engines are rewriting throughput visibility standards in heavy process sectors. Steel and cement operators deploy sub-50-millisecond inference pipelines directly on production lines. This compression is eliminating cloud-reliant analytics for safety-critical control loops.
REACH chemical substance restrictions are forcing material traceability system upgrades across European automotive supply chains. Component suppliers must demonstrate full substance disclosure from raw material to finished assembly. Battery manufacturers face the steepest compliance cost escalation.
Automotive OEMs now mandate outcome-based uptime guarantees from automation vendors, displacing traditional equipment procurement with performance-contracting structures. System integrators assume operational risk in exchange for recurring revenue shares. This shift concentrates most visibly in German and US electrification programs.
Digital Transformation in Manufacturing Market Segmentation
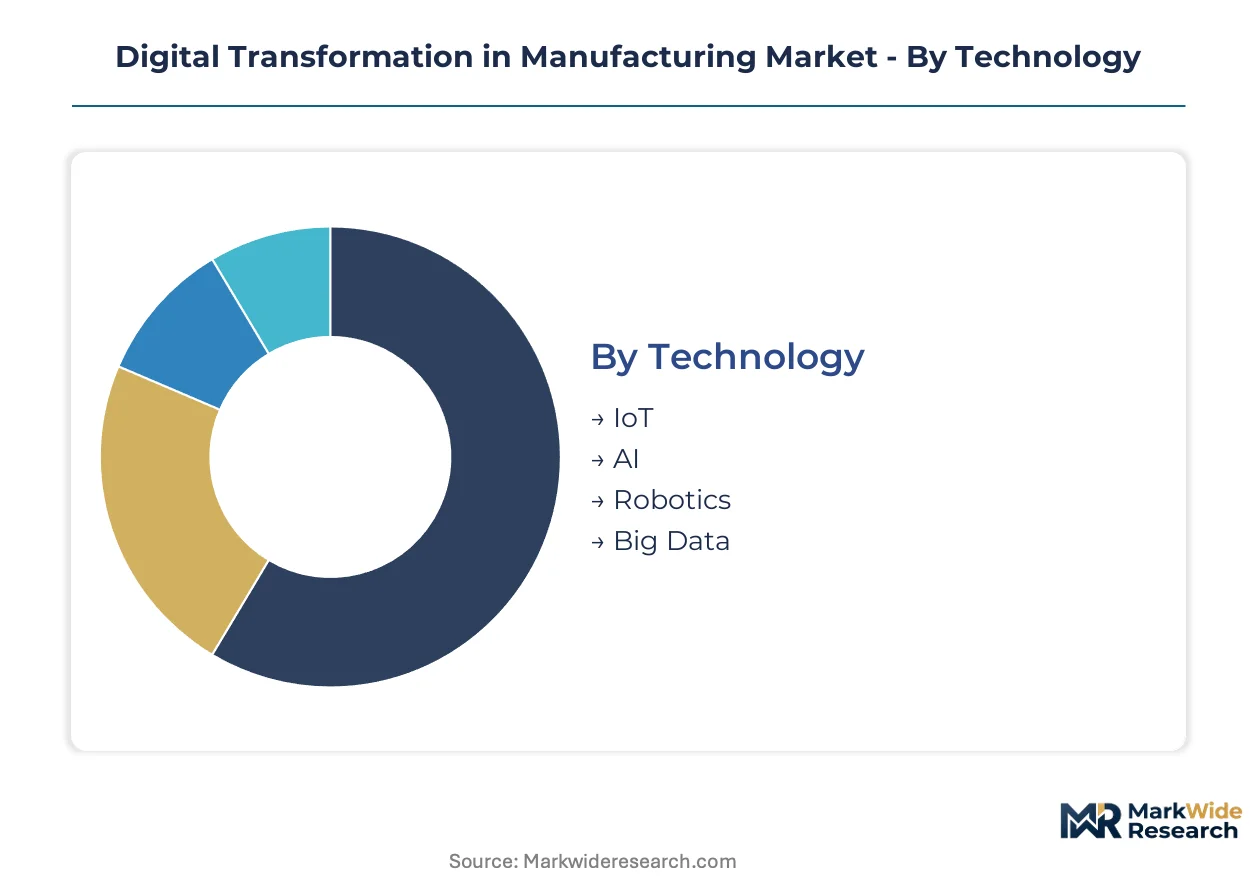
Segmentation in digital manufacturing reveals how technology choices, deployment architectures, and end-use requirements fragment procurement patterns. Buyers prioritize latency thresholds and regulatory compliance differently across heavy process versus discrete assembly environments.
Technology:
Supply concentration in semiconductor fabrication and industrial software stacks shapes which technologies achieve scale first.
- IoT:Industrial sensor networks operating at sub-50-millisecond latency enable real-time throughput visibility. Demand concentrates in German steel plants and Chinese cement facilities where MIIT dual carbon mandates force connected metering infrastructure upgrades.
- AI:Machine learning pipelines for automated quality control and predictive analytics require conformity assessments under EU AI Act high-risk classifications before CE marking. Automotive OEMs in Germany and the United States harden procurement specifications around certified vendor pools.
- Robotics:Collaborative and autonomous systems for assembly and material handling integrate with digital twin platforms.
- Big Data:Historical and real-time data lake architectures support long-term production intelligence and regulatory record-keeping.
IoT absorbs the bulk of installed capacity; AI is expanding most quickly.
Application:
Cost tier differentiation separates capex-heavy infrastructure plays from recurring-revenue analytics services.
- Predictive Maintenance:Condition-monitoring analytics platforms convert vibration, thermal, and electrical signature data into uptime guarantees. Asset-intensive process industries in the United States prioritize these solutions over capital expenditure reduction, concentrating margin pools with system integrators.
- Production Optimization:Continuous control loop refinement eliminates batch-oriented planning in favor of millisecond-scale decision architectures. Electronics manufacturers in China and Germany drive adoption to synchronize electrification program complexity.
- Supply Chain Management:End-to-end visibility platforms trace material provenance from raw inputs through finished assemblies.
- Quality Control:Automated inspection systems face tightened compliance thresholds under FDA 21 CFR Part 11 and EU AI Act requirements.
Predictive Maintenance commands premium pricing; Production Optimization is gaining share fastest.
End User:
Volume concentration in electrification programs and energy-intensive process sectors determines deployment velocity.
- Automotive OEMs:Electrification initiatives multiply factory complexity, forcing design-to-production data flow synchronization. German and US manufacturers mandate outcome-based uptime guarantees from automation vendors, displacing traditional equipment procurement.
- Pharmaceuticals:Batch release automation software carries 18-24 month FDA validation timelines under 21 CFR Part 11, directly shaping procurement specifications and vendor selection criteria.
- Electronics:Mid-market facilities seek elastic compute without physical expansion, accelerating cloud-based SCADA displacement.
- Aerospace:Defense and commercial aviation programs require material traceability systems that satisfy REACH chemical substance restrictions across European supply chains.
Automotive OEMs absorb the bulk of installed capacity; Pharmaceuticals is climbing the fastest.
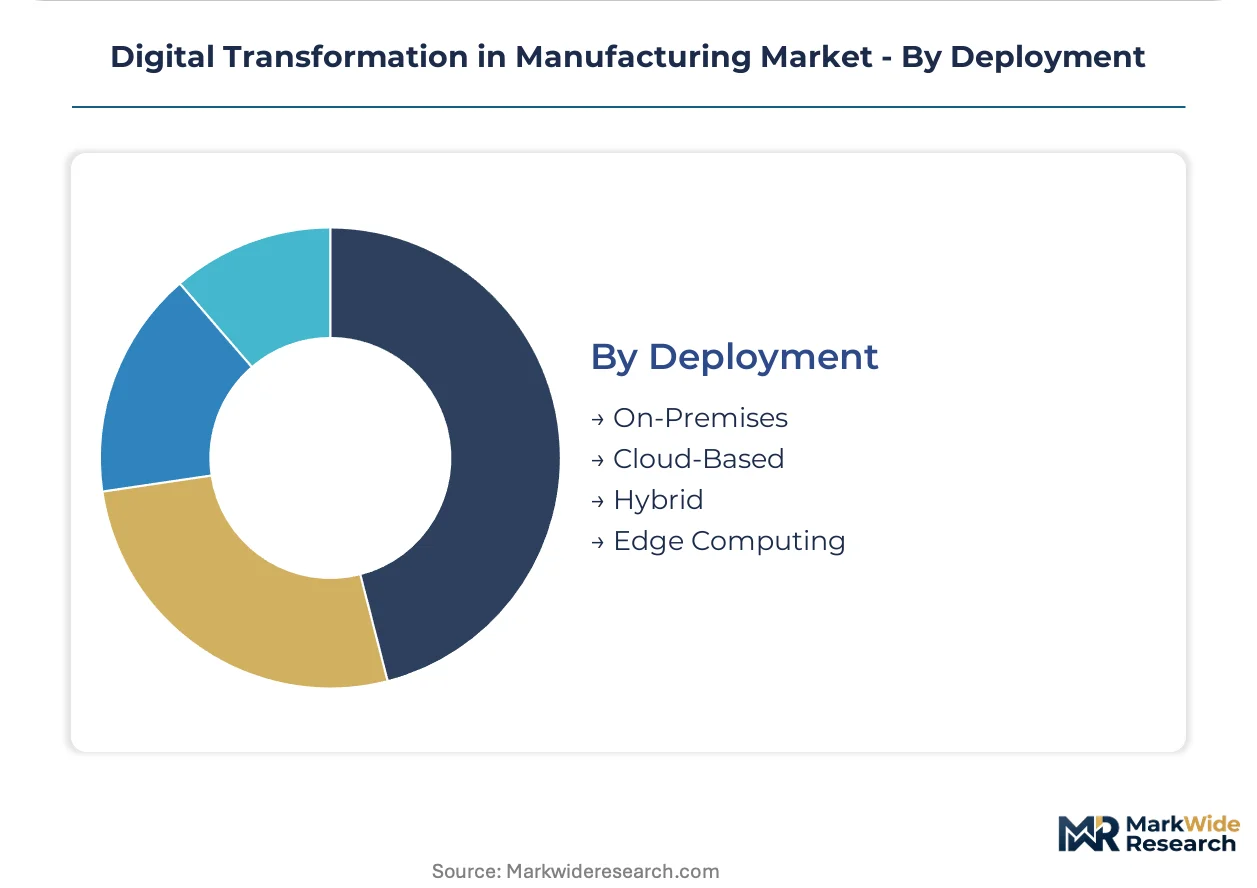
Deployment:
Maturity gradients separate legacy on-premises architectures from edge-native and cloud-elastic alternatives.
- Cloud-Based:Elastic compute architectures displace legacy SCADA in mid-market electronics and pharmaceutical facilities seeking capacity expansion without construction. US and Chinese buyers lead this migration to avoid facility capital deployment.
- Edge Computing:Sub-50-millisecond inference pipelines execute directly on production lines, eliminating cloud dependency for safety-critical control loops. Steel and cement operators in China deploy these under MIIT energy monitoring mandates.
- Hybrid:Split architectures balance latency-sensitive edge processing with centralized analytics and long-term storage.
- On-Premises:Legacy SCADA systems persist where regulatory validation timelines or cybersecurity policies constrain cloud migration.
On-Premises retains the bulk of legacy footprint; Edge Computing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Bavaria concentrate digital manufacturing investment through tax abatements and streamlined customs regimes. These zones anchor multinational facility placement decisions across three continents.
Germany
Automotive electrification programs at BMW and Volkswagen multiply factory complexity, forcing sub-50-millisecond digital thread synchronization. The EU AI Act mandates conformity assessments for automated quality control installations before CE marking. Stuttgart and Wolfsburg industrial clusters drive demand for Siemens Digital Industries' twin portfolio.
United States
Pharmaceutical batch release automation carries 18-24 month FDA validation timelines under 21 CFR Part 11, shaping vendor selection criteria. The Inflation Reduction Act's clean manufacturing credits accelerate Midwest facility retrofits. Detroit and South Carolina automotive corridors mandate outcome-based uptime guarantees from automation suppliers.
China
MIIT dual carbon mandates force GB-standard energy monitoring retrofits across steel and cement plants. National regulators tighten connected metering infrastructure specifications monthly. Yangtze River Delta heavy process operators deploy edge-native inference pipelines for real-time emissions compliance.
Japan
METI's Society 5.0 roadmap prioritizes cyber-physical system integration in precision manufacturing. JIS standards for industrial IoT interoperability constrain procurement to certified vendor pools. Nagoya automotive suppliers and Osaka electronics fabricators anchor domestic automation demand.
India
PLI scheme incentives for semiconductor and automotive component manufacturing attract digital infrastructure investment. The Bureau of Indian Standards issues IoT device certification requirements for smart factory deployments. Gujarat and Tamil Nadu industrial corridors concentrate greenfield facility announcements.
Digital Transformation in Manufacturing Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated automation vendors commanding premium positions in automotive and pharmaceutical verticals. The vendor base organizes into three tiers: full-stack platform providers, modular component specialists, and regional system integrators. Strategic archetypes include digital twin aggregators, edge compute hardware fabricators, and compliance-focused validation services. Competitive moves center on channel partnership expansion and outcome-based performance contracting structures.
Among European-headquartered industrial conglomerates, Siemens Digital Industries and ABB occupy positions as full-stack platform anchors. GE Digital exemplifies the energy-sector-focused archetype with Predix-aligned asset performance management. Rockwell Automation represents North American discrete manufacturing control through FactoryTalk-aligned distribution networks. These three companies illustrate how geographic origin and historical vertical focus shape competitive positioning without guaranteeing segment dominance.
| Leading Market Players |
|---|
| Siemens Digital Industries |
| GE Digital |
| Schneider Electric |
| Honeywell Connected Enterprise |
| IBM |
| SAP |
| PTC |
| Rockwell Automation |
| ABB |
| Others |
Supply Flow & Price Mechanics
China MIIT dual carbon mandates gate qualified supply and premium-tier pricing access for energy monitoring infrastructure, forcing steel and cement operators to source certified edge hardware at elevated cost tiers while excluding uncertified vendors from procurement pools.
Pricing Analysis
Short lead-time premiums dominate pricing structures for industrial IoT sensors and edge compute hardware, with spot inventory discounts of 15-25 percent common for non-certified components. Three-tier pricing structure across premium certified, standard compliant, and economy uncertified levels separates vendors by EU AI Act conformity and FDA 21 CFR Part 11 validation status. Cost compression in mid-market electronics tiers is intensifying because cloud-based SCADA migration reduces facility expansion avoidance expenses. Pharmaceutical buyers show least price sensitivity due to 18-24 month validation timelines that lock procurement specifications, while Chinese steel operators demonstrate highest sensitivity under MIIT mandate compliance deadlines.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific fabrication centers to European automotive clusters and North American pharmaceutical corridors is reshaping regional inventory positioning strategies. Semiconductor supply concentrates in Taiwan, South Korea, and the United States for industrial edge processors, while sensor assembly draws from China, Vietnam, and Mexico. Raw material dependencies span silicon wafers, rare earth magnets, and copper interconnects. Single-source vulnerability in advanced node semiconductor fabrication creates systemic risk for sub-50-millisecond control hardware. Distribution runs through authorized system integrator channels with FactoryTalk-aligned or digital twin-certified partnerships dominating North American and European discrete manufacturing procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over edge compute semiconductor supply and certified system integrator channels determines pricing power and contract win rates.
For Market Incumbents: Anticipate margin compression from Chinese edge hardware vendors by deepening captive supply of industrial AI inference chips and securing exclusive channel partnerships with German automotive electrification programs. Lock in multi-year outcome-based performance contracts with US pharmaceutical batch release automation buyers before FDA validation timelines lengthen procurement cycles further. For New Entrants and Emerging Players: The premium-to-economy price-point gap in cloud-based SCADA for mid-market electronics facilities offers white-space entry through subscription-tiered deployment models with elastic compute guarantees. Target Indian PLI scheme semiconductor fabrication corridors for greenfield smart factory deployments. Lead with compliance-as-a-service bundling that accelerates BIS IoT certification timelines for Gujarat and Tamil Nadu industrial clusters. For Investors and Strategic Acquirers: FDA 21 CFR Part 11 warning letter issuance to pharmaceutical automation vendors is the leading indicator that validated software assets will command acquisition premiums. Position for 5-10 year consolidation around compliance-focused system integrators with established FDA and EU AI Act conformity assessment track records. Monitor MIIT GB-standard revision announcements for inflection timing on Chinese steel and cement retrofit demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Edge Silicon | Captive supply of inference processors insulates against Taiwan semiconductor shortage cycles and secures sub-50-millisecond latency guarantees for automotive OEMs. |
| EU AI Act Conformity Pre-Certification | Pre-validated quality control modules accelerate CE marking timelines and lock out uncertified competitors from German automotive automation procurement. |
| Outcome-Based Performance Contracting | Risk-sharing uptime guarantees displace equipment sales with recurring revenue streams concentrated in US and German electrification programs. |
| Cloud-Native SCADA Platform Launch | Elastic compute architectures capture mid-market electronics and pharmaceutical buyers seeking capacity expansion without physical construction. |
| System Integrator Channel Acquisition | FactoryTalk-aligned or digital twin-certified partner networks control North American discrete manufacturing and European automotive automation distribution. |
Methodological Framework
Multi-period observation of industrial IoT sensor deployment rates, FDA 21 CFR Part 11 validation timeline data, and MIIT GB-standard revision announcements anchored the trend analysis, supplemented by interviews with plant engineers at German automotive OEMs, pharmaceutical regulatory affairs leads, steel mill maintenance directors, and system integrator channel heads. Secondary validation drew from SEC 10-K filings of industrial automation vendors, ECHA REACH substance restriction updates, customs records for edge compute hardware trade flows, and IEA industrial energy efficiency reports. Bottom-up facility-level deployment tracking and top-down market sizing triangulated volume estimates.
Input-output matrix modeling connected semiconductor supply constraints to edge hardware pricing tiers, regulatory compliance timelines to software procurement specifications, and electrification program schedules to digital twin adoption curves across the projection horizon. Segmentation dimensions spanned technology layer, application function, end-user vertical, and deployment architecture, with regional regulatory cluster as an additional modeling dimension. CAGRs were derived from fitted growth curves against historical adoption patterns and policy mandate enforcement schedules, with automotive electrification investment cycles and pharmaceutical validation backlogs as key forecast inputs.
Underlying measurement precision varies by segment; automotive OEM digital thread deployments carry tighter precision than mid-market electronics cloud migration estimates due to disclosed program timelines. Forecasts embed assumptions regarding MIIT mandate enforcement consistency, EU AI Act conformity assessment capacity, and semiconductor supply normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Latin America Automated Storage and Retrieval System Market
Industrial Automation
Europe Process Automation Market
Industrial Automation
Switzerland Industrial Automation Market
Industrial Automation
Middle East and Africa Industrial Automation Market
Industrial Automation
Asia Pacific Warehouse Automation Market
Industrial Automation
Smart Industries Market
Industrial Automation
Asia-Pacific Automation Components Market
Industrial Automation
Rotary Vector (RV) Reducer Market
Industrial Automation
Europe Sortation Systems Market
Industrial Automation
Europe Automation Components Market
Industrial Automation
South Korea Factory Automation and Industrial Controls Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
US and Europe Warehouse Automation Market
Industrial Automation
Digital Industrial Scales Market
Industrial Automation
Motion Control Drive Market
Industrial Automation
India Warehouse Automation Market