
 Europe Warehouse Automation Systems Market | 2026-2036
Europe Warehouse Automation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Warehouse Automation Systems Market Insights
Multi-source equipment procurement is consolidating as European third-party logistics providers reduce vendor fragmentation. Swisslog Holding AG leverages its KUKA robotics parentage to sustain integrated gripper-to-WMS solutions across German pharmaceutical hubs. SSI Schaefer AG anchors its position through captive steel fabrication and in-house control software development. TGW Logistics Group GmbH differentiates via Austrian-engineered shuttle systems that compete directly with Dematic GmbH's modular pouch sorter lines.
Europe warehouse automation systems encompass electromechanical material handling equipment, control software, and sensor networks orchestrating inventory movement without direct human intervention. Typical installations achieve throughput rates exceeding 20,000 picks per hour in high-density shuttle configurations, with PLC-based controllers coordinating motor drives, barcode scanners, and weight verification modules. Robotic picking segments lead capital deployment as vacuum and gripper technologies mature for polybag and fragile-item handling. AI integration within warehouse management software represents the fastest-expanding technology category, though machine vision still occupies the dominant installed base for barcode and package-dimension verification. Conveyor systems remain the mature workhorse segment where margin pools have compressed to maintenance-service contracts.
CE marking under the EU Machinery Directive and the F-Gas Regulation for cooling-equipped automation shape product certification timelines and component sourcing across European integrator workshops. REACH compliance for battery chemistries in AGV fleets adds material disclosure burdens that favor suppliers with established European compound registration. Stakeholders must monitor how the EU AI Act's risk classification framework will apply to autonomous navigation algorithms before committing to long-term robotic platform roadmaps.
Market Dynamics
Third-party logistics consolidation is compressing vendor ecosystems across European distribution networks, with pharmaceutical and automotive hubs demanding unified gripper-to-WMS platforms that eliminate multi-contractor integration friction.
Growth Catalysts
- EU Green Deal energy mandates:The EU Green Deal pushes integrators toward regenerative drive systems and kinetic energy recovery in shuttle modules, accelerating retrofit cycles in German and Dutch fulfillment centers.
- Robotic picking for fragile-item handling:Vacuum and adaptive gripper technologies mature for polybag and glass-container manipulation, opening pharmaceutical and cosmetics distribution to full automation.
- France's logistics corridor densification:E-commerce fulfillment nodes cluster around Paris-Valenciennes-Lille, concentrating demand for high-throughput AGV fleets and dense storage configurations.
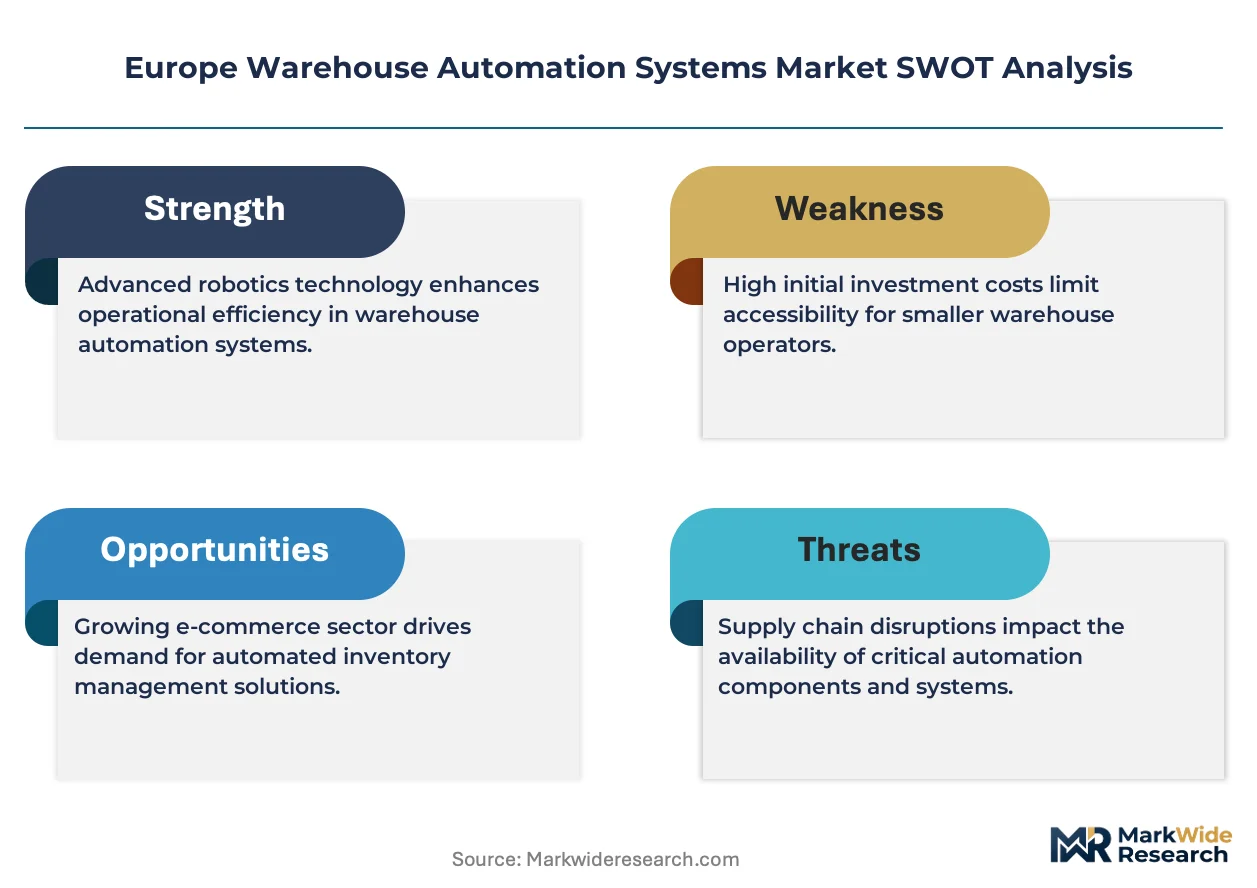
Market Restraints
- CE marking timeline compression:The EU Machinery Directive's conformity assessment procedures extend deployment schedules by four to eight months for complex robotic installations.
- Lithium-ion compound supply concentration:REACH compliance for AGV battery chemistries favors suppliers with established European compound registration, narrowing qualified vendor pools.
- Steel and aluminum input volatility:Captive fabrication capabilities at major integrators buffer against commodity swings that erode margins for pure software-hardware bundlers.
Strategic Opportunities
- Poland and Czech Republic greenfield hubs:Underpenetrated Central European markets offer first-mover positioning for modular shuttle systems serving automotive supplier networks.
- EU AI Act risk classification alignment:Early certification of autonomous navigation algorithms against forthcoming AI Act requirements locks in platform roadmaps before compliance deadlines harden.
- Machine vision and WMS convergence:Real-time dimensioning data feeds directly into inventory optimization engines, compressing picking-path algorithms in high-SKU environments.
Industry Challenges
- PLC programming and mechatronics skill scarcity:Integrators compete for control-systems engineers capable of coordinating multi-axis robotic cells with legacy warehouse management architectures.
- Retrofit integration with existing conveyor infrastructure:Brownfield pharmaceutical sites require phased automation deployment that maintains 99.9% uptime during mechanical overlay installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Warehouse Automation Systems Market |
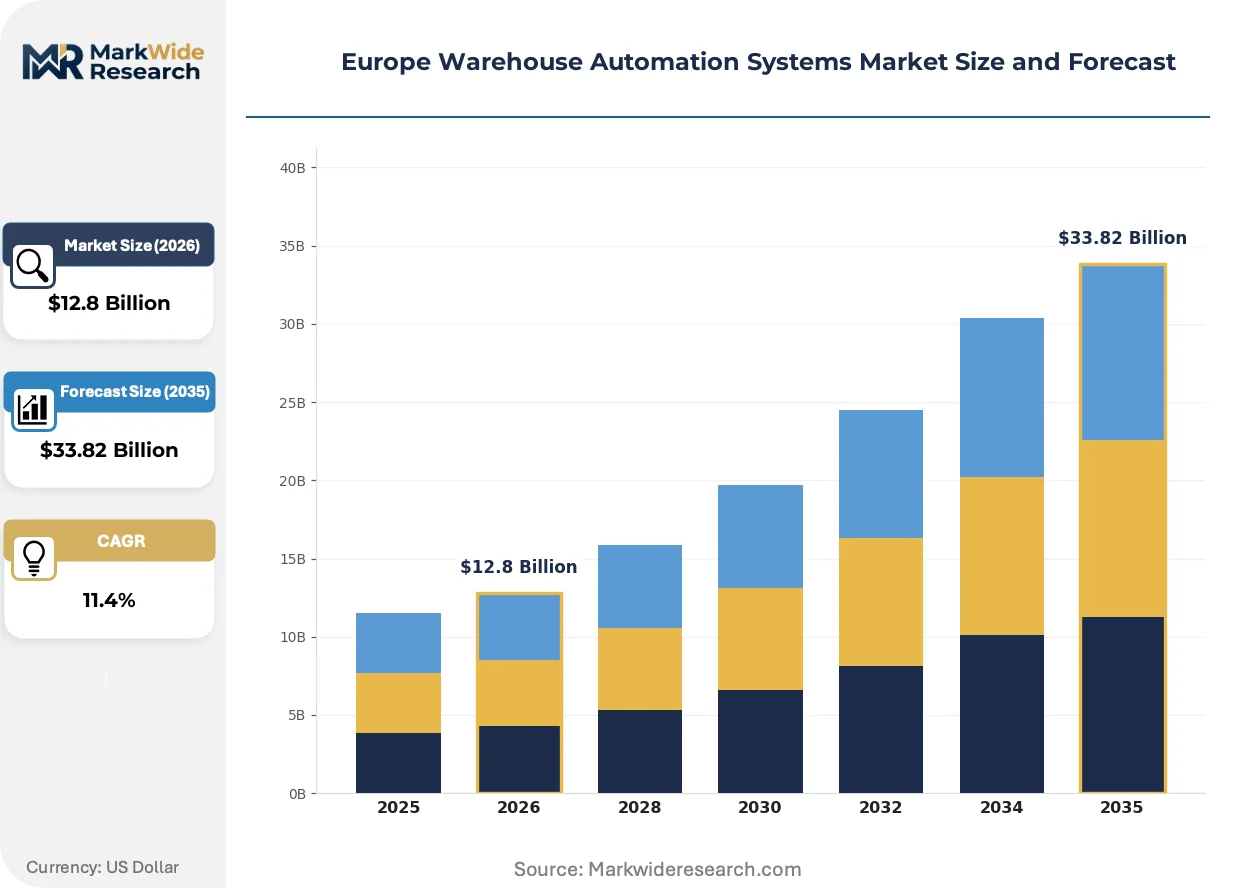
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Automated Guided Vehicles, Robotic Picking, Conveyor Systems, Sortation Systems Technology: IoT Solutions, AI Integration, Machine Vision, Warehouse Management Software End User: E-commerce, Retail, Food & Beverage, Pharmaceuticals Service Type: Installation Services, Maintenance Services, Consulting Services, Training Services |
| Companies Covered | Swisslog Holding AG, SSI Schaefer AG, TGW Logistics Group GmbH, KNAPP AG, Vanderlande Industries B.V., Dematic GmbH, WITRON Logistik + Informatik GmbH, Jungheinrich AG, Mecalux S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Warehouse Automation Systems Market Trends and Innovations
AI-driven orchestration layers are displacing rule-based warehouse management systems across European pharmaceutical and automotive distribution networks, compressing the gap between sensor data and actuator response.
Collaborative robotic arms with force-torque sensing and adaptive grasp planning are automating piece-picking in pharmaceutical fulfillment centers where vial and blister-pack variability previously required human dexterity. German and Dutch third-party logistics providers deploy these systems at pilot scale, with throughput validation cycles running six to twelve months before fleet expansion. The technology is automating quality-control stations that previously bottlenecked at 3,000 picks per hour, now sustaining 8,000-plus with integrated weight verification.
REACH and the F-Gas Regulation tighten material disclosure and thermal-system compliance timelines for automation equipment deployed in temperature-controlled pharmaceutical environments. Integrators must document battery chemistry chains and refrigerant containment specifications before CE marking issuance, extending procurement cycles for cold-chain AGV fleets. Dutch and Belgian pharmaceutical hubs face the steepest compliance ramps due to dense clustering of insulin and vaccine distribution centers.
Consolidated equipment procurement contracts are displacing fragmented multi-vendor sourcing as European third-party logistics providers seek single-point accountability for throughput guarantees. Pharmaceutical distributors in Germany's Rhine-Ruhr corridor now specify unified gripper-to-WMS solutions with penalty clauses for integration failure, compressing vendor selection to integrators with captive steel fabrication and in-house control software. French automotive parts distributors follow at twelve-to-eighteen-month lag, prioritizing modular pouch sorter lines with standardized maintenance protocols.
Europe Warehouse Automation Systems Market Segmentation
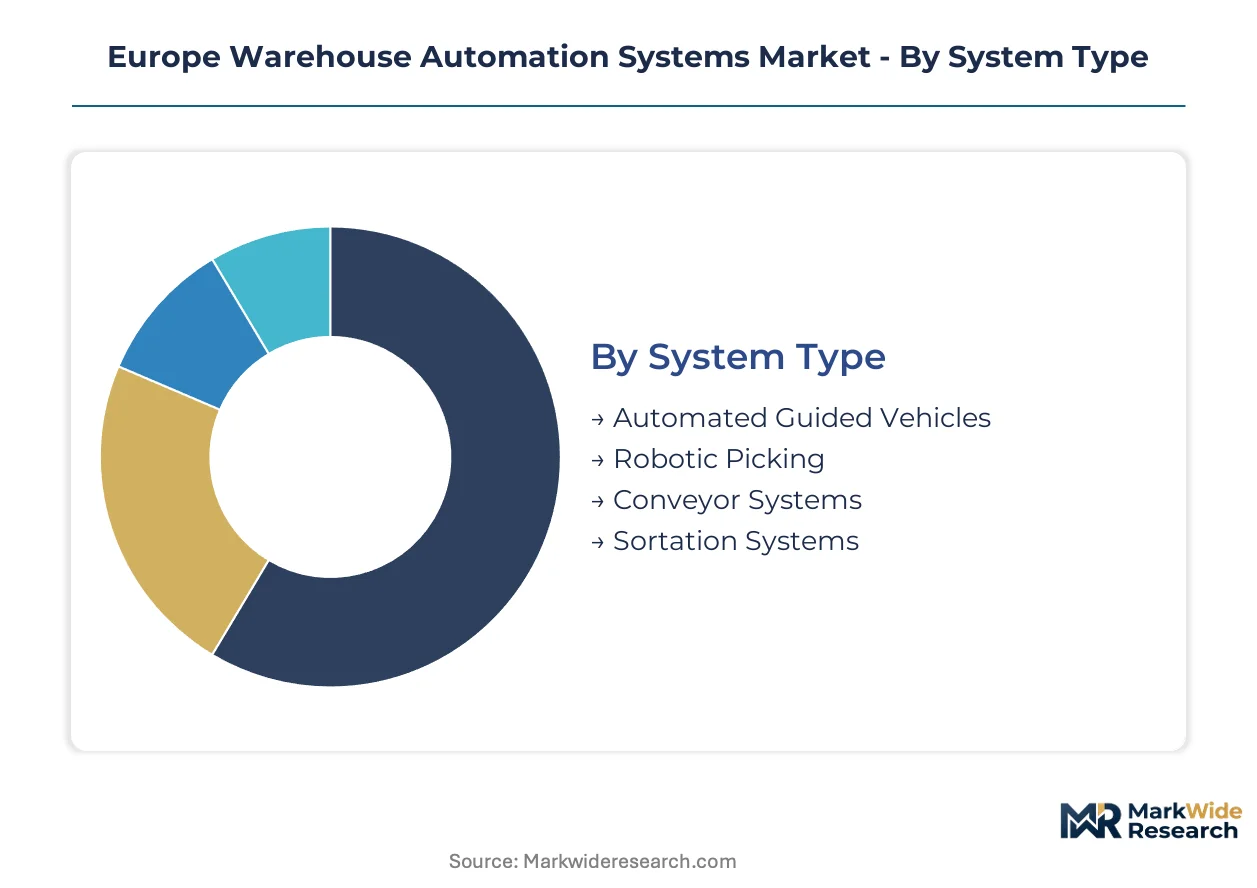
Automation procurement in Europe fragments across equipment categories with divergent capital intensity and integration complexity. Pharmaceutical and e-commerce distributors weight their technology portfolios differently based on throughput requirements and regulatory exposure.
System Type:
Standardized mechanical platforms dominate high-volume lanes while adaptive robotics command premium positioning in variable-SKU environments.
- Automated Guided Vehicles:Battery-powered mobile platforms navigate warehouse floors via magnetic tape, laser guidance, or SLAM-based navigation. Dutch and Belgian pharmaceutical hubs deploy lithium-ion AGV fleets for temperature-controlled insulin distribution under REACH battery disclosure mandates.
- Robotic Picking:Articulated arms with vacuum and adaptive grippers manipulate polybags, vials, and blister packs without human dexterity. German fulfillment centers validate these systems through six-to-twelve-month pilot cycles before fleet scaling.
- Conveyor Systems:Belt and roller configurations remain the installed base workhorse across European distribution networks.
- Sortation Systems:Modular pouch sorters and tilt-tray configurations handle parcel routing at throughput rates exceeding 20,000 units hourly.
Leading the category by volume: Conveyor Systems. Expanding most quickly: Robotic Picking.
Technology:
Software layers extract margin from hardware commoditization as integrators bundle control intelligence with mechanical platforms.
- AI Integration:Neural network-based orchestration compresses picking-path algorithms and demand-forecast accuracy in high-SKU pharmaceutical environments. The EU AI Act's risk classification framework will shape autonomous navigation certification timelines.
- Warehouse Management Software:PLC-based controllers coordinate motor drives, barcode scanners, and weight verification modules across multi-vendor installations. SSI Schaefer and Swisslog bundle proprietary WMS with captive hardware to lock in pharmaceutical accounts.
- Machine Vision:Camera arrays verify package dimensions and barcode readability at throughput bottlenecks.
- IoT Solutions:Sensor networks feed real-time equipment health data into predictive maintenance engines.
Capturing the largest installed base: Machine Vision. Climbing fastest: AI Integration.
End User:
Regulatory exposure and SKU variability determine automation sophistication across vertical applications.
- Pharmaceuticals:CE marking under the EU Machinery Directive and F-Gas Regulation for cooling-equipped automation extend deployment schedules. German Rhine-Ruhr distributors specify unified gripper-to-WMS solutions with penalty clauses for integration failure.
- E-commerce:France's Paris-Valenciennes-Lille corridor clusters fulfillment nodes demanding dense AGV fleets and shuttle storage. Amazon and Zalando drive standardization of modular pouch sorter interfaces.
- Retail:Seasonal demand volatility favors flexible robotic cells over fixed conveyor infrastructure.
- Food & Beverage:Cold-chain compliance adds refrigerant containment documentation burdens to equipment procurement.
Highest automation penetration: Pharmaceuticals. Fastest capital deployment: E-commerce.
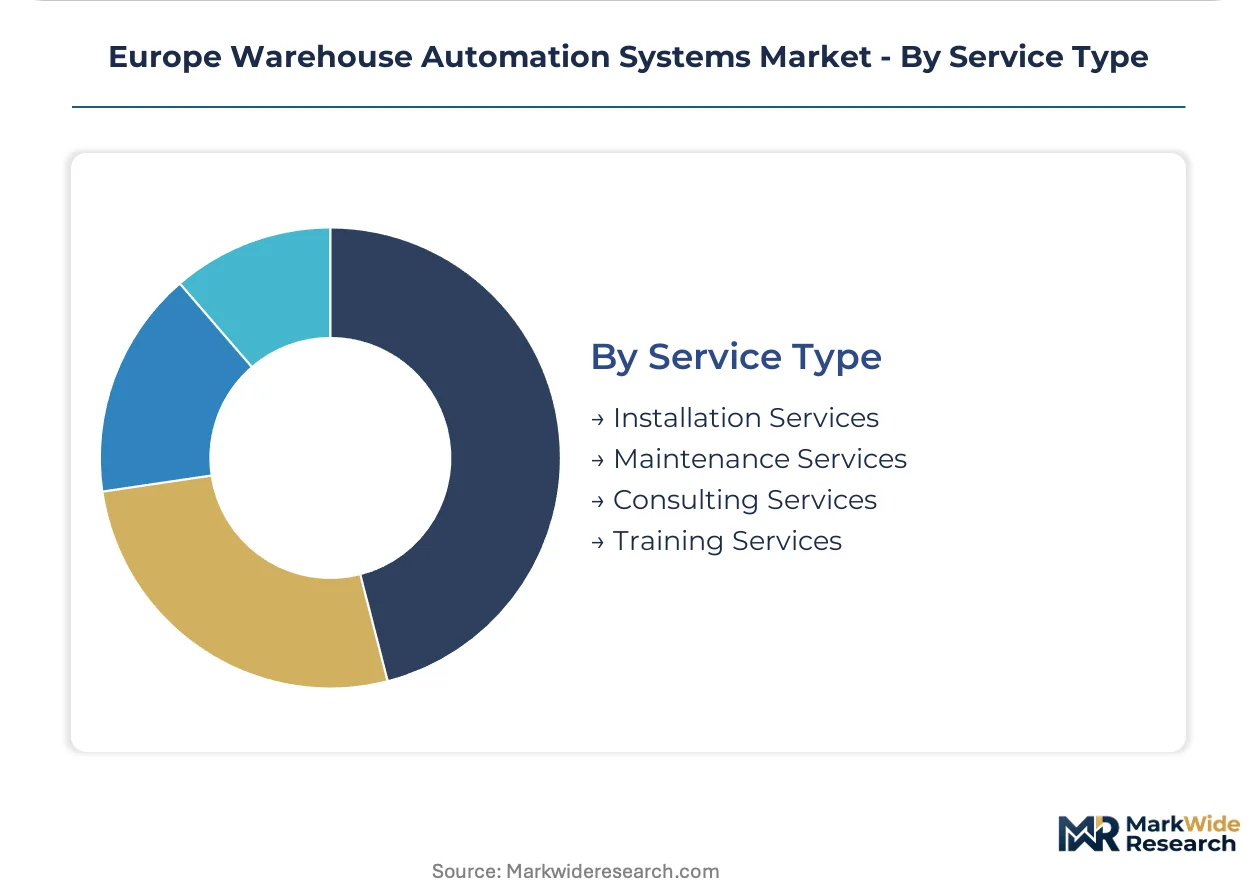
Service Type:
Recurring revenue streams stabilize integrator margins as hardware commoditization compresses upfront equipment pricing.
- Maintenance Services:Preventive and corrective contracts covering PLC firmware updates, motor drive calibration, and sensor replacement. Swisslog and TGW bundle multi-year service agreements with throughput guarantees.
- Installation Services:Mechanical overlay deployment requiring phased cutover to maintain 99.9% uptime in brownfield pharmaceutical sites.
- Consulting Services:Workflow analysis and ROI modeling for greenfield hub design.
- Training Services:PLC programming and mechatronics instruction addressing skill scarcity in control-systems engineering.
Generating the steadiest revenue: Maintenance Services. Fastest-growing attach rate: Consulting Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel fabrication clusters in Germany's Ruhr Valley anchor European warehouse automation manufacturing, with component supply chains radiating outward to assembly workshops in Austria, the Netherlands, and Switzerland.
Germany
Automotive and pharmaceutical distribution networks in the Rhine-Ruhr corridor demand high-throughput shuttle systems and unified gripper-to-WMS platforms. CE marking under the EU Machinery Directive extends deployment schedules for complex robotic installations. Stuttgart and Munich host integrator engineering centers developing PLC-based controllers for pan-European deployment.
Netherlands
Rotterdam and Venlo cluster e-commerce fulfillment nodes requiring dense AGV fleets for cross-dock operations. REACH compliance for lithium-ion battery chemistries in automated vehicle fleets adds material disclosure burdens that favor established European compound registrants. Dutch pharmaceutical hubs face steep F-Gas Regulation compliance ramps for cold-chain automation.
France
The Paris-Valenciennes-Lille logistics corridor concentrates demand for modular pouch sorters and robotic picking cells serving cosmetics and pharmaceutical distribution. The EU AI Act's forthcoming risk classification framework shapes autonomous navigation certification timelines for French integrators. Lyon hosts specialized machine vision development for barcode verification systems.
Austria
Shuttle system engineering expertise concentrates around Graz and Vienna, with Austrian-engineered storage and retrieval modules competing directly with German pouch sorter lines. The EU Green Deal's regenerative drive mandates accelerate retrofit cycles in Austrian-built systems deployed across Central Europe. Domestic integrators leverage captive mechatronics talent pools for control software development.
Poland
Underpenetrated Central European markets offer greenfield positioning for modular automation serving automotive supplier networks around Wrocław and Poznań. Polish logistics operators prioritize phased brownfield deployment that maintains uptime during mechanical overlay installation. Warsaw-based distributors specify standardized maintenance protocols to reduce multi-vendor integration friction.
Europe Warehouse Automation Systems Market Competitive Landscape
Global majors compete with regional champions across engineering depth and captive fabrication capabilities, producing a tiered structure where integrated hardware-software bundlers hold pharmaceutical accounts while specialized shuttle engineers dominate dense storage configurations. Three archetypes populate the vendor base: steel-fabricating integrators with in-house control development, robotics-parented solution providers leveraging gripper-to-WMS integration, and modular subsystem specialists licensing shuttle or sorter mechanics to third-party installers. Competitive moves concentrate on multi-year service contracts with throughput guarantees and early alignment with EU AI Act risk classifications for autonomous navigation platforms.
Among German fabricators with captive steel production, SSI Schaefer AG and WITRON Logistik + Informatik GmbH exemplify the vertically integrated archetype controlling component supply through in-house workshop capacity. Swisslog Holding AG represents the robotics-parented model, leveraging KUKA lineage for integrated arm-to-software solutions. These three occupy positions across the premium-tier contract spectrum where pharmaceutical distributors specify penalty clauses for integration failure.
| Leading Market Players |
|---|
| Swisslog Holding AG |
| SSI Schaefer AG |
| TGW Logistics Group GmbH |
| KNAPP AG |
| Vanderlande Industries B.V. |
| Dematic GmbH |
| WITRON Logistik + Informatik GmbH |
| Jungheinrich AG |
| Mecalux S.A. |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical distributor consolidation across Germany's Rhine-Ruhr corridor is forcing integrators toward unified gripper-to-WMS platforms with penalty-backed throughput guarantees, compressing vendor selection to steel-fabricating bundlers with captive control software development and squeezing margin pools for pure hardware vendors.
Pricing Analysis
Throughput-guarantee bundling now dominates contract structures, with premium tiers covering multi-year maintenance and PLC firmware updates while economy positioning strips out installation services. Price differentiation rests on CE marking pre-certification status and captive steel fabrication capacity. Pricing pressure intensifies in conveyor system segments where margin pools have compressed to service-contract residuals. E-commerce fulfillment centers exhibit highest price sensitivity due to volume-scale procurement, while pharmaceutical hubs prioritize integration reliability over unit cost.
Supply Chain Analysis
EU Green Deal local-content preferences for regenerative drive systems are reshaping component sourcing toward German and Austrian motor-drive suppliers. Steel and aluminum inputs draw from Ruhr Valley fabrication clusters and Swiss precision-machining centers. Battery cell supply for AGV fleets rests on established European REACH registrants, creating single-source vulnerability for non-compliant vendors. Distribution runs through integrator-owned assembly workshops with direct-to-site mechanical overlay deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act risk classification timelines are elevating compliance costs for autonomous navigation platforms, erecting certification barriers that favor incumbents with established regulatory affairs infrastructure and documented algorithm audit trails.
For Market Incumbents: Deploy captive mechatronics talent pools to accelerate PLC-based controller development for brownfield pharmaceutical retrofits. Consolidate position through multi-year service contracts with 99.9% uptime guarantees that lock out modular subsystem specialists. Counter emerging shuttle-system competitors by deepening in-house steel fabrication capacity and control software bundling. For New Entrants and Emerging Players: Enter via Poland and Czech Republic greenfield automotive supplier networks where unified gripper-to-WMS penetration remains underdeveloped. Target modular shuttle system deployment with standardized maintenance protocols as the most penetrable wedge. Pursue consulting-led go-to-market positioning that front-loads workflow analysis before equipment specification. For Investors and Strategic Acquirers: The window for entry favors steel-fabricating integrators with captive control software development and established CE marking track records. Over the medium-term horizon, acquisition targets should demonstrate documented EU AI Act alignment progress for autonomous navigation algorithms. Watch for F-Gas Regulation enforcement intensity in Dutch and Belgian pharmaceutical hubs as inflection signal for cold-chain automation demand.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Risk Classification Alignment | Early certification locks in platform roadmaps before compliance deadlines harden for autonomous navigation. |
| Captive Steel Fabrication Expansion | Ruhr Valley workshop capacity buffers commodity volatility and accelerates CE marking timelines. |
| Multi-Year Service Contract Bundling | Throughput guarantees with pharmaceutical distributors create recurring revenue moats against modular competitors. |
| Machine Vision-WMS Convergence | Real-time dimensioning data feeds compress picking-path algorithms in high-SKU environments. |
| Central European Greenfield Positioning | Polish and Czech automotive supplier networks offer first-mover positioning for modular shuttle systems. |
Research Methodology
Document review covered EU Machinery Directive implementation guidance, ECHA REACH substance registration databases, and integrator technical documentation, complemented by interviews with warehouse operations directors at German pharmaceutical distributors, automation procurement leads at Dutch third-party logistics providers, control systems engineers at Austrian shuttle manufacturers, and aftermarket service heads at steel-fabricating integrators. Secondary validation drew from customs trade data for material handling equipment, SEC filings of robotics-parented solution providers, and EU Green Deal policy implementation trackers. Bottom-up equipment shipment analysis and top-down end-user capital expenditure surveys were triangulated.
Historical installation data was cross-referenced against panel input from integrator engineering centers to model deployment trajectories across the projection horizon. Segmentation dimensions included system type, technology layer, end-user vertical, and service attachment rate. CAGRs were derived from equipment order backlog analysis and capital commitment patterns. Industry-specific forecast inputs incorporated EU AI Act regulatory timeline assumptions and F-Gas Regulation compliance cost trajectories for cold-chain automation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act enforcement intensity variations and lithium-ion compound supply disruptions. Forecasts reflect documented assumptions regarding regulatory implementation schedules and technology maturation curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Assembly Line Solutions Market
Industrial Automation
Factory Automation Platform As a Service Market
Industrial Automation
Distribution Feeder Automation Market
Industrial Automation
Mini-Load Systems Market
Industrial Automation
Industrial Automation Software Market
Industrial Automation
Model Based Manufacturing Technologies Market
Industrial Automation
North America Process Automation Market
Industrial Automation
HMI Market
Industrial Automation
North America Machine Control System Market
Industrial Automation
Intelligent Conveyor System Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
Asia-Pacific Programmable Logic Controller Market
Industrial Automation
Factory Automation Market
Industrial Automation
Middle East and Africa Industrial Automation Market
Industrial Automation
North America Industrial Vending Machine Market
Industrial Automation
Asia Pacific Warehouse Automation Market