
 North America Freight and Logistics Market | 2026-2036
North America Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Freight and Logistics Market Analytics
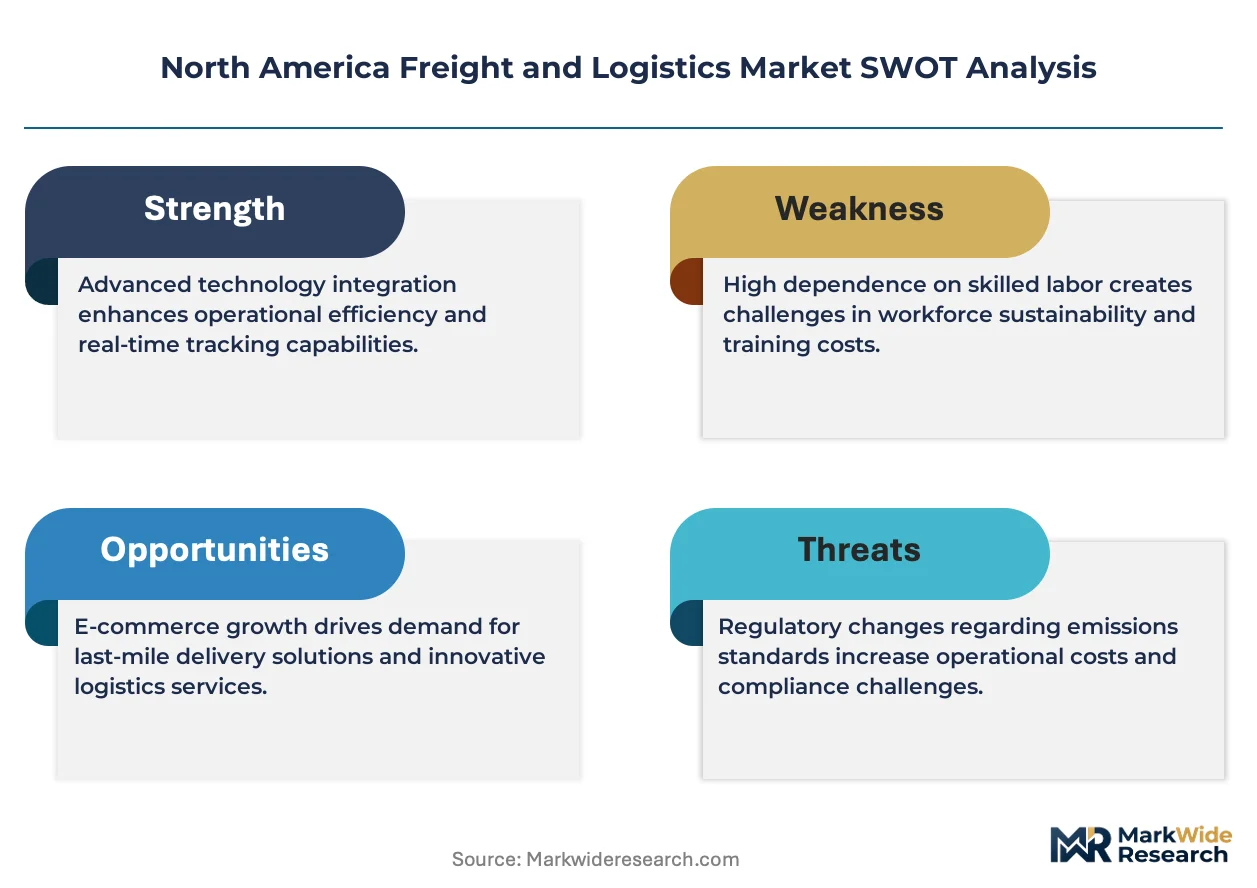
The EPA Phase 3 greenhouse gas standards for heavy-duty vehicles is rebalancing capital allocation across North American trucking fleets, raising compliance costs for smaller operators while advantaging scaled players. JB Hunt leverages its intermodal density and private fleet scale to absorb regulatory costs without rate disruption. Old Dominion Freight Line sustains superior operating ratios through disciplined terminal density and minimal reliance on brokered capacity. FedEx Freight navigates the same emissions trajectory by accelerating electric vehicle pilots in California corridors.
North America Freight and Logistics encompasses the physical movement, storage, and customs facilitation of goods across road, rail, air, and maritime networks, typically measured by ton-miles, dwell time, and line-haul cost per hundredweight. Its primary purpose is synchronizing inventory flows with manufacturing schedules and consumer delivery expectations across integrated supply chains. Transportation services generate the largest revenue pool but face compressed margins from fuel volatility and driver availability constraints. Warehousing commands expanding margin contribution as e-commerce end users demand same-day and next-day fulfillment infrastructure. AI and automation technologies within the technology segment represent the fastest-growing investment category as operators deploy predictive routing and autonomous yard management to offset labor scarcity.
The Federal Motor Carrier Safety Administration governs hours-of-service rules and safety fitness determinations that directly constrain trucking capacity and insurance costs across US lanes. Transport Canada and the Canadian Trucking Alliance coordinate cross-border equipment standards and driver credential reciprocity that shape north-south freight fluidity. Mexico's Secretariat of Infrastructure, Communications and Transport oversees port and rail concession terms that influence nearshoring cargo routing decisions. Stakeholders must weigh regulatory compliance timelines against infrastructure deployment cycles as emissions rules, border modernization, and automation thresholds converge.
Market Dynamics
EPA Phase 3 greenhouse gas standards for heavy-duty vehicles are forcing fleet operators to reallocate capital toward electrification and alternative fuel infrastructure, compressing margins for asset-light carriers while rewarding scaled players with private charging networks and intermodal density.
Growth Catalysts
- Nearshoring manufacturing flows:Mexico's Secretariat of Infrastructure, Communications and Transport has expanded port and rail concession capacity along the Texas-Mexico border corridor, drawing container volume away from transpacific lanes.
- EPA regulatory compliance deadlines:Fleet electrification mandates are accelerating investment in battery-electric tractors and hydrogen fuel cell pilot programs across California and Texas freight corridors.
- AI-powered predictive routing:Machine learning platforms are reducing empty miles and dwell time in yard operations, directly addressing driver availability constraints through automation of dispatch and load matching.
Market Restraints
- Driver labor scarcity:The Federal Motor Carrier Safety Administration's hours-of-service rules cap available driving hours, constraining capacity expansion even as freight demand rises.
- Charging infrastructure gaps:Electrification rollout faces site acquisition delays and utility interconnection backlogs, particularly in secondary markets beyond California and Texas.
- Diesel price volatility:Fuel cost swings compress margins for carriers without fuel surcharge mechanisms or private fleet scale to negotiate long-term supply contracts.
Strategic Opportunities
- Cross-border customs automation:Transport Canada and the Canadian Trucking Alliance are piloting digital credential reciprocity systems that could accelerate north-south freight fluidity and reduce border dwell time.
- Autonomous yard management:Convergence of computer vision and robotics is creating unattended gate operations and automated trailer positioning at distribution centers.
- Same-day fulfillment infrastructure:E-commerce end users in Southern California and Dallas-Fort Worth are driving demand for urban micro-fulfillment centers with direct last-mile injection capability.
Industry Challenges
- Technician skill gaps:High-voltage battery maintenance and fuel cell system repair require specialized certifications that existing diesel mechanic workforces lack, slowing fleet electrification timelines.
- Interoperability complexity:Integration of telematics, warehouse management systems, and carrier platforms demands API standardization that fragmented software vendors have not achieved.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Freight and Logistics Market |
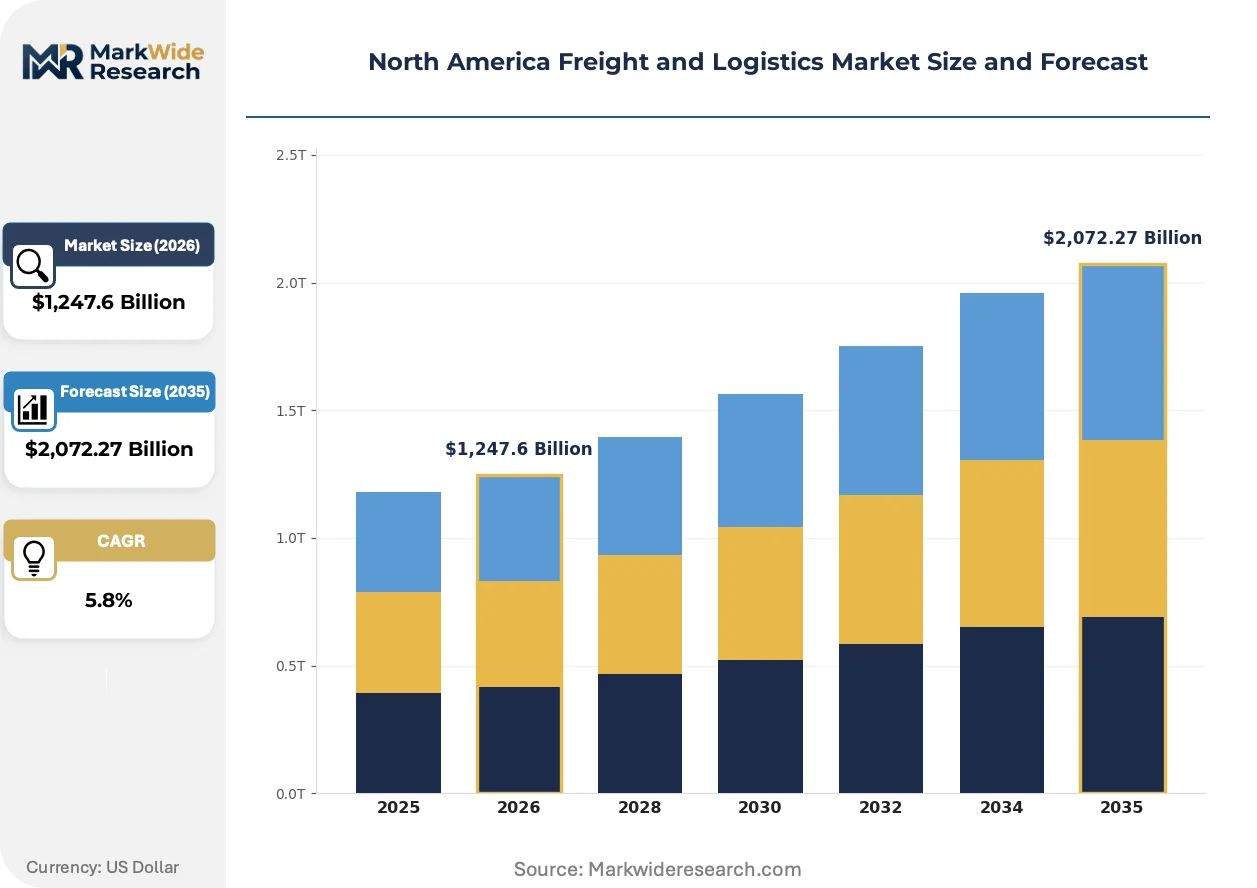
| Market Size in 2026 | $1,247.6 Billion |
| Market Size in 2035 | $2,072.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Customs Brokerage End User: E-commerce, Manufacturing, Retail, Automotive Technology: IoT, Blockchain, AI, Automation Distribution Channel: Direct Sales, Online Platforms, Third-party Providers, Brokers |
| Companies Covered | ABF Freight, Schneider, FedEx Freight, C.H. Robinson, Knight-Swift, XPO Logistics, JB Hunt, RXO, Old Dominion Freight Line, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Freight and Logistics Market Evolving Landscape
Technology deployment across North American freight networks is absorbing capital at unprecedented rates as operators automate to offset structural labor constraints. Three distinct innovation trajectories are reshaping competitive positioning.
Autonomous yard trucks are absorbing repetitive trailer-movement tasks at major distribution hubs. Walmart and Amazon fulfillment centers in California and Texas have deployed pilot fleets of self-driving terminal tractors operating in geofenced environments. This technology is absorbing labor hours previously lost to chassis repositioning and gate congestion, compressing turnaround times by fifteen to twenty percent at high-volume facilities.
The EPA Phase 3 greenhouse gas standards are mandating fleet-wide emissions reductions through model year 2032. Heavy-duty truck manufacturers must achieve cumulative carbon dioxide cuts of approximately sixty percent versus current baselines, forcing accelerated powertrain diversification. California's Advanced Clean Trucks regulation extends these mandates to medium-duty segments, with the state's Air Resources Board enforcing sales quotas for zero-emission vehicles.
Shippers are consolidating freight procurement through digital freight matching platforms that displace traditional broker relationships. Large retail and manufacturing accounts now allocate thirty to forty percent of spot volume through algorithmic pricing engines rather than contracted carrier networks. This behavioral shift is most visible in the Southern California port hinterland, where drayage capacity is increasingly accessed through app-based dispatch rather than long-term service agreements.
North America Freight and Logistics Market Segmentation
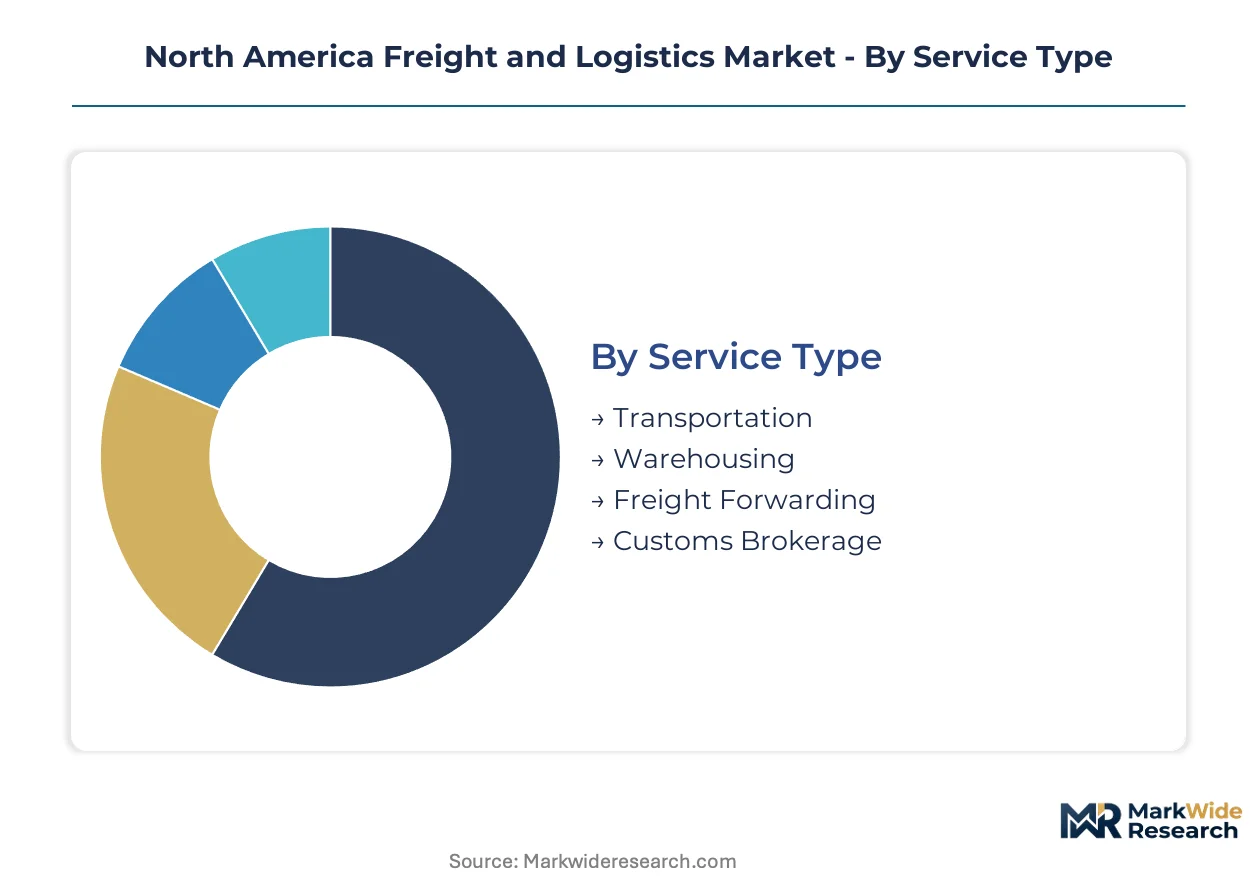
Segmentation reveals how capital flows diverge across North American freight networks. Transportation services generate volume revenue pools while warehousing captures expanding margins from e-commerce fulfillment compression.
Service Type:
Transportation dominates ton-mile volume. Warehousing commands premium pricing from inventory velocity demands.
- Transportation:Road, rail, air, and maritime modes move goods across the Texas-Mexico corridor and Southern California port hinterland. Fleet electrification investments under EPA Phase 3 standards are raising asset intensity for trucking operators while intermodal density rewards scaled players.
- Warehousing:E-commerce fulfillment centers and distribution facilities synchronize inventory with last-mile injection points. Demand concentrates in Dallas-Fort Worth and Inland Empire submarkets where same-day delivery radii overlap with population density.
- Freight Forwarding:Third-party coordinators manage multimodal routing and customs documentation for cross-border manufacturing flows.
- Customs Brokerage:Regulatory compliance services facilitate north-south cargo clearance through digital credential systems piloted by Transport Canada.
Today's leader: Transportation. Tomorrow's challenger: Warehousing.
End User:
Manufacturing anchors contracted capacity. E-commerce is disrupting procurement patterns.
- E-commerce:Digital retail platforms demand micro-fulfillment infrastructure with direct last-mile capability. Southern California and Texas urban clusters are absorbing the densest warehousing investment as delivery windows compress toward same-day thresholds.
- Manufacturing:Automotive and industrial producers synchronize inbound parts flows with assembly schedules through dedicated fleet contracts and cross-dock facilities. Nearshoring flows through Mexico are reallocating volume from transpacific lanes to overland corridors.
- Retail:Omnichannel distributors balance store replenishment with direct-to-consumer fulfillment from shared inventory pools.
- Automotive:Just-in-sequence parts delivery requires precise arrival windows at assembly plants, favoring dedicated contract carriage over spot market exposure.
E-commerce expands most quickly. Manufacturing retains the deepest contract moats.
Technology:
Automation reduces labor dependency. AI optimizes asset utilization.
- AI:Machine learning platforms reduce empty miles through predictive routing and dynamic load matching. California and Texas freight corridors are deploying these systems to offset driver availability constraints under Federal Motor Carrier Safety Administration hours-of-service caps.
- Automation:Autonomous yard trucks and robotic trailer positioning compress turnaround times at high-volume distribution centers. Walmart and Amazon fulfillment hubs in geofenced environments are absorbing fifteen to twenty percent labor hour reductions.
- IoT:Sensor networks provide real-time visibility into location, temperature, and shock events across refrigerated and high-value cargo lanes.
- Blockchain:Distributed ledger applications streamline customs documentation and reduce border dwell time through immutable credential verification.
Automation commands capital deployment today. AI offers the steepest expansion trajectory.
Distribution Channel:
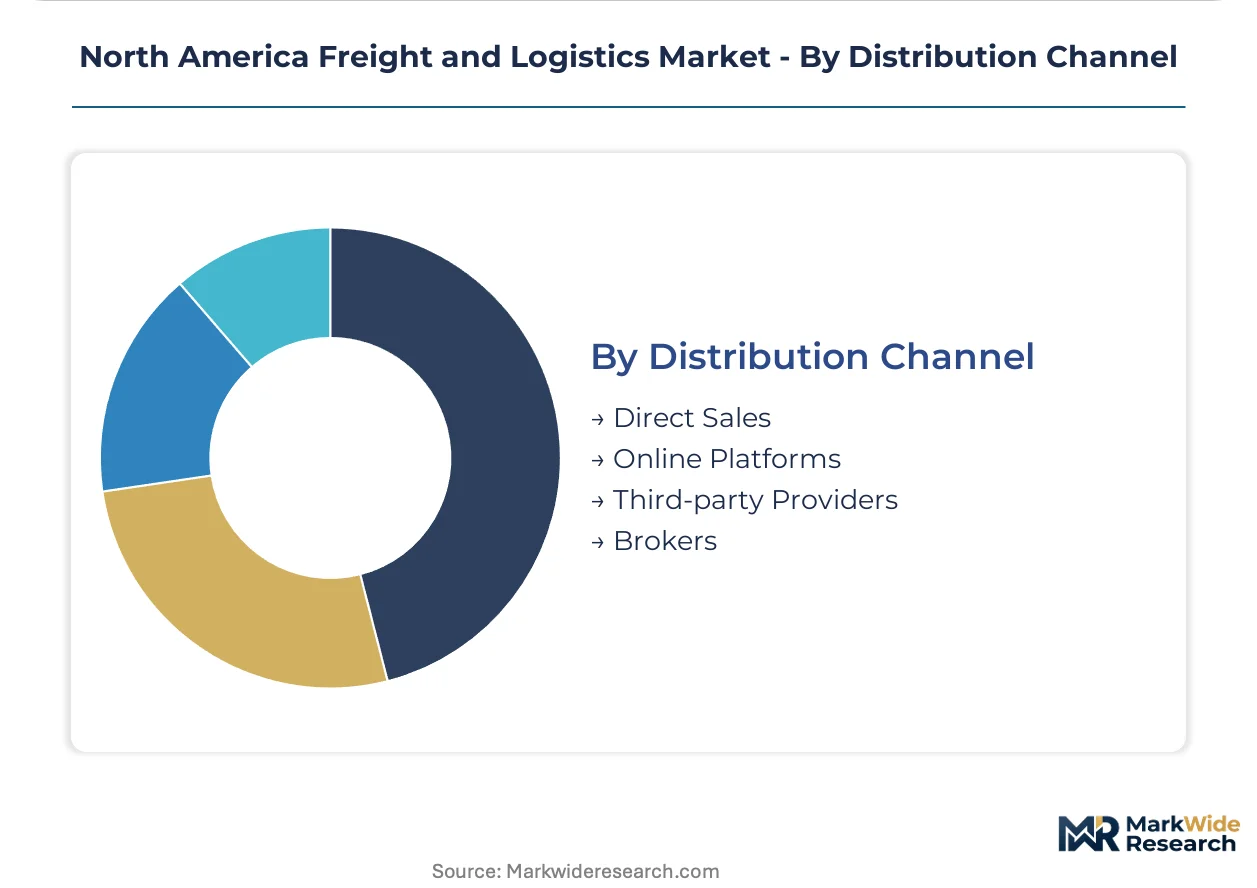
Direct sales anchor contracted revenue. Digital platforms are fragmentating spot procurement.
- Third-party Providers:Integrated logistics operators bundle transportation, warehousing, and customs services under single accountability structures. Scaled players absorb regulatory compliance costs that compress margins for smaller competitors.
- Brokers:Traditional intermediaries face displacement as algorithmic pricing engines capture thirty to forty percent of spot volume from large retail accounts.
- Direct Sales:Asset-based carriers maintain dedicated relationships with manufacturing and automotive shippers through multi-year capacity commitments.
- Online Platforms:Digital freight matching applications connect shippers with available capacity through app-based dispatch, concentrated in Southern California drayage markets.
Third-party providers hold position. Online platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trucking workforce density along the Texas-Mexico border corridor anchors North American logistics capacity. California's port hinterland concentrates drayage operators and warehousing labor pools. Canadian cross-border drivers and Mexican manufacturing logistics specialists complete the regional talent distribution.
United States
Southern California's Inland Empire and Dallas-Fort Worth absorb the densest warehousing investment as e-commerce fulfillment compresses delivery windows toward same-day thresholds. The EPA Phase 3 greenhouse gas standards for heavy-duty vehicles mandate fleet-wide emissions reductions through model year 2032, accelerating battery-electric tractor deployments. California's Advanced Clean Trucks regulation extends zero-emission vehicle sales quotas to medium-duty segments, with the Air Resources Board enforcing compliance across the state's freight corridors.
Canada
Cross-border manufacturing flows through Ontario and Quebec generate dedicated fleet contracts for automotive parts and industrial components. Transport Canada coordinates equipment standards reciprocity with US regulators under the Federal Motor Carrier Safety Administration framework. The Windsor-Detroit corridor concentrates the heaviest truck crossing volume between the two countries, with digital credential pilot programs reducing border dwell time for qualified carriers.
Mexico
Nearshoring manufacturing expansion across Nuevo León and the Bajío Region reallocates container volume from transpacific lanes to overland corridors. Mexico's Secretariat of Infrastructure, Communications and Transport oversees expanded port and rail concession capacity along the Texas-Mexico border. Laredo and the broader border logistics corridor absorb the densest cross-border trucking activity as manufacturing supply chains regionalize.
North America Freight and Logistics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented service tiers. The vendor base spans asset-heavy trucking operators, asset-light brokerage platforms, and integrated third-party logistics providers with bundled warehousing and customs capabilities. Three archetypes dominate: scaled intermodal operators with private fleet density, terminal-density less-than-truckload specialists, and digital freight matching platforms disrupting spot procurement. Consolidation pressure favors M&A activity among mid-cap regional carriers, while technology partnerships between established operators and autonomous vehicle developers accelerate automation deployment.
Among asset-based trucking operators, JB Hunt and Old Dominion Freight Line exemplify divergent scale strategies within the sector. JB Hunt occupies a position anchored by intermodal density and private fleet scale that absorbs regulatory compliance costs without rate disruption. Old Dominion Freight Line exemplifies the terminal-density specialist archetype, sustaining superior operating ratios through disciplined network configuration and minimal reliance on brokered capacity. FedEx Freight represents the integrated parcel-less-than-truckload hybrid model, navigating emissions trajectories through accelerated electric vehicle pilots in California corridors.
| Leading Market Players |
|---|
| ABF Freight |
| Schneider |
| FedEx Freight |
| C.H. Robinson |
| Knight-Swift |
| XPO Logistics |
| JB Hunt |
| RXO |
| Old Dominion Freight Line |
| Others |
Value Network & Pricing Analysis
EPA Phase 3 greenhouse gas standards for heavy-duty vehicles gate qualified supply and premium-tier pricing access, as carriers with compliant fleets command rate premiums while non-compliant operators face margin compression from regulatory exclusion.
Pricing Analysis
Bundled service contracts dominate transportation procurement, though unbundled spot pricing gains share through digital freight matching platforms. Three-tier pricing structure across premium, standard, and economy levels reflects service reliability, equipment compliance status, and dedicated capacity guarantees. Price differentiation centers on EPA certification tier and intermodal density scale. Pricing pressure stems from driver labor scarcity under Federal Motor Carrier Safety Administration hours-of-service caps. Manufacturing shippers show least price sensitivity due to just-in-sequence delivery requirements, while spot market retail accounts exhibit highest sensitivity.
Supply Chain Analysis
SmartWay certification and EPA compliance credentials gate carrier participation in shipper networks, filtering supply toward qualified operators. Equipment manufacturing concentrates in the United States, Mexico, and Canada through integrated North American production corridors. Battery-electric tractors and hydrogen fuel cell systems draw from lithium, rare earth, and semiconductor inputs. Single-source vulnerability runs through specialized high-voltage component suppliers. Distribution runs through direct sales relationships for contracted manufacturing volumes and app-based platforms for spot drayage capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as e-commerce fulfillment demands compress delivery windows toward same-day thresholds, rewarding operators with premium infrastructure density.
For Market Incumbents: Hedge regulatory compliance exposure by accelerating private charging network deployment in California and Texas corridors. Deepen intermodal density to absorb EPA Phase 3 costs without rate disruption. Counter digital freight matching encroachment through embedded shipper relationships with multi-year capacity commitments. For New Entrants and Emerging Players: Begin with autonomous yard management pilots at high-volume distribution hubs in Dallas-Fort Worth and Inland Empire submarkets. Target secondary markets beyond California and Texas where charging infrastructure gaps delay incumbent electrification timelines. Pursue technology licensing partnerships with established carriers rather than asset-heavy fleet buildouts. For Investors and Strategic Acquirers: Valuations sit cheapest among terminal-density less-than-truckload specialists with disciplined network configuration and minimal brokered capacity reliance. Long-term viability favors scaled intermodal operators with private fleet density and cross-border customs automation capabilities. Monitor EPA enforcement intensity and zero-emission vehicle sales quota compliance as inflection signals for carrier restructuring activity.| Strategic Initiative | Industry Significance |
|---|---|
| Private Charging Network Deployment | EPA Phase 3 compliance secures rate premiums and shipper network access for qualified carriers. |
| Autonomous Yard Management Pilot | Walmart and Amazon fulfillment hubs achieve fifteen to twenty percent labor hour reductions through geofenced automation. |
| Cross-Border Customs Automation | Transport Canada digital credential reciprocity accelerates north-south freight fluidity and reduces border dwell time. |
| Intermodal Density Expansion | JB Hunt's rail-highway integration absorbs regulatory costs without disrupting contracted rate structures. |
| Digital Freight Matching Platform |
Research Methodology
Direct dialogue with fleet operations directors, shipper procurement managers, intermodal terminal supervisors, and regulatory compliance officers grounded qualitative findings in operational reality. Secondary validation drew from Federal Motor Carrier Safety Administration enforcement data, EPA certification databases, Transport Canada cross-border statistics, and SEC filings from publicly traded carriers. Bottom-up triangulation across carrier capacity reports and top-down reconciliation against customs trade flows ensured methodological rigor.
Segmented outputs across service type, end user, technology deployment, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs derived from freight volume trends, equipment replacement cycles, and regulatory compliance timelines. Forecast inputs incorporated EPA Phase 3 implementation schedules, nearshoring manufacturing relocation patterns, and e-commerce fulfillment infrastructure investment trajectories.
Caveats apply where EPA enforcement intensity, charging infrastructure deployment delays, or cross-border trade policy shifts could materially shift the outlook. Forecasts reflect assumptions about regulatory timelines and technology cost curves. A model refresh is warranted upon material change in zero-emission vehicle adoption rates or federal emissions rulemaking.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
High-Tech Logistics Market
Logistics and Shipping
Egypt Third Party Logistics (3PL) Market
Logistics and Shipping
Europe Container Terminal Operations Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
China Freight Forwarding Market
Logistics and Shipping
Colombia Freight and Logistics Market
Logistics and Shipping
Latin America Container Terminal Operations Market
Logistics and Shipping
Poland Freight and Logistics Market
Logistics and Shipping
Thailand Cold Chain Logistics Market
Logistics and Shipping
Hungary Third Party Logistics (3PL) Market
Logistics and Shipping
North America Cargo Handling Equipment Market
Logistics and Shipping
Air Cargo Container Market
Logistics and Shipping
Smart Shipping Containers Market
Logistics and Shipping
Global 3PL in Cold Chain Logistics Market
Logistics and Shipping
Global Courier Market
Logistics and Shipping
Government and Education Logistics Market