
 North America Electric Bus Market | 2026-2036
North America Electric Bus Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Bus Market Outlook
Transit agency procurement is rebalancing from fragmented pilot orders toward consolidated fleet-scale contracts. Proterra Inc. anchors the battery-electric segment through integrated powertrain manufacturing. BYD Motors Inc. leverages its North American assembly footprint to compete on delivery timelines for large municipal orders. NFI Group Inc. sustains its position via dual-brand production capacity across the United States and Canada.
North America electric buses are heavy-duty vehicles propelled by electric motors drawing energy from onboard battery packs or fuel cells, with lithium-ion configurations currently dominating due to energy density thresholds exceeding 250 Wh per kilogram. These vehicles serve to eliminate tailpipe emissions from high-utilization passenger transport routes while reducing lifetime operating costs through lower fuel and maintenance expenditures. Battery electric configurations lead volume deployment among bus type categories, while fuel cell variants represent the fastest-growing sub-segment for extended-range corridor applications. Public transportation end users command the largest share of current orders, though school districts are emerging as a concentrated margin pool driven by dedicated federal grant streams.
The US Environmental Protection Agency administers the Clean School Bus Program, which directs competitive rebate funding toward zero-emission vehicle procurement by school districts. The Federal Transit Administration coordinates capital assistance programs that prioritize electrification projects in urbanized areas. California Air Resources Board enforces the Innovative Clean Transit regulation, which mandates complete transition to zero-emission bus fleets by 2040 for the state's largest operators. Stakeholders must monitor the interplay between federal appropriation continuity and state-level zero-emission fleet deadlines to calibrate production capacity and service network investments.
Market Dynamics
Fleet-scale electrification mandates from California Air Resources Board and the EPA's Clean School Bus Program are compressing procurement timelines and forcing manufacturers to reconfigure production capacity around multi-year municipal contracts rather than fragmented pilot deployments.
Growth Catalysts
- California Air Resources Board's Innovative Clean Transit regulation:This mandate requires the state's largest transit operators to achieve complete zero-emission bus fleet conversion by 2040, creating predictable long-term demand corridors for manufacturers.
- School districts:Dedicated federal grant streams through the EPA's Clean School Bus Program are channeling competitive rebate funding toward zero-emission vehicle procurement, establishing a concentrated margin pool distinct from municipal transit.
- Lithium-ion battery energy density:Configurations now exceeding 250 watt-hours per kilogram are enabling extended route operations without midday charging infrastructure, expanding addressable service territory for electric bus deployments.
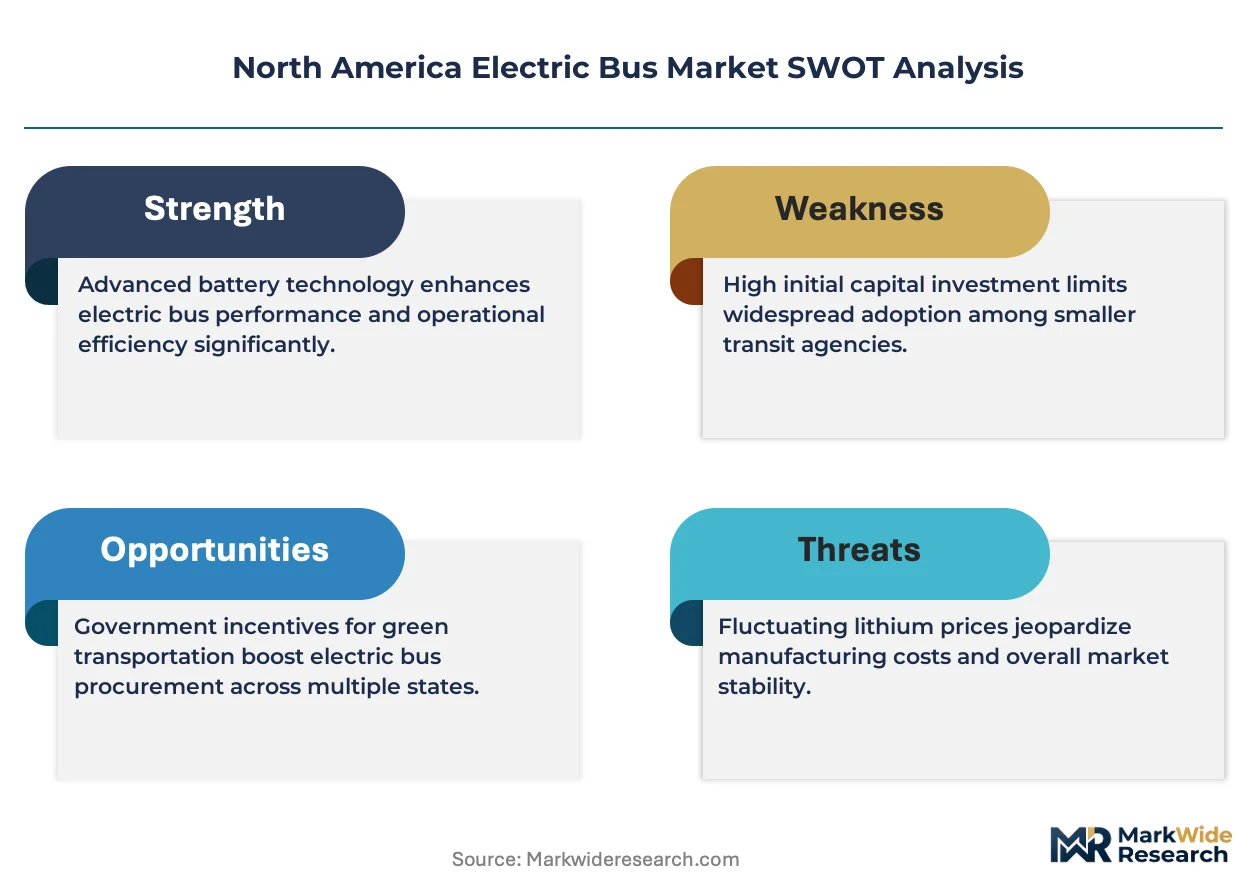
Market Restraints
- Charging infrastructure capex concentration:Depot electrification requires utility coordination and grid upgrades that concentrate capital burden on transit agencies with constrained balance sheets.
- Battery supply concentration:Cell manufacturing capacity clusters in Asia-Pacific regions, exposing North American bus assemblers to tariff exposure and shipping bottlenecks.
- Extended-range fuel cell cost structure:Platinum catalyst requirements and hydrogen distribution gaps limit fuel cell electric bus deployment to corridor applications with dedicated refueling infrastructure.
Strategic Opportunities
- Canadian provincial transit authorities:Ontario and British Columbia municipalities are accelerating fleet electrification commitments with less saturated vendor competition than California corridors.
- Vehicle-to-grid integration:Bidirectional charging protocols enable transit agencies to monetize onboard battery capacity as grid stabilization assets during idle periods.
- EPA Clean School Bus Program expansion:Federal appropriation continuity beyond initial rebate rounds would extend dedicated funding to rural districts currently priced out of electrification.
Industry Challenges
- High-voltage technician certification timelines:Transit agencies face 12-to-18-month training pipelines for maintenance personnel qualified on battery-electric powertrain systems.
- Utility interconnection queue delays:Distribution upgrade approvals for depot charging infrastructure frequently extend 24 to 36 months, misaligning with fleet delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Bus Market |
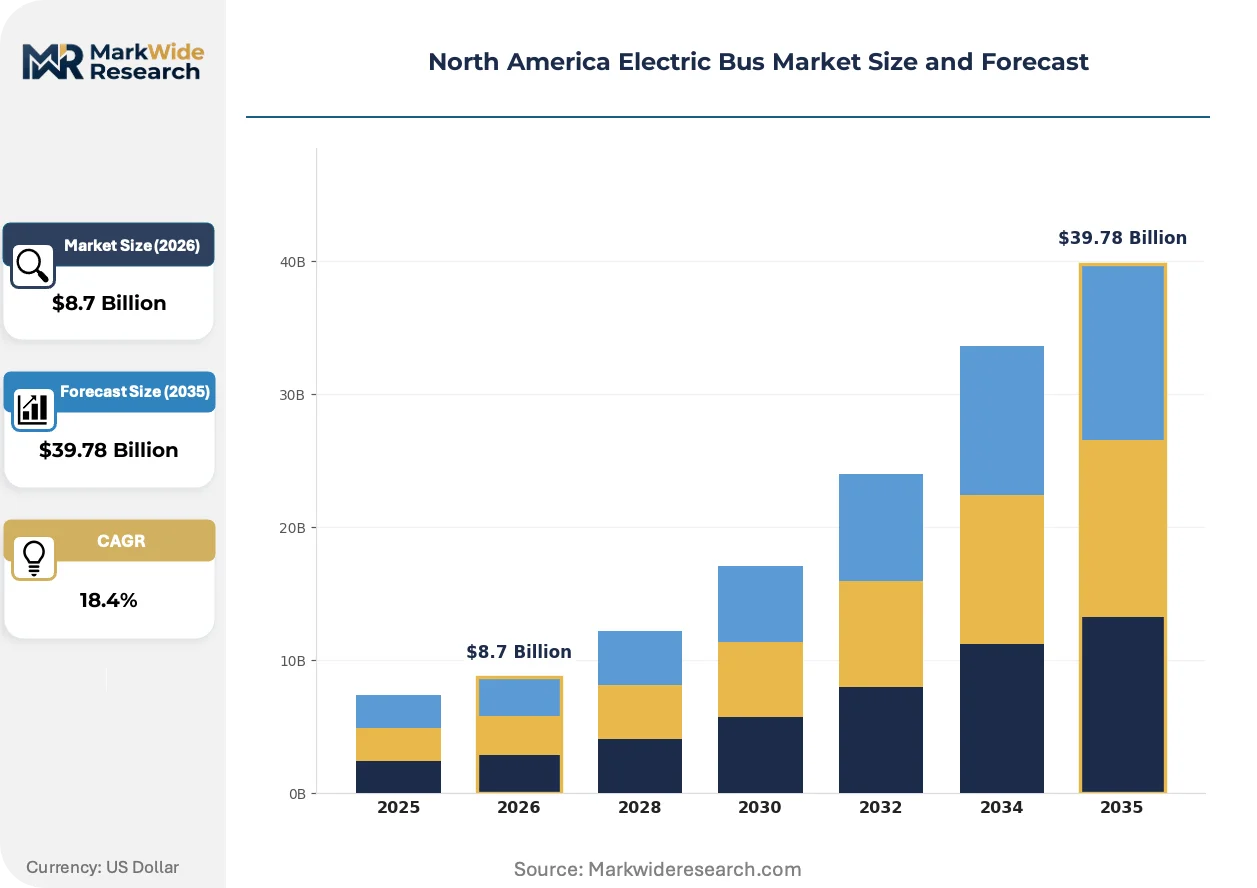
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bus Type: Fully Electric, Plug-in Hybrid, Battery Electric, Fuel Cell Charging Infrastructure: Overhead Charging, Plug-in Charging, Wireless Charging, Fast Charging End User: Public Transportation, School Districts, Tour Operators, Corporate Fleets Battery Technology: Lithium-ion, Solid-state, Lead-acid, Nickel Metal Hydride |
| Companies Covered | BYD Motors Inc., Proterra Inc., NFI Group Inc., GreenPower Motor Company Inc., Gillig LLC, Blue Bird Corporation, The Lion Electric Co., AB Volvo, New Flyer of America Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Bus Market Strategic Shifts
Battery pack architecture is fragmenting from monolithic designs toward serviceable sub-assemblies, while regulatory pressure intensifies around domestic content requirements and procurement rules favor multi-year fleet contracts over incremental pilot programs.
Cell-to-pack battery architecture is modularizing the physical integration of lithium-ion cells, eliminating module housings to improve volumetric energy density and simplify thermal management. Transit agencies in California and the Pacific Northwest are specifying this configuration for 2026-2028 delivery windows. The shift is compressing supplier margins on traditional module-based systems while rewarding manufacturers with in-house cell engineering capabilities.
The EPA's Clean School Bus Program rebate structure is tightening domestic assembly requirements, with funding tiers favoring vehicles sourced from North American production facilities. This industrial consequence is pressuring foreign-owned manufacturers to expand local assembly footprints or risk exclusion from federal grant streams. School districts in Texas and Florida are responding by consolidating procurement timelines to capture available rebate pools before program sunset.
Municipal transit authorities are consolidating fragmented pilot orders into coordinated fleet-scale contracts spanning 50 to 200 units, displacing the incremental adoption patterns of the early 2020s. This behavioral shift disrupts manufacturer sales cycles accustomed to smaller batch production. The pattern is most visible in California's largest air districts, where Innovative Clean Transit compliance deadlines are forcing multi-year procurement commitments.
North America Electric Bus Market Segmentation
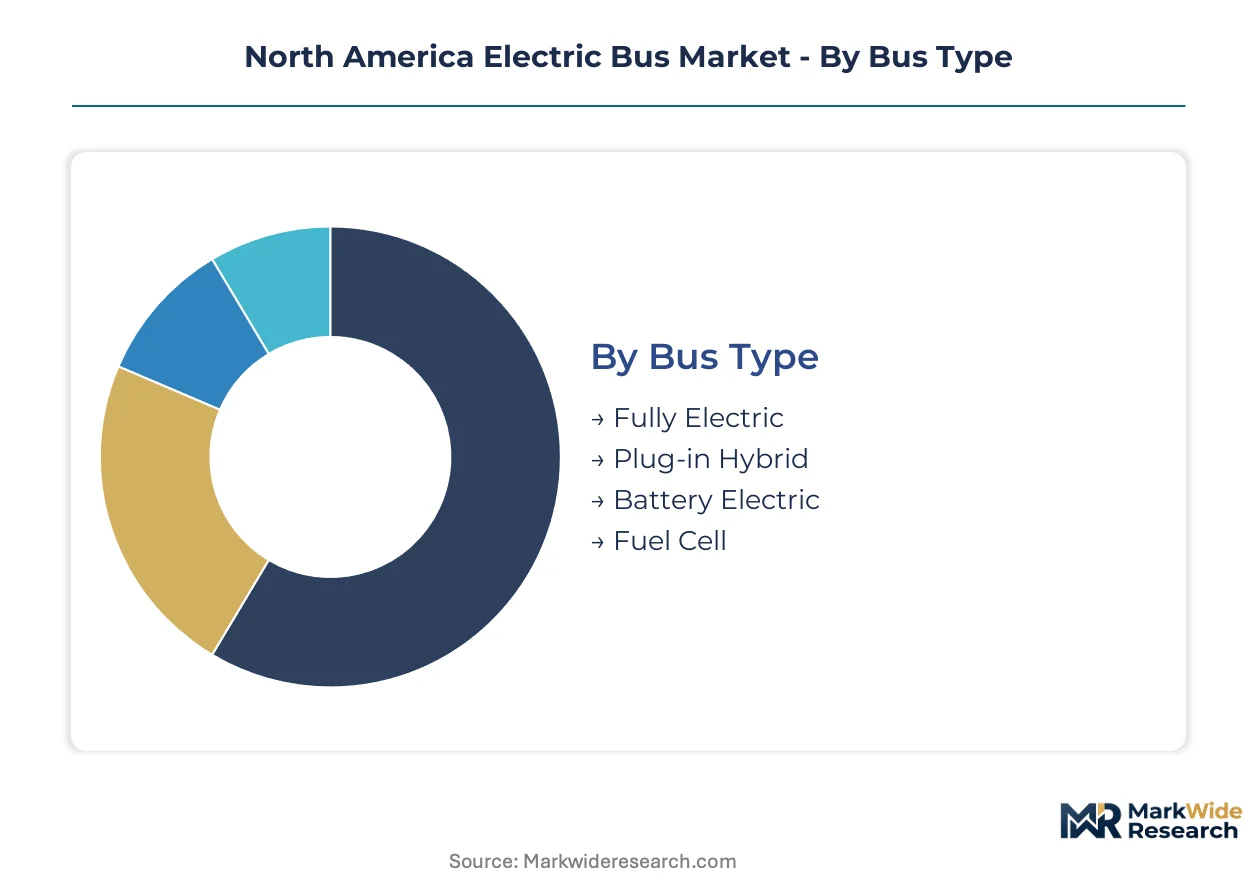
Segmentation in North America's electric bus market reveals divergent procurement economics across powertrain architectures and operational duty cycles. Fleet operators calibrate technology selection against route length, depot infrastructure, and available federal or state funding streams.
Bus Type:
Battery electric configurations command volume leadership while fuel cell variants capture premium corridor applications requiring extended range.
- Battery Electric:Lithium-ion packs exceeding 250 watt-hours per kilogram power these vehicles, eliminating tailpipe emissions from high-utilization municipal routes. California transit agencies under Innovative Clean Transit mandates concentrate procurement here, prioritizing depot-charged fleets for urban duty cycles.
- Fuel Cell:Hydrogen fuel cell powertrains deliver zero-emission operation without battery weight penalties, enabling 300-plus mile daily ranges. Deployment concentrates in California's Central Valley and Pacific Northwest corridors where hydrogen refueling infrastructure receives state capital subsidies.
- Fully Electric:Encompasses all battery-dominant architectures without range-extending combustion elements, serving as the procurement default for districts with predictable route lengths.
- Plug-in Hybrid:Combines electric propulsion with onboard combustion range extenders, bridging infrastructure gaps in rural districts with limited depot electrification timelines.
Mature deployment sits with battery electric configurations. Newer deployment is concentrated in fuel cell variants for extended-range corridor applications.
Charging Infrastructure:
Depot-based plug-in systems dominate capital planning while overhead and wireless configurations address operational constraints at scale.
- Plug-in Charging:Standard conductive charging via CCS or proprietary connectors dominates North American depot infrastructure, leveraging overnight dwell periods for cost-effective energy procurement. Utility interconnection queues in California and Texas extend 24 to 36 months, compressing fleet delivery synchronization.
- Fast Charging:High-power dispensers exceeding 350 kilowatts enable opportunity charging at route terminals, extending daily vehicle utilization. King County Metro and Toronto Transit Commission deploy these for high-frequency corridors with minimal midday layover.
- Overhead Charging:Pantograph or inverted pantograph systems deliver automated high-power connection without driver intervention, reducing dwell time at transit centers.
- Wireless Charging:Inductive pad systems embedded in pavement enable en-route energy transfer, piloted in limited California and Washington State deployments for specific corridor applications.
Volume procurement concentrates on plug-in depot infrastructure. Fast charging represents the steepest expansion trajectory as agencies prioritize vehicle utilization over capital minimization.
End User:
Public transit agencies anchor fleet-scale contracts while school districts emerge as a discrete margin pool through dedicated federal funding.
- Public Transportation:Municipal transit authorities operate the largest deployed fleets, with California's largest operators facing 2040 zero-emission mandates. Consolidated procurement now spans 50 to 200 units per contract, displacing fragmented pilot orders.
- School Districts:EPA Clean School Bus Program rebates channel competitive funding toward zero-emission replacements, with Texas and Florida districts consolidating timelines to capture available pools. Domestic assembly requirements in rebate tiers favor North American production footprints.
- Tour Operators:Charter and intercity sightseeing fleets prioritize passenger experience and brand differentiation through zero-emission branding, though route flexibility requirements limit battery electric adoption.
- Corporate Fleets:Technology campus and airport shuttle operators deploy electric buses for employee transport and ground transportation, responding to internal sustainability commitments rather than regulatory mandates.
Established procurement patterns sit with public transportation agencies. School districts represent the fastest-climbing segment as federal appropriation continuity extends rebate accessibility.
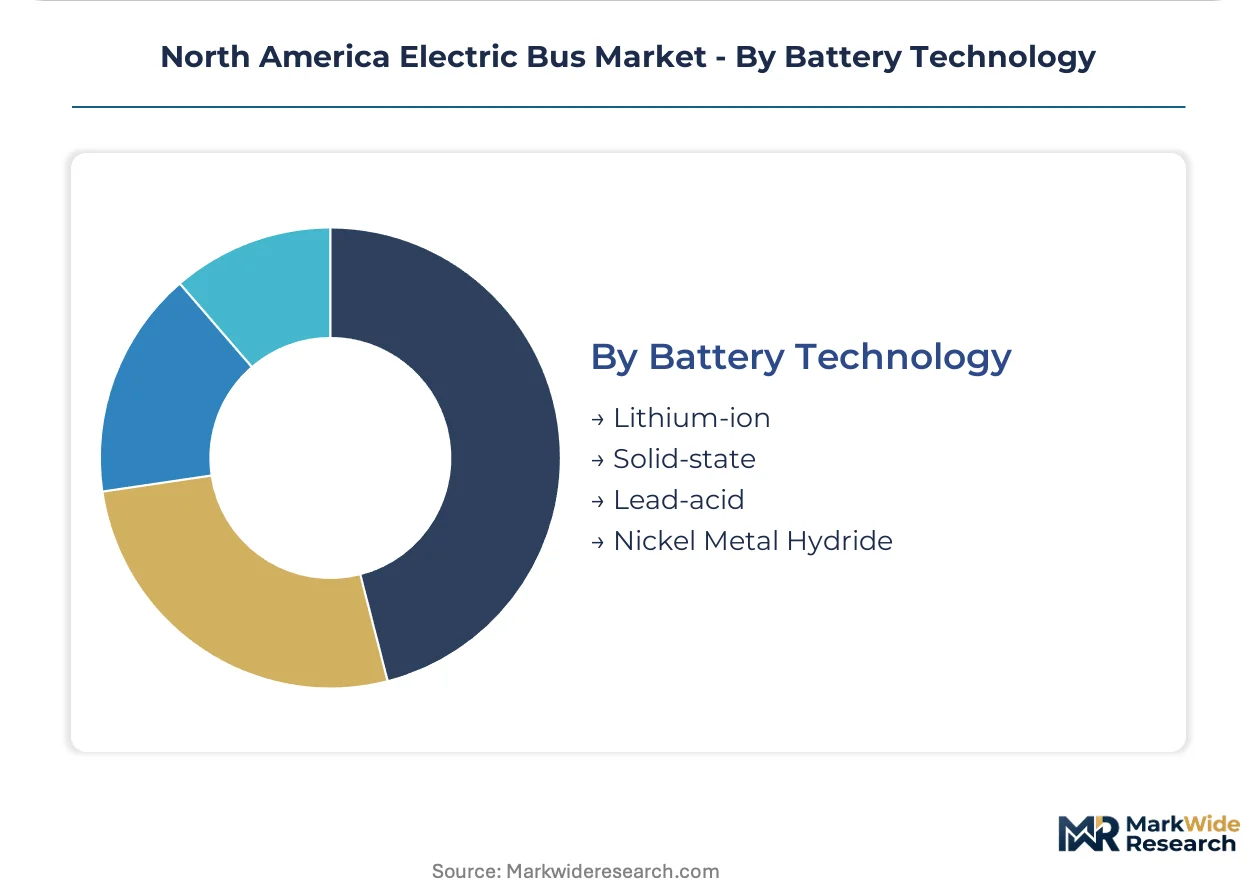
Battery Technology:
Lithium-ion chemistry dominates energy density thresholds while solid-state architectures approach commercialization for next-generation deployments.
- Lithium-ion:NMC and LFP cell configurations currently power virtually all deployed North American electric buses, with cell-to-pack architectures improving volumetric density and thermal management. California agencies specify these for 2026-2028 delivery windows.
- Solid-state:Ceramic or polymer electrolyte systems promise enhanced safety and energy density, with pilot integration timelines targeting late-decade commercialization for extended-range applications.
- Nickel Metal Hydride:Mature chemistry with limited current deployment, primarily in legacy hybrid configurations rather than full battery electric platforms.
- Lead-acid:Auxiliary power applications only, excluded from traction power due to insufficient energy density for commercial bus duty cycles.
Commercial maturity sits with lithium-ion configurations. Solid-state systems concentrate emerging development investment for next-generation energy density thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most intensely in California, where state-level mandates and utility partnerships are creating dense procurement corridors. Municipal transit agencies across the United States and Canada are accelerating fleet electrification commitments.
United States
California transit agencies under the Innovative Clean Transit regulation are consolidating procurement into fleet-scale contracts spanning 50 to 200 units. The EPA's Clean School Bus Program channels competitive rebate funding toward zero-emission replacements in Texas and Florida districts. Los Angeles Metro and San Francisco MUNI anchor the densest deployment clusters for battery-electric configurations.
Canada
Ontario and British Columbia municipalities are accelerating fleet electrification with less saturated vendor competition than California corridors. Transport Canada coordinates federal funding streams that prioritize electrification projects in urbanized areas. Toronto Transit Commission and TransLink Vancouver represent the largest committed procurement volumes for 2026-2028 delivery windows.
Mexico
Mexico City Metro is piloting battery-electric bus deployments for high-frequency corridor applications. The Secretariat of Environment and Natural Resources coordinates federal incentives for zero-emission public transport procurement. Monterrey and Guadalajara metropolitan areas are emerging as secondary demand nodes with dedicated clean mobility programs.
North America Electric Bus Market Competitive Environment
United States producers anchor one tier; Chinese specialists with North American assembly footprints hold contract volume for large municipal orders. The vendor base clusters around three strategic archetypes: integrated powertrain manufacturers, dual-brand production operators, and dedicated electric vehicle specialists. Consolidation pressure intensifies as fleet-scale mandates compress procurement timelines toward multi-year municipal contracts. Dominant competitive moves include capacity reconfiguration around depot-charged fleet architectures and strategic partnerships with utility operators for charging infrastructure coordination.
Within the integrated powertrain tier, Proterra Inc. and BYD Motors Inc. exemplify contrasting geographic origins and production strategies. NFI Group Inc. anchors the dual-brand production archetype with cross-border manufacturing presence. These three entities represent the primary competitive anchors around which procurement consolidation is crystallizing.
| Leading Market Players |
|---|
| BYD Motors Inc. |
| Proterra Inc. |
| NFI Group Inc. |
| GreenPower Motor Company Inc. |
| Gillig LLC |
| Blue Bird Corporation |
| The Lion Electric Co. |
| AB Volvo |
| New Flyer of America Inc. |
| Others |
Value Chain & Pricing Dynamics
California's Innovative Clean Transit mandate compressing procurement timelines toward fleet-scale contracts forces battery pack suppliers to reconfigure production for multi-year municipal commitments, compressing margins on traditional module-based systems while rewarding manufacturers with captive cell engineering capabilities.
Pricing Analysis
Fleet-scale municipal contracts anchor volume procurement at compressed unit economics while pilot-tier orders retain premium pricing for smaller batch flexibility. Three-tier pricing structure across premium, standard, and economy levels stratifies by battery energy density thresholds and domestic assembly certification tiers. Cost compression in the standard tier is intensifying because cell-to-pack architectures eliminate module housing overhead. School districts under EPA rebate programs exhibit highest price sensitivity, while California transit agencies facing 2040 compliance deadlines prioritize performance specifications over procurement cost.
Supply Chain Analysis
End-of-life battery refurbishment flows and second-life stationary storage applications are emerging as reverse-logistics revenue streams for North American assemblers. Cell manufacturing capacity clusters in China, South Korea, and Japan, exposing bus manufacturers to tariff exposure and shipping bottlenecks on lithium carbonate, nickel sulfate, and electrolyte solvents. Single-source vulnerability concentrates in cathode active material supply. Distribution runs through OEM-direct contracting to municipal transit authorities and school district procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America electric bus market functions as a cost-of-compliance arena where California Air Resources Board's 2040 zero-emission mandate erects regulatory moats favoring manufacturers with certified domestic assembly footprints and utility partnership networks.
For Market Incumbents: Lock in multi-year fleet contracts with California's largest air districts before procurement windows consolidate further, while securing captive lithium supply through offtake agreements with South Korean cell producers to mitigate tariff exposure. Threat of Chinese manufacturers expanding North American assembly capacity intensifies margin pressure on mid-tier producers. Backward integration into battery pack assembly represents the critical defensive lever. For New Entrants and Emerging Players: The mid-tier price-point gap between Proterra's premium integrated powertrains and economy-tier school bus configurations offers white-space entry for modular platform specialists. Ontario and British Columbia municipalities present the most penetrable geography given less saturated vendor competition. A service-based revenue model bundling charging infrastructure with vehicle lease terms provides differentiated go-to-market positioning against capital-sale incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with dual-brand production operators given EPA domestic assembly requirements tightening rebate eligibility tiers. Five-to-ten year viability hinges on utility interconnection queue navigation capabilities and state-level zero-emission mandate continuity. Acquisition target archetype: mid-cap assemblers with established California air district relationships and pending cell-to-pack certification. Signal to watch: Federal Transit Administration appropriation continuity beyond initial Clean School Bus Program rounds.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Certification | California transit agencies specify this configuration for 2026-2028 delivery windows, compressing module-based supplier margins. |
| Utility Partnership Formation | Depot charging infrastructure coordination with Pacific Gas and Electric and Southern California Edison accelerates interconnection queue navigation. |
| Domestic Assembly Footprint Expansion | EPA rebate tiers favor North American production facilities, pressuring foreign-owned manufacturers to localize or face exclusion. |
| Battery Second-Life Program Development | Transit agencies monetize end-of-life packs for stationary grid storage, extending asset value capture beyond vehicle service life. |
| High-Voltage Technician Training Pipeline | Twelve-to-eighteen-month certification timelines for maintenance personnel create service network moats around early fleet deployers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving transit agency procurement directors, utility interconnection planners, battery pack engineering leads, and EPA program administrators. American Public Transportation Association fleet survey data, California Air Resources Board compliance filings, Federal Transit Administration capital assistance records, and utility interconnection queue databases supplied quantitative foundations. Bottom-up unit economics modeling triangulated against top-down market sizing from vehicle registration databases.
Data-stream reconciliation across production capacity announcements, confirmed procurement contracts, and federal rebate disbursement records informed the analytical framework across the analysis window. Segmentation dimensions modeled include powertrain architecture, charging infrastructure type, end-user category, and battery technology tier. CAGRs were derived from logistic diffusion curves fitted to fleet penetration thresholds and mandate compliance deadlines. Forecast inputs incorporated lithium-ion cell cost trajectories and utility rate structures for depot electrification.
Inputs from EPA rebate program databases and state air district procurement records were available through the study window; gaps in hydrogen refueling infrastructure deployment timelines introduce uncertainty bands for fuel cell electric bus adoption curves. Practitioners should monitor Federal Transit Administration appropriation continuity and utility interconnection queue clearance rates for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Bus Pantograph Charger Market
Electric Vehicles
Central and Eastern Europe E-Bike Market
Electric Vehicles
Global Electric Vehicles Engineering Plastics Market
Electric Vehicles
EV Thermal System Market
Electric Vehicles
Electric Passenger Cars Market
Electric Vehicles
Asia Pacific Electric Commercial Vehicles Market
Electric Vehicles
ASEAN EV Battery Pack Market
Electric Vehicles
Vietnam Solar E-Bike Market
Electric Vehicles
Three Wheel E-Scooter Market
Electric Vehicles
Battery Electric Vehicle (BEV) Market
Electric Vehicles
Golf Cart Battery Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
Automotive EV HUB Market
Electric Vehicles
Middle East Electric Vehicle Market
Electric Vehicles
Electric Van Market
Electric Vehicles
South America Electric Vehicle (EV) Fluids Market