
 Hybrid Electric Vehicle Market | 2026-2036
Hybrid Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Electric Vehicle Market Intelligence
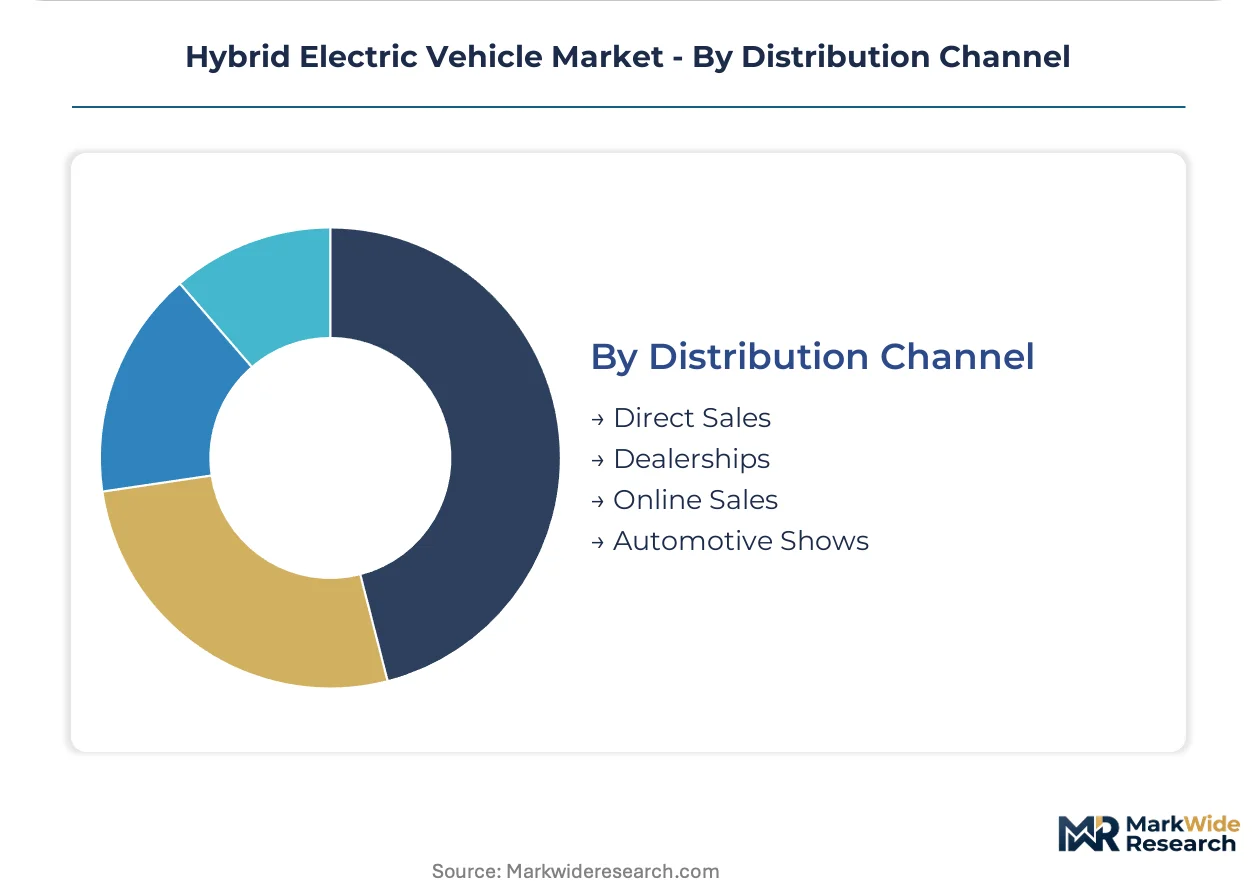
The dealership channel is narrowing as direct sales and online platforms capture greater volume from traditional franchise networks. Toyota leverages its hybrid-first heritage to sustain manufacturing scale across multiple continents. BYD anchors vertical integration through in-house battery cell production, controlling cost structures that competitors struggle to match. Honda competes on powertrain specialization, particularly in two-motor hybrid architectures for mid-size segments.
A hybrid electric vehicle combines an internal combustion engine with one or more electric motors and a battery pack, typically operating at voltages between 200 and 800 volts depending on architecture. The system captures kinetic energy through regenerative braking, stores it in lithium-ion or nickel-metal hydride packs, and deploys electric torque to reduce fuel consumption during low-load driving cycles. Full hybrid systems lead installed base volumes due to their established cost curve and absence of charging infrastructure dependency. Plug-in hybrid architectures represent the fastest-expanding category as battery energy densities improve and fleet operators prioritize electric-only range for urban duty cycles. Power electronics constitute a concentrated margin pool, with inverter and converter suppliers capturing disproportionate value relative to mechanical component providers.
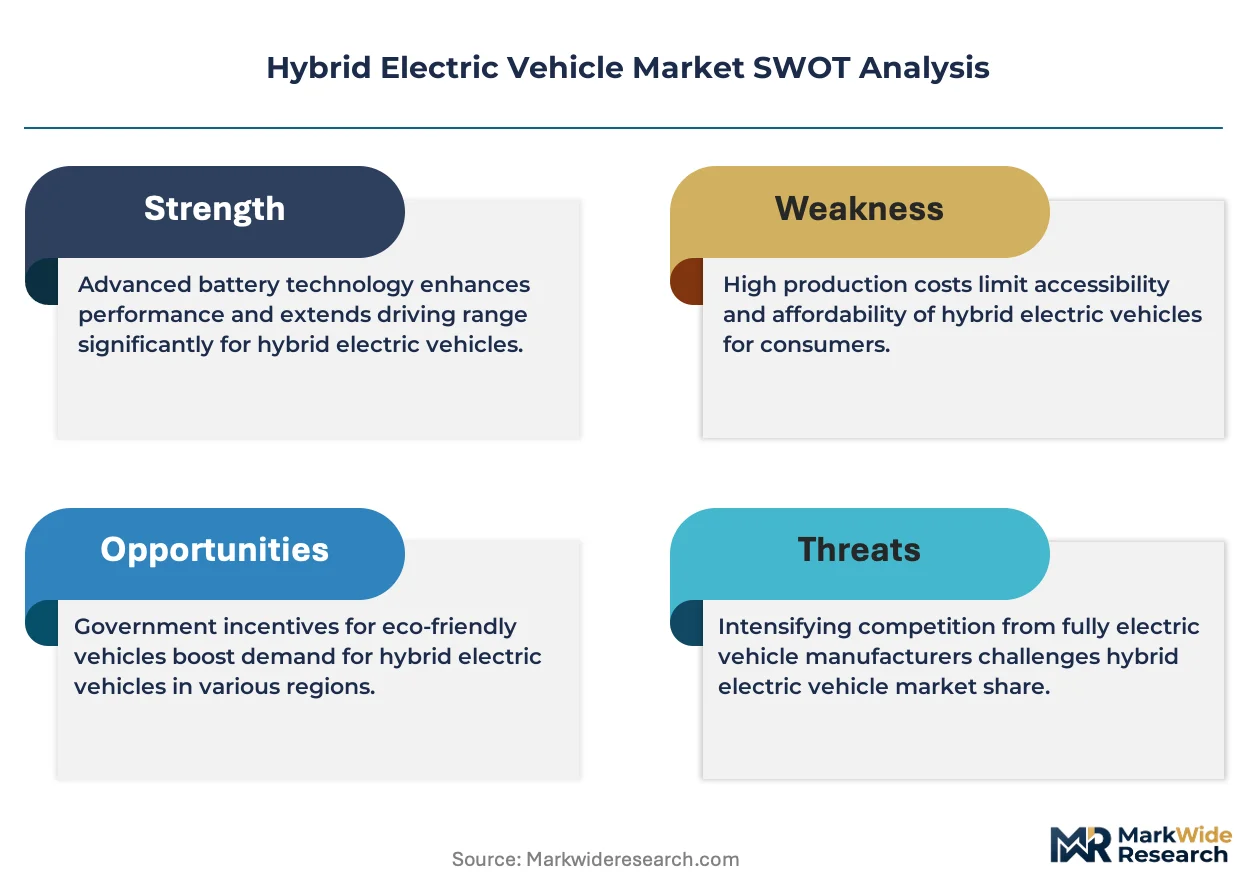
EPA Corporate Average Fuel Economy standards, California Air Resources Board zero-emission vehicle mandates, and EU CO2 fleet targets collectively reshape product planning timelines and powertrain investment allocations. NHTSA safety protocols for high-voltage systems add compliance layers that favor established manufacturers with dedicated electrification engineering teams. Stakeholders must monitor battery raw material cost trajectories and regional subsidy phase-out schedules to calibrate production commitments against evolving total cost of ownership equations.
Market Dynamics
The transition from mechanical to electrified powertrains is compressing traditional supplier hierarchies and forcing automakers to reallocate engineering capacity toward battery thermal management and power electronics integration.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Automakers face escalating penalties for fleet-wide emissions, accelerating hybrid powertrain deployment across light-duty truck and SUV segments.
- Lithium-ion cell cost curves:Battery pack economics now support plug-in hybrid architectures with 40-plus mile electric-only range, opening fleet procurement to urban delivery operators.
- China's dual carbon goals:Provincial manufacturing subsidies and NEV credit trading systems concentrate hybrid production capacity in Jiangsu and Guangdong provinces.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet motor production depends on Chinese-processed neodymium and dysprosium, exposing automakers to export quota volatility.
- Nickel-cobalt price volatility:High-nickathode cathode chemistries face input cost swings that compress power electronics margins during contract renegotiation cycles.
- High-voltage technician scarcity:Service networks lack certified personnel for 400-800V system diagnostics, extending warranty repair timelines and elevating customer satisfaction risk.
Strategic Opportunities
- India's PLI scheme for auto and auto components:Domestic cell manufacturing incentives create localized supply chain options for hybrid variants targeting price-sensitive entry segments.
- Vehicle-to-home integration:Bidirectional charging hardware convergence with residential solar installations positions plug-in hybrids as distributed energy assets.
- EU CO2 fleet targets:2035 phase-out timelines for pure internal combustion engines preserve hybrid relevance as compliance bridge technology for mass-market brands.
Industry Challenges
- Functional safety certification:ISO 26262 ASIL-D compliance for battery management systems demands 18-24 month validation cycles that delay platform launches.
- Legacy powertrain retooling:Existing engine plant assets require substantial modification for hybrid-specific assembly sequences, straining capital allocation committees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Electric Vehicle Market |
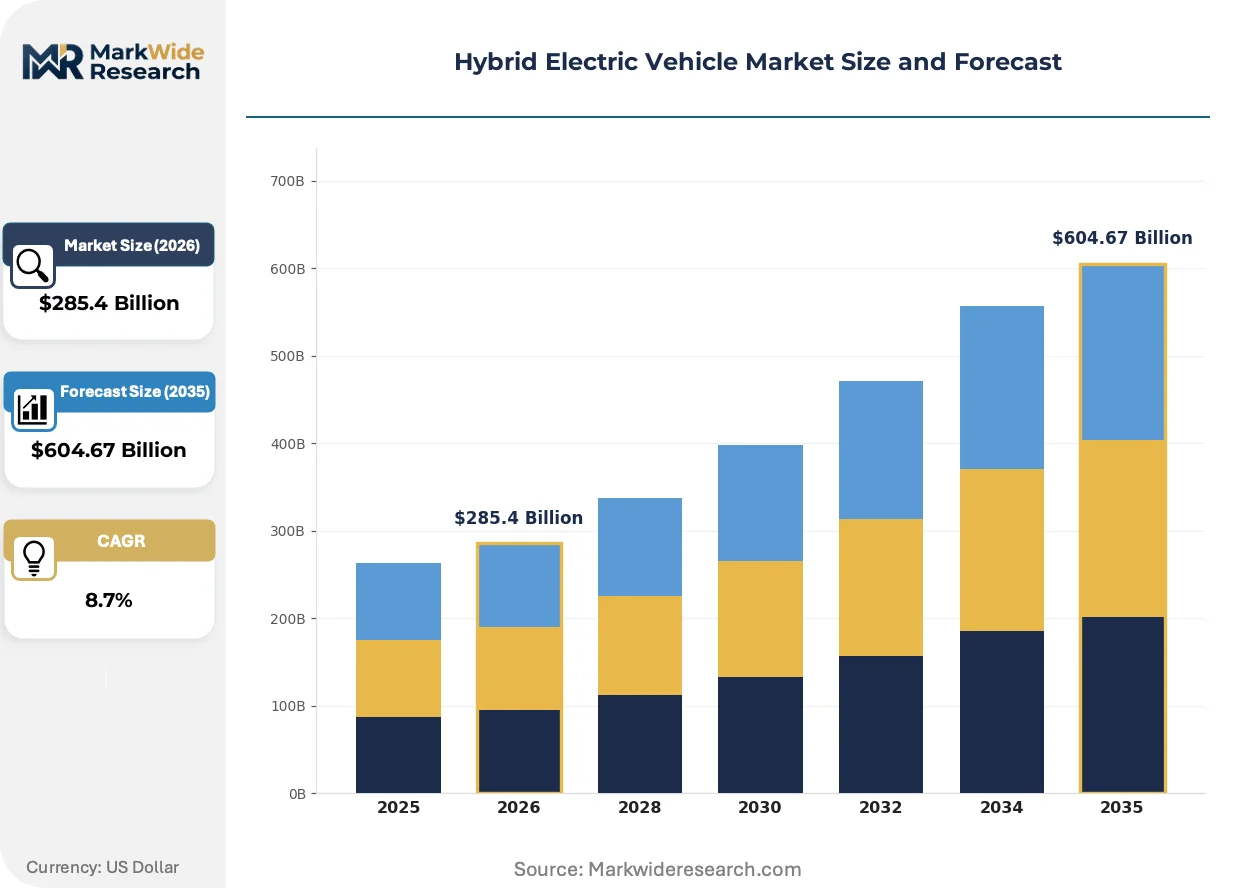
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $604.67 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plug-in Hybrid, Mild Hybrid, Full Hybrid, Extended Range Electric End User: Private Consumers, Fleet Operators, Ride-sharing Services, Government Agencies Technology: Regenerative Braking, Battery Management, Thermal Management, Power Electronics Distribution Channel: Direct Sales, Dealerships, Online Sales, Automotive Shows |
| Companies Covered | Honda, BMW, Toyota, BYD, Ford, Hyundai Motor Company, Stellantis, Genesis, Nissan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Electric Vehicle Market Strategic Shifts & Innovations
Power semiconductor architectures and thermal management systems are converging to enable higher voltage platforms, while regulatory compliance timelines compress product development cycles across all major automotive markets.
Silicon carbide MOSFETs are replacing insulated-gate bipolar transistors in traction inverters, cutting switching losses by two-thirds and permitting downsized cooling hardware. Tier-1 suppliers in Germany and Japan are qualifying 800V-rated modules for next-generation full hybrid systems. This voltage escalation is virtualizing the traditional boundary between power electronics and battery pack engineering, forcing consolidated supplier relationships.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are phasing out conventional refrigerants in automotive climate systems. Automakers must certify CO2 heat pump alternatives that maintain cabin comfort during electric-only operation. European premium hybrid variants face the steepest compliance deadlines, accelerating supplier qualification of transcritical cycle hardware.
Fleet operators now specify total cost of ownership guarantees over fixed lease terms rather than acquiring vehicles through outright purchase. Direct sourcing agreements with OEM captive finance units are displacing traditional dealership fleet departments. This contractual pivot is most advanced among North American last-mile delivery consolidators managing mixed hybrid and plug-in hybrid pools.
Hybrid Electric Vehicle Market Segmentation
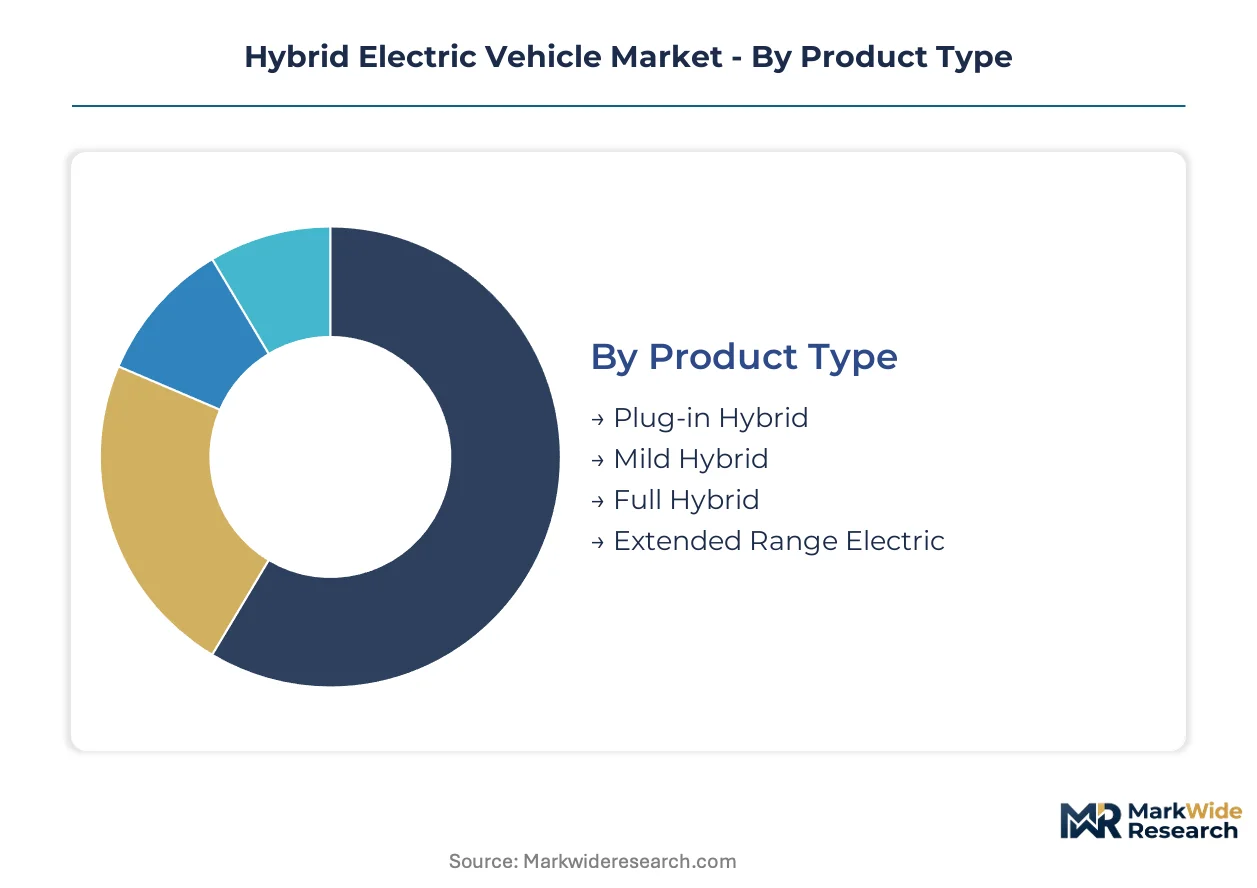
Segmentation in the hybrid electric vehicle market reveals distinct procurement rhythms and technology maturities. Fleet operators cycle vehicles faster than private consumers, while power electronics refresh on semiconductor timelines unrelated to mechanical wear. Understanding these asynchronous replacement patterns shapes inventory and service network planning.
Product Type:
Full hybrid architectures turn over slowest due to proven reliability curves, while plug-in variants refresh fastest as battery energy densities improve.
- Full Hybrid:Combines internal combustion engine with electric motor and self-charging battery pack without plug-in capability. Demand concentrates among North American fleet operators seeking zero infrastructure dependency combined with EPA compliance for light-duty truck segments.
- Plug-in Hybrid:Features larger battery packs enabling 40-plus miles of electric-only range with external charging capability. Urban delivery fleets in China prioritize this architecture as provincial NEV credit systems reward electric kilometers logged during city duty cycles.
- Mild Hybrid:Employs 48V belt-driven starter-generators for torque assist and stop-start functionality. European mass-market brands deploy this as a cost bridge toward full electrification under EU CO2 fleet targets.
- Extended Range Electric:Uses combustion engine exclusively as generator for battery replenishment, eliminating mechanical drivetrain connection. Niche positioning among operators requiring long-distance capability with electric drivetrain benefits.
Full hybrid dominates installed base. Plug-in hybrid is where expansion concentrates.
End User:
Procurement scale separates segments, with fleet operators commanding volume pricing and standardized specifications unavailable to fragmented private demand.
- Fleet Operators:Consolidated purchasers managing mixed-vehicle pools across last-mile delivery, utility services, and corporate transport. Direct OEM finance agreements displace traditional dealership channels as total cost of ownership guarantees replace outright acquisition.
- Private Consumers:Individual buyers selecting vehicles through retail channels with financing arranged through captive lenders or third-party institutions. Preference patterns split between fuel economy optimization and technology feature adoption.
- Ride-sharing Services:High-utilization operators prioritizing durability and rapid charging turnaround over premium amenities. Mileage accumulation rates compress replacement cycles versus private ownership patterns.
- Government Agencies:Public procurement entities with mandated domestic content requirements and electrification targets. Municipal fleets in Germany and Japan anchor early adoption of standardized hybrid specifications.
Fleet operators command procurement volume. Ride-sharing services are climbing the fastest.
Technology:
Margin concentration varies sharply across this category, with semiconductor content capturing disproportionate value versus mechanical systems.
- Power Electronics:Traction inverters, DC-DC converters, and onboard chargers processing 200-800V flows. Silicon carbide MOSFET adoption is gaining share fastest as Tier-1 suppliers in Germany and Japan qualify next-generation modules.
- Battery Management:Cell monitoring, state-of-charge algorithms, and thermal runaway prevention systems. ISO 26262 ASIL-D certification requirements extend validation timelines for suppliers serving European premium variants.
- Thermal Management:Heat pump and liquid cooling systems maintaining battery and cabin temperatures across operating envelopes. EU F-Gas Regulation compliance pressures accelerate CO2 refrigerant adoption.
- Regenerative Braking:Kinetic energy recovery systems converting deceleration into stored electrical energy. Mature cost curves limit differentiation opportunity except in software optimization of blending algorithms.
Power electronics captures margin concentration. Battery management is where engineering investment concentrates.
Distribution Channel:
Channel economics are restructuring as direct relationships displace intermediary markups and inventory risk allocation.
- Direct Sales:Manufacturer-controlled transactions eliminating franchise dealer participation. Fleet procurement in North America is expanding through this channel as operators negotiate enterprise pricing.
- Dealerships:Traditional franchised networks handling inventory, financing, and service for private consumers. Volume compression pressures fixed-cost absorption across rural and secondary market locations.
- Online Sales:Digital configurators with home delivery or pickup point fulfillment. Urban private consumers in China and Germany increasingly complete transactions without physical showroom visits.
- Automotive Shows:Event-based marketing and limited-run pre-order campaigns. Niche positioning for extended range and premium plug-in variants seeking technology differentiation signaling.
Dealerships retain private consumer volume. Direct sales is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in battery cell exports and hybrid component logistics. Germany's Rhine-Alpine rail corridor links Stuttgart powertrain clusters to Rotterdam distribution hubs. Japan's coastal manufacturing belt between Tokyo and Osaka concentrates inverter and motor assembly.
China
Jiangsu and Guangdong provinces anchor hybrid production scale as provincial NEV credit trading systems reward electric kilometer accumulation. MIIT production quotas mandate electrified powertrain penetration across domestic OEM portfolios. BYD's Shenzhen headquarters coordinates vertical battery cell manufacturing with assembly plants in Xi'an and Changzhou.
United States
Fleet procurement concentrates in California and Texas as EPA Corporate Average Fuel Economy penalties escalate for light-duty truck segments. NHTSA high-voltage safety protocols favor established manufacturers with dedicated electrification engineering teams. Michigan's Detroit-Warren corridor hosts powertrain development centers serving North American hybrid programs.
Germany
EU CO2 fleet targets compress product planning timelines for mass-market brands seeking compliance bridge technologies. KBA type-approval processes for 800V high-voltage systems add validation layers that strain development budgets. Baden-Württemberg's Stuttgart region concentrates Tier-1 inverter suppliers and power electronics engineering.
Japan
METI technology roadmaps prioritize silicon carbide MOSFET adoption in next-generation traction inverters. JIS standards for battery thermal management systems create certification benchmarks adopted across Asia-Pacific supply chains. Toyota City anchors hybrid-first manufacturing heritage with multi-continent platform replication.
India
PLI scheme incentives for auto and auto components attract domestic cell manufacturing investment for price-sensitive hybrid variants. BIS certification requirements for high-voltage systems extend market entry timelines for new entrants. Tamil Nadu's Chennai-Sriperumbudur belt concentrates assembly capacity serving domestic and export demand.
Hybrid Electric Vehicle Market Key Industry Players
On the supply side, the industry is consolidating around three strategic tiers. Established full-line manufacturers leverage captive battery supply and multi-continent assembly footprints. Specialist power electronics houses capture disproportionate margin through silicon carbide inverter qualification. Emerging challengers compete on provincial subsidy capture and localized cost structures. Capacity expansion and strategic partnerships dominate competitive moves as players secure cell supply and qualify next-generation voltage platforms.
Among Asia-Pacific-based manufacturers, Toyota, BYD, and Honda occupy distinct archetype positions. Toyota exemplifies the heritage-driven incumbent with manufacturing scale replicated across multiple continents. BYD anchors the vertically integrated challenger archetype through in-house battery cell production controlling cost structures. Honda represents the powertrain specialization archetype with two-motor hybrid architectures for mid-size segments.
| Leading Market Players |
|---|
| Honda |
| BMW |
| Toyota |
| BYD |
| Ford |
| Hyundai Motor Company |
| Stellantis |
| Genesis |
| Nissan |
| Others |
Cost & Logistics Intelligence
Rare earth magnet supply concentration determines both tier spreads and supply chain configuration in hybrid electric vehicle manufacturing. Chinese-processed neodymium and dysprosium export quota volatility compress margins in premium inverter modules while forcing procurement diversification into higher-cost alternative motor architectures.
Pricing Analysis
Volume-discount tiering separates fleet procurement agreements from fragmented private retail transactions. Pricing stratifies across premium silicon carbide inverter systems, standard IGBT-based architectures, and economy-grade mild hybrid configurations. Cost compression in entry-level segments intensifies as China's provincial NEV credit systems subsidize electric kilometer accumulation. Fleet operators command the lowest unit economics through enterprise direct sourcing, while private consumers absorb the highest per-vehicle premiums.
Supply Chain Analysis
Extended payment terms from OEMs to Tier 1 suppliers now stretch 90-120 days, straining working capital across inverter and battery management system producers. Manufacturing concentrates in China, South Korea, and Japan for lithium-ion cells, power semiconductors, and permanent magnet motors. Nickel-cobalt cathode chemistries draw from Indonesian and Chilean feedstocks. Single-source vulnerability in Chinese rare earth processing exposes automakers to supply interruption. Distribution runs through captive OEM logistics networks and third-party battery pack integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid electric vehicle demand acceleration reflects EPA Corporate Average Fuel Economy penalty escalation and EU CO2 fleet target compression. These regulatory inflections transform powertrain procurement from compliance option to strategic necessity.
For Market Incumbents: Pre-empt emerging challenger cost structures through captive battery cell supply and multi-continent assembly footprint replication. Secure silicon carbide MOSFET allocation through long-term foundry partnerships before capacity constraints harden. Defend against vertically integrated Chinese entrants by accelerating 800V platform qualification cycles.
For New Entrants and Emerging Players: Pursue India's PLI scheme incentives for domestic cell manufacturing serving price-sensitive hybrid variants. Target European fleet operators seeking compliance bridge technologies under 2035 ICE phase-out timelines. Establish direct sales channels with municipal procurement entities in Germany and Japan.
For Investors and Strategic Acquirers: EU CO2 fleet targets and EPA penalty escalation reshape the acquisition landscape toward power electronics specialists with silicon carbide inverter qualification. Long-term viability favors suppliers with ISO 26262 ASIL-D certification capabilities and thermal management system integration. Monitor battery raw material cost trajectories as the primary inflection signal for production commitment calibration.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Captive lithium-ion cell sourcing locks in cost structures against nickel-cobalt volatility. |
| Silicon Carbide Inverter Qualification | 800V module adoption cuts switching losses and enables downsized cooling hardware. |
| Platform Standardization | Multi-continent powertrain replication spreads development costs across regional variants. |
| Direct Fleet Sales Channel | Enterprise procurement agreements displace dealership markups with total cost guarantees. |
| Vehicle-to-Home Integration | Bidirectional charging positions plug-in hybrids as residential distributed energy assets. |
Research Approach
Cross-validation between OEM platform engineering disclosures and Tier 1 supplier production schedules anchors the qualitative findings. Primary interviews with power electronics procurement managers, battery thermal system engineers, and fleet operations directors combined with secondary validation from vehicle registration databases, customs trade flows, and EPA compliance filings. Bottom-up assembly volume estimates and top-down regulatory target analysis triangulate market sizing.
Calibration against historical powertrain penetration curves and regional subsidy phase-out schedules shapes the projection framework. Segmentation models incorporate vehicle class, propulsion architecture, battery energy density tier, and regional production cluster. CAGRs derive from fitted adoption curves across the analysis window, with inputs including lithium-ion cell cost trajectories and NEV credit system evolution.
Sensitivities concentrate around rare earth export quota volatility, high-voltage technician certification bottlenecks, and F-Gas Regulation compliance timelines. Forecasts reflect documented assumptions on regulatory enforcement intensity and battery chemistry cost curves. Macroeconomic contraction, subsidy acceleration, or solid-state battery breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Smart Hybrid Vehicle Market
Hybrid Vehicles
Hydrogen Vehicles Market
Hybrid Vehicles
Middle East and Africa Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Canada Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Asia-Pacific Mild-Hybrid Vehicles Market
Hybrid Vehicles
Global Hybrid Vehicle Transmission Market
Hybrid Vehicles
North America Mild Hybrid Vehicles Market
Hybrid Vehicles
Hypercar Market
Hybrid Vehicles
Europe Mild Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Electric Self-Driving Car Market
Hybrid Vehicles
Crossovers Market
Hybrid Vehicles
Global Hybrid-Electric Vehicle Insulation Market
Hybrid Vehicles
Asia-Pacific Micro-Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Vehicle Market
Hybrid Vehicles
Micro-Hybrid Vehicle Market
Hybrid Vehicles
Hybrid Drivetrain Market