
 New Energy Vehicle (NEV) Taxi Market | 2026-2036
New Energy Vehicle (NEV) Taxi Market Size, Share, and Industry Trends Forecast 2026-2036
New Energy Vehicle (NEV) Taxi Market Analysis
The EU Green Deal's zero-emission fleet mandate for urban transport is pivoting procurement strategies across European taxi cooperatives and ride-hailing platforms. BYD Company leverages its integrated battery manufacturing to anchor supply contracts with major fleet operators across multiple continents. Tesla Inc. competes through its proprietary Supercharger network, which sustains driver uptime advantages in high-density urban taxi corridors. SAIC Motor Corporation Limited dominates the domestic Chinese NEV taxi segment through cost-optimized battery-swap configurations purpose-built for intensive daily mileage.
A New Energy Vehicle (NEV) Taxi is a commercially operated passenger transport vehicle powered wholly or partially by electric drivetrain systems, typically incorporating lithium-ion battery packs with energy densities exceeding 160 Wh/kg and regenerative braking architectures designed for stop-and-go urban duty cycles. Its primary industrial purpose is to replace fossil-fuel taxi fleets with zero-tailpipe-emission alternatives capable of meeting municipal air quality targets while reducing per-kilometer operating costs for drivers. Battery Electric Vehicle configurations command the largest installed base among vehicle type segments due to lower total cost of ownership in high-utilization fleet settings, while Fuel Cell Electric Vehicle variants occupy niche positions in markets with established hydrogen refueling infrastructure. Ride-hailing service type segments generate disproportionate revenue concentration as platform economics favor centralized fleet electrification over fragmented owner-operator conversions.
China's MIIT enforces GB standards for NEV range and safety that dictate battery chemistry approvals and vehicle platform eligibility for taxi registration subsidies. The EPA's vehicle emission standards and the EU's F-Gas Regulation jointly constrain thermal management system designs, pushing manufacturers toward CO2-based heat pump architectures for cabin climate control. Stakeholders must monitor the divergence between China's battery-swap standardization push and Europe's plug-in charging infrastructure commitments, as this technical fragmentation will determine which vehicle-platform and energy-service business models achieve transcontinental scalability.
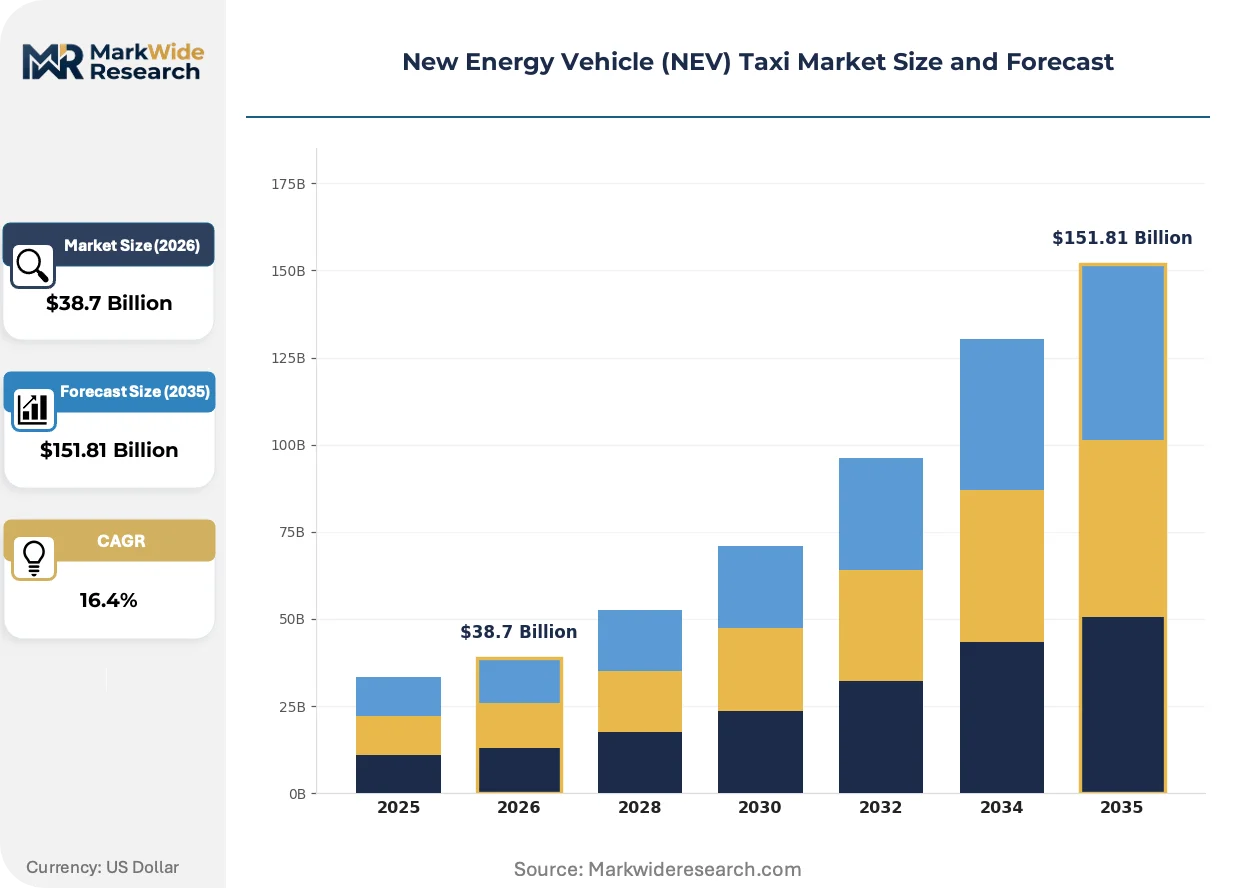
Market Dynamics
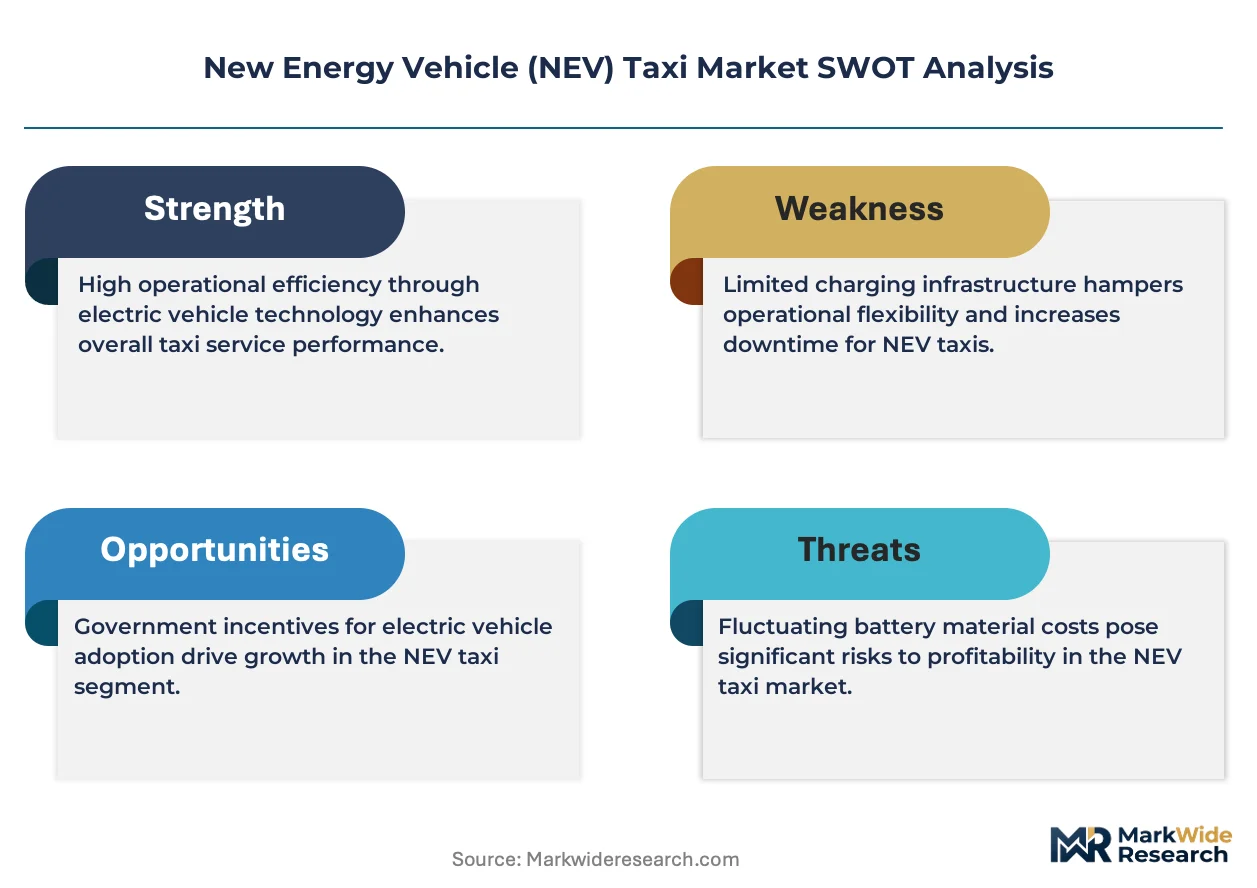
Municipal zero-emission fleet mandates are compressing replacement cycles for legacy internal combustion taxis, forcing fleet operators to absorb upfront battery electric vehicle premiums while negotiating charging infrastructure commitments with municipal authorities.
Growth Catalysts
- China's dual carbon goals:Municipal electrification deadlines in Shenzhen, Shanghai, and Beijing are mandating complete taxi fleet turnover by specified target years, eliminating registration renewals for fossil-fuel vehicles.
- Battery-swap standardization:GB standards from China's MIIT are enabling sub-three-minute energy replenishment for high-utilization commercial fleets, reducing driver downtime penalties versus conventional plug-in charging.
- Ride-hailing platform economics:Centralized fleet procurement by mobility-as-a-service operators achieves volume discounts on electric drivetrains unavailable to fragmented owner-operator taxi markets.
Market Restraints
- Lithium carbonate price volatility:Cathode material cost swings compress manufacturer margins on fixed-price municipal fleet contracts, discourging aggressive bidding for multi-year supply agreements.
- Hydrogen infrastructure concentration:Fuel cell electric vehicle deployment remains tethered to Japan and South Korea refueling networks, limiting geographic scalability for this drivetrain variant.
- EU F-Gas Regulation compliance costs:CO2 heat pump thermal management systems add manufacturing complexity and warranty risk versus conventional refrigerant-based climate control.
Strategic Opportunities
- India's PLI scheme for automotive:Production-linked incentives for advanced chemistry cell manufacturing could localize battery supply chains for emerging NEV taxi fleets in Delhi and Bangalore.
- V2G grid services integration:Bidirectional charging infrastructure enables taxi fleets to monetize stationary battery capacity during off-peak hours, creating ancillary revenue streams for fleet operators.
- Battery second-life applications:Retired taxi battery packs with diminished range capability retain value for stationary energy storage, improving total lifecycle economics for fleet asset managers.
Industry Challenges
- High-voltage technician scarcity:Commercial garages lack certified personnel for lithium-ion battery diagnostics and thermal runaway containment, extending vehicle downtime during maintenance events.
- Multi-standard charging interoperability:Divergent connector protocols and payment systems across municipal networks fragment driver experience and complicate cross-border fleet operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Energy Vehicle (NEV) Taxi Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Battery Electric Vehicle, Plug-in Hybrid Electric Vehicle, Fuel Cell Electric Vehicle, Range-extended Electric Vehicle Service Type: Ride-Hailing, Car Rental, Fleet Management, Shuttle Service Charging Infrastructure: Fast Charging Stations, Standard Charging Points, Wireless Charging, Solar Charging Stations Market Segment: Urban Transport, Rural Transport, Corporate Transport, Government Fleet |
| Companies Covered | Daimler AG, Anhui Jianghuai Automobile Co Ltd (JAC), Tesla Inc., Beijing Automotive Industry Holding Co. Ltd. (BAIC), Changan Automobile Co. Ltd, BYD Company, Nissan Motor Corporation, SAIC Motor Corporation Limited, Toyota Motor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Energy Vehicle (NEV) Taxi Market Emerging Trajectories
Powertrain architectures and energy service models are converging around modular battery platforms that decouple vehicle ownership from energy asset management, restructuring traditional taxi fleet economics.
Lithium iron phosphate chemistry is consolidating as the dominant cathode material for high-cycle commercial applications. Fleet operators in China's tier-one cities specify this chemistry for its thermal stability and extended cycle life under intensive daily mileage. The technology is consolidating procurement specifications away from nickel-cobalt alternatives that carry price volatility and supply chain concentration risks.
The EU Green Deal's zero-emission urban transport mandate is accelerating municipal fleet electrification timelines across European capitals. National implementation laws are translating framework targets into binding procurement quotas for taxi cooperatives and ride-hailing platforms. German and French municipalities are responding with consolidated charging infrastructure tenders that bundle installation, maintenance, and renewable energy sourcing.
Fleet operators are unbundling vehicle acquisition from energy service contracts through battery-as-a-subscription models. This shifts capital expenditure to operating expenditure, appealing to ride-hailing platforms with investor pressure for asset-light balance sheets. The model is most visible in China where SAIC Motor's battery-swap configurations enable per-kilometer energy pricing without driver exposure to battery degradation risk.
New Energy Vehicle (NEV) Taxi Market Segmentation
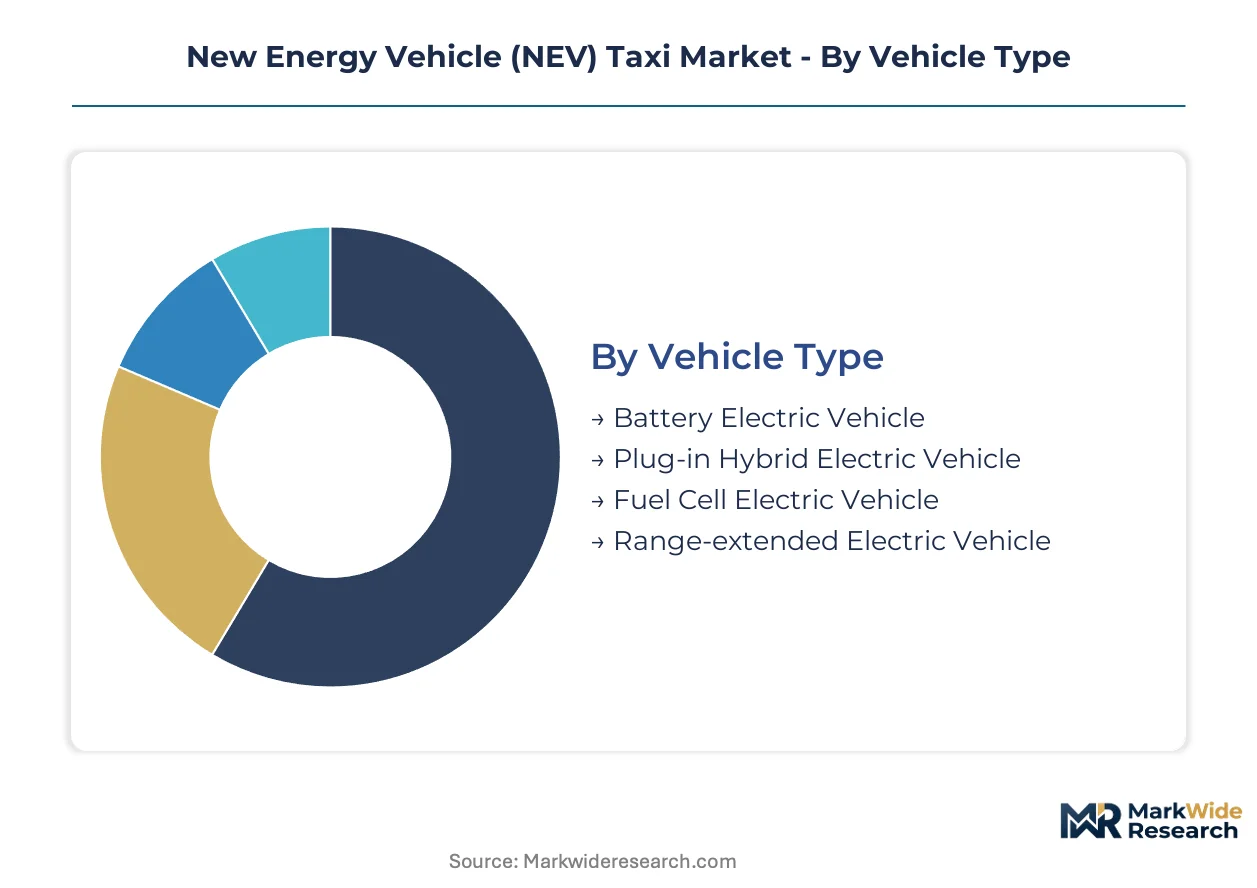
NEV taxi procurement decisions pivot on duty-cycle intensity, energy replenishment speed, and fleet ownership structure. Each segmentation dimension reveals divergent total-cost-of-ownership calculations between high-utilization ride-hailing operators and fragmented owner-driver markets.
Vehicle Type:
Fleet operators select drivetrain configurations based on daily mileage thresholds and local energy infrastructure density.
- Battery Electric Vehicle:Lithium-ion battery packs with energy densities exceeding 160 Wh/kg power these zero-tailpipe configurations. Shenzhen and Shanghai municipal mandates concentrate demand here, with battery-swap-enabled variants reducing driver downtime penalties during shift changes.
- Plug-in Hybrid Electric Vehicle:Dual-mode architectures combine electric range for urban cores with combustion backup for extended routes. European taxi cooperatives in charging-infrastructure-constrained peripheries favor this configuration for operational flexibility.
- Fuel Cell Electric Vehicle:Proton exchange membrane stacks paired with hydrogen storage tanks serve Japanese and South Korean markets with established refueling networks.
- Range-extended Electric Vehicle:Small onboard generators supplement battery capacity for intercity taxi routes where charging station density remains insufficient.
Battery Electric Vehicle leads on scale; Fuel Cell Electric Vehicle leads on momentum.
Service Type:
Platform economics and asset ownership models determine which service configurations achieve electrification viability.
- Ride-Hailing:Centralized fleet procurement by mobility-as-a-service platforms achieves volume discounts on electric drivetrains unavailable to fragmented markets. Beijing and Delhi platform operators leverage this scale for battery-as-a-service contracting.
- Fleet Management:Third-party operators bundle vehicle acquisition, maintenance, and energy provisioning for corporate clients. German and French municipalities tender consolidated charging infrastructure through these intermediaries.
- Car Rental:Short-term electric vehicle access serves tourist corridors and airport transfer segments with lower utilization intensity.
- Shuttle Service:Fixed-route operations with predictable scheduling enable optimized charging window planning for campus and corporate transport.
Ride-Hailing dominates installed capacity; Fleet Management is climbing fastest.
Charging Infrastructure:
Energy replenishment speed directly correlates with driver revenue hours in high-utilization commercial settings.
- Fast Charging Stations:DC rapid chargers delivering 80% capacity within 30 minutes anchor urban corridor networks. EU Green Deal implementation funds are consolidating these installations across Paris, Berlin, and Amsterdam taxi districts.
- Standard Charging Points:AC overnight charging serves depot-based fleet operations with extended dwell periods between shifts.
- Wireless Charging:Inductive pad systems enable opportunity charging at taxi ranks without connector handling.
- Solar Charging Stations:Photovoltaic canopy installations reduce grid dependency for daytime fleet operations in high-insolation markets.
Fast Charging Stations command deployment capital; Solar Charging Stations show steepest expansion trajectory.
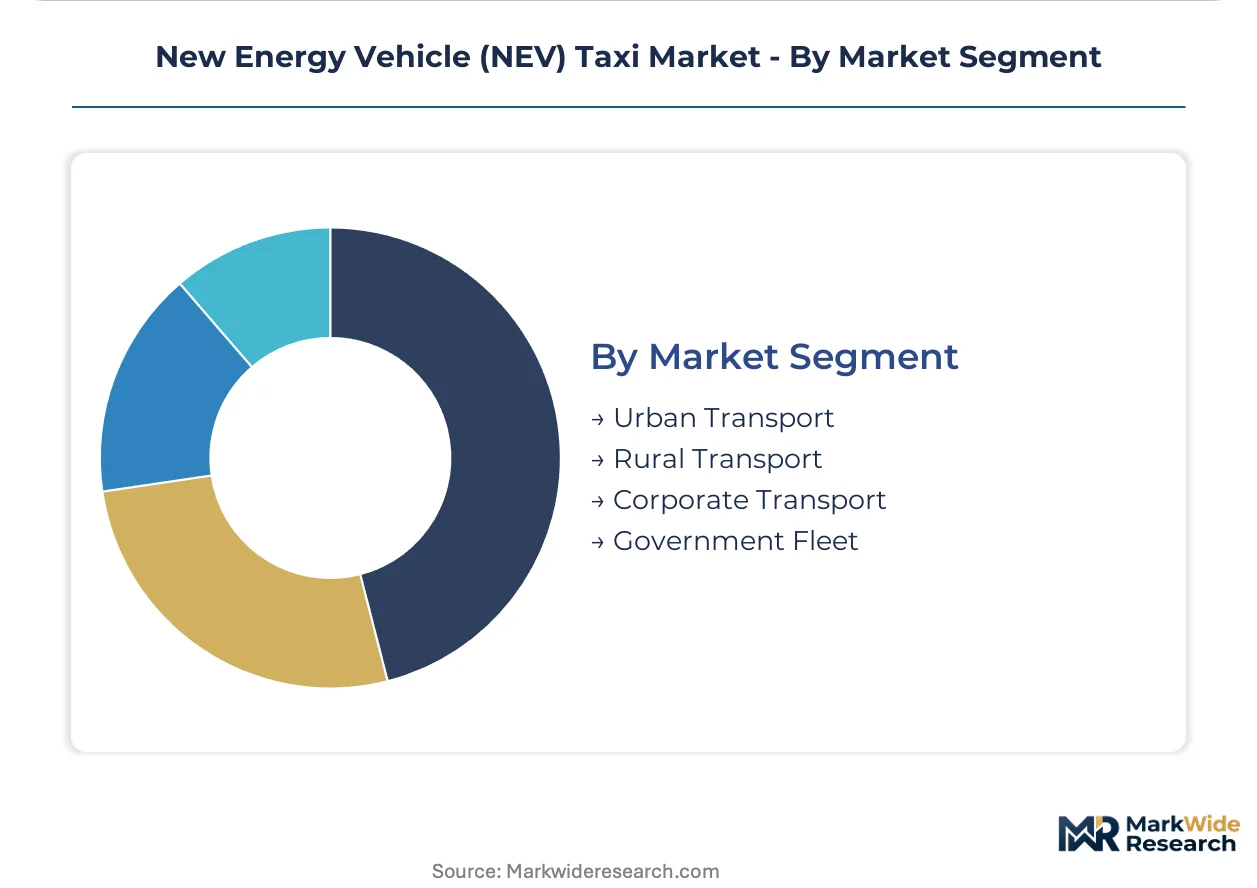
Market Segment:
Municipal procurement mandates and subsidy eligibility criteria segment demand by operator type and service territory.
- Urban Transport:Municipal zero-emission fleet mandates in Shenzhen, Beijing, and Shanghai compress replacement cycles for legacy combustion taxis. China's MIIT registration subsidies flow predominantly to this segment.
- Government Fleet:Central and local government procurement quotas prioritize domestic NEV manufacturers for official vehicle pools.
- Corporate Transport:Employee shuttle and executive car services adopt electrification for sustainability reporting compliance under EU CSRD requirements.
- Rural Transport:Lower population density and extended inter-city distances constrain battery electric viability without battery-swap infrastructure.
Urban Transport anchors volume; Corporate Transport gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's battery-chemistry talent concentration anchors the global NEV taxi supply chain, while European thermal engineering expertise and South Korean hydrogen fuel cell specialists complete the geographic capability map.
China
Shenzhen and Shanghai municipal authorities enforce complete taxi fleet electrification deadlines that eliminate fossil-fuel vehicle registrations. MIIT's GB standards for battery-swap compatibility dictate which vehicle platforms qualify for municipal subsidies. The Yangtze River Delta industrial corridor concentrates battery manufacturing capacity serving ride-hailing operators in Hangzhou and Nanjing.
Germany
Berlin and Hamburg taxi cooperatives face binding zero-emission procurement quotas under EU Green Deal national implementation laws. The KBA enforces type-approval standards that constrain thermal management system designs toward CO2 heat pump architectures. The Stuttgart industrial cluster hosts engineering centers developing range-extended electric configurations for intercity taxi routes.
United States
New York City and Los Angeles ride-hailing platforms negotiate consolidated charging infrastructure commitments with municipal authorities. The EPA's vehicle emission standards shape powertrain eligibility for fleet operator incentives. The San Francisco Bay Area anchors technology development for vehicle-to-grid integration services targeting taxi fleet ancillary revenue.
Japan
Tokyo and Osaka taxi operators deploy fuel cell electric vehicles within METI-supported hydrogen corridor networks. The national hydrogen roadmap mandates refueling station density targets that determine FCEV fleet viability. The Nagoya industrial cluster manufactures proton exchange membrane stacks for domestic taxi and export markets.
India
Delhi and Bangalore municipal corporations tender electric vehicle fleet contracts tied to PLI scheme localization requirements. The Ministry of Heavy Industries administers FAME subsidy disbursements contingent on domestic battery assembly thresholds. The Tamil Nadu industrial corridor attracts cell manufacturing investments serving emerging NEV taxi demand in Chennai.
New Energy Vehicle (NEV) Taxi Market Vendor Landscape
Capital-heavy automakers compete with asset-light mobility platforms across divergent business models. The market structure consolidates around integrated manufacturers with captive battery supply and platform operators with centralized fleet procurement scale. Three archetypes dominate: state-linked conglomerates with swap-station networks, pure-play electric specialists with proprietary charging infrastructure, and legacy OEMs with combustion-era service footprints. Competitive moves center on battery-swap standardization alliances and municipal concession bidding for charging infrastructure monopolies.
Within the integrated-manufacturer tier, BYD Company and SAIC Motor Corporation Limited exemplify state-linked conglomerates leveraging backward integration into lithium-ion cell production. Tesla Inc. occupies a position as the pure-play electric specialist with proprietary fast-charging network advantages. Among legacy OEMs transitioning powertrain portfolios, Daimler AG and Toyota Motor Corporation represent combustion-era incumbents retooling for zero-emission fleet segments.
| Leading Market Players |
|---|
| Daimler AG |
| Anhui Jianghuai Automobile Co Ltd (JAC) |
| Tesla Inc. |
| Beijing Automotive Industry Holding Co. Ltd. (BAIC) |
| Changan Automobile Co. Ltd |
| BYD Company |
| Nissan Motor Corporation |
| SAIC Motor Corporation Limited |
| Toyota Motor Corporation |
| Others |
Supply Flow & Price Mechanics
Battery-swap standardization under China's MIIT GB protocols is compressing vehicle acquisition costs while concentrating procurement power among state-linked fleet operators capable of negotiating multi-year energy service contracts. This technical shift simultaneously reduces per-kilometer operating expenditure for ride-hailing platforms and locks out fragmented owner-operators from subsidy-eligible supply tiers.
Pricing Analysis
Per-kilometer subscription pricing for battery-as-a-service dominates fleet procurement, separating premium swap-enabled configurations from standard plug-in variants from economy depot-charged models. Price differentiation rests on energy replenishment speed and thermal management certification tier. Cost compression in the economy tier is intensifying because lithium carbonate volatility squeezes fixed-contract margins. Ride-hailing platforms exhibit lowest price sensitivity due to centralized procurement scale; individual taxi cooperatives in peripheral European markets face highest budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with Chinese cathode material refining and South Korean separator membrane production. Cell manufacturing draws from lithium carbonate feedstocks anchored in Australia and Chile, plus nickel laterite concentrates from Indonesia. Tariff exposure on finished battery packs threatens European fleet operators dependent on Chinese platform imports. Distribution runs through municipal concession holders operating swap-station networks and fast-charging corridor monopolies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between China's subsidized battery-swap infrastructure and Europe's premium-priced CO2 heat pump compliance tier, exploiting a cost differential exceeding thermal management system manufacturing complexity.
For Market Incumbents: Deploy backward integration into lithium iron phosphate cell production to defend against cathode material price volatility threatening fixed-price municipal contracts. Secure MIIT GB standard certification for swap compatibility to maintain subsidy eligibility as China's tier-one cities accelerate electrification deadlines. Lock in decade-long energy service agreements with ride-hailing platforms before India's PLI scheme matures domestic supply alternatives.
For New Entrants and Emerging Players: Solid-state battery prototyping offers entry into premium fleet segments demanding extended cycle life beyond lithium-ion degradation curves. Target Delhi and Bangalore municipal tenders where PLI localization requirements have not yet concentrated supply among established incumbents. Lead with V2G grid integration software to differentiate from hardware-focused competitors.
For Investors and Strategic Acquirers: Valuations sit cheapest among battery-swap infrastructure operators with municipal concession lock-in but limited vehicle platform diversification. Long-term viability hinges on transcontinental scalability of Chinese GB standards versus European plug-in charging commitments. Monitor divergence between China's dual carbon goal implementation pace and EU Green Deal national law translation as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL and BYD cell offtake contracts secure cathode chemistry allocation for high-cycle taxi duty under MIIT GB standards. |
| Swap Station Network Expansion | SAIC Motor's consolidation of battery-swap infrastructure in Shenzhen creates municipal concession barriers for plug-in competitors. |
| CO2 Heat Pump Certification | KBA type-approval for EU F-Gas Regulation compliance unlocks Berlin and Hamburg procurement quotas under Green Deal mandates. |
| V2G Software Platform Development | Bidirectional charging integration with FERC-regulated grid services generates ancillary revenue streams for San Francisco Bay Area taxi fleets. |
| Second-Life Battery Partnership | Retired pack repurposing agreements with stationary storage developers improve total lifecycle economics for fleet asset managers. |
Methodological Framework
Bottom-up fleet operator procurement modeling reconciled against top-down battery cell production tracking forms the analytical core of this study. Primary interviews with ride-hailing platform procurement directors, municipal transport authority fleet managers, Tier 1 supplier battery system engineers, and swap-station infrastructure operators combined with secondary validation from MIIT GB standard filings, EPA vehicle emission certification databases, EU Green Deal national implementation law texts, and IHS Markit vehicle registration data. Triangulation across these sources isolates true electrification penetration from subsidy-driven registration anomalies.
Historical trendline analysis of municipal fleet replacement cycles and battery chemistry cost curves established baseline growth parameters across the projection horizon. Segmentation dimensions modeled include vehicle propulsion architecture, service type ownership structure, charging infrastructure category, and regional regulatory cluster. CAGRs derive from fitted adoption curves weighted by policy mandate binding strength and infrastructure deployment schedules. Industry-specific forecast inputs incorporate lithium carbonate spot price volatility bands and hydrogen refueling station density thresholds for FCEV viability.
The model holds under sustained policy enforcement of zero-emission fleet mandates; deviation in subsidy withdrawal timelines or battery-swap standard fragmentation would shift volume concentration between vehicle platforms. Forecasts reflect documented assumptions regarding cathode chemistry cost trajectories and municipal procurement quota adherence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Singapore Electric Vehicle Market
Electric Vehicles
Electric Tuk-Tuks Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
Mexico Automotive Electric Bus Market
Electric Vehicles
Poland E-Bike Market
Electric Vehicles
ASEAN EV Battery Pack Market
Electric Vehicles
Mexico E-Bike Market
Electric Vehicles
Electric Vehicle Reducer Market
Electric Vehicles
Asia-Pacific Electric Vehicle Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market
Electric Vehicles
Folding E-Scooter Market
Electric Vehicles
Global Solar Powered Car Market
Electric Vehicles
APAC E-Bikes Market
Electric Vehicles
Australia Electric Vehicle Market
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
Worldwide EV Range Extender Market