
 Electric Vehicle Insulation Market | 2026-2036
Electric Vehicle Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Insulation Market Analysis
Automotive-grade thermal barrier specifications are rotating toward multi-layer composite architectures that withstand sustained temperatures above 800°C. DuPont de Nemours leverages its fluoropolymer expertise to dominate high-voltage cable insulation for premium EV platforms. BASF SE anchors European supply through its polyurethane foam operations serving battery enclosure applications. Morgan Advanced Materials specializes in ceramic fiber solutions that compete on extreme-temperature performance in motorsport-derived EV programs.
Electric vehicle insulation encompasses engineered materials and assemblies that manage heat flux, acoustic transmission, flame propagation, and electrical isolation across powertrain and cabin systems. Ceramic fiber mats rated to 1260°C service temperature protect battery modules during thermal runaway events, while closed-cell polymer foams dampen road noise in cabin floor assemblies. Thermal insulation leads product type demand as OEMs chase faster charging cycles that generate concentrated heat loads at cell level. Acoustic insulation grows fastest among product categories as luxury EV brands chase cabin silence parity with legacy combustion flagships. Injection molding captures margin pools among technologies by enabling complex geometries for battery pack housings at automotive production volumes.
EPA tailpipe regulations and the EU Green Deal's fleet CO2 targets tighten material flame-resistance and recyclability mandates simultaneously. NHTSA crashworthiness standards and China's GB/T battery safety protocols shape how insulation integrates with structural battery enclosures. Stakeholders must monitor divergence between regional thermal runaway test protocols as a determinant of product platform standardization versus localization.
Market Dynamics
Battery pack thermal management systems are forcing material suppliers to engineer multi-layer composites that withstand sustained temperatures above 800°C while maintaining electrical isolation properties across high-voltage architectures.
Growth Catalysts
- EU Green Deal fleet standards:Binding CO2 targets for 2035 are compelling OEMs to redesign battery enclosures with advanced thermal barriers that prevent cell-to-cell propagation during thermal runaway events.
- Ceramic fiber mat adoption:Motorsport-derived EV programs are transferring extreme-temperature insulation technologies into production vehicle platforms, validating performance at 1260°C service ratings.
- Germany's manufacturing corridor:Concentrated OEM and Tier-1 presence around Stuttgart, Munich, and Wolfsburg generates localized demand pull for automotive-grade polyurethane foam and fluoropolymer solutions.
Market Restraints
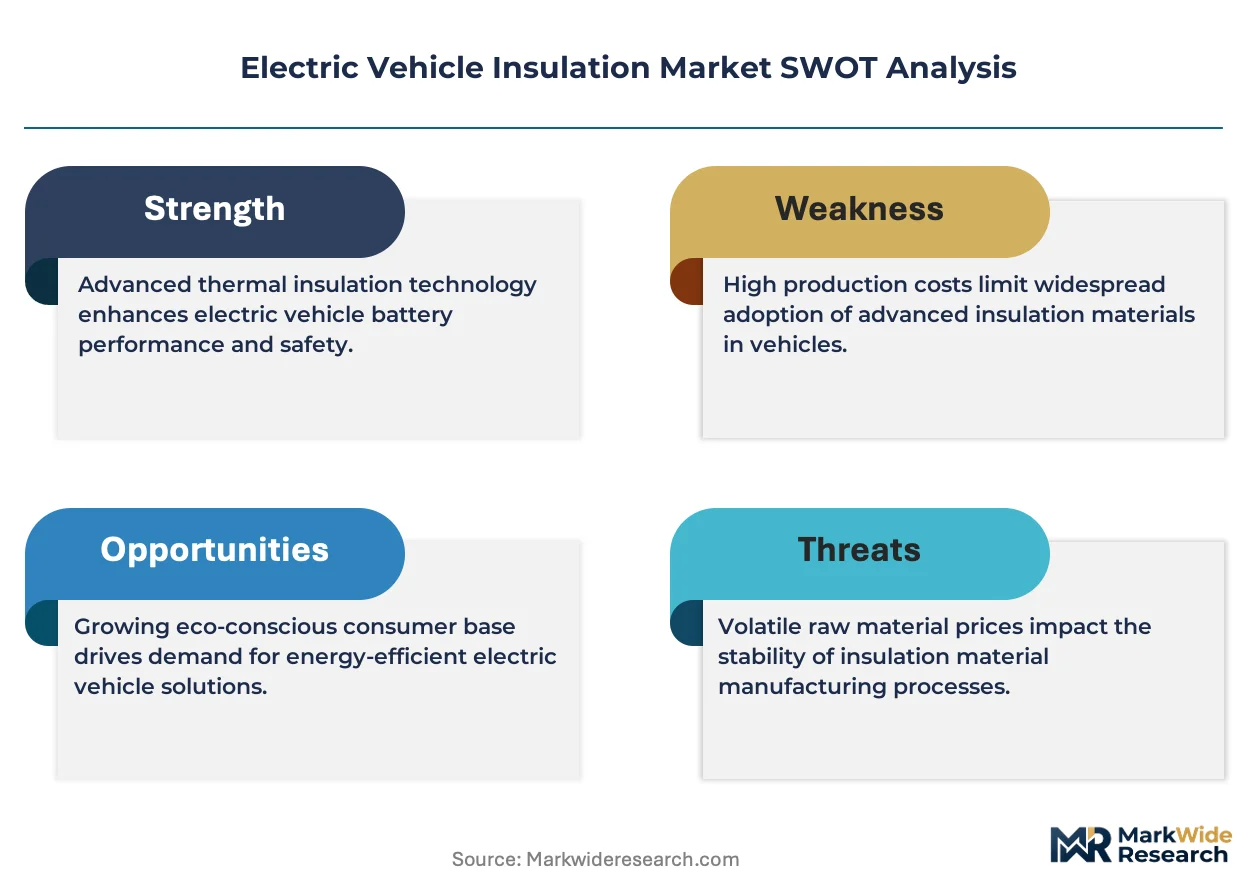
- Fluoropolymer feedstock volatility:PTFE and PVDF resin prices track fluorspar mining output concentrated in China and Mexico, exposing insulation converters to input cost swings without pass-through mechanisms.
- REACH authorization timelines:ECHA's substance evaluation procedures for flame retardants add 18-24 month certification delays before new chemistries enter European battery supply chains.
- Closed-cell foam density limits:Acoustic performance targets above 40 dB reduction require material thicknesses that encroach on cabin space budgets in compact EV platforms.
Strategic Opportunities
- India PLI scheme localization:Production-linked incentives for advanced chemistry cell manufacturing are attracting insulation suppliers to establish compounding operations near Gujarat and Tamil Nadu battery gigafactories.
- Acoustic insulation white space:Luxury EV brands pursuing cabin silence parity with combustion flagships are specifying multi-density foam assemblies that dampen road noise across frequency ranges.
- GB/T battery safety protocol alignment:China's mandatory thermal runaway propagation resistance testing is creating export certification pathways for suppliers with validated 5-minute no-fire performance data.
Industry Challenges
- Multi-physics simulation talent scarcity:Coupled thermal-electrical-mechanical modeling for battery pack insulation requires expertise in COMSOL and Ansys platforms that automotive suppliers struggle to recruit.
- Injection molding tool capex cycles:Complex geometries for battery housings demand hardened steel molds with 20-week lead times, compressing program development schedules.
- Regional test protocol divergence:NHTSA, ECE R100, and GB/T thermal runaway standards employ different ignition methods and pass-fail criteria, fragmenting product platform standardization versus localization trade-offs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Insulation Market |
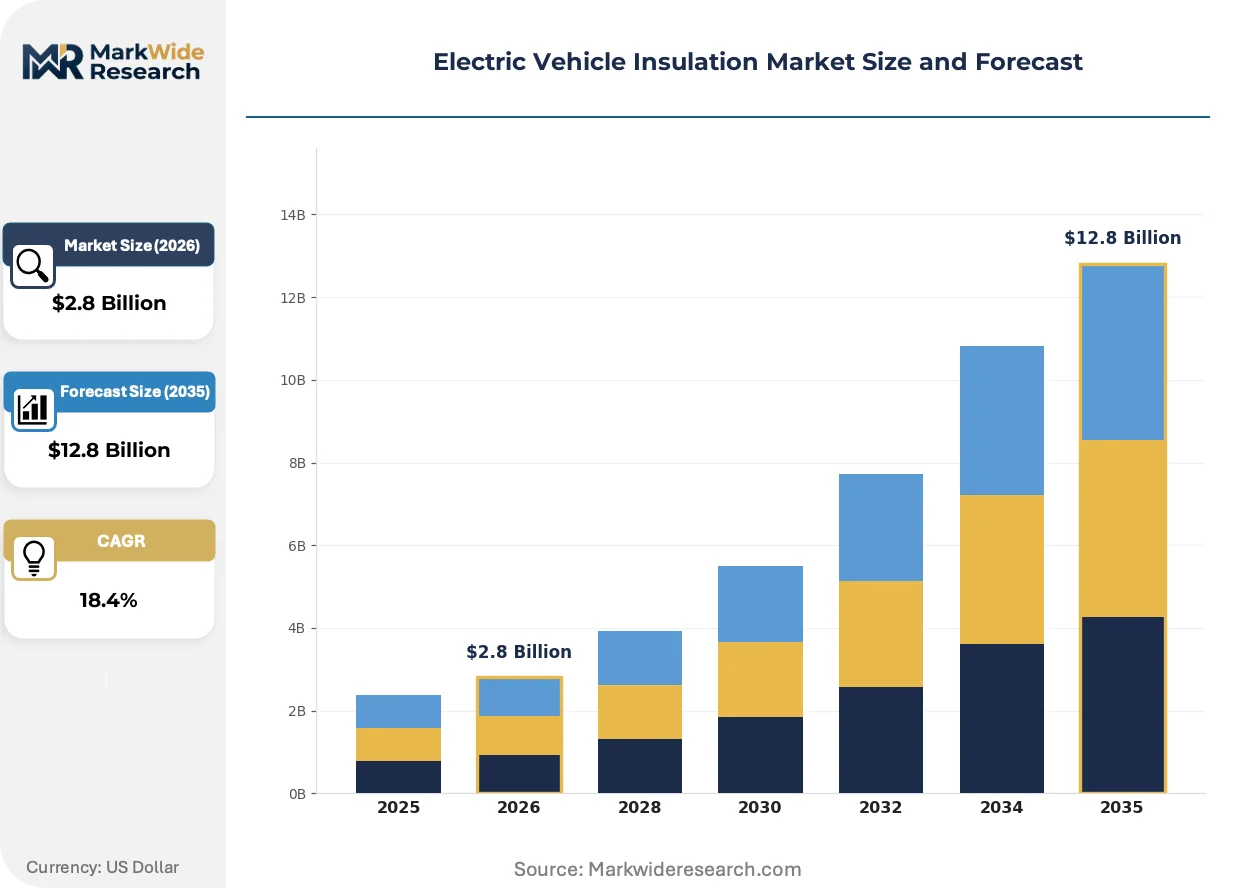
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.8 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Insulation, Acoustic Insulation, Fire-Resistant Insulation, Electric Insulation End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Material: Foam, Fiberglass, Ceramic, Polymer Technology: Injection Molding, Compression Molding, Extrusion, Laminating |
| Companies Covered | DuPont de Nemours, Inc., The Dow Chemical Company, BASF SE, Autoneum, Morgan Advanced Materials, 3M Company, Covestro AG, Rogers Corporation, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Insulation Market Emerging Trajectories
Material architectures are converging around functional integration, where single assemblies manage heat flux, acoustic transmission, and electrical isolation simultaneously rather than stacking discrete layers.
Aerogel composites are fragmenting the high-performance thermal barrier segment by replacing microporous insulation in battery pack applications. Premium EV platforms from European and Korean OEMs are specifying silica aerogel blankets for their sub-20 mW/m·K thermal conductivity and compression resilience. The technology is fragmenting procurement patterns as buyers bypass traditional ceramic fiber suppliers and contract directly with aerogel manufacturers.
REACH restriction proposals for halogenated flame retardants are accelerating substitution toward phosphorus-nitrogen intumescent systems in battery enclosure foams. ECHA's 2023-2024 regulatory scrutiny of decabromodiphenyl ether alternatives is forcing reformulation cycles across European polyurethane supply chains. Battery pack producers are responding by qualifying melamine-based char-forming additives that meet both UL 94 V-0 ratings and recyclability mandates.
Fleet operators are consolidating insulation procurement through long-term supply agreements tied to cell chemistry roadmaps rather than vehicle program cycles. Commercial EV buyers in logistics and ride-hail segments are negotiating performance warranties covering thermal runaway containment across 8-10 year service lives. This behavior is most visible in California and the Netherlands, where zero-emission fleet mandates have concentrated buyer power among large-scale electrification programs.
Electric Vehicle Insulation Market Segmentation
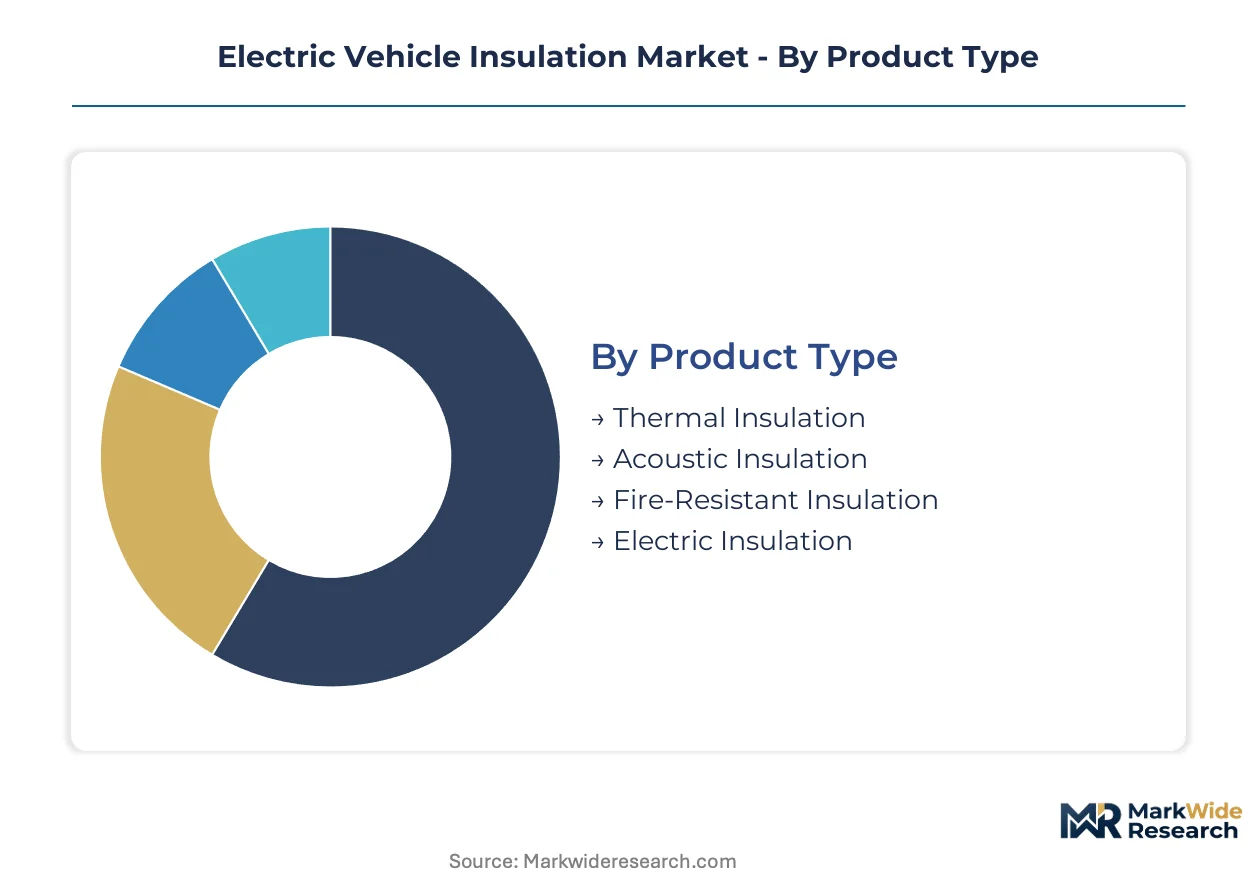
Segmentation in electric vehicle insulation reveals how regulatory pressure fragments procurement across product categories while concentrating volume in battery-adjacent applications. Material suppliers must navigate divergent certification timelines across thermal, acoustic, and electrical performance tiers.
Product Type:
REACH authorization timelines and ECHA substance evaluations create 18-24 month gaps between chemistry approval and commercial deployment across European supply chains.
- Thermal Insulation:Multi-layer composite architectures withstand sustained temperatures above 800°C in battery pack thermal management systems. Demand concentrates in Germany's automotive manufacturing corridor around Stuttgart and Munich, where OEMs redesign enclosures to meet EU Green Deal fleet CO2 targets for 2035.
- Acoustic Insulation:Closed-cell polymer foams dampen road noise in cabin floor assemblies, with luxury EV brands chasing cabin silence parity with legacy combustion flagships. Multi-density foam assemblies spanning frequency ranges are expanding most quickly among product categories as premium platforms specify complex damping geometries.
- Fire-Resistant Insulation:Ceramic fiber mats rated to 1260°C service temperature protect battery modules during thermal runaway events, validated under China's GB/T battery safety protocols.
- Electric Insulation:Fluoropolymer solutions maintain electrical isolation across high-voltage architectures, though PTFE and PVDF resin prices track fluorspar mining output concentrated in China and Mexico.
Established volume favors thermal insulation; emerging adoption favors acoustic insulation.
End User:
Procurement authority is shifting from vehicle program cycles toward long-term supply agreements tied to cell chemistry roadmaps.
- OEMs:Direct specification of aerogel composites and ceramic fiber solutions for premium EV platforms, bypassing traditional supplier tiers. California and Netherlands fleet operators negotiate performance warranties covering 8-10 year thermal runaway containment.
- Tier-1 Suppliers:Injection molding operations for battery pack housings at automotive production volumes, managing 20-week hardened steel mold lead times.
- Aftermarket Providers:Replacement insulation for collision repair and battery refurbishment, constrained by diagnostic access to proprietary thermal management systems.
- Vehicle Assemblers:Integration of multi-physics assemblies managing heat flux, acoustic transmission, and electrical isolation simultaneously.
Direct OEM relationships capture margin; Tier-1 partnerships capture volume scale.
Material:
Feedstock volatility and recyclability mandates are forcing substitution patterns across polymer and ceramic supply chains.
- Foam:Polyurethane operations anchored by BASF SE serve battery enclosure applications across European manufacturing corridors.
- Ceramic:Morgan Advanced Materials specializes in fiber solutions competing on extreme-temperature performance in motorsport-derived EV programs.
- Polymer:DuPont de Nemours leverages fluoropolymer expertise for high-voltage cable insulation, exposed to input cost swings without pass-through mechanisms.
- Fiberglass:Cost-effective thermal barriers for non-battery applications, facing displacement by aerogel composites in premium platforms.
Ceramic commands performance premiums; foam dominates unit economics.
Technology:
Tooling capex cycles and multi-physics simulation talent scarcity compress program development schedules for complex geometries.
- Injection Molding:Captures margin pools by enabling complex geometries for battery pack housings at automotive production volumes. Programs demand COMSOL and Ansys platform expertise that automotive suppliers struggle to recruit.
- Compression Molding:Lower tooling costs for ceramic fiber mat consolidation, serving thermal runaway containment applications.
- Extrusion:Continuous profiles for cable insulation and sealing systems, aligned with high-voltage architecture scaling.
- Laminating:Multi-layer functional integration where single assemblies replace discrete stacked layers.
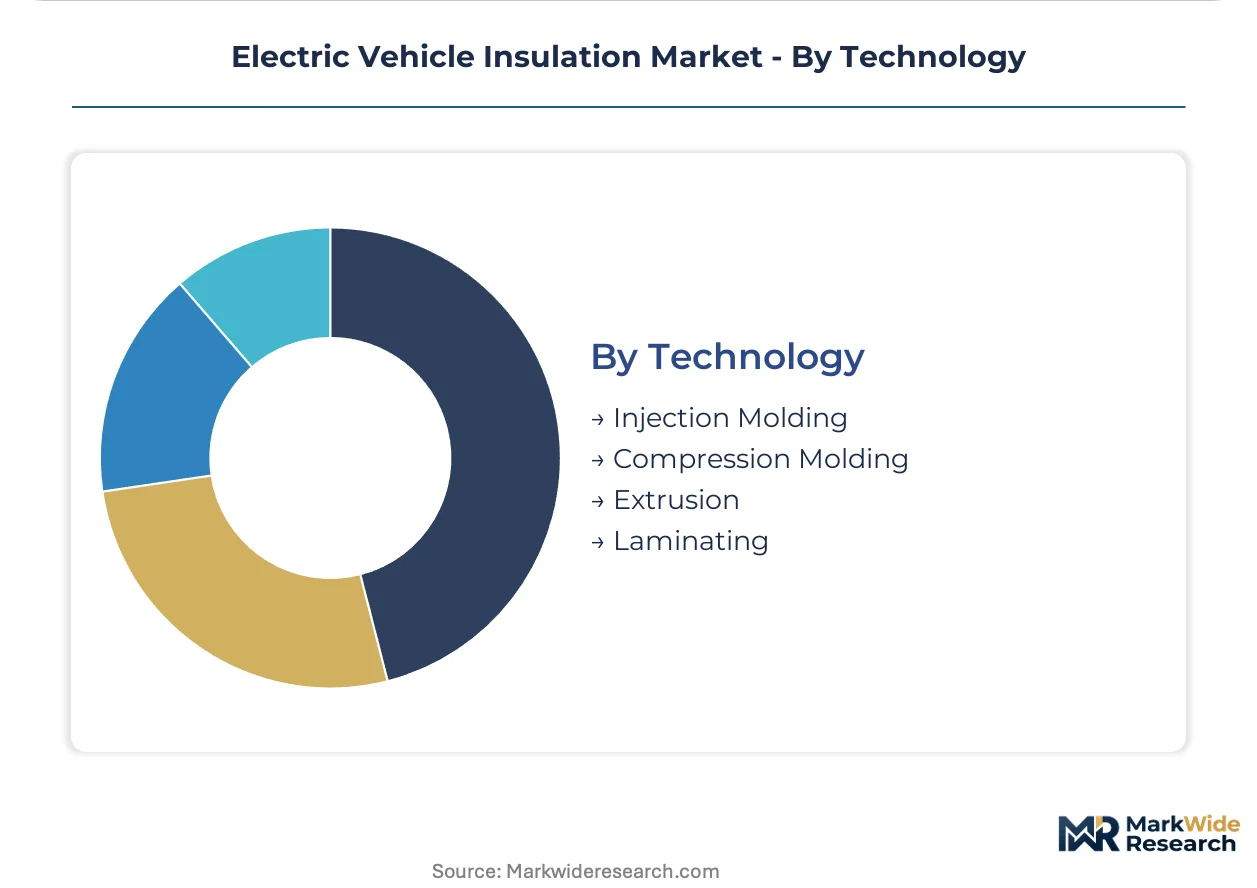
Injection molding leads revenue concentration; laminating offers steepest expansion trajectory for integrated architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in electric vehicle insulation track the geographic spread of battery gigafactory investments. Countries with concentrated cathode and cell production attract insulation suppliers seeking co-location advantages. Regional regulatory divergence on thermal runaway testing creates localized certification requirements that shape supplier footprints.
Germany
OEM engineering centers in Stuttgart and Munich drive specification authority for multi-layer thermal barriers. EU Green Deal fleet CO2 targets for 2035 compel redesign of battery enclosures with advanced fire-resistant materials. The Baden-Württemberg manufacturing corridor hosts BASF SE polyurethane operations serving European battery enclosure demand.
China
Domestic EV production exceeding seven million units annually generates unmatched volume demand for ceramic fiber and aerogel solutions. GB/T battery safety protocols mandate thermal runaway propagation resistance testing with 5-minute no-fire performance criteria. Yangtze River Delta gigafactory clusters near Shanghai attract insulation compounders seeking direct OEM supply relationships.
United States
IRA production tax credits for domestic battery manufacturing accelerate insulation localization decisions. NHTSA crashworthiness standards shape integration of thermal barriers with structural battery enclosures. Michigan and Ohio automotive corridors concentrate Tier-1 injection molding capacity for battery pack housings.
India
PLI scheme incentives for advanced chemistry cell manufacturing attract insulation suppliers to Gujarat and Tamil Nadu. Central Electricity Authority battery safety guidelines establish thermal management performance floors for domestic EV platforms. The Delhi-Mumbai Industrial Corridor hosts emerging compounding operations serving nascent battery gigafactories.
South Korea
Premium EV platform exports from Hyundai and Kia drive demand for fluoropolymer high-voltage cable insulation. Ministry of Trade, Industry and Energy battery R&D programs fund next-generation thermal barrier development. Busan-Ulsan manufacturing belt concentrates polymer compounding expertise for automotive supply chains.
Electric Vehicle Insulation Market Vendor Landscape
Listed leaders compete with private specialists across material technology tiers, creating a bifurcated structure where scale-driven chemical conglomerates face focused ceramic and polymer converters. The market organizes around three strategic archetypes: diversified materials giants with fluoropolymer and polyurethane portfolios, specialized ceramic fiber manufacturers with motorsport heritage, and emerging aerogel pure-plays disrupting high-performance thermal barriers. Dominant competitive moves include backward integration into fluorspar and petrochemical feedstocks, plus geographic co-location with battery gigafactory investments.
Among diversified chemical conglomerates, DuPont de Nemours, Inc. and BASF SE exemplify the scale-driven archetype with integrated polymer operations spanning multiple insulation categories. Morgan Advanced Materials occupies a specialist position within the ceramic fiber tier, leveraging technical ceramics heritage. The Dow Chemical Company and Covestro AG represent the polyurethane-centric segment serving battery enclosure applications. Rogers Corporation and 3M Company sit within the advanced materials tier with electrical and thermal management portfolios. Autoneum anchors acoustic insulation specialization for cabin applications.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| The Dow Chemical Company |
| BASF SE |
| Autoneum |
| Morgan Advanced Materials |
| 3M Company |
| Covestro AG |
| Rogers Corporation |
| Saint-Gobain |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between automotive OEMs and fluoropolymer converters lock in supply access and price visibility across volatile PTFE and PVDF resin markets, insulating battery pack producers from fluorspar mining disruptions concentrated in China and Mexico.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing structures that stratify across premium, standard, and economy tiers based on certification grade and volume scale. Price differentiation stems from UL 94 V-0 flame-resistance ratings and automotive IATF 16949 quality certification. Cost compression in standard-grade polyurethane foams is intensifying because BASF SE and Covestro AG are expanding European compounding capacity. Fleet operators negotiating 8-10 year performance warranties demonstrate lowest price sensitivity, while aftermarket collision repair channels face acute margin pressure.
Supply Chain Analysis
Strait of Malacca transit underwrites raw material flows for ceramic fiber precursors and silica aerogel feedstocks feeding Yangtze River Delta gigafactory clusters. Supply concentrates in China for processed aerogel blankets, Germany for automotive-grade polyurethane systems, and South Korea for fluoropolymer cable insulation. Raw material dependencies include fluorspar ore, petrochemical-derived polyols, and alumina-silica ceramic precursors. Single-source vulnerability runs through Chinese fluorspar processing. Distribution runs through Tier-1 converter networks co-located with battery enclosure assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's 2035 fleet CO2 targets represent a regulatory inflection accelerating material substitution cycles and compressing certification timelines for thermal barrier suppliers.
For Market Incumbents: Consolidate backward integration into fluorspar and petrochemical feedstocks to defend margin position against resin price volatility. Lock in IATF 16949 certification investments ahead of REACH authorization delays for next-generation flame retardants. Capacity expansion in Gujarat and Tamil Nadu captures PLI scheme localization demand before new entrants establish compounding footholds. For New Entrants and Emerging Players: Differentiate on aerogel composite performance for premium EV platforms where procurement bypasses traditional ceramic fiber supplier tiers. Target acoustic insulation white space in luxury cabin applications where multi-density foam assemblies command specification authority. Pursue direct OEM relationships through GB/T battery safety protocol alignment and validated 5-minute no-fire performance data. For Investors and Strategic Acquirers: Capital is best deployed toward specialized ceramic fiber manufacturers with motorsport heritage and established 1260°C service temperature validation. Long-term viability over the coming decade hinges on multi-physics simulation capabilities and injection molding tool access for complex battery housing geometries. Watch for divergence between NHTSA, ECE R100, and GB/T thermal runaway test protocols as the signal for platform standardization versus localization trade-offs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar | Captive supply of PTFE and PVDF precursors insulates converters from Chinese mining output volatility. |
| GB/T Battery Safety Certification | Validated 5-minute no-fire performance data unlocks direct OEM supply relationships in Yangtze River Delta clusters. |
| Aerogel Composite Manufacturing Scale-Up | Silica aerogel blankets with sub-20 mW/m·K thermal conductivity displace microporous insulation in premium platforms. |
| Multi-Physics Simulation Talent Acquisition | COMSOL and Ansys platform expertise compresses battery pack development schedules for injection molding programs. |
| India PLI Scheme Localization | Compounding operations near Gujarat and Tamil Nadu gigafactories capture production-linked incentive benefits. |
Methodological Framework
Desk research of customs and trade flow databases, SEC 10-K filings from chemical conglomerates, and ECHA substance evaluation precedents preceded structured interviews with OEM platform engineers, Tier-1 procurement leads, thermal management R&D directors, and aftermarket collision repair operators. Secondary validation drew from IHS Markit vehicle production data, EU Green Deal regulatory impact assessments, and battery safety protocol documentation. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Variance decomposition across product type, material technology, end-user procurement authority, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories and value-per-unit assumptions. Industry-specific forecast inputs included cell chemistry roadmap disclosures from major battery producers and thermal runaway test protocol evolution timelines from NHTSA, ECE R100, and GB/T standard bodies.
The analysis sits within stated boundaries; outcomes outside sustained EV production scaling and current regulatory enforcement intensity would require recalibration. Forecasts reflect documented assumptions on material substitution rates and certification timeline adherence. Practitioners should keep alternative scenarios live as REACH restriction proposals for halogenated flame retardants and IRA domestic content requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Unicycle Market
Electric Vehicles
Electric Light Commercial Vehicle Lithium-Ion Battery Market
Electric Vehicles
Asia-Pacific Lithium-Ion Battery for Electric Vehicle Market
Electric Vehicles
Electric Tricycle Market
Electric Vehicles
Automotive Intelligent Battery Sensor Market
Electric Vehicles
Silicone in Electric Vehicles Market
Electric Vehicles
Electric Vehicle Skateboard Platform Market
Electric Vehicles
Mexico Solar E-Bike Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
Electric Vehicle Thermal Management Market
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
Lithium Battery Electric Scooters Market
Electric Vehicles
Luxury Electric Vehicle Market
Electric Vehicles
Electric Vehicle Liquid Cold Plates Market
Electric Vehicles
EV Transmission System Market
Electric Vehicles
Electric Vehicle on Board Charger Market