
 Asia-Pacific Electric Bus Market | 2026-2036
Asia-Pacific Electric Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Electric Bus Market Outlook
China GB/T 34014 battery certification is unwinding supplier eligibility across the Asia-Pacific electric bus supply base. BYD leverages in-house cell production to control cost structures across ASEAN markets. Tata Motors anchors its position through captive chassis and powertrain integration at Indian plants. Yutong Bus Co., Ltd. dominates export volumes into Central Asian republics with standardized platform architectures.
An electric bus is a road vehicle powered by electric traction motors drawing energy from onboard battery packs, fuel cells, or hybrid electric systems, typically operating at 350-800V DC architectures with regenerative braking functionality, designed for scheduled passenger transit routes. Battery Electric Bus configurations currently capture the dominant production share as cell energy densities improve and thermal management costs decline. Fast Charging Stations infrastructure is expanding fastest among charging modalities, though Depot Chargers retain stronger margin pools due to lower grid interconnection complexity and longer asset amortization cycles.
India's FAME III scheme, China's MIIT new energy vehicle catalog, and Japan's METI green innovation fund collectively shape product qualification thresholds and subsidy access across the region. These frameworks mandate minimum domestic content ratios, battery recycling accountability, and vehicle-to-grid interoperability standards that filter market participants. Stakeholders must track how subsidy phase-out timelines intersect with battery cost curves to calibrate manufacturing capacity commitments against import tariff schedules.
Market Dynamics
China's MIIT battery-swap standards and India's FAME subsidy regime are forcing manufacturers to localize supply chains while tier-one megacities concentrate procurement authority in fewer hands.
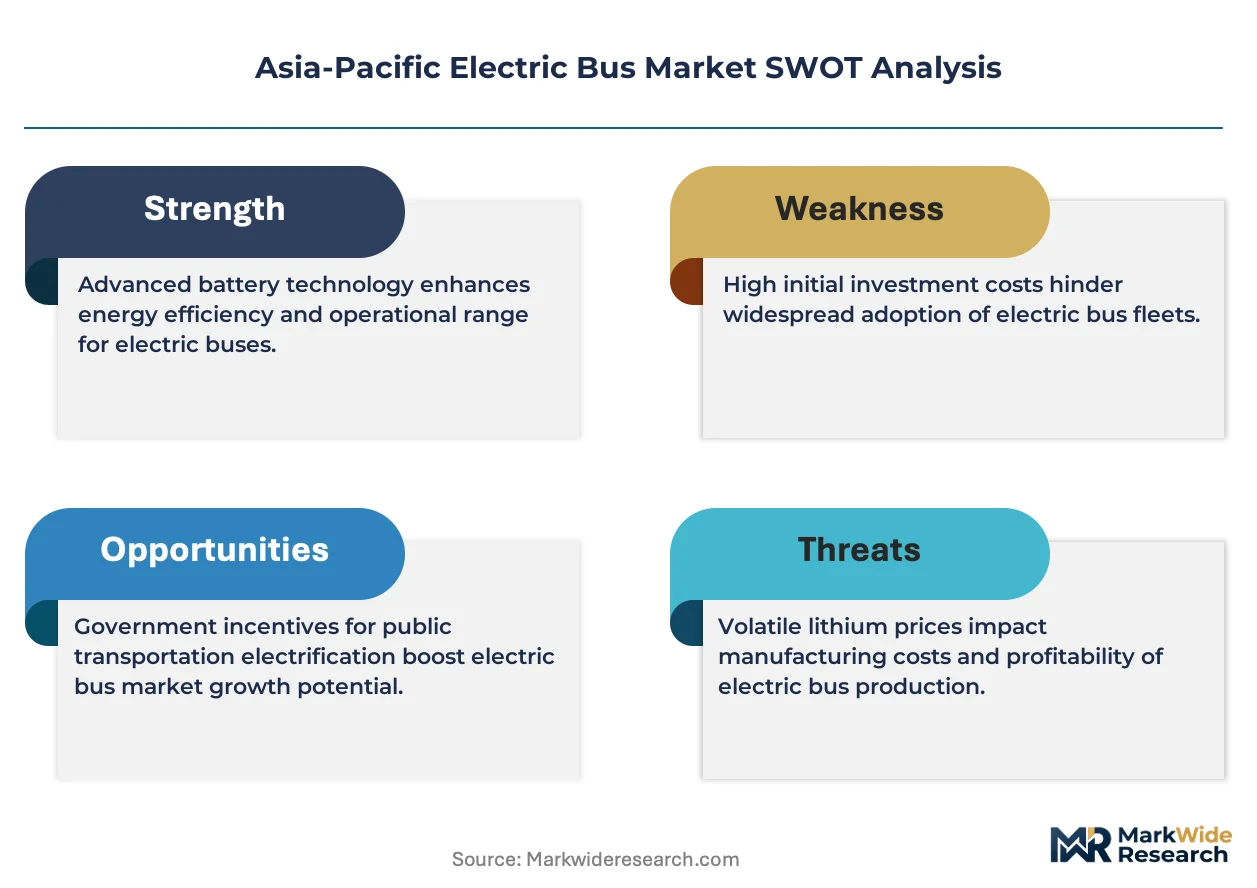
Growth Catalysts
- FAME III subsidy regime:India's production-linked incentive structure mandates minimum domestic content ratios, pulling cell pack assembly into Gujarat and Tamil Nadu manufacturing zones.
- 350-800V DC architectures:Higher-voltage platforms reduce copper harnessing weight and enable faster charge acceptance, improving route utilization rates for city transit authorities.
- Shenzhen fleet mandates:The city's complete electrification of municipal bus operations provides operational data that de-risks procurement decisions for other Chinese provincial capitals.
Market Restraints
- Lithium carbonate price volatility:Cell input cost swings compress assembler margins when transit authorities lock multi-year procurement contracts at fixed pricing.
- GB/T 34014 certification concentration:China's battery qualification standards limit eligible suppliers to domestic cell producers, restricting ASEAN fleet operators' sourcing flexibility.
- Grid interconnection complexity:Fast charging stations require distribution network upgrades that utilities in Indonesian and Philippine secondary cities cannot prioritize.
Strategic Opportunities
- Vietnam's urban transit expansion:Ho Chi Minh City and Hanoi lack domestic bus manufacturing, creating import substitution potential for Thai and Chinese assemblers with local partnership structures.
- Vehicle-to-grid interoperability:Japan's METI green innovation fund rewards bi-directional charging capabilities that turn depot fleets into grid stabilization assets during peak demand.
- Battery leasing models:Separation of vehicle and energy asset ownership lowers upfront capital barriers for Indian state transport undertakings with constrained fiscal capacity.
Industry Challenges
- Power electronics engineering scarcity:Inverter and thermal management system design expertise concentrates in Shenzhen and Seoul, forcing ASEAN assemblers to license foreign IP.
- Depot charger certification timelines:India's CEA electrical safety approvals for 150kW+ infrastructure extend deployment schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Electric Bus Market |
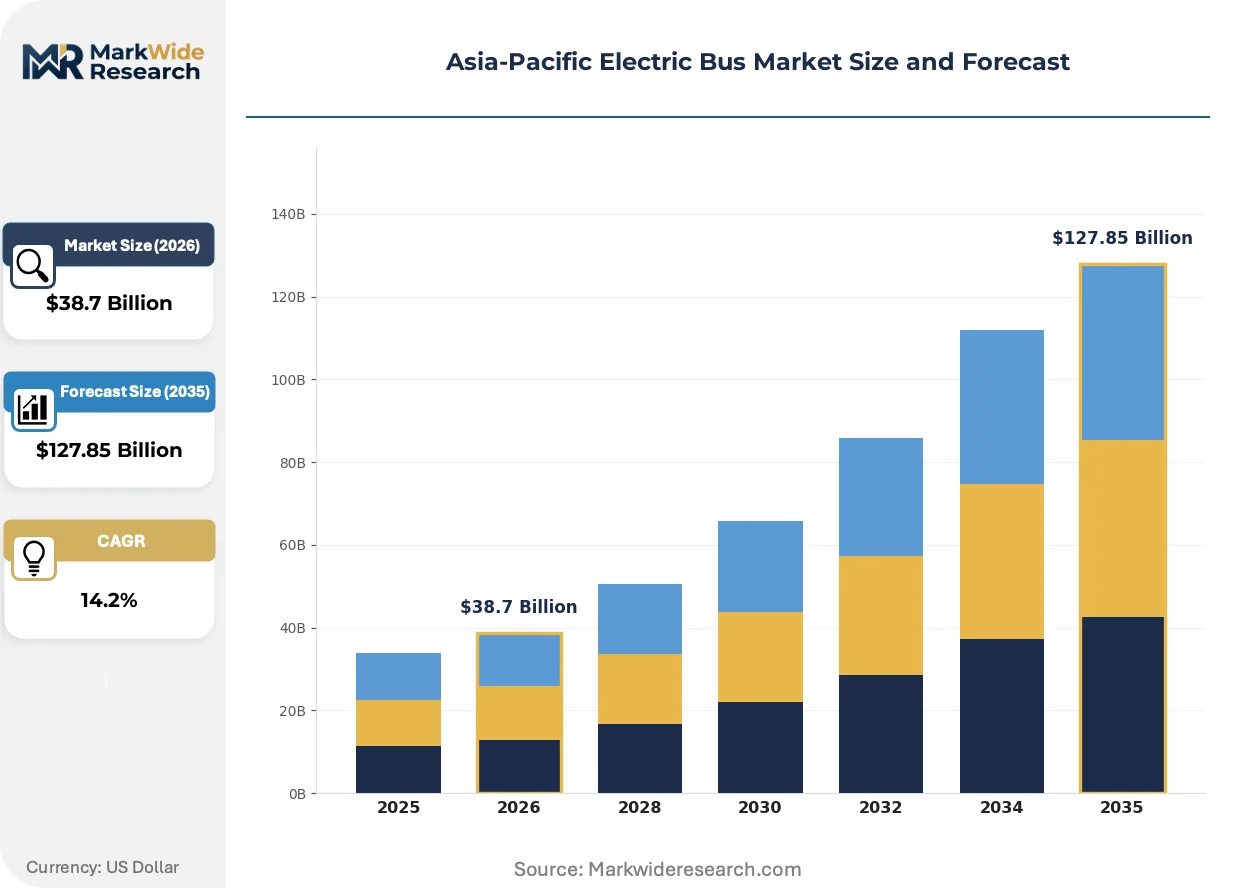
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Electric Bus, Plug-In Hybrid Bus, Fuel Cell Bus, Others End User: Public Transportation, Private Operators, School Districts, Urban Mobility Charging Infrastructure: Fast Charging Stations, Depot Chargers, Wireless Charging, On-Route Chargers Vehicle Size: Standard Bus, Articulated Bus, Mini Bus, Double-Decker Bus |
| Companies Covered | Tata Motors, Ashok Leyland, BYD, Higer Bus, King Long United Automotive Industry Co., Ltd., Yutong Bus Co., Ltd., Hyundai Motor Company, JBM Auto Ltd., Zhongtong Bus Holding Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Electric Bus Market Strategic Shifts
Electrification architectures are converging with energy storage and grid management systems, blurring traditional boundaries between vehicle OEMs, utilities, and charging infrastructure providers across the region.
Solid-state cell chemistries are displacing liquid electrolyte lithium-ion configurations in premium long-range bus specifications. Japanese and South Korean material suppliers are shipping pilot volumes to Australian and Singaporean fleet operators seeking 400km+ daily range without midday charging. This chemistry transition is compressing thermal management system costs while extending asset replacement cycles.
China's MIIT new energy vehicle catalog revisions now mandate real-time battery health monitoring and second-life traceability. The regulation forces assemblers to integrate telematics hardware and recycling partnerships from vehicle design phase. Bus operators in Chengdu and Xi'an face compliance audits that disqualify non-certified suppliers from municipal tenders.
Aggregated fleet procurement consortia are consolidating buyer power across Indian state transport undertakings. Tamil Nadu and Maharashtra road transport corporations now coordinate tender specifications and volume commitments, squeezing assembler pricing flexibility. This concentration is visible in Karnataka's recent 5,000-unit single-tender structure that awarded sole-supplier status for standardized platform architectures.
Asia-Pacific Electric Bus Market Segmentation
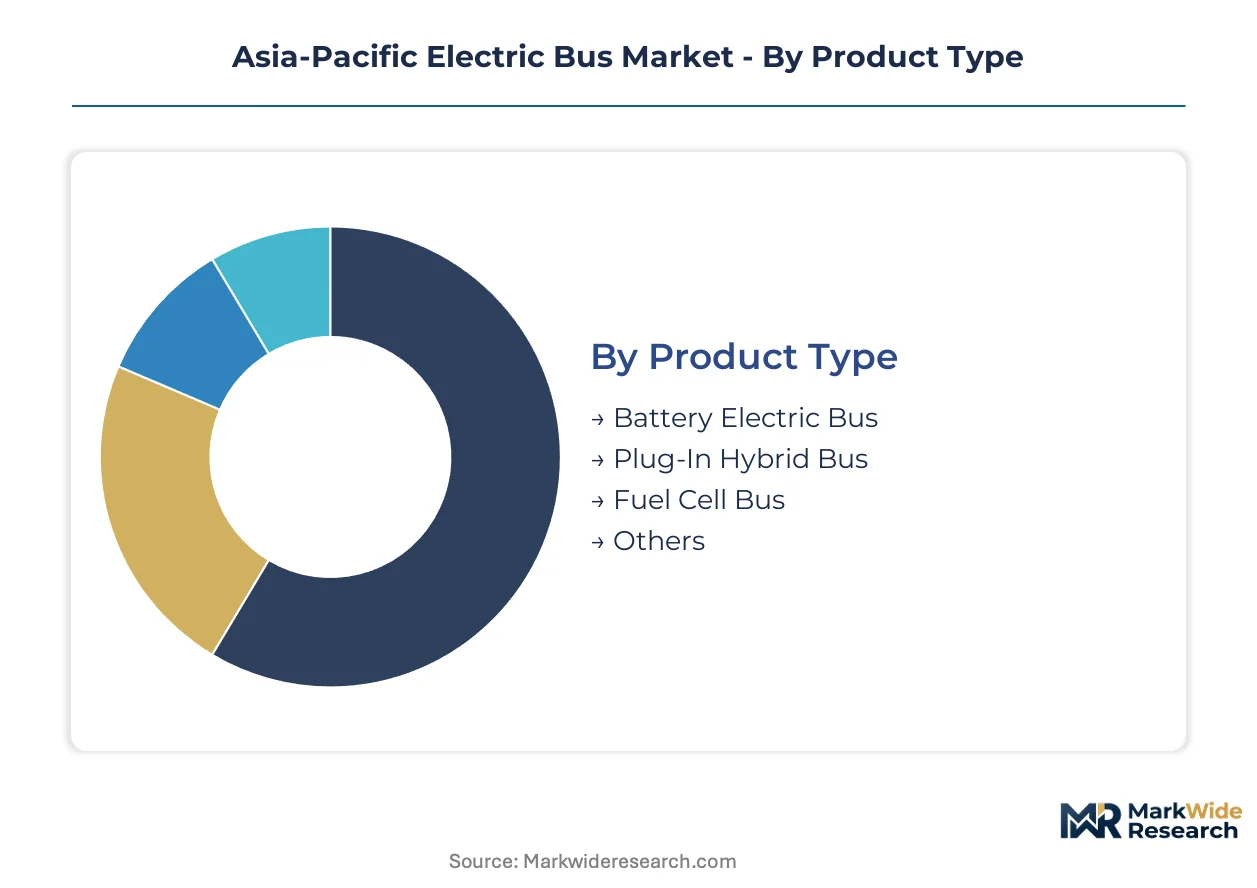
Segmentation reveals how procurement authority concentrates among city transit authorities versus private fleet operators, and how charging infrastructure choices lock in operational architectures for decades. Understanding these divides exposes where margin pools accumulate and which technology transitions threaten incumbent positions.
Product Type:
Domestic absorption dominates in China and India, while fuel cell configurations find traction in Japanese and Australian export corridors.
- Battery Electric Bus:These vehicles operate on 350-800V DC architectures with regenerative braking and liquid-cooled lithium-ion packs. Demand clusters in Shenzhen, Delhi, and Jakarta where municipal mandates eliminate diesel procurement from tier-one city tenders. Cell cost declines and MIIT battery-swap standards are compressing total cost of ownership below diesel parity.
- Plug-In Hybrid Bus:Combustion-electric dual-mode systems with 50-150km electric-only range and onboard range extenders. Indian state transport undertakings in Maharashtra and Karnataka favor this segment for intercity routes lacking depot charging infrastructure, hedging against grid reliability constraints.
- Fuel Cell Bus:Proton exchange membrane systems with 350-700 bar hydrogen storage, deployed by METI-funded consortia in Tokyo and Fukuoka prefectures.
- Others:Trolleybus retrofits and capacitor-based systems retain niche presence in former Soviet-aligned Central Asian networks.
Battery Electric Bus commands the established base. The steepest expansion runs through Fuel Cell Bus.
End User:
Procurement scale and subsidy access separate concentrated public authority buyers from fragmented private capital.
- Public Transportation:Municipal corporations and state road transport undertakings with fleet sizes exceeding 1,000 units. These buyers leverage FAME III production-linked incentives and coordinate tender specifications across Tamil Nadu, Maharashtra, and Karnataka, extracting volume pricing from assemblers.
- Private Operators:Airport shuttle consortia, corporate campus fleets, and intercity coach services with 50-200 unit deployments. These operators face capital constraints that battery leasing models address, separating vehicle ownership from energy asset exposure.
- School Districts:Subnational education authorities in Australian states and Japanese prefectures with dedicated route structures and midday dwell times suited to depot charging.
- Urban Mobility:Micromobility integrators and on-demand shuttle platforms in Ho Chi Minh City and Bangkok experimenting with mini-bus electrification for last-mile connectivity.
Public Transportation absorbs the dominant procurement volume. Private Operators are climbing the fastest as battery leasing structures unlock capital-constrained segments.
Charging Infrastructure:
Margin pools diverge between high-interconnection-complexity fast charging and amortization-favorable depot configurations.
- Fast Charging Stations:150-450kW pantograph or plug-in systems enabling 10-15 minute opportunity charging at route termini. Shenzhen and Singapore deploy these at highest density, though Indonesian and Philippine utilities struggle with distribution network upgrade timelines.
- Depot Chargers:50-150kW overnight systems with lower grid interconnection complexity and 15-20 year asset amortization cycles. These retain stronger margin pools for infrastructure providers and dominate Indian and Vietnamese procurement.
- Wireless Charging:Inductive pad systems embedded in bus stops, piloted by Japanese METI-funded projects in Nagoya and Kobe for route electrification without overhead catenary.
- On-Route Chargers:Opportunity charging at intermediate stops via overhead pantograph or ground-level conductive rails, deployed in Brisbane and Sydney for high-frequency corridor services.
Depot Chargers hold the installed base. Fast Charging Stations are gaining share fastest where grid capacity permits.
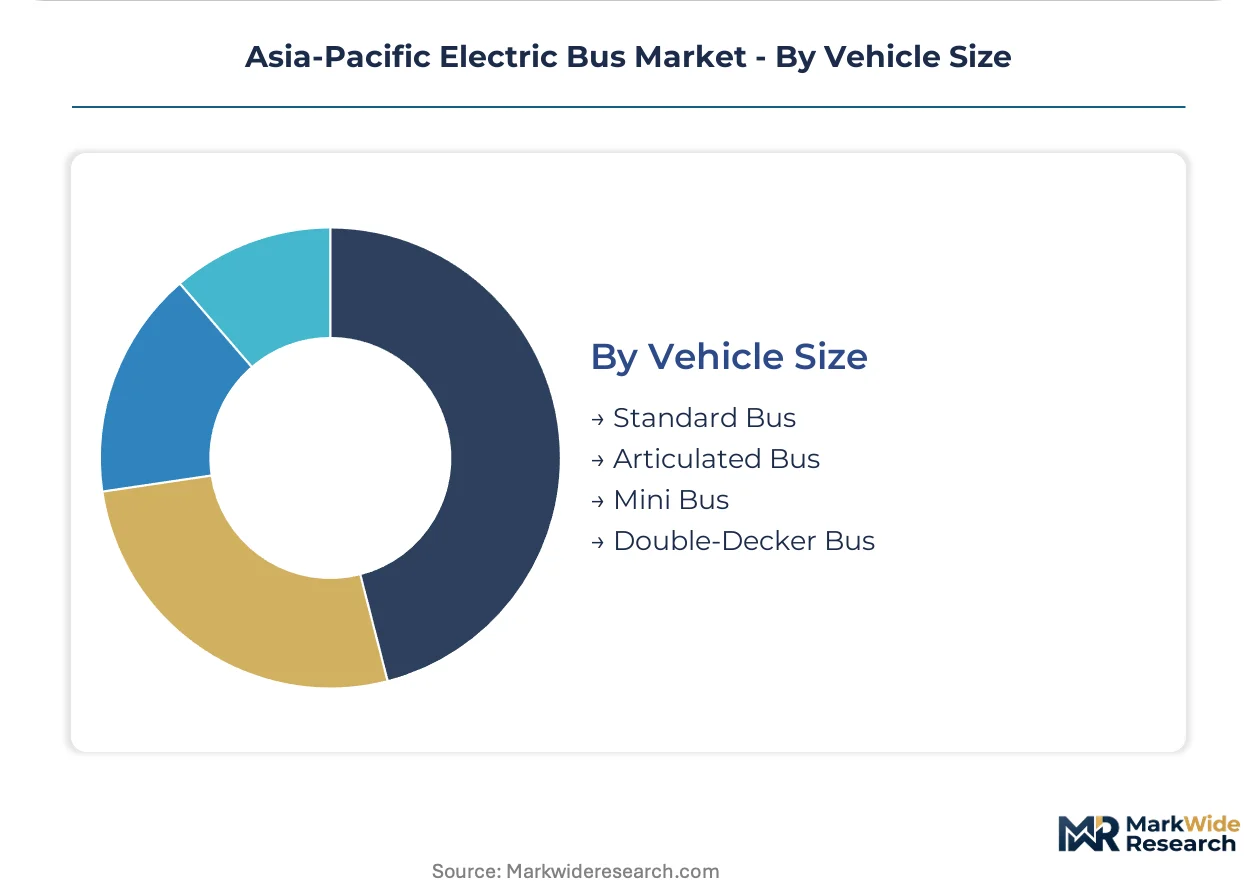
Vehicle Size:
Platform standardization versus customization tension plays out across corridor capacity requirements and import tariff structures.
- Standard Bus:10-12 meter single-deck configurations with 60-80 passenger capacity, dominating procurement in Chinese tier-one megacities and Indian state transport undertakings. These platforms achieve lowest per-unit cost through volume production at Gujarat and Tamil Nadu assembly plants.
- Articulated Bus:18-meter bendy-bus designs with 120-150 passenger capacity for high-volume corridors in Seoul, Singapore, and Sydney where platform dwell time minimization justifies premium capital outlay.
- Mini Bus:6-9 meter configurations for narrow street networks in Hanoi, Ho Chi Minh City, and secondary Indonesian cities lacking domestic manufacturing.
- Double-Decker Bus:Two-level designs retaining presence in Hong Kong, Singapore, and Australian state capitals with established depot height clearances and strong passenger volume per road space constraints.
Standard Bus captures the volume base. Articulated Bus shows the steepest expansion trajectory where corridor density justifies capacity investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAME III production-linked incentives and China's MIIT battery-swap standards are redirecting manufacturing investment toward Gujarat, Tamil Nadu, and Shenzhen industrial corridors while compressing import-dependent supply chains.
China
Shenzhen's complete municipal fleet electrification generates operational datasets that de-risk procurement for Chengdu, Xi'an, and other provincial capitals. MIIT's GB/T 34014 battery certification limits eligible cell suppliers to domestic producers, constraining ASEAN fleet operators' sourcing flexibility. BYD and Yutong Bus Co., Ltd. anchor production clusters in the Pearl River Delta and Zhengzhou respectively, exporting standardized platforms into Central Asian republics.
India
State transport undertakings in Maharashtra, Karnataka, and Tamil Nadu coordinate tender specifications through aggregated procurement consortia, extracting volume pricing from assemblers. FAME III mandates minimum domestic content ratios, pulling cell pack assembly into Gujarat and Tamil Nadu manufacturing zones. Tata Motors and Ashok Leyland operate captive chassis and powertrain integration plants in these states, supplying Delhi's expanding fleet mandates.
Japan
METI's green innovation fund rewards bi-directional charging capabilities that convert depot fleets into grid stabilization assets during peak demand periods. Fuel cell configurations find traction in Tokyo and Fukuoka prefectures through hydrogen infrastructure consortia. Hyundai Motor Company and domestic material suppliers ship pilot solid-state cell volumes to Australian and Singaporean fleet operators seeking extended daily range.
Australia
Brisbane and Sydney deploy on-route pantograph charging for high-frequency corridor services, while state education authorities in New South Wales and Victoria electrify school district fleets with depot-dominant architectures. Grid interconnection complexity limits fast charging expansion in secondary cities, favoring overnight charging infrastructure with longer amortization cycles.
Vietnam
Ho Chi Minh City and Hanoi lack domestic bus manufacturing capacity, creating import substitution openings for Thai and Chinese assemblers with local partnership structures. Depot chargers dominate procurement due to distribution network constraints, while battery leasing models address capital barriers for municipal corporations with constrained fiscal capacity.
Asia-Pacific Electric Bus Market Competitive Environment
Player mix skews toward integrated manufacturers with captive cell or chassis production, creating a tiered structure where supply security separates premium-tier participants from import-dependent assemblers. Three archetypes dominate: state-linked enterprises with preferential access to municipal tenders, vertically integrated specialists controlling cost structures through in-house component production, and regional licensees leveraging foreign IP for local assembly. Competitive intensity concentrates on manufacturing capacity commitments against subsidy phase-out timelines, and on securing CEA electrical safety approvals for 150kW+ charging infrastructure ahead of rival deployment schedules.
Within the integrated-manufacturer tier, BYD exemplifies the archetype of cell production control, while Yutong Bus Co., Ltd. anchors export-oriented platform standardization. Tata Motors occupies a position representing captive chassis and powertrain integration in protected domestic markets. Among specialists with regional licensing structures, JBM Auto Ltd. and Ashok Leyland sit within the tier serving Indian state transport undertakings through production-linked incentive compliance. King Long United Automotive Industry Co., Ltd. and Zhongtong Bus Holding Co., Ltd. represent scale-driven fabrication clusters competing on per-unit cost in standardized 10-12 meter configurations.
| Leading Market Players |
|---|
| Tata Motors |
| Ashok Leyland |
| BYD |
| Higer Bus |
| King Long United Automotive Industry Co., Ltd. |
| Yutong Bus Co., Ltd. |
| Hyundai Motor Company |
| JBM Auto Ltd. |
| Zhongtong Bus Holding Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Multi-year procurement contracts with fixed pricing clauses lock in supply access for Indian state transport undertakings while exposing assemblers to lithium carbonate volatility that compresses margins when cell input costs swing.
Pricing Analysis
Certification level (GB/T 34014 battery-grade) creates the primary spread between qualified domestic suppliers and import-dependent ASEAN operators. Contract-based long-term offtake dominates municipal tenders, with price differentiation hinging on volume scale and domestic content ratios mandated by FAME III. Pricing pressure stems from aggregated procurement consortia squeezing assembler flexibility across Tamil Nadu and Maharashtra. Indian state transport undertakings exhibit highest price sensitivity due to fiscal constraints, while Japanese METI-funded operators prioritize bi-directional charging capabilities over per-unit cost.
Supply Chain Analysis
China and South Korea anchor cell production and power electronics fabrication for the regional electric bus supply base. Lithium carbonate, copper harnessing, and thermal management systems feed from concentrated upstream sources. Single-source vulnerability runs through GB/T 34014-certified cell suppliers that restrict ASEAN fleet operators' sourcing alternatives. Distribution runs through captive assembly plants in Gujarat and Tamil Nadu serving protected domestic markets, with export corridors reaching Central Asian republics via Zhengzhou and Shenzhen industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery leasing and depot charging infrastructure represent service-attach layers expanding faster than vehicle hardware, as Indian state transport undertakings separate energy asset ownership from upfront capital deployment.
For Market Incumbents: Compound defensive positioning through backward integration into cell pack assembly and captive powertrain production at Gujarat and Tamil Nadu plants. Certification investment in CEA electrical safety approvals for 150kW+ infrastructure creates timing advantages against rival deployment schedules. Threat substitution emerges from solid-state chemistry transitions that extend asset replacement cycles beyond current lithium-ion service intervals. For New Entrants and Emerging Players: After-sales service networks in Vietnamese secondary cities present white-space where incumbents under-serve municipal corporations lacking domestic manufacturing partnerships. Battery leasing models for capital-constrained Indian state transport undertakings offer the most penetrable entry vector. Go-to-market execution should anchor on local joint venture structures that satisfy FAME III domestic content thresholds. For Investors and Strategic Acquirers: Regional licensees with foreign IP access and local assembly footprints in protected ASEAN markets present acquisition targets with tariff-advantaged positioning. Long-term viability hinges on manufacturing capacity commitments calibrated against subsidy phase-out timelines rather than import-dependent supply chains. Signal to monitor: MIIT catalog revisions tightening battery health monitoring and second-life traceability requirements that disqualify non-compliant suppliers from municipal tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Cell procurement contracts with GB/T 34014-certified producers secure qualification for Chinese municipal tenders. |
| Backward Integration | In-house powertrain assembly at Tamil Nadu plants satisfies FAME III domestic content ratio mandates. |
| Charging Infrastructure Partnership | CEA-approved depot charger deployment accelerates fleet electrification schedules for Indian state transport undertakings. |
| Platform Standardization | Unified 10-12 meter architectures reduce per-unit cost across volume procurement by Maharashtra and Karnataka consortia. |
| Software-Defined Vehicle Investment | Real-time battery health monitoring integration ensures compliance with MIIT traceability mandates in Chengdu and Xi'an. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with municipal fleet managers, state road transport procurement leads, cell pack assembly plant managers, and charging infrastructure EPC contractors. Secondary validation drew from MIIT new energy vehicle catalog filings, CEA electrical safety approval databases, FAME subsidy disbursement records, and vehicle production registration data. Bottom-up tender analysis and top-down industrial capacity assessments were triangulated to reconcile volume estimates.
Across the analysis window, projections incorporate propulsion architecture, vehicle size class, charging modality, and end-user procurement authority as segmentation dimensions. CAGRs were derived from slope-intercept modeling of historical fleet deployment trajectories against subsidy phase-out schedules and battery cost curve assumptions. Forecast inputs include lithium carbonate price volatility bands and grid interconnection capacity buildout timelines for Indonesian and Philippine distribution networks.
Underlying assumptions cover subsidy continuity through FAME III and MIIT catalog revision schedules, with deviation risk concentrated in lithium carbonate supply shocks and utility distribution upgrade delays. Recalibration cycles align with material shifts in national clean vehicle mandates and battery chemistry transition milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Construction Electric Vehicle Market
Electric Vehicles
India Hybrid Electric Vehicle Battery Market
Electric Vehicles
Europe Electric Car Market
Electric Vehicles
Folding E-Scooter Market
Electric Vehicles
Canada Solar E-Bike Market
Electric Vehicles
Luxury Electric Vehicle Market
Electric Vehicles
Middle-East E-Bike Market
Electric Vehicles
Electric Vehicle Rental Market
Electric Vehicles
Middle East Wireless EV Charging Market
Electric Vehicles
Europe Electric Scooter Market
Electric Vehicles
France Electric Bus Battery Pack Market
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
Electric Transporters Market
Electric Vehicles
Asia-Pacific Electric Vehicle Thermal Management System Market
Electric Vehicles
EV Coolants Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market