
 Asia-Pacific Electric Vehicle Thermal Management System Market | 2026-2036
Asia-Pacific Electric Vehicle Thermal Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Electric Vehicle Thermal Management System Market Outlook
The Asia-Pacific electric vehicle thermal management system supply base is restructuring around a sharp split between premium integrated systems and standalone commodity hardware. DENSO Corporation leverages its captive semiconductor and sensor portfolio to dominate high-voltage battery cooling modules. Hanon Systems anchors its position through manufacturing scale across South Korean and Chinese plants. MAHLE GmbH competes on refrigerant compatibility across multiple OEM thermal architectures.
Electric vehicle thermal management systems regulate heat flux in battery packs, electric motors, and cabin HVAC circuits through liquid coolant loops, refrigerant cycles, and phase-change materials operating at temperatures between minus forty and one hundred fifty degrees Celsius. Heat exchangers represent the most mature product category with established margin pools, while compressor electrification for heat pumps commands the fastest growth trajectory as cold-climate range retention becomes critical. OEM end users currently absorb the majority of installed value, though retrofitted solutions for government bus fleets are expanding as a secondary demand channel.
China's MIIT enforces GB/T standards for battery thermal runaway containment, while Japan's METI mandates efficiency benchmarks that directly shape heat pump adoption timelines. South Korea's MFDS and KATRI frameworks coordinate with automotive safety regulators on coolant toxicity and fire suppression protocols. Stakeholders must monitor how refrigerant transition schedules under the F-Gas Regulation interact with domestic content requirements across ASEAN manufacturing zones.
Market Dynamics
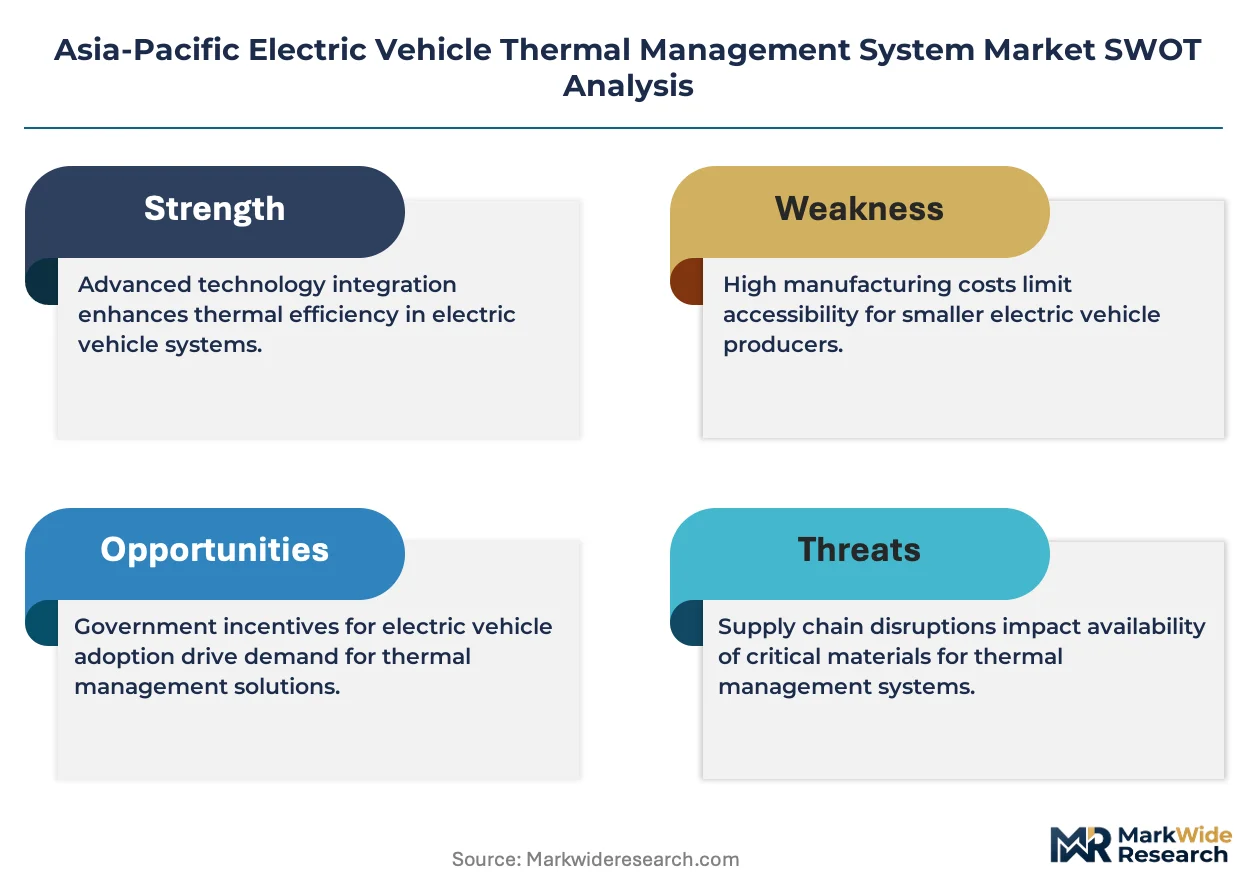
Thermal management system suppliers across Asia-Pacific face a structural squeeze between China's MIIT-mandated battery safety thresholds and the cost compression demanded by mass-market EV platforms. The divergence between premium integrated architectures and commodity hardware is hardening into two distinct supply tiers with incompatible margin structures.
Growth Catalysts
- GB/T thermal runaway standards:China's MIIT enforcement of battery containment protocols forces OEMs to upgrade cooling infrastructure across all vehicle classes, creating baseline demand for advanced heat exchangers and phase-change materials.
- Ride-sharing fleet electrification:Battery cooling intensity requirements surge as commercial operators in Indonesia, Thailand, and Vietnam deploy high-utilization EVs with rapid-charging duty cycles.
- Heat pump compressor electrification:Cold-climate range retention specifications from Japan's METI accelerate adoption of integrated refrigerant cycles that capture waste heat from power electronics.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger manufacturers absorb margin compression when base metal inputs spike, with limited pass-through power against consolidated OEM procurement desks.
- Refrigerant supply concentration:F-Gas Regulation phase-down schedules in Europe disrupt Asia-Pacific supply chains for R-134a and R-1234yf, forcing reformulation investments without guaranteed volume returns.
- Coolant toxicity compliance:South Korea's MFDS coordination with KATRI on fire suppression protocols adds testing burdens that extend qualification timelines for new thermal fluid formulations.
Strategic Opportunities
- Retrofit bus fleet channel:Government electrification mandates in the Philippines and Malaysia create secondary demand for modular cooling systems that integrate with legacy chassis architectures.
- Refrigerant transition tailwind:Japan's METI efficiency benchmarks accelerate heat pump adoption timelines, opening white space for suppliers with CO2-compatible compressor portfolios.
- Sensor-cooling convergence:Integration of thermal management with battery state-of-health monitoring creates bundled value propositions for fleet operators seeking predictive maintenance capabilities.
Industry Challenges
- Systems integration engineering scarcity:Shortage of specialists capable of optimizing multi-loop thermal architectures across battery, motor, and cabin circuits delays platform launches.
- Dual certification timelines:Parallel validation against China's GB standards and Japan's JIS protocols fragments R&D resources for suppliers serving multiple OEM footprints.
- Legacy HVAC supplier repositioning:Incumbent compressor manufacturers face capability gaps in high-voltage electrification that require capital-intensive retooling of test facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Electric Vehicle Thermal Management System Market |
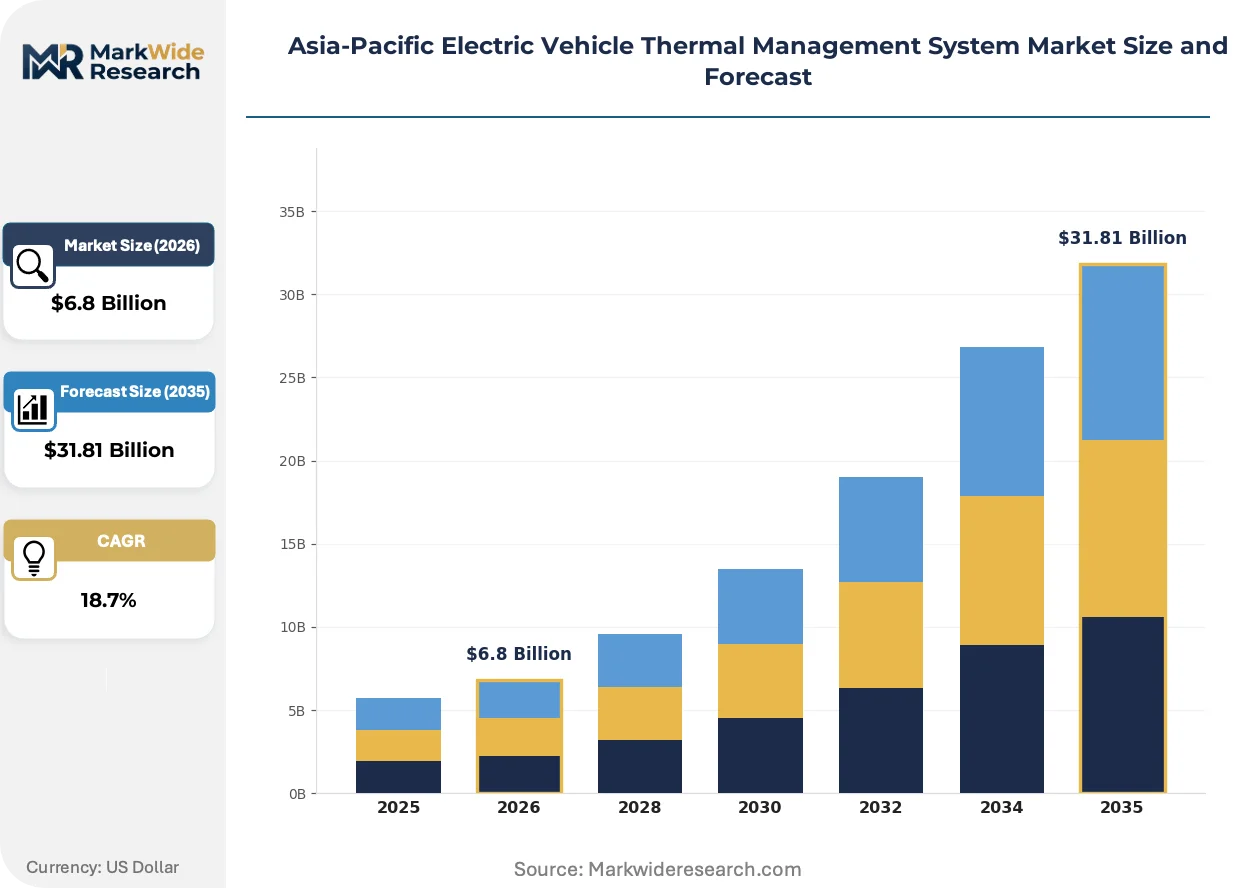
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.81 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Exchangers, Coolant Pumps, Temperature Sensors, Compressors Application: Battery Cooling, Motor Cooling, HVAC Systems, Powertrain Thermal Management End User: OEMs, Aftermarket Providers, Government Fleets, Ride-Sharing Services Installation Type: Integrated Systems, Standalone Units, Retrofitted Solutions, Modular Designs |
| Companies Covered | DENSO Corporation, Hanon Systems, Valeo, MAHLE GmbH, Robert Bosch GmbH, BorgWarner Inc., Continental AG, Dana Limited, Marelli Holdings Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Electric Vehicle Thermal Management System Market Strategic Shifts
Technology trajectories in Asia-Pacific thermal management are converging on integrated system architectures that consolidate previously separate cooling loops. Suppliers are racing to capture the interface between battery thermal regulation and cabin climate control.
Immersion cooling with dielectric fluids is expanding into high-performance battery packs for premium EV platforms. Chinese OEMs in the Jiangsu corridor are piloting direct-contact systems that eliminate cold plate thermal resistance. This architecture is expanding into ride-sharing vehicle specifications where rapid-charge heat rejection demands exceed conventional liquid loop capacity.
Japan's METI efficiency mandates are compressing heat pump adoption timelines across the region's cold-climate markets. The policy framework requires measurable coefficient-of-performance gains that OEMs can only achieve through integrated refrigerant cycles. South Korean and Chinese suppliers are responding with modular heat pump units that retrofit onto existing BEV platforms.
Fleet procurement desks are consolidating thermal system specifications across multiple OEM relationships. Commercial operators in Thailand and Indonesia now demand standardized service intervals and interchangeable components that override proprietary OEM architectures. This pattern is most visible in government bus tenders where lifecycle cost models dominate upfront capital decisions.
Asia-Pacific Electric Vehicle Thermal Management System Market Segmentation
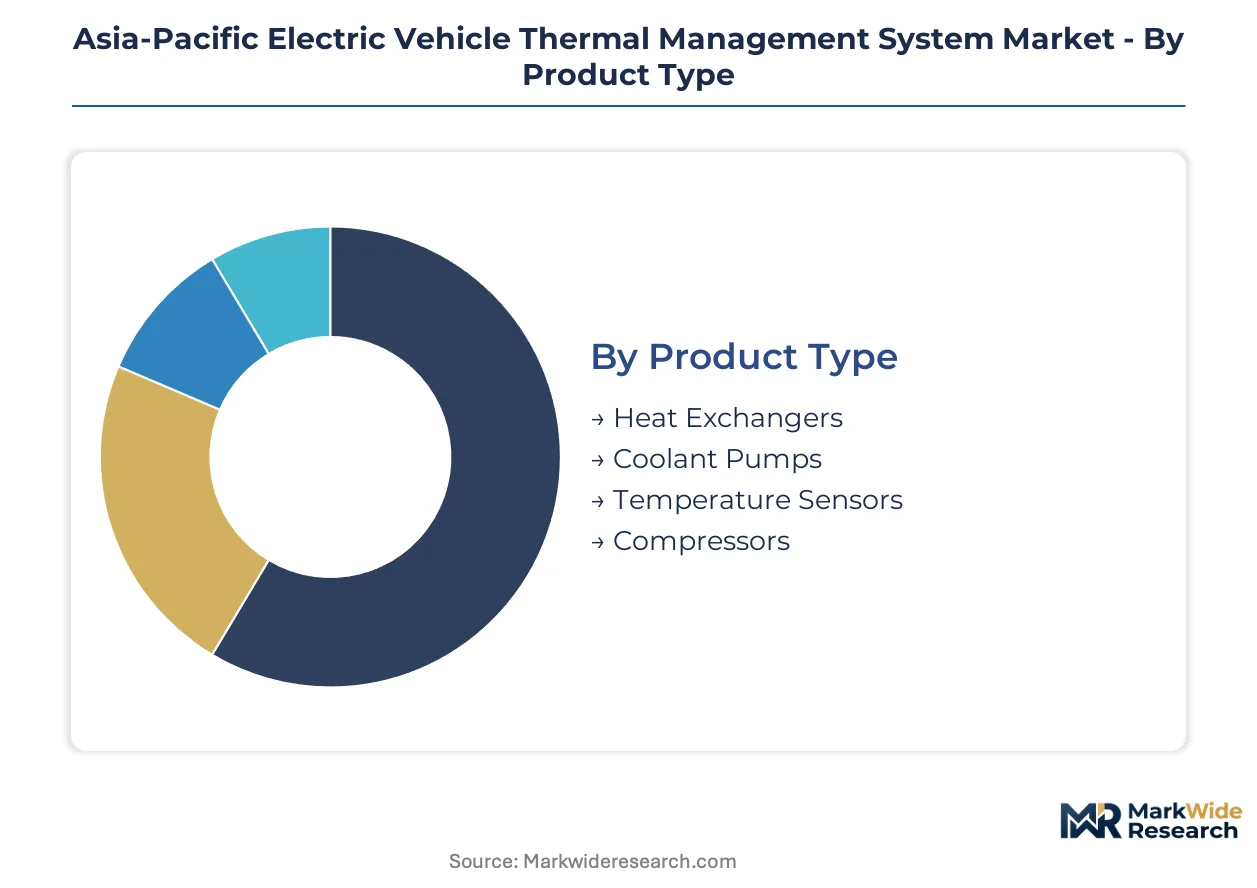
Asia-Pacific electric vehicle thermal management system procurement splits sharply between integrated architectures for new platforms and modular retrofits for fleet conversions. Segment boundaries increasingly blur as battery cooling intensity requirements force cross-category engineering convergence.
Product Type:
Specification hierarchies separate mature heat exchange hardware from electrified compressor platforms capturing METI efficiency mandates.
- Heat Exchangers:Aluminum-brazed plate-and-fin assemblies dominate battery cold plate applications across Chinese Jiangsu manufacturing corridors. OEM procurement desks in Japan and South Korea specify these for baseline thermal duty cycles in mass-market BEV platforms.
- Compressors:Electrified scroll and swashplate designs enable heat pump integration that meets Japan's METI coefficient-of-performance benchmarks. South Korean suppliers scale CO2-compatible variants for cold-climate range retention specifications.
- Coolant Pumps:Brushless DC circulation units with variable speed control serve multi-loop architectures spanning battery, motor, and cabin circuits.
- Temperature Sensors:Thermistor and RTD elements embedded in cell-level monitoring harnesses feed battery management system algorithms.
Mature deployment sits with Heat Exchangers. Newer deployment is concentrated in Compressors.
Application:
End-use thermal loads define engineering priorities, with battery heat rejection commanding the most intensive cooling infrastructure investments.
- Battery Cooling:Liquid coolant loops and emerging dielectric immersion systems manage cell-level temperatures during rapid-charge events. Chinese ride-sharing operators in Shenzhen and Chengdu specify enhanced capacity for high-utilization duty cycles.
- HVAC Systems:Integrated heat pump cycles capture waste heat from power electronics to reduce cabin climate load on traction batteries. METI efficiency mandates in Japan accelerate adoption timelines across cold-climate prefectures.
- Motor Cooling:Stator jacket cooling and rotor oil spray circuits maintain permanent magnet performance in high-torque drive units.
- Powertrain Thermal Management:Consolidated architectures coordinate inverter, converter, and on-board charger heat rejection through shared coolant manifolds.
Volume concentration tracks Battery Cooling. Technology refresh centers on HVAC Systems.
End User:
Procurement authority separates platform-integrated specification from fleet-level standardization pressures.
- OEMs:Vehicle manufacturers specify proprietary thermal architectures that lock suppliers into multi-year platform contracts. Chinese OEMs in Zhejiang corridor drive integration depth for export-bound BEV models.
- Ride-Sharing Services:Commercial operators in Indonesia, Thailand, and Vietnam demand standardized service intervals and interchangeable components that override OEM proprietary designs. High-utilization duty cycles intensify cooling capacity requirements.
- Government Fleets:Bus electrification mandates in the Philippines and Malaysia create modular retrofit demand compatible with legacy chassis architectures.
- Aftermarket Providers:Independent service networks supply replacement heat exchangers and coolant pumps for out-of-warranty vehicle populations.
Specification authority rests with OEMs. Procurement consolidation is advancing fastest among Ride-Sharing Services.
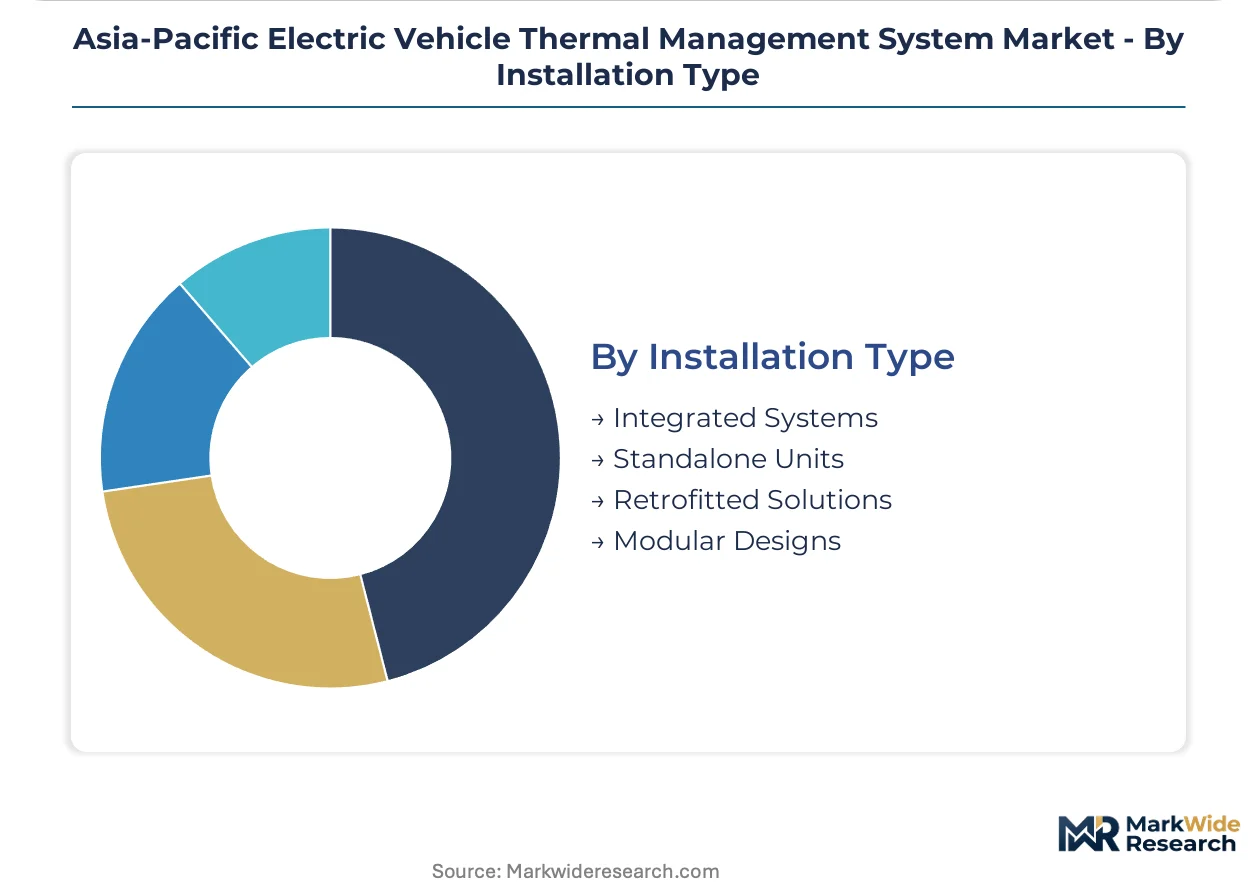
Installation Type:
Integration depth determines margin capture, with factory-installed systems commanding premium positioning against field-retrofitted alternatives.
- Integrated Systems:Multi-loop architectures consolidate battery, motor, and cabin circuits through centralized control modules. Japanese and South Korean OEMs specify these for platform efficiency optimization.
- Retrofitted Solutions:Modular cooling packages adapt to legacy bus chassis for government fleet electrification programs across ASEAN markets. Philippine and Malaysian tender specifications prioritize lifecycle cost over upfront capital.
- Standalone Units:Discrete compressor or pump assemblies serve repair and replacement demand in independent service channels.
- Modular Designs:Standardized component interfaces enable fleet operators to mix suppliers across vehicle generations.
Engineering investment concentrates in Integrated Systems. Volume expansion is strongest for Retrofitted Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang manufacturing corridors concentrate the region's thermal system production capacity. China's MIIT battery safety mandates and Japan's METI efficiency benchmarks are reshaping procurement specifications across the Asia-Pacific EV supply base.
China
Ride-sharing fleet operators in Shenzhen and Chengdu drive demand for rapid-charge cooling infrastructure. MIIT enforces GB/T thermal runaway containment standards that force OEMs to upgrade heat exchanger specifications across all vehicle classes. The Jiangsu corridor anchors aluminum-brazed plate production for export-bound BEV platforms.
Japan
Cold-climate range retention specifications accelerate heat pump compressor adoption timelines. METI mandates coefficient-of-performance benchmarks that OEMs meet through integrated refrigerant cycles capturing power electronics waste heat. Nagoya-based suppliers coordinate with Toyota and Honda on multi-loop thermal architectures.
South Korea
Battery cell manufacturers in Gyeonggi Province specify enhanced coolant circulation for high-energy-density packs. MFDS coordinates with KATRI on fire suppression protocol compliance that extends qualification timelines for new thermal fluid formulations. Busan-Ulsan industrial clusters scale CO2-compatible compressor production for cold-climate export markets.
Thailand
Government bus electrification programs create modular retrofit demand compatible with legacy chassis architectures. Board of Investment incentives attract Chinese and Japanese suppliers to establish regional assembly operations for ASEAN distribution. Bangkok-based fleet operators consolidate procurement specifications across multiple OEM relationships.
Indonesia
Commercial ride-sharing operators deploy high-utilization EVs with intensified cooling capacity requirements for tropical duty cycles. Ministry of Industry regulations on local content ratios shape supplier localization decisions for thermal system components. Batam and Jakarta manufacturing zones host assembly operations serving domestic and export demand.
Asia-Pacific Electric Vehicle Thermal Management System Market Competitive Environment
Premium-margin players sit above commodity-margin players across integration depth and semiconductor content. The supplier base organizes into three tiers: integrated system architects with captive sensor portfolios, scale-driven heat exchange manufacturers, and modular component specialists serving retrofit channels. Consolidation pressures concentrate among standalone hardware fabricators facing OEM procurement desk consolidation. Dominant competitive moves include backward integration into semiconductor supply and geographic expansion into ASEAN manufacturing zones.
Among Japanese and South Korean integrated system suppliers, DENSO Corporation and Hanon Systems occupy positions defined by manufacturing scale and captive technology portfolios. MAHLE GmbH represents the European archetype competing on refrigerant compatibility across multiple OEM thermal architectures. These three anchors illustrate how supplier positioning stratifies between premium integrated platforms and commodity hardware tiers.
| Leading Market Players |
|---|
| DENSO Corporation |
| Hanon Systems |
| Valeo |
| MAHLE GmbH |
| Robert Bosch GmbH |
| BorgWarner Inc. |
| Continental AG |
| Dana Limited |
| Marelli Holdings Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Performance-grade bifurcation between integrated thermal system architects and standalone component fabricators manifests in margin spreads exceeding three-to-one, with premium tier suppliers capturing value through captive sensor portfolios while commodity hardware vendors absorb metal price volatility without pass-through leverage.
Pricing Analysis
Value-based pricing anchors on coefficient-of-performance guarantees for heat pump compressors meeting Japan's METI benchmarks. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth against GB/T thermal runaway protocols and coolant toxicity compliance. Cost compression in aluminum-brazed heat exchangers intensifies because OEM procurement desks consolidate volume across Jiangsu corridor suppliers. Ride-sharing fleet operators exhibit highest price sensitivity, while Japanese and South Korean OEMs prioritize performance guarantees over unit economics.
Supply Chain Analysis
Engineering talent scarcity in Gyeonggi Province and Zhejiang corridor constrains expansion timelines for multi-loop thermal architecture specialists. Manufacturing concentration centers on China, South Korea, and Japan, with aluminum coil and refrigerant feedstock drawing from domestic smelters and European chemical suppliers. Single-source vulnerability sits with CO2-compatible compressor valve assemblies from Busan-Ulsan industrial clusters. Distribution runs through OEM captive logistics networks and Tier 1 supplier consolidation hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialist engineering capacity shortages prop pricing power for integrated system architects, with qualification bottlenecks against dual GB/JIS certification timelines limiting supply elasticity.
For Market Incumbents: To counter margin erosion from consolidated OEM procurement desks, deepen backward integration into thermistor and RTD sensor production to defend premium positioning. Add capacity in Thai Board of Investment zones to capture ASEAN bus electrification retrofit demand while maintaining proximity to Indonesian ride-sharing fleet operators. For New Entrants and Emerging Players: GB/T thermal runaway standards in China open a window for modular cooling package suppliers targeting Philippine and Malaysian government fleet tenders. Prioritize dielectric fluid immersion systems for Shenzhen ride-sharing specifications. Lead with lifecycle cost models that override proprietary OEM architectures in commercial operator procurement. For Investors and Strategic Acquirers: Re-rating potential sits with CO2-compatible compressor specialists given Japan's METI efficiency mandate acceleration. Long-term viability favors suppliers with demonstrated dual-certification capabilities spanning Chinese GB standards and Japanese JIS protocols. Monitor refrigerant transition schedules under Europe's F-Gas Regulation as inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces thermal architecture variants for OEMs serving multiple ASEAN markets from single engineering base. |
| Battery Supply Agreement | Locks in cell-level thermal duty specifications with Gyeonggi Province manufacturers for export-bound platforms. |
| Software-Defined Vehicle Investment | Enables predictive thermal management algorithms integrating battery state-of-health monitoring for fleet operators. |
| Geographic Manufacturing Footprint | Positions CO2-compatible compressor production in Busan-Ulsan clusters for cold-climate Japanese export demand. |
| Charging Infrastructure Partnership | Coordinates rapid-charge heat rejection specifications with network operators in Indonesian and Thai ride-sharing corridors. |
Study Parameters
Vehicle production databases, customs and trade flow records, and IHS Markit registration data formed the secondary backbone for market sizing. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, thermal system R&D directors, and aftermarket service heads validated technical specifications and adoption timelines. Bottom-up component demand modeling and top-down OEM platform penetration analysis were triangulated against regulatory filing disclosures.
Historical trendline analysis of heat pump compressor electrification rates and immersion cooling pilot deployments informed growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include product type, application thermal load, end-user procurement authority, and installation integration depth. CAGRs were derived from slope analysis of technology adoption curves and policy mandate compliance deadlines, with specific inputs from MIIT enforcement timelines and METI efficiency benchmark phase-ins.
The model assumes a particular technology adoption path; alternative pathways for dielectric immersion cooling would alter the outlook if Chinese OEMs accelerate direct-contact architectures beyond pilot scale. Forecasts reflect assumptions regarding refrigerant transition schedules and base metal price stability. Material deviation in GB/T standard enforcement rigor or F-Gas Regulation phase-down pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Three Wheel E-Scooter Market
Electric Vehicles
Saudi Arabia E-Bike Market
Electric Vehicles
Automotive Intelligent Battery Sensor Market
Electric Vehicles
Global Automotive Lithium Ion Battery Controller Market
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
Global EV on-Board Chargers Market
Electric Vehicles
EV PTC Heaters Market
Electric Vehicles
E-Axle Market
Electric Vehicles
Global Electric Vehicles Market
Electric Vehicles
India Electric Bus Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market
Electric Vehicles
Singapore Electric Vehicle Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
Asia-Pacific Solar E-Bike Market
Electric Vehicles
Norway Electric Cars Market