
 Solar Golf Cart Market | 2026-2036
Solar Golf Cart Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Golf Cart Market Analytics
ISO 9001 quality management certification is rotating as a baseline qualifier for OEMs seeking fleet contracts with premium golf resorts. Club Car leverages its dealership density across North American vacation corridors to sustain recurring revenue from service attachments. Yamaha Golf-Car anchors its position through in-house production of electric drivetrain components, reducing supplier dependency. Garia Luxury Golf Car differentiates through bespoke cabin configurations that command pricing premiums in European resort markets.
A solar golf cart integrates photovoltaic roof panels with lithium-ion storage and brushless DC motor propulsion, typically achieving 15-25 miles of extended range per full solar charge cycle under standard irradiance conditions. The vehicle serves commercial fleet operators seeking to eliminate grid dependency during peak daylight operating hours. Lithium-ion Battery Carts capture the dominant margin pool as cell chemistry improvements reduce weight penalties and extend duty cycles beyond lead-acid alternatives. Solar-assisted Carts represent the fastest-growing product configuration, particularly where courses and resorts face diesel generator bans or carbon disclosure mandates. End-user demand from Residential Communities is concentrating in master-planned developments where HOA sustainability targets override upfront capital cost sensitivity.
The US EPA tailpipe emission guidelines for non-road equipment and the EU Green Deal carbon neutrality benchmarks for leisure infrastructure are converging to restrict fossil-fuel cart procurement in public and semi-public venues. India's BIS certification requirements for electric vehicle safety and China's GB standards for photovoltaic system integration add compliance layers for manufacturers targeting import markets. Stakeholders must monitor how evolving storage efficiency standards and local renewable portfolio obligations reshape total cost-of-ownership calculations against conventional electric alternatives.
Market Dynamics
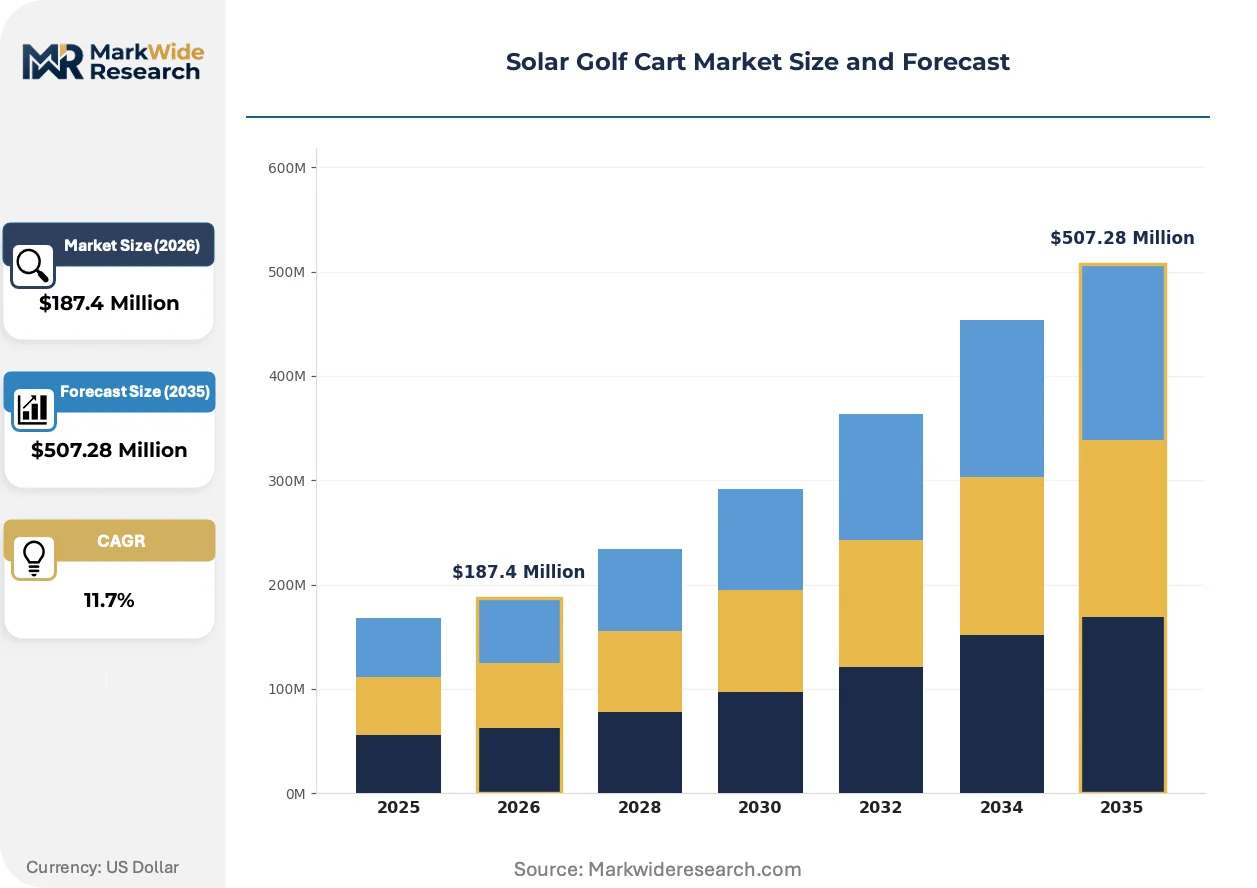
Capital deployment toward photovoltaic charging infrastructure is compressing total cost-of-ownership calculations for fleet operators, while lithium-ion cell chemistry improvements are eliminating the weight-performance tradeoffs that previously constrained solar-assisted vehicle adoption.
Growth Catalysts
- US Inflation Reduction Act tax credits:Clean mobility equipment incentives are accelerating resort procurement cycles in Florida and Arizona Sun Belt corridors.
- EU Green Deal carbon neutrality benchmarks:Leisure infrastructure mandates are restricting fossil-fuel cart procurement across semi-public venues in Germany and France.
- Photovoltaic roof integration:Extended range capabilities under standard irradiance conditions are eliminating grid dependency during peak daylight operating hours for commercial fleets.
Market Restraints
- Cell material cost volatility:Lithium and cobalt price swings compress margin pools for lithium-ion battery cart manufacturers.
- Supply concentration in East Asian cell production:Dependency on concentrated cathode and anode supply creates geopolitical exposure for Western OEMs.
- GB standards compliance friction:China's photovoltaic system integration requirements add certification layers and timeline risk for import-market entrants.
Strategic Opportunities
- Master-planned residential communities:HOA sustainability targets in Arizona and Texas are overriding upfront capital cost sensitivity for net-zero amenity infrastructure.
- Diesel generator bans:Carbon disclosure mandates at European resorts are creating first-mover advantages for solar-assisted fleet configurations.
- Brushless DC motor convergence:Integration with smart energy management systems is opening premium pricing tiers in bespoke cabin configurations.
Industry Challenges
- ISO 9001 certification timelines:Quality management documentation requirements are elongating sales cycles for premium resort fleet contracts.
- Photovoltaic-electrical integration complexity:Legacy maintenance technician skill gaps are expanding service training costs for dealership networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Golf Cart Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Golf Carts, Lithium-ion Battery Carts, Solar-assisted Carts, Customized Models End User: Golf Courses, Resorts, Residential Communities, Corporate Parks Charging Technology: Photovoltaic Systems, Plug-in Chargers, Fast Charging Stations, Renewable Energy Solutions Distribution Channel: Online Retail, Dealerships, Direct Sales, Rentals |
| Companies Covered | EverGreen Electrical Vehicles, Xiamen Dalle Electric Car, Club Car, Star EV, Garia Luxury Golf Car, Yamaha Golf-Car, Columbia ParCar, Maini Material Movement, E-Z-GO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Golf Cart Market Evolving Landscape
Photovoltaic roof panel technology is compressing the performance gap between solar-assisted and conventional electric drivetrains, while procurement patterns among resort operators are rotating toward lifecycle cost metrics rather than upfront capital expenditure.
Perovskite-enhanced photovoltaic cells are displacing traditional silicon panels in premium golf cart configurations by delivering higher conversion efficiency under diffuse light conditions. Arizona resort operators are piloting these systems for dawn-to-dusk fleet operations without grid tethering. The technology is displacing lead-acid battery backup requirements in solar-assisted cart designs, reducing vehicle weight penalties and extending duty cycles.
The US EPA tailpipe emission guidelines for non-road equipment are converging with state-level renewable portfolio obligations to restrict fossil-fuel procurement in public venues. California and New York regulators are tightening enforcement windows for fleet compliance. Equipment lessors are responding by accelerating solar-assisted cart deployment to secure carbon disclosure advantages ahead of disclosure mandate deadlines.
After-sales service unbundling is fragmenting traditional dealership revenue models as fleet operators seek direct relationships with photovoltaic component suppliers. North American vacation corridor resorts are negotiating separate maintenance contracts for roof panel systems and drivetrain components. This pattern concentrates most visibly in Florida master-planned communities where HOA boards demand transparent lifecycle cost accounting across multi-year fleet agreements.
Solar Golf Cart Market Segmentation
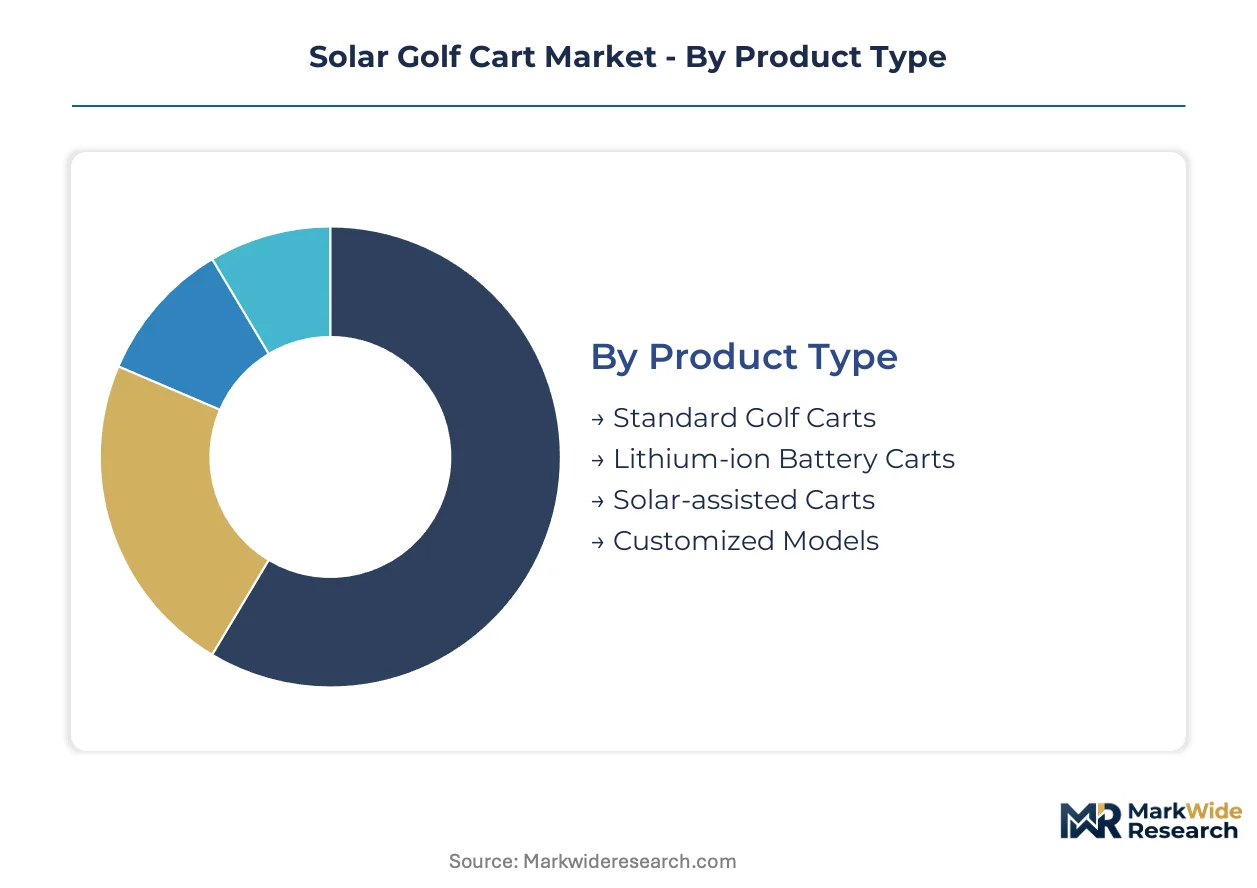
Segmentation in the solar golf cart market reveals how technology substitution pressures and regulatory compliance requirements reshape procurement patterns across fleet operators and individual buyers. Understanding these divides illuminates where margin pools concentrate and which configurations face displacement risk from advancing photovoltaic integration.
Product Type:
Substitution pressure from solar-assisted configurations is intensifying most acutely against lead-acid and conventional electric variants as lithium-ion chemistry improvements compress total cost-of-ownership gaps.
- Lithium-ion Battery Carts:These vehicles deploy high-density cell packs with reduced weight penalties versus lead-acid alternatives, enabling extended duty cycles and faster recharge intervals. Demand concentrates among Arizona and Florida resort operators seeking to eliminate midday grid dependency during peak season operations, driven by US Inflation Reduction Act tax credit eligibility and state-level renewable portfolio obligations.
- Solar-assisted Carts:Photovoltaic roof integration with brushless DC motor propulsion delivers 15-25 miles of extended range per solar charge cycle under standard irradiance. European resorts in Germany and France facing EU Green Deal carbon neutrality mandates are accelerating fleet conversion to avoid diesel generator bans and secure carbon disclosure advantages.
- Standard Golf Carts:Conventional lead-acid electric configurations retain presence in price-sensitive municipal fleet procurement where capital constraints override lifecycle cost analysis.
- Customized Models:Bespoke cabin configurations with premium seating and climate control command pricing premiums in master-planned residential communities across Texas and Arizona.
Lithium-ion Battery Carts retain volume leadership among commercial fleets; Solar-assisted Carts hold the steepest expansion curve as regulatory deadlines compress conversion timelines.
End User:
Cost tier stratification separates capital-intensive resort procurement from residential community purchases where HOA sustainability targets override upfront expenditure sensitivity.
- Resorts:Fleet operators across Florida and Arizona Sun Belt corridors are deploying solar-assisted vehicles to achieve dawn-to-dusk operations without grid tethering, capitalizing on photovoltaic charging infrastructure investments and carbon disclosure positioning ahead of compliance windows.
- Residential Communities:Master-planned developments in Texas and Arizona with net-zero amenity mandates are procuring lithium-ion and solar-assisted configurations despite 40-60% upfront premiums versus conventional alternatives, driven by HOA board sustainability targets and transparent lifecycle cost accounting requirements.
- Golf Courses:Traditional country clubs are converting maintenance and pro shop fleets under US EPA tailpipe emission guideline pressure, with procurement rotating toward ISO 9001-certified OEMs.
- Corporate Parks:Campus mobility operators are piloting renewable energy solutions for employee shuttle services, though deployment remains concentrated in technology sector headquarters with explicit carbon neutrality commitments.
Resorts dominate current procurement volume; Residential Communities are gaining share fastest as HOA mandate adoption accelerates across Sun Belt states.
Charging Technology:
Supply concentration in East Asian photovoltaic component manufacturing is creating margin pressure for Western integrators while opening differentiation opportunities for domestic fast-charging infrastructure providers.
- Photovoltaic Systems:Roof-integrated panels with perovskite-enhanced cells are displacing traditional silicon in premium configurations, delivering higher conversion efficiency under diffuse light conditions for dawn-to-dusk operations.
- Fast Charging Stations:High-amperage infrastructure enabling 30-minute partial recharge cycles is concentrating at Arizona resort clusters where fleet utilization rates demand minimal downtime between rounds.
- Plug-in Chargers:Conventional overnight charging infrastructure retains installed base among residential community garages with predictable daily usage patterns.
- Renewable Energy Solutions:Hybrid configurations combining photovoltaic generation with grid-tied battery storage are emerging at European resorts facing simultaneous diesel generator bans and carbon disclosure mandates.
Photovoltaic Systems command the dominant installed base; Fast Charging Stations are expanding most quickly as fleet utilization intensifies.
Distribution Channel:
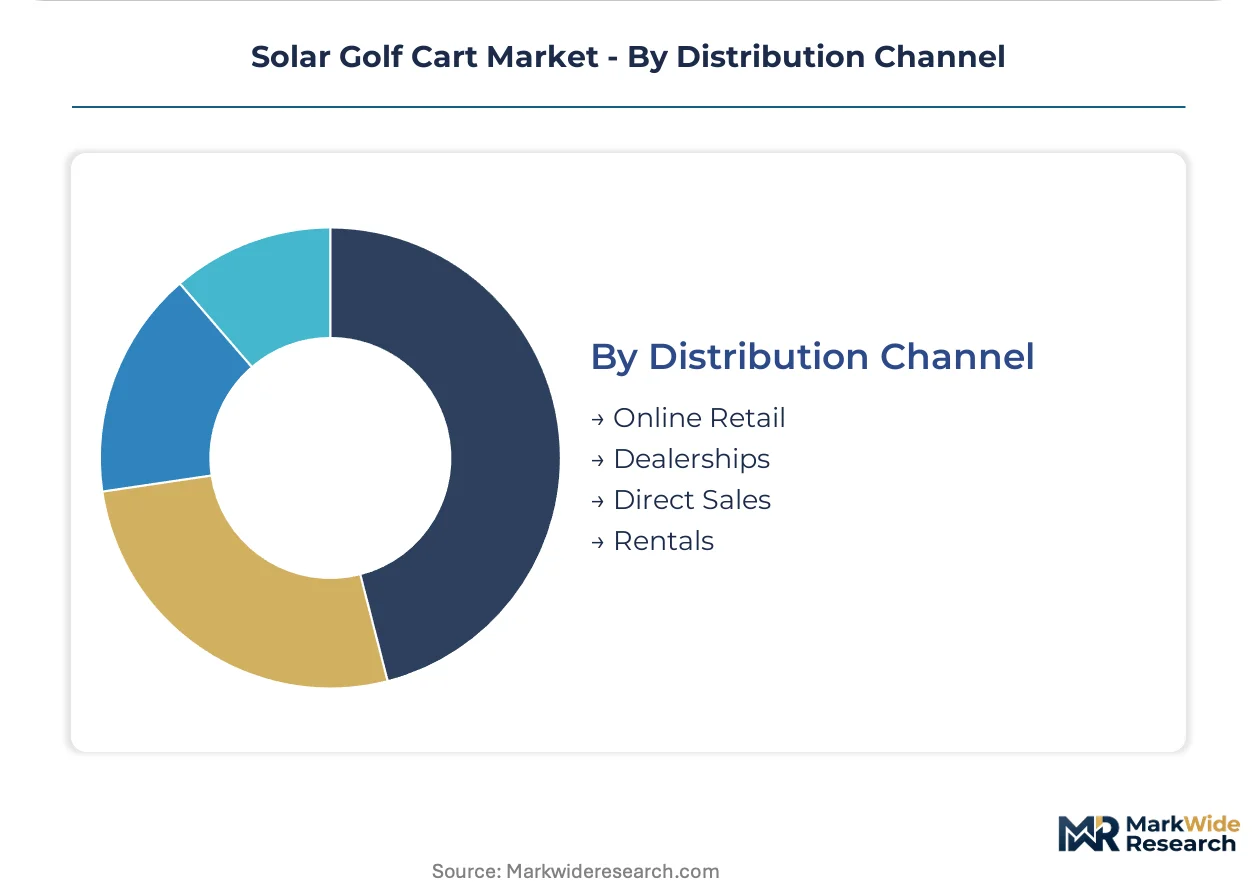
Customer type fragmentation between fleet operators and individual buyers is unbundling traditional dealership revenue models as procurement patterns diverge toward direct supplier relationships.
- Dealerships:Service-attachment revenue from maintenance contracts and parts replacement sustains recurring income streams across North American vacation corridor networks, particularly in Florida master-planned communities where HOA boards demand multi-year lifecycle cost transparency.
- Direct Sales:Large resort operators are negotiating manufacturer-direct procurement for fleet volumes exceeding fifty units, bypassing dealer markups and securing customized photovoltaic-electrical integration specifications.
- Online Retail:Individual buyers in residential communities are configuring lithium-ion and solar-assisted carts through digital platforms, though fulfillment still routes through regional service networks for installation and warranty support.
- Rentals:Equipment lessors are accelerating solar-assisted cart deployment to secure carbon disclosure advantages ahead of mandate deadlines, particularly in California and New York where enforcement windows are tightening.
Dealerships retain volume leadership in residential and small-fleet segments; Direct Sales are climbing fastest as resort procurement scales and unbundles service relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Resort operators and master-planned residential communities concentrate procurement across Sun Belt corridors, with regulatory pressure and photovoltaic infrastructure investments reshaping geographic demand patterns.
United States
Florida and Arizona resort clusters drive fleet procurement ahead of EPA tailpipe emission guideline enforcement windows. The US Inflation Reduction Act tax credits for clean mobility equipment accelerate capital deployment toward photovoltaic charging systems. Phoenix and Scottsdale master-planned communities override upfront cost sensitivity with HOA sustainability mandates.
Germany
EU Green Deal carbon neutrality benchmarks restrict fossil-fuel cart procurement across semi-public leisure venues. The country's national environmental regulator enforces diesel generator bans at Bavarian and Baden-Württemberg resort properties. Frankfurt and Munich equipment lessors accelerate solar-assisted deployment ahead of disclosure mandate deadlines.
China
Domestic resort development and export manufacturing capacity expansion concentrate demand in Jiangsu and Zhejiang provinces. GB standards for photovoltaic system integration add certification layers for manufacturers targeting import markets. Shenzhen and Guangzhou industrial clusters supply cathode and anode materials to Western OEMs.
India
BIS certification requirements for electric vehicle safety reshape procurement specifications for hospitality and residential segments. State-level renewable energy obligations in Maharashtra and Karnataka incentivize photovoltaic fleet conversions. Bangalore and Hyderabad master-planned developments pilot net-zero amenity infrastructure.
France
Provence-Alpes-Côte d'Azur resort operators face simultaneous EU Green Deal mandates and carbon disclosure requirements. The country's national environmental regulator tightens enforcement windows for leisure infrastructure compliance. Cannes and Nice equipment lessors unbundle maintenance contracts to secure transparent lifecycle cost accounting.
Solar Golf Cart Market Competitive Landscape
Player mix skews toward established powers with captive supply chains and specialized regional fabricators with photovoltaic integration capabilities. The vendor base separates into three strategic archetypes: diversified powers with in-house drivetrain production, solar-specialized boutiques with bespoke configurations, and regional assemblers with cost-focused positioning. Competitive moves concentrate on dealership network density expansion and direct sales channel development for large fleet accounts.
Among diversified powers, Club Car and Yamaha Golf-Car occupy positions anchored by North American vacation corridor service networks and captive electric drivetrain component production respectively. Garia Luxury Golf Car represents the solar-specialized boutique archetype with European resort market positioning. Xiamen Dalle Electric Car sits within the regional fabricator tier with export-focused manufacturing scale.
| Leading Market Players |
|---|
| EverGreen Electrical Vehicles |
| Xiamen Dalle Electric Car |
| Club Car |
| Star EV |
| Garia Luxury Golf Car |
| Yamaha Golf-Car |
| Columbia ParCar |
| Maini Material Movement |
| E-Z-GO |
| Others |
Value Network & Pricing Analysis
Sixty-day lithium carbonate delivery windows from Jiangsu cathode suppliers compress margin buffers for Western OEMs while amplifying pricing power for integrated cell manufacturers with captive material streams. This lead-time volatility concentrates procurement leverage among resort fleet operators capable of committing to multi-year offtake agreements, tilting contract structures toward cost-plus arrangements with raw material indexation clauses.
Pricing Analysis
Cost-plus contracts with London Metal Exchange-linked lithium carbonate indexation dominate procurement between Arizona resort operators and cell pack integrators. Price differentiation separates ISO 9001-certified OEMs commanding premium-mid-economy tiers from uncertified regional assemblers competing on upfront capital expenditure. Cost compression in the standard tier intensifies as Chinese GB-compliant photovoltaic modules flood export markets. Residential community buyers exhibit lowest price sensitivity, accepting forty-to-sixty percent upfront premiums for net-zero amenity compliance.
Supply Chain Analysis
Strait of Malacca transit risk for lithium hydroxide shipments from Australian spodumene concentrators to Jiangsu processing hubs concentrates geopolitical exposure for Western drivetrain manufacturers. Cathode active material production draws from Chinese, South Korean, and Japanese chemical complexes; anode graphite rests on Heilongjiang mining and Shandong spheronization capacity. Single-source vulnerability in perovskite precursor chemicals threatens premium photovoltaic roof panel output. Distribution runs through North American vacation corridor dealerships with service-attachment revenue sustaining recurring income.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in aftermarket service unbundling as fleet operators demand direct photovoltaic component relationships, creating specialist niches for technical training providers and lifecycle cost auditors.
For Market Incumbents: Fortify dealership network density across Florida and Arizona Sun Belt corridors to capture recurring service-attachment revenue as procurement shifts toward direct manufacturer relationships for fleet volumes. Invest in ISO 9001 certification maintenance to defend premium tier positioning against emerging solar-specialized boutiques with perovskite integration capabilities. Build backward integration into lithium-ion cell pack assembly to reduce Jiangsu supply dependency. For New Entrants and Emerging Players: Photovoltaic-electrical integration training gaps present immediate white-space opportunity for technical education providers serving legacy dealership maintenance networks. Target European resort markets facing EU Green Deal diesel generator bans with solar-assisted fleet configurations emphasizing carbon disclosure compliance. Pursue direct sales channel development for equipment lessors seeking carbon positioning ahead of tightening enforcement windows. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial parents with under-optimized electric vehicle divisions lacking photovoltaic integration capabilities. Long-term viability centers on lithium-ion chemistry improvement trajectories and renewable portfolio obligation expansion across Sun Belt states. Monitor Arizona HOA mandate adoption velocity as inflection indicator for residential community demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Photovoltaic System Integration Partnership | Perovskite-enhanced roof panels enable dawn-to-dusk operations for Arizona resort fleets. |
| Backward Integration into Cell Assembly | Captive lithium-ion pack production reduces Jiangsu cathode supply concentration exposure. |
| ISO 9001 Certification Investment | Quality management documentation unlocks premium resort fleet contract eligibility. |
| Direct Sales Channel Development | Bypassing dealer markups secures large fleet procurement with customized specifications. |
| Technical Training Program Expansion | Legacy technician skill gaps create recurring revenue from photovoltaic maintenance education. |
Research Methodology
A standing panel of resort fleet procurement directors, HOA board sustainability officers, lithium-ion cell engineering leads, and photovoltaic system integrators provided ongoing calibration across primary interview cycles. Secondary validation drew from US EPA non-road equipment filings, EU Green Deal implementation trackers, BIS electric vehicle safety notifications, and GB standards compliance databases. Bottom-up unit shipment modeling from OEM production disclosures triangulated against top-down fleet replacement cycle analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type configuration, end-user archetype, charging technology integration, and distribution channel structure. CAGRs derived from logistic diffusion curves fitted to regulatory deadline compression patterns and photovoltaic efficiency improvement trajectories. Forecast inputs incorporated lithium carbonate price volatility bands and state-level renewable portfolio obligation adoption schedules.
Forecasts assume regulatory continuity in US Inflation Reduction Act tax credit regimes and EU Green Deal carbon neutrality benchmarks; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as BIS certification timeline extensions and GB standards enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle (EV) Battery Housing Market
Electric Vehicles
Vehicle-To-Grid (V2G) Market
Electric Vehicles
Asia-Pacific Electric Vehicle Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market
Electric Vehicles
North America Wireless Electric Vehicle Charging Market
Electric Vehicles
High-Performance Electric Sports Cars Market
Electric Vehicles
Electric Vehicle Rental Market
Electric Vehicles
Electric Bicycle Market
Electric Vehicles
US Automotive High Performance Electric Vehicle Market
Electric Vehicles
Pedelec Market
Electric Vehicles
New Energy Vehicle (NEV) Market
Electric Vehicles
Self Balancing Electric Scooter Market
Electric Vehicles
Electric Transporters Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
Commercial Electric Vehicle Dynamic Braking Resistors Market
Electric Vehicles
Electric Utility Vehicle Market