
 Electric Vehicle Extruded Aluminum Battery Trays Market | 2026-2036
Electric Vehicle Extruded Aluminum Battery Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Extruded Aluminum Battery Trays Market Insights
Chinese aluminum extrusion capacity is consolidating around dedicated EV component corridors. Constellium leverages its European rolling and extrusion network to anchor supply for premium passenger vehicle platforms. Novelis Inc sustains R&D intensity on high-recycled-content alloys that compete across OEM qualification programs. Hindalco Industries Ltd. dominates South Asian feedstock supply through backward integration into primary aluminum and captive alloy development.
Electric vehicle extruded aluminum battery trays are structural enclosures fabricated from 6xxx-series aluminum alloys through direct or indirect extrusion, typically achieving wall thicknesses of 2-5 mm with integrated cooling channel geometries; their primary purpose is to house and protect lithium-ion cell modules while contributing to chassis torsional rigidity and thermal management efficiency. Structural trays command the deepest margin pools due to their qualification complexity and long-term OEM lock-in, while modular trays represent the fastest-growing configuration as platform-sharing strategies proliferate across passenger vehicle lineups. Lightweight trays face margin compression from magnesium and composite substitution threats despite current aluminum cost advantages.
The EPA tailpipe emissions framework and NHTSA crashworthiness standards in the United States, alongside China's MIIT new energy vehicle technical guidelines and GB standards for battery enclosure integrity, collectively mandate minimum structural performance thresholds that only extruded aluminum configurations consistently satisfy at scale. ECHA's REACH restrictions on certain surface treatment chemistries are forcing European tray suppliers to reformulate pretreatment and coating workflows. Stakeholders must monitor alloy sourcing transparency requirements under emerging battery passport regulations and decide whether to qualify alternative extrusion alloys before current qualification windows close.
Market Dynamics
OEM platform consolidation is compressing qualification timelines for extruded aluminum battery tray suppliers, forcing simultaneous engineering validation across multiple vehicle architectures while Ecodesign traceability mandates extend compliance obligations upstream into bauxite sourcing.
Growth Catalysts
- EPA Tailpipe Emissions Framework:The United States regulatory threshold for fleet-average CO2 is accelerating passenger EV platform launches, each requiring qualified aluminum tray architectures.
- 6xxx-Series Alloy Extrusion:Advanced heat-treatable aluminum alloys with integrated cooling channel geometries are achieving torsional rigidity targets that magnesium alternatives cannot match at equivalent cost.
- China MIIT New Energy Vehicle Guidelines:Beijing's technical mandates for battery enclosure integrity are specifying extruded aluminum as the baseline structural configuration for domestic OEM qualification.
Market Restraints
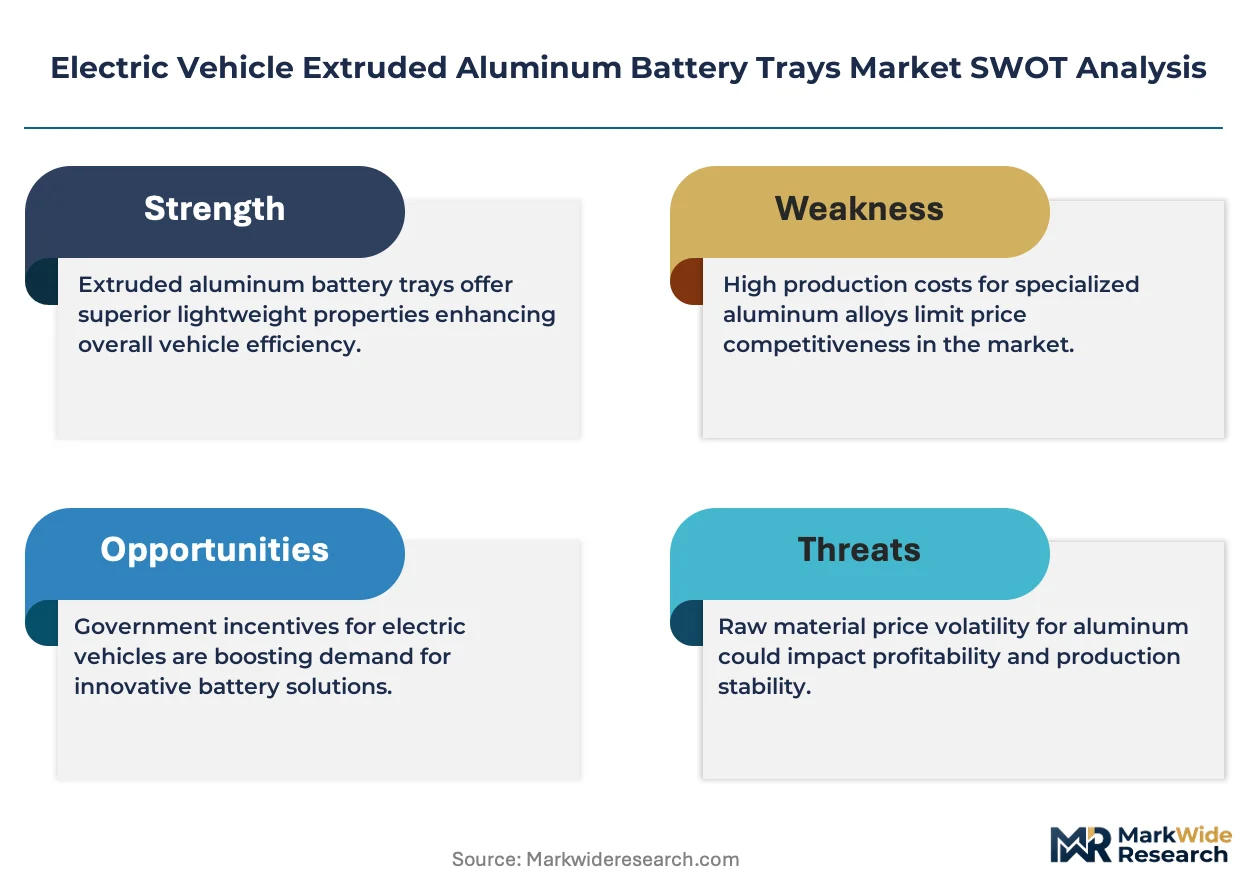
- Primary Aluminum Price Volatility:LME aluminum contract fluctuations are compressing fabrication margins for tray suppliers without captive smelter access.
- South Asian Feedstock Concentration:Hindalco's backward integration into primary metal creates single-source dependency risks for European and North American extruders.
- Magnesium Substitution Threat:AZ91D die-cast enclosures are penetrating cost-sensitive modular tray segments where crashworthiness requirements permit thinner-wall geometries.
Strategic Opportunities
- India PLI Scheme for Advanced Chemistry Cell Manufacturing:New Delhi's production-linked incentive framework is attracting cell gigafactories that will require localized tray supply.
- Closed-Loop Alloy Recycling:Novelis' high-recycled-content 6xxx formulations are qualifying for EU battery passport traceability requirements ahead of virgin-metal competitors.
- Thermal Management Convergence:Integration of extruded cooling channels with direct refrigerant contact is enabling dual-function tray architectures that displace separate cold plates.
Industry Challenges
- GB Standard Certification Timelines:China's battery enclosure integrity testing protocols are extending qualification cycles by 8-14 months for non-domestic suppliers.
- REACH Surface Treatment Reformulation:ECHA restrictions on hexavalent chromium pretreatments are forcing European extruders to validate alternative chemistries without disrupting OEM paint-line compatibility.
- Extrusion Die Capex Intensity:Integrated cooling channel geometries require hardened tool steel dies with 40,000-ton press compatibility, concentrating fabrication capacity among capitalized players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Extruded Aluminum Battery Trays Market |
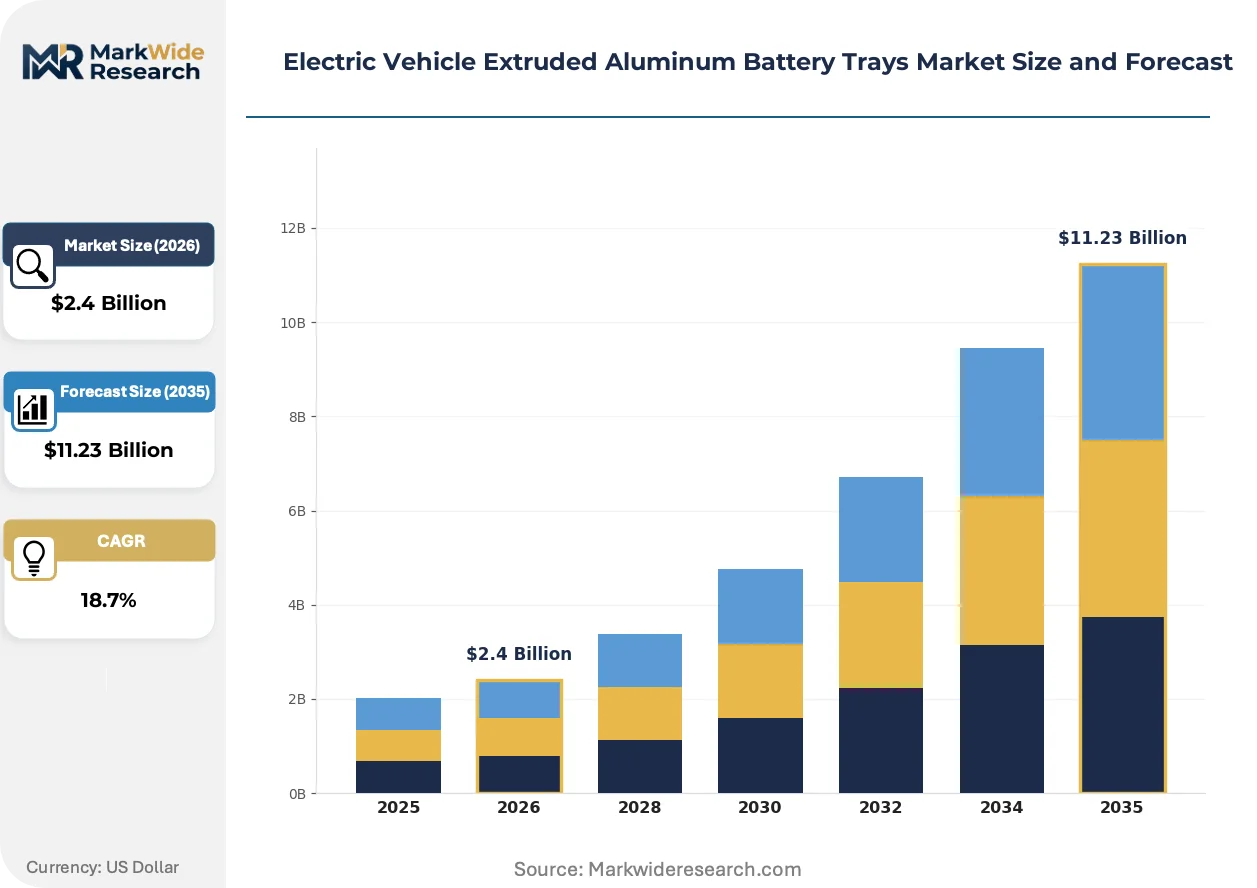
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $11.23 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Trays, Modular Trays, Lightweight Trays, Reinforced Trays End User: OEMs, Aftermarket Providers, Commercial Fleets, Retail Customers Application: Passenger Vehicles, Commercial Vehicles, E-Bikes, E-Scooters Delivery Mode: Direct Supply, Third-Party Logistics, Distribution Centers, Online Retail |
| Companies Covered | Constellium, BENTELER, Novelis Inc, Gestamp, Guangdong Hoshion Industrial Aluminium, Foshan Shijun Hongmao Aluminum Technology Co. Ltd., Waldaschaff Automotive GmbH, Hindalco Industries Ltd., Standard Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Extruded Aluminum Battery Trays Market Trends and Innovations
Extrusion process control and alloy formulation are converging to enable thinner-wall, higher-strength tray architectures that simultaneously satisfy crashworthiness and thermal management requirements.
Direct-to-die water-cooling extrusion is overtaking indirect extrusion for complex hollow profiles with internal rib structures. Tier 1 suppliers in Germany and the United States are adopting 12,000-ton presses with real-time temperature monitoring to achieve 2.0 mm wall consistency. This process shift is overtaking legacy air-quench methods in premium passenger vehicle programs where dimensional tolerance dictates assembly automation compatibility.
REACH restrictions on chromate conversion coatings are forcing European tray suppliers to transition toward trivalent chromium and zirconium-based pretreatment chemistries. The industrial consequence is a 15-20% increase in surface treatment line capital intensity and requalification of coating adhesion for 10-year corrosion warranties. German OEMs are responding by consolidating supplier panels to those with validated alternative workflows ahead of 2027 enforcement windows.
Cell-to-pack architectural abandonment of module housings is compressing tray procurement cycles from 36-month platform development to 18-month refresh timelines. Passenger vehicle OEMs in China are unbundling tray engineering from chassis integration, creating direct sourcing relationships with extruders that bypass traditional tiered supply structures. This disintermediation is most visible in Ningbo and Shenzhen manufacturing corridors where CATL and BYD cell plants anchor localized tray fabrication clusters.
Electric Vehicle Extruded Aluminum Battery Trays Market Segmentation
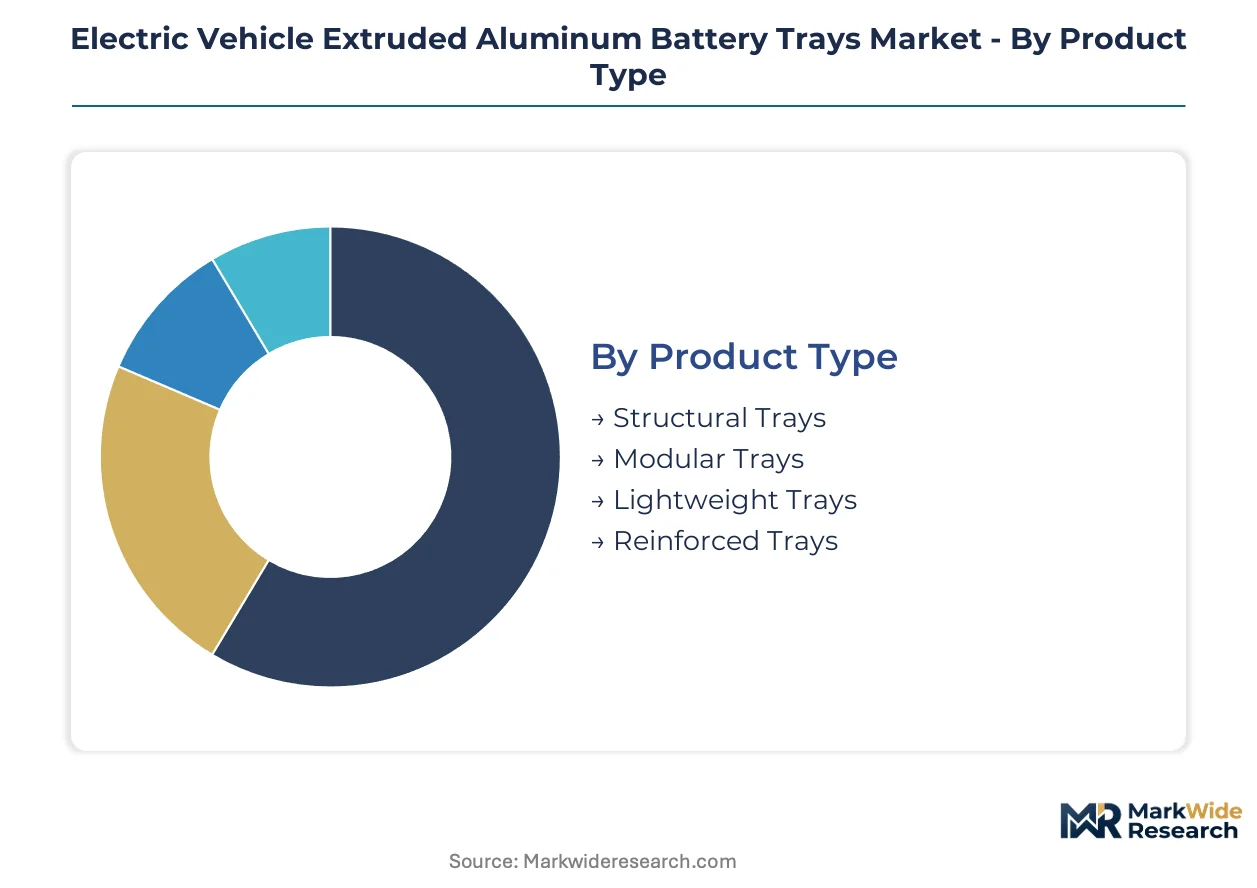
Extruded aluminum battery tray procurement patterns diverge sharply across product architecture, end-user integration depth, and vehicle electrification platform scale. Segmentation reveals where qualification complexity concentrates margin pools versus where volume commoditization threatens supplier returns.
Product Type:
Customization intensity spans from fully integrated structural assemblies to interchangeable modular configurations, with alloy specification and cooling channel geometry serving as the primary differentiation levers.
- Structural Trays:Monolithic 6xxx-series extrusions with integrated floor pan and side rail members achieve torsional rigidity targets exceeding 25 kNm/degree. German OEM qualification programs for premium passenger platforms command 36-48 month engineering validation cycles that lock in long-term supply relationships.
- Modular Trays:Segmented extrusion assemblies with bolted or friction-stir welded joints enable platform-sharing across multiple vehicle lineups. Chinese passenger EV manufacturers in Ningbo and Shenzhen manufacturing corridors are adopting these configurations to compress procurement cycles from 36 months to 18 months.
- Lightweight Trays:Thin-wall 2.0-2.5 mm extrusions with hollow rib structures compete against magnesium AZ91D die-cast alternatives in cost-sensitive segments.
- Reinforced Trays:Hybrid architectures combining extruded aluminum channels with steel or composite reinforcement members address commercial vehicle payload requirements.
Most installed capacity flows through Structural Trays. Expansion is steepest in Modular Trays.
End User:
Procurement authority concentrates with entities controlling platform architecture decisions, while downstream channels fragment across fleet-scale and individual replacement demand.
- OEMs:Original equipment manufacturers specify alloy grade, extrusion tolerance, and surface treatment chemistry through direct engineering relationships with tier-1 extruders. EPA tailpipe emissions thresholds and China MIIT new energy vehicle guidelines mandate structural performance baselines that only qualified aluminum tray architectures satisfy.
- Commercial Fleets:Aggregated procurement for electric delivery van and bus platforms drives volume pricing leverage, though specification authority often resides with chassis OEMs rather than fleet operators.
- Aftermarket Providers:Replacement tray supply for collision repair and battery retrofit applications operates through distributor networks with limited alloy traceability documentation.
- Retail Customers:Direct-to-consumer channels for e-bike and e-scooter battery enclosures represent minimal revenue concentration due to low per-unit aluminum content.
Engineering validation investment concentrates with OEMs. Volume growth is climbing fastest in Commercial Fleets.
Application:
Crashworthiness requirements and thermal management duty cycles create distinct specification tiers across mobility segments.
- Passenger Vehicles:Full-scale automotive platforms demand integrated cooling channels, 10-year corrosion warranties, and NHTSA crashworthiness compliance. United States and German OEMs specify 6xxx-series alloys with T6 temper for floor pan integration.
- Commercial Vehicles:Electric bus and medium-duty truck applications prioritize payload capacity and service accessibility over dimensional refinement, enabling thicker-wall extrusions with simplified geometries.
- E-Bikes:Low-voltage battery enclosures utilize 6063-T5 extrusions with minimal thermal management integration.
- E-Scooters:Shared mobility fleet operators specify impact-resistant tray configurations with standardized mounting interfaces.
Qualification complexity peaks in Passenger Vehicles. Penetration gains are broadest in Commercial Vehicles.
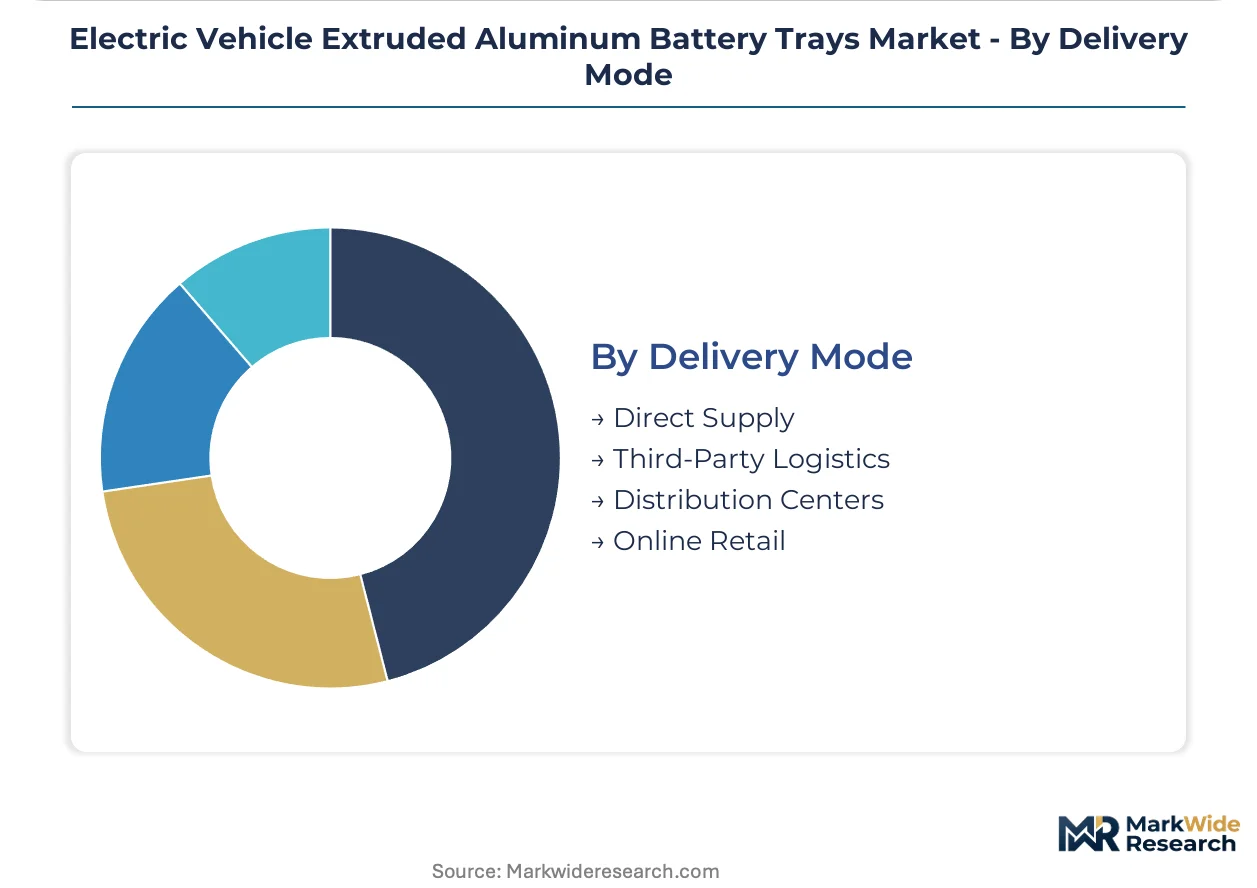
Delivery Mode:
Supply chain configuration ranges from mill-direct extrusion supply to fragmented last-mile distribution, with inventory ownership and quality documentation responsibility shifting across channel tiers.
- Direct Supply:Extruders ship finished trays directly to OEM assembly plants or cell-to-pack integration facilities, maintaining alloy certification documentation through the entire chain. CATL and BYD manufacturing corridors in China anchor this configuration.
- Third-Party Logistics:Specialized automotive logistics providers manage sequencing and just-in-time delivery for multi-source tray programs.
- Distribution Centers:Regional warehousing for aftermarket and commercial fleet replacement demand carries inventory risk without engineering support capabilities.
- Online Retail:E-commerce channels for e-bike and e-scooter accessories operate with minimal technical specification compliance.
Alloy traceability compliance flows through Direct Supply. Channel development is accelerating in Third-Party Logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are reshaping where extruded aluminum battery tray fabrication concentrates, with compliance burdens in Europe and North America pushing capital toward jurisdictions offering streamlined qualification pathways and integrated raw material access.
China
CATL and BYD manufacturing corridors in Ningbo and Shenzhen anchor the densest concentration of tray extrusion capacity globally. MIIT new energy vehicle guidelines mandate aluminum enclosure integrity standards that domestic suppliers satisfy faster than foreign competitors. Shanghai and Chongqing extrusion clusters now supply both local OEMs and export programs to Southeast Asian EV assembly plants.
Germany
Premium passenger vehicle platforms from BMW, Mercedes-Benz, and Volkswagen drive demand for structural tray architectures with 36-month qualification cycles. ECHA REACH restrictions on hexavalent chromium surface treatments force Stuttgart and Munich-area extruders to reformulate pretreatment workflows ahead of 2027 enforcement. Bavarian and North Rhine-Westphalia fabrication hubs maintain European supply for domestic OEMs despite higher compliance costs than Asian competitors.
United States
EPA tailpipe emissions thresholds accelerate EV platform launches requiring NHTSA crashworthiness-compliant tray supply. Michigan and Ohio extrusion facilities serve Detroit Three OEMs with captive alloy certification documentation. Tesla's Nevada and Texas manufacturing footprints pull dedicated tray supply chains toward southwestern and midwestern production corridors.
India
PLI scheme incentives for advanced chemistry cell manufacturing attract gigafactory investments that will require localized tray fabrication capacity. Hindalco Industries' backward integration into primary aluminum feedstock dominates South Asian supply. Gujarat and Maharashtra industrial corridors host emerging extrusion capacity targeting domestic passenger and commercial EV programs.
South Korea
Hyundai-Kia EV platform expansion drives tray procurement from domestic extruders with SAMR-qualified export capabilities. Busan-Ulsan manufacturing clusters supply both local OEM assembly and Chinese cell-to-pack integration facilities. Seoul Capital Area engineering centers coordinate alloy specification with European and North American qualification programs.
Electric Vehicle Extruded Aluminum Battery Trays Market Competitive Landscape
Chinese producers anchor the volume-driven tier; European and North American specialists hold premium qualification positions. The vendor base stratifies across three tiers: integrated aluminum majors with captive smelter access, independent extrusion houses serving regional OEM clusters, and emerging Asian fabricators competing on compressed lead times. Strategic archetypes include backward-integrated feedstock controllers, platform-locked engineering partners, and scale-focused modular tray suppliers. Dominant competitive moves encompass geographic expansion into battery corridor proximities and qualification portfolio diversification across multiple OEM architectures.
Among European rolling and extrusion networks, Constellium occupies a position exemplifying premium-tier platform anchoring, while Novelis Inc represents the high-recycled-content alloy development archetype. Hindalco Industries Ltd. sits within the backward-integrated feedstock controller tier, leveraging captive primary aluminum supply. These three entities illustrate how competitive positioning diverges between qualification-locked engineering relationships and raw material security strategies.
| Leading Market Players |
|---|
| Constellium |
| BENTELER |
| Novelis Inc |
| Gestamp |
| Guangdong Hoshion Industrial Aluminium |
| Foshan Shijun Hongmao Aluminum Technology Co. Ltd. |
| Waldaschaff Automotive GmbH |
| Hindalco Industries Ltd. |
| Standard Technologies |
| Others |
Pricing and Supply Chain Analysis
LME aluminum contract fluctuations cascade through extrusion fabrication tiers, compressing margins for tray suppliers without captive smelter access while amplifying pricing power for Hindalco Industries and other backward-integrated feedstock controllers. This upstream cost volatility stratifies downstream pricing across structural, modular, and lightweight tray configurations, with OEM direct contracts absorbing alloy risk differently than aftermarket channels.
Pricing Analysis
Distributor margins in aftermarket channels run 18-25 points above direct-to-OEM contract rates, creating a three-tier pricing structure across premium structural trays, standard modular configurations, and economy lightweight alternatives. Certification grade under NHTSA and China MIIT protocols commands substantial premiums over uncertified commercial fleet supply. Pricing pressure stems from magnesium AZ91D substitution in cost-sensitive modular segments where crashworthiness thresholds permit thinner-wall geometries. Commercial fleet aggregators exhibit highest price sensitivity, while German premium OEMs prioritize qualification-locked engineering partnerships over unit cost.
Supply Chain Analysis
India PLI scheme domestic-content mandates are reshaping sourcing patterns, requiring localized tray fabrication adjacent to cell gigafactories in Gujarat and Maharashtra corridors. Primary aluminum feedstock concentrates in China, India, and Russia, with 6xxx-series billet supply drawing from Hindalco's backward-integrated smelter network and Constellium's European rolling assets. Single-source vulnerability around South Asian feedstock concentration threatens European and North American extruders during LME price spikes. Distribution runs through mill-direct supply to OEM assembly plants and CATL-BYD manufacturing corridors, bypassing traditional tiered automotive supply structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with EPA tailpipe emissions thresholds and China MIIT mandates driving steady procurement expansion across passenger EV platforms regardless of cyclical automotive demand fluctuations.
For Market Incumbents: Cement platform-locked engineering relationships through 36-month qualification cycles before alternative alloy windows close, while deepening captive smelter or recycling-stream access to defend against primary aluminum price volatility. Magnesium substitution threats in modular tray segments require accelerated R&D on integrated cooling channel geometries that AZ91D die-casting cannot replicate at equivalent thermal performance.
For New Entrants and Emerging Players: Advanced friction-stir welding automation offers a technology-first wedge into modular tray assembly, where Chinese OEMs in Ningbo and Shenzhen manufacturing corridors unbundle engineering from chassis integration. Target commercial fleet aggregated procurement for electric delivery van platforms, where specification authority fragmentation creates entry pathways absent in premium passenger vehicle direct-OEM channels. Lead with compressed 18-month qualification timelines against incumbent 36-month cycles.
For Investors and Strategic Acquirers: Roll-up economics work for regional extrusion houses with SAMR-qualified export capabilities because OEM platform consolidation is compressing supplier panels to multi-architecture-qualified partners. Five-to-ten year viability hinges on battery passport traceability compliance and closed-loop alloy recycling infrastructure. Watch ECHA REACH enforcement timelines as inflection indicators for European pretreatment chemistry requalification costs that will concentrate fabrication capacity among capitalized players.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Alloy Recycling | Novelis' high-recycled-content 6xxx formulations qualify for EU battery passport requirements ahead of virgin-metal competitors. |
| Geographic Manufacturing Footprint | CATL and BYD manufacturing corridors in Ningbo and Shenzhen anchor localized tray fabrication clusters bypassing tiered supply structures. |
| Platform Standardization | OEMs compress procurement cycles from 36-month platform development to 18-month refresh timelines through modular tray architectures. |
| Long-term Supply Agreement | Constellium leverages European rolling and extrusion network to anchor supply for premium German passenger vehicle platforms. |
| Joint Venture | Hindalco Industries' backward integration into primary aluminum creates feedstock security for South Asian EV component corridors. |
Research Methodology
Multiple input streams — extrusion plant operating data, OEM platform engineering specifications, and regulatory filing databases — were reconciled through bottom-up and top-down triangulation. Primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and aluminum alloy R&D directors were validated against secondary sources including EPA emissions filings, China MIIT technical guideline publications, ECHA REACH restriction documentation, and vehicle production registration databases.
Historical shipment volumes were cross-referenced against panel input from extruder capacity announcements and OEM platform launch schedules to model progression across the analysis window. Segmentation dimensions included product architecture type, end-user procurement authority, vehicle electrification platform scale, and regional regulatory compliance cluster. CAGRs were derived from alloy intensity per vehicle projections, platform penetration curves, and substitution elasticity estimates for magnesium alternatives.
The model holds under stable LME aluminum pricing and sustained EPA emissions enforcement; deviation in primary metal volatility or REACH restriction acceleration would shift margin distribution across integrated versus non-integrated supply chain tiers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Asia Pacific Automotive High Performance Electric Vehicles Market
Electric Vehicles
China Electric Truck Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
Global Solar Powered Car Market
Electric Vehicles
UK Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
EV Transmission System Market
Electric Vehicles
Electric Vehicle Operations Management Solutions Market
Electric Vehicles
Electric Van Market
Electric Vehicles
Off-Highway Electric Machine Battery Pack Systems Market
Electric Vehicles
Electric Commercial Vehicle Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
Automotive EV HUB Market
Electric Vehicles
Busbar for EV Market
Electric Vehicles
Luxury Electric Vehicle Market
Electric Vehicles
EV PTC Heaters Market
Electric Vehicles
Singapore Electric Vehicle Market