
 China Same Day Delivery Market | 2026-2036
China Same Day Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
China Same Day Delivery Market Outlook
Urban fulfillment networks is reconfiguring last-mile economics across Chinese megacities. SF Express leverages its integrated air-ground infrastructure to dominate premium same-day corridors. JD Logistics anchors customer expectations through owned warehouse-to-door capacity. Meituan competes on density, sustaining sub-30-minute averages in tier-one restaurant and grocery verticals.
Same day delivery denotes logistics execution completing order fulfillment within twenty-four hours of purchase confirmation, requiring real-time inventory positioning, dynamic route algorithms, and distributed micro-fulfillment nodes. E-commerce delivery commands the largest volume pool while food delivery generates the highest frequency and customer retention metrics. Motorbike delivery occupies the dominant modal share in dense urban cores, though automated systems and drone delivery pilot zones are expanding fastest in regulatory sandboxes across Shenzhen and Chengdu.
MIIT's digital logistics standards, SAMR's platform economy compliance frameworks, and municipal traffic bureaus' electric vehicle mandates collectively shape fleet composition, rider certification, and data transparency obligations. Stakeholders must monitor how evolving GB standards for autonomous delivery vehicles intersect with local airspace and road access permissions.
Market Dynamics
MIIT's digital logistics mandates are forcing fleet-wide compliance retrofits across China's same-day delivery networks, accelerating consolidation among operators lacking capital reserves for GB-standard telematics and electric vehicle transitions.
Growth Catalysts
- Dual carbon goals:Municipal electric vehicle mandates in Shanghai, Hangzhou, and Shenzhen subsidize battery-swapping infrastructure, lowering last-mile fleet operating costs.
- Fresh grocery verticals:Cold-chain micro-fulfillment nodes positioned within three kilometers of dense residential clusters compress delivery windows for perishables.
- Yangtze River Delta cluster:Intercity highway networks and shared sorting facilities enable cross-metropolitan same-day coverage at unit economics previously limited to single-city operations.
Market Restraints
- Lithium carbonate volatility:Battery pack costs fluctuate with raw material indices, squeezing margins for electric two-wheeler fleets comprising over seventy percent of urban delivery vehicles.
- Rider supply concentration:Platform-dependent gig workers cluster in tier-one cities, creating recruitment bottlenecks during peak demand windows in lower-tier markets.
- Autonomous vehicle certification delays:GB standards for unmanned ground vehicles remain draft status, freezing commercial deployment timelines in designated pilot zones.
Strategic Opportunities
- Chengdu-Chongqing corridor:Western China's underpenetrated same-day infrastructure offers first-mover advantages for operators establishing automated sorting hubs ahead of demand maturation.
- Drone-aircraft convergence:Low-altitude economy policies in Shenzhen enable beyond-visual-line-of-sight trials, opening mountainous and island geographies previously excluded from same-day networks.
- SAMR data transparency mandates:Real-time tracking requirements create demand for third-party logistics software vendors serving mid-tier retailers lacking in-house development capacity.
Industry Challenges
- Telematics integration complexity:Legacy warehouse management systems require API overhauls to interface with MIIT-mandated vehicle monitoring platforms, extending IT project timelines.
- Rider certification bottlenecks:Municipal traffic bureau licensing backlogs for electric commercial vehicles delay fleet expansion during seasonal demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Same Day Delivery Market |
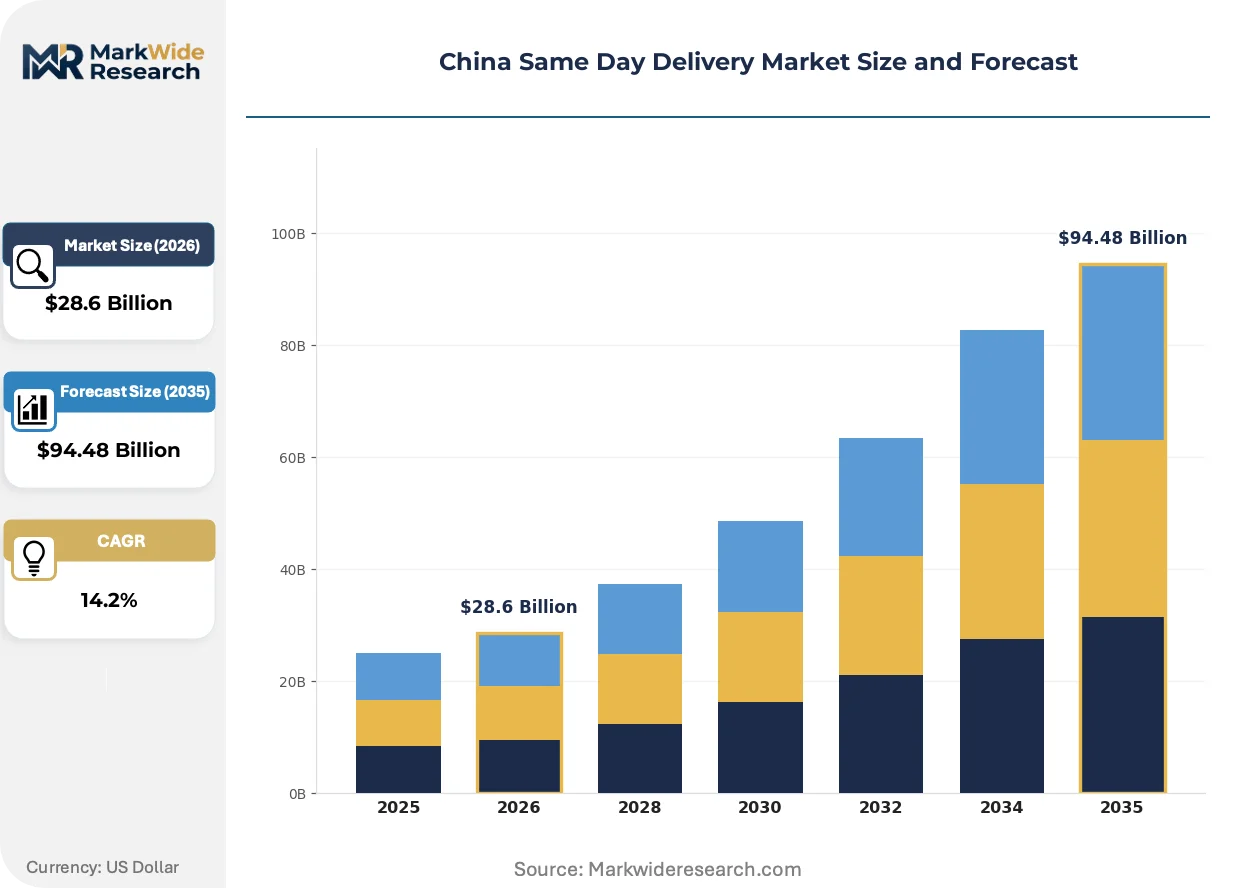
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Retail Delivery, Food Delivery, Courier Services, E-commerce Delivery Technology: Mobile Apps, Logistics Software, GPS Tracking, Automated Systems Customer Type: Businesses, Individual Consumers, Enterprises, Startups Delivery Method: Drone Delivery, Bicycle Courier, Motorbike Delivery, Van Delivery |
| Companies Covered | SF Express, ZTO Express, STO Express, Shanghai YTO Express, China Post, JD Logistics, Cainiao Network, Meituan, Ele.me, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Same Day Delivery Market Strategic Shifts
Operational technology is hybridizing across China's same-day delivery sector, blending automated hardware with human-augmented workflows as regulators and cost pressures force simultaneous efficiency and compliance investments.
Motorized last-mile fleets are hybridizing with battery-swapping infrastructure to eliminate charging downtime. Food delivery platforms deploy modular battery exchange cabinets at merchant kitchens and residential compounds. This convergence compresses vehicle utilization rates while satisfying municipal electric vehicle quotas without range anxiety penalties.
MIIT's digital logistics standards mandate real-time vehicle telemetry and driver behavior monitoring for all commercial delivery fleets. Operators must retrofit existing two-wheelers with GB-compliant IoT hardware or face route license suspensions. Premium same-day corridors face the steepest compliance costs, accelerating consolidation among capital-constrained regional players.
Merchant procurement of delivery services is fragmenting across dedicated, platform, and hybrid fulfillment models. Large grocery chains build captive rider pools for high-frequency SKUs while outsourcing long-tail items to third-party platforms. This bifurcation is most visible in Shanghai, where warehouse-to-door operators compete directly with density-optimized platform networks for identical customer segments.
China Same Day Delivery Market Segmentation
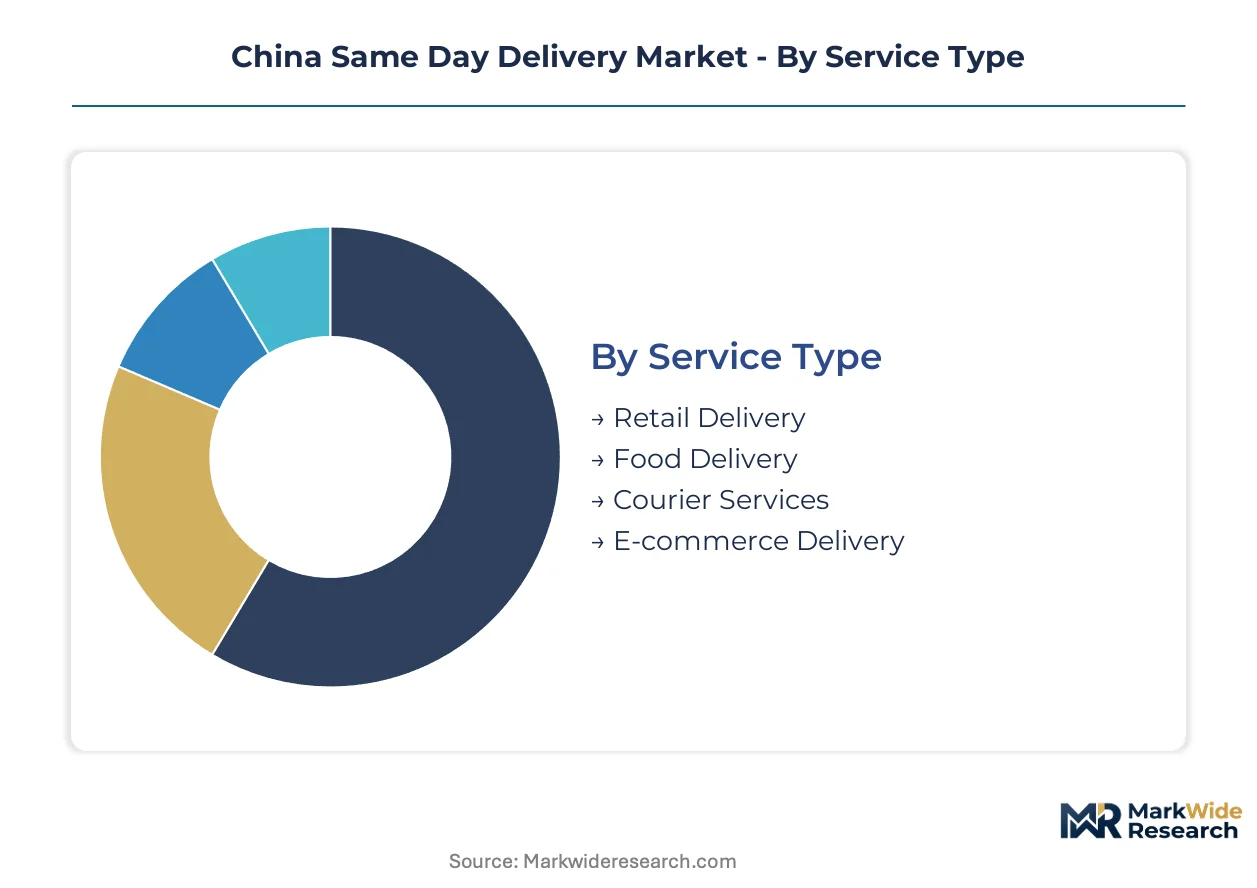
Same-day delivery economics diverge sharply across service types and delivery methods, with perishables demanding sub-hour cycles while courier services operate on extended windows. Technology deployment and customer procurement patterns further stratify unit costs and capital intensity across the value chain.
Service Type:
Food delivery compresses fulfillment cycles to under thirty minutes, while retail and courier segments stretch toward the full twenty-four-hour boundary. E-commerce occupies the middle ground with afternoon cutoffs for evening arrival.
- Food Delivery:Restaurant and fresh grocery orders require thermal packaging and real-time inventory synchronization with merchant POS systems. Meituan and Ele.me battle for density in Shanghai and Beijing, where kitchen-to-door averages now sit below twenty-five minutes during peak windows. Cold-chain micro-fulfillment nodes within three kilometers of residential clusters anchor this segment's infrastructure.
- E-commerce Delivery:JD Logistics and SF Express dominate premium same-day corridors through owned warehouse-to-door capacity. Intercity highway networks across the Yangtze River Delta enable cross-metropolitan coverage at unit economics previously limited to single-city operations.
- Retail Delivery:Department store and specialty retail orders concentrate in tier-one cities with established dark store networks. Hema and 7FRESH anchor supermarket same-day through hybrid online-offline inventory pools.
- Courier Services:Document and small parcel express operates on longer fulfillment windows with lower frequency but higher margin per shipment. SF Express leverages integrated air-ground infrastructure to capture premium corporate accounts.
Food delivery dominates transaction volume. E-commerce is where infrastructure investment concentrates most heavily.
Technology:
Platform operators stratify technology spend across customer-facing interfaces and back-end optimization layers, with compliance mandates now forcing universal telemetry adoption regardless of scale.
- Mobile Apps:Consumer-facing order interfaces with real-time tracking, estimated arrival windows, and rider communication channels anchor customer retention. Super-app integration within WeChat and Alipay ecosystems concentrates discovery and payment flows.
- Logistics Software:Route optimization, dynamic batching, and demand forecasting engines determine fleet utilization rates. Third-party vendors serve mid-tier retailers lacking in-house development capacity under SAMR data transparency mandates.
- GPS Tracking:Real-time vehicle telemetry satisfies MIIT digital logistics standards while enabling customer-facing location services. GB-compliant IoT hardware retrofits extend IT project timelines for legacy operators.
- Automated Systems:Robotic sorting hubs and unmanned ground vehicles pilot in Shenzhen and Chengdu regulatory sandboxes. Draft GB standards freeze commercial deployment timelines despite low-altitude economy policy momentum.
Mobile apps capture the largest user touchpoint base. Automated systems are climbing the fastest on regulatory momentum.
Customer Type:
Procurement patterns bifurcate between high-frequency, low-margin consumer orders and negotiated enterprise contracts with dedicated capacity guarantees and SLA penalties.
- Individual Consumers:End-users ordering meals, groceries, and personal goods through platform marketplaces with dynamic pricing and promotional subsidies. Retention depends on sub-thirty-minute reliability during peak demand windows.
- Businesses:Small and mid-sized merchants purchasing delivery-as-a-service on per-order or subscription bases. Fragmentation across dedicated, platform, and hybrid fulfillment models is most visible in Shanghai.
- Enterprises:Large retailers and brands negotiating captive rider pools or volume commitments with tiered pricing structures. Grocery chains build in-house capacity for high-frequency SKUs while outsourcing long-tail items.
- Startups:Emerging brands and vertical specialists testing same-day propositions before scaling to owned logistics. Capital constraints force platform dependency during market validation phases.
Individual consumers generate the highest transaction frequency. Enterprises command the steepest expansion trajectory on vertical integration incentives.
Delivery Method:
Modal choice trades speed against payload capacity and regulatory compliance burden, with municipal electric vehicle mandates now reshaping fleet composition regardless of operational preference.
- Motorbike Delivery:Two-wheelers comprise over seventy percent of urban delivery vehicles, navigating congestion and parking constraints in dense cores. Battery-swapping infrastructure eliminates charging downtime while satisfying municipal EV quotas.
- Bicycle Courier:Human-powered delivery persists in historic districts and pedestrianized zones with vehicle restrictions. Limited to lightweight payloads and short-radius operations.
- Van Delivery:Four-wheeled vehicles handle bulk grocery orders and B2B shipments requiring payload capacity beyond two-wheeler limits. Electric van adoption accelerates under dual carbon goals with subsidized charging infrastructure.
- Drone Delivery:Beyond-visual-line-of-sight trials in Shenzhen enable mountainous and island geographies previously excluded from same-day networks. Low-altitude economy policies anchor regulatory permissioning.
Motorbike delivery anchors the installed fleet base. Drone delivery is gaining share fastest on geographic expansion potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium same-day corridors in Shanghai command unit economics three times denser than comparable routes in Chengdu, creating a pricing-power asymmetry that rewards early infrastructure deployment in the Yangtze River Delta over western expansion bets.
Yangtze River Delta
Shanghai, Hangzhou, and Suzhou generate the highest same-day transaction density through intercity highway networks and shared sorting facilities. MIIT's digital logistics mandates accelerate GB-standard telematics adoption across fleets operating cross-metropolitan routes. Cold-chain micro-fulfillment nodes within three kilometers of residential clusters compress delivery windows for fresh grocery verticals.
Pearl River Delta
Shenzhen anchors drone delivery pilot zones through low-altitude economy policies enabling beyond-visual-line-of-sight trials. SAMR's platform economy compliance frameworks reshape data transparency obligations for operators serving Guangzhou and Dongguan. Battery-swapping infrastructure subsidies under municipal electric vehicle mandates lower last-mile fleet operating costs.
Beijing-Tianjin-Hebei
Corporate courier accounts concentrate in the capital's premium document and small parcel express segments. Dual carbon goals drive electric van adoption through subsidized charging infrastructure across the northern corridor. Dark store networks for supermarket same-day service hybridize online-offline inventory pools.
Sichuan-Chongqing
The Chengdu-Chongqing corridor offers first-mover advantages for automated sorting hubs ahead of demand maturation in western China. Municipal traffic bureau licensing backlogs for electric commercial vehicles delay fleet expansion during seasonal demand spikes. Restaurant and fresh grocery orders require thermal packaging synchronized with merchant POS systems.
Shandong Peninsula
Qingdao and Jinan emerge as testing grounds for unmanned ground vehicle pilots pending final GB standard certification. Lithium carbonate volatility squeezes margins for electric two-wheeler fleets comprising the dominant urban delivery modal share. Platform-dependent gig workers cluster in tier-one adjacent markets, creating recruitment bottlenecks during peak windows.
China Same Day Delivery Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The China same-day delivery market consolidates around three structural layers: integrated logistics operators with captive air-ground infrastructure, density-optimized food delivery platforms, and e-commerce ecosystem players with warehouse-to-door capacity. Strategic archetypes include premium corridor specialists, vertical-integrated grocery networks, and merchant-facing fulfillment-as-a-service providers. Dominant competitive moves encompass battery-swapping infrastructure partnerships and compliance-driven fleet retrofit programs.
Among integrated operators, SF Express and JD Logistics exemplify the premium infrastructure archetype through owned warehouse-to-door capacity and air-ground network control. Meituan occupies a position within the density-optimized platform tier, competing on sub-thirty-minute averages in restaurant and grocery verticals. These three anchors illustrate how capital intensity and regulatory compliance capabilities stratify competitive positioning across China's same-day delivery corridors.
| Leading Market Players |
|---|
| SF Express |
| ZTO Express |
| STO Express |
| Shanghai YTO Express |
| China Post |
| JD Logistics |
| Cainiao Network |
| Meituan |
| Ele.me |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta cluster concentrates same-day fulfillment capacity within a three-hour highway radius, granting operators in Shanghai and Hangzhou pricing power over western corridors where infrastructure gaps force premium surcharges. MIIT's GB-standard telematics mandates compress margins for regional players lacking capital reserves, accelerating consolidation that reshapes competitive pricing dynamics.
Pricing Analysis
The customization-premium spread between configured same-day corridors and standard next-day service widens as battery-swapping infrastructure subsidies lower operating costs in tier-one cities. Three-tier pricing structure across premium, standard, and economy levels segments buyers by delivery window urgency and payload requirements. Cost compression in economy tiers intensifies because lithium carbonate volatility squeezes electric two-wheeler fleet margins. Individual consumers exhibit highest price sensitivity to delivery fees, while enterprise accounts negotiating captive rider pools prioritize SLA reliability over per-order cost.
Supply Chain Analysis
Supplier-financing facilities from battery manufacturers extend payment terms for fleet operators retrofitting GB-compliant IoT hardware under MIIT compliance deadlines. Component manufacturing draws from China, South Korea, and Japan for lithium-ion cells, electric motors, and telematics modules. Distribution runs through platform-controlled rider networks and merchant-facing fulfillment-as-a-service providers. Single-source vulnerability concentrates in battery cell supply, where raw material index fluctuations transmit directly to fleet operating costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Same-day delivery functions as a service-attach opportunity where recurring logistics software subscriptions and battery-swapping membership fees expand faster than hardware-dependent vehicle sales. The shift toward compliance-driven fleet retrofits accelerates demand for third-party telematics and route optimization platforms.
For Market Incumbents: Harden compliance capabilities ahead of final GB standard certification for autonomous vehicles, securing route licenses that freeze out capital-constrained regional operators. Deepen backward integration into battery-swapping infrastructure to capture recurring revenue streams and lock in rider supply through exclusive cabinet networks. Defend density advantages in Shanghai and Hangzhou by preempting automated sorting hub deployment in the Chengdu-Chongqing corridor. For New Entrants and Emerging Players: Pursue white-space opportunities in Sichuan-Chongqing's underpenetrated same-day infrastructure before demand maturation attracts incumbent capacity expansion. Target merchant-facing fulfillment-as-a-service for mid-tier retailers lacking in-house logistics development capacity under SAMR data transparency mandates. Differentiate through specialized cold-chain micro-fulfillment for fresh grocery verticals where thermal packaging expertise creates switching costs. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compliance-enabled platform operators with demonstrated GB-standard telematics integration and municipal EV mandate adherence. Long-term viability hinges on regulatory permissioning for beyond-visual-line-of-sight drone trials and unmanned ground vehicle commercial deployment. The signal to watch is MIIT's publication timeline for final autonomous vehicle certification standards, which would unlock capital deployment into automated sorting and last-mile robotics.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Swapping Infrastructure Partnership | MIIT subsidies in Shanghai and Shenzhen lower fleet operating costs while creating captive rider lock-in through exclusive cabinet networks. |
| GB-Standard Telematics Retrofit Program | Compliance-driven fleet upgrades satisfy MIIT digital logistics mandates and extend IT project timelines that advantage capital-rich operators. |
| Cold-Chain Micro-Fulfillment Node Expansion | Three-kilometer residential positioning compresses delivery windows for perishables and anchors fresh grocery customer retention metrics. |
| Drone Delivery Pilot Zone Application | Shenzhen's low-altitude economy policies enable beyond-visual-line-of-sight trials opening mountainous geographies previously excluded from same-day networks. |
| Automated Sorting Hub Deployment | Chengdu-Chongqing corridor first-mover positioning captures western China demand maturation ahead of incumbent Yangtze River Delta expansion. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with logistics operations directors, fleet procurement managers, municipal traffic bureau officials, and cold-chain infrastructure specialists; and secondary validation against MIIT policy filings, SAMR compliance bulletins, municipal EV subsidy disclosures, and customs records for electric two-wheeler component trade. Bottom-up triangulation across operator-reported fleet metrics and top-down reconciliation with Yangtze River Delta highway utilization data anchored volume estimates.
Forecast inputs considered service type segmentation across food delivery, e-commerce, retail, and courier verticals alongside technology deployment patterns including mobile app penetration, GPS tracking adoption, and automated systems pilot status. CAGRs were derived through demand elasticity modeling against urban consumption growth and fleet capacity expansion curves across the projection horizon. Battery-swapping infrastructure rollout schedules and GB standard certification timelines served as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate pricing indices, municipal EV subsidy continuity, or MIIT enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about regulatory permissioning timelines and fleet electrification compliance costs. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Pharmaceutical Logistics Market
Logistics and Shipping
GCC Dangerous Goods Logistics Market
Logistics and Shipping
Event Logistics Market
Logistics and Shipping
Australia Freight and Logistics Market
Logistics and Shipping
Cargo Transportation Market
Logistics and Shipping
Singapore Chemical Logistics Market
Logistics and Shipping
China Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Digital Freight Brokerage Market
Logistics and Shipping
Czech Republic Freight and Logistics Market
Logistics and Shipping
Last Mile Delivery Transportation Market
Logistics and Shipping
Hong Kong Container Transshipment Market
Logistics and Shipping
Germany Last Mile Delivery Market
Logistics and Shipping
Middle Mile Delivery Market
Logistics and Shipping
Central and Eastern Europe Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Latin America Logistics Market
Logistics and Shipping
China Shipping Agency Services Market