
 Electric Vehicle Battery on Demand Market | 2026-2036
Electric Vehicle Battery on Demand Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Battery on Demand Market Foresight
Modular battery leasing is decoupling vehicle ownership from energy procurement, forcing OEMs to redesign chassis architectures around swappable pack geometries. Contemporary Amperex Technology Co., Limited leverages its cell-to-pack expertise to dominate swapping-station supply contracts across Asian logistics hubs. BYD Company Ltd. anchors its vertical battery-manufacturing chain to undercut third-party lessors on cost per kilowatt-hour. LG Energy Solution Ltd. competes by specializing in high-nickel chemistries optimized for rapid-swap thermal profiles.
Electric Vehicle Battery on Demand denotes a service model where traction energy storage is procured through subscription, rental, or per-use contracts rather than capital purchase, with packs typically rated between 40 kWh and 150 kWh and engineered for standardized mechanical interfaces enabling sub-five-minute exchange. The model eliminates residual-value risk for fleet operators while transferring cell-degradation liability to the service provider. Lithium-ion chemistry occupies the dominant share of installed swap capacity owing to mature recycling infrastructure and established supply chains, though solid-state configurations are attracting R&D capital for their potential to halve cooling-system mass. Passenger vehicles represent the largest addressable volume pool, while commercial vehicles command premium pricing due to higher duty cycles and guaranteed uptime clauses.
The EPA tailpipe-emission standards and California Air Resources Board mandates are accelerating fleet electrification timelines and expanding the addressable base for battery-service contracts in North America. China's MIIT enforces GB/T swap-connector standards that lock foreign pack suppliers into domestic certification pathways. Europe's CSRD disclosure rules pressure fleet operators to outsource battery lifecycle accountability to specialized service firms. Stakeholders must monitor regulatory divergence in pack-recycling obligations and interoperability standards, as these will determine which service architectures achieve cross-border scalability.
Market Dynamics
Modular battery-swapping infrastructure is decoupling energy procurement from vehicle ownership, forcing fleet operators to outsource cell lifecycle management while concentrating capex burdens among specialized service providers.
Growth Catalysts
- China's GB/T swap-connector standards:Domestic certification pathways lock in pack suppliers while accelerating station deployment across logistics corridors serving commercial van fleets.
- Ride-hailing electrification mandates:Fleet operators in dense urban clusters face zero-emission deadlines that favor subscription-based energy models over capital-intensive battery purchases.
- Cell-to-pack thermal engineering:Advances in rapid-swap cooling architectures reduce exchange downtime below five minutes, enabling uptime guarantees for last-mile delivery contracts.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings compress leasing margins and force service providers to index contracts to commodity benchmarks.
- Pack geometry fragmentation:Proprietary chassis designs from major OEMs prevent cross-platform swap compatibility, fragmenting station utilization rates.
- Station infrastructure capex intensity:Automated battery handling systems and fire-suppression installations require eight-figure capital commitments per hub.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Domestic manufacturing incentives attract swapping-station operators seeking localized pack supply chains.
- Solid-state chemistry convergence:Next-generation electrolytes promise reduced cooling-system mass, enabling denser station layouts and faster exchange cycles.
- Second-life grid storage applications:Retired swap packs find secondary revenue streams in stationary energy arbitrage, improving unit economics for lessors.
Industry Challenges
- Battery management system software integration:Fleet telematics platforms must reconcile state-of-charge data across heterogeneous pack vintages and chemistries.
- Fire-safety certification timelines:UL 9540A thermal runaway testing protocols delay station permitting in jurisdictions with stringent hazard-mitigation codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Battery on Demand Market |
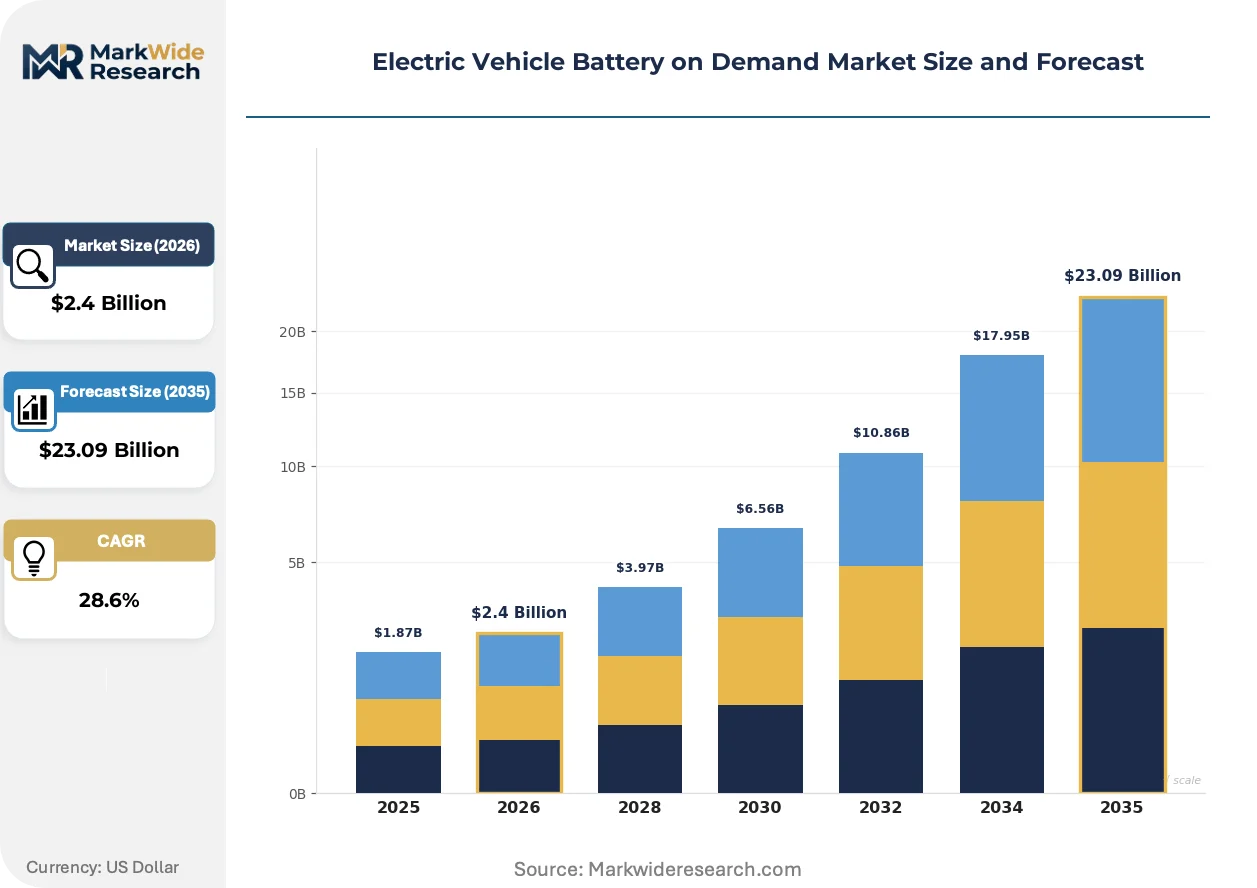
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $23.09 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Nickel-metal Hydride, Solid State, Lead-acid Application: Passenger Vehicles, Commercial Vehicles, E-Scooters, E-Bikes Distribution Channel: Online Retail, Dealerships, Third-party Retailers, Direct Sales Performance Rating: High Capacity, Fast Charging, Long Cycle Life, Thermal Stability |
| Companies Covered | Contemporary Amperex Technology Co., Limited, BYD Company Ltd., LG Energy Solution Ltd., Panasonic Corporation, Samsung SDI Co., Ltd., SK On Co., Ltd., CATL, CALB, Tesla, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Battery on Demand Market Shifts & Advancements
Standardized mechanical interfaces and predictive degradation analytics are converging to transform battery swapping from a niche logistics solution into a scalable urban mobility infrastructure layer.
Silicon-anode chemistries are integrating into next-generation swap packs to boost energy density without expanding physical footprint. Commercial van operators in Germany's Berlin-Munich corridor are piloting these configurations to extend route range. The technology is compressing total cost-of-ownership calculations for high-mileage fleets by reducing swap frequency.
Europe's F-Gas Regulation is tightening coolant specifications for thermal management systems, forcing station operators to retrofit refrigeration loops with lower-global-warming-potential alternatives. Pack suppliers serving Dutch and Belgian logistics hubs face accelerated compliance deadlines. The regulatory pressure is concentrating procurement among service firms with captive retrofit capabilities.
Fleet managers are unbundling battery warranties from vehicle purchase agreements, preferring per-kilometer service contracts that transfer degradation risk to third-party lessors. This preference shift displaces traditional equipment financing in urban delivery segments. The Netherlands and Denmark show the highest penetration of unbundled energy procurement among European commercial operators.
Electric Vehicle Battery on Demand Market Segmentation
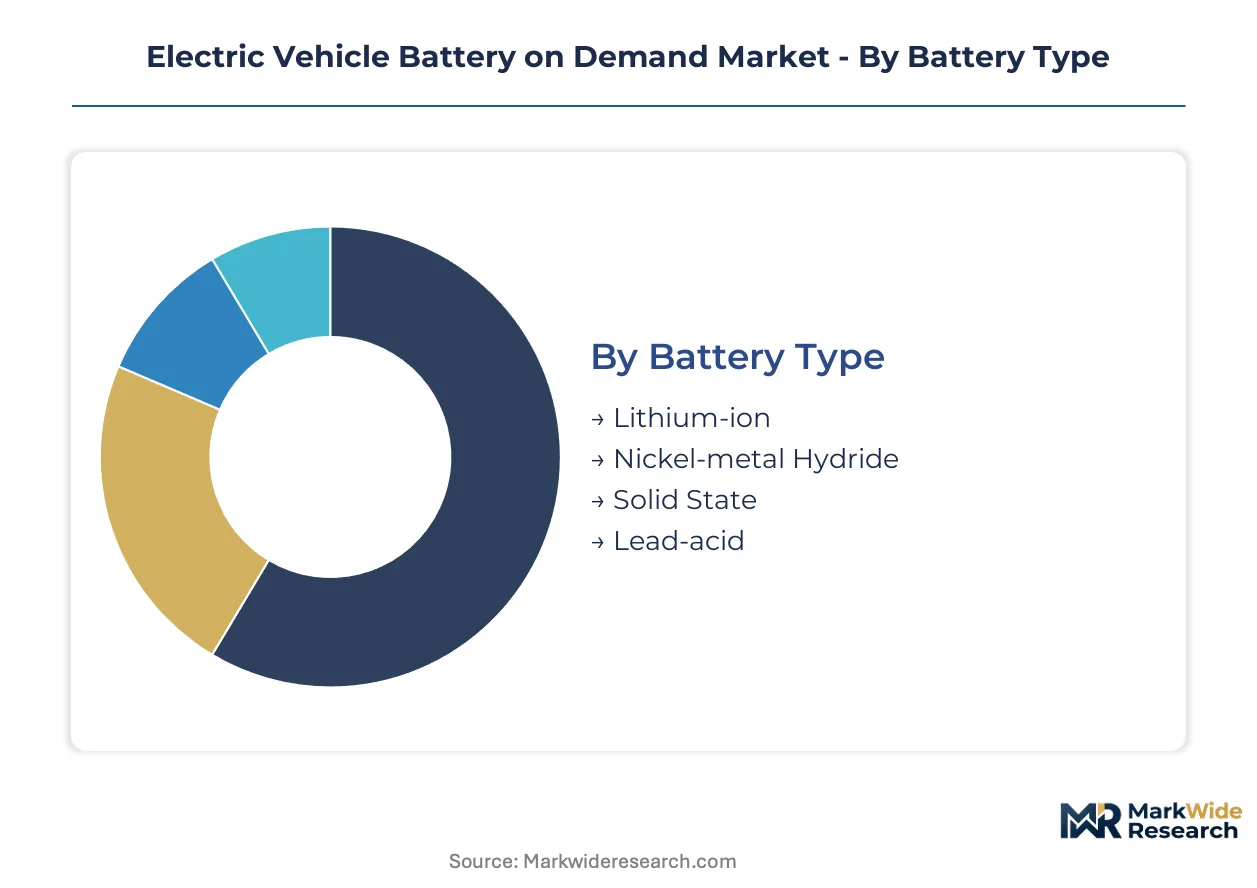
Battery-as-a-service architectures fragment across multiple technical and commercial dimensions, each demanding distinct procurement strategies and infrastructure investments. Fleet operators select segments based on duty-cycle intensity, swap-frequency requirements, and residual-value risk allocation preferences.
Battery Type:
Standardization pressures dominate cell chemistry selection, yet proprietary thermal-management designs create lock-in effects across swapping networks.
- Lithium-ion:Mature cell-to-pack architectures leverage established recycling infrastructure and GB/T-certified connector standards. Demand concentrates in Chinese logistics corridors where MIIT-mandated interoperability accelerates station deployment for commercial van fleets.
- Solid State:Next-generation electrolyte configurations eliminate liquid cooling loops, enabling denser station layouts and sub-three-minute exchange cycles. Pilot programs in Germany's Berlin-Munich corridor test silicon-anode variants for extended route range.
- Nickel-metal Hydride:Legacy chemistry persists in cost-sensitive e-bike segments with lower energy-density requirements.
- Lead-acid:Niche stationary-buffer applications at swapping stations exploit second-life economics.
Leading the category by volume: Lithium-ion. Expanding most quickly: Solid State.
Application:
Commercial intensity separates premium uptime guarantees from consumer-grade convenience pricing.
- Commercial Vehicles:High-duty-cycle vans and trucks command guaranteed-availability clauses and premium per-kilometer contracts. Fleet operators in the Netherlands and Denmark unbundle battery warranties from chassis purchases, transferring degradation liability to specialized lessors.
- Passenger Vehicles:Ride-hailing electrification mandates in dense urban clusters favor subscription models over capital-intensive pack purchases. EPA tailpipe standards and CARB mandates accelerate fleet conversion timelines across US metropolitan networks.
- E-Scooters:Micromobility operators prioritize weight-minimized packs with standardized mechanical interfaces for automated handling systems.
- E-Bikes:Last-mile delivery couriers drive demand for rapid-swap networks with high station density and low per-use pricing.
Dominant by revenue: Commercial Vehicles. Gaining share fastest: Passenger Vehicles.
Distribution Channel:
Channel selection reflects fleet scale and integration depth with vehicle procurement workflows.
- Direct Sales:Large logistics operators negotiate enterprise service agreements with captive swapping infrastructure and dedicated pack pools.
- Dealerships:OEM-anchored channels bundle battery subscriptions with vehicle financing, locking customers into proprietary swap geometries.
- Third-party Retailers:Independent service firms compete on cross-platform compatibility and commodity-indexed pricing.
- Online Retail:Digital platforms enable spot-market battery access for intermittent users and seasonal demand spikes.
Primary volume route: Direct Sales. Climbing the fastest: Online Retail.
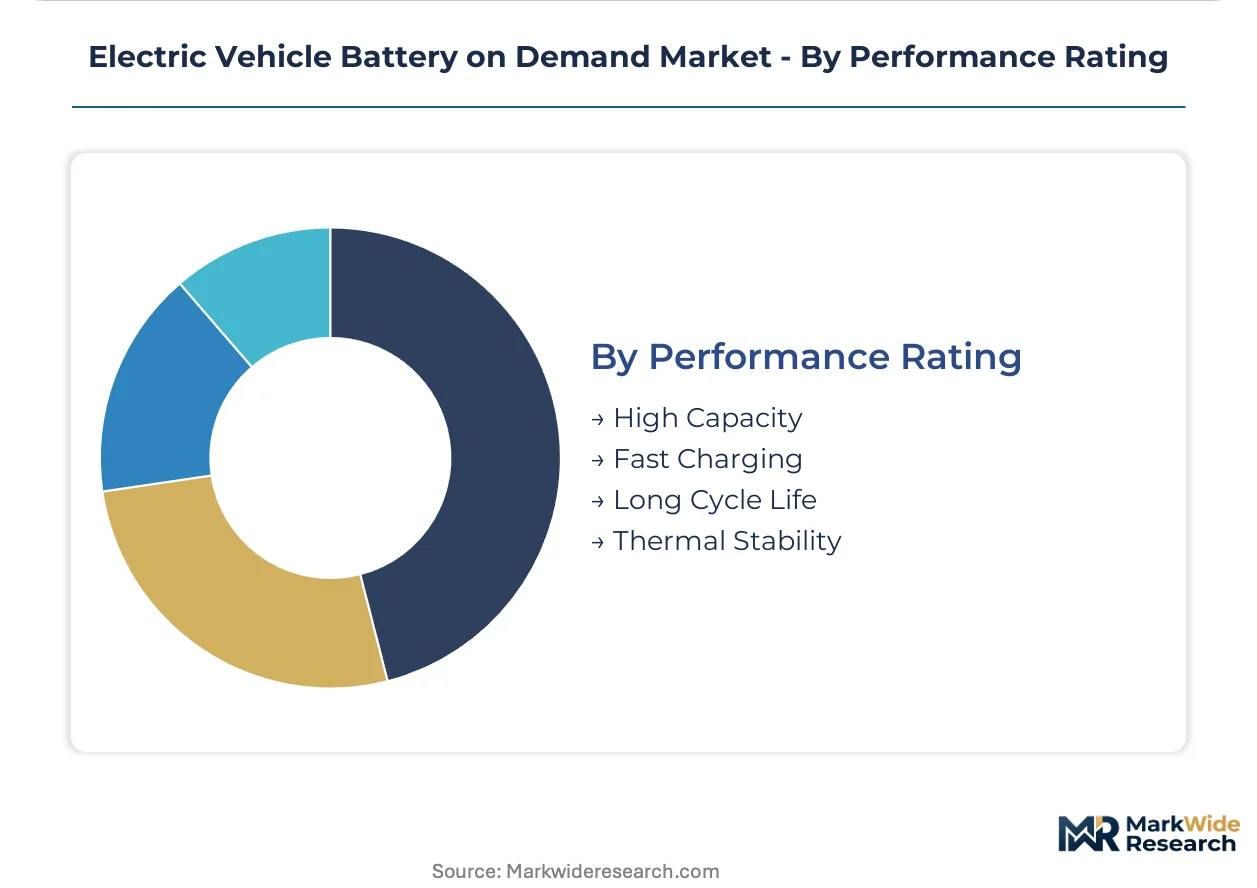
Performance Rating:
Specification priorities shift with climate exposure and route electrification density.
- Fast Charging:Rapid-swap thermal profiles demand advanced cooling architectures to prevent cell degradation during high-frequency exchange cycles.
- Thermal Stability:Europe's F-Gas Regulation mandates lower-global-warming-potential refrigerants, forcing station retrofit investments.
- High Capacity:Extended-range configurations reduce swap frequency for intercity commercial routes.
- Long Cycle Life:Degradation-resistant chemistries improve unit economics for lessors retaining residual-value risk.
Highest procurement priority: Fast Charging. Steepest specification growth: Thermal Stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of swappable battery cells while Germany and the United States concentrate demand from commercial fleet operators. This production-consumption divide shapes cross-border supply agreements and certification reciprocity negotiations.
China
MIIT enforces GB/T swap-connector standards that accelerate station deployment across logistics corridors serving commercial van fleets. The dual carbon goals tighten emissions benchmarks and reshape procurement rules for mobile energy assets. Contemporary Amperex Technology Co., Limited anchors supply contracts across Asian logistics hubs in Shanghai and Shenzhen.
Germany
Berlin and Munich host dense networks of swapping stations serving commercial van operators with guaranteed uptime clauses. The F-Gas Regulation tightens coolant specifications for thermal management systems, forcing station retrofit investments. Pack suppliers serving Dutch and Belgian logistics hubs face accelerated compliance deadlines through 2026.
United States
EPA tailpipe-emission standards and California Air Resources Board mandates accelerate fleet electrification timelines across metropolitan networks. Ride-hailing operators in dense urban clusters face zero-emission deadlines that favor subscription-based energy models. Los Angeles and New York Metro areas show concentrated pilot programs for rapid-swap commercial delivery.
India
The PLI scheme for advanced chemistry cells attracts swapping-station operators seeking localized pack supply chains. Last-mile delivery couriers drive demand for rapid-swap networks with high station density and low per-use pricing. Maharashtra and Karnataka states host pilot corridors connecting Mumbai-Pune and Bangalore-Chennai logistics routes.
South Korea
High-nickel chemistry specialists optimize rapid-swap thermal profiles for premium commercial contracts. The country's national industrial regulator coordinates with automotive OEMs on pack standardization initiatives. Seoul Capital Area operators test silicon-anode configurations to extend route range for intercity delivery services.
Electric Vehicle Battery on Demand Market Competitive Landscape
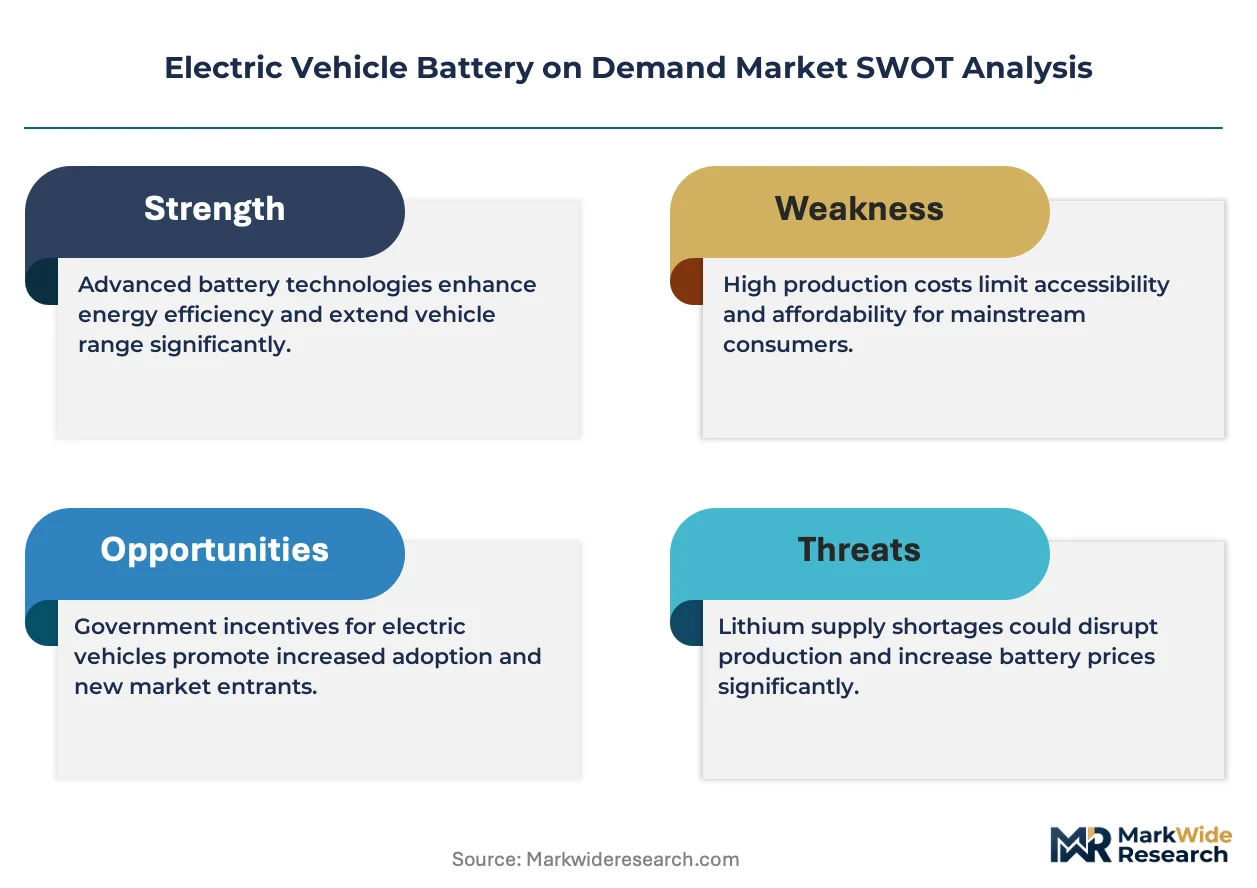
The competitive structure tilts toward cell-to-pack specialists with captive manufacturing depth. Tier-one lessors dominate station supply contracts through backward integration into cell production, while third-party service firms compete on cross-platform compatibility. Two archetypes prevail: vertically integrated battery manufacturers and independent swapping-network operators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure logistics corridor exclusivity.
Among Asia-Pacific-based manufacturers, Contemporary Amperex Technology Co., Limited and BYD Company Ltd. exemplify the integrated archetype through in-house cell production and station deployment. LG Energy Solution Ltd. occupies a position within the chemistry-specialist tier, focusing on high-nickel configurations. These three anchors illustrate how manufacturing depth and thermal-engineering capabilities determine competitive positioning in swap-infrastructure procurement.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co., Limited |
| BYD Company Ltd. |
| LG Energy Solution Ltd. |
| Panasonic Corporation |
| Samsung SDI Co., Ltd. |
| SK On Co., Ltd. |
| CATL |
| CALB |
| Tesla, Inc. |
| Others |
Supply & Pricing Matrix
Large commercial van fleet operators in Germany's Berlin-Munich corridor anchor procurement volumes and enforce per-kilometer subscription pricing that transfers degradation liability to service providers. This buyer concentration compresses leasing margins while rewarding lessors with captive cell production and standardized swap geometries.
Pricing Analysis
Margin tightening in the commercial vehicle tier reflects lithium carbonate price volatility and GB/T certification costs for pack suppliers serving Chinese logistics corridors. Three-tier pricing structure across premium uptime-guaranteed, standard fleet, and economy spot-access levels differentiates service contracts based on swap-frequency commitments and thermal-management specifications. Cost-down pressure on mid-tier offerings accelerates as ride-hailing operators in dense urban clusters index contracts to commodity benchmarks. Small e-bike couriers exhibit highest price sensitivity, while multinational logistics operators prioritize guaranteed availability over per-kilometer rates.
Supply Chain Analysis
Regional distribution centers in Shanghai, Shenzhen, and Incheon anchor hub-and-spoke patterns for swappable pack logistics. Cell production concentrates in China, South Korea, and Japan, with contemporary amperex technology and BYD anchoring domestic supply chains through backward integration into cathode materials. Raw material dependencies draw from lithium brine operations in Chile, nickel laterite in Indonesia, and cobalt concentrates from the DRC. Single-source vulnerability in high-nickel cathode precursors threatens station deployment timelines. Distribution runs through dedicated swapping-station networks with automated handling systems and fire-suppression installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state electrolyte configurations are displacing liquid-cooled lithium-ion architectures across premium commercial contracts, compressing total cost-of-ownership for high-duty-cycle fleets.
For Market Incumbents: Extend swap-station exclusivity along logistics corridors through capacity addition in Maharashtra and Karnataka states under India's PLI scheme. Deepen backward integration into silicon-anode cell production to undercut chemistry specialists on rapid-swap thermal profiles. Defend against cross-platform compatibility threats from third-party retailers by locking OEM chassis designs around proprietary pack geometries. For New Entrants and Emerging Players: Independent regional logistics operators in the Netherlands and Denmark represent underserved buyer concentration with unbundled warranty preferences and spot-market procurement flexibility. Target second-life grid storage applications for retired swap packs as a white-space revenue stream with lower capex intensity than primary cell manufacturing. Enter through digital platforms enabling commodity-indexed pricing for seasonal demand spikes. For Investors and Strategic Acquirers: The window for entry favors chemistry specialists with high-nickel rapid-swap thermal expertise and captive retrofit capabilities for Europe's F-Gas compliance deadlines. Long-term viability hinges on consolidation of fragmented third-party swapping networks into platform-scale operators with cross-border certification reciprocity. Monitor MIIT announcements on GB/T standard revisions as the inflection signal for foreign pack supplier market access.| Strategic Initiative | Industry Significance |
|---|---|
| Swap-Station Infrastructure Buildout | Automated handling systems in Berlin and Munich enable sub-five-minute exchange guarantees for commercial van operators. |
| Backward Integration into Cell Production | Captive cathode material supply insulates lessors from lithium carbonate price volatility compressing leasing margins. |
| Platform Standardization Initiative | GB/T connector certification accelerates station deployment across Chinese logistics corridors serving commercial fleets. |
| Solid-State Chemistry Licensing | Silicon-anode configurations eliminate liquid cooling loops, enabling denser station layouts and faster exchange cycles. |
| Second-Life Grid Storage Partnership | Retired swap packs generate stationary energy arbitrage revenue, improving unit economics for specialized lessors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with fleet operations directors, swapping-station infrastructure planners, cell procurement managers at logistics operators, and thermal engineering leads at pack suppliers. Bottom-up triangulation against MIIT deployment statistics, EPA tailpipe-emission compliance timelines, and F-Gas retrofit investment disclosures validated volume estimates. Top-down reconciliation with EIA energy storage projections and IEA electrification roadmaps anchored demand-side assumptions.
Data-stream reconciliation across the projection horizon modeled segmentation by battery chemistry, application intensity, distribution channel integration depth, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to station deployment trajectories and fleet conversion timelines, with silicon-anode pilot program results and solid-state thermal-profile test data informing technology-transition assumptions.
Revisions become necessary when lithium carbonate price volatility exceeds indexed contract bandwidths, GB/T certification pathways restrict foreign supplier access, or F-Gas retrofit deadlines accelerate beyond station permitting timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Automotive EV HUB Market
Electric Vehicles
Automotive Energy Harvesting and Regeneration Market
Electric Vehicles
Hybrid E-Scooter Market
Electric Vehicles
Global Electric Classic Car Market
Electric Vehicles
New Zealand E-Bike Market
Electric Vehicles
Neighbourhood Electric Vehicle Market
Electric Vehicles
Electric Vehicle (EV) Range Extender Market
Electric Vehicles
Electric Vehicle Power Control Unit Market
Electric Vehicles
Global Electric Light Commercial Vehicles Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market
Electric Vehicles
North America E-Bike Market
Electric Vehicles
Nordic E-Bike Market
Electric Vehicles
Japan Solar E-Bike Market
Electric Vehicles
RV SLI Battery Market
Electric Vehicles
ASEAN Electric Vehicle Market
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market