
 Canada Automotive Engine Oils Market | 2026-2036
Canada Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Automotive Engine Oils Market Outlook
Multi-pack bundling of synthetic and semi-synthetic grades is expanding buyer choice across Canadian retail channels. Imperial Oil Limited leverages its integrated refining network in Sarnia to sustain domestic supply security. Shell Plc anchors its position through branded service partnerships with Canadian tire and lube chains. FUCHS specializes in high-performance OEM specification oils for Detroit Three assembly plants in Ontario.
Canada automotive engine oils are formulated lubricants derived from refined petroleum or synthesized base stocks, blended with additive packages containing detergents, dispersants, anti-wear agents, and viscosity modifiers to reduce friction, dissipate heat, and prevent engine component degradation in internal combustion powertrains. Synthetic oils command premium positioning due to extended drain intervals and cold-start performance in subarctic conditions, while mineral oils retain volume leadership in older vehicle parc maintenance. API and ILSAC performance level categories structure procurement decisions for Canadian independent repair shops and fleet managers, with OEM specifications capturing margin pools in new-vehicle warranty servicing. Passenger vehicles and light trucks dominate end-user consumption patterns, though heavy-duty vehicles generate higher per-unit lubricant throughput in long-haul and resource extraction applications.
Health Canada's PMRA evaluates environmental fate of lubricant additives, while Environment and Climate Change Canada administers vehicle emissions regulations that indirectly tighten oil performance requirements through engine efficiency mandates. The Canadian General Standards Board maintains voluntary specifications that influence provincial fleet procurement and federal vehicle pool management. Stakeholders must monitor evolving API SP and ILSAC GF-6 standards alongside provincial carbon intensity programs to align product portfolios with compliance trajectories and fleet decarbonization timelines.
Market Dynamics
Environment and Climate Change Canada's tightening emissions standards are forcing fleet operators to migrate toward synthetic formulations with extended drain intervals, compressing demand for conventional mineral grades while elevating performance specifications across the entire lubricant value chain.
Growth Catalysts
- API SP and ILSAC GF-6 standards:These performance categories mandate lower viscosity, higher thermal stability oils that reduce fuel consumption. Canadian independent repair shops and fleet managers now specify these grades for warranty-compliant servicing.
- Alberta energy logistics hubs:Heavy-duty fleet density in this corridor generates concentrated demand for high-throughput synthetic products. Resource extraction and long-haul applications require lubricants with superior cold-flow properties.
- Subarctic cold-start requirements:Synthetic base stocks deliver reliable pumpability at temperatures below minus forty degrees Celsius. This technical necessity drives premium-grade adoption in northern provinces and territories.
Market Restraints
- Group III+ base oil import concentration:Domestic refining capacity for premium synthetic feedstocks remains limited. Supply security depends on pipeline and rail shipments from US Gulf Coast production centers.
- PMRA additive evaluation timelines:Health Canada's environmental fate assessments for novel friction modifiers and detergents extend commercialization cycles. Formulation innovation faces twelve-to-eighteen-month regulatory lag.
- Electric powertrain penetration:Battery electric vehicles eliminate internal combustion engine lubricant demand entirely. Fleet electrification pilots in Ontario and Quebec directly displace volume in the passenger car segment.
Strategic Opportunities
- Atlantic Canada underpenetration:Maritime provinces maintain older vehicle parc with elevated mineral oil consumption. Synthetic upgrade campaigns targeting independent service networks capture margin expansion potential.
- Carbon intensity programs:Provincial clean fuel regulations create credit value for lubricants demonstrating lifecycle emissions reductions. Low-viscosity synthetic grades qualify for preferential treatment in British Columbia and Quebec compliance frameworks.
- Telematics-enabled predictive maintenance:Connected fleet management platforms integrate oil condition monitoring. Real-time viscosity and contamination data trigger just-in-time replacement scheduling.
Industry Challenges
- OEM specification complexity:Detroit Three assembly plants in Ontario enforce proprietary factory-fill approvals. Aftermarket formulators must maintain parallel certification tracks for Ford, General Motors, and Stellantis requirements.
- Blending asset utilization:Seasonal demand swings between winter-formulation production and summer-grade campaigns strain fixed tankage capacity. Multi-product facilities face changeover downtime penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Automotive Engine Oils Market |
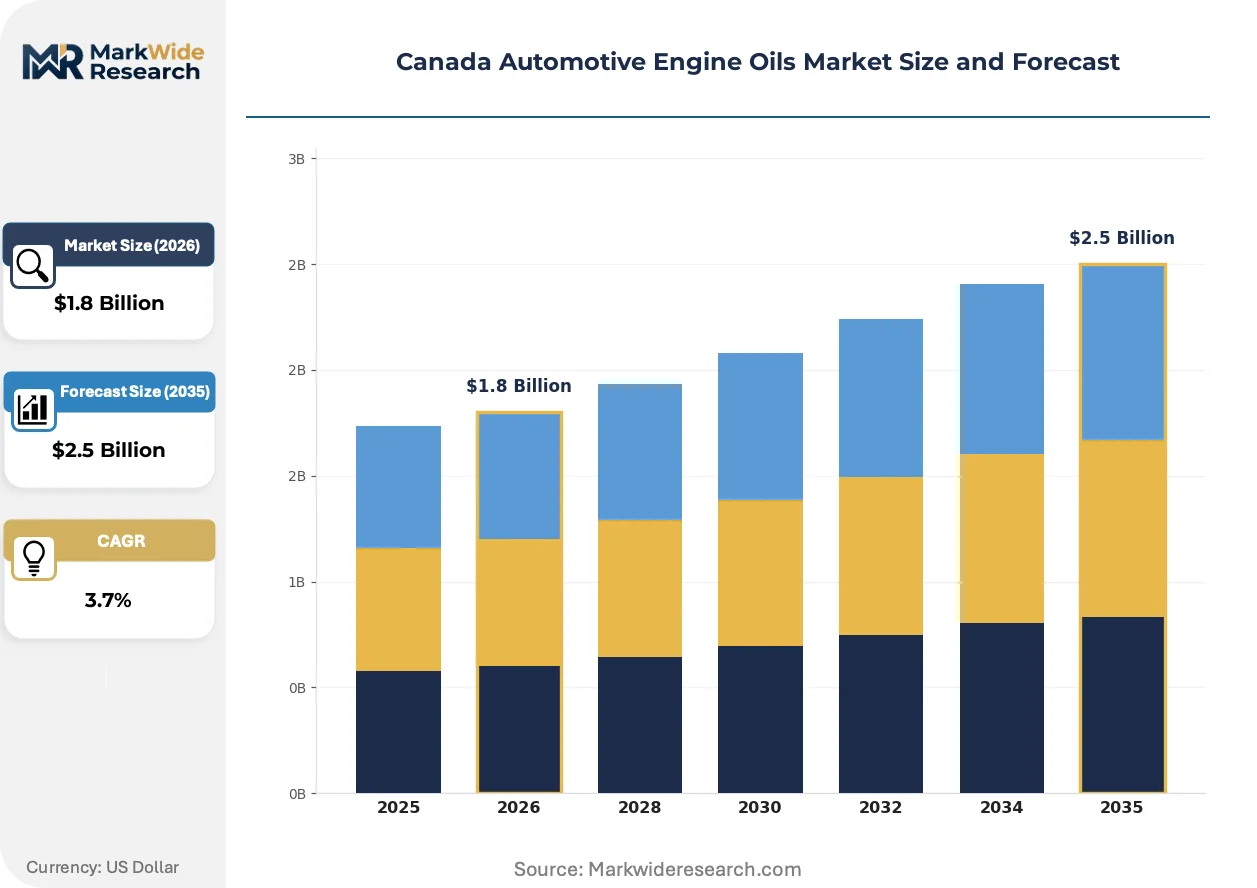
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Oils, Mineral Oils, Semi-Synthetic Oils, Bio-Based Oils End User: Passenger Vehicles, Light Trucks, Heavy-Duty Vehicles, Motorcycles Performance Level: API Standards, ILSAC Standards, ACEA Standards, OEM Specifications Distribution Channel: Online Retail, Auto Parts Stores, Supermarkets, Direct Sales |
| Companies Covered | BP p.l.c., HF Sinclair Corporation, Imperial Oil Limited, Shell Plc, ExxonMobil Corporation, Chevron Corporation, TotalEnergies, FUCHS, Phillips 66 Lubricants, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Automotive Engine Oils Market Strategic Shifts
Digital integration and regulatory compression are restructuring how lubricant value is created and captured. Formulation science, compliance architecture, and distribution economics are converging to redefine competitive advantage.
Automated oil analysis systems are automating fleet maintenance decision-making. These platforms combine particle counting, viscosity measurement, and spectroscopic elemental analysis in portable field units. Canadian trucking operators and mining contractors deploy them at depot checkpoints. The technology is automating drain interval extension approvals that previously required laboratory submission and manual review.
Environment and Climate Change Canada's Clean Fuel Regulations impose carbon intensity reduction obligations on transportation fuel suppliers. Lubricant manufacturers now document product lifecycle emissions to support downstream compliance claims. Low-viscosity synthetic grades with verified carbon footprints command preferential positioning in federal and provincial fleet procurement.
Fleet procurement consolidation is compressing supplier relationships toward direct manufacturer agreements. Large commercial operators in Ontario and Alberta bypass traditional distributor tiers. National account structures with volume commitments and technical service integration displace transactional purchasing through jobber networks.
Canada Automotive Engine Oils Market Segmentation
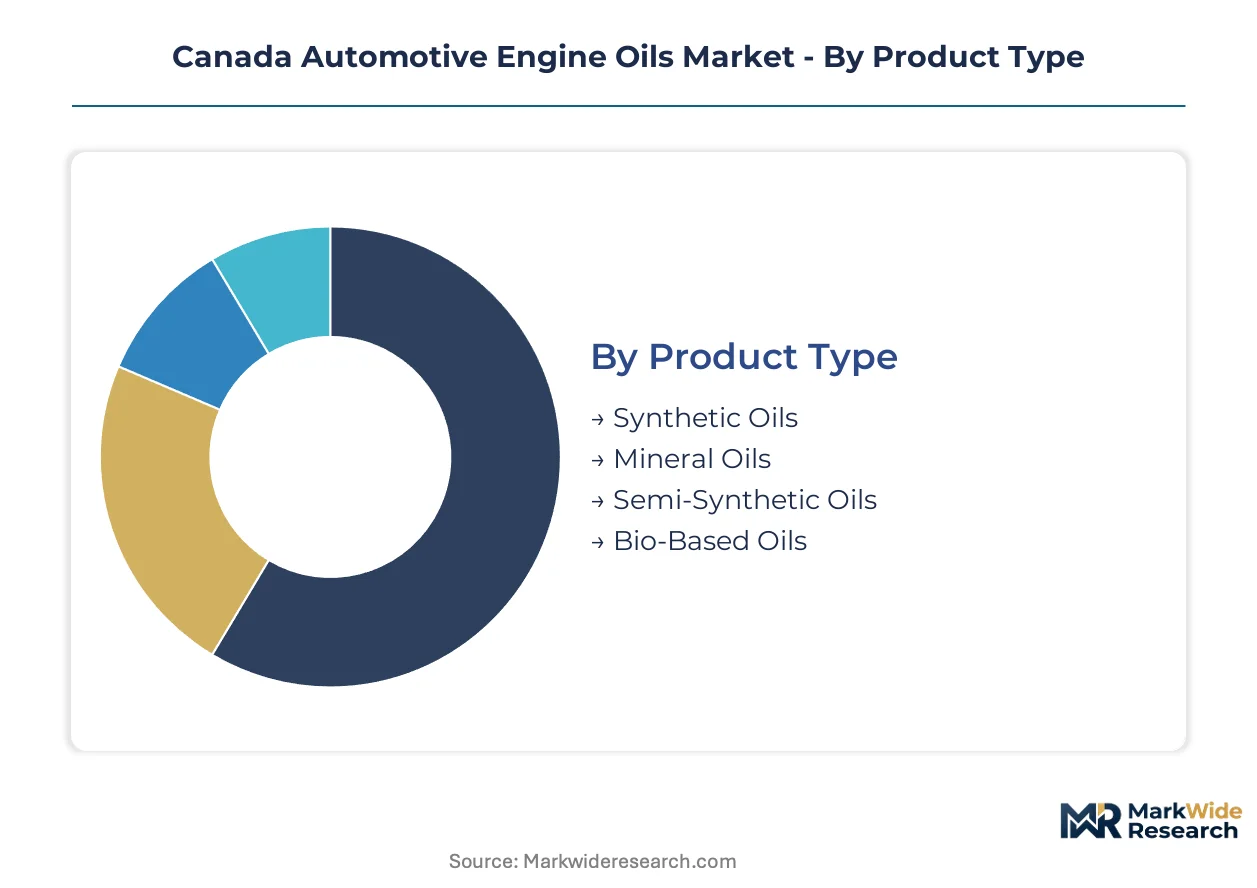
Segmentation in the Canada automotive engine oils market reflects divergent technical requirements across climate zones, vehicle ages, and fleet operator procurement sophistication. Understanding these splits enables suppliers to align formulation investments with margin concentration points and regulatory compliance trajectories.
Product Type:
Synthetic formulations capture premium positioning and extended drain economics, while mineral oils retain volume leadership in cost-sensitive maintenance segments.
- Synthetic Oils:Manufactured from chemically engineered base stocks with uniform molecular structures delivering thermal stability and cold-flow performance below minus forty degrees Celsius. Demand concentrates in Alberta's energy logistics corridors where heavy-duty fleets prioritize uptime protection and Environment and Climate Change Canada emissions compliance through reduced fuel consumption.
- Mineral Oils:Refined directly from crude petroleum with natural hydrocarbon variance limiting extreme-temperature performance. Atlantic Canada service networks and older vehicle parc owners in rural Ontario sustain volume through lower per-liter procurement costs despite shorter recommended drain intervals.
- Semi-Synthetic Oils:Blended formulations combining synthetic and mineral base stocks to balance performance upgrade with cost containment.
- Bio-Based Oils:Derived from vegetable or animal feedstocks with biodegradability advantages for sensitive watershed applications.
Mature deployment sits with mineral oils. Newer deployment is concentrated in synthetic formulations.
End User:
Vehicle duty cycles and annual mileage intensity create divergent lubricant throughput and specification requirements across customer segments.
- Heavy-Duty Vehicles:Class 8 trucks and off-highway equipment generate the highest per-unit lubricant consumption through extended operational hours and severe-service conditions. Long-haul fleets operating Ontario-Quebec corridors and resource extraction contractors in northern Alberta specify synthetic grades with OEM-approved extended drain protocols to maximize equipment availability.
- Passenger Vehicles:Light-duty automobiles represent the largest addressable unit population with lower per-vehicle consumption and price sensitivity shaping retail channel preferences.
- Light Trucks:Pickup trucks and vans serving commercial trades and personal transportation blend passenger-car specifications with intermittent towing demands.
- Motorcycles:Powersport applications require specialized formulations addressing wet clutch compatibility and high-revving engine thermal loads.
Volume concentration favors passenger vehicles. Margin expansion is climbing the fastest in heavy-duty fleet segments.
Performance Level:
Certification hierarchies structure procurement compliance and warranty protection across Canadian repair networks and fleet maintenance operations.
- API Standards:American Petroleum Institute categories including SP and CK-4 define minimum performance baselines recognized across North American service channels. Independent repair shops in Ontario's manufacturing corridor specify these grades for warranty-compliant servicing of Detroit Three vehicles.
- ILSAC Standards:International Lubricant Standardization and Approval Committee specifications including GF-6 mandate fuel economy performance through lower viscosity grades. Quebec and British Columbia fleet operators prioritize these certifications for provincial carbon intensity program compliance.
- ACEA Standards:European Automobile Manufacturers Association specifications addressing high-temperature high-shear requirements for imported vehicle servicing.
- OEM Specifications:Proprietary factory-fill approvals from Ford, General Motors, and Stellantis capturing margin pools in new-vehicle warranty maintenance.
Procurement breadth runs widest through API and ILSAC tiers. OEM specifications command tightest supplier relationships.
Distribution Channel:
Channel selection reflects purchase urgency, technical consultation requirements, and fleet procurement centralization trends.
- Auto Parts Stores:Canadian Tire and independent jobber networks dominate immediate-need retail with counter staff technical guidance. These locations capture walk-in demand from independent repair shops and DIY consumers across Ontario's urban centers and prairie agricultural communities.
- Direct Sales:National account structures with volume commitments and technical service integration serve consolidated fleet operators in Alberta energy logistics and Ontario commercial transport. Large operators bypass distributor tiers to secure manufacturer-direct pricing and predictive maintenance program integration.
- Online Retail:E-commerce platforms expanding multi-pack bundling and subscription replenishment for synthetic and semi-synthetic grades.
- Supermarkets:Mass merchandisers carrying entry-level mineral oils for emergency top-off purchases.
Transactional volume flows through auto parts retail. Strategic account development is concentrating in direct sales structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's manufacturing corridor operates as Canada's dominant automotive lubricant demand cluster, with provincial tax incentives for clean technology adoption accelerating fleet operator procurement of synthetic formulations.
Ontario
Detroit Three assembly plants in Windsor and Oshawa generate concentrated OEM specification demand for factory-fill approvals. Environment and Climate Change Canada emissions regulations tighten engine efficiency requirements, forcing fleet operators toward API SP and ILSAC GF-6 compliant grades. Toronto's commercial transport density anchors national account structures with direct manufacturer agreements displacing traditional distributor channels.
Alberta
Heavy-duty fleet density in Calgary-Edmonton energy logistics corridors drives premium synthetic throughput for long-haul and resource extraction applications. Provincial carbon intensity programs create credit value for low-viscosity lubricants demonstrating lifecycle emissions reductions. Fort McMurray mining contractors specify extended-drain synthetic protocols to maximize equipment uptime in severe-service conditions.
Quebec
Provincial clean fuel regulations under carbon intensity frameworks prioritize ILSAC GF-6 certified grades for fleet compliance. Montreal's urban density supports telematics-enabled predictive maintenance pilot programs integrating real-time oil condition monitoring. Battery electric vehicle penetration in provincial fleet electrification programs directly displaces passenger car lubricant volumes.
British Columbia
CleanBC regulations extend carbon intensity compliance obligations to transportation fuel suppliers, with lubricant manufacturers documenting product lifecycle emissions for downstream claims. Vancouver's port logistics generate concentrated demand for heavy-duty synthetic formulations serving trans-Pacific shipping corridors. Provincial fleet procurement mandates preference for verified low-carbon lubricant grades.
Atlantic Canada
Maritime provinces sustain elevated mineral oil consumption through older vehicle parc maintenance patterns and limited synthetic upgrade penetration. Health Canada's PMRA environmental fate assessments for novel additives extend commercialization timelines for formulation innovations targeting regional service networks. Halifax's marine logistics generate specialized demand distinct from automotive applications.
Canada Automotive Engine Oils Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation tiers and distribution channels. The vendor base organizes around three strategic archetypes: integrated petroleum majors with captive refining networks, independent blenders with flexible specialty portfolios, and OEM-captive lubricant divisions serving factory-fill specifications. Consolidation pressure intensifies as national account procurement centralization compresses distributor margins. Competitive moves concentrate on backward integration into base oil supply and predictive maintenance service bundling.
Among integrated petroleum majors, BP p.l.c., Shell Plc, and Imperial Oil Limited exemplify scale-driven archetypes leveraging refining assets and branded retail networks. Imperial Oil's Sarnia refining complex anchors domestic supply security for Ontario demand clusters. Shell's service partnerships with Canadian tire and lube chains sustain retail channel presence. BP's North American lubricant operations occupy positions across both passenger car and heavy-duty fleet segments.
| Leading Market Players |
|---|
| BP p.l.c. |
| HF Sinclair Corporation |
| Imperial Oil Limited |
| Shell Plc |
| ExxonMobil Corporation |
| Chevron Corporation |
| TotalEnergies |
| FUCHS |
| Phillips 66 Lubricants |
| Others |
Value Chain & Pricing Dynamics
Synthetic-mineral grade bifurcation drives divergent margin structures across Canadian lubricant channels, with API SP-certified synthetics commanding premium positioning through extended drain economics while mineral oils compete on per-liter procurement cost in Atlantic Canada service networks. This performance ladder manifests in supply chain configurations: premium synthetic feedstocks flow through direct manufacturer agreements with Alberta fleet operators, while mineral grades move via layered distributor tiers to independent jobbers in underpenetrated Maritime provinces.
Pricing Analysis
Short lead-time premiums reward just-in-time procurement from Ontario distribution hubs, compressing margins for spot inventory held in prairie bulk terminals. Three-tier pricing structure across premium synthetic, mid-grade semi-synthetic, and economy mineral levels reflects certification grade and volume scale differentiation. Cost compression in mineral tiers is intensifying because Atlantic Canada distributors compete for declining parc maintenance volume. DIY consumers in rural Ontario exhibit highest price sensitivity, while Alberta energy logistics contractors prioritize uptime protection over per-liter cost.
Supply Chain Analysis
Warehouse-distribution layers anchor on Sarnia refining complex feedstock with spoke patterns radiating to Calgary-Edmonton energy corridors and Toronto-Windsor manufacturing clusters. Geographic supply concentration draws from United States Gulf Coast Group III+ base oil production, domestic Sarnia refining capacity, and European additive package imports. Raw material dependencies rest on polyalphaolefin base stocks, detergent-dispersant additive systems, and viscosity modifier polymers. Single-source vulnerability runs through US Gulf Coast pipeline shipments subject to cross-border logistics chokepoints. Distribution runs through national account direct sales for consolidated fleets and auto parts retail networks for transactional demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canadian automotive engine oils operate as a supply-constrained market where Group III+ base oil import bottlenecks prop synthetic grade pricing power through the analysis window.
For Market Incumbents: Deploy predictive maintenance service bundling to lock in Alberta fleet operator renewal rates. Deepen backward integration into additive blending capacity at Sarnia to offset PMRA evaluation timeline delays. Electric powertrain penetration in Quebec and Ontario threatens passenger car volume displacement. For New Entrants and Emerging Players: Enter via Atlantic Canada independent service network partnerships where synthetic upgrade penetration remains lowest among Canadian regions. Target Maritime provinces mineral oil replacement cycles with semi-synthetic conversion campaigns. Pursue telematics-enabled oil condition monitoring as differentiated fleet acquisition tool. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty blender acquisition by integrated petroleum majors seeking Ontario OEM specification capabilities. Long-term viability hinges on carbon intensity credit generation under provincial clean fuel regulations. Watch battery electric vehicle fleet conversion rates in Ontario and Quebec as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Blending | Captures margin pool from imported detergent packages while compressing PMRA evaluation cycle exposure. |
| Telematics-Enabled Predictive Maintenance Launch | Integrates real-time viscosity monitoring with Alberta fleet operator equipment uptime requirements. |
| Carbon Intensity Certification Program | Qualifies low-viscosity synthetics for preferential procurement under British Columbia CleanBC regulations. |
| Atlantic Canada Service Network Expansion | Converts mineral oil maintenance parc through semi-synthetic upgrade campaigns in Maritime provinces. |
| Direct Sales National Account Structure | Bypasses distributor tiers to secure volume commitments from Ontario commercial transport consolidators. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated with primary interviews across lubricant blenders, fleet procurement managers, and aftermarket distribution channel heads. Bottom-up volume modeling drew from API certification registry analysis and provincial vehicle registration databases, cross-checked against top-down refining capacity and base oil trade flow assessments from Environment and Climate Change Canada disclosures.
Granularity-level modeling operated at product type, end user segment, performance certification tier, and provincial demand cluster dimensions across the analysis window. CAGRs derived from trend extrapolation of synthetic adoption rates, fleet electrification displacement curves, and carbon intensity program compliance trajectories. Industry-specific inputs incorporated PMRA additive approval timelines and Detroit Three OEM specification renewal cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated battery electric vehicle penetration or US Gulf Coast supply disruption scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Dual Clutch Transmission (DCT) Market
Powertrain
Drivetrain Vibration and Condition Monitoring Sensor Systems Market
Powertrain
Automotive Turbo-Compounding System Market
Powertrain
High Speed Engine Market
Powertrain
Automotive Drivetrain Market
Powertrain
Automotive Counter Shaft Market
Powertrain
Global Automotive Transmission Engineering Services Outsourcing Market
Powertrain
Automotive Intermediate Shaft Market
Powertrain
India Automotive Engine Oils Market
Powertrain
Clutch Hub Puller Market
Powertrain
Gasoline Direct Injection (GDI) System Market
Powertrain
Europe Electro Hydraulic Power Steering Market
Powertrain
Global Automotive Powertrain Systems Market
Powertrain
Brazil Automotive Market
Powertrain
Power Assisted Steering Market
Powertrain
Automotive Hydraulic Lash Adjuster Market