
 North America Automotive Battery Thermal Management System Market | 2026-2036
North America Automotive Battery Thermal Management System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Battery Thermal Management System Market Analytics
Canadian battery module producers is repositioning manufacturing lines toward thermal management subassemblies for cross-border OEM supply chains. Robert Bosch GmbH leverages its powertrain electronics heritage to anchor liquid cooling controller production in the Great Lakes region. DENSO Corporation sustains R&D intensity on refrigerant-based battery chillers through its Tennessee technical center. Hanon Systems dominates heat exchanger supply to Detroit-area EV assembly plants.
The North America Automotive Battery Thermal Management System encompasses hardware and control systems that regulate electrochemical cell temperatures within lithium-ion battery packs through active liquid circulation, passive conductive spreading, or phase-change material absorption, typically maintaining cells between 15°C and 35°C to prevent thermal runaway and preserve cycle life. Liquid Cooling leads product deployment due to its heat flux capacity in high-energy-density pouch and prismatic cell configurations. Phase Change Materials represent the fastest-growing technology segment as OEMs seek passive safety redundancy for highway-speed battery architectures. Fleet Operators concentrate aftermarket demand for retrofit thermal monitoring systems as commercial EV uptime requirements intensify.
The EPA tailpipe emissions standards and NHTSA fuel economy rules collectively mandate battery thermal performance thresholds that shape OEM procurement specifications across the United States. Health Canada and Environment and Climate Change Canada coordinate refrigerant containment standards that govern cross-border component certification for suppliers serving Ontario and Michigan assembly plants. Stakeholders must monitor pending revisions to refrigerant global warming potential limits and their cascading impact on coolant selection and system redesign cycles.
Market Dynamics
EPA tailpipe emissions rules and NHTSA fuel economy mandates are compressing OEM development cycles, forcing thermal management system suppliers to accelerate liquid-cooled pack validation while integrating passive safety redundancies into highway-speed battery architectures.
Growth Catalysts
- EPA Phase 3 Standards:Stringent tailpipe emissions thresholds compel Detroit and Windsor OEMs to procure high-performance thermal systems that preserve battery efficiency across temperature extremes.
- Great Lakes Manufacturing Cluster:Concentrated EV assembly capacity spanning Michigan and Ontario generates procurement scale for liquid-cooled battery pack suppliers.
- Refrigerant-Based Chillers:Advancements in refrigerant loop integration enable faster thermal response in high-energy-density prismatic cell configurations.
Market Restraints
- Copper and Aluminum Input Volatility:Heat exchanger and cold plate fabrication faces margin pressure from base metal price swings in commodity markets serving Tennessee and Michigan stamping operations.
- Cross-Border Certification Friction:Divergent refrigerant containment standards between EPA and Health Canada create compliance duplication for suppliers serving Ontario-Michigan assembly corridors.
- Phase Change Material Performance Limits:Passive PCM systems exhibit thermal conductivity constraints above 45°C ambient, restricting deployment in southwestern US fleet applications.
Strategic Opportunities
- Canadian Module Producer Repositioning:Ontario-based battery manufacturers are retooling lines toward thermal subassembly production for US OEM supply chains.
- Commercial Fleet Retrofit Demand:Fleet operators in California and Texas seek aftermarket thermal monitoring installations to meet uptime guarantees for electric delivery vehicles.
- Refrigerant GWP Rule Revisions:Pending EPA limits on global warming potential create redesign cycles favoring low-GWP coolant adoption in next-generation chiller architectures.
Industry Challenges
- Thermal Simulation Talent Scarcity:CFD modeling expertise for electrochemical cell behavior remains concentrated among a limited pool of specialists in Detroit and Toronto engineering centers.
- Validation Timeline Compression:Accelerated OEM platform launches compress thermal cycling test schedules, forcing suppliers to parallelize hardware and software verification.
- Legacy ICE Supplier Transition:Established powertrain electronics manufacturers face capability gaps in battery-specific thermal control algorithm development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Battery Thermal Management System Market |
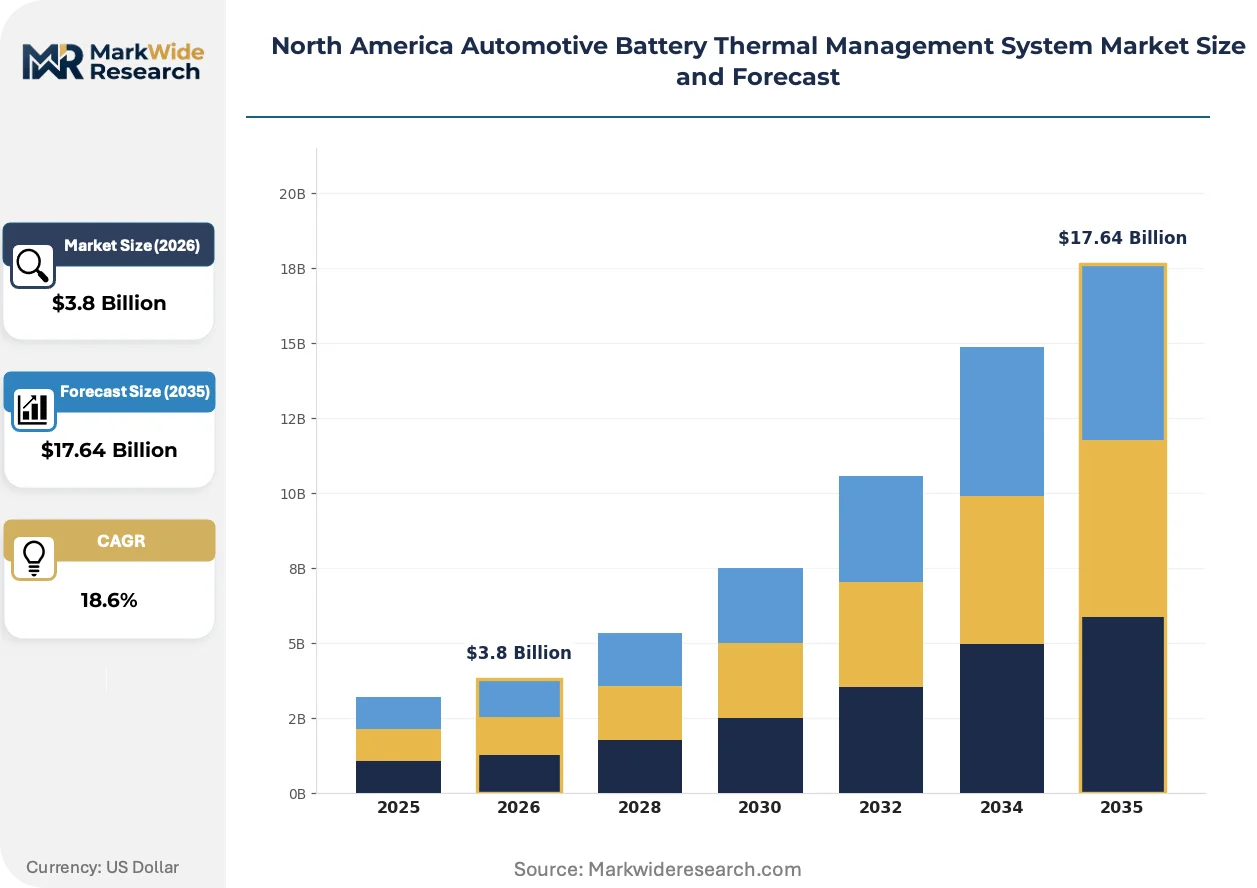
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Systems, Passive Systems, Refrigeration Systems, Heat Exchangers End User: OEMs, Aftermarket Providers, Fleet Operators, Individual Consumers Technology: Liquid Cooling, Air Cooling, Phase Change Materials, Thermal Interface Materials Application: Electric Vehicles, Hybrid Vehicles, Commercial Vehicles, Luxury Vehicles |
| Companies Covered | Robert Bosch GmbH, DENSO Corporation, Hanon Systems, Continental AG, Gentherm Incorporated, Sensata Technologies, BorgWarner Inc., Mahle GmbH, Dana Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Battery Thermal Management System Market Evolving Landscape
Active liquid circulation architectures are fragmenting into specialized subsystems as OEMs demand configurable thermal zones within single battery packs. This specialization is compressing supplier development cycles and enabling platform-scale reuse across vehicle classes.
Integrated cooling plates with embedded microchannel geometries are modularizing battery pack construction. EV OEMs in Michigan and Ontario specify these components for pouch and prismatic cell formats. The technology is modularizing pack assembly from monolithic designs toward cell-level thermal zones that simplify repair and upgrade pathways.
EPA refrigerant management rules and Health Canada coordination on cross-border containment standards are tightening certification requirements for chiller subsystem suppliers. Component manufacturers must now document leak-rate testing across wider temperature ranges. The regulatory friction most affects heat exchanger producers serving dual-jurisdiction assembly plants in the Detroit-Windsor corridor.
Fleet procurement teams are consolidating thermal system specifications into multi-year service agreements that bundle hardware, monitoring software, and predictive maintenance. This bundling displaces transactional component purchasing in commercial EV segments. The shift is most visible among last-mile delivery operators in California and Texas seeking guaranteed battery uptime contracts.
North America Automotive Battery Thermal Management System Market Segmentation
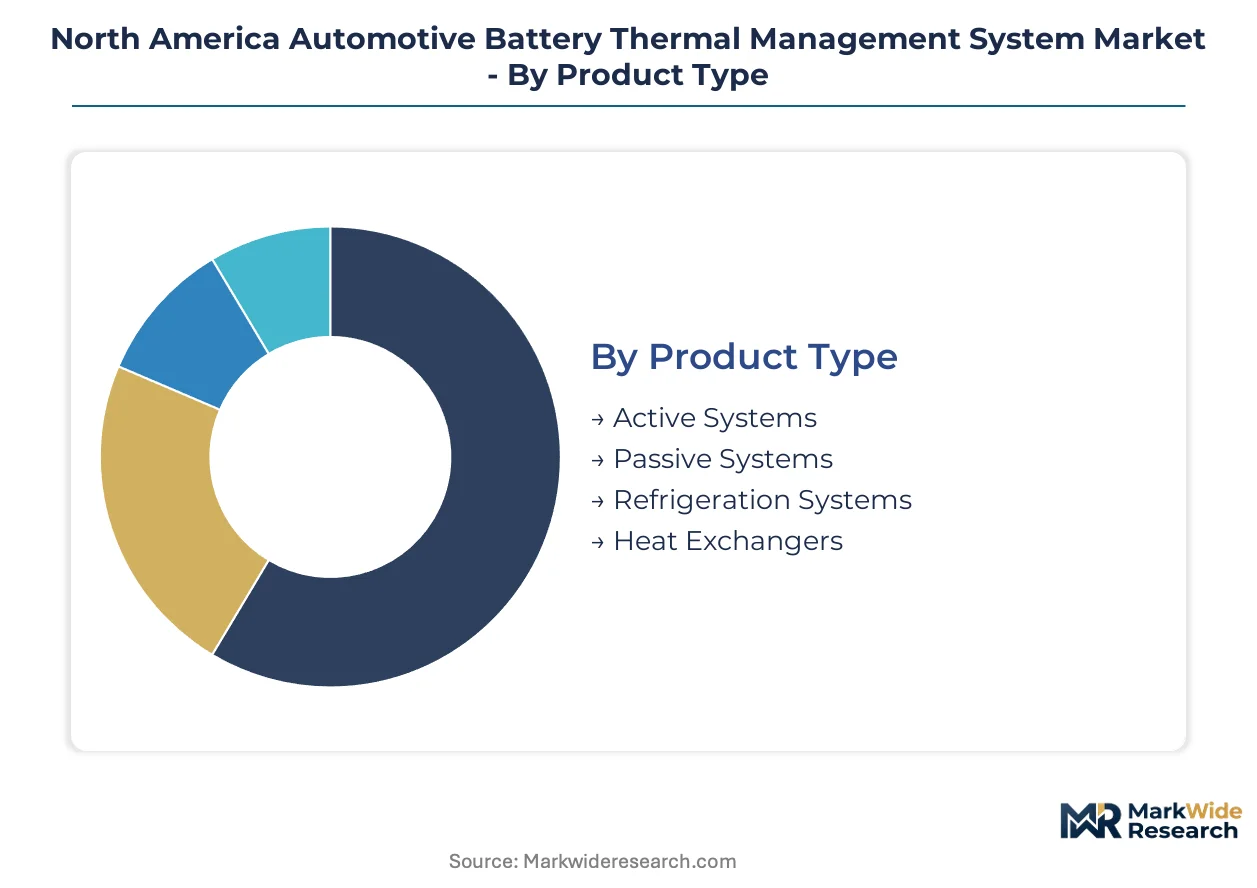
Segmentation reveals how thermal management procurement splits between integrated OEM supply chains and fragmented aftermarket channels. Understanding these divides exposes where margin pools concentrate and which technology transitions will reshape competitive positioning.
Product Type:
Replacement cycles for battery thermal hardware accelerate as EPA Phase 3 standards force OEMs toward higher-performance architectures, compressing the effective lifespan of first-generation cooling designs.
- Active Systems:These architectures deploy pumps, valves, and control electronics to circulate coolant through cold plates and jacketed battery modules. Demand clusters around Detroit and Windsor assembly corridors where liquid-cooled pack volumes for high-energy-density prismatic cells dominate procurement specifications.
- Heat Exchangers:Aluminum-brazed plate-and-fin or tube-and-fin configurations transfer thermal energy between coolant loops and ambient air or refrigerant circuits. Michigan stamping operations supply these components to Tier 1 integrators serving Ontario-Michigan EV platforms, with copper price volatility compressing fabrication margins.
- Passive Systems:Conductive spreading plates and natural convection fins eliminate pumping parasitics in cost-optimized hybrid battery packs.
- Refrigeration Systems:Vapor-compression chillers integrate with HVAC loops to achieve sub-ambient battery temperatures in fast-charging architectures.
Volume placements concentrate in Active Systems; the faster expansion belongs to Refrigeration Systems.
End User:
Cost tier stratification separates specification-intensive OEM programs from price-sensitive aftermarket retrofit opportunities.
- OEMs:Integrated vehicle manufacturers define thermal performance thresholds, validation protocols, and platform-scale procurement volumes. Their Great Lakes manufacturing footprint spans Detroit, Windsor, and Toronto assembly plants, with cross-border supply chains requiring dual EPA and Health Canada certification.
- Fleet Operators:Commercial EV deployers in California and Texas negotiate multi-year service agreements bundling hardware, monitoring software, and predictive maintenance. Their uptime guarantees for electric delivery vehicles drive aftermarket thermal monitoring installations.
- Aftermarket Providers:Independent distributors and service networks supply replacement components and retrofit kits for out-of-warranty vehicles.
- Individual Consumers:Retail purchasers acquire thermal management hardware for DIY battery projects or classic EV conversions.
Revenue concentration sits with OEMs; margin expansion is climbing the fastest among Fleet Operators.
Technology:
Application requirements dictate thermal response speed, with highway-speed battery architectures demanding active circulation while passive solutions serve auxiliary power units.
- Liquid Cooling:Ethylene glycol or dielectric fluid circulation through cold plates maintains cell temperatures within 15°C to 35°C operating windows. This technology anchors procurement from Michigan and Ontario EV OEMs scaling pouch and prismatic cell production.
- Phase Change Materials:Paraffin or salt hydrate formulations absorb latent heat at constant temperature during thermal excursions. OEMs specify these materials for passive safety redundancy in highway-speed battery architectures, though conductivity constraints above 45°C ambient limit southwestern US fleet deployment.
- Air Cooling:Forced convection through finned heat sinks serves lower-energy-density cylindrical cell configurations.
- Thermal Interface Materials:Gap pads, adhesives, and phase-change films minimize contact resistance between cells and cooling surfaces.
Platform-scale adoption concentrates in Liquid Cooling; the steepest expansion trajectory belongs to Phase Change Materials.
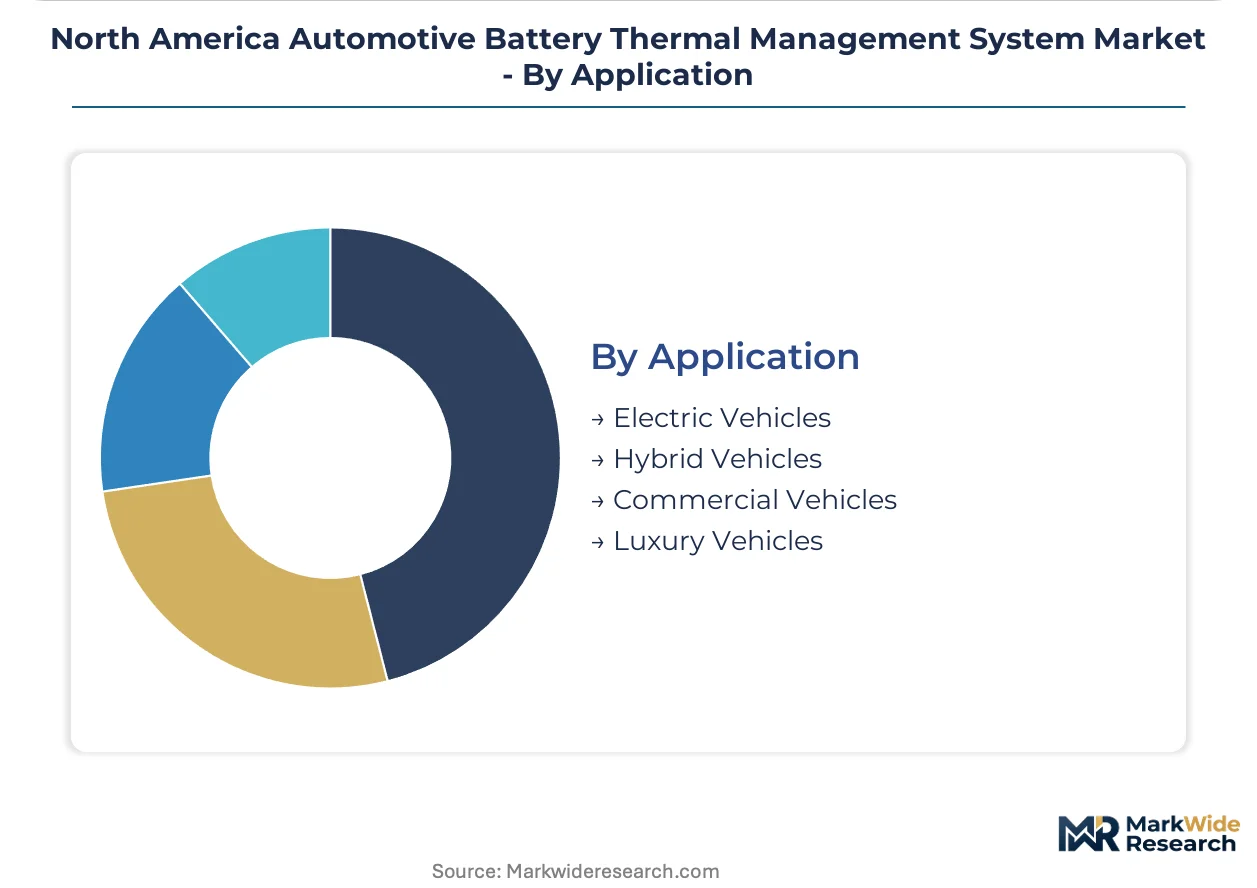
Application:
Customer maturity separates established electric vehicle platforms from emerging commercial segments still defining thermal performance specifications.
- Electric Vehicles:Battery electric platforms with 60-150 kWh capacities require sophisticated thermal management to preserve range, charging speed, and cycle life. EPA tailpipe emissions rules and NHTSA fuel economy mandates compel Detroit and Windsor OEMs to procure high-performance systems.
- Commercial Vehicles:Electric delivery vans, transit buses, and medium-duty trucks operate under severe duty cycles with frequent fast-charging events. Fleet procurement teams in California and Texas consolidate thermal specifications into multi-year service agreements with guaranteed uptime clauses.
- Hybrid Vehicles:Smaller battery packs with lower thermal loads utilize simplified air-cooled or passive architectures.
- Luxury Vehicles:Premium EV platforms prioritize cabin comfort and battery longevity through redundant thermal zones.
Procurement scale concentrates in Electric Vehicles; gaining share fastest is Commercial Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium deposits in Quebec's James Bay region and cobalt supply chains anchored in Ontario feed thermal management component fabrication across the Great Lakes manufacturing corridor.
United States
EPA Phase 3 tailpipe standards and NHTSA fuel economy mandates compel Detroit-area OEMs to procure liquid-cooled battery packs with validated thermal performance across temperature extremes. The IRA domestic content provisions accelerate qualification of US-sourced cold plates and heat exchangers for federal tax credit eligibility. Michigan's automotive engineering cluster concentrates CFD modeling talent and thermal cycling test facilities in Ann Arbor and Detroit.
Canada
Ontario-based battery module producers retool manufacturing lines toward thermal subassembly production for cross-border OEM supply chains. Health Canada coordinates refrigerant containment standards with EPA rules, creating dual certification requirements for suppliers serving Windsor-Toronto assembly plants. Quebec's critical mineral processing infrastructure supplies lithium hydroxide for thermal interface material production.
Mexico
Fast-growing EV assembly capacity in Nuevo León and the Bajío Region generates procurement pull for aluminum-brazed heat exchangers and stamped cold plates. Mexican trade integration under USMCA enables tariff-free component flow to Texas and California battery pack facilities. Monterrey's metalworking cluster supplies fabrication services to Tennessee-based thermal system integrators.
North America Automotive Battery Thermal Management System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue refrigerant-based chiller specialization and phase-change material integration. The supplier base concentrates around powertrain electronics heritage and heat exchanger fabrication capability, with cross-border certification competence separating viable contenders from regional players. Three archetypes dominate: diversified automotive Tier 1s with thermal control algorithm libraries; HVAC specialists leveraging refrigerant loop expertise; and materials-focused fabricators optimizing aluminum-copper joining for cold plate production. Competitive moves center on backward integration into coolant formulation and strategic partnerships with cell manufacturers for pack-level thermal design.
Within the diversified Tier 1 tier, Robert Bosch GmbH and DENSO Corporation anchor positions through powertrain electronics heritage and controller production scale. Hanon Systems exemplifies the HVAC-specialist archetype, occupying a position in heat exchanger supply to Detroit-area assembly plants. These three entities represent the competitive core around which smaller fabricators and regional specialists coordinate.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| DENSO Corporation |
| Hanon Systems |
| Continental AG |
| Gentherm Incorporated |
| Sensata Technologies |
| BorgWarner Inc. |
| Mahle GmbH |
| Dana Incorporated |
| Others |
Value Network & Pricing Analysis
Microchannel cold plate fabrication scaling across Michigan and Ontario stamping operations simultaneously compresses unit economics and concentrates procurement leverage among heat exchanger specialists serving Detroit-Windsor assembly corridors. This production-method transition forces tier-two fabricators into service partnerships or exit as OEMs consolidate vendor lists for platform-scale thermal subassembly supply.
Pricing Analysis
Warranty bundling now separates multi-year thermal performance guarantees from bare hardware transactions, with fleet operators in California and Texas negotiating uptime clauses that embed predictive maintenance software into per-pack pricing. Price differentiation hinges on EPA certification tier and coolant formulation grade, with low-GWP refrigerant architectures commanding premiums over legacy R-134a systems. Cost compression in aluminum-brazed heat exchangers is intensifying because copper price volatility erodes fabrication margins. Aftermarket retrofit providers exhibit highest price sensitivity; OEM direct procurement shows lowest.
Supply Chain Analysis
Reverse logistics for end-of-life battery packs creates refurbishment flows from California and Texas fleet depots back to Tennessee remanufacturing centers, recovering rare earth elements and aluminum cold plate substrates. Supply concentration rests on Mexico, Canada, and the United States, with Monterrey metalworking feeding Tennessee integrators and Ontario module producers serving cross-border OEM platforms. Raw material dependencies span lithium hydroxide from Quebec, copper cathode from Chile, and aluminum billet from domestic smelters. Single-source vulnerability in refrigerant formulation exposes chiller subsystem suppliers to EPA GWP rule revisions. Distribution runs through Tier 1 integrators to OEM assembly plants, bypassing traditional aftermarket channels for new vehicle content.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating rapidly as EPA Phase 3 validation timelines compress development cycles beyond the reach of capital-constrained regional fabricators, forcing exits and acquisition by diversified Tier 1s.
For Market Incumbents: Anchor liquid cooling controller production scale through captive supply of coolant formulation and embedded microchannel geometries, defending against HVAC specialists encroaching from refrigerant chiller adjacencies. Deepen backward integration into thermal interface material production to secure lithium hydroxide offtake from Quebec processors. Cross-border certification competence in EPA-Health Canada dual jurisdiction serves as the primary moat against emerging Mexican metalworking competitors. For New Entrants and Emerging Players: Launch via direct fleet operator service agreements bundling hardware, monitoring software, and predictive maintenance, bypassing OEM supply chain qualification barriers that favor incumbents. Target commercial vehicle retrofit installations in southwestern US states where PCM thermal conductivity constraints above 45°C ambient create openings for active liquid circulation upgrades. White-space exists in aftermarket thermal monitoring for out-of-warranty hybrid packs. For Investors and Strategic Acquirers: Re-rating potential sits with refrigerant-based chiller specialists given pending EPA global warming potential limits that force redesign cycles favoring low-GWP architectures. Long-term viability over the next decade hinges on algorithm development capability for cell-level thermal zone control and partnerships with solid-state battery manufacturers. Acquisition target archetype: mid-cap fabricators with Health Canada certification and Ontario manufacturing footprint. Monitor refrigerant rulemaking comment periods for early signals of compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEMs in Detroit and Windsor reuse thermal zone architectures across vehicle classes, reducing validation costs. |
| Battery Supply Agreement | Cell manufacturers lock in pack-level thermal design partnerships to secure platform placement. |
| Software-Defined Vehicle Investment | Predictive thermal control algorithms enable over-the-air updates for fleet uptime optimization. |
| Geographic Manufacturing Footprint | Nuevo León assembly expansion pulls aluminum heat exchanger fabrication south from Michigan. |
| Charging Infrastructure Partnership | Fast-charging network operators specify sub-ambient chiller performance for battery longevity guarantees. |
Research Methodology
Independent corroboration across OEM platform engineering directors, Tier 1 thermal system procurement leads, fleet operator maintenance chiefs, and aftermarket distributor network managers underwrites the qualitative findings. Primary fieldwork combined structured interviews with heat exchanger fabricators in Tennessee and Ontario with secondary validation from EPA rulemaking dockets, NHTSA fuel economy compliance filings, vehicle production databases, and IHS Markit registration data. Bottom-up thermal component demand estimates triangulate against top-down OEM platform production schedules.
Comparable-period anchoring to historical EPA regulatory phase transitions calibrates the forecast window against prior compliance-driven procurement surges. The analytical framework segments across propulsion architecture, vehicle class, thermal technology type, and regional production cluster throughout the projection horizon. CAGRs derive from thermal content-per-vehicle trajectories and platform launch cadences. Forecast inputs include coolant formulation adoption curves and cross-border trade flow elasticity under USMCA provisions.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery architectures with reduced thermal management intensity would alter the outlook. Forecasts reflect assumptions about EPA Phase 3 enforcement timing and Health Canada refrigerant coordination. Practitioners should monitor copper futures volatility and OEM platform delay announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
EV Condenser Market
Electric Vehicles
Electric Two-Wheeler Market
Electric Vehicles
Belgium E-Bike Market
Electric Vehicles
Electric Car Rental Market
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
Luxury Electric Vehicle Market
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
Preassembled Harness Modules for Skateboard EV Platforms Market
Electric Vehicles
North America Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Speed Reducer Market
Electric Vehicles
Vietnam Electric Vehicle Market
Electric Vehicles
North America Electric Vehicle Thermal Management System Market
Electric Vehicles
Global Electric Scooter Lift and Carrier Market
Electric Vehicles
Middle-East and Africa Electric Vehicle (EV) Fluids Market
Electric Vehicles
ASEAN EV Battery Pack Market