
 Automotive Battery Pack Compression Pad Market | 2026-2036
Automotive Battery Pack Compression Pad Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Battery Pack Compression Pad Market Insights
The gap between aerospace-grade silicone and commodity polyurethane foam is rebalancing as cell-to-pack designs demand uniform pressure distribution at lower cost-per-kWh. Rogers Corporation leverages its BISCO silicone portfolio to anchor premium thermal management contracts with European battery manufacturers. Saint-Gobain competes through vertically integrated ceramic coating capabilities that extend fire-retardant performance thresholds. Avery Dennison specializes in adhesive-backed compression laminates that simplify module assembly for tier-1 suppliers.
Automotive battery pack compression pads are engineered elastomeric or foam components, typically 2–10 mm thick with compression set resistance below 15%, designed to maintain consistent mechanical pressure on pouch or prismatic cells across temperature cycles and vibration loads. Their primary purpose is preventing cell delamination, managing thermal expansion, and containing thermal runaway propagation within sealed pack enclosures. Silicone rubber dominates where electrical isolation and fire retardancy command priority, while polyurethane foam occupies cost-sensitive hybrid vehicle applications where vibration damping suffices. The technology segment around thermal insulation is maturing fastest as OEMs consolidate suppliers capable of multi-functional pads combining shock absorption with electrical isolation.
The EU Battery Regulation, China's GB/T standards administered by SAMR, and NHTSA guidance on electric vehicle safety collectively mandate compression materials that withstand 800°C flame exposure and maintain dielectric strength above 500 V/mil. These frameworks force material suppliers to certify batch consistency and trace raw material origins, raising barriers for uncertified entrants. Stakeholders must monitor how solid-state battery architectures with rigid cell formats alter compression pad specifications and whether in-situ pressure sensing integration becomes a procurement requirement.
Market Dynamics
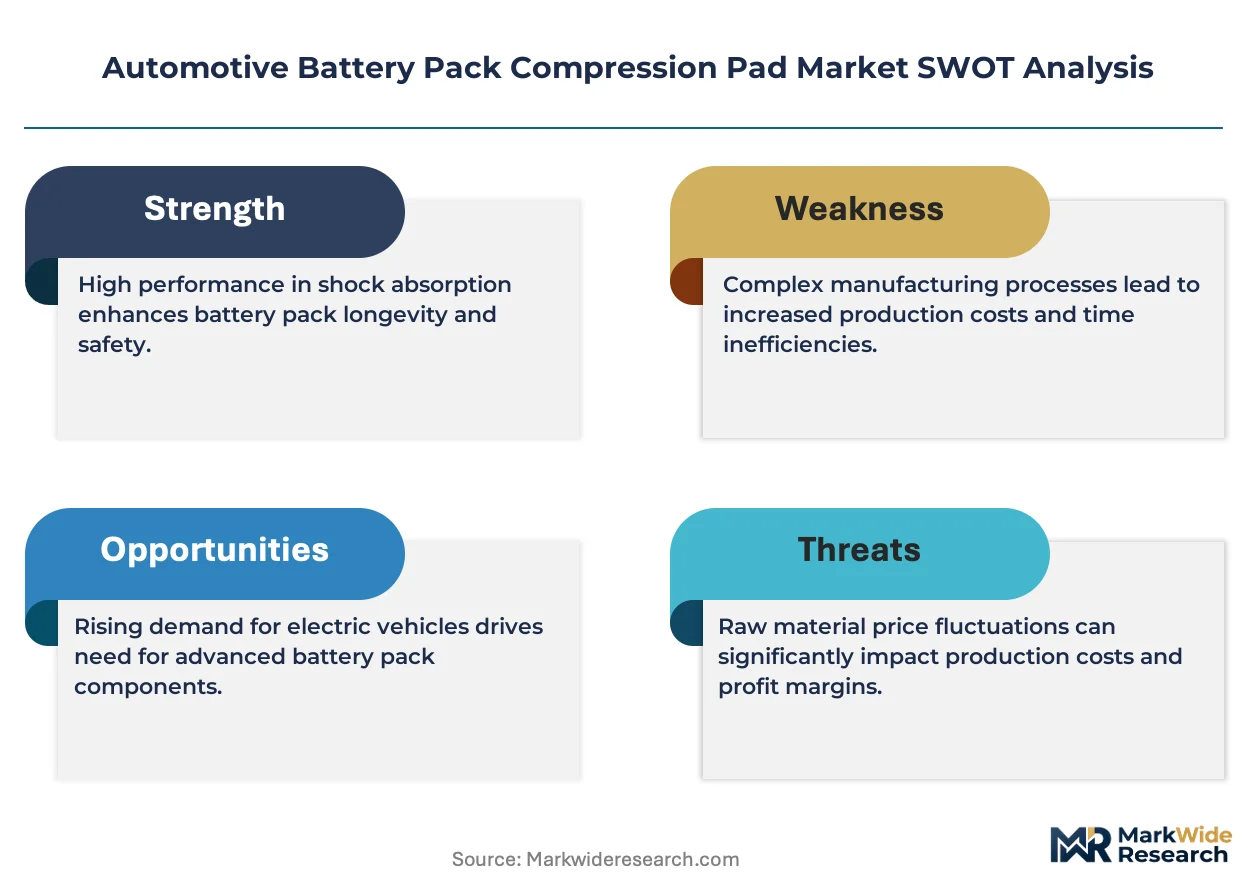
Cell-to-pack architecture migration is compressing module-level component counts while demanding multi-functional compression materials that simultaneously manage thermal runaway, electrical isolation, and mechanical stress across wider temperature ranges than legacy module designs required.
Growth Catalysts
- EU Battery Regulation thermal containment mandates:The regulation's 800°C flame exposure requirements are disqualifying commodity foam suppliers and accelerating silicone rubber qualification cycles at European gigafactories.
- China's GB/T standards administered by SAMR:These standards mandate dielectric strength thresholds above 500 V/mil, forcing material traceability systems that favor certified batch producers over uncertified entrants.
- Silicone rubber formulation advances:Next-generation ceramic-filled silicones achieve UL 94 V-0 ratings at lower density, opening cost-competitive positioning against polyurethane in hybrid vehicle segments previously closed to premium materials.
Market Restraints
- Raw material concentration in Asian silicone supply:Precipitated silica and platinum catalyst supply chains concentrate in China and South Korea, exposing European and North American pad fabricators to input volatility and tariff exposure.
- Cell-to-pack integration timeline compression:OEM platform consolidation from 12-18 month to 6-9 month qualification windows prevents iterative material optimization and locks in suboptimal compression set specifications.
- Solid-state battery rigidity:Ceramic and sulfide electrolyte cells exhibit minimal dimensional swelling under charge cycling, threatening compression pad volume assumptions built on liquid electrolyte pouch cell expansion coefficients.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cell manufacturing:Subsidy thresholds favoring local content creation open first-mover positioning for compression pad suppliers establishing bonded warehousing near Tamil Nadu and Gujarat cell plants.
- In-situ pressure sensor integration:Embedding fiber optic or piezoelectric sensing layers within pad laminates creates recurring revenue streams through predictive maintenance contracts with fleet operators.
- Recyclable thermoplastic elastomer formulations:TPE pads compatible with pack disassembly and material recovery align with EU Battery Regulation end-of-life recycling targets and circular economy procurement scoring.
Industry Challenges
- Multi-physics simulation talent scarcity:Coupled thermal-mechanical-electrochemical modeling for compression pad specification requires expertise spanning finite element analysis, battery electrochemistry, and fire dynamics that concentrates at Tier-1 suppliers and specialized consultancies.
- Batch-to-batch certification latency:SAMR and NHTSA traceability requirements demand 90-120 day validation cycles for each silicone compound variation, compressing R&D iteration rates and freezing formulation pipelines during regulatory review.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Battery Pack Compression Pad Market |
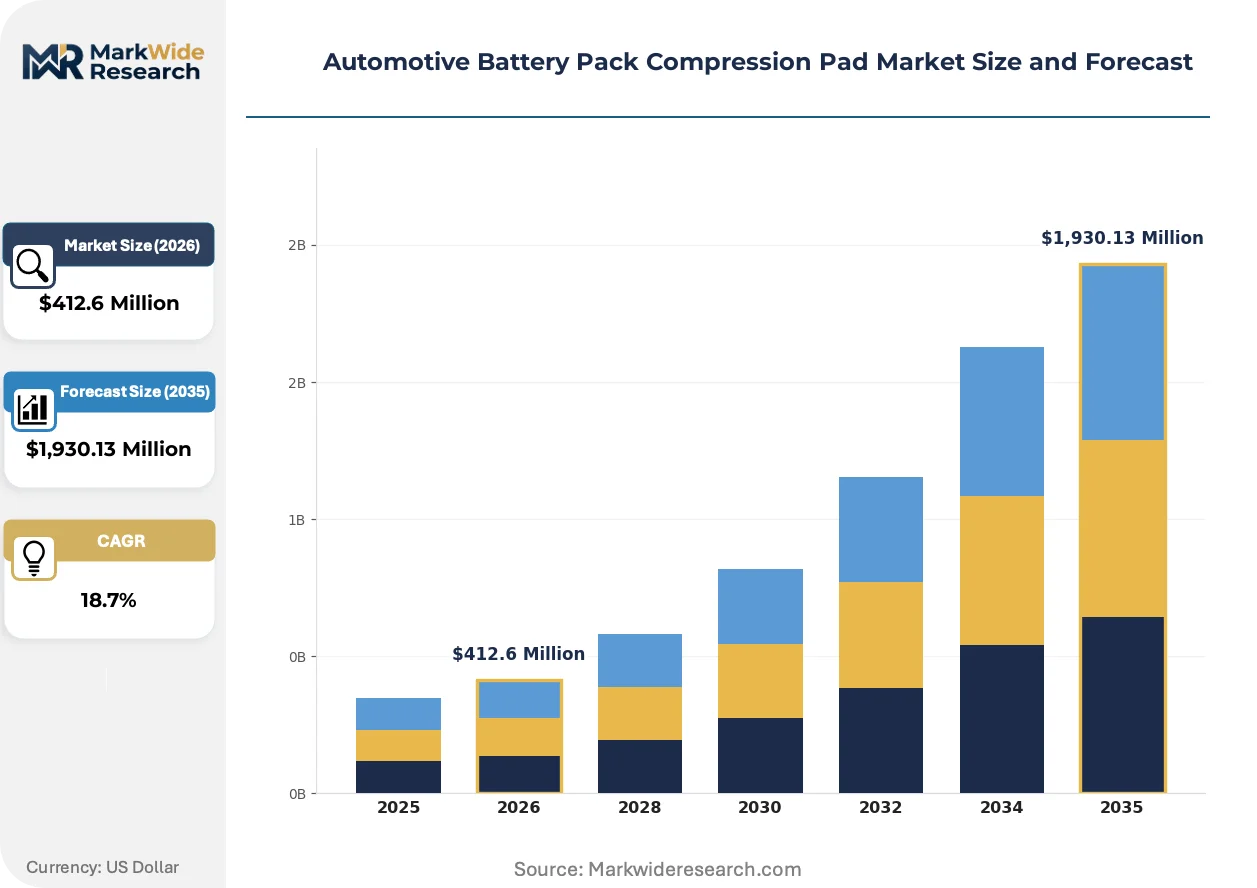
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,930.13 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyurethane Foam, Silicone Rubber, Neoprene, EPDM, EVA Foam Application: Electric Vehicles, Hybrid Electric Vehicles, E-Bikes, Commercial Electric Vehicles, Utility Vehicles End User: OEMs, Tier-1 Suppliers, Battery Manufacturers, Aftermarket Providers Technology: Thermal Insulation, Vibration Damping, Shock Absorption, Electrical Isolation, Fire Retardancy |
| Companies Covered | Rogers Corporation, Saint-Gobain, Avery Dennison, JBC Technologies, Elmelin, Marian, 3M, Henkel, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Battery Pack Compression Pad Market Trends and Innovations
Material science convergence with embedded sensing capabilities is redefining compression pad value propositions from passive mechanical components to active pack health monitoring interfaces.
Ceramic-coated silicone laminates are electrifying thermal management architecture by consolidating previously separate fire barriers, compression layers, and electrical isolators into single-substrate solutions. European OEMs adopting cell-to-pack designs specify these materials at 3-4x the rate of conventional foam-silicone hybrids. This consolidation is electrifying supplier selection criteria toward multi-functional certification capability and away from single-property specialists.
REACH Annex XVII restrictions on halogenated flame retardants are accelerating phosphorus-nitrogen intumescent coating development for polyurethane foams previously dependent on brominated additives. Industrial consequence includes reformulation costs exceeding EUR 2 million per certified product line for mid-cap European foam converters. Pouch cell applications in German premium EV platforms are most affected, with OEMs now requiring third-party REACH compliance attestation as a purchase order precondition.
Buyer consolidation around vertically integrated cell manufacturers is compressing tier-2 and tier-3 component supplier margins. CATL and BYD internal sourcing groups now specify compression pads directly, bypassing traditional module integrators who previously aggregated material procurement. This disintermediation is most visible in Chinese domestic market supply chains, where in-house material development teams at cell producers absorb functions historically outsourced to specialized elastomer fabricators.
Automotive Battery Pack Compression Pad Market Segmentation
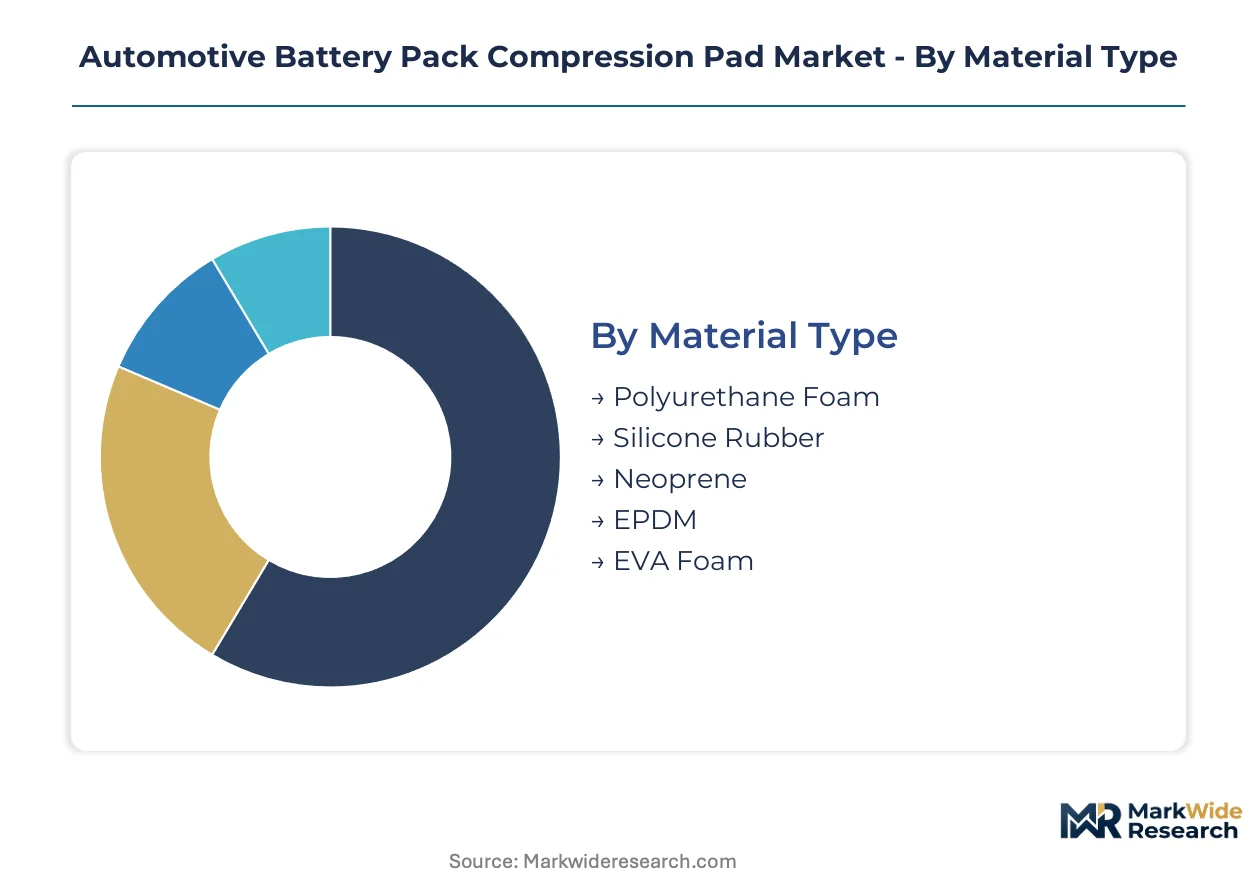
Compression pad specifications diverge sharply based on whether they serve as standalone mechanical components or integrated multi-functional layers within cell-to-pack architectures. Material selection and technology integration depth directly determine qualification pathways and procurement economics across vehicle electrification platforms.
Material Type:
Integration depth varies dramatically across material chemistries, with ceramic-filled formulations embedding directly into thermal management subsystems while commodity foams remain standalone mechanical inserts.
- Silicone Rubber:Ceramic-filled formulations achieve UL 94 V-0 fire ratings at densities below 1.2 g/cm³, enabling direct lamination to cell surfaces as combined compression and thermal barrier layers. European OEM procurement of these integrated pads concentrates at gigafactories in Germany and Hungary where SAMR-equivalent traceability systems are being implemented preemptively ahead of EU Battery Regulation enforcement.
- Polyurethane Foam:Open-cell structures with compression set resistance of 8-12% dominate cost-sensitive hybrid applications where vibration damping operates independently of thermal management functions. Demand clusters in Japanese and South Korean hybrid platforms where module-level assembly persists and cell-to-pack migration lags pure-electric architectures.
- Neoprene:Chloroprene-based pads with oil resistance specifications serve commercial vehicle battery packs exposed to underhood fluid contamination.
- EPDM:Ethylene-propylene-diene monomer formulations offer ozone stability for outdoor utility vehicle applications in extreme climate exposure.
- EVA Foam:Ethylene-vinyl acetate closed-cell structures provide lightweight compression in low-voltage e-bike battery enclosures where thermal runaway containment requirements remain minimal.
Silicone rubber leads volumes today; polyurethane foam is gaining share fastest in hybrid vehicle cost optimization programs.
Application:
Vehicle electrification intensity dictates pad complexity tiers, with high-voltage platforms demanding multi-functional integration absent from low-power mobility segments.
- Electric Vehicles:Cell-to-pack architectures specify 4-6 mm multi-layer laminates combining compression, electrical isolation, and fire retardancy in single substrates. German and Chinese OEM procurement teams now require batch-level material traceability from pad suppliers as a contract precondition, reflecting EU Battery Regulation and SAMR GB/T standard convergence on documentation rigor.
- Commercial Electric Vehicles:Heavy-duty cycle durability demands compression set specifications below 10% after 10,000 mechanical cycles, with pad geometries customized to prismatic cell formats dominant in bus and truck platforms. North American fleet operators are specifying predictive maintenance integration through embedded pressure sensing layers, creating technology pull distinct from passenger car procurement patterns.
- Hybrid Electric Vehicles:Lower thermal management intensity permits simpler foam-based pads serving purely mechanical retention functions.
- E-Bikes:Cylindrical cell formats and minimal safety regulation sustain commodity EVA and polyurethane pad demand.
- Utility Vehicles:Off-road vibration exposure prioritizes shock absorption over thermal management in agricultural and construction equipment electrification.
Electric vehicles anchor current procurement volumes; commercial electric vehicles exhibit the steepest expansion trajectory as fleet electrification accelerates.
End User:
Procurement authority concentration is restructuring supplier relationships, with backward integration by cell manufacturers displacing traditional tiered supply arrangements.
- Battery Manufacturers:CATL, BYD, and LG Energy Solution internal sourcing groups now specify compression pad materials directly, bypassing module integrators who previously aggregated component procurement. This disintermediation compresses margin pools for standalone pad fabricators while rewarding suppliers with in-house formulation and certification capabilities.
- OEMs:Premium European and North American vehicle manufacturers retain direct material qualification authority for platforms where cell-to-pack integration demands close coordination between pad specifications and pack thermal architecture.
- Tier-1 Suppliers:Module integrators face margin compression as procurement authority shifts upstream to cell producers and downstream to OEM platform teams.
- Aftermarket Providers:Replacement pad demand remains minimal given pack sealed-life designs, though fleet maintenance contracts are emerging for pressure-sensing pad retrofits.
Battery manufacturers lead procurement volumes today; OEM direct sourcing is gaining share fastest as platform integration complexity increases.
Technology:
Functional consolidation is collapsing previously separate technology categories into unified material specifications, with multi-functional pads displacing single-property alternatives.
- Thermal Insulation:Ceramic-coated silicone laminates now consolidate fire barrier, compression, and electrical isolation functions previously requiring three discrete material layers. European cell-to-pack adoption specifies these integrated solutions at rates substantially exceeding conventional foam-silicone hybrid configurations.
- Fire Retardancy:Intumescent phosphorus-nitrogen coatings are displacing halogenated additives in polyurethane formulations as REACH Annex XVII restrictions tighten, with reformulation costs restructuring competitive positioning among mid-cap European foam converters.
- Vibration Damping:Standalone mechanical isolation functions persist in hybrid vehicle modules where thermal management intensity remains low.
- Shock Absorption:Crash-load distribution specifications are integrating with compression set requirements in new pad design protocols.
- Electrical Isolation:Dielectric strength above 500 V/mil is becoming a baseline specification across all pad categories rather than a premium feature.
Thermal insulation leads technology volumes today; fire retardancy is climbing the fastest as regulatory flame exposure thresholds tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Materials scientists and thermal engineers cluster around gigafactory construction sites in Germany, China, and the United States where cell-to-pack adoption drives compression pad specification complexity.
Germany
BMW and Volkswagen platform teams source multi-functional silicone laminates for cell-to-pack architectures at their Leipzig and Zwickau plants. The EU Battery Regulation's 800°C flame exposure mandates disqualify uncertified foam suppliers from European OEM procurement lists. Bavarian material labs near Munich coordinate REACH Annex XVII compliance documentation for ceramic-filled silicone formulations.
China
CATL and BYD internal sourcing groups specify compression pad materials directly, bypassing traditional module integrators who previously aggregated component procurement. SAMR-administered GB/T standards mandate dielectric strength above 500 V/mil and 90-120 day batch validation cycles. Gigafactory construction concentrates in Ningde and Shenzhen where in-house material development teams absorb functions historically outsourced to specialized elastomer fabricators.
United States
North American fleet operators specify predictive maintenance integration through embedded pressure sensing layers in commercial vehicle platforms. NHTSA guidance on electric vehicle safety requires compression materials that maintain dielectric strength above 500 V/mil. Michigan-based battery engineering clusters near Detroit coordinate thermal runaway containment specifications with Tier-1 pack integrators supplying GM and Ford platforms.
South Korea
LG Energy Solution and Samsung SDI procurement teams drive ceramic-coated silicone qualification for prismatic cell formats dominant in premium EV exports. Precipitated silica and platinum catalyst supply chains concentrate near Seoul and Ulsan, exposing pad fabricators to input volatility. Busan-region material converters face margin compression as cell manufacturers consolidate direct material specification authority.
India
Tata Motors and Ola Electric platform development creates first-mover positioning for compression pad suppliers establishing bonded warehousing near Tamil Nadu and Gujarat cell plants. The PLI scheme for advanced chemistry cell manufacturing favors local content creation above subsidy thresholds. Chennai-based engineering teams coordinate with European OEMs to implement SAMR-equivalent traceability systems preemptively.
Automotive Battery Pack Compression Pad Market Competitive Landscape
Top-tier vendors anchor premium thermal management contracts, while mid-cap foam converters face margin compression from regulatory reformulation costs. The vendor base stratifies across three tiers: multinational material conglomerates with vertically integrated certification capabilities, regional specialists in adhesive-backed laminates, and commodity foam fabricators losing share to silicone substitution. Two strategic archetypes dominate: formulation innovators consolidating fire barrier and compression functions into single substrates, and assembly simplification specialists reducing module integration labor. Capacity expansion near gigafactory clusters and strategic partnerships for in-situ sensing integration represent the dominant competitive moves.
Within the multinational material conglomerate tier, Rogers Corporation, Saint-Gobain, and Avery Dennison occupy positions exemplifying divergent specialization vectors. Rogers Corporation represents the ceramic-filled silicone formulation archetype with premium thermal management positioning. Saint-Gobain exemplifies vertically integrated fire-retardant coating capabilities extending performance thresholds. Avery Dennison anchors the adhesive-backed laminate simplification vector for tier-1 module assembly reduction. These three firms collectively illustrate how certification depth and multi-functional integration capability determine supplier selection in cell-to-pack procurement.
| Leading Market Players |
|---|
| Rogers Corporation |
| Saint-Gobain |
| Avery Dennison |
| JBC Technologies |
| Elmelin |
| Marian |
| 3M |
| Henkel |
| DuPont |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed cell manufacturers in China and state-supported gigafactory consortia in Germany exercise asymmetric pricing power over compression pad suppliers, compressing margins for uncertified foam converters while rewarding ceramic-filled silicone specialists with multi-year offtake premiums tied to EU Battery Regulation compliance.
Pricing Analysis
Bundled certification-and-material contracts dominate European procurement, while unbundled commodity foam transactions persist in hybrid vehicle segments. Three-tier pricing structure across premium silicone laminates, standard polyurethane foams, and economy EVA pads reflects dielectric strength certification tiers under SAMR GB/T standards. Cost compression in polyurethane foam runs through REACH Annex XVII reformulation expenses exceeding two million euros per product line. Tier-1 module integrators exhibit highest price sensitivity as cell manufacturers disintermediate their procurement role.
Supply Chain Analysis
Dual-sourcing mandates from CATL and BYD procurement teams require pad suppliers to maintain qualified secondary production lines, fragmenting volume concentration across fabricators. Precipitated silica and platinum catalyst supply chains center on China and South Korea, exposing European and North American converters to tariff volatility. Raw material dependencies include ceramic fillers, silicone elastomers, and intumescent coatings. Single-source vulnerability concentrates in Asian catalyst supply. Distribution runs through bonded warehousing near Ningde, Leipzig, and Detroit gigafactory clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate among ceramic-filled silicone formulators as cell-to-pack architectures displace commodity foam volumes, with cost-down drivers emerging from batch-level traceability automation reducing SAMR validation overhead.
For Market Incumbents: Extend ceramic-filled silicone formulation capabilities into predictive maintenance-integrated pads embedding fiber optic sensing layers. Consolidate fire barrier and compression functions to defend against emerging thermoplastic elastomer recyclability positioning. Prioritize bonded warehousing capacity near Tamil Nadu and Gujarat to capture India's PLI scheme local content thresholds. For New Entrants and Emerging Players: A forty-percent price-point gap between UL 94 V-0 certified silicone laminates and uncertified polyurethane foams creates entry space for phosphorus-nitrogen intumescent coated foams achieving REACH compliance. Target Indian commercial electric vehicle fleet operators specifying pressure-sensing retrofits. Pursue qualification partnerships with European material labs near Munich to accelerate EU Battery Regulation certification. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap European foam converters facing REACH reformulation cost burdens without vertically integrated coating capabilities. Five-to-ten year viability favors suppliers with in-house ceramic formulation and multi-functional pad certification. Watch for solid-state battery platform announcements eliminating compression set specifications as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-Filled Silicone Capacity Expansion | Captures EU Battery Regulation thermal containment mandates at German gigafactories. |
| In-Situ Pressure Sensor Integration | Creates recurring revenue streams through predictive maintenance contracts with North American fleet operators. |
| REACH-Compliant Intumescent Coating Development | Preserves polyurethane foam positioning as halogenated flame retardants face Annex XVII restrictions. |
| Bonded Warehousing Near Indian Cell Plants | Secures PLI scheme subsidy eligibility for local content creation in Tamil Nadu and Gujarat. |
| Recyclable Thermoplastic Elastomer Formulation | Aligns with EU Battery Regulation end-of-life targets and circular economy procurement scoring. |
Research Methodology
Multiple input streams — primary interviews with OEM platform engineers, Tier-1 procurement leads, and ceramic formulation specialists; secondary validation through SAMR GB/T documentation, EU Battery Regulation draft texts, and SEC filings from listed material suppliers; plus customs data on silicone elastomer trade flows — were reconciled through bottom-up and top-down triangulation to derive segment-level volume and value estimates.
Data-stream reconciliation applied across vehicle propulsion architecture, material chemistry tier, and regional regulatory cluster dimensions to model compression pad content per battery pack over the projection horizon. CAGRs were derived from production ramp schedules at named gigafactories and cell-to-pack adoption curves by OEM platform. Forecast inputs included thermal runaway containment specification evolution and solid-state battery commercialization timelines.
Caveats apply where solid-state battery platform shifts or SAMR certification timeline acceleration could materially shift the outlook. Deviation in ceramic filler supply chain concentration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Europe Electric Scooter Market
Electric Vehicles
Asia Pacific Automotive High Performance Electric Vehicles Market
Electric Vehicles
Oman EV Market
Electric Vehicles
Electric Vehicle Air Conditioning Market
Electric Vehicles
Africa Electric Vehicle Market
Electric Vehicles
China Electric Truck Market
Electric Vehicles
Middle-East and Africa E-Bike Market
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market
Electric Vehicles
Electric Vehicle Communication Controller Market
Electric Vehicles
Asia Pacific Hybrid Electric Vehicle Battery Market
Electric Vehicles
Global Electric Light Commercial Vehicles Market
Electric Vehicles
Asia-Pacific Electric Vehicle (EV) Fluids Market
Electric Vehicles
Electric Vehicle Battery on Demand Market
Electric Vehicles
Latin America E-Bike Market
Electric Vehicles
Global Electric Classic Car Market
Electric Vehicles
Electric Three Wheeler Market