
 Reusable Laparoscopic Instrument Market | 2026-2036
Reusable Laparoscopic Instrument Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Laparoscopic Instrument Market Insights
Hospital procurement consolidation is recalibrating how reusable laparoscopic instrument vendors structure contracts and service agreements. Ethicon leverages its end-to-end sterilization assurance programs to anchor long-term supply relationships with integrated delivery networks. Karl Storz competes through specialized rigid endoscope manufacturing that sustains premium positioning in academic medical centers.
Reusable laparoscopic instruments comprise precision-engineered graspers, scissors, needle holders, and dilators manufactured primarily from surgical-grade stainless steel or titanium alloys, designed for repeated sterilization cycles via autoclave or hydrogen peroxide plasma systems while maintaining tactile feedback and jaw alignment critical for minimally invasive tissue manipulation. Scissors and graspers fabricated from titanium alloys command margin premiums due to superior strength-to-weight ratios and corrosion resistance under repeated thermal cycling. General surgery applications dominate volume throughput, though bariatric procedures represent the fastest-growing application segment as sleeve gastrectomy and gastric bypass volumes expand across hospital and ambulatory surgical center settings.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape sterilization validation protocols and biocompatibility testing burdens for reusable instrument manufacturers seeking market access. ISO 13485 quality management systems and IEC 62304 software lifecycle standards govern design controls for electrosurgical-enabled laparoscopic devices with integrated energy delivery. Stakeholders must monitor evolving FDA guidance on reprocessing validation as healthcare systems weigh total cost-of-ownership against single-use alternatives in capital-constrained environments.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while extending contract durations, forcing reusable instrument manufacturers to embed sterilization validation and repair services into multi-year supply agreements rather than compete on unit pricing alone.
Growth Catalysts
- EU MDR sterilization validation extensions:The regulation's phased compliance timeline grants manufacturers additional runway to complete biocompatibility documentation, reducing market access barriers for titanium-alloy instrument portfolios.
- Bariatric procedure volume expansion:Sleeve gastrectomy and gastric bypass operations in ambulatory surgical centers are generating incremental demand for precision graspers and needle holders with enhanced tactile feedback.
- Titanium alloy adoption:Germany's precision manufacturing corridor is scaling production of corrosion-resistant scissors and graspers that withstand repeated autoclave cycling without jaw misalignment.
Market Restraints
- Input cost volatility:Surgical-grade stainless steel and titanium alloy prices fluctuate with energy-intensive smelting operations, compressing margin predictability for mid-tier manufacturers.
- Single-use instrument substitution:Polymer-based disposable laparoscopic tools are capturing cases in capital-constrained health systems where sterilization infrastructure investment is deferred.
- Supply concentration risk:Precision forging and CNC machining capacity for complex jaw mechanisms clusters in southwestern Germany and northern Italy, creating geographic vulnerability to regional disruptions.
Strategic Opportunities
- Electrosurgical integration:Convergence of monopolar energy delivery with reusable graspers enables premium positioning in general surgery suites seeking reduced instrument exchange frequency.
- Refurbishment service models:Third-party reconditioning channels are emerging as viable alternatives to OEM replacement cycles, particularly for academic medical centers with captive sterilization departments.
- ISO 13485 certification arbitrage:Manufacturers achieving quality management accreditation ahead of EU MDR full enforcement capture procurement preference from integrated delivery networks consolidating supplier bases.
Industry Challenges
- Sterilization validation backlog:FDA 510(k) reprocessing documentation requirements are extending clearance timelines for instruments with complex luminal geometries, delaying revenue recognition.
- Repair technician scarcity:Specialized skills for jaw alignment restoration and insulation testing are concentrated among aging workforce cohorts in instrument manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Laparoscopic Instrument Market |
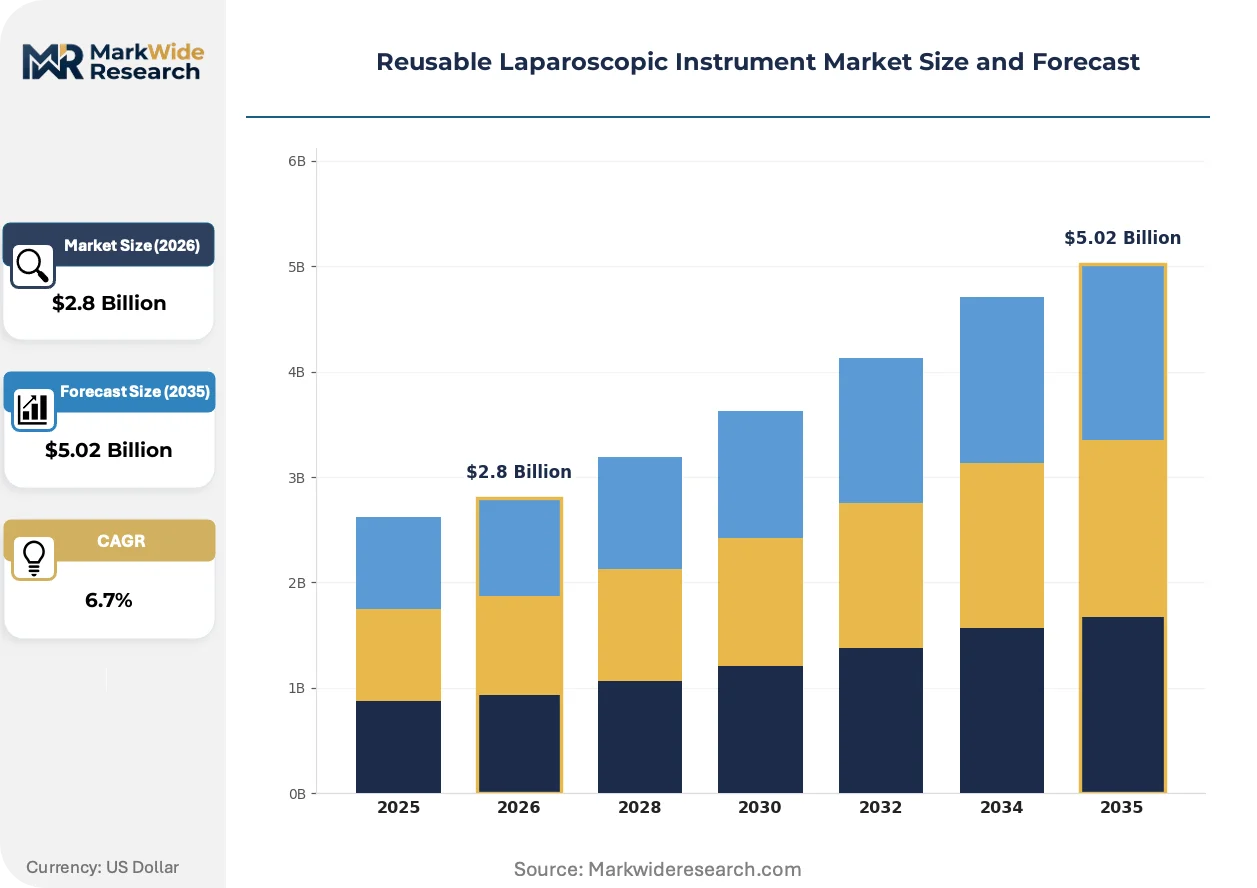
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scissors, Graspers, Needle Holders, Dilators Application: General Surgery, Gynecological Procedures, Urological Surgery, Bariatric Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Material: Stainless Steel, Titanium, Plastics, Composites |
| Companies Covered | Ethicon, Karl Storz, Olympus Corporation, Stryker, Smith & Nephew, Medtronic, B. Braun, Richard Wolf GmbH, ConMed Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Laparoscopic Instrument Market Trends and Innovations
Digital traceability systems and modular instrument architectures are redefining how reusable laparoscopic devices are maintained, tracked, and valued across healthcare delivery networks.
Radio-frequency identification tagging is decentralizing asset management from centralized sterile processing departments to point-of-use tracking. Academic medical centers in the United States are embedding RFID chips into titanium-alloy graspers to monitor sterilization cycle counts and automate maintenance scheduling. This distributed accountability model is compressing instrument loss rates and extending functional lifespans beyond OEM-specified replacement intervals.
EU MDR technical documentation requirements for reprocessing validation are elevating compliance investment thresholds for market entry. Manufacturers must now submit exhaustive biocompatibility testing protocols and sterilization efficacy data that previously satisfied notified bodies through abbreviated pathways. Smaller instrument fabricators without dedicated regulatory affairs functions are outsourcing documentation preparation to specialized consultancies, creating a secondary compliance services market.
Integrated delivery networks are unbundling after-sales service contracts from capital equipment purchases. Procurement officers in North American hospital systems now negotiate sterilization assurance and preventive maintenance as separate line items, enabling competitive benchmarking between OEM service divisions and independent repair specialists. This disaggregation is most pronounced in multi-hospital systems operating centralized sterile processing facilities with standardized equipment portfolios.
Reusable Laparoscopic Instrument Market Segmentation
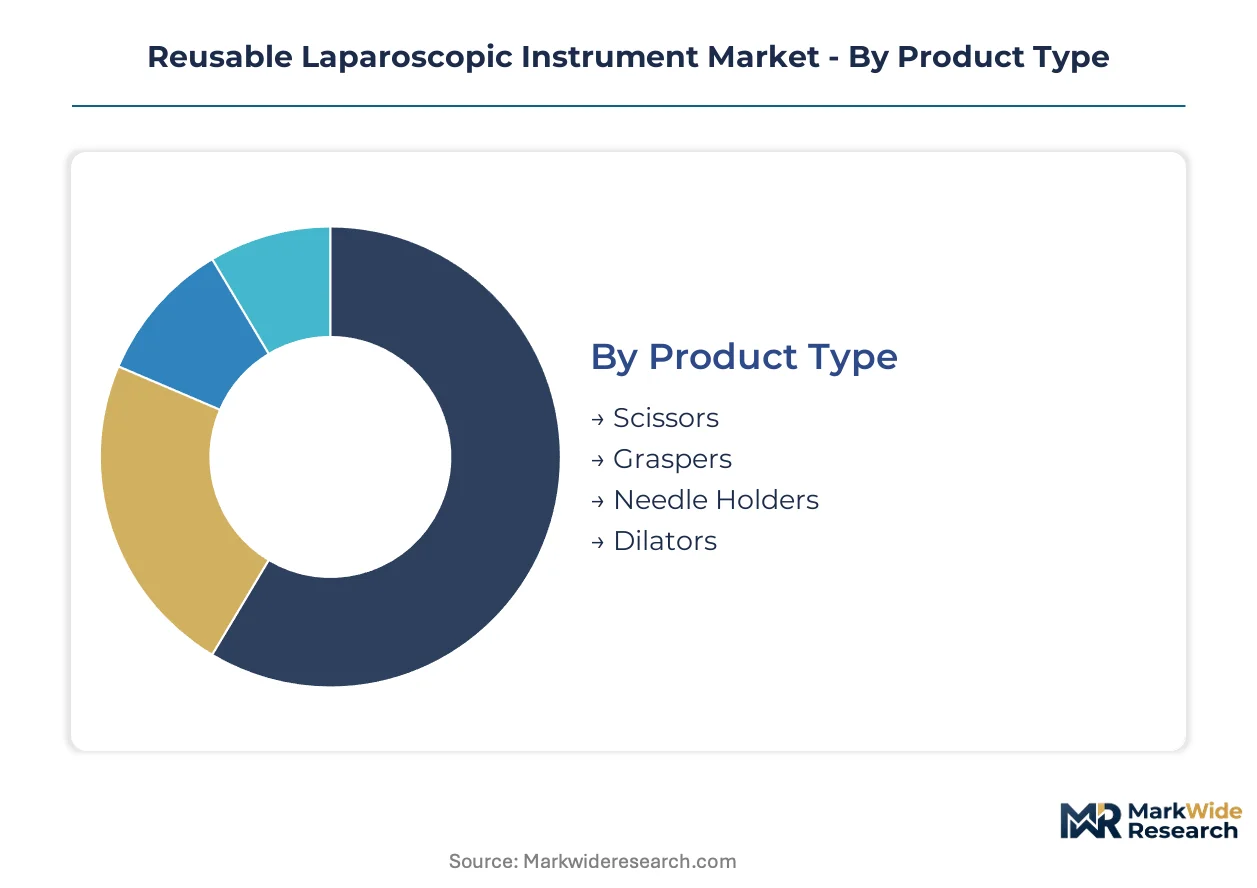
Segmentation in reusable laparoscopic instruments reveals how procurement consolidation and sterilization economics reshape competitive positioning across product tiers and customer channels. Understanding these splits enables vendors to calibrate service bundling and pricing architecture against total cost-of-ownership calculations.
Product Type:
Volume throughput concentrates in graspers and scissors, while premium positioning accrues to instruments with integrated energy delivery or specialized jaw geometries.
- Graspers:Titanium-alloy variants with ratcheted locking mechanisms dominate general surgery suites requiring secure tissue manipulation through multiple port sites. German precision manufacturers in Tuttlingen and Solingen capture procurement preference from integrated delivery networks standardizing on corrosion-resistant instruments that withstand thermal cycling without jaw fatigue.
- Scissors:Curved and straight configurations with micro-serrated blades enable precise dissection in bariatric and gynecological procedures. Demand clusters in academic medical centers performing high-volume sleeve gastrectomy operations where instrument durability compresses per-procedure costs.
- Needle Holders:Carbide-insert jaw designs for suturing in confined spaces.
- Dilators:Tapered instruments for trocar site preparation and fascial closure.
Today's leader: Graspers. Tomorrow's challenger: Scissors with electrosurgical integration.
Application:
Procedure-specific instrument configurations drive margin differentiation, with bariatric and gynecological applications commanding specialized designs.
- General Surgery:Appendectomy, cholecystectomy, and hernia repair generate the highest instrument throughput across hospital systems. Standardized grasper-scissors combinations with 5mm shaft diameters satisfy most procedural requirements, enabling volume pricing from manufacturers serving consolidated procurement networks.
- Bariatric Surgery:Sleeve gastrectomy and gastric bypass procedures demand extended-length instruments with reinforced shafts for morbidly obese patient populations. Ambulatory surgical centers in the United States are expanding dedicated bariatric suites, creating incremental demand for needle holders with enhanced tactile feedback during stapled anastomosis.
- Gynecological Procedures:Hysterectomy and myomectomy applications requiring atraumatic grasping surfaces.
- Urological Surgery:Nephrectomy and prostatectomy configurations with extended reach capabilities.
General Surgery anchors current procurement volumes; Bariatric Surgery climbs the fastest as ambulatory capacity expands.
End User:
Capital availability and sterilization infrastructure maturity determine customer tier attractiveness and service contract structure.
- Hospitals:Centralized sterile processing departments with autoclave and hydrogen peroxide plasma systems support comprehensive reusable instrument programs. Integrated delivery networks in the United States negotiate multi-year supply agreements bundling preventive maintenance and repair services to reduce total cost-of-ownership.
- Ambulatory Surgical Centers:Capital-constrained facilities with limited sterilization capacity favor streamlined instrument portfolios with rapid turnaround requirements. These settings generate expanding demand for titanium-alloy instruments that tolerate accelerated reprocessing cycles without degradation.
- Specialty Clinics:Gynecological and urological focused practices with procedure-specific instrument needs.
- Research Institutions:Academic medical centers with captive sterilization departments and training program requirements.
Hospitals dominate contract value; Ambulatory Surgical Centers gain share fastest as procedure migration accelerates.
Material:
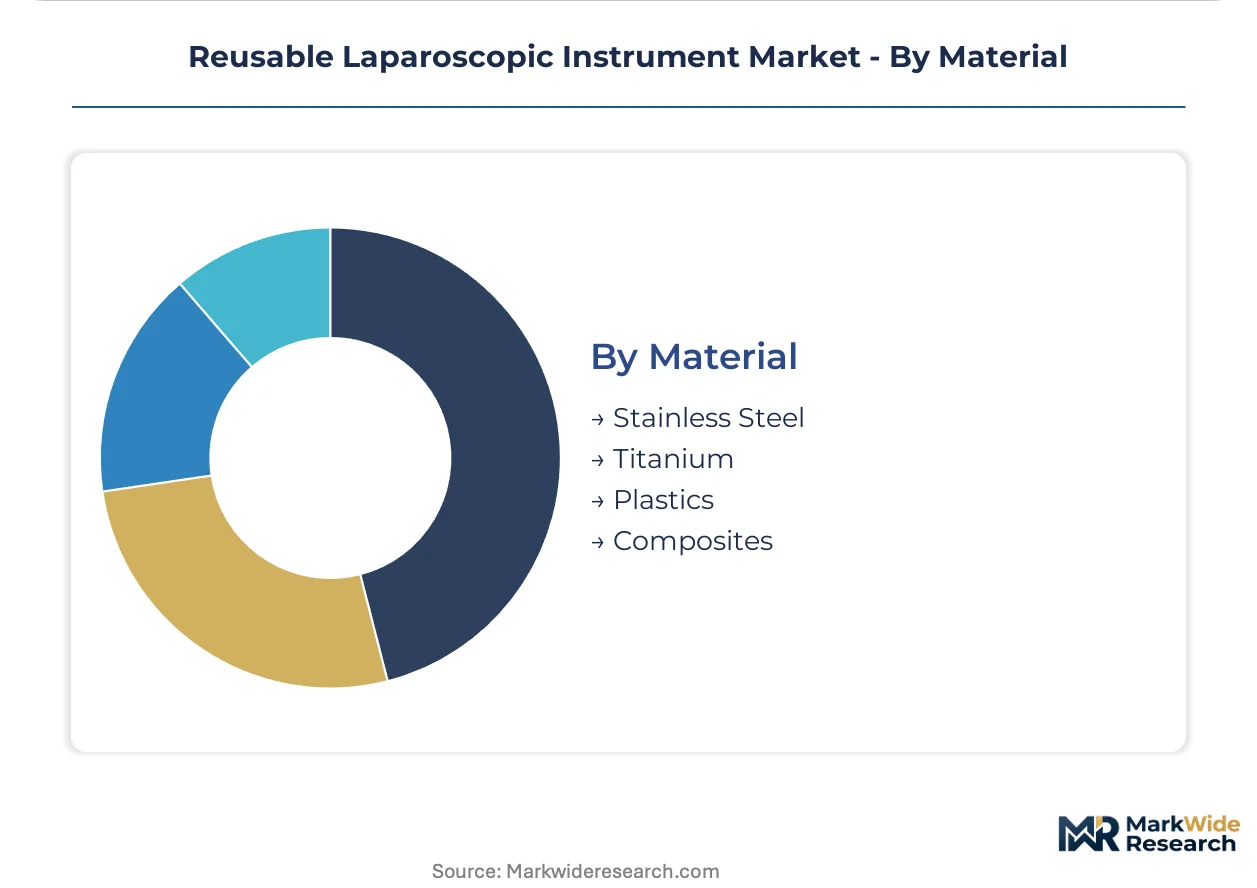
Raw material selection governs corrosion resistance, weight characteristics, and regulatory documentation burden.
- Titanium:Surgical-grade titanium alloys deliver superior strength-to-weight ratios and thermal stability under repeated autoclave cycling. Production concentrates in Germany's precision manufacturing corridor where CNC machining expertise enables complex jaw mechanism fabrication with tight tolerance control.
- Stainless Steel:Surgical-grade 400-series and precipitation-hardened alloys provide cost-effective alternatives for standard graspers and dilators. Mid-tier manufacturers source forged blanks from Italian and German suppliers, competing on unit pricing where procurement consolidation squeezes margins.
- Plastics:Insulating components and ergonomic handle overlays for electrosurgical instruments.
- Composites:Ceramic-reinforced polymers for specialized insulating applications.
Titanium commands premium positioning; Stainless Steel retains volume leadership across price-sensitive procurement segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium manufacturing capacity while the United States drives procurement consolidation through integrated delivery networks. Surgical instrument demand concentrates in precision manufacturing corridors and academic medical centers with captive sterilization infrastructure.
United States
Integrated delivery networks consolidate supplier contracts across multi-hospital systems, bundling preventive maintenance with instrument procurement. FDA 510(k) reprocessing validation requirements extend clearance timelines for complex luminal geometries. Academic medical centers in Boston and the Research Triangle deploy RFID-tagged titanium graspers to automate sterilization cycle tracking.
Germany
Tuttlingen and Solingen anchor precision CNC machining clusters for titanium-alloy jaw mechanisms with tight tolerance control. EU MDR phased compliance timelines grant manufacturers additional runway for biocompatibility documentation. Bavarian sterilization validation consultancies serve mid-tier fabricators lacking dedicated regulatory affairs functions.
Japan
PMDA quality management inspections enforce rigorous design controls for electrosurgical-enabled devices. METI industrial policy supports domestic production of surgical-grade stainless steel instruments. Osaka-based manufacturers supply academic medical centers across East Asia with corrosion-resistant graspers.
India
CDSCO medical device rules classify reusable laparoscopic instruments under risk-based regulatory pathways with escalating documentation requirements. PLI scheme incentives attract contract manufacturers serving European OEMs. Gujarat and Maharashtra host forging operations for standard-grade stainless steel instrument blanks.
Switzerland
Swissmedic expedited review pathways reward manufacturers with pre-submitted sterilization validation protocols. Precision watchmaking expertise transfers to micro-surgical instrument fabrication in the Jura Arc. Zurich and Basel academic hospitals specify titanium needle holders for bariatric procedures.
Reusable Laparoscopic Instrument Market Competitive Landscape
German producers anchor the premium tier through precision titanium machining; American specialists hold procurement consolidation advantages through integrated service contracts. Market structure bifurcates between consolidated OEMs with end-to-end sterilization programs and fragmented regional fabricators competing on unit pricing. Three archetypes dominate: precision manufacturers with metallurgical expertise, diversified medtech conglomerates with service bundling capabilities, and independent reconditioning specialists. Competitive moves center on backward integration into forging operations and geographic expansion through distributor acquisitions.
Within the diversified medtech tier, Ethicon and Stryker occupy positions defined by sterilization assurance bundling and multi-year IDN contracting. German precision specialists Karl Storz and Richard Wolf GmbH exemplify manufacturing-driven positioning anchored in Tuttlingen's CNC machining corridor. Olympus Corporation sits within the endoscopy-integrated archetype, leveraging optical system expertise across rigid and flexible platforms.
| Leading Market Players |
|---|
| Ethicon |
| Karl Storz |
| Olympus Corporation |
| Stryker |
| Smith & Nephew |
| Medtronic |
| B. Braun |
| Richard Wolf GmbH |
| ConMed Corporation |
| Others |
Pricing and Supply Chain Analysis
Family-owned precision manufacturers in Tuttlingen and Solingen anchor supply-side discipline through generational metallurgical expertise, translating captive CNC machining capabilities into premium pricing power for titanium-alloy instruments while resisting margin erosion from consolidated hospital procurement.
Pricing Analysis
Capacity additions in India's forging corridor are reshaping price floors for standard-grade stainless steel graspers, compressing margins for mid-tier European fabricators. Three-tier pricing structure across premium, standard, and economy levels separates German titanium specialists from Italian stainless-steel volume producers from Asian contract manufacturers. Pricing pressure stems from integrated delivery networks unbundling service contracts from instrument procurement. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while academic medical centers prioritize total cost-of-ownership over unit pricing.
Supply Chain Analysis
Direct-to-hospital channels handle integrated delivery network demand, while distributor networks serve fragmented ambulatory surgical centers. Precision forging and CNC machining capacity clusters in Germany, Italy, and Switzerland. Raw material sourcing draws from surgical-grade titanium sponge processors and 400-series stainless steel mills. Single-source vulnerability concentrates in southwestern Germany's jaw mechanism specialists. Distribution runs through specialized surgical instrument distributors with sterile processing technical support capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR sterilization validation extensions compound procurement demand for compliant instrument portfolios, creating structural advantage for manufacturers with pre-submitted technical documentation.
For Market Incumbents: Deepen backward integration into titanium forging operations to secure input cost predictability against energy-intensive smelting volatility. Anchor multi-year supply agreements with sterilization assurance bundling to defend against single-use polymer substitution. Prioritize ISO 13485 certification maintenance ahead of full EU MDR enforcement to capture procurement preference from consolidating integrated delivery networks. For New Entrants and Emerging Players: EU MDR in Europe opens a window for regulatory compliance consultancies serving mid-tier fabricators lacking dedicated affairs functions. Target ambulatory surgical center demand for accelerated-turnaround titanium instruments with streamlined sterilization protocols. Pursue refurbishment service model partnerships with academic medical centers operating captive sterile processing departments. For Investors and Strategic Acquirers: Diversified medtech conglomerates with service bundling capabilities are the most active acquirer in this space. Five-to-ten year viability hinges on electrosurgical integration convergence and digital traceability adoption. Acquisition focus centers on precision CNC machining specialists with metallurgical IP in corrosion-resistant alloys. Monitor RFID-tagged instrument deployment rates in academic medical centers as inflection indicator for maintenance service model viability.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Pathway | Phased sterilization validation timelines reduce market access barriers for titanium-alloy portfolios. |
| Hospital System Partnership | Integrated delivery network contracting secures multi-year revenue visibility through bundled service agreements. |
| Electrosurgical Integration | Monopolar energy delivery convergence enables premium positioning in general surgery suites. |
| Software Companion Development | RFID-enabled asset management platforms automate sterilization cycle tracking for academic medical centers. |
| Reimbursement Strategy | Bariatric procedure volume expansion in ambulatory settings drives instrument demand through payer coverage alignment. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down precision manufacturing capacity tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and sterile processing department directors inform demand-side calibration. Secondary validation draws from FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement contract registries, and German mechanical engineering association production surveys. Cross-referencing bottom-up instrument shipment estimates with top-down titanium alloy consumption data ensures triangulation integrity.
Input-output matrices map procedure volume projections to instrument replacement cycles across the analysis window. Segmentation dimensions encompass product type, application specialty, end-user facility tier, and raw material grade. CAGRs derive from regression analysis of historical procurement patterns against sterilization infrastructure investment trajectories. Forecast inputs incorporate bariatric surgery migration rates to ambulatory settings and EU MDR compliance cost absorption capacity among mid-tier manufacturers.
Revisions become necessary when sterilization validation backlog clearance timelines extend beyond modeled assumptions or when titanium alloy price volatility exceeds historical bands. Forecasts reflect documented assumptions regarding integrated delivery network consolidation velocity and single-use instrument substitution thresholds. Periodic stress-testing of base assumptions against FDA guidance evolution and hospital capital expenditure cycles is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Nebuliser Market
Medical Devices
Global Cochlear Implant Market
Medical Devices
US Peripheral Vascular Devices and Accessories Market
Medical Devices
Digital Migraine Treatment Device Market
Medical Devices
Interlaminar Device Market
Medical Devices
Global Blood Ketone Meter Market
Medical Devices
Venous Procedure Devices Market
Medical Devices
Thoracolumbar Stabilization Devices Market
Medical Devices
Global Brachytherapy Treatment Planning Systems Market
Medical Devices
Medical Devices Vigilance Market
Medical Devices
Otoscope Devices Market
Medical Devices
Airway Clearance Systems Market
Medical Devices
ePTFE Vascular Prosthesis Market
Medical Devices
Prosthetic Disc Nucleus Market
Medical Devices
Digital Blood Pressure Monitors Market
Medical Devices
Drug Delivery Devices Market