
 India Hemostats Market | 2026-2036
India Hemostats Market Size, Share, and Industry Trends Forecast 2026-2036
India Hemostats Market Insights
CDSCO's medical device licensing framework is reorganizing competitive access in the India Hemostats Market. Baxter leverages its established regulatory dossiers to sustain premium positioning across cardiac surgery lines. Ethicon Inc. anchors its presence through deep specialization in absorbable hemostat formats. B. Braun Melsungen competes on manufacturing scale, extending distribution reach into government procurement channels.
Hemostats comprise agents or devices designed to arrest bleeding through mechanical occlusion, accelerated clotting cascades, or tissue adhesion, typically incorporating oxidized regenerated cellulose, gelatin matrices, or polysaccharide spheres with absorption profiles spanning 24 hours to 6 weeks depending on composition. Their primary purpose centers on reducing intraoperative blood loss and transfusion requirements across open and minimally invasive procedures. Absorbable hemostats lead volume share given their bioresorbable convenience and broad surgical compatibility, while combination hemostats represent the fastest-expanding margin pool as surgeons seek dual-action products integrating mechanical and active clotting components. Mechanical hemostats occupy a mature position in trauma care settings where immediate vessel compression remains protocol.
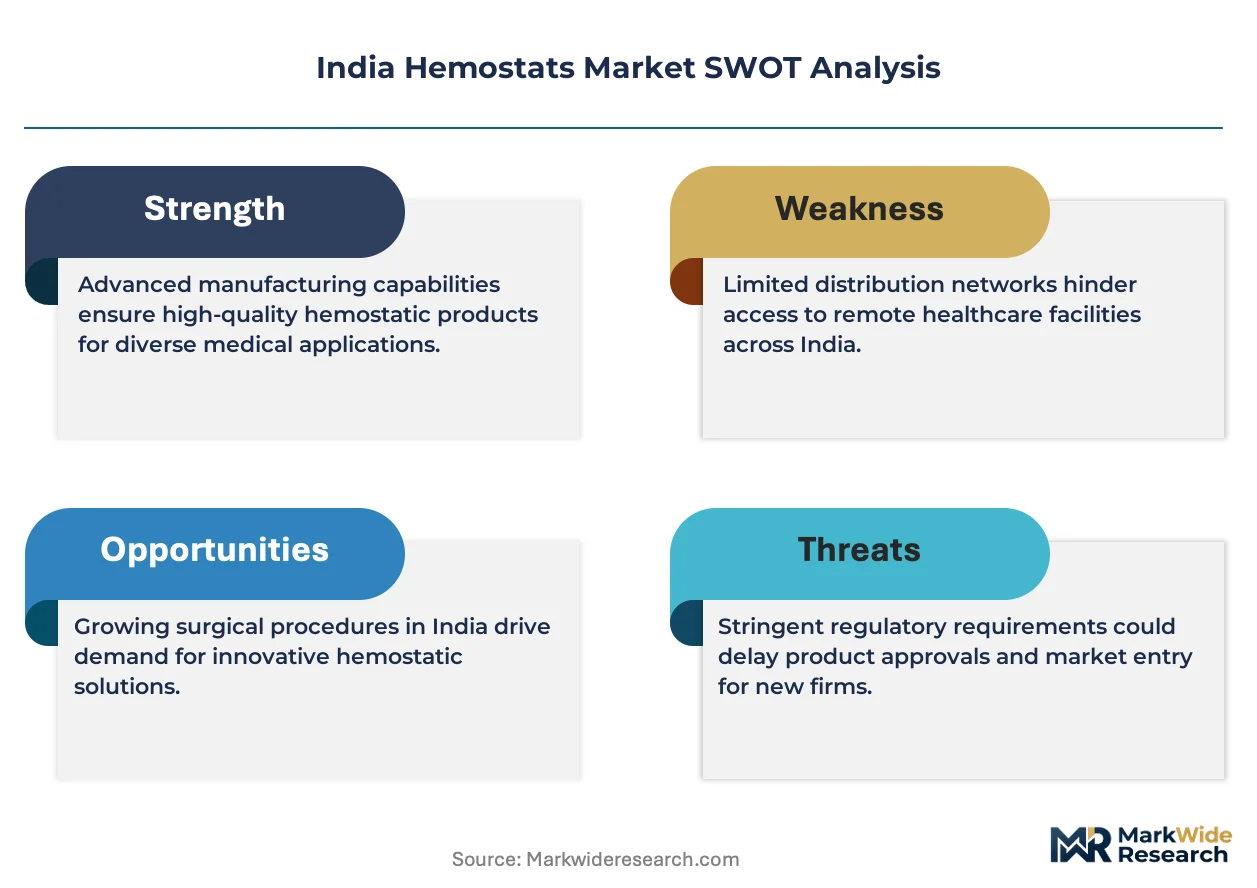
BIS certification requirements and CDSCO's Quality Management System mandate for Class C and D devices shape product registration timelines and testing expenditures for both domestic manufacturers and importers. The PLI scheme for medical devices further redirects capital toward local production of gelatin and oxidized cellulose substrates, altering sourcing economics for multinational suppliers. Stakeholders must monitor how state-level tendering reforms in Tamil Nadu and Maharashtra reshape price realization versus volume commitments.
Market Dynamics
CDSCO's tightened Quality Management System mandate for Class C and D hemostat devices is forcing manufacturers to restructure compliance investments and registration timelines. This regulatory pressure concentrates competitive advantage among dossier-heavy incumbents while marginalizing smaller importers.
Growth Catalysts
- PLI scheme for medical devices:Domestic production incentives redirect capital toward local gelatin and oxidized cellulose substrate manufacturing, reducing import dependency for absorbable hemostat raw materials.
- Tertiary care infrastructure expansion:Maharashtra, Karnataka, and Tamil Nadu are deepening surgical capacity in cardiac and orthopedic centers, concentrating hemostat procurement volumes in these states.
- Absorbable hemostat bioresorbability:Elimination of foreign body removal procedures accelerates turnover in high-volume surgical settings, driving format preference over mechanical alternatives.
Market Restraints
- BIS certification timelines:Extended testing protocols for oxidized regenerated cellulose products delay market entry for new entrants, compressing competitive pressure on established suppliers.
- Gelatin raw material concentration:Collagen sourcing clusters in specific Indian states create geographic supply vulnerability for matrix-based hemostat production.
- Combination hemostat R&D costs:Dual-action mechanical-active clotting formulations require parallel validation streams, elevating development expenditure versus single-mechanism products.
Strategic Opportunities
- Tier-2 city surgical centers:Expansion of equipped operating theaters in secondary Indian cities opens distribution channels underserved by current premium-focused supplier networks.
- State tendering reform leverage:Tamil Nadu and Maharashtra procurement restructuring creates volume commitment mechanisms for manufacturers willing to accept compressed margins.
- Combination format white space:Integration of mechanical occlusion with active clotting agents represents underdeveloped product architecture with surgeon preference tailwinds.
Industry Challenges
- CDSCO dossier compilation expertise:Scarce regulatory affairs talent capable of navigating Class C and D device licensing creates bottlenecks for both domestic and multinational market entrants.
- Legacy distribution reconfiguration:Shift from importer-dependent models toward direct government channel engagement requires relationship rebuilding with state-level procurement authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Hemostats Market |
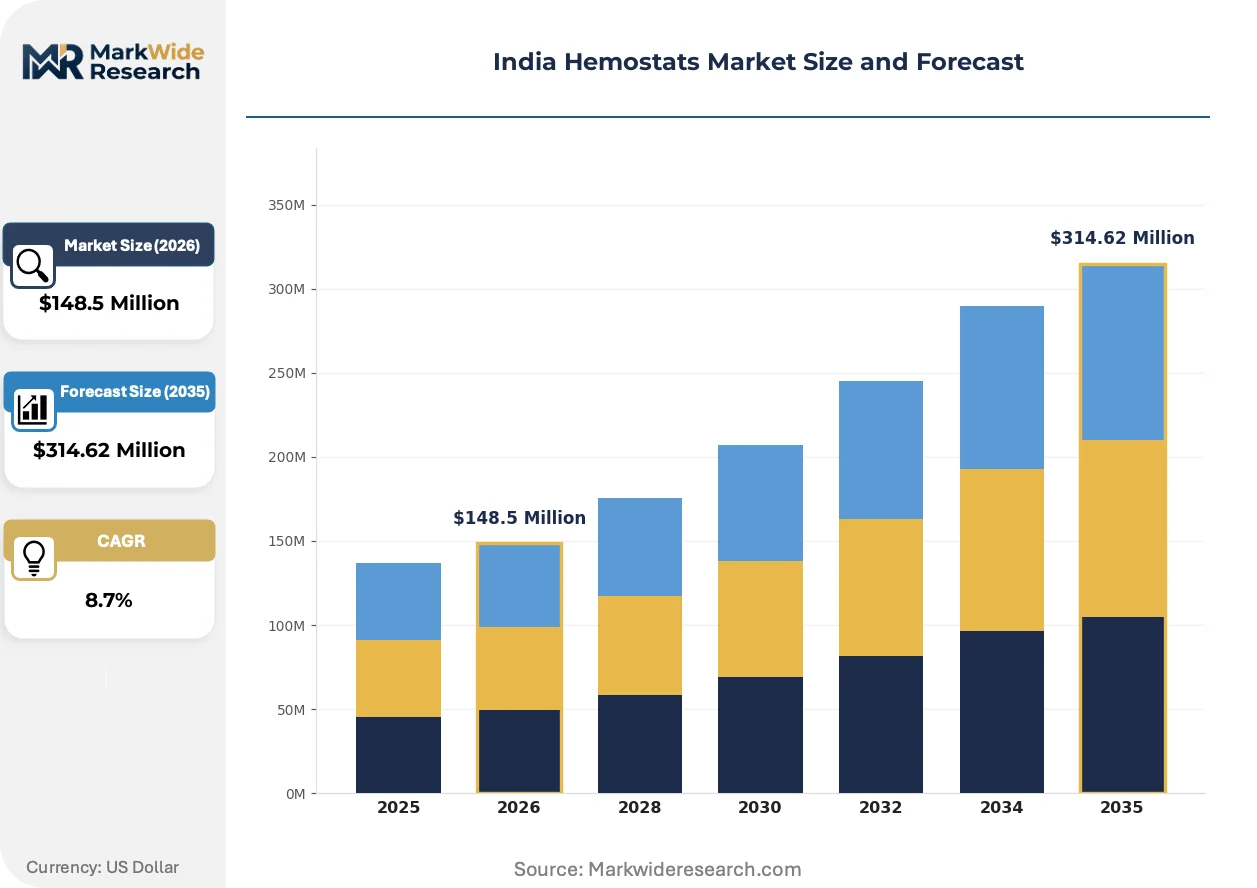
| Market Size in 2026 | $148.5 Million |
| Market Size in 2035 | $314.62 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable Hemostats, Topical Hemostats, Mechanical Hemostats, Combination Hemostats End User: Hospitals, Surgical Centers, Clinics, Emergency Departments Application: Cardiac Surgery, Orthopedic Surgery, Trauma Care, General Surgery Distribution Channel: Online Stores, Direct Sales, Distributors, Medical Supply Stores |
| Companies Covered | Baxter, Mil Laboratories Pvt Ltd, Ethicon Inc., B. Braun Melsungen, Meril Life Sciences, Aegis Lifesciences, Axio Biosolutions Pvt Ltd, Teleflex, Eucare Pharmaceuticals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Hemostats Market Trends and Innovations
Product architecture in the India Hemostats Market is bifurcating between premium combination formats and cost-optimized absorbable matrices. This evolution reflects diverging surgeon preferences across public and private care settings.
Combination hemostats integrating oxidized regenerated cellulose with thrombin-active components is fragmenting the traditional absorbable-dominant landscape. Cardiac surgery departments in tertiary Mumbai and Bengaluru hospitals are piloting these dual-action products for complex procedures. The technology is fragmenting procurement categories, forcing purchasing committees to evaluate performance tiers rather than single-format standardization.
CDSCO's 2023 Medical Device Rules amendment tightened post-market surveillance obligations for Class C and D hemostats. Manufacturers must now maintain vigilance reporting infrastructure that smaller importers struggle to fund. Absorbable hemostat importers face the steepest compliance cost escalation, accelerating exit of undercapitalized traders from Karnataka and Tamil Nadu markets.
Hospital buying committees are unbundling hemostat procurement from suture and staple vendor contracts, creating direct manufacturer relationships. Corporate hospital chains in Maharashtra are leading this disintermediation, establishing technical evaluation panels independent of traditional distributor influence. The shift concentrates price negotiation leverage with large-volume purchasers while compressing margins for multi-product distributors serving smaller surgical centers.
India Hemostats Market Segmentation
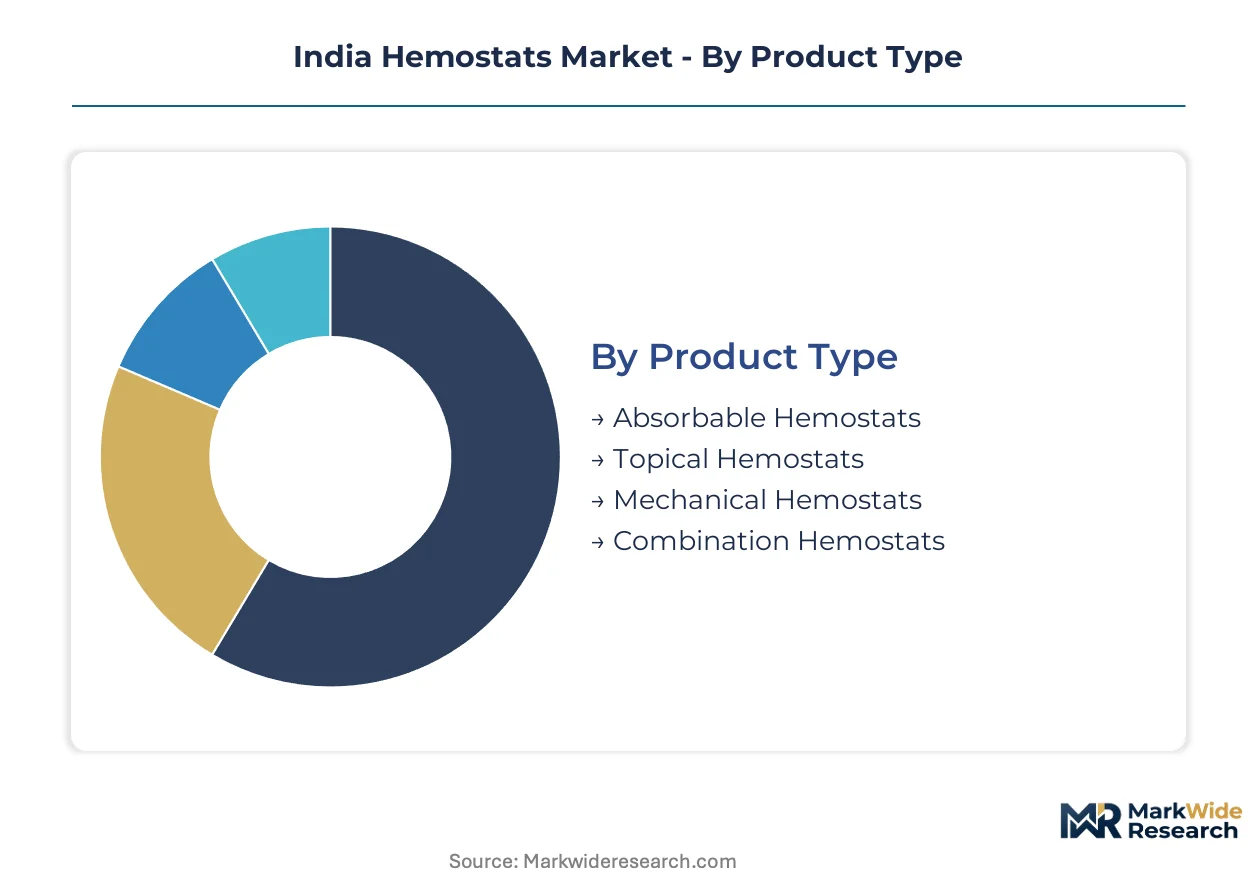
Product architecture in the India Hemostats Market fragments across mechanism of action, care setting, and procurement pathway. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning.
Product Type:
Combination formats face the steepest substitution pressure as surgeons weigh dual-action performance against absorbable convenience in high-throughput settings.
- Absorbable Hemostats:Oxidized regenerated cellulose and gelatin matrices dissolve within 24 hours to 6 weeks without foreign body retrieval. Maharashtra cardiac centers prioritize these for turnover efficiency in multi-procedure schedules.
- Combination Hemostats:Mechanical-active hybrids integrate cellulose matrices with thrombin or other clotting accelerators. Mumbai and Bengaluru tertiary hospitals pilot these for complex cardiac procedures where bleeding control demands exceed single-mechanism limits.
- Mechanical Hemostats:Compression-based devices for immediate vessel occlusion in trauma protocols.
- Topical Hemostats:Surface-applied agents for minor surgical bleeding and dermatological procedures.
Absorbable hemostats anchor the volume base while combination formats gain share at the steepest rate.
End User:
Cost tier stratification separates high-volume government procurement from premium private channel purchasing.
- Hospitals:Tertiary institutions in Karnataka, Tamil Nadu, and Maharashtra concentrate procurement volumes through centralized tendering. CDSCO Class C and D compliance requirements filter supplier participation toward dossier-capable incumbents.
- Surgical Centers:Tier-2 city expansion in Madhya Pradesh and Gujarat creates new addressable demand outside metro hospital networks.
- Clinics:Outpatient settings with limited surgical throughput favor single-use topical formats.
- Emergency Departments:Trauma-focused mechanical hemostat demand with compressed decision timelines.
Hospitals dominate absolute procurement value while surgical centers represent the most rapid expansion trajectory.
Application:
Procedure complexity determines hemostat specification tier and reimbursement pathway.
- Cardiac Surgery:Sternotomy and bypass procedures demand premium absorbable or combination formats with validated biocompatibility profiles. Tamil Nadu and Maharashtra cardiac centers drive format innovation adoption.
- Orthopedic Surgery:Joint replacement and trauma fixation procedures utilize matrix-based hemostats for cancellous bone bleeding control.
- Trauma Care:Emergency protocols favor mechanical compression devices for immediate hemorrhage control.
- General Surgery:Abdominal and soft tissue procedures with standardized absorbable hemostat protocols.
Cardiac surgery commands the highest specification tier while orthopedic applications scale most quickly.
Distribution Channel:
Channel restructuring reflects disintermediation pressure from corporate hospital chains.
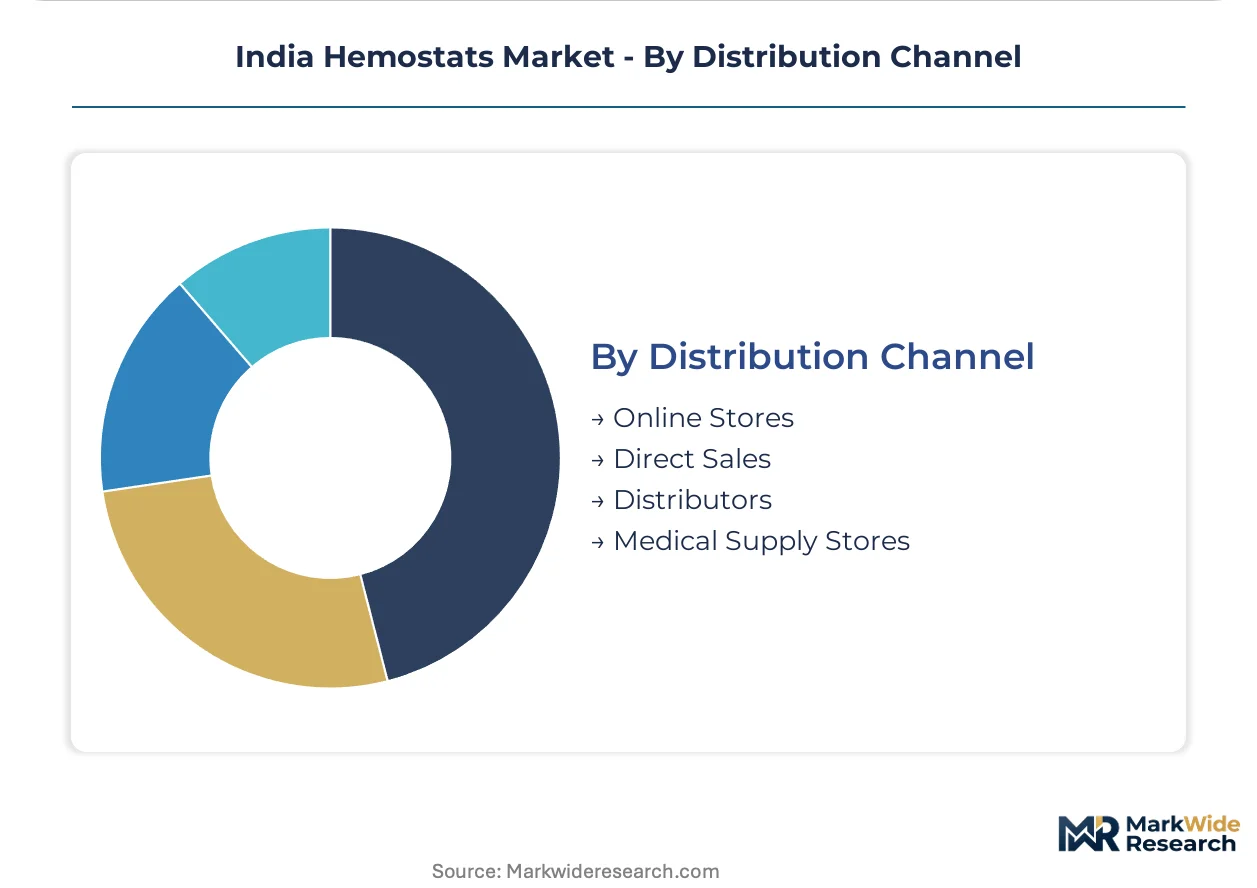
- Direct Sales:Manufacturer relationships with Maharashtra and Tamil Nadu corporate hospital chains bypass traditional distributor margins. Technical evaluation panels now operate independently of multi-product vendor influence.
- Distributors:Legacy channel serving tier-2 surgical centers and government procurement with consolidated logistics.
- Online Stores:Emerging procurement pathway for standardized absorbable formats in smaller clinical settings.
- Medical Supply Stores:Local inventory access for emergency replenishment and clinic-level purchasing.
Direct sales capture the steepest share gains while distributor relationships retain volume concentration in government channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dedicated Freight Corridor linking Delhi to Mumbai underwrites Maharashtra's dominance in medical device distribution, cutting transit times for temperature-sensitive hemostat shipments from western ports to inland surgical hubs.
Maharashtra
Mumbai's cardiac surgery centers drive premium absorbable hemostat procurement through multi-procedure scheduling demands. CDSCO's Class C and D licensing filters supplier participation toward dossier-capable incumbents with established quality management systems. The Mumbai-Pune pharmaceutical belt concentrates gelatin substrate manufacturing under PLI scheme incentives, redirecting raw material sourcing from import-dependent models.
Karnataka
Bengaluru's medical technology cluster generates combination hemostat pilot programs in tertiary cardiac departments. BIS certification timelines for oxidized regenerated cellulose products delay market entry for new entrants, entrenching established suppliers. The state's electronics manufacturing corridors are diversifying into medical device components, creating local testing infrastructure for hemostat biocompatibility validation.
Tamil Nadu
Chennai's corporate hospital chains are disintermediating procurement through direct manufacturer relationships and independent technical evaluation panels. State-level tendering reforms reshape price realization versus volume commitments for hemostat suppliers. The Sriperumbudur medical device park anchors local production investments for absorbable matrix substrates under central government production-linked incentives.
Gujarat
Ahmedabad's pharmaceutical formulation heritage extends into hemostat raw material processing for gelatin and collagen matrices. CDSCO's tightened post-market surveillance obligations accelerate exit of undercapitalized importers from distribution channels. The state's specialty chemical infrastructure supplies oxidized cellulose precursors to domestic hemostat manufacturers reducing import dependency.
Telangana
Hyderabad's life sciences corridor attracts contract manufacturing organizations for hemostat final formulation and packaging. The state's medical device policy complements central PLI schemes with additional capital subsidies for local production. Genome Valley's research institutions are developing indigenous thrombin-active components for combination hemostat formats.
India Hemostats Market Competitive Landscape
Listed leaders compete with private specialists across regulatory dossier depth and government channel access. The vendor base stratifies between multinational incumbents with established CDSCO registrations and domestic challengers leveraging PLI scheme manufacturing incentives. Three archetypes dominate: dossier-heavy premium suppliers, scale-driven government contractors, and innovation-focused domestic specialists. Competitive moves concentrate on capacity expansion in gelatin and oxidized cellulose substrates and strategic partnerships with state procurement authorities.
Among the established multinational tier, Baxter and Ethicon Inc. occupy positions defined by regulatory compliance infrastructure and cardiac surgery specialization. B. Braun Melsungen anchors the scale-driven archetype with manufacturing breadth extending into government procurement channels. Domestic specialists including Meril Life Sciences and Aegis Lifesciences exemplify the PLI scheme beneficiary model, redirecting capital toward local substrate production. Axio Biosolutions Pvt Ltd and Mil Laboratories Pvt Ltd represent innovation-focused entrants navigating BIS certification timelines to establish market presence.
| Leading Market Players |
|---|
| Baxter |
| Mil Laboratories Pvt Ltd |
| Ethicon Inc. |
| B. Braun Melsungen |
| Meril Life Sciences |
| Aegis Lifesciences |
| Axio Biosolutions Pvt Ltd |
| Teleflex |
| Eucare Pharmaceuticals |
| Others |
Pricing and Supply Chain Analysis
PLI-scheme-driven substitution of imported gelatin and oxidized cellulose with Maharashtra and Gujarat-produced substrates is simultaneously redrawing raw material sourcing maps and compressing landed-cost premiums for absorbable hemostat manufacturers. This input swap concentrates pricing power with domestic substrate producers while forcing multinational incumbents to recalibrate transfer pricing strategies.
Pricing Analysis
Volume-discount tiering separates corporate hospital chains securing direct manufacturer contracts from tier-2 surgical centers purchasing through distributor markups. CDSCO Class C and D certification grade determines which suppliers qualify for government tender participation, creating a two-tier price architecture. Cost compression in the standard absorbable segment is intensifying because Tamil Nadu and Maharashtra procurement reforms mandate volume commitments at compressed margins. Government procurement channels exhibit the highest price sensitivity, while private cardiac surgery centers prioritize performance specifications over unit cost.
Supply Chain Analysis
Inbound logistics costs from western ports through the Dedicated Freight Corridor to inland surgical hubs have stabilized temperature-sensitive hemostat shipment economics. Raw material sourcing draws from Gujarat for gelatin matrices, Maharashtra for oxidized cellulose precursors, and Karnataka for biocompatibility testing infrastructure. Single-source vulnerability clusters in collagen extraction from specific Indian states threaten matrix-based production continuity. Distribution runs through direct sales to corporate hospital chains alongside legacy distributor networks serving government procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Hemostats Market functions as a service-attach opportunity where technical support for CDSCO compliance dossier preparation and post-market surveillance infrastructure generates recurring revenue expanding faster than hardware margins. Regulatory service contracts now anchor long-term supplier relationships.
For Market Incumbents: Fortify market position by deepening captive production of oxidized cellulose substrates in the Mumbai-Pune pharmaceutical belt and embedding dedicated regulatory affairs teams within Tamil Nadu and Maharashtra procurement authorities. CDSCO's tightened Quality Management System mandate threatens smaller importers but creates service-attach revenue streams for dossier-capable incumbents willing to manage vigilance reporting for hospital clients. For New Entrants and Emerging Players: Anchor in tier-2 city surgical centers in Madhya Pradesh and Gujarat where distributor-dependent supply models leave service gaps unaddressed. Combination hemostat formats represent the most penetrable product architecture given surgeon preference tailwinds in Bengaluru and Mumbai tertiary cardiac departments. Pursue white-label manufacturing partnerships with PLI scheme beneficiaries to bypass BIS certification timeline disadvantages. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed domestic specialists possessing PLI scheme manufacturing infrastructure but lacking CDSCO registration expertise. The five-to-ten year viability window favors targets combining gelatin substrate production capability with established state government channel relationships. Monitor Karnataka and Tamil Nadu tendering reform implementation pace as the signal indicating when volume commitment mechanisms will consolidate supplier tiers.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Class C and D Registration Investment | Quality Management System compliance unlocks government procurement channel access in Maharashtra and Tamil Nadu. |
| PLI Scheme Manufacturing Scale-Up | Domestic oxidized cellulose substrate production reduces import dependency and shortens BIS certification timelines. |
| Hospital System Direct Partnership | Corporate chains in Bengaluru and Chennai bypass distributor margins through technical evaluation panel relationships. |
| Combination Format R&D Pipeline | Dual-action mechanical-active clotting integration addresses unmet surgeon demand in complex cardiac procedures. |
| State Tendering Reform Engagement | Volume commitment mechanisms in restructured Tamil Nadu and Maharashtra procurement reshape competitive positioning. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with cardiac surgeons, hospital purchasing committee members, biomedical engineers, and CDSCO regulatory affairs consultants; and secondary validation through CDSCO medical device registration databases, state-level tender documents from Maharashtra and Tamil Nadu, PLI scheme beneficiary disclosures, and hospital procurement records. Bottom-up demand modeling from surgical procedure volumes and hemostat utilization rates was triangulated against top-down manufacturer shipment data.
Across the analysis window, the forecasting framework modeled volume and value trajectories across product type segmentation, end user tier, application complexity, and distribution channel structure. CAGRs were derived from procedure growth assumptions, substitution dynamics between absorbable and combination formats, and pricing elasticity estimates from tender outcome analysis. CDSCO regulatory timeline projections and PLI scheme capacity addition schedules served as key industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained PLI scheme incentives and stable CDSCO regulatory enforcement intensity; material deviation in either would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Wearable Injectors Market
Medical Devices
MRI-Compatible IV Infusion Pump Systems Market
Medical Devices
Global Wheelchair Market
Medical Devices
Lacrimal Duct Stent Tube Market
Medical Devices
Invasive SEEG Depth Electrodes Market
Medical Devices
Global Microcatheter Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
Global Medical Exoskeleton Market
Medical Devices
Life Science and Chemical Instruments Market
Medical Devices
Video Dermatoscope Market
Medical Devices
Asia-Pacific Single-Use Medical Device Reprocessing Market
Medical Devices
Digital Ureteroscopes Market
Medical Devices
Epistaxis Devices Market
Medical Devices
Brachytherapy Catheters Market
Medical Devices
Temperature Sensing Foley Catheter Market
Medical Devices
Coil Assisted Flow Diverters Market