
 Directed Energy Based Surgical Systems Market | 2026-2036
Directed Energy Based Surgical Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Directed Energy Based Surgical Systems Market Intelligence
The integration of artificial intelligence for real-time tissue analysis and feedback is reshaping the development of next-generation directed energy surgical platforms. Medtronic leverages its extensive R&D in robotics to enhance its electrosurgical system offerings. Johnson & Johnson Services sustains a dominant market position through its broad portfolio spanning multiple surgical specialties. Meanwhile, Boston Scientific Corporation specializes in minimally invasive devices for urology and oncology applications.
Directed energy based surgical systems are medical devices that use focused energy—such as light, sound, or electricity—to cut, coagulate, or ablate biological tissue. Their primary purpose is to enable precise, minimally invasive surgical interventions with reduced collateral damage. Laser Systems, particularly those using Fiber Laser technology, command a significant share due to their precision in ophthalmology and dermatology. Hospitals remain the largest end user segment, while Ambulatory Surgical Centers represent the fastest-growing channel for these procedures.
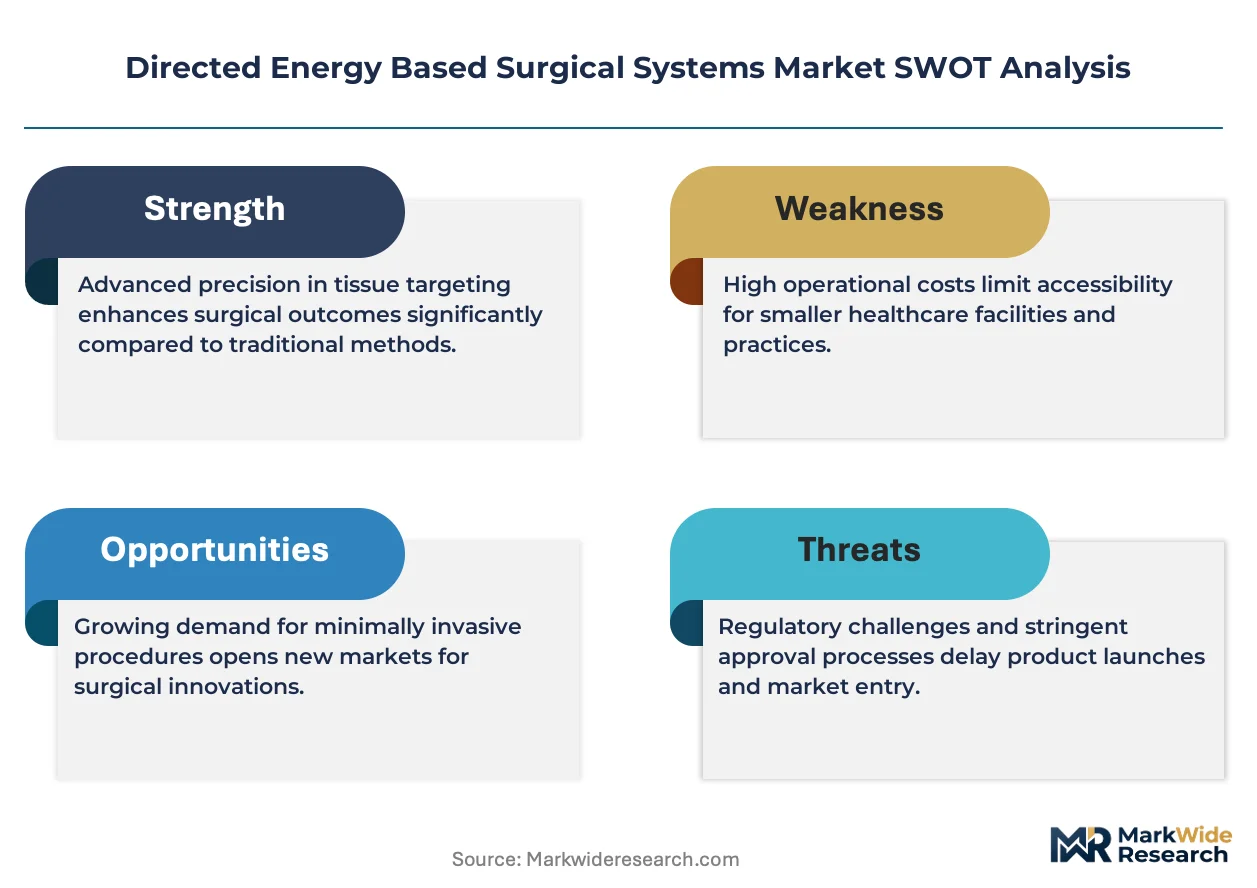
Market access for these systems is governed by stringent regulatory frameworks, including premarket approval from the US FDA. In parallel, compliance with the EU's Medical Device Regulation (MDR) and China's NMPA standards is mandatory for market entry. These regulations enforce rigorous clinical data requirements and post-market surveillance, influencing product development timelines. Vendor success will depend on navigating these complex and diverging regulatory pathways while innovating in system efficacy and safety.
Market Dynamics
The market's trajectory is defined by the increasing precision of energy delivery technologies, particularly Fiber Laser systems, meeting clinical demand for less invasive surgical options that shorten patient recovery times and improve outcomes.
Growth Catalysts
- Minimally Invasive Demand:The growing patient and provider preference for minimally invasive procedures in developed healthcare systems like Germany and Japan accelerates adoption of directed energy technologies over traditional open surgery.
- Technology Refinement:Continuous improvements in Fiber Laser technology are expanding its application beyond ophthalmology into high-precision fields like neurology and dermatology, where minimal collateral tissue damage is paramount.
- Favorable Regulatory Pathways:Devices that demonstrate substantial equivalence or incremental innovation over existing predicate devices can leverage streamlined premarket notification pathways from regulators like the US FDA, quickening market access.
Market Restraints
- High Capital Investment:The significant upfront cost of acquiring and installing advanced laser and electrosurgical systems remains a substantial barrier for smaller hospitals and clinics with constrained capital budgets.
- Specialized Training Requirements:Effective and safe operation of these complex systems necessitates extensive, specialized training for surgeons and support staff, which can slow the pace of adoption within healthcare facilities. li>Regulatory Divergence: Conflicting clinical data and documentation requirements between major regulatory bodies, such as the US FDA and the EU under its MDR, create compliance complexities and extend product development timelines.
Strategic Opportunities
- Emerging Market Penetration:Significant opportunity exists in expanding into fast-modernizing healthcare markets in the Middle East and Southeast Asia, where new hospital construction often includes state-of-the-art surgical suites.
- AI and Robotics Integration:The convergence of artificial intelligence for real-time tissue recognition with robotic-assisted surgical platforms presents a major avenue for developing next-generation autonomous and semi-autonomous systems.
- New Clinical Applications:There is untapped demand for developing tailored directed energy systems for use in cardiology for arrhythmia ablation and in neurosurgery for precise tumor removal.
Industry Challenges
- Technical Skill Gaps:A persistent shortage of biomedical engineers and technicians qualified to service and maintain sophisticated directed energy surgical systems can lead to equipment downtime and increased operational costs for hospitals.
- System Interoperability:Integrating new surgical platforms with legacy hospital information systems and electronic health records presents a significant technical and logistical challenge, hindering seamless data flow and workflow efficiency.
- Reimbursement Uncertainty:Inconsistent and evolving reimbursement codes and coverage policies for procedures using novel directed energy technologies create financial uncertainty for both providers and manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Directed Energy Based Surgical Systems Market |
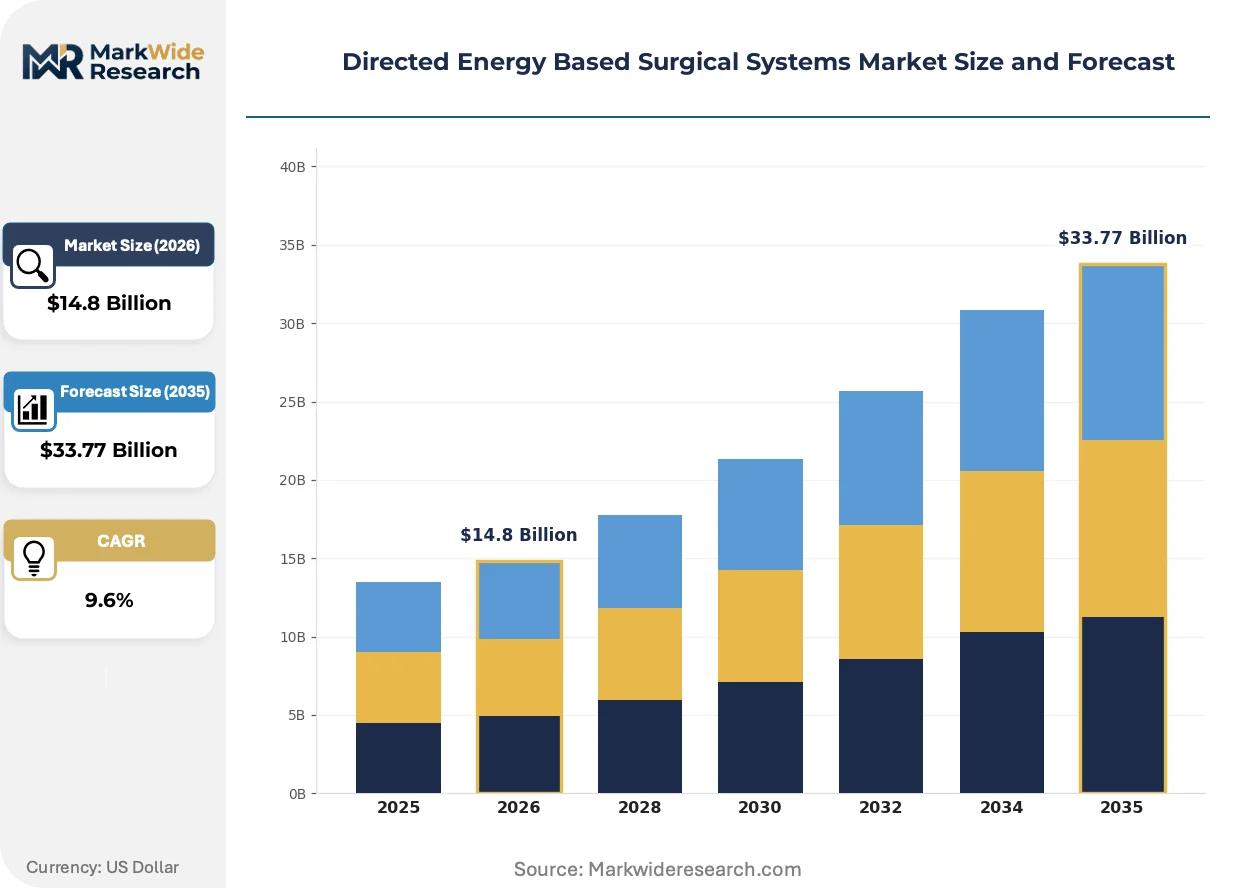
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $33.77 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Systems, Microwave Systems, Ultrasound Systems, Electrosurgical Systems Technology: Fiber Laser, CO2 Laser, High-Intensity Focused Ultrasound, Radiofrequency Application: Oncology, Ophthalmology, Dermatology, Urology End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions |
| Companies Covered | Bausch & Lomb Incorporated, Medtronic, Abbott Laboratories, Biolase, Johnson & Johnson Services, Stryker Corporation, Olympus Corporation, Boston Scientific Corporation, Apyx Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Directed Energy Based Surgical Systems Market Strategic Shifts & Innovations
The evolution of directed energy surgical systems is reshaping the boundaries of surgical intervention through the integration of intelligent control systems. This shift prioritizes real-time feedback and autonomous adjustments, moving beyond static energy delivery to create more responsive and precise tools for surgeons.
AI-powered, real-time tissue analysis is a key product evolution. Advanced surgical centers in oncology and urology are adopting these systems for enhanced margin detection during tumor resections. This capability is rendering obsolete traditional reliance on manual, post-operative pathological assessment, allowing for immediate intraoperative adjustments and potentially reducing re-operation rates.
The EU's Medical Device Regulation (MDR) represents a significant policy shift with wide-ranging impact. This regulation is forcing manufacturers to generate more robust clinical evidence and implement comprehensive post-market surveillance systems to maintain market access in Europe. High-risk devices, including many advanced energy systems, face the most intense scrutiny, compelling vendors to invest heavily in clinical trials and quality management systems.
A clear shift in procurement from one-time capital equipment purchases toward flexible, procedure-based consumption models is underway. This change disrupts traditional sales cycles and benefits facilities like Ambulatory Surgical Centers, which can adopt new technology with lower upfront financial risk. This demand-side trend is particularly visible in the United States, where healthcare providers face intense pressure to manage costs while improving surgical outcomes.
Directed Energy Based Surgical Systems Market Segmentation
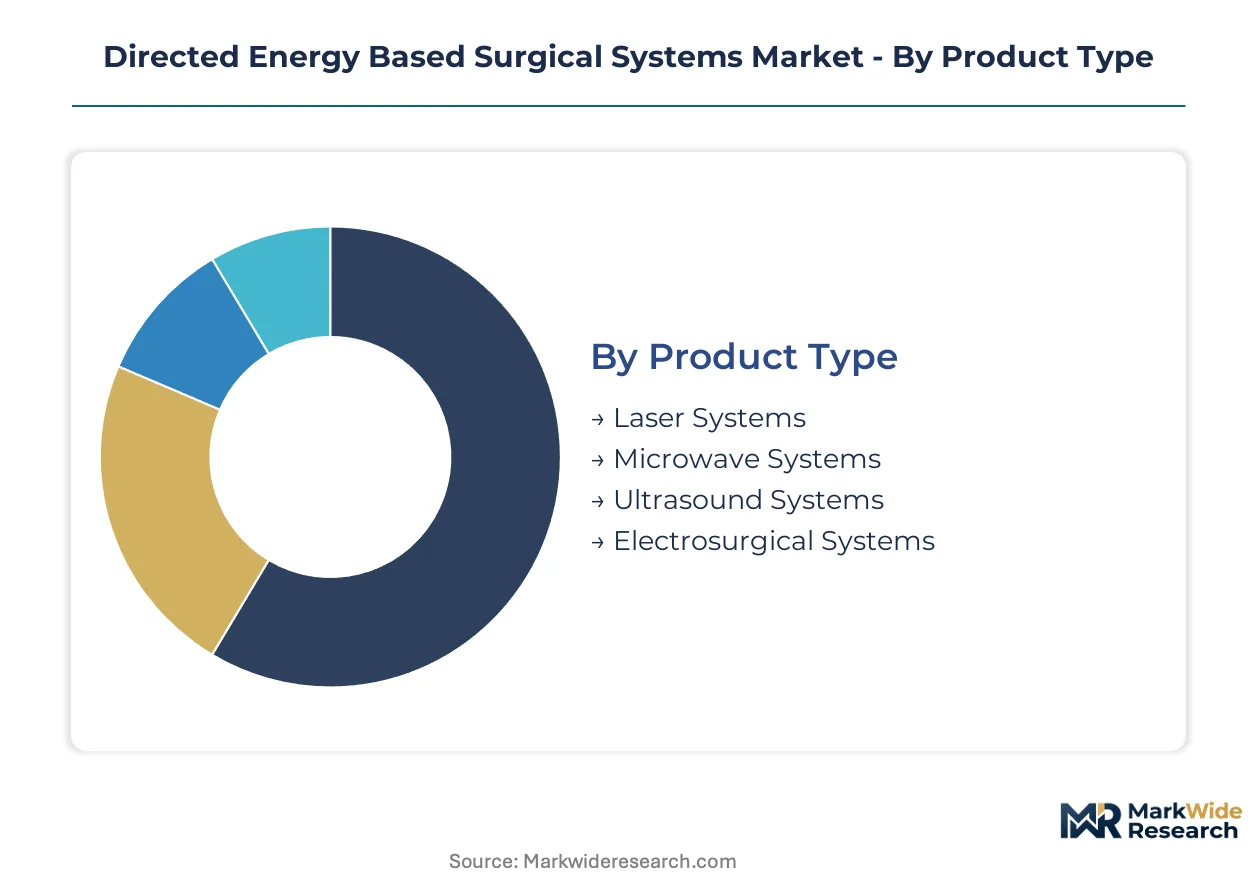
Understanding the distinct segments within the directed energy based surgical systems market reveals varied adoption patterns and technological preferences across clinical settings. This granular view helps stakeholders align product development and market access strategies with specific end-user requirements and procedural demands.
Product Type:
The spectrum of surgical applications dictates the specific energy delivery modality employed by medical professionals.
- Laser Systems:These devices utilize focused light energy for precise cutting, ablation, and coagulation of tissue, minimizing collateral damage. Demand concentrates in ophthalmology and dermatology due to their unparalleled precision in delicate procedures.
- Electrosurgical Systems:These systems employ high-frequency electrical currents to cut tissue and control bleeding, offering versatility across numerous surgical specialties. Johnson & Johnson Services maintains a dominant market position with a broad portfolio in this segment.
- Microwave Systems:Microwave energy generates heat within tissues, primarily used for tumor ablation in oncology applications. These systems provide a targeted approach for thermal destruction of diseased cells.
- Ultrasound Systems:High-intensity focused ultrasound (HIFU) systems deliver acoustic energy for non-invasive tissue ablation, particularly in prostate and uterine fibroid treatments.
Established volume favors Laser Systems; emerging adoption favors Electrosurgical Systems.
Technology:
Technological advancements drive the efficacy and precision of directed energy systems, influencing their clinical utility across diverse surgical fields.
- Fiber Laser:This technology delivers highly precise and controllable laser energy through flexible optical fibers, expanding its application beyond ophthalmology into neurology. Continuous improvements in Fiber Laser technology meet clinical demand for less invasive surgical options.
- High-Intensity Focused Ultrasound:HIFU uses focused sound waves to ablate tissue non-invasively, offering a significant advantage for procedures requiring minimal patient discomfort. The broader healthcare shift towards minimally invasive surgery accelerates its adoption.
- CO2 Laser:Carbon dioxide lasers are widely used in dermatological and ENT surgeries for their excellent tissue cutting and vaporization capabilities. This technology provides broad utility in surface tissue removal.
- Radiofrequency:Radiofrequency ablation employs electrical currents to generate heat for tissue destruction, commonly used in cardiology for arrhythmia and in oncology for tumor treatment.
Technology refinement in Fiber Laser systems maintains a strong market presence, while High-Intensity Focused Ultrasound gains share through its non-invasive benefits.
Application:
The clinical application segment highlights where directed energy surgical systems are most critically deployed, reflecting specific disease burdens and treatment paradigms.
- Ophthalmology:Directed energy systems, particularly laser systems, are indispensable for high-precision eye procedures such as refractive surgery and cataract removal. The rising application of these systems in ophthalmology drives significant market expansion.
- Oncology:These systems are used for precise tumor removal and ablation, with AI-powered real-time tissue analysis enhancing margin detection during resections. Advanced surgical centers increasingly adopt these systems for improved patient outcomes.
- Dermatology:Laser and electrosurgical systems treat various skin conditions, including lesion removal, skin resurfacing, and vascular treatments. Precision energy delivery minimizes scarring and improves cosmetic results.
- Urology:Directed energy devices address conditions like benign prostatic hyperplasia and kidney stones, offering minimally invasive solutions. Boston Scientific Corporation specializes in these devices for urology applications.
Ophthalmology procedures represent a stable revenue base, while Oncology applications are expanding most quickly.
End User:
The end-user segment delineates the primary healthcare facilities adopting directed energy surgical systems, each with distinct procurement and operational characteristics.
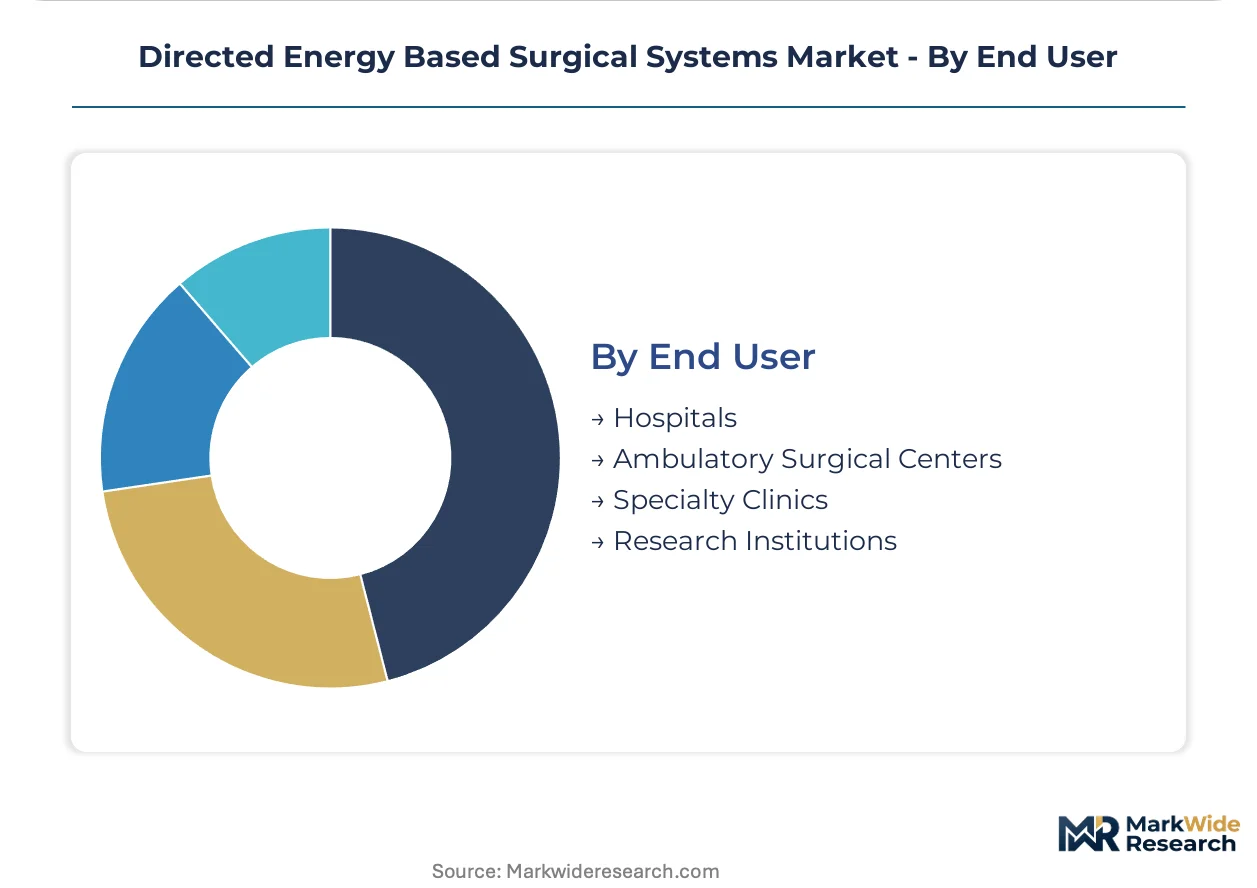
- Hospitals:These institutions remain the largest end user segment, driven by their comprehensive surgical departments, high patient volumes, and capacity for advanced capital equipment. Hospitals typically manage complex procedures requiring sophisticated energy systems.
- Ambulatory Surgical Centers:ASCs represent the fastest-growing channel for these procedures, benefiting from lower overheads and a focus on outpatient surgeries. A shift toward flexible, procedure-based consumption models aids ASC adoption.
- Specialty Clinics:These clinics focus on specific medical areas like ophthalmology or dermatology, often requiring specialized directed energy systems. They cater to a targeted patient demographic.
- Research Institutions:Academic and private research institutions utilize directed energy systems for developing new surgical techniques and advancing medical science. These entities drive innovation in the field.
Hospitals command the largest segment share, with Ambulatory Surgical Centers exhibiting the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for directed energy surgical systems concentrates in developed healthcare markets with robust hospital infrastructure and expanding ambulatory surgical centers. These regions prioritize advanced medical technologies for minimally invasive procedures and improved patient outcomes. Procurement patterns are shifting towards flexible consumption models.
United States
The United States market sees high demand for directed energy systems due to patient preference for minimally invasive procedures and significant investment in AI-powered platforms. US FDA premarket approval processes govern device market entry. Medical technology hubs like Boston drive innovation in surgical robotics.
Germany
Germany exhibits robust demand for directed energy systems, driven by its advanced healthcare infrastructure and clinical preference for less invasive surgical options. Compliance with the EU's Medical Device Regulation (MDR) mandates rigorous clinical data for market access. The Rhine-Main region fosters innovation in precision surgical instruments.
Japan
Japan's market benefits from an aging demographic requiring high-precision procedures and continuous technology refinement. The Pharmaceuticals and Medical Devices Agency (PMDA) enforces strict standards for device approval and post-market safety. Research institutions in Tokyo actively develop advanced fiber laser applications.
China
China presents significant growth as its healthcare infrastructure modernizes and oncology applications expand rapidly. Compliance with China's NMPA standards is mandatory for market entry. Medical technology parks in Shanghai are becoming centers for developing advanced surgical platforms.
India
India offers substantial opportunities for directed energy systems, driven by new hospital construction and a growing patient base. The Central Drugs Standard Control Organization (CDSCO) oversees medical device approvals, balancing safety with market access. Bengaluru's technology ecosystem supports innovative, affordable surgical technologies.
Directed Energy Based Surgical Systems Market Key Industry Players
Channel-controlling players compete with product-specialist players across the directed energy surgical systems market, creating a dynamic competitive landscape. The market exhibits a tiered structure, characterized by the presence of large diversified medical technology companies alongside niche innovators. Strategic archetypes include integrated solution providers offering broad portfolios and specialized device manufacturers focusing on specific clinical applications. Dominant competitive moves involve strategic partnerships for technology co-development and continuous portfolio diversification to enter new surgical specialties.
Diversified medical technology firms such as Johnson & Johnson Services sustain a strong market presence through extensive product portfolios covering multiple surgical specialties and global distribution networks. Companies like Medtronic occupy a position of innovation, leveraging advanced robotics and R&D capabilities to enhance their electrosurgical system offerings, particularly in the realm of real-time tissue analysis. Boston Scientific Corporation exemplifies a focused strategy, specializing in minimally invasive devices tailored for urology and oncology applications, addressing specific clinical needs effectively and expanding patient access.
| Leading Market Players |
|---|
| Bausch & Lomb Incorporated |
| Medtronic |
| Abbott Laboratories |
| Biolase |
| Johnson & Johnson Services |
| Stryker Corporation |
| Olympus Corporation |
| Boston Scientific Corporation |
| Apyx Medical |
| Others |
Cost & Logistics Intelligence
Suez Canal transit costs influence the global supply of specialized optical fibers, concentrating component availability and impacting the price points for advanced laser systems. This cost structure differentiates market offerings based on regional manufacturing proximity.
Pricing Analysis
Cost-plus contracts, often indexed to raw material prices like rare-earth elements, govern the procurement of directed energy systems. Price differentiation stems from FDA/NMPA certification levels and bundled after-sales service packages. Pricing softness runs through the Ambulatory Surgical Center segment, driven by their lower overhead models. Hospitals, requiring comprehensive support, exhibit less price sensitivity.
Supply Chain Analysis
Export control regimes, particularly those impacting advanced laser components, limit the free flow of critical technologies globally. Supply for high-precision directed energy systems centers in Germany, Japan, and the USA. The market relies on specialized optical fibers and rare-earth elements for laser and ultrasound systems. Single-source vulnerability for these advanced components poses a significant structural risk. Downstream, a direct sales model dominates for large hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The directed energy based surgical systems market is entering an early-cycle expansion phase, driven by the increasing penetration of minimally invasive procedures across developed healthcare economies. Technology refinement in Fiber Laser systems accelerates this adoption.
For Market Incumbents:
Harden existing hospital channel control by integrating AI-powered real-time tissue analysis into next-generation electrosurgical platforms, countering specialized device manufacturers. Incumbents must also secure long-term supply agreements for specialized optical fibers and rare-earth elements to mitigate single-source vulnerabilities. Investing in advanced robotics R&D will enhance system efficacy and maintain competitive advantage against emerging threats.
For New Entrants and Emerging Players:
Establish a beachhead in underpenetrated clinical applications like cardiology for arrhythmia ablation or neurosurgery for precise tumor removal. New entrants can target Ambulatory Surgical Centers in the United States, leveraging flexible, procedure-based consumption models to lower upfront financial risk for providers. Focus on specialized, cost-effective solutions that offer clear clinical advantages in these niche areas.
For Investors and Strategic Acquirers:
The EU's Medical Device Regulation (MDR) reshapes the acquisition landscape, favoring companies with robust clinical data and post-market surveillance systems. The long-term viability of this market remains strong, driven by aging populations and the continuous demand for minimally invasive treatments. Investors should target niche innovators specializing in AI-enabled tissue analysis or advanced Fiber Laser applications. Successful FDA premarket approval for novel AI-integrated systems represents a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Integration for Real-time Feedback | Enhances surgical precision and reduces re-operation rates in oncology procedures. |
| Expansion into Emerging Markets | Captures new patient volumes and modernizing healthcare infrastructure in regions like the Middle East. |
| Development of HIFU for New Applications | Broadens non-invasive treatment options for conditions beyond prostate and uterine fibroids. |
| Compliance with MDR and NMPA Standards | Ensures continued market access and strengthens trust in product safety and efficacy. |
| Flexible Consumption Model Adoption | Lowers capital barriers for Ambulatory Surgical Centers, accelerating technology adoption. |
Research Approach
Initial hypotheses were tested against primary input from surgeons, biomedical engineers, hospital procurement managers, and regulatory affairs specialists, then refined through an iterative process. This involved triangulating insights from these interviews with extensive secondary validation. Secondary data sources included US FDA premarket approval databases, EU MDR clinical data reports, NMPA approval documents, and medical device company SEC filings. A bottom-up data collection and top-down market sizing approach ensured robust market estimates.
Demand-supply balance models projected market trajectory across the analysis window, considering both clinical need and manufacturing capacity. Segmentation dimensions modeled included Product Type, Technology, Application, End User, and regional regulatory cluster. Compound annual growth rates were derived from historical trends and anticipated shifts in surgical procedure volumes and healthcare infrastructure investment. This framework accounts for both technological innovation and market penetration rates.
Sensitivities concentrate around unforeseen regulatory changes and major technological breakthroughs impacting energy delivery mechanisms. Forecasts reflect assumptions regarding clinical adoption rates and healthcare spending priorities. Material shifts in US FDA or EU MDR guidance would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Urinary Catheters Market
Medical Devices
Robotic Surgical Procedures Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
Cytology Brush Market
Medical Devices
Osmotic Pumps Market
Medical Devices
Biomedical Temperature Sensors Market
Medical Devices
Spinal Trauma Devices Market
Medical Devices
Global Artificial Organ Market
Medical Devices
Phlebotomy Equipments Market
Medical Devices
Endoscope Procedure Kits Market
Medical Devices
Nasal Atomizer Devices Market
Medical Devices
Global Hemostasis Valves Market
Medical Devices
Europe Single-Use Medical Device Reprocessing Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Fluidics for Preclinical Market
Medical Devices
Transradial Closure Devices Market