
 Intraocular Lens (IOL) Market | 2026-2036
Intraocular Lens (IOL) Market Size, Share, and Industry Trends Forecast 2026-2036
Intraocular Lens (IOL) Market Intelligence
The proficiency of ophthalmic surgeons in implanting advanced presbyopia-correcting lenses is redrawing the competitive landscape for premium IOLs. This specialized surgical skill set directly influences adoption rates of new technologies. Alcon Inc. leverages its extensive surgeon training programs to support its portfolio, while Johnson & Johnson Vision Care, Inc. competes through its focus on clinical data and product innovation. Bausch + Lomb Corporation sustains its market position with a broad offering across different IOL categories.
An intraocular lens is a medical implant designed to replace the eye's natural crystalline lens during cataract surgery. These lenses are typically made from biocompatible materials like hydrophobic acrylic and are engineered to specific dioptric powers to correct vision. While monofocal lenses remain the standard for cataract surgery, the multifocal and toric product segments represent the fastest-growing categories. These premium options address presbyopia and astigmatism, expanding the procedure's scope beyond simple cataract removal.
Market access for new IOL technologies is governed by stringent regulatory approvals. The U.S. FDA, Europe's EMA, and China's NMPA mandate extensive clinical trials to demonstrate both safety and efficacy before granting market authorization. These regulatory hurdles directly influence product development timelines and R&D investment strategies. Stakeholders must now navigate the evolving reimbursement landscape for premium lenses that offer superior visual outcomes.
Market Dynamics
The central force shaping the IOL market is the bifurcation of surgical practice between standard cataract removal and refractive cataract surgery. This split is driven by patient demand for spectacle independence, creating distinct segments for basic and premium, vision-correcting lenses.
Growth Catalysts
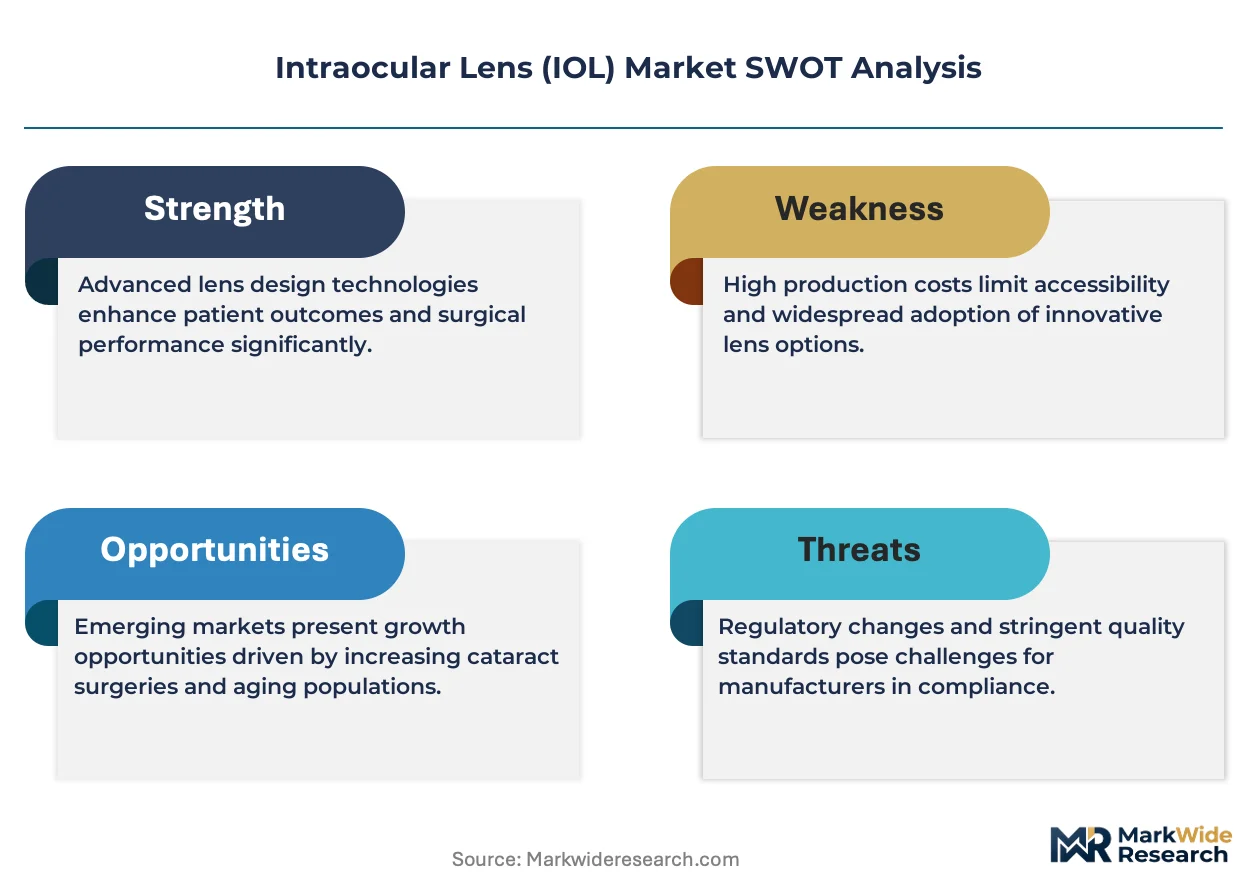
- Advanced IOL Technology:The commercialization of Extended Depth of Focus (EDOF) and trifocal lenses provides surgeons with tools to correct presbyopia, expanding the procedure's value beyond simple cataract treatment and driving patient demand for premium outcomes.
- Demographic Shifts in Asia:An aging population and rising healthcare expenditure in countries like China and India are increasing the volume of cataract surgeries, creating a large and sustained patient pool for IOL implantation.
- Surgical Site Migration:The ongoing shift of cataract procedures from hospital outpatient departments to more efficient, high-volume ambulatory surgical centers (ASCs) improves patient access and increases the total number of surgeries performed annually.
Market Restraints
- Reimbursement Hurdles:Inconsistent or non-existent reimbursement policies for premium presbyopia-correcting and toric IOLs in many healthcare systems limit patient access and surgeon adoption, confining these technologies to a self-pay market.
- Stringent Regulatory Pathways:Extensive and costly clinical trial requirements from bodies like the U.S. FDA and Europe's EMA delay the market entry of new IOL technologies and increase R&D expenditure for manufacturers.
- Post-Operative Visual Disturbances:A subset of patients receiving multifocal IOLs experience visual phenomena such as glare, halos, and reduced contrast sensitivity, which can lead to surgeon hesitancy in recommending these premium lenses.
Strategic Opportunities
- Underserved International Markets:Large populations in Latin America and Southeast Asia with growing middle classes and developing healthcare infrastructure represent significant untapped markets for both standard and premium IOL procedures.
- Smart IOL Development:The integration of microelectronics and sensors into IOLs offers a pathway to new functionalities, such as continuous intraocular pressure monitoring for glaucoma management, creating a new high-value product category.
- Adjustable Lens Platforms:Light-adjustable lenses that allow for post-operative, non-invasive refinement of the lens's power give surgeons a tool to achieve greater refractive precision, addressing residual errors and improving patient satisfaction.
Industry Challenges
- Specialized Surgeon Training:The successful implantation of premium toric and multifocal IOLs requires advanced surgical skills, patient selection acumen, and management of patient expectations, creating a training bottleneck that limits widespread adoption.
- Clinical Evidence Generation:Demonstrating the superiority of premium lenses to secure favorable reimbursement and drive adoption requires long-term, large-scale clinical studies, which are both time-consuming and capital-intensive to conduct.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intraocular Lens (IOL) Market |
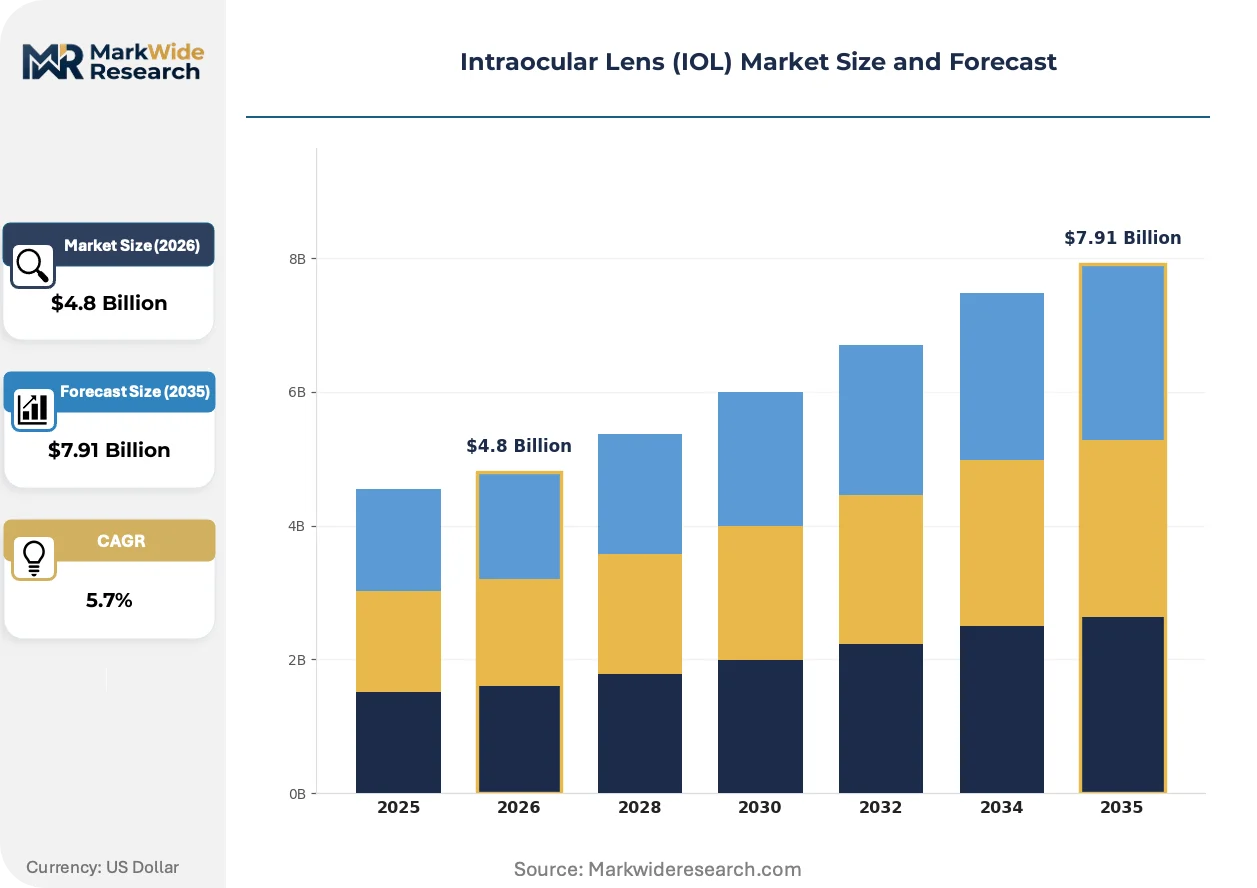
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monofocal, Multifocal, Toric, Accommodating, Extended Depth of Focus Technology: Hydrophobic Acrylic, Hydrophilic Acrylic, Silicone, PMMA, Collamer Application: Cataract Surgery, Refractive Lens Exchange, Presbyopia Correction, Aphakia Treatment End User: Ophthalmology Clinics, Specialty Eye Hospitals, Ambulatory Surgical Centers, Optical Retailers |
| Companies Covered | Carl Zeiss Meditec AG, Rayner Intraocular Lenses Limited, Alcon Inc., Lenstec, Inc., STAAR Surgical Company, Johnson & Johnson Vision Care, Inc., Hoya Surgical Optics, Inc., PhysIOL SA, Bausch + Lomb Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intraocular Lens (IOL) Market Strategic Shifts & Innovations
Product evolution is defined by the pursuit of a wider range of continuous vision with fewer optical compromises. This drive for spectacle independence is influencing IOL material science, optical design, and the surgical techniques required for implantation.
Extended Depth of Focus (EDOF) technology utilizes advanced optical principles to create a single elongated focal point, providing a continuous range of high-quality vision. Ophthalmic surgeons in private practices and ambulatory surgical centers are increasingly adopting EDOF lenses for patients who desire functional vision at multiple distances. This technology is fragmenting the premium lens category away from discrete focal points, characteristic of older multifocal designs, toward more customized and seamless visual experiences.
Regulatory frameworks are intensifying their focus on post-market clinical follow-up. The European Union's Medical Device Regulation (MDR) mandates more rigorous collection of real-world performance and safety data for all medical implants, including IOLs. This forces manufacturers to invest in long-term registries and surveillance systems to maintain their CE marking. The premium IOL segments, which make specific claims about superior visual performance, face the highest burden of proof under these stricter evidence requirements.
A significant behavioral shift is occurring as patients become more active participants in the selection of their IOL. Driven by online resources and direct-to-consumer marketing, patients arrive at consultations with greater awareness of premium options that can correct astigmatism and presbyopia. This disrupts the traditional surgeon-directed model, requiring clinics to adapt their patient education and consultation processes. This trend is most visible in developed markets across North America and Europe where patients often have a financial stake in the decision through co-pays for premium technologies.
Intraocular Lens (IOL) Market Segmentation
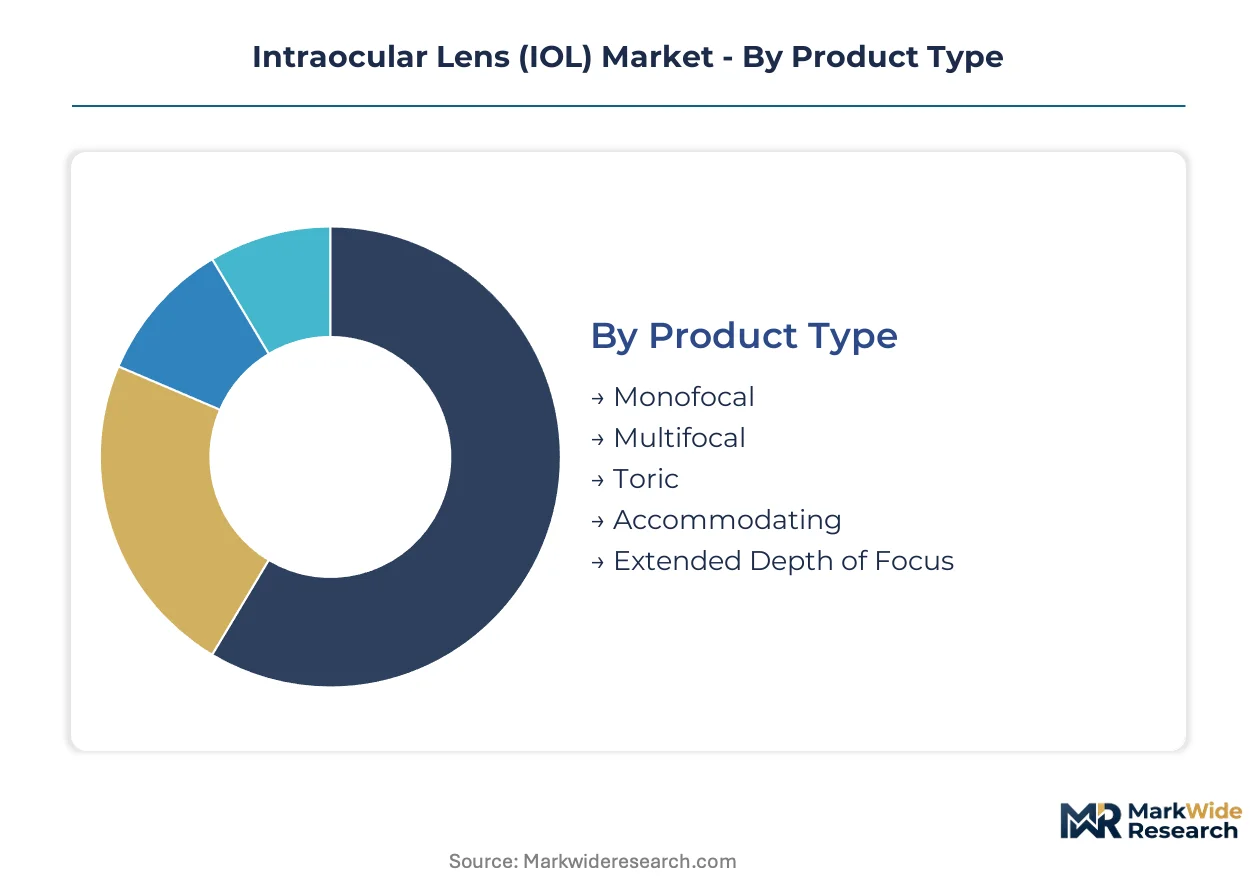
The Intraocular Lens (IOL) market bifurcates across product types, technologies, applications, and end-user settings. This granular segmentation illuminates varied demands and clinical requirements driving innovation and adoption within ophthalmic surgery. Understanding these segments is crucial for manufacturers to align product development with evolving patient needs.
Product Type:
Margin pools within the IOL product type category sit with advanced lenses offering spectacle independence. These premium options command higher pricing due to their complex optical designs and enhanced patient outcomes.
- Multifocal:These lenses feature multiple focal points, enabling patients to see clearly at near, intermediate, and far distances. Demand concentrates in developed markets like the United States for presbyopia correction.
- Extended Depth of Focus:EDOF lenses create an elongated focal point, providing a continuous range of vision from intermediate to far. Adoption accelerates in ambulatory surgical centers across Europe to minimize visual disturbances.
- Monofocal:Standard monofocal IOLs provide clear vision at a single focal distance. They remain the most frequently implanted IOL type for basic cataract removal globally.
- Toric:Toric IOLs are specifically designed to correct pre-existing astigmatism in patients undergoing cataract surgery. Patient demand rises in China, targeting improved uncorrected visual acuity.
- Accommodating:Accommodating IOLs attempt to mimic the eye's natural accommodation by changing shape or position. Their market penetration remains limited due to design complexities.
Monofocal lenses hold installed capacity due to widespread use in standard cataract procedures. Extended Depth of Focus lenses are rotating up the share rankings, reflecting patient preference.
Technology:
Supply concentration in IOL technology centers on hydrophobic acrylic materials, which offer excellent biocompatibility and long-term stability. Manufacturers prioritize these materials for their proven performance and widespread acceptance.
- Hydrophobic Acrylic:These lenses are made from a water-repelling acrylic polymer, known for their excellent optical clarity and resistance to posterior capsule opacification. They are the dominant material choice for IOLs implanted worldwide.
- Hydrophilic Acrylic:Composed of water-absorbing acrylic, these lenses are softer and more flexible, allowing for smaller incision sizes during implantation. Demand for hydrophilic acrylic lenses is notable in Asian markets.
- Silicone:Silicone IOLs offer good optical properties and are foldable for small incision surgery.
- PMMA:Polymethyl methacrylate (PMMA) lenses represent an older generation of IOL technology, requiring larger incisions due to their rigid nature.
- Collamer:Collamer is a biocompatible collagen copolymer primarily used in phakic IOLs, implanted without removing the natural lens.
Hydrophobic Acrylic maintains its foundational position in IOL manufacturing. Hydrophilic Acrylic shows a steeper expansion trajectory.
Application:
Demand concentration within IOL applications is heavily weighted towards the treatment of age-related vision impairments. Cataract surgery represents the largest segment, driven by global demographic shifts and increasing life expectancies.
- Cataract Surgery:This application involves replacing the eye's clouded natural lens with an artificial IOL to restore clear vision. It constitutes the vast majority of IOL procedures, with millions performed annually.
- Presbyopia Correction:This application utilizes advanced IOLs, such as multifocal or EDOF lenses, to restore near and intermediate vision, reducing spectacle dependence. Patient demand is strong in North America.
- Refractive Lens Exchange:RLE involves replacing a clear natural lens with an IOL to correct refractive errors like myopia, hyperopia, or astigmatism. This elective procedure targets younger patients.
- Aphakia Treatment:Aphakia refers to the absence of the natural crystalline lens, often from trauma or congenital conditions. IOL implantation is critical for restoring vision.
Cataract Surgery remains the undisputed volume leader. Presbyopia Correction is gaining share fastest, reflecting patient desire for spectacle independence.
End User:
Volume throughput for IOL procedures increasingly shifts towards specialized facilities optimized for ophthalmic care. These environments prioritize efficiency and patient flow, influencing IOL distribution channels.
- Ambulatory Surgical Centers:ASCs are dedicated outpatient facilities performing high volume cataract and other ophthalmic surgeries with greater efficiency. The United States sees significant growth in IOL procedures within ASCs.
- Specialty Eye Hospitals:These hospitals offer comprehensive ophthalmic services, including complex IOL implantations and managing associated comorbidities. They serve as referral centers for complicated cases in India.
- Ophthalmology Clinics:Clinics primarily focus on patient consultations, pre-operative assessments, and post-operative follow-up care. They play a crucial role in patient education.
- Optical Retailers:While not primary implanters, some optical retailers may offer post-operative eyewear or provide information on IOL options. Their direct involvement is minimal.
Specialty Eye Hospitals retain their role for complex cases. Ambulatory Surgical Centers are climbing the fastest in terms of procedural volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. FDA’s rigorous approval process influences global intraocular lens market dynamics. This regulatory environment shapes product innovation and market entry strategies for manufacturers worldwide. Demand for advanced IOLs is intensifying across diverse international markets.
United States
Patient demand for spectacle independence drives the premium IOL segment across the nation. The Centers for Medicare & Medicaid Services (CMS) reimbursement policies significantly impact premium lens adoption in ambulatory surgical centers. Major ophthalmic device manufacturers concentrate R&D efforts in California's medical technology hubs.
China
A large and aging population fuels substantial demand for cataract surgery in Chinese provinces. The National Medical Products Administration (NMPA) oversees product registration and clinical trial requirements for IOLs. Shanghai and Beijing are key centers for IOL manufacturing and distribution.
Germany
High healthcare standards and an aging demographic sustain a strong market for IOLs throughout Germany. The European Medicines Agency (EMA) and EU MDR regulations govern market access for advanced ophthalmic implants. Bavaria hosts several specialized medical device companies focusing on optical solutions.
Japan
Patient preference for precision and quality shapes the IOL market, especially for premium lenses. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures strict safety and efficacy standards for IOL products. Tokyo's medical technology sector sees continuous innovation in IOL materials.
India
The growing middle class and increasing healthcare expenditure boost cataract surgery volumes across India. The Central Drugs Standard Control Organization (CDSCO) regulates IOL imports and local manufacturing. Bengaluru is emerging as a hub for ophthalmic device production and R&D.
Intraocular Lens (IOL) Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the intraocular lens market. The market exhibits a tiered structure, with established multinational corporations alongside specialized innovators and regional manufacturers. Strategic archetypes include premium lens developers focusing on advanced optical designs, volume-focused providers emphasizing accessibility, and niche technology specialists. Portfolio diversification into complementary ophthalmic solutions and strategic partnerships with surgical centers are dominant competitive moves.
On the premium-tier vector, Alcon Inc. exemplifies a multinational corporation with extensive surgeon training programs and a broad product portfolio. Johnson & Johnson Vision Care, Inc. occupies a position among innovators, anchoring product innovation through rigorous clinical data and advanced optical designs. Furthermore, Bausch + Lomb Corporation represents a diversified market presence with a broad offering across different IOL categories. These companies collectively demonstrate the industry's focus on both advanced technology development and comprehensive market penetration, setting benchmarks for product quality and patient outcomes.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Rayner Intraocular Lenses Limited |
| Alcon Inc. |
| Lenstec, Inc. |
| STAAR Surgical Company |
| Johnson & Johnson Vision Care, Inc. |
| Hoya Surgical Optics, Inc. |
| PhysIOL SA |
| Bausch + Lomb Corporation |
| Others |
Cost & Logistics Intelligence
Specialized IOL manufacturing scale shapes both supply concentration and price floors, particularly for advanced lens designs. This scale enables cost efficiencies that reinforce the market position of established manufacturers, influencing pricing across various product tiers.
Pricing Analysis
Geographic price spreads for intraocular lenses reflect varied reimbursement structures and patient willingness to pay for spectacle independence. The market operates on a value-based pricing model, with premium-mid-economy pricing differentiation evident across product types. Price differentiation drivers include complex optical designs, enhanced patient outcomes, and regulatory approval status. Pricing pressure stems from inconsistent reimbursement policies for premium lenses in many healthcare systems. Patients seeking premium IOLs in self-pay markets demonstrate high price sensitivity, while healthcare systems prioritize cost-effectiveness for standard monofocal IOLs.
Supply Chain Analysis
China, the United States, and Germany anchor IOL manufacturing and distribution, reflecting both demand centers and R&D hubs. The supply chain draws from specialized biocompatible materials like hydrophobic acrylic and hydrophilic acrylic polymers. Supply chain risk arises from stringent regulatory pathways, which delay market entry and increase R&D expenditure. Distribution runs through a network of specialized facilities, including ambulatory surgical centers and specialty eye hospitals, which manage high-volume IOL procedures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intraocular lens market presents a defensive-moat story for established players, largely due to regulatory entrenchment and the significant switching costs associated with surgeon training on new technologies.
For Market Incumbents: Secure leadership in advanced IOL technology by investing heavily in R&D for smart and adjustable lenses. Diversify product portfolios to address both premium and standard segments, mitigating threats from niche innovators. Leverage extensive surgeon training programs to maintain adoption rates for new products, reinforcing market share against emerging competitors.
For New Entrants and Emerging Players: Anchor in underserved international markets, particularly Latin America and Southeast Asia, where healthcare infrastructure is developing. Target the EDOF and adjustable lens segments, offering novel solutions for presbyopia correction and greater refractive precision. A go-to-market angle focused on strong clinical evidence generation and targeted surgeon education can drive initial adoption in these regions.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized innovators with strong intellectual property in advanced optical designs and materials science. Long-term viability for investments hinges on companies demonstrating robust pipelines for next-generation IOLs, such as smart or adjustable platforms. A signal to watch is the evolution of reimbursement policies for premium lenses in major markets, which could unlock significant growth potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Optical Design Investment | Manufacturers gain competitive advantage through superior visual outcomes for patients. |
| Surgeon Training Program Expansion | Companies drive adoption of complex premium IOLs by enhancing ophthalmic surgeon proficiency. |
| Regulatory Pathway Optimization | Firms accelerate market entry for new IOL technologies across key geographies like the EU and US. |
| Targeted Emerging Market Entry | Businesses access large, untapped patient populations in regions with rising healthcare expenditure. |
| Biocompatible Material Innovation | Developers improve IOL safety and long-term performance, reducing post-operative complications. |
Research Approach
The analysis maps intraocular lens product types, technologies, applications, and end-user settings, each validated through extensive primary interviews with ophthalmic surgeons, R&D directors, and regulatory affairs specialists. This approach combined insights from industry stakeholders with secondary validation from sources including FDA filings, EMA submissions, NMPA guidelines, and clinical trial registries. The research employed both bottom-up and top-down triangulation to ensure data accuracy and comprehensive market coverage.
Outputs were validated against external benchmarks to ensure the consistency of the analytical framework across the analysis window. The model segmented the market by product types like multifocal and EDOF lenses, material technologies such as hydrophobic acrylic, application areas including cataract surgery, and end-user facilities like ambulatory surgical centers. Compounded annual growth rates were derived from historical data and projected market drivers, with demographic shifts and healthcare expenditure trends serving as key forecast inputs.
Decision-makers should treat outputs as directional under current reimbursement policies and regulatory frameworks; material deviation would warrant model refresh. Forecasts reflect assumptions regarding patient demand for spectacle independence and the pace of technological innovation in IOLs. Recalibration cycles align with material shifts in regulatory approvals or major demographic trends.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Surgical Tourniquets Market
Medical Devices
Knee Reconstruction Devices Market
Medical Devices
Global Structural Heart Devices Market
Medical Devices
Single Lead ECG Equipment Market
Medical Devices
Global Pulse Oximetry Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
Nanotechnology in Medical Devices Market
Medical Devices
Root Canal Irrigators Market
Medical Devices
Asia-Pacific Vaginal Slings Market
Medical Devices
Oxygen Delivery Units Market
Medical Devices
Brazil Clear Aligners Market
Medical Devices
Global Medical Device Cleaning Market
Medical Devices
Internal Nasal Dilators Market
Medical Devices
Ophthalmic Microscopes Market
Medical Devices
Prosthetic Disc Nucleus Market