
 Sinus Implants Market | 2026-2036
Sinus Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Sinus Implants Market Analytics
Supplier base rationalization is consolidating around fewer contract manufacturers with ISO 13485 certification and dedicated cleanroom capacity for absorbable polymers. Medtronic leverages captive resin compounding to secure supply continuity for its biodegradable stent portfolios. Stryker Corporation anchors North American hospital contracting through integrated sinus navigation and implant bundles. Smith & Nephew competes on ambulatory surgical center access with streamlined procedure kits that reduce OR turnover time.
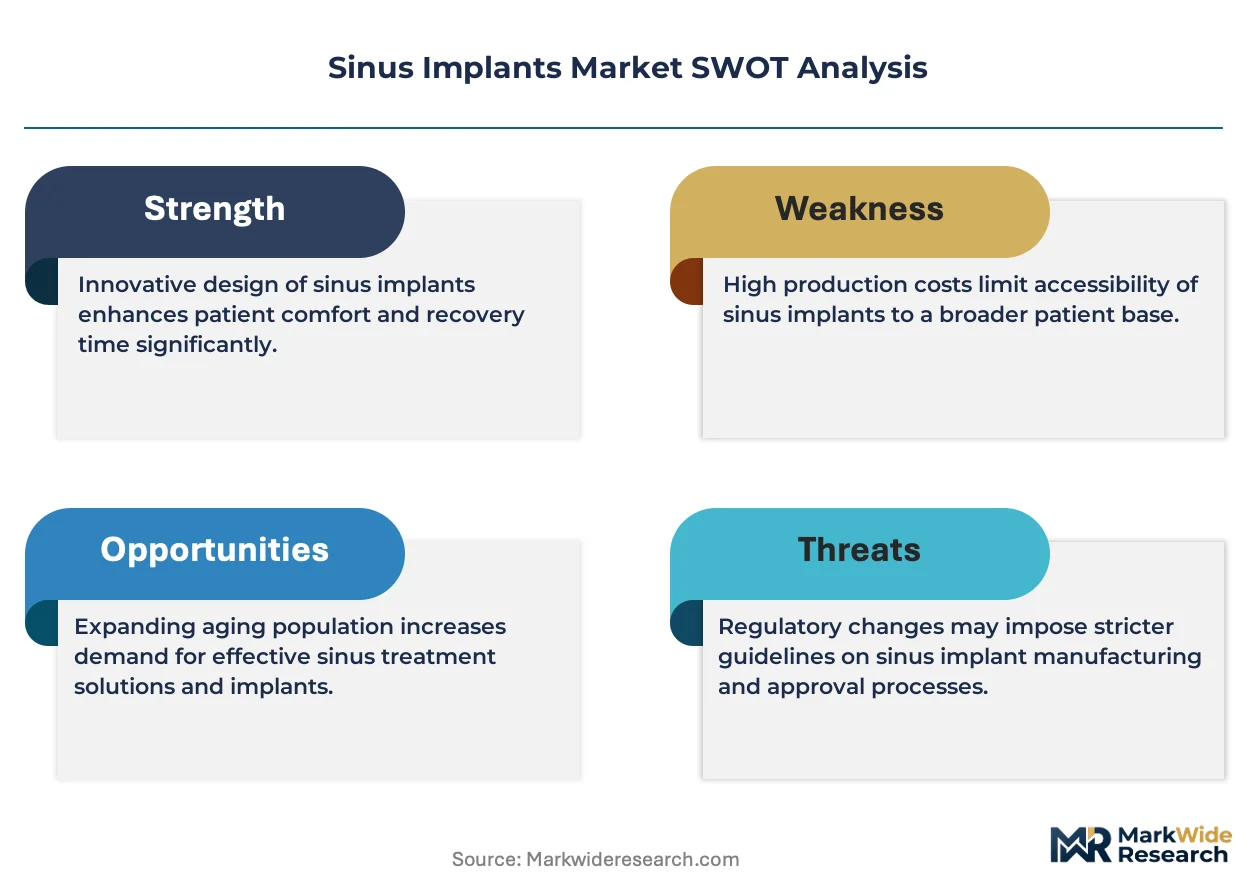
Sinus implants are sterile, anatomically conformable devices—typically composed of bioabsorbable polymers, silicone, or porous polyethylene—inserted endoscopically to maintain ostial patency following functional endoscopic sinus surgery or to deliver corticosteroids locally. Drug-eluting variants incorporate mometasone furoate or fluticasone propionate into poly(lactic-co-glycolic acid) matrices that elute over 30–90 days, reducing polyp recurrence and revision surgery rates. Balloon sinus dilation systems and drug-eluting implants now capture the majority of new product development investment, while standalone non-drug biodegradable spacers face margin compression as reimbursement shifts toward outcomes-validated technologies. Silicone and polymer material segments retain volume leadership, though titanium-reinforced expandable implants command premium pricing in complex revision cases.
FDA 510(k) and PMA pathways govern US market entry, with the agency intensifying scrutiny of real-world evidence for drug-device combination products. EMA MDR compliance and CE marking requirements under the EU Medical Device Regulation are extending timelines for European launches, particularly for novel biodegradable formulations. Japan's PMDA demands localized clinical data for absorbable implants, creating a bottleneck for foreign manufacturers. Stakeholders must monitor evolving payer evidence requirements for drug-eluting platforms as health technology assessment bodies in major markets tighten reimbursement conditionalities.
Market Dynamics
Drug-eluting implant platforms are compressing reimbursement bandwidth toward outcomes-validated technologies, forcing standalone biodegradable spacers into commodity positioning while hospital systems consolidate purchasing around bundled navigation-implant contracts.
Growth Catalysts
- Drug-Eluting Formulations:Poly(lactic-co-glycolic acid) matrices releasing mometasone furoate over 30–90 days reduce polyp recurrence rates and revision surgery frequency, driving hospital adoption.
- Japan PMDA Pathways:Localized clinical data requirements for absorbable implants create structured entry barriers that reward committed market entrants with durable positioning.
- Ambulatory Surgical Centers:Streamlined procedure kits with reduced OR turnover time capture volume migration from inpatient settings.
Market Restraints
- Absorbable Polymer Supply Concentration:ISO 13485-certified contract manufacturers with dedicated cleanroom capacity operate limited facilities, creating single-source vulnerability.
- FDA PMA Scrutiny:Intensified real-world evidence requirements for drug-device combination products extend regulatory timelines and development costs.
- Balloon Dilation Substitution:Standalone sinus dilation systems compete for overlapping indications without implant-related reimbursement complexity.
Strategic Opportunities
- German Outpatient Reimbursement:Evolving ambulatory procedure codes create pathway expansion for office-based sinus interventions.
- Titanium-Reinforced Expandables:Premium-priced complex revision cases remain underserved by current biodegradable portfolios.
- EMA MDR Compliance Services:Extended CE marking timelines under EU Medical Device Regulation create advisory and regulatory outsourcing demand.
Industry Challenges
- ENT Specialist Density Variability:Regional concentration of trained surgeons limits procedural volume scaling in underserved territories.
- Health Technology Assessment Alignment:Payer evidence requirements for drug-eluting platforms diverge across national assessment bodies, complicating parallel submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sinus Implants Market |
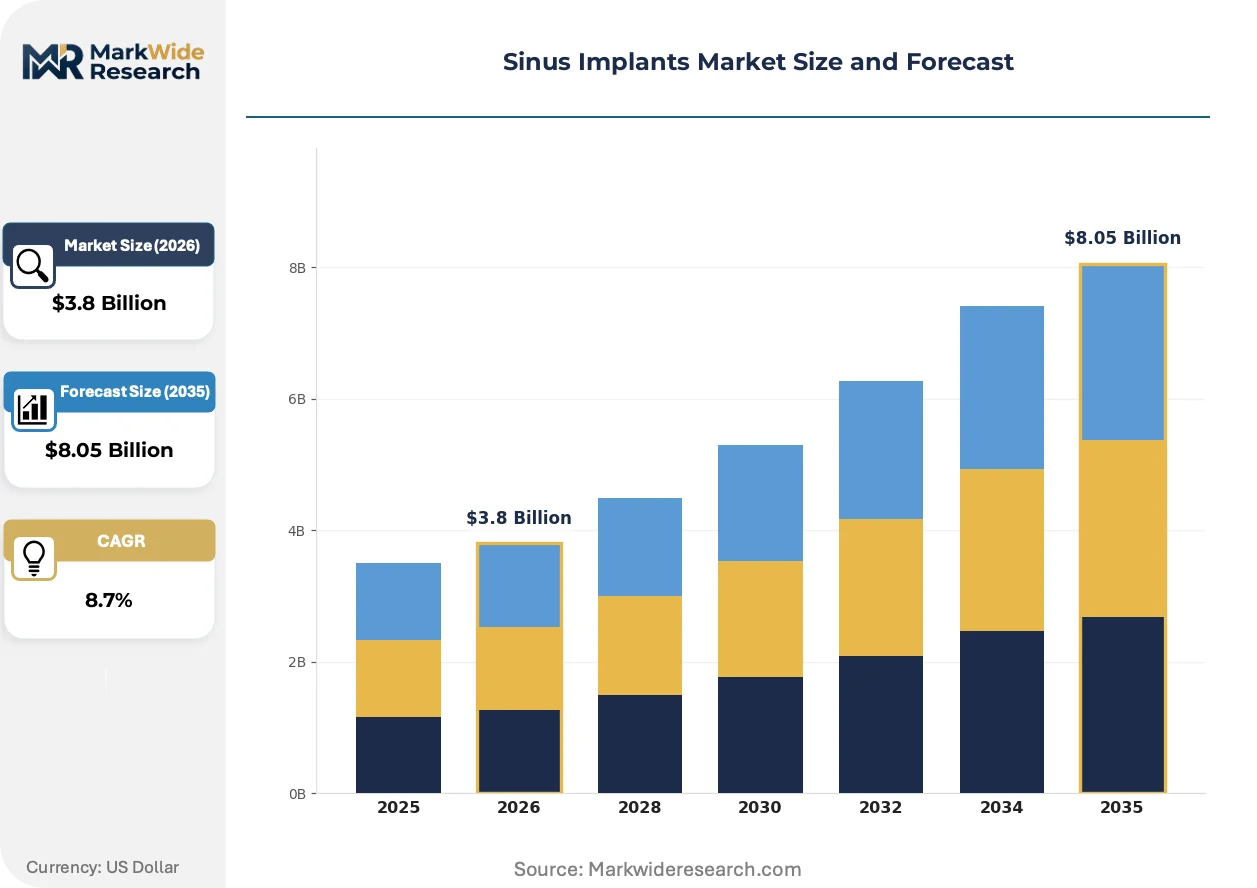
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Sinus Dilation, Biodegradable Implants, Expandable Implants, Drug-Eluting Implants End User: Hospitals, ENT Clinics, Ambulatory Surgical Centers, Home Care Settings Application: Surgery, Chronic Sinusitis Treatment, Allergy Management, Nasal Obstruction Relief Material: Silicone, Polyethylene, Titanium, Polymers |
| Companies Covered | Medtronic, Stryker Corporation, Smith & Nephew, Olympus Corporation, Intersect ENT, Johnson & Johnson, Zimmer Biomet Holdings, Arthrex, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sinus Implants Market Evolving Landscape
Implant functionality is converging with navigation and delivery systems, compressing standalone device margins while elevating integrated platform economics. Three developments are restructuring competitive positioning.
Drug-device combination platforms is unifying corticosteroid delivery with mechanical patency maintenance in single-procedure interventions. Hospital systems in the United States are prioritizing these platforms for their bundled contracting advantages. The technology is unifying previously separate pharmaceutical and device reimbursement codes into single episode-based payment structures.
EMA MDR implementation is extending European launch timelines for novel biodegradable formulations by 12–24 months. Manufacturers are responding with earlier-stage regulatory strategy engagement and increased notified body pre-submission activity. Absorbable polymer segments face the most pronounced timeline compression as biocompatibility documentation requirements expand.
OR turnover economics now dominate ambulatory surgical center vendor selection criteria. Streamlined procedure kits disassemble traditional component purchasing patterns. Germany and Japan exhibit the most pronounced preference consolidation around kit-based procurement models.
Sinus Implants Market Segmentation
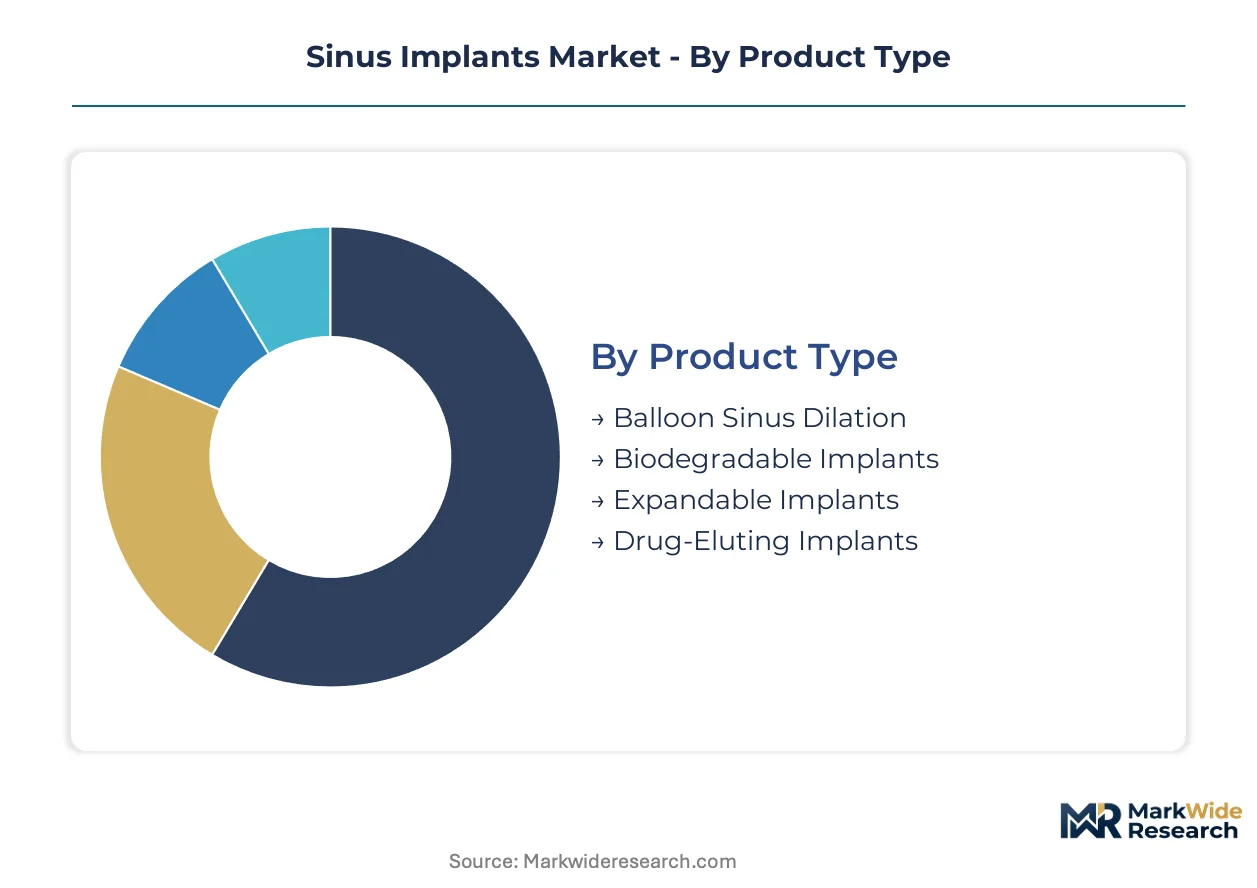
Sinus implant segmentation reveals divergent margin structures across material and functional categories. Product type and end-user splits determine reimbursement pathways and procurement leverage in distinct ways.
Product Type:
Functional sophistication separates segments with drug-device combination status from mechanical-only alternatives.
- Drug-Eluting Implants:Poly(lactic-co-glycolic acid) matrices release mometasone furoate or fluticasone propionate over 30–90 days. United States hospital systems concentrate demand here as bundled navigation-implant contracts favor outcomes-validated platforms with polyp recurrence reduction data.
- Balloon Sinus Dilation:Catheter-based systems dilate sinus ostia without permanent implantation. Ambulatory surgical centers in Germany and Japan drive volume for this segment given simpler reimbursement coding and reduced OR turnover requirements.
- Biodegradable Implants:Bioabsorbable polymer spacers maintain patency during healing then dissolve. Standalone variants face margin compression as payers shift toward drug-eluting alternatives with demonstrated clinical endpoints.
- Expandable Implants:Titanium-reinforced or polymer-based devices deploy to customized anatomical conformations. Complex revision cases in tertiary hospitals command premium pricing for this segment.
Mature deployment sits with biodegradable spacers. Newer deployment is concentrated in drug-eluting platforms with corticosteroid matrices.
End User:
Site-of-care economics reshape vendor contracting power and kit configuration requirements.
- Hospitals:Tertiary centers with integrated navigation systems dominate procedural volume. United States health systems leverage scale for bundled implant-navigation contracts that compress standalone device margins.
- Ambulatory Surgical Centers:Streamlined procedure kits with reduced turnover time capture migrating volume from inpatient settings. Germany's evolving outpatient reimbursement codes accelerate this shift.
- ENT Clinics:Office-based interventions concentrate in markets with favorable procedure coding. Japan's PMDA pathways for absorbable implants create structured entry barriers that limit clinic-based adoption.
- Home Care Settings:Post-procedural monitoring and patient-administered therapies occupy this nascent segment. Regulatory complexity around sterile implant handling constrains expansion.
Procurement consolidation favors hospitals. Fastest volume gains are occurring in ambulatory surgical centers with kit-based purchasing models.
Application:
Clinical indication determines reimbursement tiering and evidence requirements for market access.
- Surgery:Functional endoscopic sinus surgery with implant placement represents the core revenue pool. Post-surgical patency maintenance drives demand across all material categories.
- Chronic Sinusitis Treatment:Recalcitrant cases with polyp recurrence history qualify for drug-eluting implant coverage. FDA PMA scrutiny for combination products intensifies evidence burdens here.
- Allergy Management:Corticosteroid-eluting platforms address inflammatory components of allergic rhinitis. Payer validation of pharmaceutical-device synergy remains uneven across national health technology assessment bodies.
- Nasal Obstruction Relief:Mechanical dilation and stenting for structural blockage occupies lower reimbursement tiers. Balloon dilation systems compete aggressively for this indication without implant-related complexity.
Established revenue concentration sits with surgery. Steepest expansion trajectory is emerging in chronic sinusitis treatment as drug-eluting platforms displace revision procedures.
Material:
Supply chain configuration and biocompatibility documentation demands differentiate manufacturing economics.
- Polymers:Poly(lactic-co-glycolic acid) and bioabsorbable formulations dominate drug-eluting and biodegradable segments. ISO 13485-certified contract manufacturers with dedicated cleanroom capacity face capacity constraints.
- Silicone:Inert, non-absorbable spacers retain volume leadership in cost-sensitive applications. Long-term implantation without degradation suits permanent structural support cases.
- Titanium:Reinforced expandable implants command premium pricing in complex revision scenarios. Biocompatibility documentation under EMA MDR extends European launch timelines for novel formulations.
- Polyethylene:Porous high-density variants provide permanent structural scaffolding. Lower manufacturing complexity relative to absorbable polymers preserves margin in commoditized segments.
Volume leadership remains with silicone and polymer segments. Titanium-reinforced configurations are gaining fastest in high-acuity revision cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poly(lactic-co-glycolic acid) resin compounding capacity clusters in Germany and the United States anchor regional supply security for absorbable implant manufacturers. Hospital procurement consolidation and ambulatory surgical center expansion are reshaping demand geography across major markets.
United States
Integrated health systems drive bundled navigation-implant contracting at tertiary centers. FDA intensifies real-world evidence requirements for drug-device combination products under 510(k) and PMA pathways. Minneapolis and Memphis anchor Medtronic's captive resin operations for biodegradable stent portfolios.
Germany
Outpatient procedure code evolution accelerates ambulatory surgical center volume migration. EMA MDR compliance extends CE marking timelines for novel biodegradable formulations. Baden-Württemberg's ISO 13485-certified contract manufacturers face cleanroom capacity constraints amid supplier base rationalization.
Japan
ENT specialist density supports procedural volume concentration in urban centers. PMDA demands localized clinical data for absorbable implants, creating structured entry barriers. Tokyo and Osaka metropolitan areas concentrate hospital-based functional endoscopic sinus surgery capacity.
United Kingdom
NHS procurement frameworks favor outcomes-validated drug-eluting platforms with polyp recurrence reduction data. MHRA post-Brexit regulatory alignment with EMA MDR creates transitional compliance complexity. London and Manchester tertiary centers dominate complex revision case referrals.
Switzerland
Swissmedic maintains stringent biocompatibility documentation requirements for titanium-reinforced expandable implants. Premium pricing tolerance in complex revision cases attracts specialized manufacturer focus. Basel and Zurich hospital networks concentrate high-acuity sinus surgery volume.
Sinus Implants Market Competitive Landscape
Supplier base rationalization dominates the current landscape as contract manufacturers with ISO 13485 certification consolidate around dedicated cleanroom capacity. The vendor structure exhibits tiered concentration: multinational device conglomerates with captive polymer supply, mid-scale navigation-implant bundlers, and specialized ambulatory surgical center kit providers. Strategic archetypes include integrated platform owners, component outsourcing specialists, and regional distribution anchors. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure absorbable polymer supply continuity.
Among diversified medical technology conglomerates, Medtronic, Stryker Corporation, and Smith & Nephew occupy positions that exemplify distinct strategic vectors. Medtronic represents the integrated supply chain archetype through captive resin compounding capabilities. Stryker Corporation anchors the navigation-implant bundling tier within North American hospital contracting frameworks. Smith & Nephew sits within the ambulatory surgical center access specialization, reflecting streamlined kit-based procurement models.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| Smith & Nephew |
| Olympus Corporation |
| Intersect ENT |
| Johnson & Johnson |
| Zimmer Biomet Holdings |
| Arthrex |
| Integra LifeSciences |
| Others |
Value Network & Pricing Analysis
EMA MDR biocompatibility documentation mandates now gate qualified supply access for absorbable polymer manufacturers, compressing premium-tier pricing power toward ISO 13485-certified contract manufacturers with dedicated cleanroom capacity while forcing uncertified competitors into commodity positioning.
Pricing Analysis
Service-bundling configurations separate navigation-implant integrated contracts from standalone device transactions across United States hospital systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by drug-eluting versus mechanical-only functionality and FDA PMA versus 510(k) clearance status. Pricing pressure stems from balloon dilation substitution in nasal obstruction indications where implant-related reimbursement complexity disadvantages mechanical spacers. Ambulatory surgical centers exhibit highest price sensitivity due to kit-based procurement models, while tertiary hospitals with bundled contracts demonstrate lowest sensitivity.
Supply Chain Analysis
Regional distribution centers in Minneapolis and Memphis anchor Medtronic's captive resin compounding network for poly(lactic-co-glycolic acid) formulations. Manufacturing concentrates in Germany, the United States, and Japan where ISO 13485-certified cleanroom facilities cluster. Raw material dependencies center on lactic acid and glycolic acid monomers, medical-grade silicone feedstock, and titanium powder for reinforced expandables. Single-source vulnerability pervades absorbable polymer resin supply as limited contract manufacturers control qualified capacity. Distribution runs through hospital system GPO contracts and ambulatory surgical center kit assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA PMA pathway intensification for drug-device combination products constructs a cost-of-compliance moat that rewards incumbent investment in real-world evidence generation while filtering undercapitalized entrants.
For Market Incumbents: Acquire captive resin compounding assets to secure poly(lactic-co-glycolic acid) supply continuity against balloon dilation substitution threats. Expand Baden-Württemberg cleanroom capacity to capture EMA MDR compliance service demand from competitors facing timeline compression. Cement hospital system bundling relationships through integrated navigation-implant contracting before ambulatory surgical center volume migration accelerates. For New Entrants and Emerging Players: German outpatient reimbursement evolution represents the most penetrable white-space target for office-based sinus intervention platforms. Japan PMDA localized clinical data requirements create structured entry barriers that committed entrants can leverage for durable positioning. Pursue streamlined procedure kit partnerships with ambulatory surgical centers to bypass hospital GPO contracting consolidation. For Investors and Strategic Acquirers: FDA PMA approval for novel mometasone furoate matrix formulations is the leading indicator that drug-eluting platform economics will displace standalone biodegradable spacer margins. Five-to-ten year viability favors manufacturers with backward integration into absorbable polymer supply. Monitor EMA MDR notified body pre-submission volume as inflection signal for European launch timeline competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR extended timelines reward early-stage regulatory strategy engagement for novel biodegradable formulations. |
| Hospital System Partnership | Bundled navigation-implant contracts compress standalone device margins while elevating integrated platform economics. |
| Reimbursement Strategy | Outcomes-validated polyp recurrence data unlocks bundled episode-based payment structures in United States health systems. |
| Capacity Expansion | ISO 13485-certified cleanroom additions in Germany address supplier base rationalization demand from absorbable polymer manufacturers. |
| Software Companion Development | Sinus navigation system integration deepens hospital contracting stickiness and procedure workflow capture. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs across this sinus implants market analysis. Primary interviews with ENT surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with FDA 510(k) and PMA submission databases, EMA MDR notified body records, and hospital procurement transaction logs. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation validated segment-level outputs.
Product type, material composition, end-user site-of-care, and geographic regulatory cluster dimensions were modeled at country-level granularity across the analysis window. CAGRs were derived from procedure volume forecasts calibrated to ENT specialist density and reimbursement code evolution. Forecast inputs incorporated drug-eluting platform adoption curves, ambulatory surgical center migration rates, and absorbable polymer supply capacity constraints.
Revisions become necessary when FDA PMA scrutiny intensifies beyond current real-world evidence requirements, EMA MDR notified body capacity bottlenecks extend CE marking timelines, or balloon dilation technology captures chronic sinusitis indications previously reserved for implants. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Transilluminators Market
Medical Devices
Global Medical Implants Market
Medical Devices
Germany Drug Delivery Devices Market
Medical Devices
Soft Tissue Release Systems Market
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
Global Artificial Tendons and Ligaments Market
Medical Devices
Spinal Trauma Devices Market
Medical Devices
Buccal Drug Delivery System Market
Medical Devices
Struts Implants Market
Medical Devices
Mobile Operating Rooms Market
Medical Devices
Global Microdermabrasion Devices Market
Medical Devices
Mechanical Chest Compression System Market
Medical Devices
Ultrasound Transducers Market
Medical Devices
Veterinary Arthroscopy Device Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
Water Bath Vaporizer Market