
 Accelerator Pedal Module Market | 2026-2036
Accelerator Pedal Module Market Size, Share, and Industry Trends Forecast 2026-2036
Accelerator Pedal Module Market Intelligence
A widening capability gap between integrated sensor manufacturers and standalone mechanical suppliers is reorganizing competitive tiers in the accelerator pedal module sector. Bosch leverages captive semiconductor production to dominate electronic pedal architectures. Continental AG anchors European OEM relationships through embedded system integration. KSR International specializes in mechanical-hybrid designs for cost-sensitive vehicle programs.
An accelerator pedal module translates driver foot input into electronic or mechanical signals that regulate engine throttle response, typically incorporating position sensors with resolution below 0.1 millimeter and operating temperatures spanning minus 40 to 120 degrees Celsius. Electronic modules with Hall Effect technology lead value generation due to precision requirements in drive-by-wire platforms, while haptic feedback variants represent the fastest-expanding technology segment as OEMs add programmable pedal resistance for autonomous handoff scenarios. Smart sensor integration concentrates margin pools with Tier-1 suppliers capable of firmware development, leaving standalone mechanical installations in mature cost-competition.
NHTSA mandates govern unintended acceleration prevention and pedal entrapment geometry in the United States, while ECE R79 and ISO 26262 shape functional safety thresholds across European and Asian supply chains. China's GB standards and MIIT new-energy vehicle directives accelerate domestic electronic module certification requirements. Stakeholders must monitor sensor fusion trends where brake and pedal modules converge into unified chassis control units.
Market Dynamics
Electronic throttle control architectures are displacing mechanical linkages across vehicle platforms, compressing supplier margins while concentrating firmware-capable Tier-1s in Hall Effect sensor integration.
Growth Catalysts
- EPA emissions benchmarks:Stringent fuel-efficiency mandates in the United States force OEMs toward precision electronic throttle modulation, expanding module specification rates.
- Electric vehicle powertrain electrification:Battery-electric platforms require drive-by-wire pedal systems with programmable response curves, generating module demand distinct from internal combustion architectures.
- China's MIIT new-energy vehicle directives:Domestic certification requirements accelerate electronic module adoption across Chinese OEM supply chains.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings in Hall Effect sensor production compress module margins unpredictably.
- Semiconductor foundry concentration:Taiwan and South Korea wafer fabrication bottlenecks create single-source vulnerability for sensor-integrated controllers.
- ISO 26262 functional safety compliance:ASIL-D certification timelines extend product development cycles by eighteen to twenty-four months.
Strategic Opportunities
- India's PLI scheme for automotive components:Production-linked incentives attract module assembly investment for export-oriented OEM programs.
- Sensor fusion with brake-by-wire systems:Unified chassis control units merge pedal and brake module architectures, opening integrated supplier contracts.
- Haptic feedback programming:Autonomous handoff scenarios create demand for variable-resistance pedals with OEM-customizable force profiles.
Industry Challenges
- Embedded firmware engineering scarcity:Functional safety software development talent concentrates at established Tier-1s, constraining new entrants.
- Legacy mechanical platform coexistence:Hybrid vehicle programs require dual-sourcing strategies that fragment production scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Accelerator Pedal Module Market |
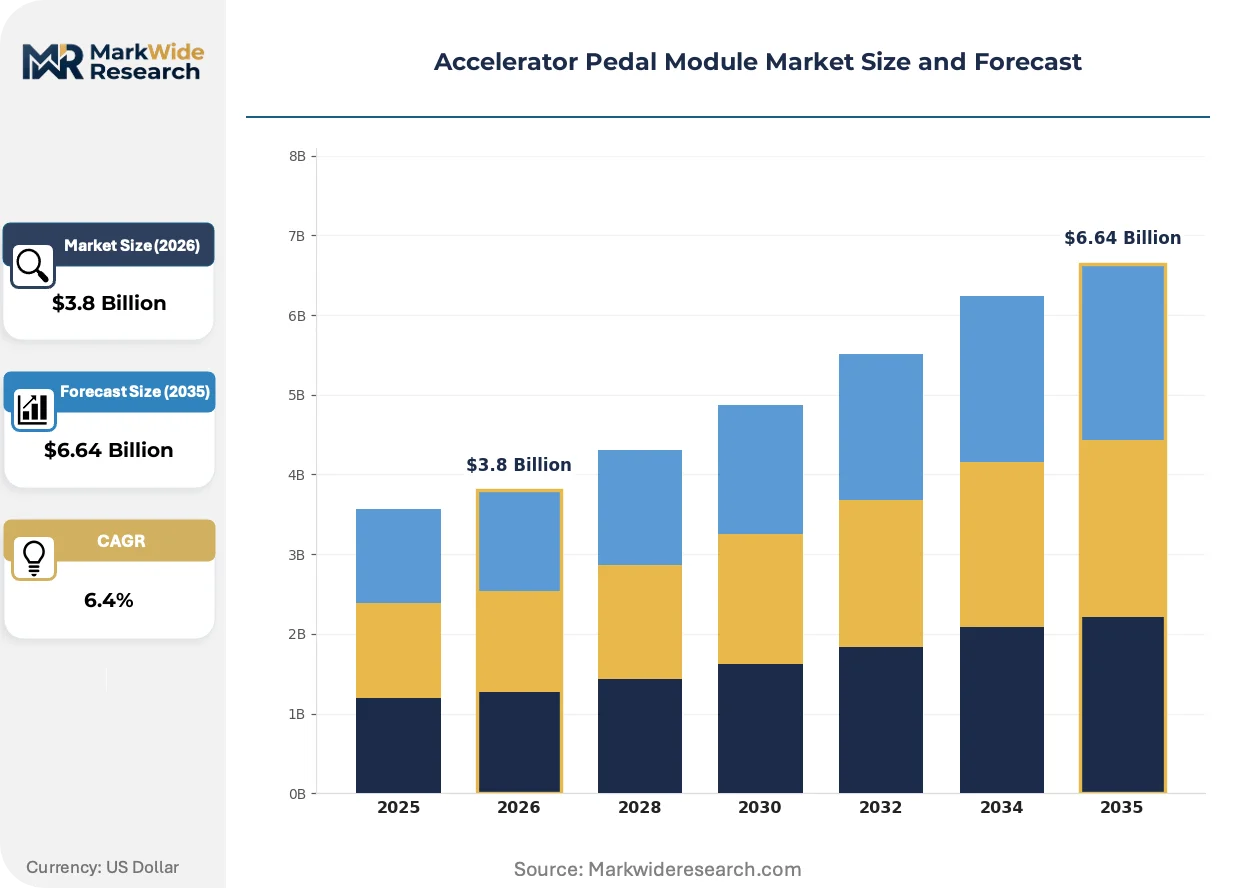
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic, Mechanical, Hybrid, Wireless Technology: Haptic Feedback, Hall Effect, Potentiometer, Smart Sensors End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation: Integrated, Standalone, Embedded, Removable |
| Companies Covered | Denso Corporation, KSR International, Bosch, F-TECH Inc., ZF Friedrichshafen AG, Continental AG, CTS Corporation, Magna, HELLA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Accelerator Pedal Module Market Strategic Shifts & Innovations
Accelerator pedal architectures are bifurcating between premium electronic platforms with programmable characteristics and cost-optimized mechanical-hybrid designs for emerging-market vehicle programs.
Hall Effect position sensing is fragmenting the supplier landscape by requiring captive semiconductor packaging capabilities that standalone mechanical producers cannot replicate. European and Japanese OEMs are specifying sub-0.1 millimeter resolution thresholds for drive-by-wire platforms, compressing margins for suppliers without in-house sensor calibration. The technology is fragmenting competitive tiers into firmware-integrated specialists and commodity mechanical assemblers.
China's GB standards for new-energy vehicle safety are mandating redundant electronic throttle circuits with independent power supplies. The regulation forces module redesigns that add cost but enable domestic certification for export-bound Chinese OEMs. European suppliers with existing ASIL-D experience are capturing compliance-driven specification wins.
Fleet procurement of autonomous-ready vehicles is compressing development cycles for haptic-enabled pedal modules. Commercial vehicle operators in Germany and Japan are specifying programmable resistance curves for human-machine handoff protocols. This demand pattern favors suppliers with rapid firmware iteration capabilities over traditional mechanical specialists.
Accelerator Pedal Module Market Segmentation
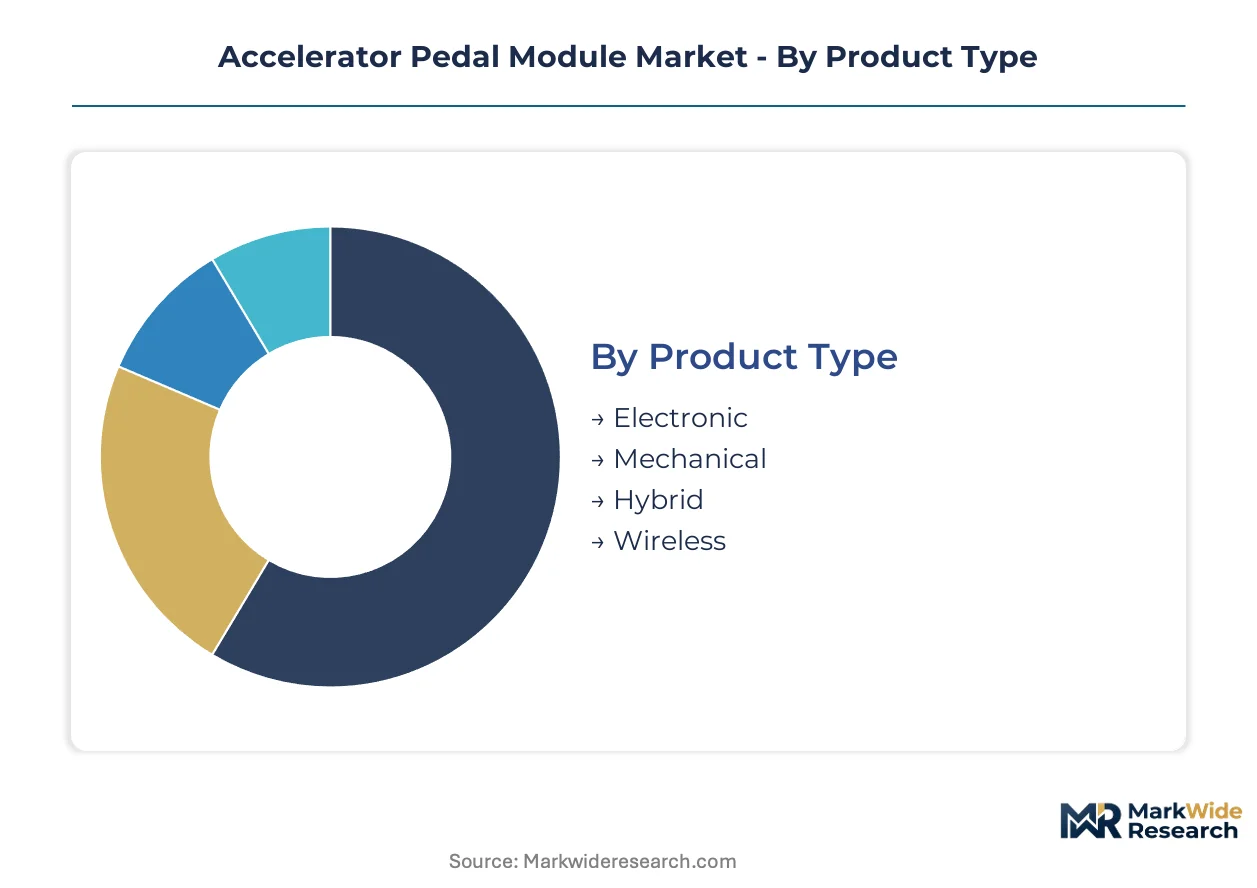
Accelerator pedal module segmentation reveals how margin pools concentrate with sensor-integrated architectures while mechanical variants compete on scale. Understanding these divides exposes where procurement power shifts and which supplier capabilities command premium positioning.
Product Type:
Margin pools concentrate in electronic architectures with firmware-integrated sensing, while mechanical and hybrid formats serve cost-optimized vehicle programs.
- Electronic:Hall Effect position sensing with sub-0.1 millimeter resolution dominates drive-by-wire platforms. Demand concentrates in German and Japanese OEM electrification programs where EPA emissions benchmarks and ECE R79 safety thresholds mandate precision throttle modulation.
- Hybrid:Combines mechanical backup linkages with electronic primary sensing for transitional vehicle architectures. Chinese OEM procurement is expanding fastest here as MIIT new-energy vehicle directives accelerate dual-mode certification requirements.
- Mechanical:Pure cable-actuated designs persist in emerging-market commercial vehicles and legacy internal combustion platforms.
- Wireless:Bluetooth Low Energy transmission eliminates physical harness connections for modular vehicle interiors.
Electronic holds installed capacity. Hybrid is rotating up the share rankings.
Technology:
Technology selection tracks directly to functional safety certification tiers and OEM program positioning.
- Hall Effect:Non-contact magnetic sensing delivers ASIL-D compliant redundancy for autonomous-ready platforms. Fleet procurement in Germany specifies programmable resistance curves for human-machine handoff protocols.
- Smart Sensors:Edge-computing modules with embedded firmware enable real-time diagnostic telemetry. Rare earth magnet cost volatility in neodymium supply chains compresses margins unpredictably.
- Haptic Feedback:Variable-resistance actuators create programmable pedal feel for autonomous transition scenarios.
- Potentiometer:Contact-based resistive sensing remains cost-competitive for price-sensitive vehicle programs.
Hall Effect dominates value capture. Smart Sensors are climbing the fastest.
End User:
Customer type determines specification authority and contract duration structures.
- OEMs:Direct procurement of electronic modules with proprietary firmware stacks locks in multi-year supply agreements. NHTSA pedal entrapment standards and ISO 26262 compliance requirements extend development cycles.
- Tier-1 Suppliers:System integrators consolidate brake and pedal architectures into unified chassis control units. Semiconductor foundry concentration in Taiwan creates single-source vulnerability for sensor-integrated controllers.
- Vehicle Assemblers:Contract manufacturers source pre-calibrated modules for white-label production.
- Aftermarket Providers:Replacement mechanical units serve aging vehicle parc maintenance.
OEMs hold specification authority. Tier-1 Suppliers are rotating up the share rankings.
Installation:
Physical integration depth shapes supplier technical support obligations and margin structures.
- Integrated:Pedal modules fused into cockpit structural elements require collaborative design with interior Tier-1s. China's GB standards mandate redundant electronic circuits with independent power supplies.
- Embedded:Controllers housed within transmission tunnel assemblies demand thermal management for minus 40 to 120 degree Celsius operating ranges.
- Standalone:Bolt-on units simplify replacement logistics for aftermarket channels.
- Removable:Quick-release designs service commercial fleet maintenance protocols.
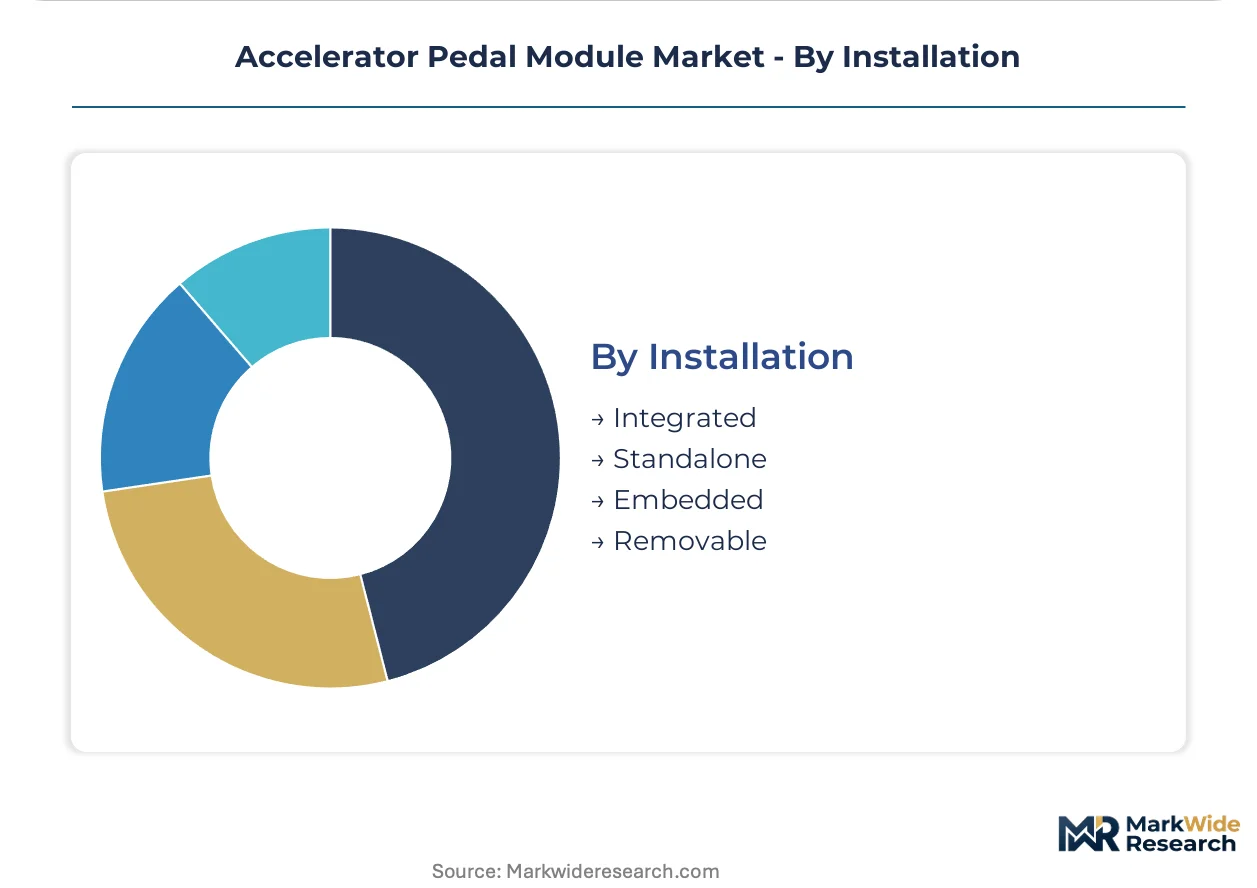
Integrated holds design-in complexity. Embedded is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry separates German Tier-1 suppliers commanding firmware-integrated premiums from Chinese mechanical assemblers competing on scale. Module procurement in Stuttgart and Wolfsburg locks in multi-year electronic architecture contracts. Cost-optimized sourcing in Shanghai and Chongqing rotates toward hybrid designs for domestic electrification programs.
China
MIIT new-energy vehicle directives force redundant electronic throttle circuits across battery-electric platforms. GB standards mandate independent power supplies for safety certification. Yangtze River Delta clusters in Shanghai and Suzhou concentrate module assembly investment for export-bound OEM supply chains.
Germany
ECE R79 functional safety thresholds and KBA type-approval protocols shape precision sensor specifications. Stuttgart anchors Continental AG and Bosch captive semiconductor integration for Hall Effect architectures. Bavarian automotive corridors around Munich and Ingolstadt specify sub-0.1 millimeter resolution for drive-by-wire platforms.
United States
NHTSA pedal entrapment geometry mandates and EPA emissions benchmarks tighten electronic throttle modulation requirements. Detroit Three procurement concentrates specification authority with firmware-capable Tier-1s. Tennessee and Kentucky assembly corridors absorb module supply for North American electrification programs.
Japan
METI carbon-neutrality roadmaps accelerate drive-by-wire adoption across Toyota and Honda electrification pipelines. JIS standards align with ISO 26262 ASIL-D thresholds for autonomous-ready platforms. Nagoya and Toyota City industrial basins concentrate precision sensor calibration for domestic OEM captive supply.
India
PLI scheme production-linked incentives attract module assembly investment for export-oriented European and Japanese OEM programs. BIS automotive component standards tighten electronic module certification timelines. Tamil Nadu and Gujarat manufacturing corridors expand capacity for hybrid mechanical-electronic transitional architectures.
Accelerator Pedal Module Market Key Industry Players
Concentration sits with diversified automotive electronics conglomerates possessing captive semiconductor packaging and firmware development capabilities. The supplier landscape compresses into three tiers: integrated sensor-software specialists, mechanical-hybrid assemblers, and commodity cable-actuated producers. Strategic moves center on Hall Effect sensor calibration acquisitions and embedded system integration partnerships with brake-by-wire chassis control units.
Within the diversified electronics tier, Denso Corporation, Bosch, and Continental AG exemplify archetypes spanning captive semiconductor production, European OEM relationship anchoring, and embedded firmware integration. These entities occupy positions where functional safety certification concentration creates defensive moats. KSR International and CTS Corporation sit within mechanical-hybrid specialization brackets serving cost-sensitive vehicle programs. ZF Friedrichshafen AG and Magna represent scale-driven chassis integration plays where pedal modules merge into unified control architectures.
| Leading Market Players |
|---|
| Denso Corporation |
| KSR International |
| Bosch |
| F-TECH Inc. |
| ZF Friedrichshafen AG |
| Continental AG |
| CTS Corporation |
| Magna |
| HELLA |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between Tier-1 suppliers and German OEMs lock in multi-year supply access while providing price visibility for Hall Effect sensor-integrated modules. These arrangements insulate firmware-capable suppliers from rare earth magnet cost volatility while binding mechanical assemblers to spot-market exposure.
Pricing Analysis
Configured-to-order pricing for ASIL-D certified electronic modules commands substantial premiums over standard mechanical-hybrid units. Three-tier pricing structure across premium, standard, and economy levels separates firmware-integrated specialists from commodity assemblers. Price differentiation rests on ISO 26262 certification grade and customization depth for OEM-specific force profiles. Pricing pressure stems from neodymium cost swings in Hall Effect sensor production, compressing margins unpredictably. Cost-sensitive vehicle programs in emerging markets exhibit highest price sensitivity, while autonomous-ready fleet procurement in Germany shows lowest sensitivity.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for sensor-integrated controllers, creating single-source vulnerability for semiconductor packaging. China concentrates rare earth magnet processing and module final assembly for domestic electrification programs. The supply chain draws from neodymium-dysprosium feedstocks, silicon wafer substrates, and automotive-grade resin housings. Distribution runs through OEM captive supply networks and Tier-1 system integrators consolidating brake-pedal architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Accelerator pedal module economics are shifting toward platform-based competition where sensor-firmware integration determines ecosystem lock-in. Interoperability between pedal modules and unified chassis control units is restructuring procurement authority toward brake-by-wire system integrators.
For Market Incumbents: Compound firmware development capabilities through embedded system acquisitions that bridge pedal and brake module architectures. Prioritize ASIL-D certification pipelines to defend against emerging sensor-fusion specialists. Capacity addition in Yangtze River Delta clusters captures Chinese OEM export growth while hedging Taiwan foundry concentration risks. For New Entrants and Emerging Players: Lead with haptic feedback programming expertise targeting commercial fleet autonomous handoff specifications in Germany and Japan. India's PLI scheme production corridors offer the most penetrable geography for hybrid mechanical-electronic module assembly. Position through rapid firmware iteration partnerships rather than capital-intensive sensor fabrication. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among firmware-integrated Tier-1s with multi-year OEM platform contracts. Long-term viability favors suppliers with captive semiconductor packaging and functional safety software development depth. Watch sensor fusion consolidation signals where brake and pedal architectures merge into unified chassis control units.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Integration | Unifies brake and pedal architectures into chassis control units, capturing OEM specification authority. |
| Hall Effect Sensor Calibration Acquisition | Secures sub-0.1 millimeter resolution capabilities required by ECE R79 and German OEM platforms. |
| India PLI Scheme Manufacturing Footprint | Positions module assembly for export-oriented European and Japanese OEM supply chains. |
| Embedded Firmware Development Partnership | Addresses engineering scarcity constraining new entrants in functional safety software. |
| Redundant Circuit Design Certification | Enables Chinese GB standards compliance for MIIT new-energy vehicle directive access. |
Research Approach
Desk research of automotive production databases, regulatory filing repositories, and supplier contract disclosures preceded structured interviews with OEM platform engineers, Tier-1 procurement directors, semiconductor packaging specialists, and functional safety compliance officers. Primary fieldwork combined with secondary validation from EPA emissions benchmarks, NHTSA pedal entrapment standards, and MIIT new-energy vehicle directives. Bottom-up module shipment analysis triangulated against top-down vehicle production forecasts across propulsion architectures.
Variance decomposition separated volume drivers from value-mix effects across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user category, and installation depth alongside vehicle class and regional production cluster. CAGRs were derived from fitted growth curves anchored to electrification program timelines and regulatory compliance deadlines. Forecast inputs incorporated rare earth magnet price trajectory assumptions and semiconductor foundry capacity expansion plans.
The analysis sits within stated boundaries; outcomes outside sustained electric vehicle penetration rates or stable rare earth supply conditions would require recalibration. Forecasts reflect documented assumptions about OEM platform standardization timelines and functional safety certification throughput. Recalibration cycles align with material shifts in EPA emissions stringency, MIIT directive revisions, and autonomous vehicle deployment protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Road Snow Melt Market
Automotive Parts
Russia Automotive Airfilters Market
Automotive Parts
HCV Brake Components Market
Automotive Parts
Automotive Electric Vacuum Pump Market
Automotive Parts
India Automotive Parts Magnesium Die Casting Market
Automotive Parts
Engine Fogging Oil Market
Automotive Parts
Canada Automotive Pneumatic Actuators Market
Automotive Parts
Saudi Arabia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
Europe Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Spacer Ring Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Colombia Commercial Vehicles Lubricants Market
Automotive Parts
India Automotive Parts Aluminum Die Casting Market
Automotive Parts
Global Automotive Brake Hose Market
Automotive Parts
Global Automotive Springs and Damper Market