
 Autonomous Forklift Market | 2026-2036
Autonomous Forklift Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Forklift Market Analysis
Equipment-as-a-service and third-party leasing is reshaping capital deployment for mid-size warehouse operators. Jungheinrich AG leverages its European service network to anchor long-term fleet contracts. Toyota Industries Corporation sustains R&D intensity across sensor fusion architectures. KION GROUP AG competes through manufacturing scale in automated guided vehicle platforms.
An autonomous forklift is a self-propelled industrial truck equipped with LiDAR, vision systems, or AI navigation that transports palletized loads without human operation across warehouse and manufacturing floors. These vehicles execute load transportation, inventory management, and order picking through real-time path planning and obstacle detection. Automated guided vehicle deployments retain the largest installed base among product types, though robotic forklift configurations capture expanding margin pools in high-mix distribution environments. Vision systems technology leads adoption in retail end-user settings where barcode and package recognition demands precision.
OSHA warehouse safety standards in the United States, EU machinery directives under CE marking requirements, and Japan's METI industrial robot guidelines collectively shape product certification and operational liability frameworks. Compliance with these regimes determines market access and insurance cost structures for fleet deployments. Stakeholders must monitor evolving liability allocation between equipment vendors and facility operators as autonomous decision-making depth expands.
Market Dynamics
Equipment-as-a-service capital models are compressing deployment timelines for mid-size warehouse operators, forcing traditional manufacturers to restructure revenue recognition around utilization-based contracts rather than unit sales.
Growth Catalysts
- EU Machinery Directive compliance:CE marking requirements for autonomous industrial vehicles create standardized safety baselines that reduce insurance friction and accelerate fleet approvals across German, French, and Dutch distribution hubs.
- LiDAR cost curves:Solid-state sensor manufacturing scale in Asian component ecosystems is collapsing per-unit navigation costs, enabling two-pallet robotic configurations in mid-market warehouses previously priced out of automation.
- E-commerce fulfillment density:Same-day delivery commitments from retail distribution networks are mandating 24-hour throughput capacity that human-operated fleets cannot sustain, pulling autonomous replacements into regional sorting centers.
Market Restraints
- LiDAR supply concentration:High-performance sensor fabrication remains captive to Taiwanese and Chinese component specialists, exposing fleet operators to single-source vulnerability and 12-16 week lead time volatility.
- OSHA liability allocation:Ambiguous fault determination between equipment vendors and facility operators under existing warehouse safety standards is inflating commercial general liability premiums for early adopters in US markets.
- Battery chemistry constraints:Lithium iron phosphate cell thermal management requirements limit continuous operation cycles in ambient temperatures above 40°C, constraining deployment in Middle Eastern and Southeast Asian manufacturing environments without climate-controlled infrastructure.
Strategic Opportunities
- Indian warehouse automation:PLI scheme incentives for logistics infrastructure and fragmented cold-chain networks present first-mover positioning for vision-guided forklifts in pharmaceutical and agricultural distribution.
- 5G private network convergence:Ultra-reliable low-latency communication is enabling centimeter-precision fleet coordination without on-vehicle computing overhead, opening retrofit opportunities in legacy facilities with existing cellular infrastructure.
- Japan METI robot certification:Streamlined safety validation pathways for collaborative industrial robots are reducing type-approval timelines, accelerating pilot-to-production transitions for sensor-fusion architectures in automotive assembly plants.
Industry Challenges
- Multi-fleet integration complexity:Harmonizing navigation protocols across mixed-vendor autonomous vehicle populations requires middleware development that most warehouse operators lack in-house, forcing reliance on systems integrators with 6-9 month deployment cycles.
- Functional safety engineering scarcity:ISO 13849 and IEC 62061 certification expertise for autonomous mobile robots concentrates in German and Japanese engineering consultancies, creating talent bottlenecks for North American and Chinese OEMs seeking independent safety validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Forklift Market |
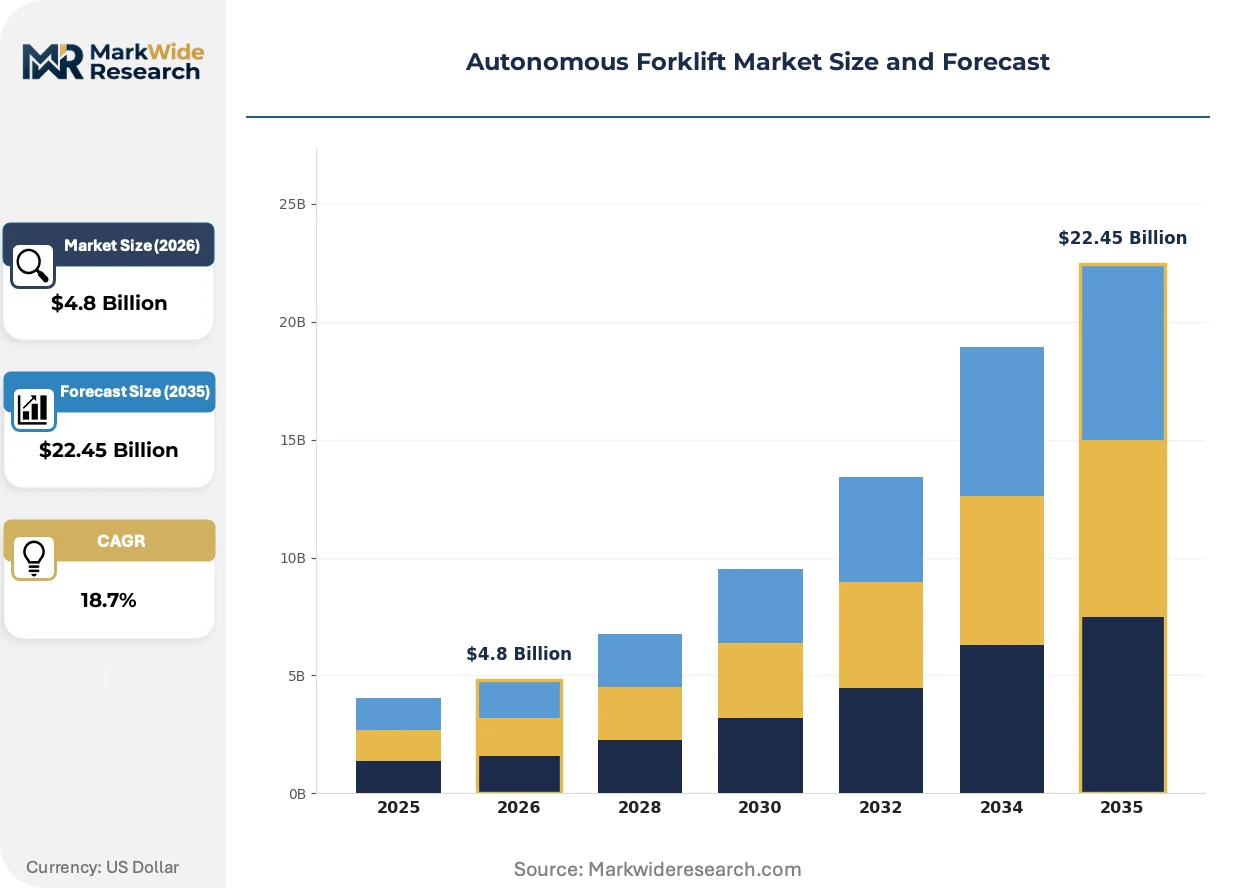
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicle, Self-Driving Forklift, Robotic Forklift, Dockless Forklift End User: Manufacturing, Warehousing, Retail, Distribution Centers Technology: LiDAR, Vision Systems, AI Navigation, GPS Application: Load Transportation, Inventory Management, Order Picking, Material Handling |
| Companies Covered | Jungheinrich AG, Crown Equipment Corporation, Toyota Industries Corporation, Hangcha Group, CLARK Material Handling Company, KION GROUP AG, Hyster-Yale Materials Handling, Inc., Doosan Corporation, Mitsubishi Logisnext Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Forklift Market Emerging Trajectories
Navigation architectures are bifurcating between high-cost LiDAR-dominant systems for precision manufacturing and stripped-down vision-plus-IMU configurations for cost-sensitive distribution, with middleware abstraction layers emerging to bridge operational differences.
Sensor fusion is migrating from hardware-redundant LiDAR-camera-radar stacks to software-defined perception pipelines that dynamically weight input streams based on environmental conditions. Third-party logistics operators in Benelux distribution corridors are piloting these architectures to reduce per-vehicle sensor costs by 30-40 percent while maintaining 99.9 percent localization accuracy. The compression is enabling three-shift deployment economics in grocery retail networks previously restricted to single-shift human operations.
EU AI Act risk classification for autonomous industrial vehicles is mandating explainability documentation for path-planning algorithms that override human safety overrides. German automotive component warehouses are restructuring procurement specifications to require algorithmic audit trails, pushing vendors to adopt deterministic fallback modes rather than black-box neural navigation. The compliance burden favors established European automation suppliers with existing functional safety documentation systems over Asian entrants.
Leasing structures are displacing capital purchase as the dominant acquisition mode for fleets under 50 units. Mid-size food and beverage distributors in the US Southeast are contracting through regional equipment finance platforms that bundle maintenance, software updates, and utilization insurance into per-hour rates. The shift transfers residual value risk to lessors and accelerates technology refresh cycles from seven-year depreciation schedules to 36-month replacement intervals.
Autonomous Forklift Market Segmentation
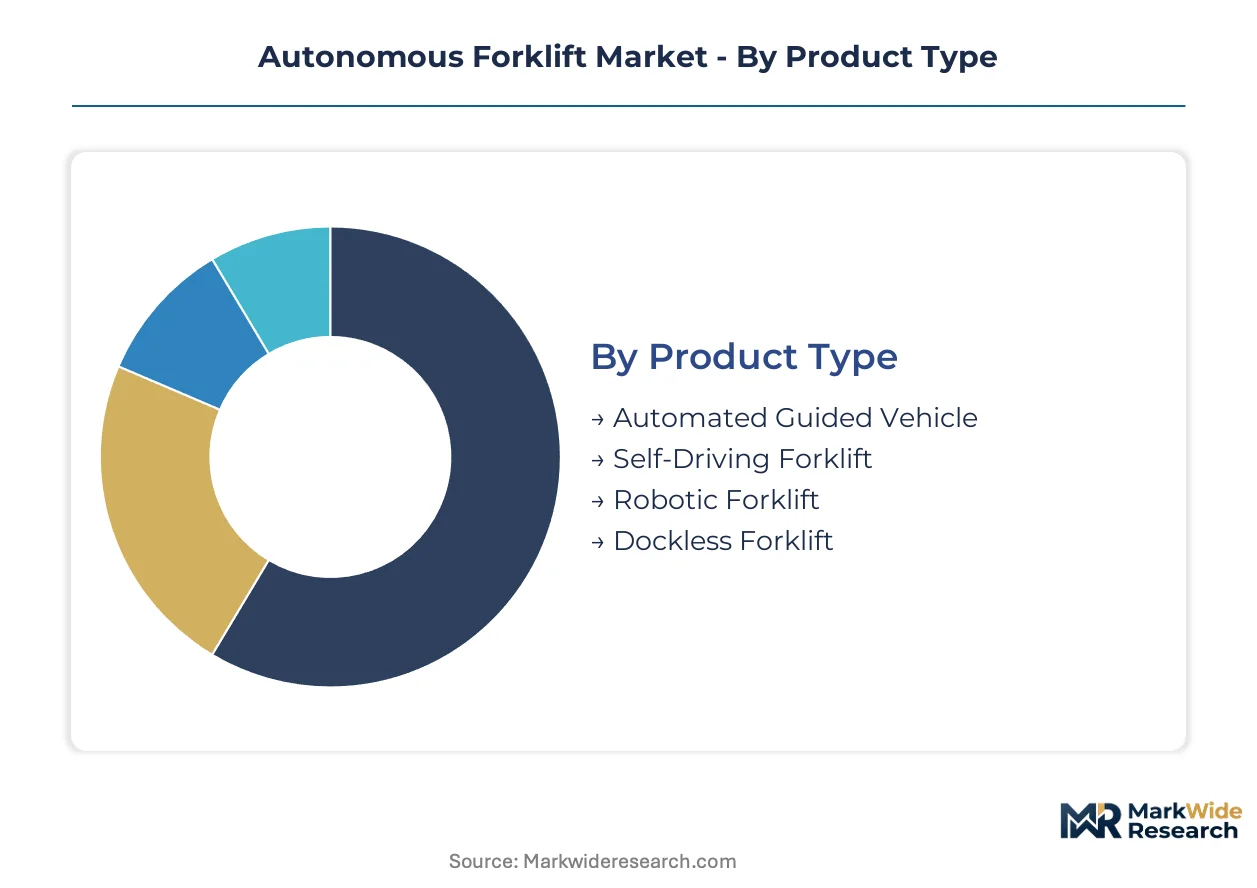
Equipment replacement cycles vary dramatically across autonomous forklift configurations, with some segments refreshing every 36 months under leasing structures while others depreciate over seven-year schedules. Understanding these velocity differences helps vendors align service revenue models and inventory planning with actual fleet turnover patterns.
Product Type:
Cycle times compress fastest in configurations serving high-throughput e-commerce environments, while heavy manufacturing deployments retain assets longest.
- Automated Guided Vehicle:Wire-guided and magnetic tape-based navigation systems dominate legacy installations across automotive assembly plants in Germany and Japan. These vehicles retain the largest installed base among autonomous forklift categories, though retrofit costs and infrastructure dependencies limit expansion in greenfield facilities.
- Self-Driving Forklift:Sensor-fusion architectures with dynamic path planning enable operation without facility modifications, concentrating demand in US third-party logistics networks seeking rapid deployment. Battery thermal management constraints restrict continuous operation in Middle Eastern ambient conditions above 40°C.
- Robotic Forklift:Articulated manipulator configurations handle non-standard pallet dimensions in European pharmaceutical distribution.
- Dockless Forklift:Battery-swappable designs eliminate charging infrastructure requirements, gaining traction in Southeast Asian contract manufacturing facilities with space constraints.
Automated Guided Vehicle dominates installed base. Self-Driving Forklift is where expansion concentrates.
End User:
Capital deployment intensity separates segments, with some end users purchasing outright while others demand full equipment-as-a-service bundling.
- Manufacturing:Automotive and electronics producers in China and Japan drive LiDAR-guided vehicle adoption for just-in-time component delivery. METI robot certification requirements and ISO 13849 functional safety standards shape procurement specifications, with certification timelines extending 6-9 months for new vendor qualification.
- Warehousing:E-commerce fulfillment centers in Germany scale autonomous fleet deployments under EU machinery safety directives, with same-day delivery mandates mandating 24-hour throughput capacity. Vision systems lead adoption where barcode and package recognition demands precision.
- Retail:Grocery and general merchandise networks in the US Southeast contract through regional equipment finance platforms.
- Distribution Centers:Benelux corridor operators pilot software-defined perception pipelines to reduce per-vehicle sensor costs.
Manufacturing commands the highest average selling prices. Warehousing is expanding most quickly as fleet sizes scale.
Technology:
Component cost trajectories and supply concentration risks differentiate technology choices, with some sensor categories exposed to 12-16 week lead time volatility.
- LiDAR:Solid-state sensor manufacturing scale in Taiwanese and Chinese component ecosystems is collapsing per-unit navigation costs. High-performance fabrication remains captive to single-source vulnerability, exposing fleet operators to supply disruption.
- Vision Systems:Camera-plus-IMU configurations strip hardware redundancy for cost-sensitive distribution, with middleware abstraction layers bridging operational differences against LiDAR-dominant precision manufacturing systems. Retail end-user settings favor these where package recognition demands precision.
- AI Navigation:EU AI Act risk classification mandates explainability documentation for path-planning algorithms overriding human safety overrides.
- GPS:Outdoor yard management applications in US intermodal facilities leverage differential correction signals.
LiDAR retains premium positioning in precision applications. Vision Systems are climbing the fastest as cost compression enables mid-market access.
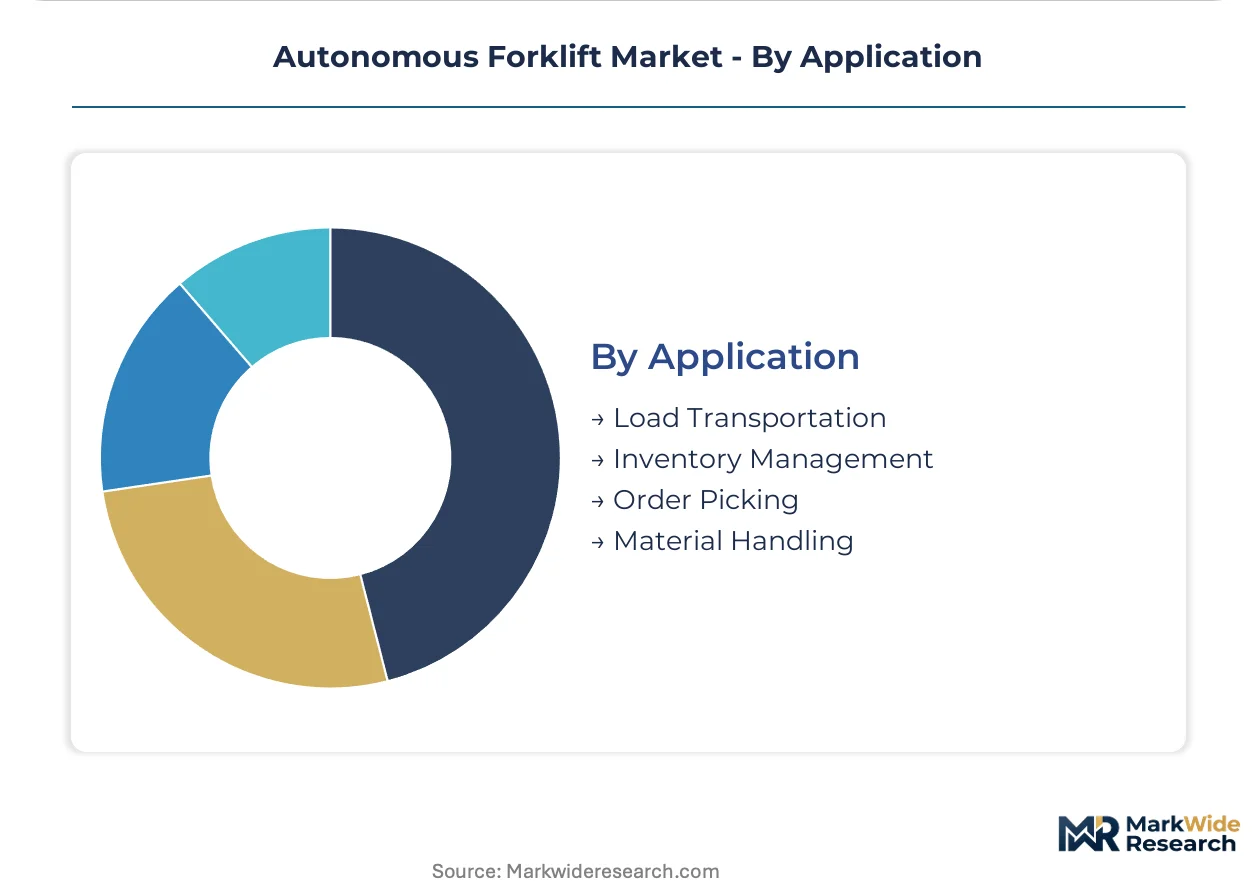
Application:
Labor substitution economics vary by task complexity, with some applications achieving full payback in under 24 months while others require extended utilization to justify automation.
- Load Transportation:Point-to-point pallet movement between fixed stations represents the most mature autonomous forklift application, with standardized navigation protocols reducing deployment complexity. German distribution hubs leverage these for CE marking compliance advantages that reduce insurance friction.
- Inventory Management:Real-time location tracking integration with warehouse management systems drives demand in high-SKU pharmaceutical and electronics facilities. Multi-fleet integration complexity forces reliance on systems integrators with 6-9 month deployment cycles.
- Order Picking:Variable destination routing with dynamic obstacle avoidance concentrates development investment.
- Material Handling:Bulk container and non-palletized load manipulation requires specialized end-effector configurations.
Load Transportation dominates installed base. Inventory Management is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentives for logistics automation are redirecting capital flows across major warehouse economies. Germany's CE marking acceleration, China's domestic LiDAR manufacturing subsidies, and India's PLI scheme for cold-chain infrastructure are compressing deployment timelines for mid-size operators.
United States
OSHA warehouse safety standards and liability allocation ambiguity are inflating commercial general liability premiums for early autonomous forklift adopters. Regional equipment finance platforms in the Southeast are bundling maintenance and utilization insurance into per-hour leasing rates. The Southeast corridor, spanning Georgia and Florida distribution hubs, is seeing 36-month replacement cycles displace seven-year depreciation schedules.
Germany
EU machinery directives under CE marking requirements are creating standardized safety baselines that reduce insurance friction across German, French, and Dutch distribution hubs. E-commerce fulfillment centers in the Ruhr industrial cluster are scaling autonomous fleet deployments to meet same-day delivery mandates. Jungheinrich AG leverages its European service network to anchor long-term fleet contracts in this regulatory environment.
China
Domestic warehouses are accelerating LiDAR-guided vehicle adoption as solid-state sensor manufacturing scale in Taiwanese and Chinese component ecosystems collapses per-unit navigation costs. METI robot certification requirements in Japan and ISO 13849 functional safety standards shape procurement specifications for automotive and electronics producers. The Yangtze River Delta manufacturing corridor is driving just-in-time component delivery automation.
Japan
METI industrial robot guidelines and streamlined safety validation pathways for collaborative industrial robots are reducing type-approval timelines. Automotive assembly plants in the Nagoya industrial zone are accelerating pilot-to-production transitions for sensor-fusion architectures. Certification expertise concentrates in German and Japanese engineering consultancies, creating talent bottlenecks for OEMs seeking independent safety validation.
India
PLI scheme incentives for logistics infrastructure and fragmented cold-chain networks present first-mover positioning for vision-guided forklifts in pharmaceutical and agricultural distribution. The country's national machinery safety regulator is developing certification frameworks aligned with EU machinery directives. Maharashtra and Gujarat warehouse clusters are piloting equipment-as-a-service models to bypass capital constraints.
Autonomous Forklift Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic archetypes: European engineering consultancies with functional safety certification depth, Asian component-integrated OEMs leveraging LiDAR cost curves, and North American leasing platforms restructuring revenue recognition around utilization-based contracts. Competitive moves center on manufacturing scale expansion in automated guided vehicle platforms and strategic partnerships for middleware development that harmonizes multi-fleet navigation protocols.
Within the European engineering tier, Jungheinrich AG and KION GROUP AG exemplify the service-network-centric archetype, leveraging established functional safety documentation systems to meet EU AI Act explainability requirements. Toyota Industries Corporation anchors the R&D-intensive tier, sustaining investment across sensor fusion architectures. Among Asian fabricators, Hangcha Group occupies a position calibrated to domestic warehouse demand acceleration.
| Leading Market Players |
|---|
| Jungheinrich AG |
| Crown Equipment Corporation |
| Toyota Industries Corporation |
| Hangcha Group |
| CLARK Material Handling Company |
| KION GROUP AG |
| Hyster-Yale Materials Handling, Inc. |
| Doosan Corporation |
| Mitsubishi Logisnext Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
LiDAR supply concentration in Taiwanese and Chinese component ecosystems generates dual pricing tier spreads and shapes procurement strategies across fleet operators. CE marking compliance costs for EU machinery directives and ISO 13849 functional safety certification create premium-standard-economy stratification that OEMs exploit to defend margin pools against Asian cost leaders.
Pricing Analysis
Certification level creates the primary spread between premium CE-marked configurations and standard uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13849 compliance depth, after-sales service bundling, and sensor redundancy specifications. Cost compression in vision-guided economy tiers is intensifying because solid-state LiDAR manufacturing scale collapses per-unit navigation costs. Mid-size warehouse operators in the US Southeast exhibit highest price sensitivity, while German automotive component warehouses prioritize certification-grade premiums.
Supply Chain Analysis
Solid-state LiDAR feedstock fabrication draws from Taiwanese semiconductor foundries, Chinese optical component specialists, and Japanese precision sensor manufacturers. Lithium iron phosphate cells, high-performance compute modules, and industrial-grade camera arrays constitute critical input dependencies. Single-source vulnerability in high-performance sensor fabrication exposes fleet operators to 12-16 week lead time volatility. Distribution runs through regional equipment finance platforms that bundle maintenance and utilization insurance into per-hour leasing rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 13849 and IEC 62061 certification expertise concentrates in German and Japanese engineering consultancies, creating talent bottlenecks that constrain independent safety validation for North American and Chinese OEMs. This capability scarcity favors incumbent European automation suppliers with existing functional safety documentation systems.
For Market Incumbents: Entrench certification depth by acquiring German engineering consultancies with IEC 62061 validation expertise. Expand manufacturing scale in automated guided vehicle platforms to defend against Asian component-integrated OEMs leveraging LiDAR cost curves. Prioritize middleware development partnerships that harmonize multi-fleet navigation protocols before systems integrators capture that margin layer. For New Entrants and Emerging Players: Build out vision-guided forklift capabilities targeting Indian pharmaceutical and agricultural distribution under PLI scheme incentives. Fragmented cold-chain networks present first-mover positioning with lower certification barriers than German automotive markets. Pursue equipment-as-a-service contracting to bypass capital constraints among mid-size food and beverage distributors. For Investors and Strategic Acquirers: The market sits at an early consolidation phase that favors engineering consultancies with functional safety certification depth over hardware manufacturers facing margin compression. Long-term viability hinges on software-defined perception pipeline differentiation rather than sensor hardware stacking. Monitor 5G private network convergence adoption in Benelux distribution corridors as inflection indicator for retrofit opportunity scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Middleware Development Partnership | Harmonizes multi-vendor navigation protocols for warehouse operators lacking in-house integration capability. |
| Functional Safety Certification Investment | Accelerates type-approval timelines under Japan METI robot guidelines and EU AI Act risk classification. |
| Equipment-as-a-Service Platform Launch | Transfers residual value risk to lessors while capturing 36-month replacement cycle economics. |
| Vision-Guided Product Line Expansion | Reduces per-vehicle sensor costs by 30-40 percent while maintaining localization accuracy thresholds. |
| Regional Leasing Platform Acquisition | Captures Southeast US distribution hub demand through bundled maintenance and utilization insurance. |
Methodological Framework
The analysis maps automated guided vehicle, self-driving forklift, robotic forklift, and dockless forklift configurations, each validated through warehouse operations directors, OEM procurement teams, systems integrators, and aftermarket service heads. Primary interviews with fleet managers at German distribution hubs, Japanese automotive assembly plants, and US third-party logistics networks combined with secondary validation from EU machinery directive filings, METI robot certification databases, OSHA incident reports, and SEC 10-K equipment revenue disclosures. Bottom-up unit deployment estimates triangulated against top-down warehouse automation capex projections.
Assumptions held fixed include EU AI Act explainability requirements, OSHA liability allocation frameworks, and lithium iron phosphate thermal constraints above 40°C ambient. Segmentation modeling spanned product type, end user, technology, and application dimensions across the analysis window. CAGRs derived from logistic curve fitting to historical fleet deployment patterns, with sensor cost trajectories and e-commerce fulfillment density serving as primary demand elasticity inputs.
Stress conditions across LiDAR supply disruption severity, OSHA regulatory clarification timing, and battery chemistry substitution timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against customs data for solid-state sensor import volumes and regional equipment finance platform origination rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Germany Automotive Pneumatic Actuators Market
Automotive Parts
North America Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Argentina Automotive Actuators Market
Automotive Parts
Germany Automotive Hydraulic Actuators Market
Automotive Parts
Global Automotive Plain Carbon ERW Tubes Market
Automotive Parts
Automotive Differential Housing Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
Turkey Passenger Vehicles Lubricants Market
Automotive Parts
HCV Brake Components Market
Automotive Parts
Automotive Brake Shims Market
Automotive Parts
Automotive Thermal Systems Market
Automotive Parts
United States Automotive Glass Market
Automotive Parts
Latin America Electric Power Steering Market
Automotive Parts
North America Automotive Foams Market
Automotive Parts
Morocco Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Proportioning Valves Market