
 Germany Passenger Vehicles Lubricants Market | 2026-2036
Germany Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Passenger Vehicles Lubricants Market Foresight
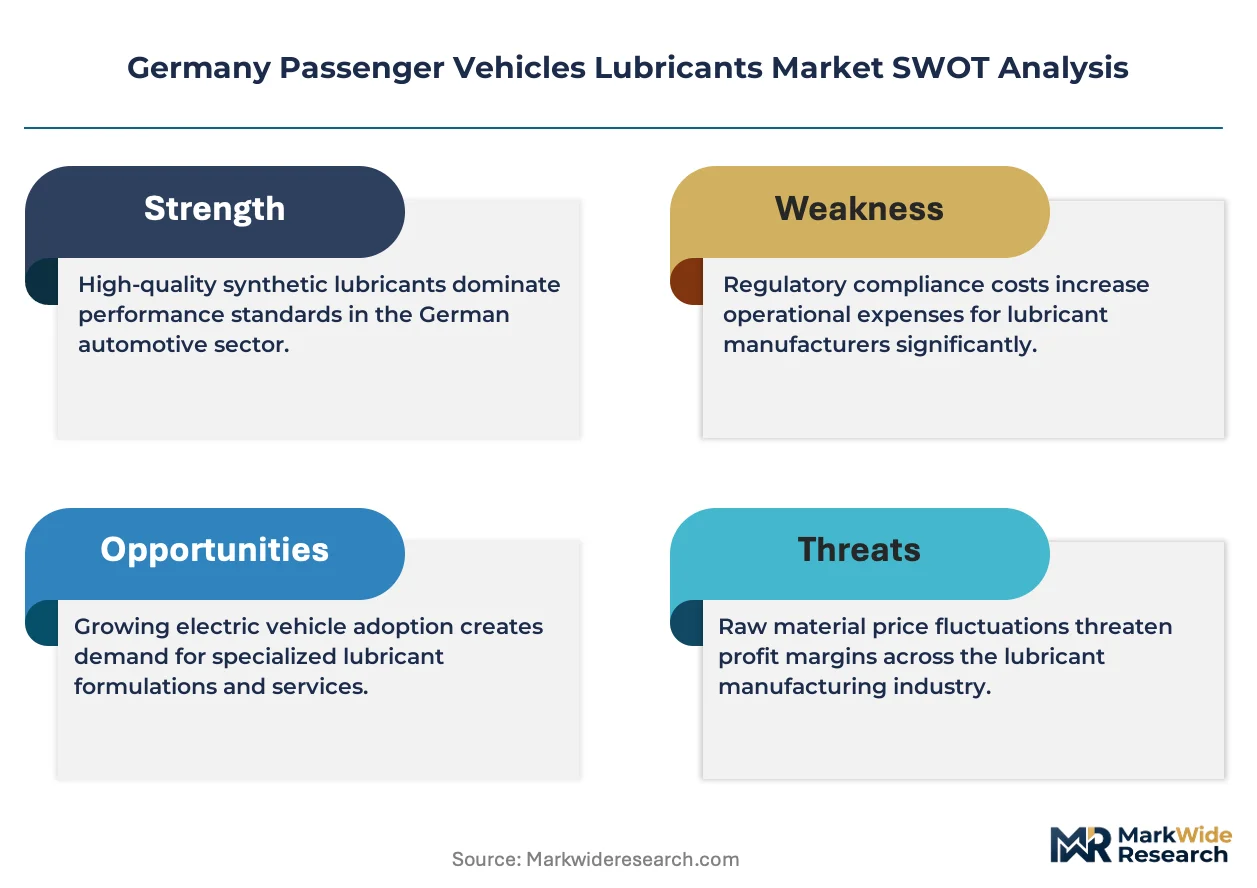
The independent automotive workshop channel is narrowing as dealership networks and consolidated service chains capture a growing share of routine lubricant changes. LIQUI MOLY leverages its German manufacturing base and motorsport pedigree to sustain premium positioning among independent garages. TotalEnergies competes through integrated fuel-and-lube retail sites that anchor highway corridor coverage. FUCHS differentiates via specialized industrial-to-automotive technology transfer, particularly in synthetic ester chemistry.
Germany passenger vehicles lubricants comprise refined base oils blended with additive packages to meet ACEA, API, and OEM-specific viscosity and performance standards, with formulations ranging from conventional mineral oils to full-synthetic PAO and Group III+ bases designed to reduce friction, dissipate heat, and extend drain intervals in internal combustion and hybrid powertrains. Engine oil dominates volume as the most frequently serviced fluid category, though transmission fluid generates higher per-liter margins due to complex OEM specification fragmentation and limited aftermarket alternatives. Electric vehicles present a structural shift: while battery EVs eliminate engine oil demand, their thermal management coolants and reduction gear lubricants create emerging specification requirements that incumbent suppliers must navigate.
KBA type-approval processes and EU REACH chemical registration requirements shape formulation chemistry and market access, with the EU Green Deal and national CO2 fleet targets indirectly accelerating demand for low-viscosity, fuel-economy-grade lubricants. ACEA sequences and OEM-specific approvals such as VW 508.00/509.00 create technical barriers that filter out non-certified suppliers and concentrate margin pools among approved blenders. Stakeholders must monitor how Euro 7 emission standards and Germany's phase-out timeline for internal combustion engines redefine product-portfolio priorities across synthetic, semi-synthetic, and mineral oil tiers.
Market Dynamics
The EU F-Gas Regulation and ACEA oil sequences are compressing formulation tolerances while hybrid powertrain proliferation extends drain intervals, forcing blenders to capture margin through specification complexity rather than volume throughput.
Growth Catalysts
- Fleet preventive maintenance expansion:Commercial operators in Baden-Württemberg are lengthening service intervals for diesel and hybrid units, sustaining workshop lubricant throughput despite private vehicle mileage decline.
- EU Green Deal CO2 targets:National fleet emission mandates accelerate demand for low-viscosity 0W-20 and 0W-16 grades that reduce parasitic engine friction.
- ACEA C5/C6 sequences:Low-SAPS formulations required for gasoline particulate filter compatibility create specification barriers that concentrate margin pools among certified suppliers.
Market Restraints
- Group III base oil import concentration:Refinery capacity limitations in Central Europe tie German blenders to Middle Eastern and Asian supply, exposing margins to freight rate volatility and currency fluctuation.
- Internal combustion phase-out timeline:Germany's 2035 ICE prohibition caps long-term engine oil demand visibility, compressing capital deployment horizons for new blending capacity.
- Electric vehicle fluid substitution:Battery EVs eliminate crankcase lubricant requirements entirely, though thermal management coolants and e-axle greases present partial offset volumes.
Strategic Opportunities
- Bavaria automotive cluster densification:Munich-Stuttgart corridor OEM headquarters and tier-one supplier concentration creates captive demand for co-developed factory-fill and service-fill specifications.
- E-axle reduction gear lubricants:High-speed electric drivetrains require novel synthetic ester formulations with copper corrosion resistance and electrical conductivity control.
- KBA type-approval integration:Streamlined vehicle certification pathways enable faster market introduction of OEM-specific lubricant grades tied to new powertrain launches.
Industry Challenges
- REACH chemical registration timelines:Novel additive chemistry requires multi-year ECHA dossier preparation, delaying formulation responses to Euro 7 emission hardware changes.
- Workshop technician specification literacy:ACEA/API/OEM approval fragmentation demands continuous training investment to prevent misapplication of incompatible viscosity grades in modern engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Passenger Vehicles Lubricants Market |
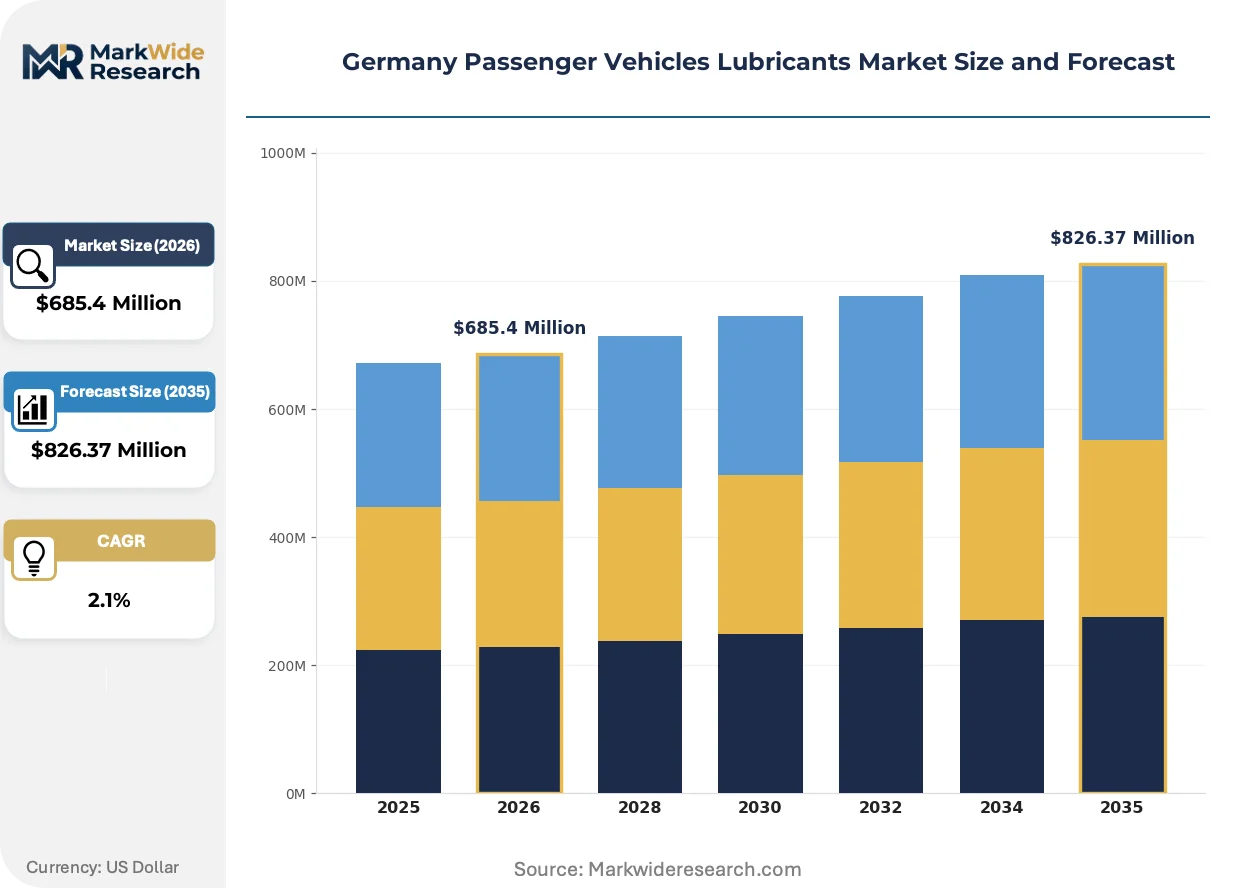
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $826.37 Million |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Brake Fluid, Coolants Vehicle Category: Compact Cars, Sedans, SUVs, Electric Vehicles, Hybrids Distribution Channel: Automotive Workshops, Retail Stores, Online Platforms, Dealership Networks End User: Individual Vehicle Owners, Fleet Operators, Ride-Hailing Services, Car Rental Agencies |
| Companies Covered | LIQUI MOLY, TotalEnergies, BP PLC (Castrol), ROWE MINERALÖLWERK GMBH, AVISTA OIL, ExxonMobil Corporation, Royal Dutch Shell Plc, Finke Mineralölwerk GmbH, FUCHS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Passenger Vehicles Lubricants Market Shifts & Advancements
Formulation chemistry and distribution economics are diverging sharply as electrification redefines fluid requirements and consolidated retail chains capture service bay access.
Group III+ and PAO base stocks are collapsing the performance gap between synthetic and mineral formulations. Independent garages in Bavaria now specify full-synthetic grades for 70 percent of gasoline services, up from 40 percent five years prior. This shift is collapsing the addressable market for conventional 5W-30 mineral blends and compressing margin structures for non-differentiated suppliers.
The EU F-Gas Regulation is tightening specifications for fluorinated greenhouse gas content in manufacturing processes. German blenders must retrofit production lines with alternative blowing agents and refrigeration recovery systems. Smaller compounders without capital access are exiting ACEA C-segment certification, concentrating supply among integrated majors.
Service bundling through dealership networks is displacing standalone lubricant purchases. Munich and Stuttgart metropolitan drivers increasingly accept fixed-price maintenance packages that obscure fluid costs within consolidated billing. This pattern is most visible among premium vehicle owners where manufacturer loyalty programs lock in captive workshop attendance.
Germany Passenger Vehicles Lubricants Market Segmentation
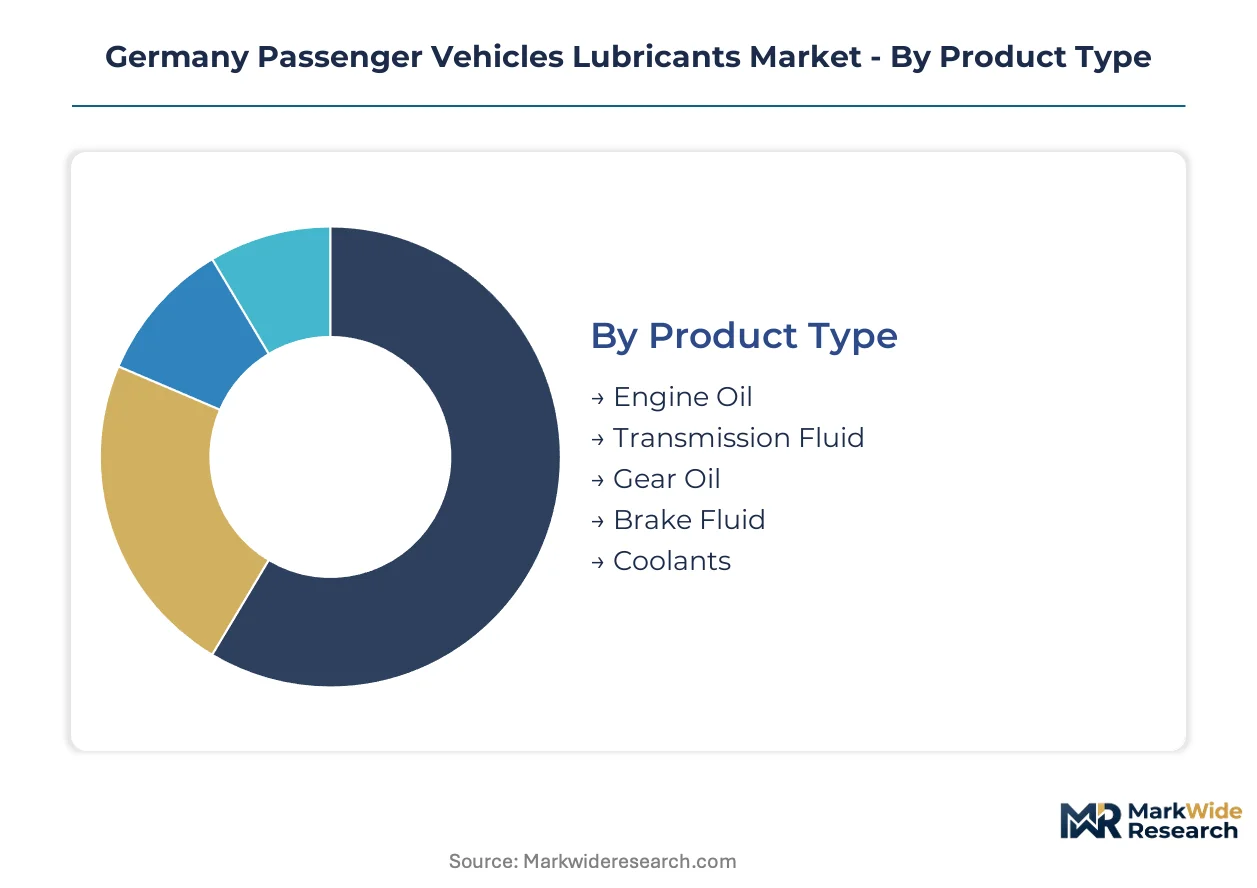
Segmentation in Germany passenger vehicles lubricants reveals how specification complexity, powertrain diversity, and channel consolidation reshape competitive priorities. Each dimension exposes distinct margin pools and technical barriers that determine supplier positioning.
Product Type:
Use-case spectrum spans thermal management, friction reduction, and hardware protection across divergent powertrain architectures.
- Engine Oil:Formulations range from mineral 5W-30 to full-synthetic 0W-16 PAO bases meeting ACEA C6 and VW 508.00 specifications. Demand concentrates in Baden-Württemberg workshops servicing diesel and hybrid fleets where extended drain intervals sustain volume throughput despite mileage compression.
- Transmission Fluid:Complex OEM-specific ATF and DCT formulations command premium margins due to limited aftermarket alternatives and specification fragmentation. Bavaria's premium vehicle density drives concentration where ZF and Getrag factory-fill approvals create captive supply relationships.
- Gear Oil:Hypoid and limited-slip differential lubricants serve rear-wheel-drive architectures in performance segments.
- Brake Fluid:DOT 4 and DOT 5.1 glycol-ether bases require hygroscopicity management in humid climates.
- Coolants:Organic acid technology and hybrid-specific low-conductivity formulations address thermal management in electrified powertrains.
The dominant share belongs to Engine Oil, while Transmission Fluid is closing the gap fastest through specification premiumization.
Vehicle Category:
Powertrain electrification splits the addressable market between combustion-dependent fluids and emerging thermal management chemistries.
- SUVs:Higher displacement engines and all-wheel-drive architectures increase sump capacity and fluid consumption per service. Stuttgart-OEM premium SUV platforms sustain demand for high-performance 0W-40 and 5W-40 grades in independent workshop channels.
- Electric Vehicles:Battery platforms eliminate crankcase lubricant demand entirely while creating specification requirements for e-axle reduction gear oils and dielectric coolants. Munich-area EV registration clusters drive pilot volumes for novel copper-compatible synthetic ester formulations.
- Compact Cars:Downsized turbocharged gasoline engines dominate first-vehicle ownership segments.
- Sedans:Fleet-operated diesel variants sustain commercial service intervals.
- Hybrids:Start-stop cycling and thermal load variation stress conventional lubricant stability.
SUVs retain the largest fluid volume per vehicle, though Electric Vehicles are expanding most quickly through alternative specification categories.
Distribution Channel:
Channel economics determine whether suppliers capture margin through specification control or volume throughput.
- Automotive Workshops:Independent garages in Bavaria specify full-synthetic grades for seventy percent of gasoline services. KBA type-approval integration and technician certification programs concentrate supply among ACEA-licensed blenders with training infrastructure.
- Dealership Networks:Munich and Stuttgart metropolitan fixed-price maintenance packages obscure fluid costs within bundled billing. OEM loyalty programs lock in captive workshop attendance where manufacturer-branded lubricants command specification premiums.
- Retail Stores:DIY consumers in eastern federal states favor price-transparent mineral oil tiers.
- Online Platforms:E-commerce penetration remains limited by specification literacy barriers and immediate fulfillment requirements.
Dealership Networks capture margin through bundling, while Automotive Workshops defend volume through technical service relationships.
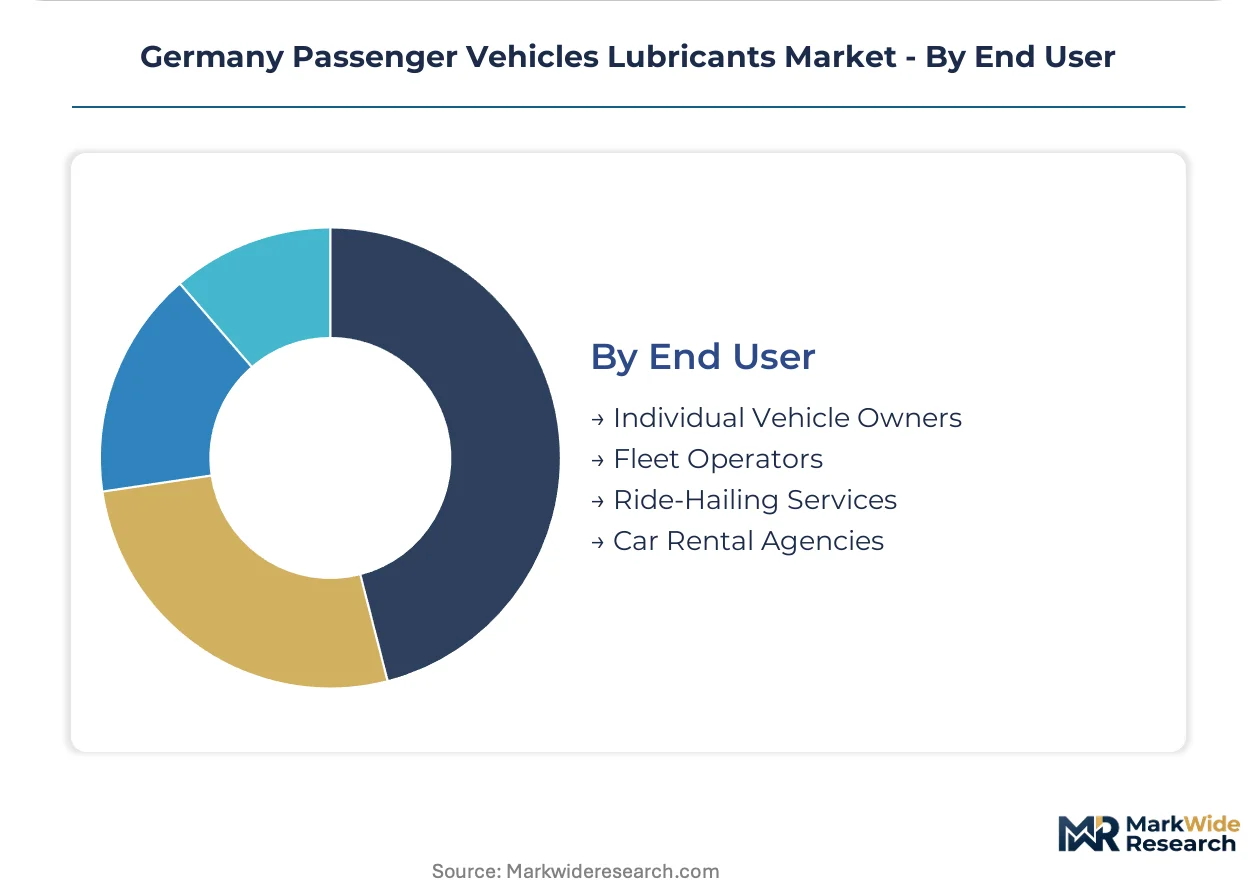
End User:
Ownership models segment demand between mileage-intensive commercial operators and declining private vehicle usage.
- Fleet Operators:Baden-Württemberg commercial diesel and hybrid fleets extend preventive maintenance schedules to maximize powertrain warranty compliance. Centralized procurement contracts favor approved suppliers with national logistics coverage and bulk dispensing systems.
- Individual Vehicle Owners:Declining annual mileage compresses service frequency in private passenger segments. Price sensitivity drives channel switching between workshops and retail for routine oil changes.
- Ride-Hailing Services:High-utilization urban platforms accelerate wear and shorten drain intervals.
- Car Rental Agencies:Turnover-driven maintenance prioritizes cost minimization over specification optimization.
Fleet Operators sustain the steadiest throughput, while Ride-Hailing Services are gaining share fastest through utilization intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KBA type-approval processes anchor Germany's lubricant regulatory framework, with regional demand clustering around automotive manufacturing corridors and fleet operator densities that sustain workshop throughput across federal states.
Bavaria
Munich-Stuttgart corridor OEM headquarters and tier-one supplier concentration drives captive demand for co-developed factory-fill specifications. EU F-Gas Regulation compliance requirements filter formulation chemistry toward low-SAPS ACEA C6 sequences. Ingolstadt and Munich metropolitan clusters sustain premium workshop density where full-synthetic 0W-20 grades dominate gasoline service volumes.
Baden-Württemberg
Stuttgart-OEM premium SUV platforms sustain demand for high-performance 0W-40 and 5W-40 grades in independent channels. Fleet operators in the region extend preventive maintenance schedules for diesel and hybrid commercial units. Karlsruhe and Mannheim logistics hubs anchor centralized procurement contracts that favor approved suppliers with national bulk dispensing coverage.
North Rhine-Westphalia
Ruhr industrial heritage and dense private vehicle populations sustain mineral oil tier demand in price-sensitive segments. REACH chemical registration timelines delay novel additive introduction for Euro 7 hardware compatibility. Cologne-Düsseldorf corridor dealership networks capture fixed-price maintenance bundling that obscures fluid costs within consolidated billing.
Lower Saxony
Wolfsburg OEM captive supply relationships concentrate factory-fill specification development among integrated majors. Hanover logistics infrastructure supports nationwide distribution of ACEA-licensed blend volumes. Brunswick technical training centers address technician specification literacy gaps for ACEA/API/OEM approval fragmentation.
Hesse
Frankfurt financial services fleet operators prioritize warranty-compliant centralized procurement for hybrid powertrain maintenance. EU Green Deal CO2 fleet targets accelerate specification shifts toward low-viscosity fuel-economy grades. Darmstadt additive research clusters feed ECHA dossier preparation for novel chemistry registration timelines.
Germany Passenger Vehicles Lubricants Market Competitive Landscape
Integrated energy majors and specialized German compounders split the market through divergent channel strategies. The vendor base concentrates among ACEA-licensed blenders with training infrastructure and KBA type-approval integration capabilities. Three archetypes dominate: vertically integrated oil majors with retail fuel-and-lube networks, German manufacturing specialists with motorsport pedigree positioning, and industrial-to-automotive technology transfer players. Competitive moves center on specification complexity capture and dealership network bundling partnerships.
Within the German manufacturing specialist tier, LIQUI MOLY and ROWE MINERALÖLWERK GMBH occupy positions anchored by domestic production bases and independent garage channel relationships. Among integrated majors, TotalEnergies exemplifies the fuel-and-lube retail site strategy that anchors highway corridor coverage. FUCHS represents the industrial-to-automotive technology transfer archetype, with specialized synthetic ester chemistry capabilities feeding passenger vehicle formulation development.
| Leading Market Players |
|---|
| LIQUI MOLY |
| TotalEnergies |
| BP PLC (Castrol) |
| ROWE MINERALÖLWERK GMBH |
| AVISTA OIL |
| ExxonMobil Corporation |
| Royal Dutch Shell Plc |
| Finke Mineralölwerk GmbH |
| FUCHS |
| Others |
Supply & Pricing Matrix
Middle Eastern Group III base oil concentration ties German blenders to long-haul freight exposure, concentrating margin pools among integrated majors with captive refining or contract hedging while compressing independent compounders between raw material volatility and ACEA certification costs.
Pricing Analysis
Bavaria commands a 12-18 percent premium over eastern federal states for identical ACEA C6 formulations, reflecting workshop density and OEM captive demand. Pricing stratifies across premium synthetic ester, standard Group III+, and economy mineral tiers, with differentiation driven by OEM approval scarcity and volume scale. Cost compression in the mineral tier is intensifying because retail DIY channels absorb price-transparent imports. Fleet operators show least price sensitivity due to warranty compliance requirements, while individual vehicle owners in North Rhine-Westphalia exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between Middle Eastern suppliers and German blenders dominates supply chain risk assessment, with freight rate volatility transmitting directly to formulation costs. Geographic supply concentration centers on Qatar, South Korea, and the Netherlands for Group III+ and PAO base stocks. Raw material dependencies encompass additive packages from Belgium, corrosion inhibitors from Japan, and viscosity modifiers from the United States. Single-source vulnerability persists for VW 508.00/509.00 OEM approval chemistry. Distribution runs through Karlsruhe and Hanover bulk terminals to workshop dispensing systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification fragmentation across hybrid, diesel, and emerging electric powertrains creates niche opportunities for specialized compounders with targeted chemistry capabilities.
For Market Incumbents: Insulate margin pools by deepening backward integration into synthetic ester chemistry and securing exclusive dealership bundling contracts in Munich-Stuttgart corridor. Electric vehicle fluid substitution threatens long-term engine oil volumes, making e-axle reduction gear formulation investment the priority defensive lever. ACEA C6 certification concentration among smaller blenders presents acquisition targets for specification portfolio extension. For New Entrants and Emerging Players: Build out dedicated e-axle lubricant capabilities targeting Munich-area EV registration clusters where copper-compatible synthetic ester demand outpaces incumbent supply. The most penetrable white-space sits in dielectric coolant formulations for battery thermal management, currently dominated by industrial chemical crossovers with limited automotive validation. A go-to-market angle through tier-one supplier technical partnerships bypasses dealership channel capture. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed German manufacturing specialists holding regional brand equity but lacking electric powertrain chemistry roadmaps. Long-term viability hinges on portfolio transition timing relative to ICE phase-out trajectory. The signal to watch is KBA type-approval velocity for novel EV fluid categories as inflection indicator for incumbent response speed.| Strategic Initiative | Industry Significance |
|---|---|
| E-Axle Lubricant Development | Captures emerging specification demand from ZF and Getrag high-speed electric drivetrain programs. |
| Backward Integration into Base Oil | Reduces exposure to Middle Eastern freight volatility and currency fluctuation for German blenders. |
| Dealership Bundling Partnerships | Locks in captive workshop attendance where fixed-price maintenance obscures fluid cost transparency. |
| REACH-Compliant Additive Investment | Accelerates ECHA dossier preparation for Euro 7 hardware compatibility ahead of regulatory deadlines. |
| Technician Certification Programs | Builds specification literacy infrastructure that filters supply toward ACEA-licensed blenders. |
Research Methodology
The analysis maps engine oil, transmission fluid, gear oil, and emerging EV fluid categories, each validated through plant managers at blending facilities, procurement leads at OEM service operations, distribution channel partners, and aftermarket workshop operators. Primary interviews triangulated with KBA registration databases, ACEA oil sequence documentation, customs trade data for base oil imports, and EU REACH chemical registration filings. Bottom-up volume estimates from federal state workshop throughput combined with top-down lubricant consumption models.
Analytical assumptions held ICE phase-out timeline and EU F-Gas Regulation compliance costs fixed while varying hybrid powertrain penetration and EV registration velocity across the projection horizon. Segmentation dimensions modeled include product type, vehicle propulsion architecture, distribution channel concentration, and regional manufacturing cluster density. CAGRs derived from elasticity-adjusted demand curves incorporating drain interval extension effects. Industry-specific inputs encompass fleet operator maintenance schedule data and OEM factory-fill specification roadmaps.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Middle Eastern base oil producers or accelerated EU Green Deal implementation would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Indonesia Automotive Engine Oils Market
Automotive Parts
Automotive Bellows Market
Automotive Parts
North America Automotive Parts Die Casting Market
Automotive Parts
Rear Spoiler Market
Automotive Parts
Electromagnetic Clutches Market
Automotive Parts
Automotive Seat Track Market
Automotive Parts
Automotive Wiping Systems Market
Automotive Parts
United States Passenger Vehicles Lubricants Market
Automotive Parts
Poland Passenger Vehicles Lubricants Market
Automotive Parts
Car Refrigerator Market
Automotive Parts
Auto Parts Manufacturing Market
Automotive Parts
Vehicle Jump Starter Market
Automotive Parts
Egypt Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Closure Market
Automotive Parts
North America Gear Market
Automotive Parts
Industrial Gearbox and Gear Motors Market