
 Cabin Air Filter Housing Replacement Parts Market | 2026-2036
Cabin Air Filter Housing Replacement Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Cabin Air Filter Housing Replacement Parts Market Insights
Multi-source procurement among tier-1 suppliers is expanding as vehicle assemblers diversify supply risk across geographic zones. MANN+HUMMEL leverages captive injection molding capacity across European and North American plants to control cost structures for plastic housing programs. MAHLE anchors its position through backward integration into filter media and housing design, sustaining margin capture across the replacement cycle. Robert Bosch competes on channel density, operating direct-to-workshop distribution networks that bypass traditional wholesale tiers in key automotive service markets.
Cabin air filter housing replacement parts encompass the structural enclosures, sealing elements, and mounting interfaces that secure filtration media within HVAC intake systems, typically engineered from glass-reinforced polypropylene or aluminum die-cast alloys to withstand thermal cycling and vibration loads across 150,000-plus mile service intervals. Plastic housing segments dominate current volume due to cost parity and corrosion resistance, while composite housing categories are gaining structural share as OEMs pursue mass reduction targets in electric vehicle architectures. Application demand from passenger vehicles remains the mature revenue base, whereas commercial truck replacement cycles generate premium pricing for metal housings subjected to severe-duty thermal and particulate loading.
EPA enforcement under the Clean Air Act influences cabin air quality system durability standards, while NHTSA safety regulations govern material flammability and crashworthiness of interior HVAC components. EMA and REACH compliance in Europe restricts certain phthalate plasticizers in rubber seals, redirecting formulation investments toward bio-based elastomer alternatives. Stakeholders must monitor regulatory divergence between EPA and EMA test protocols, as divergent certification requirements threaten to fragment tooling and inventory strategies across Atlantic supply corridors.
Market Dynamics
Fleet operators across North America are extending vehicle replacement cycles beyond 12 years, forcing aftermarket distributors to stock deeper inventories of cabin air filter housings calibrated for degraded HVAC sealing performance in aging intake systems.
Growth Catalysts
- EPA Clean Air Act enforcement:Tailpipe and cabin air quality standards are tightening material specifications for rubber seals and plastic housings, compelling replacement part upgrades across registered vehicle pools.
- Glass-reinforced polypropylene adoption:Injection molding advances are lowering unit costs for corrosion-resistant plastic housings while maintaining thermal cycling durability through 150,000-mile service intervals.
- Fleet operator procurement centralization:Large commercial vehicle operators are consolidating supplier relationships to secure volume pricing on severe-duty metal housings for truck replacement cycles.
Market Restraints
- Aluminum die-cast input volatility:Energy-intensive smelting costs for metal housing alloys expose margin compression when electricity and scrap aluminum prices spike.
- European supply concentration:MANN+HUMMEL and MAHLE anchor captive molding capacity in Germany and Poland, creating geographic dependency for North American aftermarket distributors.
- REACH phthalate restrictions:ECHA limitations on conventional rubber plasticizers force reformulation investments that delay seal certification timelines for cross-Atlantic parts programs.
Strategic Opportunities
- Electric vehicle mass reduction mandates:Composite housing categories are gaining specification share as OEMs pursue lightweight HVAC architectures in battery-electric platforms.
- Direct-to-workshop channel expansion:Bypassing traditional wholesale tiers through Bosch-style distribution networks captures margin from independent repair shops in fragmented U.S. service markets.
- Bio-based elastomer certification:Bio-derived seal compounds compliant with EMA sustainability frameworks command premium positioning in European environmental zones.
Industry Challenges
- Multi-protocol tooling fragmentation:Divergent EPA and EMA test standards threaten inventory duplication as housings require separate certification molds for Atlantic corridor markets.
- Legacy HVAC integration complexity:Replacement housings must interface with degraded mounting interfaces in vehicles beyond 10 years of age, raising warranty exposure for aftermarket suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cabin Air Filter Housing Replacement Parts Market |
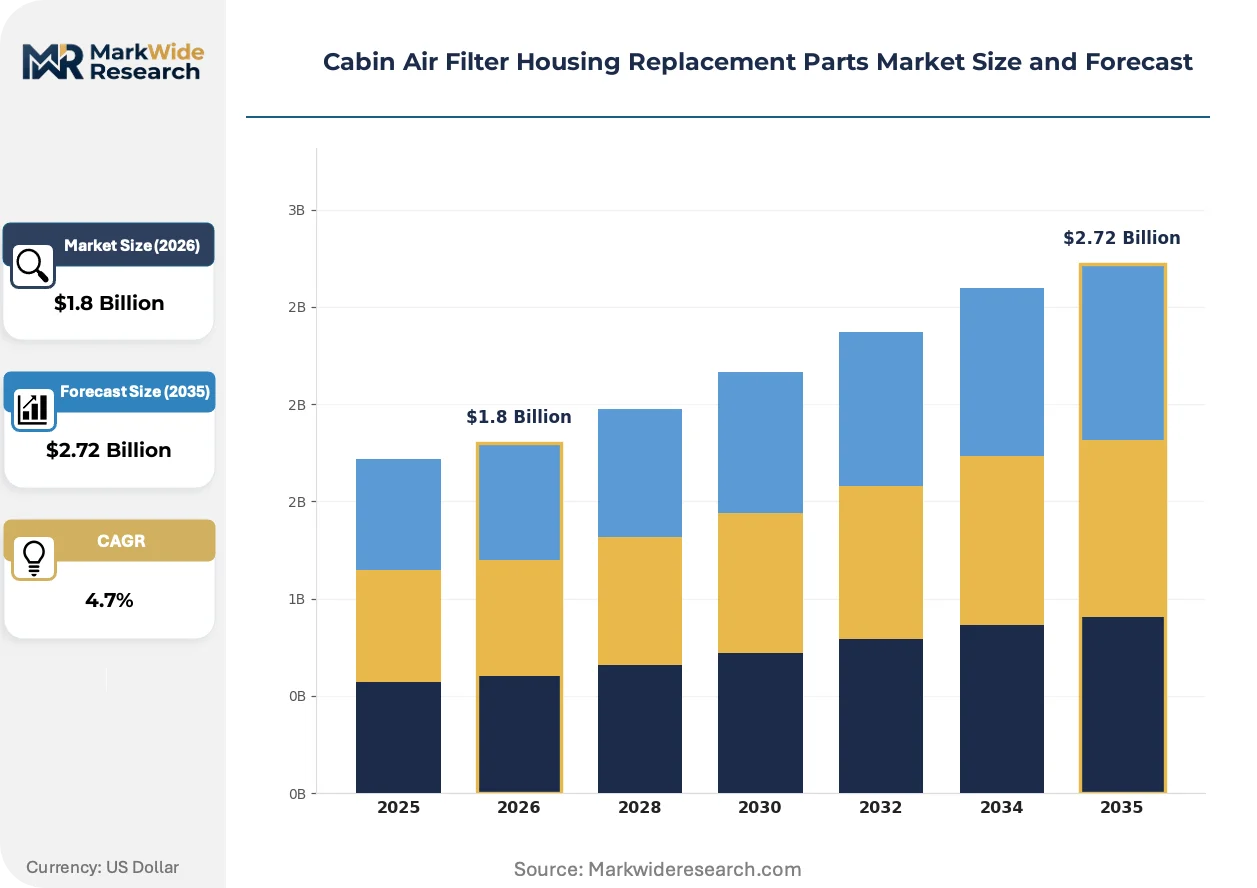
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Housing, Metal Housing, Composite Housing, Rubber Seals, Foam Gaskets Technology: Injection Molding, Blow Molding, Thermoforming, Die Casting, Compression Molding Application: Passenger Vehicles, Commercial Trucks, Construction Equipment, Agricultural Machinery, Motorcycle End User: Aftermarket Retailers, Vehicle Assemblers, Tier-1 Suppliers, Automotive Workshops, Fleet Operators |
| Companies Covered | MANN+HUMMEL, MAHLE, Robert Bosch, DENSO, Sogefi, Freudenberg, Donaldson Company, Parker Hannifin, K&N Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cabin Air Filter Housing Replacement Parts Market Trends and Innovations
Material science advances and regulatory protocol divergence are compressing product development cycles while opening premium positioning for certified sustainable alternatives in transatlantic supply corridors.
Glass-reinforced polypropylene compounds with enhanced thermal stability are rewriting competitive economics for plastic housing programs. Tier-1 suppliers are migrating passenger vehicle volumes to these formulations to offset aluminum cost volatility. The technology is compressing price premiums previously commanded by metal housings in standard-duty applications.
REACH compliance deadlines for phthalate-free rubber seals are accelerating formulation turnover across European supply bases. ECHA restrictions are redirecting R&D spending toward bio-based elastomer alternatives with equivalent compression set performance. Seal manufacturers serving EMA-regulated markets are consolidating supplier relationships to secure certified compound streams.
Workshop-level procurement consolidation is fragmenting traditional wholesale channel structures. Independent repair networks in the United States are negotiating direct supply agreements with housing manufacturers, disintermediating regional parts distributors. The behavior is most visible in high-turnover metropolitan service corridors where inventory velocity justifies bypass economics.
Cabin Air Filter Housing Replacement Parts Market Segmentation
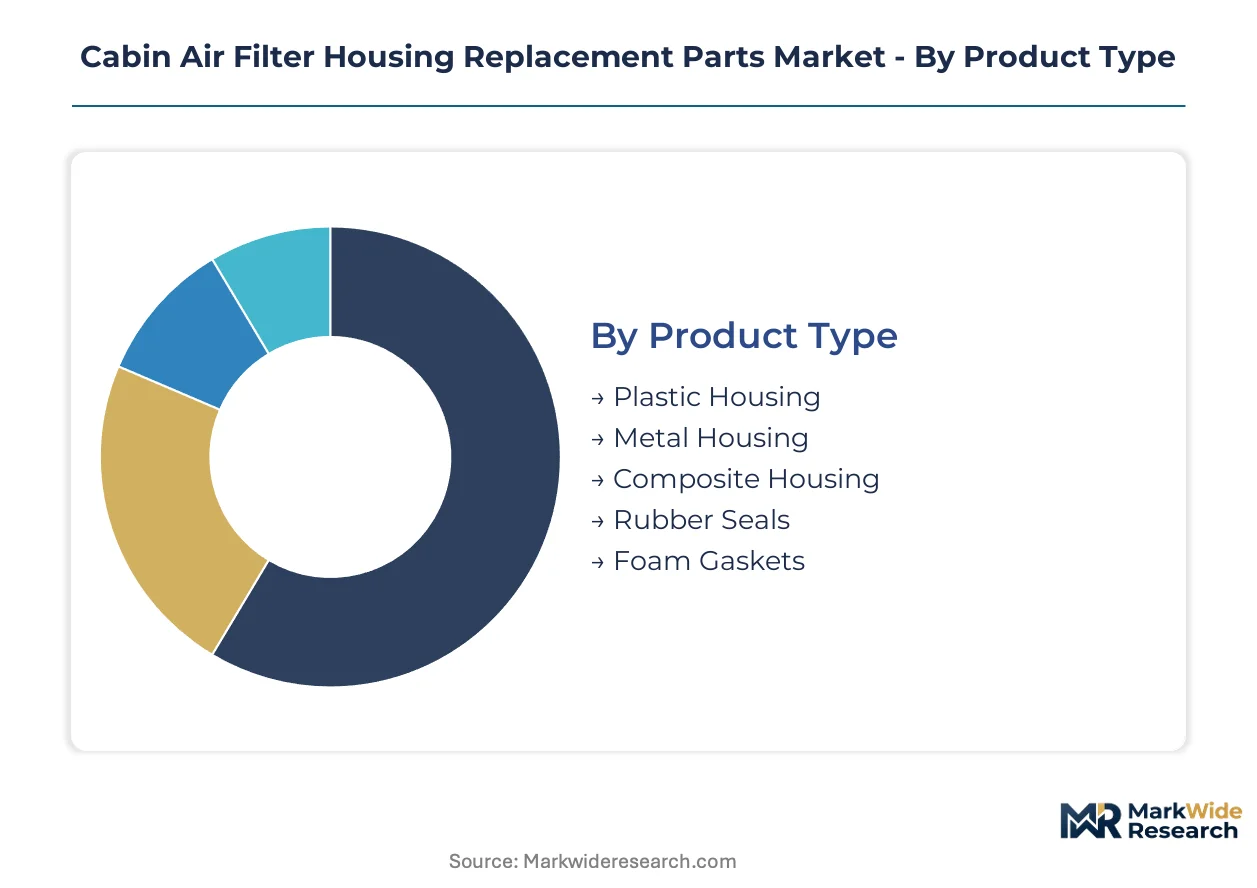
Segmentation in cabin air filter housing replacement parts reveals how material specifications, manufacturing processes, and end-use durability requirements fragment procurement strategies across automotive service channels. Certification burdens vary sharply by segment, with EPA and NHTSA compliance timelines diverging from EMA and REACH protocols for cross-Atlantic parts programs.
Product Type:
Certification requirements split across material categories, with plastic and composite housings facing distinct EPA thermal cycling standards versus metal housings governed by NHTSA crashworthiness and corrosion protocols.
- Plastic Housing:Glass-reinforced polypropylene formulations dominate passenger vehicle replacement volumes due to corrosion resistance and injection molding cost efficiency. Fleet operators in the United States specify these housings for vehicles beyond 150,000-mile service intervals where thermal degradation accelerates.
- Metal Housing:Aluminum die-cast alloys withstand severe-duty thermal and particulate loading in commercial truck replacement cycles. Energy-intensive smelting costs expose margin compression when electricity prices spike, constraining procurement flexibility for North American fleet operators.
- Composite Housing:Hybrid material constructions gaining specification share in electric vehicle architectures pursuing mass reduction targets.
- Rubber Seals:EPDM and silicone compounds facing REACH phthalate restrictions requiring bio-based elastomer reformulation for European market access.
- Foam Gaskets:Polyurethane and polyethylene foam elements providing vibration dampening in degraded mounting interfaces of aging HVAC systems.
Plastic housing sits at the top of the volume ranking, with composite housing climbing the fastest as OEMs pursue lightweight HVAC architectures in battery-electric platforms.
Technology:
Manufacturing process selection tracks material category, with molding technologies commanding aftermarket plastic volumes while casting methods anchor metal housing production for severe-duty applications.
- Injection Molding:Captive capacity at tier-1 suppliers enables cost control for high-volume plastic housing programs serving passenger vehicle aftermarket channels. MANN+HUMMEL leverages European and North American plant networks to manage resin input volatility.
- Die Casting:Aluminum alloy solidification processes producing structural housings for commercial truck HVAC systems subjected to thermal cycling extremes. Scrap aluminum price fluctuations compress margins when energy markets tighten.
- Blow Molding:Hollow-forming technology for complex ducting integrations in compact vehicle architectures.
- Thermoforming:Vacuum and pressure forming methods for lower-volume specialty housing geometries.
- Compression Molding:Rubber seal and gasket fabrication requiring REACH-compliant compound certification for European distribution.
Injection molding captures the largest production share, with die casting expanding most quickly in fleet procurement centralization for severe-duty truck replacement cycles.
Application:
Vehicle duty cycles determine housing material specifications, with passenger vehicles driving plastic volumes while commercial and off-road equipment sustains metal housing premium pricing.
- Passenger Vehicles:Mature revenue base for plastic housing replacements calibrated to 10-15 year vehicle age profiles. United States aftermarket service networks stock deepest inventories for degraded HVAC sealing performance in aging intake systems.
- Commercial Trucks:Severe-duty thermal and particulate loading generates premium pricing for metal housings in fleet operator procurement programs. Extended replacement cycles beyond 12 years force distributors to inventory severe-duty specifications.
- Construction Equipment:High-vibration environments requiring reinforced mounting interfaces and corrosion-resistant coatings.
- Agricultural Machinery:Dust-heavy operating conditions accelerating filter housing degradation and replacement frequency.
- Motorcycle:Compact form factors demanding specialized thermoformed and injection-molded housing geometries.
Passenger vehicles command the highest absolute volume, with commercial trucks gaining share fastest through fleet operator procurement consolidation.
End User:
Channel structure fragmentation determines pricing capture, with direct-to-workshop networks disintermediating traditional wholesale tiers in high-velocity metropolitan service corridors.
- Aftermarket Retailers:Traditional distribution tier facing margin compression from workshop-level procurement consolidation. Regional parts distributors in the United States defend position through inventory depth for legacy vehicle pools.
- Automotive Workshops:Independent repair networks negotiating direct supply agreements with housing manufacturers, bypassing wholesale intermediaries where inventory velocity justifies bypass economics.
- Fleet Operators:Large commercial vehicle operators consolidating supplier relationships to secure volume pricing on severe-duty metal housings.
- Vehicle Assemblers:OEM service operations specifying original-equivalent housings for warranty repair networks.
- Tier-1 Suppliers:Captive molding capacity providers integrating backward into filter media and housing design.
Aftermarket retailers retain volume leadership, with automotive workshops climbing fastest through direct procurement channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Detroit-Windsor automotive corridor anchors North American cabin air filter housing procurement, with tier-1 suppliers operating captive molding capacity to serve extended vehicle replacement cycles across aging fleet pools.
United States
Fleet operators stretching replacement cycles beyond 12 years drive aftermarket inventory depth for degraded HVAC sealing components. EPA Clean Air Act enforcement tightens material specifications for rubber seals and plastic housings in registered vehicle pools. The Southeast manufacturing belt, spanning Tennessee and South Carolina, hosts injection molding operations supplying independent repair networks.
Germany
EMA and REACH compliance deadlines force bio-based elastomer reformulation for seal compounds serving European distribution channels. ECHA restrictions on phthalate plasticizers redirect R&D spending toward certified sustainable alternatives. The Stuttgart industrial region concentrates backward-integrated suppliers controlling captive filter media and housing design operations.
China
Domestic vehicle age profiles lengthening toward 8-10 years expand replacement housing demand in aftermarket service channels. MIIT durability standards for HVAC components influence material selection in local supply chains. The Yangtze River Delta manufacturing cluster hosts injection molding capacity serving both domestic consumption and export programs.
Mexico
Nearshoring of automotive component production expands captive molding capacity to serve North American aftermarket distribution. The country's national environmental regulator enforces tailpipe and cabin air quality standards aligned with EPA protocols. The Bajío Region, centered on Guanajuato, attracts tier-1 supplier investments in plastic housing programs.
Japan
METI energy efficiency guidelines influence lightweight HVAC architecture specifications in domestic vehicle platforms. JIS standards govern material flammability and thermal cycling performance for interior components. The Nagoya industrial corridor maintains specialized die-casting capacity for severe-duty commercial vehicle applications.
Cabin Air Filter Housing Replacement Parts Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue composite material specializations for electric vehicle platforms. The market structure concentrates around tier-1 automotive suppliers with backward integration into filtration media and captive molding capacity. Three archetypes dominate: integrated system suppliers controlling resin-to-assembly value chains, channel-focused distributors operating direct-to-workshop networks, and material specialists commanding premium positioning in certified sustainable compounds. Competitive moves center on geographic capacity diversification across Atlantic supply corridors and formulation investments to meet divergent EPA and EMA certification timelines.
Within the integrated supplier tier, MANN+HUMMEL and MAHLE exemplify archetypes of backward-integrated producers. MANN+HUMMEL represents European-based capacity concentration with molding operations spanning multiple continents. MAHLE occupies a position as a German GmbH-structured entity with design integration across the replacement cycle. Robert Bosch anchors the channel-density archetype, with its corporate structure suggesting workshop-level distribution capabilities.
| Leading Market Players |
|---|
| MANN+HUMMEL |
| MAHLE |
| Robert Bosch |
| DENSO |
| Sogefi |
| Freudenberg |
| Donaldson Company |
| Parker Hannifin |
| K&N Engineering |
| Others |
Pricing and Supply Chain Analysis
Fleet operator procurement centralization in North America anchors the dominant contract-based long-term offtake model for severe-duty metal housings, while independent repair networks negotiate spot purchasing for plastic replacement volumes. This buyer-archetype concentration fragments pricing power across tier-1 suppliers and regional distributors.
Pricing Analysis
Input-cost pass-through from aluminum smelting energy exposure and glass-reinforced polypropylene resin volatility shapes tiered pricing across premium severe-duty metal, standard plastic, and economy re-manufactured housings. Price differentiation hinges on EPA certification grade and volume scale in fleet procurement programs. Cost compression in standard plastic tiers is intensifying because injection molding overcapacity in the Southeast manufacturing belt erodes supplier leverage. Fleet operators exhibit highest price sensitivity due to consolidated procurement power, while independent workshops absorb moderate premiums for direct-to-door delivery speed.
Supply Chain Analysis
Single-source vulnerability sits with German and Polish captive molding capacity that feeds North American aftermarket distributors through Atlantic supply corridors. Geographic supply concentration centers on Germany, China, and Mexico for injection molding and die-casting operations. Raw material dependencies draw from glass-reinforced polypropylene resin streams, aluminum alloy scrap, and bio-based elastomer compounds. Regulatory restriction risk looms from REACH phthalate limitations that threaten seal certification timelines. Distribution runs through tier-1 supplier direct-to-workshop networks disintermediating traditional wholesale tiers in high-velocity metropolitan service corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cabin air filter housing replacement parts constitute a late-cycle quality story as fleet operators stretch vehicle replacement cycles beyond 12 years, forcing specification upgrades toward premium severe-duty metal housings and REACH-compliant bio-based seal compounds.
For Market Incumbents: Deploy backward integration into filter media and housing design to capture margin across the replacement cycle. MANN+HUMMEL and MAHLE exemplify this lever through captive molding capacity across European and North American plants. Consolidate supplier relationships to secure certified compound streams for EMA-regulated markets. Counter emerging composite housing specialists in electric vehicle architectures by accelerating glass-reinforced polypropylene thermal stability investments. For New Entrants and Emerging Players: Independent repair networks in fragmented U.S. metropolitan service corridors represent the most penetrable buyer archetype for direct supply agreements bypassing wholesale intermediaries. Workshop-level procurement consolidation creates white-space for housing manufacturers with inventory velocity economics. Target commercial truck fleet operators with severe-duty metal housing specifications as procurement centralization opens volume pricing negotiations. Pursue bio-based elastomer certification for European environmental zone premium positioning. For Investors and Strategic Acquirers: Tier-1 automotive suppliers with backward integration into filtration media represent the most active acquirer in this space, seeking geographic capacity diversification across Atlantic supply corridors. Long-term viability frames around electric vehicle mass reduction mandates accelerating composite housing specification share. Acquisition target archetypes include material specialists commanding premium positioning in certified sustainable compounds. Watch EPA-EMA regulatory divergence as the inflection indicator threatening inventory duplication and tooling fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Media | MAHLE sustains margin capture across replacement cycles through resin-to-assembly control. |
| Direct-to-Workshop Channel Expansion | Bosch-style networks bypass wholesale tiers in fragmented U.S. metropolitan service corridors. |
| Bio-Based Elastomer Certification | REACH-compliant seal compounds command premium positioning in European environmental zones. |
| Composite Housing R&D Investment | OEM mass reduction targets in battery-electric platforms accelerate specification share gains. |
| Geographic Capacity Diversification | Nearshoring to Mexico's Bajío Region reduces Atlantic supply corridor dependency risks. |
Research Methodology
Direct dialogue with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distribution heads, and fleet operator maintenance directors grounded qualitative insights across North American and European supply corridors. Secondary validation drew from EPA enforcement records, ECHA REACH compliance databases, vehicle production registries, and SEC filings of publicly traded automotive component manufacturers. Bottom-up and top-down triangulation reconciled channel inventory estimates with production capacity disclosures.
Bottom-up modeling tracked replacement housing demand by vehicle age profile, duty cycle severity, and regional regulatory cluster across the projection horizon. Segmentation dimensions included material category, manufacturing process, application duty cycle, and end-user channel structure. CAGRs were derived from vehicle fleet age projections and replacement interval assumptions. Industry-specific forecast inputs incorporated EPA Clean Air Act enforcement timelines and electric vehicle platform rollout patterns.
Underlying measurement precision varies by segment; plastic housing volumes carry tighter precision than emerging composite categories. Forecasts reflect assumptions around fleet replacement cycle extension and regulatory protocol convergence. Aluminum price volatility, REACH compliance delays, and electric vehicle adoption speed constitute primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Cylinder Head Gasket Market
Automotive Parts
Global Automotive Plain Carbon ERW Tubes Market
Automotive Parts
Automotive Fastener Market
Automotive Parts
Asia-Pacific Passenger Vehicles Lubricants Market
Automotive Parts
Variable Valve Timing (VVT) Market
Automotive Parts
Automotive Electric Vacuum Pump Market
Automotive Parts
Brake Pad Market
Automotive Parts
Germany Automotive Pneumatic Actuators Market
Automotive Parts
Automotive Key Blanks Market
Automotive Parts
North America Ceramic Ball Bearings Market
Automotive Parts
Lug Wrench Market
Automotive Parts
Mexico Automotive Air Filters Market
Automotive Parts
Automotive Hydraulic Filter System Market
Automotive Parts
Automotive Power Window Regulator Market
Automotive Parts
Brass Synchronizer Ring Market
Automotive Parts
Automotive Remanufactured Parts Market