
 Automotive Composite Leaf Springs Market | 2026-2036
Automotive Composite Leaf Springs Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Composite Leaf Springs Market Analysis
Light commercial vehicle manufacturers are repositioning their chassis portfolios toward composite-intensive architectures to capture fuel economy gains. Hendrickson International leverages its established suspension systems footprint to extend composite leaf spring integration across vocational truck platforms. SGL Carbon anchors European supply chains with specialized carbon fiber preform capabilities tailored to automotive spring specifications. Benteler SGL competes through captive carbon fiber production that controls material cost volatility for high-volume OEM programs.
Automotive composite leaf springs are fiber-reinforced polymer suspension components, typically manufactured from glass or carbon fiber matrices with epoxy or thermoplastic resins via compression molding or filament winding, engineered to store and release mechanical energy while reducing unsprung mass by 60-70% versus conventional steel multi-leaf assemblies. Their primary purpose centers on supporting vehicle axle loads, absorbing road-induced shocks, and maintaining ride height stability across commercial, passenger, and specialty vehicle applications. Multi-axial fiber architectures dominate current OEM specifications due to their balanced torsional rigidity and fatigue resistance, while unidirectional layups represent the fastest-growing configuration for electric vehicle platforms seeking maximum specific stiffness. Glass fiber formulations occupy the largest volume share given their cost-performance ratio for heavy truck suspensions, though carbon fiber variants command premium positioning in motorsport and defense end uses where mass reduction translates directly to payload or maneuverability advantages.
EPA greenhouse gas emission standards for medium and heavy-duty vehicles directly mandate weight reduction pathways that accelerate composite leaf spring qualification timelines, while NHTSA Federal Motor Vehicle Safety Standards govern fatigue life and corrosion performance thresholds that determine market access for new material entrants. The EU Green Deal's transport decarbonization framework and associated CO2 performance standards for heavy-duty vehicles are creating parallel compliance pressure across European OEM supply chains. Stakeholders must monitor evolving crashworthiness test protocols and end-of-life recyclability requirements for fiber-reinforced composites, as these standards will increasingly determine which material technologies and manufacturing processes secure long-term platform adoption.
Market Dynamics
EPA greenhouse gas standards for medium and heavy-duty trucks are compelling chassis redesigns that favor weight-optimized composite suspension components over conventional steel assemblies.
Growth Catalysts
- EPA Phase 3 Standards:The agency's tightened CO2 emission limits for model year 2027 trucks mandate mass reduction pathways that accelerate composite leaf spring qualification timelines across OEM supply chains.
- Freight Efficiency Targets:Heavy-duty commercial vehicle fleets in the United States are accelerating procurement of composite suspension systems as operators pursue fuel economy gains through unsprung mass reduction.
- Carbon Fiber Preform Capabilities:Specialized fiber architectures with multi-axial layups are penetrating electric vehicle platforms seeking maximum specific stiffness for battery-protective suspension designs.
Market Restraints
- Epoxy Resin Cost Volatility:Feedstock price fluctuations for thermoset resins create margin compression for compression-molded spring manufacturers without captive chemical supply.
- European Supply Concentration:Carbon fiber preform production clusters in Germany and France expose automotive programs to single-source geographic risk for premium-grade material.
- End-of-Life Recyclability Gaps:Fiber-reinforced polymer waste streams lack established pyrolysis or solvolysis infrastructure, creating compliance uncertainty under evolving EU circular economy frameworks.
Strategic Opportunities
- Defense Vehicle Programs:United States military ground vehicle modernization is sustaining premium-grade composite spring orders for armor-intensive platforms where payload retention is mission-critical.
- Filament Winding Automation:Convergence of robotic fiber placement with in-situ thermoplastic consolidation is reducing cycle times for high-volume OEM programs.
- Long-Haul Logistics Electrification:Battery-electric truck architectures in California and Texas are specifying composite leaf springs to offset battery pack mass while maintaining ride height stability.
Industry Challenges
- Compression Molding Tooling Lead Times:Multi-cavity die fabrication for complex fiber architectures requires 18-24 month capital cycles that misalign with accelerated OEM platform launches.
- Fatigue Life Certification:NHTSA Federal Motor Vehicle Safety Standards governing corrosion performance and cyclic loading thresholds demand extensive validation protocols that extend time-to-revenue for new material entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Composite Leaf Springs Market |
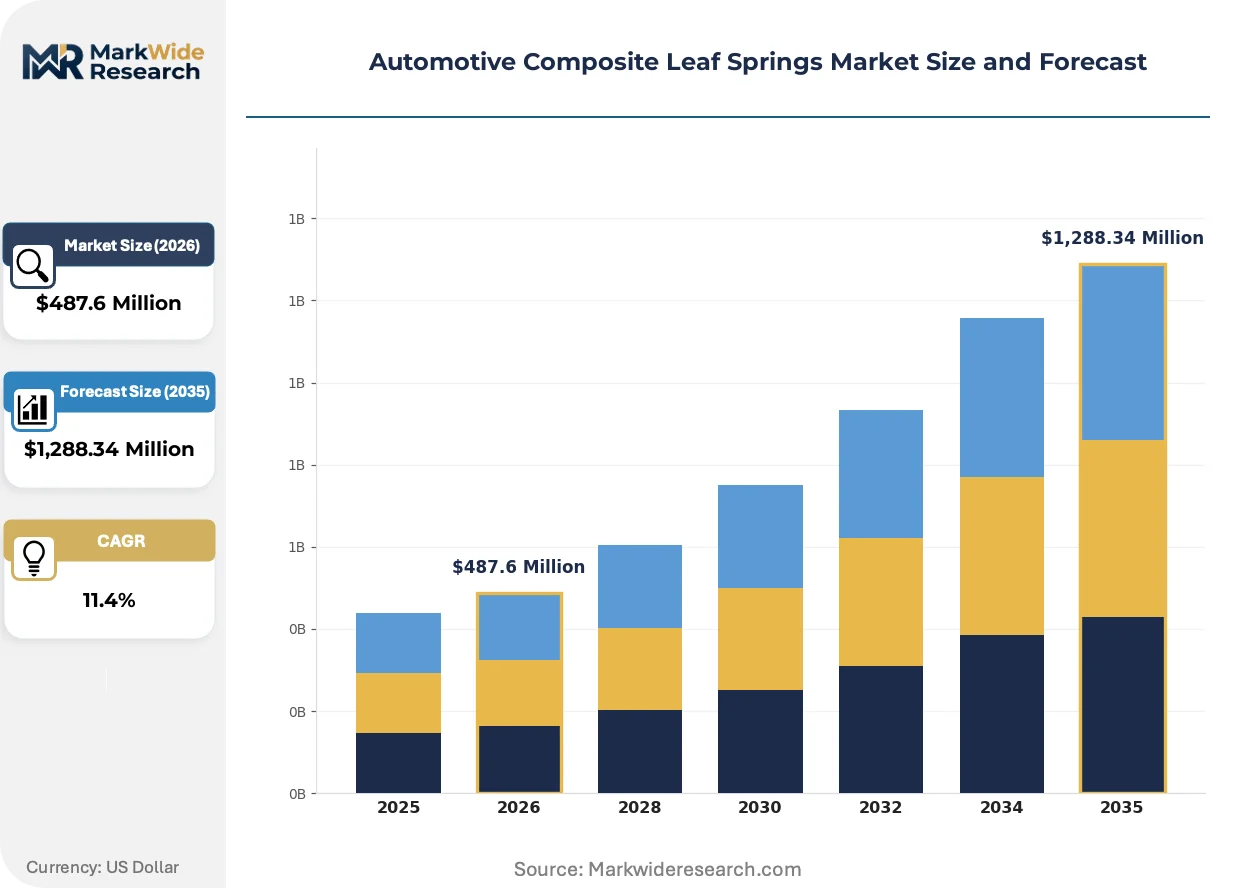
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-Axial, Unidirectional, Sandwich, Hybrid End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Material: Carbon Fiber, Glass Fiber, Thermoplastic, Resin Technology: Injection Molding, Compression Molding, Filament Winding, Thermal Mold |
| Companies Covered | Benteler SGL, LiteFlex, SGL Carbon, Hyperco, ARC Industries, Hendrickson International, Flex-Form, IFC Composite GmbH, Mubea Fahrwerkstechnologien GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Composite Leaf Springs Market Emerging Trajectories
Thermoplastic resin matrices are actively displacing epoxy formulations in next-generation suspension components, while regulatory pressure and procurement model evolution reshape competitive positioning across the value chain.
Unidirectional carbon fiber layups are expanding into electric vehicle chassis architectures as OEMs prioritize specific stiffness metrics for battery protection systems. Tier 1 suppliers in Michigan and South Carolina are qualifying these configurations for 2027 model year platforms. The technology is expanding into premium pickup and vocational truck segments previously served by glass fiber multi-leaf assemblies.
The EU Green Deal's transport decarbonization framework is mandating CO2 performance standards for heavy-duty vehicles that parallel EPA regulatory pressure. European OEMs are redesigning suspension modules to capture certified mass reduction credits toward fleet-average compliance. Heavy truck manufacturers in Germany and Sweden are responding with accelerated composite spring integration on long-haul tractor platforms.
Fleet operators are consolidating supplier relationships around vertically integrated suspension system providers capable of delivering certified weight reduction with warranty-backed fatigue performance. Direct OEM contracting is displacing traditional aftermarket distribution for composite leaf spring procurement in the United States. This concentration is most visible among national logistics carriers operating dedicated routes between California, Texas, and Illinois freight corridors.
Automotive Composite Leaf Springs Market Segmentation
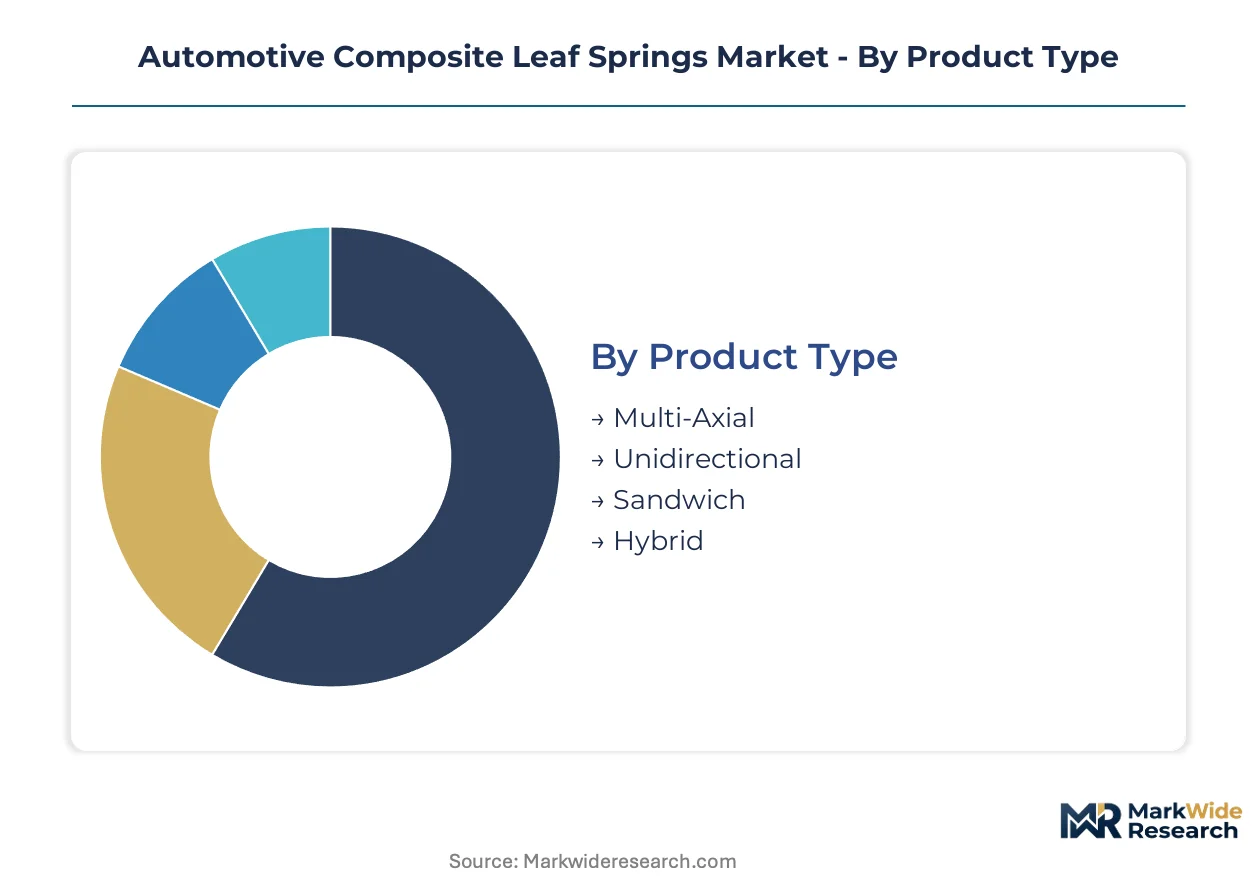
Composite leaf spring procurement decisions cascade through four distinct lenses: fiber architecture determines performance ceilings, end-user channel dictates warranty terms and volume commitments, material selection governs cost-positioning against steel alternatives, and manufacturing technology sets capital intensity and cycle time trade-offs.
Product Type:
Buyers prioritize specific stiffness and fatigue life specifications when selecting fiber architectures for suspension modules.
- Multi-Axial:Cross-plied fiber orientations deliver balanced torsional rigidity and damage tolerance for heavy truck suspensions. Fleet operators in the United States specify these configurations for long-haul tractors subject to variable load conditions and extended duty cycles.
- Unidirectional:Aligned fiber layups maximize specific stiffness along the primary stress axis. Electric vehicle platforms in Michigan and California procurement pipelines favor this architecture for battery-protective subframe designs where directional strength outweighs multi-axis loading requirements.
- Sandwich:Core-skin constructions with foam or honeycomb intermediates reduce mass in secondary load paths. Defense vehicle programs specify these for non-critical suspension brackets where stiffness-to-weight ratios must balance against ballistic fragmentation concerns.
- Hybrid:Combined glass-carbon fiber stacks optimize cost-performance for vocational trucks. Municipal fleet operators in Texas and Illinois procurement offices specify hybrid architectures for refuse and utility vehicles with moderate payload cycling.
Multi-axial configurations dominate current volume; unidirectional layups are climbing the fastest on electric vehicle platform adoption.
End User:
Channel structure determines certification burden, pricing leverage, and long-term contract visibility for composite spring suppliers.
- OEMs:Direct vehicle manufacturer contracting demands full NHTSA fatigue certification and platform-specific tooling investments. Detroit Three automakers and their electrification subsidiaries in Michigan anchor premium-grade composite spring procurement with multi-year supply agreements.
- Aftermarket Providers:Independent distributors and service chains target fleet refurbishment and upgrade cycles. Regional logistics operators in California and Texas freight corridors source through these channels for retrofit weight reduction programs on existing tractor assets.
- Vehicle Assemblers:Contract manufacturers and specialty vehicle builders integrate springs into limited-production platforms. Military ground vehicle contractors in South Carolina and Ohio sustain orders for armor-intensive platforms where payload retention determines mission profile viability.
- Tier-1 Suppliers:Suspension system integrators consolidate composite spring procurement with damper and axle module sourcing. Hendrickson International and comparable suppliers in Indiana and Illinois control specification authority for vocational truck chassis programs.
OEMs lead on scale; Tier-1 suppliers lead on specification influence over material selection.
Material:
Raw material cost structure and supply security shape procurement committee decisions across buyer organizations.
- Carbon Fiber:PAN-based and pitch-based precursors deliver maximum specific stiffness for motorsport and defense end uses. Premium pickup manufacturers in Michigan qualify these for performance trim levels where mass reduction supports towing capacity ratings.
- Glass Fiber:E-glass and S-glass formulations balance cost against mechanical properties for high-volume truck applications. Heavy-duty fleet operators in the United States specify glass fiber springs for 500,000-mile lifecycle targets at unit economics competitive with steel multi-leaf assemblies.
- Thermoplastic:Polyamide and polypropylene matrices enable in-situ consolidation and end-of-life recyclability. European OEMs in Germany and Sweden procurement pipelines specify thermoplastic springs for compliance with EU circular economy frameworks and CO2 performance standards.
- Resin:Epoxy and vinyl ester thermosets dominate current compression molding throughput. Suppliers without captive chemical production face margin compression from feedstock price volatility in Gulf Coast petrochemical corridors.
Glass fiber leads on volume; thermoplastic matrices are expanding most quickly on regulatory recyclability pressure.
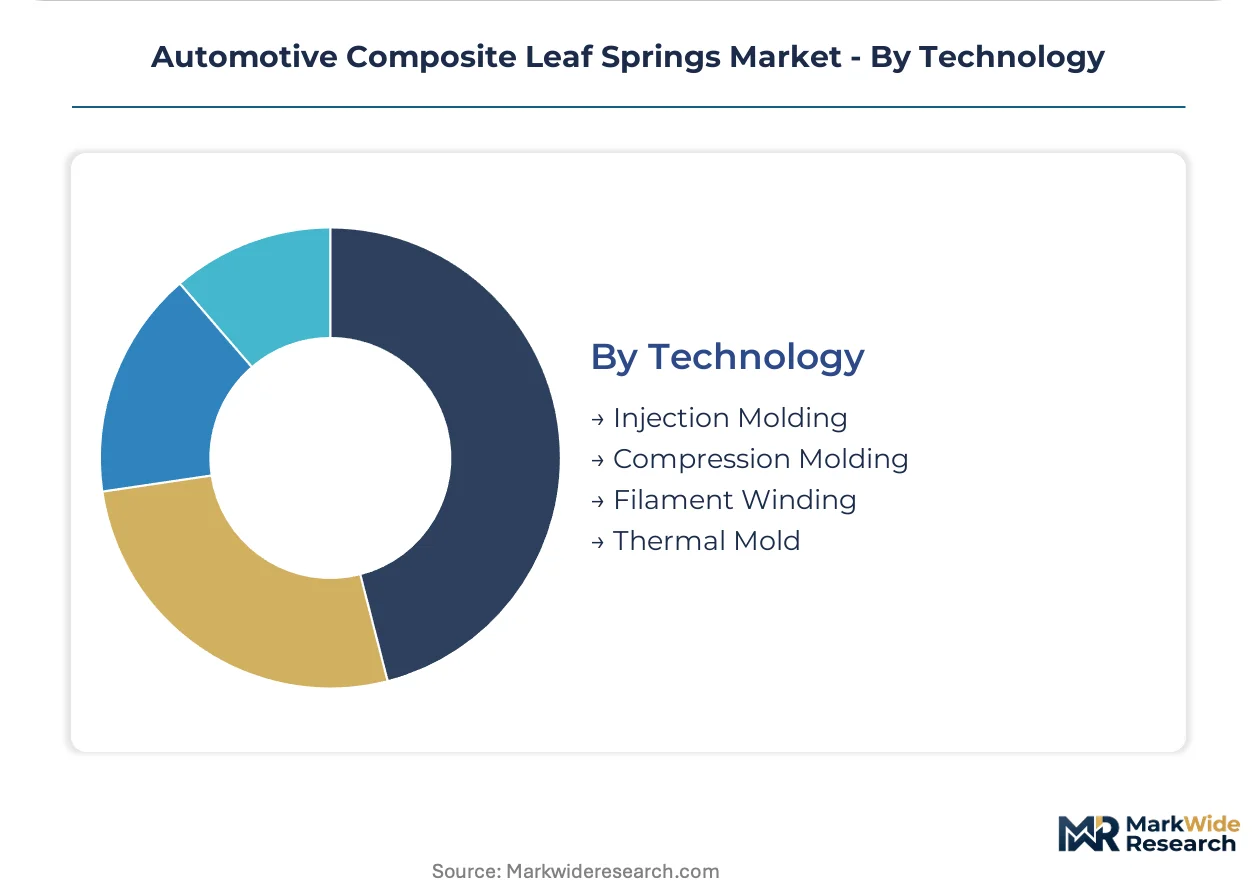
Technology:
Manufacturing process selection locks in cycle time, capital recovery periods, and geometric complexity limits for production programs.
- Injection Molding:High-pressure resin transfer suits complex three-dimensional spring eyes and attachment features. Tier-1 suppliers in South Carolina deploy this for integrated suspension modules combining leaf springs with polymer bushings in single-cycle production.
- Compression Molding:Matched die forming of prepregs delivers consistent fiber volume fraction for heavy truck specifications. Tooling lead times of 18-24 months for multi-cavity dies misalign with accelerated OEM platform launch schedules in Michigan and California.
- Filament Winding:Robotic fiber placement with tension control optimizes material utilization for constant cross-section springs. Automation convergence with in-situ thermoplastic consolidation is reducing cycle times for high-volume electric vehicle programs.
- Thermal Mold:Heated tool processing of thermoplastic preforms enables rapid cycling and welding integration. European suppliers in Germany pilot this technology for closed-loop manufacturing with regrind fiber incorporation.
Compression molding leads on installed capacity; filament winding is gaining share fastest on automation and cycle time improvements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where composite leaf spring production concentrates, as manufacturers migrate toward jurisdictions offering favorable cost-of-compliance structures for fiber-reinforced polymer processing and end-of-life handling.
United States
Long-haul logistics operators across California and Texas freight corridors are accelerating fleet procurement of composite suspension systems to capture fuel efficiency gains. EPA Phase 3 greenhouse gas standards for model year 2027 trucks mandate mass reduction pathways that compress qualification timelines for new material entrants. Detroit Three automakers and their electrification subsidiaries in Michigan anchor premium-grade composite spring procurement with multi-year supply agreements spanning vocational and battery-electric truck platforms.
Germany
Heavy truck manufacturers in Stuttgart and Munich are redesigning suspension modules to capture certified mass reduction credits toward EU fleet-average CO2 compliance. The EU Green Deal's transport decarbonization framework imposes parallel regulatory pressure to EPA standards, accelerating composite spring integration on long-haul tractor platforms. Carbon fiber preform production clusters in Bavaria and Baden-Württemberg expose automotive programs to geographic concentration risk for premium-grade material supply.
China
Domestic electric vehicle manufacturers are specifying composite leaf springs to offset battery pack mass while maintaining chassis rigidity for battery protection systems. The Ministry of Industry and Information Technology's dual carbon goals create compliance pressure for weight-optimized components across medium and heavy-duty vehicle segments. Yangtze River Delta manufacturing hubs in Shanghai and Jiangsu province are consolidating filament winding automation capabilities for high-volume OEM programs.
Sweden
European OEMs headquartered in Gothenburg are responding to EU CO2 performance standards with accelerated composite spring integration on premium long-haul platforms. REACH regulation and evolving circular economy frameworks mandate end-of-life recyclability for fiber-reinforced components, favoring thermoplastic matrix development. Scandinavian automotive suppliers are piloting closed-loop manufacturing with regrind fiber incorporation to preempt compliance uncertainty.
South Korea
Battery-electric truck architectures from Seoul Capital Area manufacturers are specifying composite leaf springs to manage unsprung mass against heavy battery configurations. The Ministry of Trade, Industry and Energy's industrial policy supports advanced materials development for automotive lightweighting applications. Busan-Ulsan industrial corridors are developing compression molding capacity for regional OEM supply chains serving domestic and export markets.
Automotive Composite Leaf Springs Market Vendor Landscape
Capacity expansion dominates the current landscape as suppliers race to install multi-cavity tooling and filament winding automation ahead of 2027 model year platform launches. The vendor base stratifies across three tiers: integrated suspension system providers controlling specification authority, specialized composite material houses with captive fiber production, and regional fabricators serving aftermarket refurbishment cycles. Strategic archetypes include vertically integrated carbon fiber producers, Tier-1 suspension module integrators, and automation-focused process technology specialists. M&A activity and strategic partnerships represent the dominant competitive moves, as players seek to secure preform supply and qualification relationships with accelerating OEM electrification programs.
Among German-based material specialists, SGL Carbon and Benteler SGL exemplify the integrated carbon fiber archetype, leveraging captive preform capabilities to control cost volatility for high-volume automotive programs. Hendrickson International represents the Tier-1 suspension integrator model, extending composite leaf spring integration across vocational truck platforms through established chassis systems relationships. These three companies anchor distinct competitive vectors—material supply security, specification authority, and manufacturing scale—that determine positioning in procurement committees across Detroit, Stuttgart, and Seoul.
| Leading Market Players |
|---|
| Benteler SGL |
| LiteFlex |
| SGL Carbon |
| Hyperco |
| ARC Industries |
| Hendrickson International |
| Flex-Form |
| IFC Composite GmbH |
| Mubea Fahrwerkstechnologien GmbH |
| Others |
Supply Flow & Price Mechanics
Filament winding automation convergence with in-situ thermoplastic consolidation simultaneously compresses cycle time economics and concentrates production capability among suppliers with capital-scale robotics in South Carolina and Michigan. This technology shift redistributes pricing power toward integrated manufacturers while squeezing margin structures for conventional compression-molding operators without captive fiber placement capacity.
Pricing Analysis
Distributor margins in aftermarket channels absorb 15-25 point spreads before fleet operators see landed costs, while direct-to-OEM contracting secures volume discounts tied to platform-specific tooling commitments. Three-tier pricing structure across premium, standard, and economy levels separates carbon fiber defense specifications from glass fiber heavy truck configurations and hybrid vocational grades. Cost compression in standard-tier glass fiber springs is intensifying because epoxy resin feedstock volatility from Gulf Coast petrochemical corridors squeezes non-integrated manufacturers. Aftermarket distributors serving regional California and Texas logistics fleets exhibit highest price sensitivity; defense vehicle contractors in South Carolina demonstrate lowest sensitivity due to mission-critical payload requirements.
Supply Chain Analysis
Skilled composite technician availability constrains expansion timelines in Germany, China, and the United States where filament winding programming and thermoplastic consolidation expertise concentrates. Raw material flows draw from PAN-based carbon fiber precursors in Bavaria, E-glass rovings from Ohio Valley suppliers, and epoxy resin formulations from Texas petrochemical complexes. Single-source vulnerability permeates premium-grade carbon fiber preform supply where SGL Carbon and Benteler SGL control European automotive qualification pathways. Distribution runs through Tier-1 suspension integrators like Hendrickson International for OEM channels, with aftermarket refurbishment cycling through independent distributors in Illinois and California freight corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
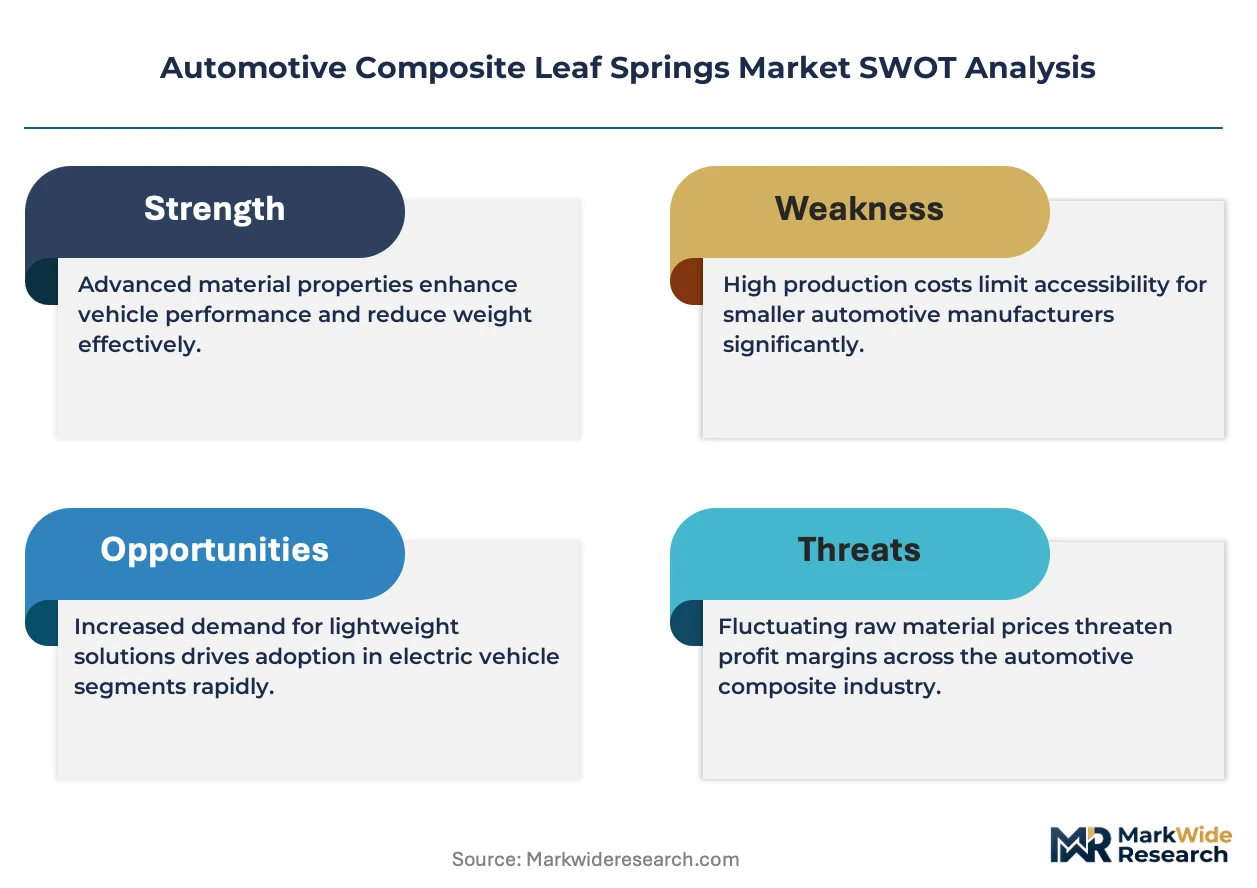
This market offers margin expansion through thermoplastic matrix adoption that eliminates autoclave curing costs while capturing premium positioning for end-of-life recyclability compliance.
For Market Incumbents: Hedge against epoxy resin cost volatility by securing captive thermoplastic preform supply or backward integration into polyamide matrix production. Defend specification authority against emerging automation-focused process specialists by accelerating NHTSA fatigue certification for next-generation filament wound architectures before 2027 platform launches lock in supplier relationships. For New Entrants and Emerging Players: EPA Phase 3 standards in the United States open a window for qualified composite spring suppliers to capture share in battery-electric truck architectures where incumbent steel spring relationships carry no historical entitlement. Target the vocational truck aftermarket in Texas and Illinois where municipal fleet operators seek retrofit weight reduction with moderate certification burden. Lead with thermal mold processing capabilities that offer closed-loop manufacturing narratives for circular economy procurement committees. For Investors and Strategic Acquirers: Valuations sit cheapest among regional compression-molding fabricators without OEM qualification relationships but with installed multi-cavity tooling capacity. Five-to-ten year viability hinges on successful thermoplastic matrix transition and defense program diversification beyond commercial automotive cyclicality. Monitor California Air Resources Board zero-emission truck mandates as inflection indicator for composite spring penetration rates in North American battery-electric platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Matrix Transition | Enables closed-loop manufacturing with regrind fiber incorporation for EU circular economy compliance. |
| Filament Winding Automation Scale-Up | Reduces cycle times for high-volume electric vehicle programs from Michigan and California OEMs. |
| Defense Program Diversification | Sustains premium-grade orders through Army ground vehicle modernization in South Carolina and Ohio. |
| Backward Integration into Carbon Fiber Preforms | Controls material cost volatility for automotive qualification timelines under EPA Phase 3 pressure. |
| Aftermarket Channel Consolidation | Captures fleet refurbishment cycles from regional logistics operators in Texas and Illinois corridors. |
Methodological Framework
Direct dialogue with Tier-1 suspension procurement managers, OEM platform engineers, aftermarket distributors, and defense vehicle contractors grounded qualitative assessment of specification authority and channel dynamics. Secondary validation drew from EPA regulatory filings, NHTSA safety standard dockets, vehicle production databases, and customs records of carbon fiber preform trade flows. Bottom-up and top-down triangulation cross-checked unit economics assumptions against fleet operator procurement patterns and supplier capacity disclosures.
Bottom-up modeling segmented volume and value across fiber architecture, end-user channel, material matrix, and manufacturing technology dimensions, with propulsion architecture and regional production cluster as automotive-specific overlays. Top-down cross-checks anchored against freight efficiency targets and EPA compliance timelines across the analysis window. CAGRs derived from regression of historical platform adoption curves against regulatory mandate acceleration patterns, with electric vehicle content-per-vehicle assumptions as critical sensitivity input.
Revisions become necessary when thermoplastic resin feedstock disruptions, NHTSA fatigue test protocol changes, or EU end-of-life recyclability enforcement shifts materialize beyond baseline assumptions. Material deviation in named triggers warrants pause and re-evaluation of qualification timeline and capacity expansion assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Mechanical Control Cable Market
Automotive Parts
Automobile Muffler Market
Automotive Parts
Italy Automotive Hydraulic Actuators Market
Automotive Parts
Gear Box and Gear Motors Market
Automotive Parts
Egypt Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
Off-Road Hoses Market
Automotive Parts
Argentina Passenger Vehicles Lubricants Market
Automotive Parts
Speed Bump Market
Automotive Parts
Latin America Automotive Airfilters Market
Automotive Parts
Global Auto Parts and Accessories Market
Automotive Parts
Vehicle Jump Starter Market
Automotive Parts
Spare Wheel Carrier Market
Automotive Parts
Electric Vehicle Brake Pad Market
Automotive Parts
Automotive Piston Engine System Market
Automotive Parts
Hydraulic Lash Adjuster Market