
 Automotive Engine Oil Coolant Market | 2026-2036
Automotive Engine Oil Coolant Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Engine Oil Coolant Market Analysis
Aftermarket service revenue is fragmenting across multiple fluid-change intervals and thermal-management service bundles. ExxonMobil Corporation leverages its integrated base-oil and additive supply chain to capture margin from high-mileage fleet contracts. Shell plc competes through differentiated synthetic formulations engineered for turbocharged direct-injection engines. Valvoline Inc. anchors its position in the quick-lube channel with proprietary coolant-exchange equipment that locks in recurring service visits.
Automotive engine oil coolant comprises glycol-based or propylene-glycol formulations combined with corrosion inhibitors, antifoam agents, and pH buffers, engineered to maintain thermal stability across operating temperatures from minus thirty-seven to one hundred twenty-nine degrees Celsius while preventing cavitation erosion in water pumps and cylinder liners. Its primary commercial purpose is to regulate engine and oil temperatures, extend component life, and protect aluminum, cast-iron, and magnesium alloys from galvanic corrosion. Synthetic formulations now lead product-type value generation due to extended drain intervals and compatibility with electrified powertrain thermal loops, while bio-based alternatives represent the fastest-growing category as OEMs face scope-three emissions scrutiny. In application terms, heavy-duty trucks concentrate margin pools because fleet operators prioritize total cost of ownership over upfront fluid expense.
The United States Environmental Protection Agency sets the regulatory pace through heavy-duty greenhouse-gas standards that effectively mandate advanced thermal management, while California Air Resources Board rules propagate through Section 177 state adoptions. The European Union's REACH regulation and F-Gas restrictions constrain formulation chemistry, compelling suppliers to reformulate corrosion inhibitor packages. Japan's Ministry of Economy, Trade and Industry promotes next-generation vehicle efficiency targets that tighten coolant thermal conductivity specifications. Stakeholders must monitor how electrification shifts thermal loads from combustion blocks to battery packs and power electronics, reshaping coolant formulation priorities and service-interval economics.
Market Dynamics
Electrification is fragmenting thermal management architectures as battery-electric powertrains shift heat loads from engine blocks to power electronics and battery packs, forcing coolant formulators to engineer dielectric properties and low-conductivity chemistries absent in conventional combustion-era products.
Growth Catalysts
- EPA Phase 3 Heavy-Duty Standards:The United States Environmental Protection Agency's tightened greenhouse-gas rules for diesel trucks mandate advanced thermal management, accelerating demand for coolants that protect exhaust aftertreatment systems from thermal degradation.
- Extended-drain synthetic formulations:Commercial fleet operators in the United States are consolidating fluid purchases around synthetic chemistries that stretch service intervals from 30,000 to 600,000 miles, reducing total cost of ownership.
- Battery thermal loop integration:Electric vehicle manufacturers require coolants compatible with lithium-ion cell chemistries and power module substrates, opening formulation development pipelines previously dormant in traditional automotive supply chains.
Market Restraints
- Ethylene glycol price volatility:Petrochemical feedstock fluctuations and refinery capacity constraints in the Texas Gulf Coast corridor create margin compression for glycol-based concentrate producers.
- REACH substance restrictions:The European Chemicals Agency's corrosion inhibitor blacklists under REACH compel European blenders to reformulate additive packages, extending R&D cycles and certification timelines.
- Propylene glycol substitution pressure:Bio-based diol alternatives and glycerin derivatives are displacing conventional base fluids in niche environmental applications, threatening volume in premium segments.
Strategic Opportunities
- India commercial vehicle fleet expansion:The Bureau of Indian Standards' adoption of BS-VI emission norms creates parallel thermal management requirements for heavy-duty trucks operating in high-ambient-temperature corridors.
- Direct battery immersion cooling:Convergence of dielectric fluid engineering and cell-to-pack architectures enables single-fluid thermal management for next-generation electric vehicle platforms.
- California Air Resources Board adoption cascade:Section 177 state adoptions of CARB's advanced clean trucks rule propagate stringent thermal specifications across seventeen U.S. states, expanding addressable market for compliant formulations.
Industry Challenges
- Electrochemical compatibility certification:Validating coolant interaction with silicon carbide power modules and solid-state battery interfaces requires extended test protocols not standardized under existing ASTM or SAE methods.
- Cross-contamination risk in service bays:Quick-lube technicians must distinguish between legacy IAT, OAT, and HOAT chemistries alongside new low-conductivity electric vehicle fluids, raising training and liability costs for service chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Engine Oil Coolant Market |
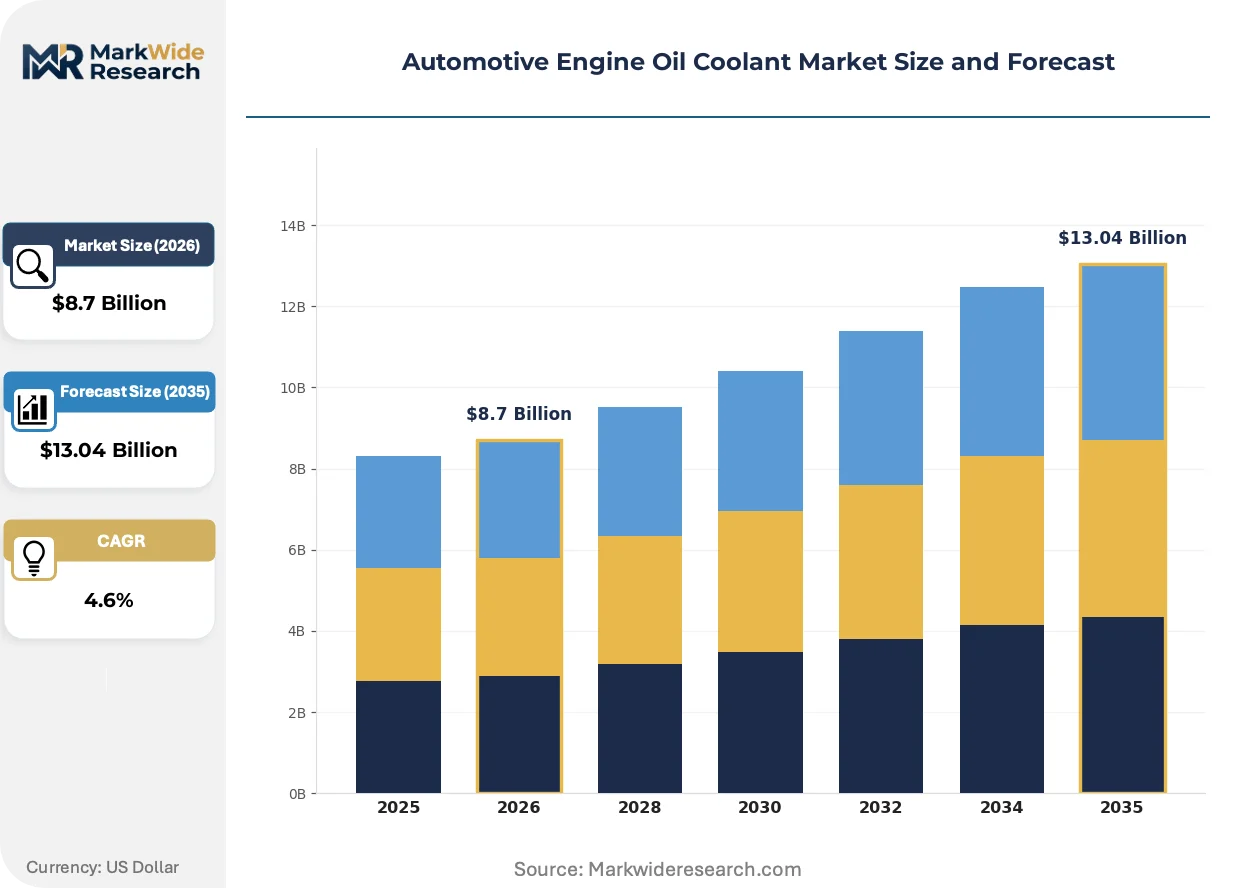
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Synthetic, Hybrid, Bio-based Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Off-Road Vehicles Technology: Heat Exchanger, Radiator, Inline Cooler, Oil Filter End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers |
| Companies Covered | ExxonMobil Corporation, Shell plc, Chevron Corporation, TotalEnergies SE, BP plc, Valvoline Inc., Castrol, BASF SE, Prestone Products Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Engine Oil Coolant Market Emerging Trajectories
Formulation science is bifurcating as electrification demands dielectric thermal fluids while legacy combustion platforms require ever-more-durable corrosion protection, splitting R&D investment across incompatible technical pathways.
Hybrid organic acid technology is migrating from passenger car light-duty applications into heavy-duty diesel segments as fleet operators demand the extended service intervals and aluminum protection that HOAT chemistries provide. Detroit-based commercial vehicle manufacturers are qualifying these formulations for 600,000-mile drain intervals. The shift is compressing demand for conventional inorganic additive technology and concentrating margin in premium synthetic concentrate supply.
The European Union's F-Gas Regulation constrains fluorinated greenhouse gas use in mobile air conditioning, indirectly pressuring coolant formulators to eliminate residual refrigerant contamination in recovery and recycling equipment. European blenders must certify closed-loop handling systems. This regulatory friction most affects service providers in Germany and France, who are consolidating around centralized fluid processing hubs to achieve compliance economies.
Fleet procurement departments are unbundling fluid supply from maintenance contracts, separating bulk coolant purchases from installation labor and creating direct relationships with petrochemical blenders rather than distributor intermediaries. This disintermediation is most visible among United States-based national trucking operators with in-house service capabilities, who now negotiate base-oil indexed pricing rather than fixed menu rates.
Automotive Engine Oil Coolant Market Segmentation
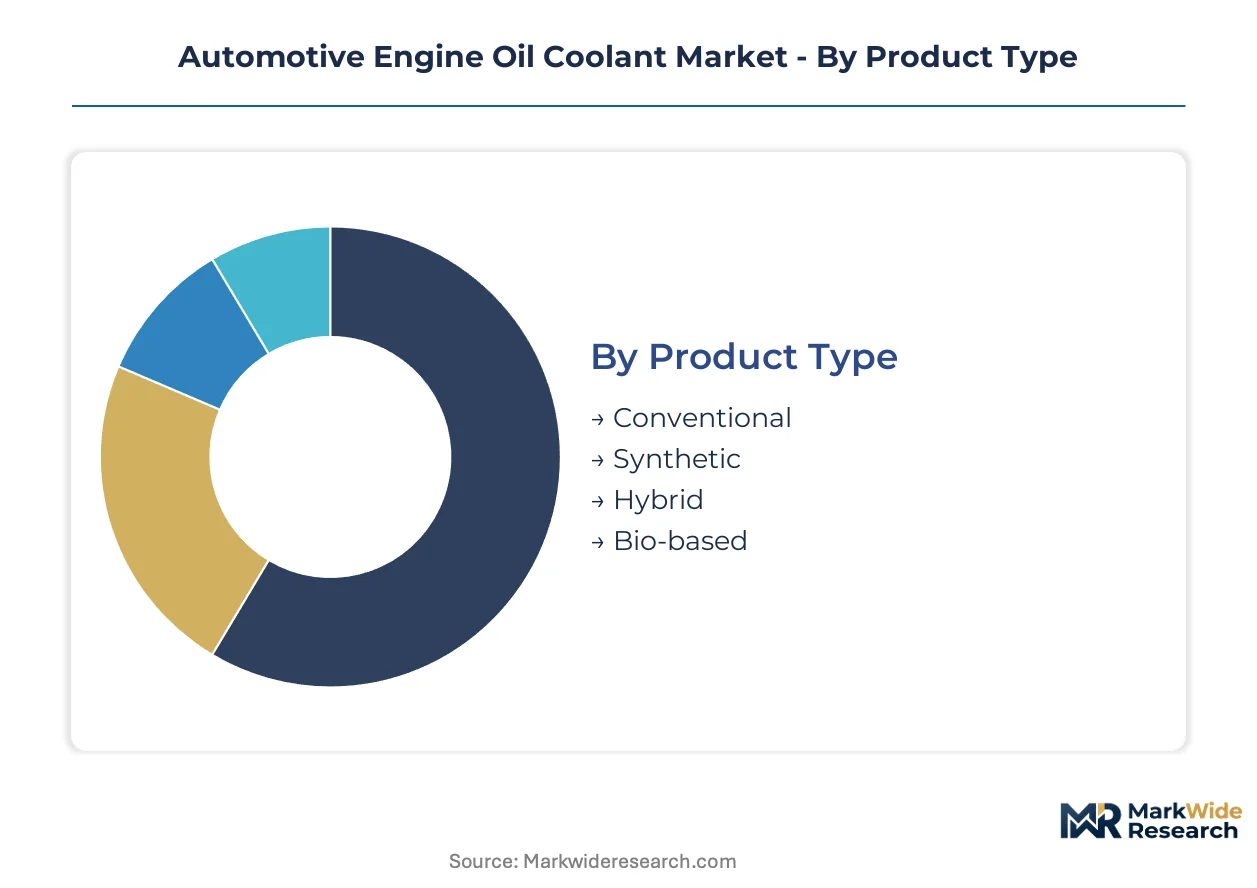
Fluid formulation cycles and hardware replacement intervals diverge sharply across automotive segments, creating distinct margin profiles and channel strategies. Procurement patterns split between long-life synthetic concentrates and commodity glycol blends, while electrification forces compatibility specifications that fragment supplier portfolios.
Product Type:
Drain intervals stretch from two years for conventional glycol to over a decade for dielectric thermal fluids, compressing revenue velocity for some formulations while extending service attach rates for others.
- Synthetic:Polyol ester and silicate-free formulations engineered for 600,000-mile drain intervals dominate heavy-duty fleet procurement. Detroit-based commercial operators consolidate volume around these chemistries to minimize downtime across Class 8 tractor fleets operating on interstate corridors.
- Conventional:Ethylene-glycol concentrates with inorganic additive packages require 30,000-mile service cycles. Demand concentrates in price-sensitive aftermarket channels and legacy vehicle populations in Texas and Florida where high ambient temperatures accelerate degradation.
- Hybrid:Organic acid technology blended with silicate buffers bridges compatibility gaps between aluminum and cast-iron engine architectures. Passenger vehicle OEMs in Michigan and Ohio qualify these formulations for 150,000-mile warranty coverage.
- Bio-based:Propylene-glycol derivatives from renewable feedstocks address scope-three emissions targets. European fleet operators under ECHA pressure trial these formulations in municipal vehicle pools.
Conventional formulations anchor the volume base while synthetic grades gain share at the steepest rate.
Application:
Total cost of ownership calculations diverge sharply between owner-operated passenger vehicles and capital-intensive commercial fleets, reshaping price elasticity and formulation priorities.
- Heavy-Duty Trucks:Class 8 vehicles operating above 80,000 pounds gross vehicle weight generate the highest per-unit fluid revenue. EPA Phase 3 thermal management mandates force adoption of low-conductivity coolants compatible with exhaust aftertreatment sensors.
- Commercial Vehicles:Delivery vans and regional haul trucks prioritize 100,000-mile service intervals. Fleet maintenance departments in California negotiate bulk pricing indexed to base-oil commodity markets.
- Passenger Vehicles:Light-duty cars and SUVs drive volume through quick-lube service networks. Valvoline and Jiffy Lube chains capture recurring revenue through coolant-exchange equipment installations.
- Off-Road Vehicles:Construction and agricultural equipment operates in high-contamination environments requiring supplemental filtration. Caterpillar and Deere dealers stock concentrated additive packages for field replenishment.
Heavy-duty trucks command premium pricing power while passenger vehicles deliver the deepest volume penetration.
Technology:
Thermal management hardware complexity escalates from passive radiator systems to active heat exchanger networks, expanding fluid specification requirements and service training burdens.
- Heat Exchanger:Plate-and-frame or shell-and-tube designs enable precise temperature control for turbocharger intercooling and transmission oil circuits. German and Japanese transmission specialists specify dielectric fluids for integrated electric axle modules.
- Radiator:Crossflow and downflow configurations remain dominant in legacy internal combustion architectures. Texas petrochemical blenders supply concentrated ethylene-glycol premix to radiator repair shops across the southern United States.
- Inline Cooler:Remote-mounted thermal management units serve high-performance and towing applications. Aftermarket suppliers in Michigan engineer adapter kits for pickup truck transmission cooling.
- Oil Filter:Spin-on and cartridge designs with integrated cooling passages protect hydraulic systems in off-road equipment. Fleet operators in Alberta oil sands specify these for extreme cold-start protection.
Radiator-based systems retain the installed base while heat exchanger configurations expand most quickly in electrified powertrains.
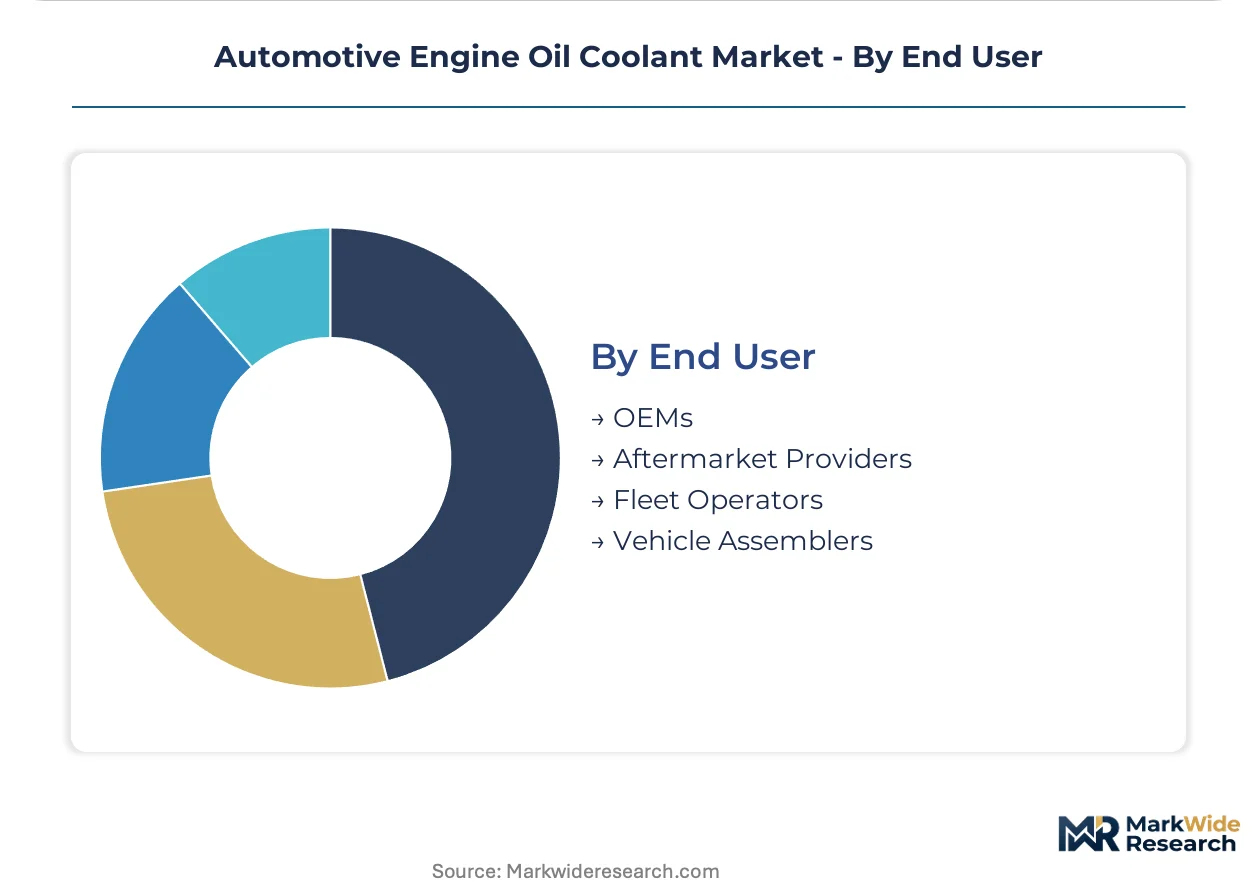
End User:
Procurement centralization varies from captive supply agreements at vehicle assemblers to fragmented spot purchasing by independent repair facilities, fragmenting pricing architecture and contract structures.
- Fleet Operators:National trucking companies with in-house maintenance capabilities negotiate direct relationships with base-oil producers. These buyers index pricing to West Texas Intermediate crude benchmarks rather than accepting fixed menu rates.
- OEMs:Vehicle manufacturers specify factory-fill coolants during powertrain assembly. Ford and General Motors qualify multiple suppliers for each assembly plant to ensure supply continuity.
- Aftermarket Providers:Quick-lube chains and independent service shops purchase through distributor intermediaries. These channels emphasize inventory turnover and equipment compatibility over formulation differentiation.
- Vehicle Assemblers:Contract manufacturers and niche EV startups source thermal fluids through tier-one subsystem suppliers. These relationships prioritize technical certification speed over volume scale.
Fleet operators drive the steepest procurement transformation while aftermarket providers maintain the broadest geographic footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in the United States demonstrate the lowest price elasticity, indexing contracts to crude benchmarks, while aftermarket channels in emerging markets remain highly sensitive to per-liter costs. European buyers navigate regulatory compliance premiums, and Asian commercial fleets prioritize total cost of ownership over upfront expenditure.
United States
Class 8 trucking fleets operating interstate corridors drive synthetic coolant procurement at 600,000-mile drain intervals. EPA Phase 3 heavy-duty greenhouse-gas standards mandate thermal management fluids protecting exhaust aftertreatment systems. Detroit's automotive manufacturing corridor concentrates formulation qualification activity, with Texas petrochemical blending facilities supplying concentrated ethylene-glycol premix to southern radiator repair networks.
Germany
Commercial vehicle manufacturers specify factory-fill coolants for export-oriented heavy-duty production. REACH substance restrictions compel reformulation of corrosion inhibitor packages, extending R&D certification timelines. Bavaria-based transmission specialists integrate dielectric fluids into electric axle modules, while centralized fluid processing hubs in Stuttgart and Munich achieve F-Gas Regulation compliance economies.
China
Domestic electric vehicle manufacturers require low-conductivity chemistries compatible with silicon carbide power modules and lithium-ion cell architectures. MIIT next-generation vehicle efficiency targets tighten thermal conductivity specifications for coolant formulators. Yangtze River Delta automotive clusters in Shanghai and Jiangsu province concentrate battery thermal loop engineering activity.
India
BS-VI emission norm adoption creates parallel thermal management requirements for heavy-duty trucks in high-ambient-temperature corridors. Bureau of Indian Standards certification protocols extend formulation development cycles for European and American suppliers. Maharashtra commercial vehicle assemblers in Pune and Nashik qualify extended-drain synthetics for long-haul fleet operators.
Japan
Automotive OEMs specify dielectric thermal fluids for solid-state battery interfaces and power electronics cooling. METI promotes next-generation vehicle efficiency targets that exceed conventional coolant thermal conductivity benchmarks. Nagoya-based Toyota supply chain partners and Tokyo-Yokohama electric vehicle engineering clusters concentrate hybrid organic acid technology qualification programs.
Automotive Engine Oil Coolant Market Vendor Landscape
Integrated petrochemical majors and specialty chemical formulators split the market between captive base-oil supply advantages and additive technology differentiation. The vendor base concentrates around three strategic archetypes: upstream-integrated oil majors controlling refinery-to-blender value chains, independent lubricant specialists with quick-lube channel lock-in, and chemical conglomerates supplying corrosion inhibitor packages. Competitive moves center on backward integration into additive manufacturing and geographic licensing agreements for regional formulation rights.
Among upstream-integrated majors, ExxonMobil Corporation and Shell plc exemplify archetypes leveraging refinery integration to capture margin from high-mileage fleet contracts. Valvoline Inc. occupies a distinct position anchoring quick-lube channel presence through proprietary service equipment installations. These three companies represent the structural segmentation between petrochemical scale, distribution reach, and service-channel captive demand.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| Chevron Corporation |
| TotalEnergies SE |
| BP plc |
| Valvoline Inc. |
| Castrol |
| BASF SE |
| Prestone Products Corporation |
| Others |
Supply Flow & Price Mechanics
Ethylene glycol price volatility on the Texas Gulf Coast determines both the compression of margin pools in commodity concentrate tiers and the geographic clustering of petrochemical blending capacity. Fleet procurement teams exploit this feedstock concentration by indexing long-term contracts to West Texas Intermediate crude benchmarks, forcing blenders to absorb basis risk while quick-lube channels lock in fixed menu rates.
Pricing Analysis
After-sales service bundles and extended-drain maintenance contracts generate lifetime value exceeding factory-fill pricing by multiples. Three-tier pricing structure across premium synthetic, standard hybrid, and economy conventional levels reflects certification grade and volume scale differentiation. Cost compression in commodity glycol concentrates is intensifying because fleet operators unbundle fluid supply from installation labor. Quick-lube chains demonstrate highest price sensitivity, while national trucking fleets with in-house capabilities exhibit lowest elasticity.
Supply Chain Analysis
Upstream ethylene oxide production anchors in the United States, Saudi Arabia, and China, with derivative glycol processing concentrated along the Texas Gulf Coast and Rotterdam port corridors. Formulation draws from petrochemical feedstocks, corrosion inhibitor additive packages, and deionized water treatment systems. Single-source vulnerability in specialty additive chemistry creates chokepoint exposure for European blenders facing REACH substance restrictions. Distribution runs through petrochemical majors direct to fleet operators, with distributor intermediaries serving fragmented aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal fluid interoperability across combustion and electric vehicle platforms creates platform-economics inflection, as OEMs demand single-supplier certification spanning legacy and electrified powertrain architectures.
For Market Incumbents: Build formulation patent moats around dielectric thermal fluid chemistries compatible with silicon carbide power modules. Secure backward integration into corrosion inhibitor manufacturing to offset REACH-driven additive package reformulation costs. Lock in quick-lube channel control through proprietary coolant-exchange equipment installations that raise switching costs for service chains. For New Entrants and Emerging Players: Build out bio-based propylene-glycol formulation capabilities targeting European municipal fleet operators under ECHA scope-three emissions pressure. India commercial vehicle fleet expansion presents the most penetrable geography, with BS-VI thermal management requirements creating qualification windows for extended-drain synthetics. Pursue direct relationships with Maharashtra-based commercial vehicle assemblers to bypass established distributor networks. For Investors and Strategic Acquirers: Specialty additive formulators with REACH-compliant corrosion inhibitor portfolios represent the priority acquisition archetype for consolidation plays. Long-term viability hinges on electrification transition speed and battery thermal loop specification standardization. Watch for CARB Section 177 adoption cascades as inflection indicators, as seventeen-state regulatory alignment would expand addressable market for compliant formulations disproportionately.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Manufacturing | Captures margin from REACH-driven reformulation cycles and secures supply continuity for corrosion inhibitor packages. |
| Dielectric Fluid Certification Investment | Unlocks electric vehicle battery thermal loop specifications from OEMs like Tesla and BYD requiring low-conductivity chemistries. |
| Quick-Lube Channel Equipment Lock-In | Valvoline's proprietary coolant-exchange systems create recurring service visit capture and raise competitor switching costs. |
| Geographic Licensing for Regional Formulation Rights | Enables compliance with India's BIS certification protocols and China's MIIT thermal conductivity specifications without full market entry. |
| Long-Term Fleet Supply Agreement | Detroit-based Class 8 manufacturers index pricing to crude benchmarks, transferring feedstock volatility risk to blenders. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet maintenance directors, OEM thermal management engineers, petrochemical procurement leads, and aftermarket distributor principals. Secondary validation drew from EPA regulatory filings, Bureau of Indian Standards certification databases, ECHA REACH substance restriction updates, and vehicle production statistics. Bottom-up volume triangulation across formulation types and top-down value reconciliation against petrochemical feedstock indices ensured cross-verification.
Calibration against historical drain interval extensions and electrification penetration curves anchored projections across the analysis window. Segmentation dimensions modeled include fluid formulation chemistry, vehicle propulsion architecture, fleet operator size tier, and regional regulatory cluster. CAGRs were derived from weighted average of technology adoption curves and fleet replacement cycles. Battery thermal loop integration timelines and heavy-duty emissions standard phase-in schedules served as key forecast inputs.
Sensitivities concentrate around ethylene glycol feedstock price swings, REACH additive blacklist expansions, and electric vehicle platform standardization delays. Cross-checking against IHS Markit vehicle registration data and American Chemistry Council production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Electric Brake Booster Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
North America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Electric HVAC Compressor Market
Automotive Parts
Crank Trigger System Market
Automotive Parts
Singapore Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Hydraulic Filters Market
Automotive Parts
Italy Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
Italy Automotive Airfilters Market
Automotive Parts
Malaysia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Engine Cooling System Market
Automotive Parts
Large Volume Injector Market
Automotive Parts
Indonesia Passenger Vehicles Lubricants Market