
 Brazil Passenger Vehicles Lubricants Market | 2026-2036
Brazil Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Passenger Vehicles Lubricants Market Outlook
The SUV and light-truck application base is restructuring Brazil's lubricant consumption profile toward higher-viscosity grades and extended-drain formulations. Petrobras anchors domestic supply through its integrated refining and blending network across the Southeast. Shell leverages its global formulation technology to compete in the premium synthetic segment. Iconic Lubrificantes specializes in regional distribution density, controlling access to smaller aftermarket channels in the Northeast and Center-West.
Brazil passenger vehicles lubricants are formulated hydrocarbon-based fluids engineered to reduce friction, dissipate heat, and protect powertrain components under operating temperatures typically ranging from minus twenty to one hundred fifty degrees Celsius. Their primary commercial purpose is to extend engine and transmission service life while enabling compliance with manufacturer warranty requirements and national emission protocols. Engine oil commands the largest volume share across all grade categories, though synthetic and semi-synthetic formulations capture disproportionate margin pools due to OEM specification tightening and consumer willingness to pay for longer service intervals. The aftermarket provider channel leads absolute volume as independent workshops and retail auto parts chains serve Brazil's aging passenger car parc, while fleet operators represent the fastest-growing end user segment through centralized procurement and telematics-linked maintenance scheduling.
ANVISA oversees chemical substance registration for lubricant additives entering Brazilian commerce, while the National Petroleum Agency regulates product quality specifications and import licensing for base oil streams. PROCONVE emission tiers directly shape lubricant formulation requirements by mandating lower ash content and improved oxidation stability to protect exhaust aftertreatment systems. IBAMA enforcement of used oil collection and recycling obligations creates compliance costs that favor larger blenders with reverse logistics infrastructure. Stakeholders must monitor pending updates to PROCONVE standards and assess whether current formulation portfolios can absorb stricter phosphorus and sulfur limits without reformulation investment cycles.
Market Dynamics
PROCONVE emission tier progression is compressing lubricant formulation cycles as blenders must recalibrate additive packages to protect gasoline particulate filters and selective catalytic reduction systems. Fleet telematics integration is simultaneously pulling demand toward centralized procurement contracts with performance-guaranteed drain intervals.
Growth Catalysts
- SUV and light-truck parc expansion:Higher-displacement engines and towing-duty cycles in Brazil's Center-West agricultural zones are pulling demand toward SAE 5W-30 and 5W-40 grades with enhanced high-temperature shear stability.
- IBAMA enforcement of used oil collection mandates:Reverse logistics requirements are favoring blenders with established collection infrastructure, consolidating aftermarket share among operators with nationwide depot networks.
- Telematics-linked preventive maintenance:Fleet management platforms are enabling condition-based oil change scheduling, extending synthetic lubricant penetration among commercial passenger vehicle operators in São Paulo's urban corridor.
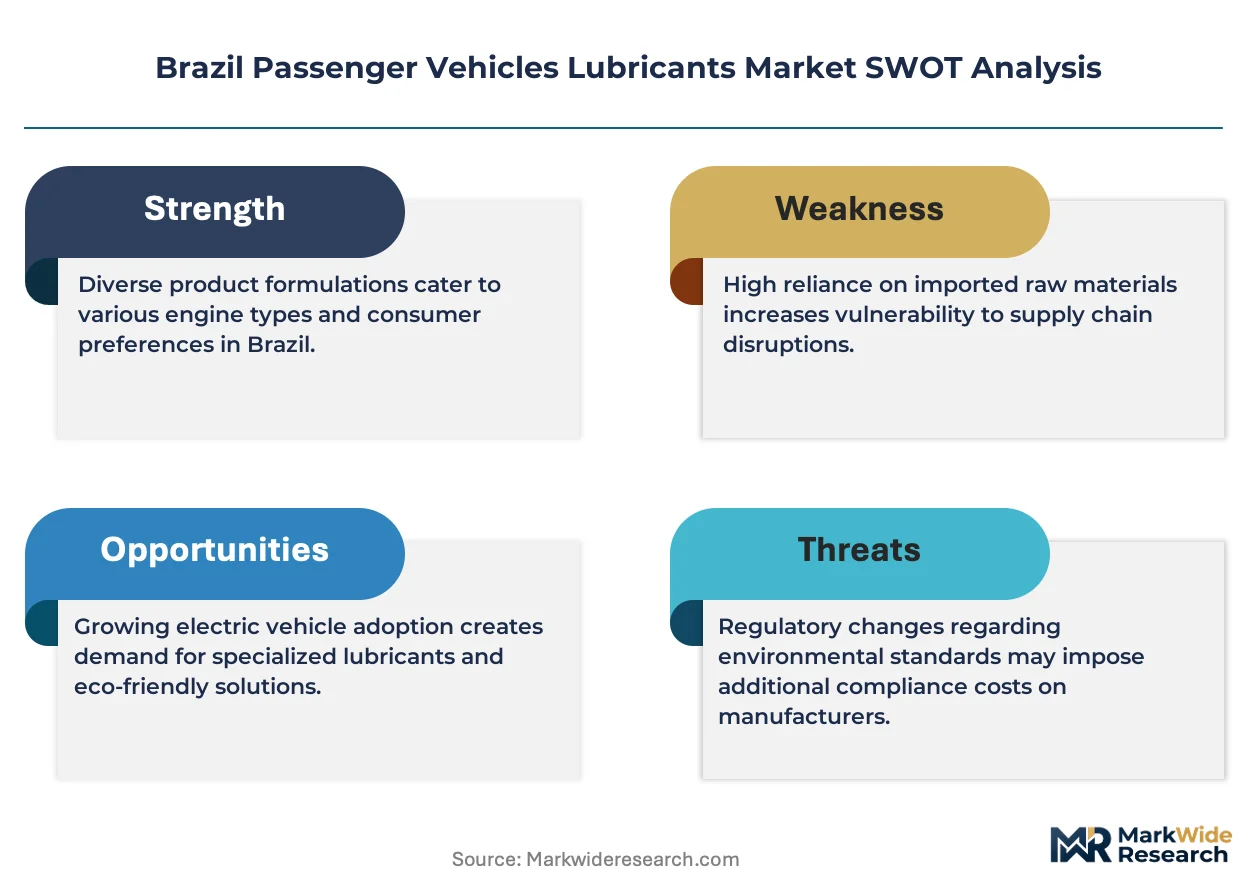
Market Restraints
- Group II/III base oil import dependency:Brazil's domestic refining capacity concentrates on fuel production, forcing lubricant blenders to source high-quality base stocks through ANP-licensed import channels subject to currency fluctuation.
- PROCONVE phosphorus and sulfur caps:Anticipated tightening of ash content limits for upcoming emission tiers requires reformulation investment before regulatory certainty solidifies, compressing R&D amortization windows.
- Extended-drain synthetic formulations:OEM-specified 15,000-kilometer and 30,000-kilometer service intervals are structurally reducing per-vehicle lubricant volume consumption despite premium pricing capture.
Strategic Opportunities
- Northeast regional aftermarket density:Lower penetration of synthetic formulations in Bahia and Pernambuco independent workshops creates white space for distribution-focused operators with technical service capabilities.
- PROCONVE L7 and L8 pre-positioning:Early formulation alignment with anticipated Euro 6-equivalent standards enables first-mover certification with Volkswagen, Fiat, and GM assembly operations in São Bernardo do Campo and Betim.
- E-commerce direct-to-consumer channels:Mercado Livre and specialized auto parts platforms are disintermediating traditional distributor tiers for DIY maintenance segments in metropolitan São Paulo and Curitiba.
Industry Challenges
- Additive chemist talent scarcity:Formulation expertise for low-SAPS (sulfated ash, phosphorus, sulfur) packages compatible with Brazilian ethanol-gasoline blends concentrates among a small cohort of Petrobras-trained specialists.
- ANVISA chemical substance registration timelines:Novel additive component approvals for imported premium formulations face 18-24 month evaluation windows, delaying product launches relative to regulatory deadline cycles.
- Legacy workshop equipment incompatibility:Independent service channels in secondary cities lack oil analysis capability to validate extended-drain synthetic performance claims, creating adoption friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Passenger Vehicles Lubricants Market |
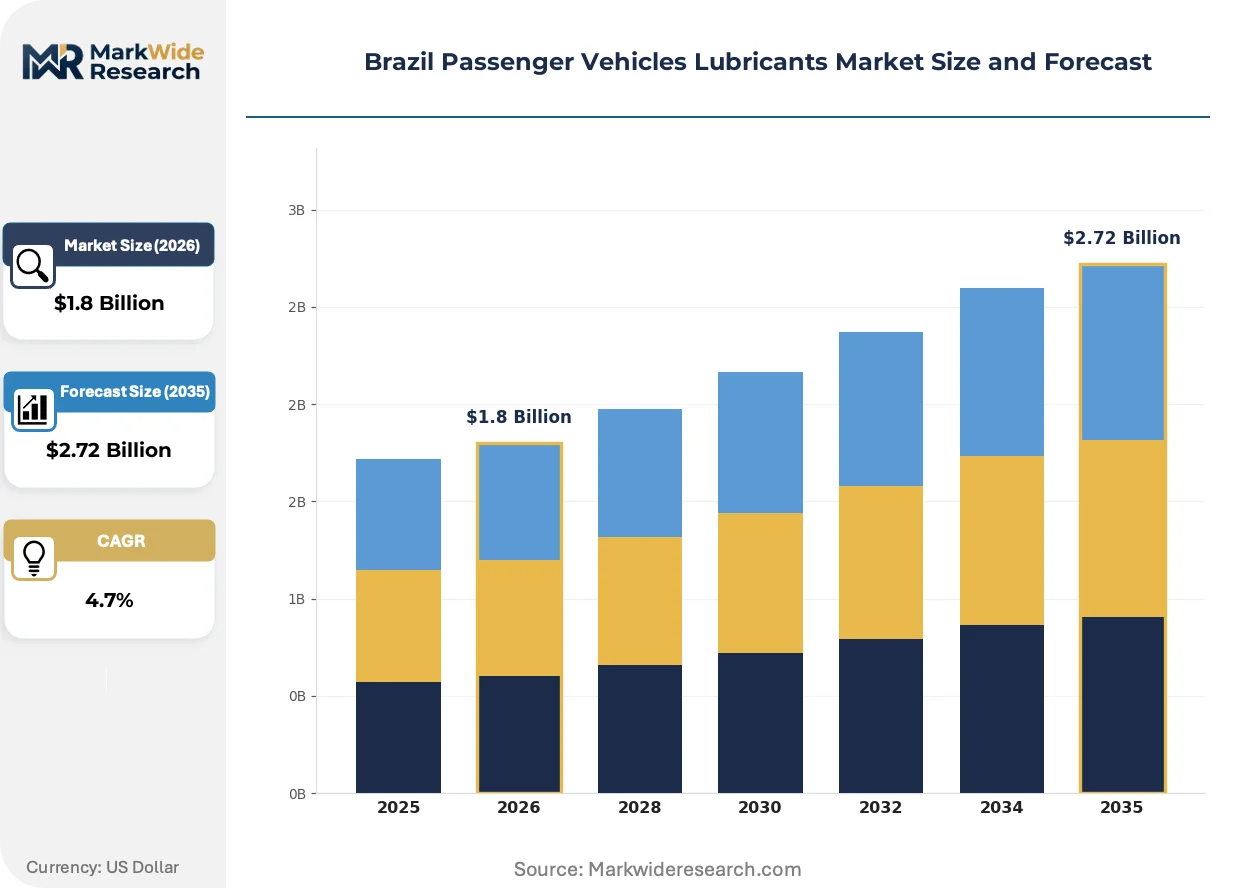
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease End User: OEMs, Aftermarket Providers, Fleet Operators, Dealerships Application: Passenger Cars, Light Trucks, SUVs, Vans Grade: Synthetic, Semi-Synthetic, Mineral, Bio-Based |
| Companies Covered | BP Plc (Castrol), Iconic Lubrificantes, Petrobras, Energis 8 Brasil, PETRONAS Lubricants International, ExxonMobil Corporation, TotalEnergies, Lucheti Lubrificantes, Royal Dutch Shell Plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Passenger Vehicles Lubricants Market Strategic Shifts
Formulation chemistry and procurement digitization are converging to restructure how lubricant value is captured across Brazil's passenger vehicle aftermarket. Three developments are compressing traditional competitive advantages.
Polyalphaolefin (PAO) and ester-based synthetic base stocks are expanding into mainstream service segments previously dominated by mineral formulations. Fleet operators with centralized maintenance contracts are adopting these chemistries at accelerated rates to align with OEM warranty requirements. This technology is expanding into independent workshop channels through co-branded certification programs that transfer technical credibility from blenders to service points.
ANVISA's alignment with OECD chemical hazard assessment protocols is accelerating additive substance re-registration requirements. Industrial consequence includes forced reformulation of legacy dispersant and anti-wear packages before 2027 compliance deadlines. Passenger car motor oil categories face the most concentrated impact, with blenders pre-substituting zinc dialkyldithiophosphate alternatives to secure registration continuity.
Subscription-based lubricant supply contracts are displacing spot procurement among ride-hailing and corporate fleet aggregators. These arrangements bundle fluid, filter, and analysis services into per-kilometer pricing, compressing distributor margins while locking in volume commitments. The model is most visible in São Paulo state's app-based transportation sector, where vehicle utilization rates justify predictive maintenance infrastructure investment.
Brazil Passenger Vehicles Lubricants Market Segmentation
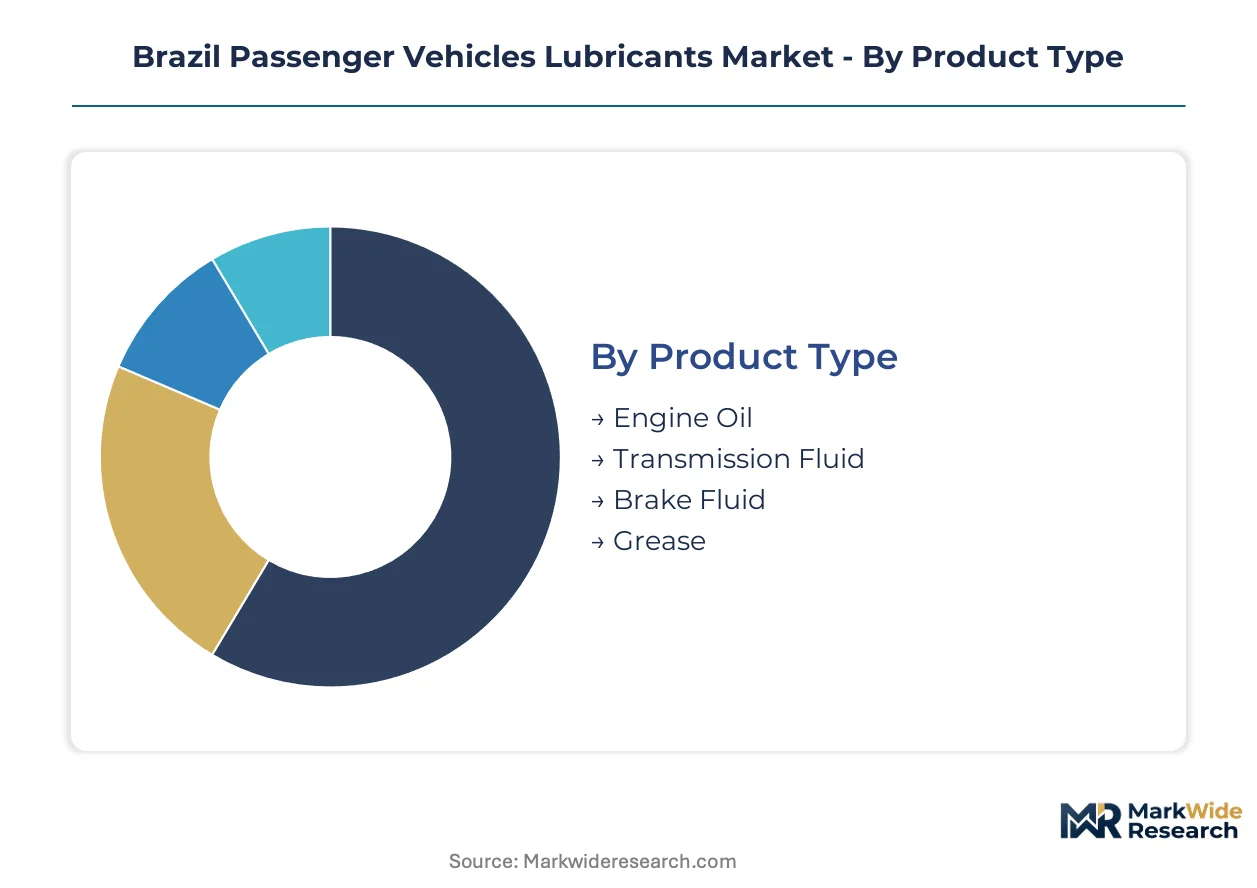
Brazil's lubricant market fragments across four critical dimensions that determine formulation requirements, procurement patterns, and margin capture. Understanding these segment boundaries reveals where volume concentrates versus where premium pricing power accumulates.
Product Type:
Engine oil commands absolute volume while specialized fluids capture disproportionate margin through technical specification barriers.
- Engine Oil:Hydrocarbon-based formulations engineered for friction reduction and thermal management across Brazil's ethanol-gasoline blended fuel environment. Demand concentrates in São Paulo's dense urban corridor where stop-start traffic accelerates oxidation stress and drives 5,000-kilometer drain interval maintenance culture.
- Transmission Fluid:Specialized lubricants for automatic and continuously variable transmissions with stringent viscosity stability requirements. Fleet operators in Curitiba's corporate transport sector are pulling demand toward synthetic ATF formulations compatible with extended service warranties from Volkswagen and Fiat assembly operations.
- Brake Fluid:Glycol-ether based hydraulic fluids meeting DOT 3 and DOT 4 specifications for ABS-equipped vehicle parc. Northeast independent workshops drive replacement volume.
- Grease:Thickened lubricants for chassis and wheel bearing applications. Agricultural vehicle operators in Mato Grosso sustain regional demand.
Mature deployment sits with Engine Oil. Newer deployment is concentrated in Transmission Fluid.
End User:
Procurement centralization separates price-takers from specification-setters across Brazil's service ecosystem.
- OEMs:Assembly plant fill operations tied to first-fill contracts with Petrobras and multinational blenders. Betim and São Bernardo do Campo manufacturing clusters anchor volume.
- Aftermarket Providers:Independent workshops and auto parts retail chains serving Brazil's aging passenger car parc. Volume leadership resides here.
- Fleet Operators:Centralized procurement entities with telematics-linked maintenance scheduling. São Paulo ride-hailing aggregators are expanding synthetic penetration fastest through per-kilometer service contracts.
- Dealerships:Authorized service channels with warranty-compliant formulation requirements. Premium synthetic grades dominate.
Volume leadership belongs to Aftermarket Providers. Margin expansion is concentrating in Fleet Operators.
Application:
Vehicle duty cycles reshape viscosity grade demand across Brazil's geographic and economic zones.
- Passenger Cars:Compact and mid-size sedans forming Brazil's core vehicle parc. Urban São Paulo density sustains highest per-capita consumption.
- Light Trucks:Commercial utility vehicles operating in Center-West agricultural zones. Towing-duty cycles pull demand toward higher-viscosity formulations.
- SUVs:Higher-displacement engines with enhanced high-temperature shear stability requirements. Fastest-expanding application base.
- Vans:Last-mile delivery and passenger transport vehicles. Fleet conversion to synthetic formulations is accelerating.
Established volume sits with Passenger Cars. Steepest expansion trajectory is visible in SUVs.
Grade:
Base stock chemistry separates commodity volume from technical premium across formulation portfolios.
- Synthetic:PAO and ester-based formulations enabling 15,000 to 30,000-kilometer drain intervals. OEM warranty compliance and PROCONVE emission system protection drive fleet adoption.
- Semi-Synthetic:Blended base stocks balancing performance upgrade with cost sensitivity. Independent workshop channels in secondary cities.
- Mineral:Group I and II base oil formulations for price-sensitive maintenance segments. Legacy vehicle parc sustains residual demand.
- Bio-Based:Vegetable oil-derived lubricants with biodegradability credentials. ANVISA registration pathways and PROCONVE compatibility constraints limit penetration.
Volume concentration remains with Mineral grades. Technology migration is accelerating fastest in Synthetic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone tax incentives concentrate lubricant blending capacity in Brazil's northern corridor, while São Paulo state's industrial density anchors downstream distribution networks serving the Southeast's vehicle parc.
São Paulo
São Paulo state's urban corridor generates the highest per-capita lubricant consumption through dense vehicle ownership and stringent PROCONVE enforcement. ANVISA chemical registration requirements shape additive import flows through Santos port infrastructure. São Bernardo do Campo automotive assembly clusters sustain first-fill contract volumes for multinational blenders.
Minas Gerais
Minas Gerais anchors Brazil's mining and agricultural equipment lubricant demand through Belo Horizonte's industrial hinterland. IBAMA used oil collection mandates favor blenders with reverse logistics networks spanning the state's dispersed workshop base. Betim manufacturing operations from Fiat and Mercedes-Benz drive OEM-specified synthetic penetration.
Rio Grande do Sul
Rio Grande do Sul's southern position creates import-dependent supply chains for Group II/III base stocks through Uruguaiana border crossings. The state's ethanol production infrastructure influences lubricant formulation compatibility with high-blend gasoline. Porto Alegre metropolitan fleet operators are expanding telematics-linked maintenance contracts.
Bahia
Bahia represents Brazil's largest underpenetrated synthetic lubricant market among independent workshops in Salvador and interior municipalities. PROCONVE enforcement lags Southeast standards, preserving mineral-grade demand patterns. Regional distributors with technical service capabilities are consolidating aftermarket share.
Paraná
Paraná's Curitiba corridor concentrates corporate fleet operations pulling demand toward extended-drain synthetic formulations. The state's logistics infrastructure supports distribution reach into Center-West agricultural zones. Volkswagen's São José dos Pinhais assembly proximity creates OEM certification requirements for local service channels.
Brazil Passenger Vehicles Lubricants Market Competitive Environment
Top-tier vendors anchor formulation technology and first-fill contracts, while mid-tier regional distributors compete on workshop channel density and technical service reach. The market structures around three archetypes: integrated national oil companies with refining infrastructure, multinational lubricant specialists with global additive technology, and regional distributors with geographic concentration in underserved corridors. Competitive moves concentrate on backward integration into base oil supply and certification partnerships with OEM assembly operations.
Among multinational lubricant specialists, Castrol and Shell exemplify global formulation technology deployment through Brazilian distribution networks. Petrobras anchors the integrated national oil company archetype with captive refining and blending infrastructure. Iconic Lubrificantes occupies the regional distribution specialist position with density in Northeast and Center-West aftermarket channels.
| Leading Market Players |
|---|
| BP Plc (Castrol) |
| Iconic Lubrificantes |
| Petrobras |
| Energis 8 Brasil |
| PETRONAS Lubricants International |
| ExxonMobil Corporation |
| TotalEnergies |
| Lucheti Lubrificantes |
| Royal Dutch Shell Plc |
| Others |
Value Chain & Pricing Dynamics
Synthetic-mineral grade bifurcation in Brazil's lubricant market manifests in both pricing premiums and supply chain configurations, with PROCONVE emission compliance creating a certification ladder that concentrates high-margin formulation sourcing among ANP-licensed importers while mineral grades flow through decentralized distributor networks.
Pricing Analysis
Short lead-time premiums for Group III base oil imports from the US Gulf Coast compress spot procurement margins, while extended-drain synthetic formulations command value-based pricing through OEM warranty alignment. Price differentiation hinges on PROCONVE certification tier and volume scale, with fleet operators capturing economies through centralized contracts. Cost compression in mineral-grade channels is intensifying because of currency-driven import cost volatility. Independent workshops in secondary cities exhibit highest price sensitivity; fleet operators with telematics infrastructure show least.
Supply Chain Analysis
Dual-sourcing requirements for additive packages mandate multi-supplier qualification across US, European, and Asian specialty chemical producers, protecting blenders against ANVISA registration delays. Geographic supply concentration centers on the US for Group II/III base stocks, South Korea for PAO synthetics, and Argentina for regional Group I alternatives. Raw material dependencies include zinc dialkyldithiophosphate anti-wear additives, polyisobutylene dispersants, and viscosity index improvers. Single-source vulnerability sits with ANVISA-approved additive importers. Distribution runs through Petrobras terminal networks and Iconic Lubrificantes regional depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's passenger vehicle lubricants market functions as a cost-of-compliance story where PROCONVE L7 and L8 pre-positioning creates a barrier-to-entry moat for blenders with early certification and reformulation capital.
For Market Incumbents: Cement first-mover advantage in PROCONVE L8 certification by locking fill contracts with São Bernardo do Campo and Betim assembly operations. Defend against emerging regional distributors through captive reverse logistics infrastructure for IBAMA-compliant used oil collection. Channel control in Northeast and Center-West workshop networks remains the priority lever against price-pressured mineral-grade competitors.
For New Entrants and Emerging Players: PROCONVE enforcement lag in Bahia and Pernambuco opens a window for synthetic formulation penetration through technical service partnerships with independent workshops. Target white space in ride-hailing fleet subscriptions and e-commerce direct-to-consumer channels in metropolitan Curitiba. Go-to-market angle: co-branded certification programs that transfer blender technical credibility to service points lacking oil analysis capability.
For Investors and Strategic Acquirers: Re-rating potential sits with regional distributors owning reverse logistics infrastructure given IBAMA enforcement acceleration. Long-term viability favors operators with backward integration into base oil supply or ANVISA registration expertise. Signal to watch: PROCONVE L7 implementation timeline announcements from the National Petroleum Agency.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Reduces currency exposure on Group II/III imports through captive refining or long-term offtake agreements with US Gulf Coast producers. |
| PROCONVE L8 Pre-Certification Investment | Secures first-mover fill contracts with Volkswagen, Fiat, and GM assembly operations before regulatory certainty solidifies. |
| Reverse Logistics Network Expansion | IBAMA enforcement of used oil collection mandates consolidates aftermarket share among operators with nationwide depot infrastructure. |
| Telematics-Linked Fleet Subscription Contracts | Locks volume commitments from São Paulo ride-hailing aggregators through per-kilometer pricing bundling fluid, filter, and analysis services. |
| E-Commerce Direct-to-Consumer Channel Buildout | Disintermediates traditional distributor tiers for DIY maintenance segments in metropolitan São Paulo and Curitiba via Mercado Livre platforms. |
Study Parameters
Independent corroboration across ANP import licensing records, IBAMA used oil collection compliance filings, and PROCONVE regulatory bulletins underwrites the qualitative findings. Primary interviews with lubricant blenders, fleet procurement managers, and independent workshop owners combined with secondary validation from customs trade data, SEC filings of multinational lubricant parents, and ANVISA chemical substance registration databases. Bottom-up volume estimates from state-level vehicle registration data and top-down triangulation against Petrobras production disclosures anchor the analysis.
Rate-of-change decomposition across the projection horizon segments volume by product type, end user procurement centralization, application duty cycle, and base stock chemistry grade. CAGRs derive from trend extrapolation of synthetic penetration rates, PROCONVE tier implementation schedules, and fleet telematics adoption curves. Industry-specific forecast inputs include ethanol-gasoline blend compatibility requirements and ANVISA additive re-registration timelines.
The model assumes a particular technology adoption path; alternative pathways for bio-based lubricant formulations would alter the outlook if ANVISA registration pathways accelerate or PROCONVE compatibility constraints ease. Deviation in PROCONVE L7 implementation timing or ANP currency policy on base oil imports would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Bitcoin Mining Hardware Market
Others
Coconut Activated Carbon Market
Others
UK Automotive LED Lighting Market
Others
Smart Home Service Market
Others
Thiamethoxam Market
Others
Global Pumpkin Candles Market
Others
Aircraft Exterior Lighting Market
Others
Digital Media Adaptor (DMA) Market
Others
Technical Films Market
Others
China Smart Home Market
Others
Silicone Molding Machinery Market
Others
Europe Tablet PC Market
Others
United States Cigarette Market
Others
Calendered Polyvinyl Chloride Flexible Films Market
Others
Africa Smart Card Market
Others
Cat Food and Snacks Market