
 Water and Waste Water Treatment Chemicals Market | 2026-2036
Water and Waste Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Water and Waste Water Treatment Chemicals Market Analytics
Power plant cooling tower treatment is decoupling from traditional municipal demand as the energy sector pursues zero-liquid-discharge targets. BASF SE leverages its integrated polymer chemistry platform to supply high-performance flocculants across European industrial clusters. Kemira anchors Nordic pulp-and-paper effluent markets with specialized coagulant blends.
Water and waste water treatment chemicals encompass coagulants, flocculants, biocides, and pH adjusters formulated to remove suspended solids, neutralize pathogens, and stabilize effluent streams for safe discharge or reuse. These formulations typically operate within specific pH windows and dosing ranges measured in parts per million to achieve regulatory compliance. Flocculants command premium positioning in mining tailings applications where particle settling velocity determines throughput economics. Biocides face margin compression in municipal treatment as UV and ozone alternatives gain traction, though oil and gas cooling systems sustain chlorinated isothiazolinone demand. Coagulants dominate volume flows into Asian manufacturing facilities treating metal-finishing effluent.
The US EPA enforces National Pollutant Discharge Elimination System permits that mandate specific chemical treatment trains for industrial outfalls. China's MEE implements GB standards for surface water quality that force upgrading of legacy municipal plants with advanced coagulation and disinfection chemistry. The EU's Urban Waste Water Treatment Directive, reinforced by REACH chemical registration requirements, shapes product formulation decisions across member states. Stakeholders must monitor regulatory divergence between jurisdictions as chemical substitution timelines and approved substance lists fragment procurement strategies.
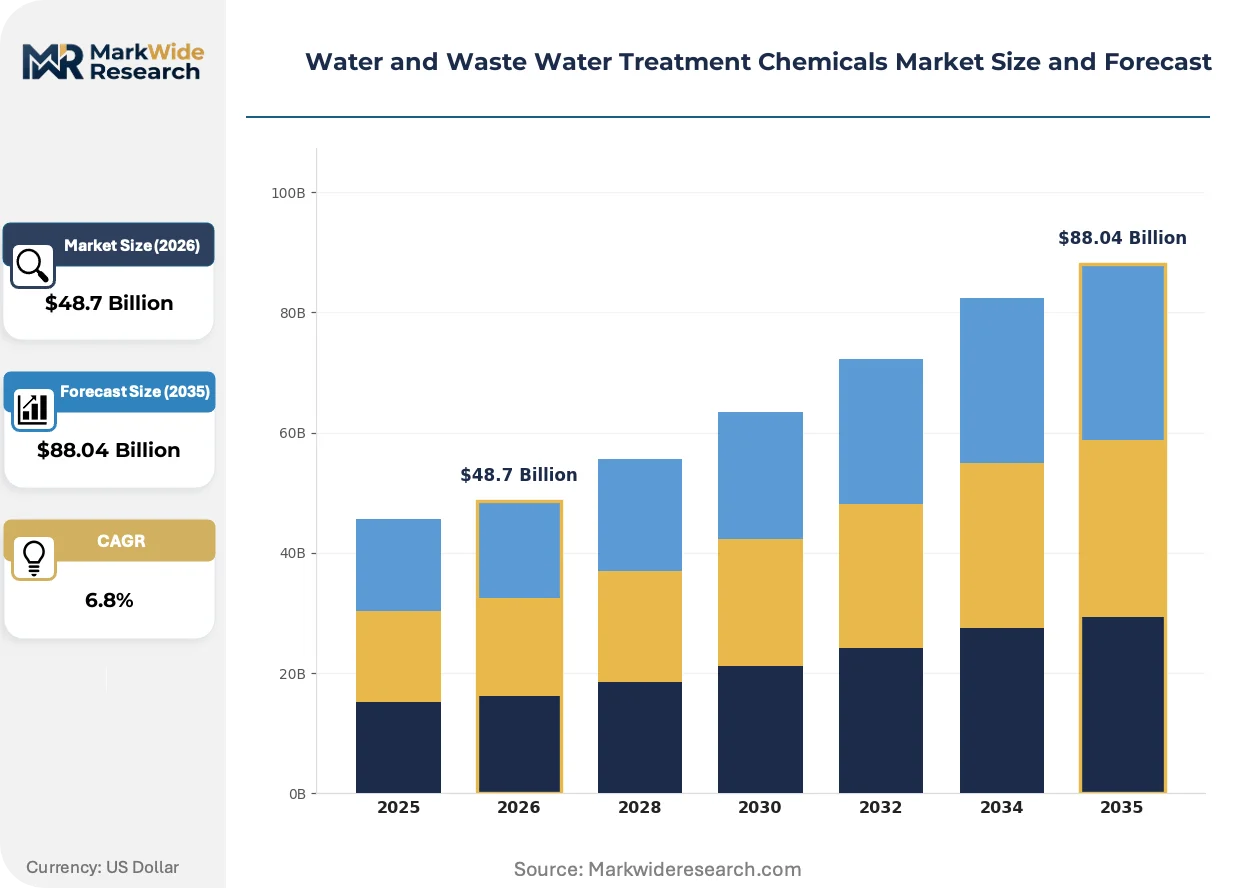
Market Dynamics
China's MEE enforcement of GB surface water standards is forcing simultaneous upgrades across thousands of legacy municipal plants, compressing procurement timelines and favoring suppliers with rapid-scale formulation capabilities.
Growth Catalysts
- US EPA emerging contaminant rules:Tightened discharge limits for PFAS and microplastics are mandating advanced tertiary treatment chemistry at industrial outfalls, expanding addressable demand for specialized coagulant blends.
- Zero-liquid-discharge targets:Power plant cooling tower operators are decoupling from municipal treatment paradigms, creating dedicated chemical streams for high-cycle closed-loop systems.
- Metal-finishing effluent expansion:Asian manufacturing facilities are scaling chemical-intensive pre-treatment capacity to meet stricter electroplating discharge protocols.
Market Restraints
- Chlor-alkali input volatility:Coagulant producers face margin compression from fluctuating caustic soda and chlorine derivative costs tied to energy-intensive electrolysis economics.
- Biocide substitution pressure:UV and ozone disinfection systems are displacing chlorinated isothiazolinones in municipal secondary treatment, constraining volume growth in legacy biocide segments.
- REACH registration friction:European polymer flocculant suppliers encounter extended substance evaluation timelines and data-cost burdens for novel monomer chemistries.
Strategic Opportunities
- Mining tailings premiumization:High-velocity particle settling requirements in Chilean and Australian copper operations are commanding price premiums for tailored anionic flocculant architectures.
- Digital dosing convergence:Integration of real-time turbidity sensors with automated polymer feed systems is expanding into mid-sized municipal utilities previously locked into manual batch operations.
- Oil and gas cooling resilience:Chlorinated isothiazolinone demand persists in offshore platform heat exchange systems where UV alternatives face saltwater corrosion constraints.
Industry Challenges
- Polymer chemistry talent scarcity:Formulation expertise for high-molecular-weight flocculant synthesis concentrates at a handful of specialized research centers, constraining supplier expansion.
- Legacy SCADA integration friction:Automated chemical dosing systems require costly retrofitting of decades-old municipal plant control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water and Waste Water Treatment Chemicals Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flocculants, Coagulants, Biocides, pH Adjusters Application: Municipal Treatment, Industrial Effluent, Oil & Gas, Mining End User: Municipalities, Power Plants, Manufacturing Facilities, Food Processing Distribution Channel: Direct Sales, Retail, Online Sales, Distributors |
| Companies Covered | BASF SE, Ecolab, Kemira, Dow Chemical, Solenis, Kurita Water Industries Ltd., Nouryon, SUEZ, SNF Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water and Waste Water Treatment Chemicals Market Evolving Landscape
Active transformation across this market centers on chemistry-digital convergence, regulatory chemistry substitution mandates, and procurement model compression favoring integrated service providers over commodity suppliers.
Polymer-enhanced coagulant hybrids are expanding into mining and pulp-and-paper effluent streams where dual-function charge neutralization and flocculation reduce dosing complexity. Industrial operators in Nordic clusters and Chilean copper belts are adopting these formulations at accelerated trial-to-contract velocity. This chemistry consolidation is expanding into premium pricing tiers previously segmented between separate coagulant and flocculant procurement categories.
REACH authorization timelines are forcing substitution of acrylamide-based monomers in European flocculant production, compressing approved substance lists and redirecting R&D toward bio-based polysaccharide alternatives. ECHA's ongoing evaluation of cationic polymer ecotoxicity is reshaping formulation roadmaps. Water utilities in Germany and the Netherlands are responding by demanding pre-certified low-toxicity alternatives with documented biodegradation profiles.
Performance-guaranteed service contracts are displacing bulk chemical spot purchasing among mid-sized North American municipalities with constrained technical staffing. Veolia and Suez subsidiaries are capturing multi-year agreements bundling chemical supply, dosing optimization, and compliance reporting. This bundling is most visible in Great Lakes states where EPA consent decrees impose strict phosphorus discharge timelines requiring guaranteed outcome accountability.
Water and Waste Water Treatment Chemicals Market Segmentation
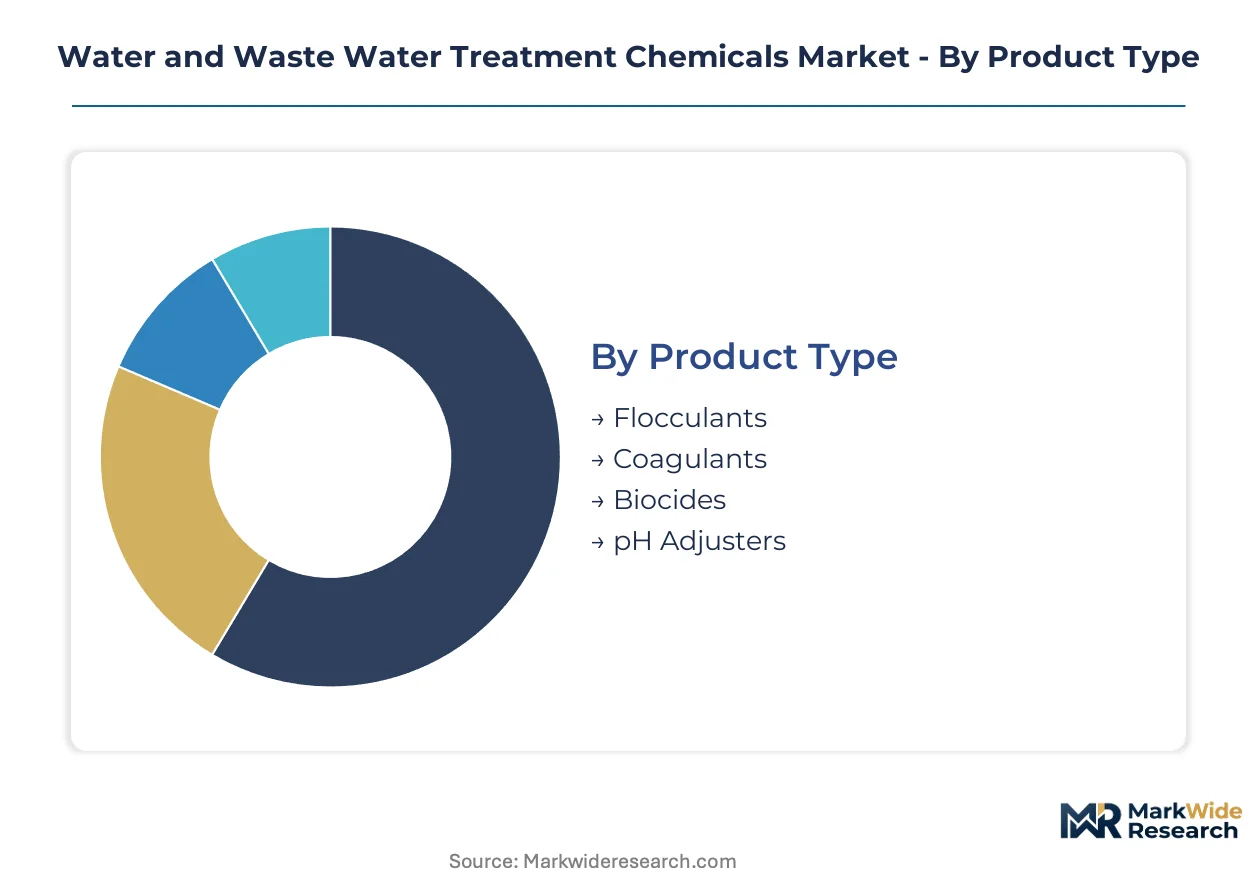
Water and waste water treatment chemicals segment along functional chemistry, application intensity, and procurement complexity. Buyers prioritize formulation efficacy, regulatory compliance pathways, and dosing automation compatibility when selecting across these dimensions.
Product Type:
Procurement decisions in this category hinge on effluent characterization and treatment train configuration, with operators balancing dosing precision against total chemical cost per thousand gallons treated.
- Flocculants:High-molecular-weight polyacrylamide polymers engineered for charge neutralization and particle agglomeration. Mining tailings operations in Chile and Australia command premium anionic architectures where settling velocity determines throughput economics.
- Coagulants:Aluminum sulfate and ferric chloride formulations precipitate suspended solids through charge destabilization. Asian metal-finishing facilities scale procurement to meet stricter electroplating discharge protocols, driving volume concentration.
- Biocides:Chlorinated isothiazolinones and quaternary ammonium compounds control microbial fouling. Oil and gas cooling systems sustain demand where UV alternatives face saltwater corrosion constraints.
- pH Adjusters:Sulfuric acid, caustic soda, and lime compounds stabilize effluent chemistry. Power plant zero-liquid-discharge systems require precise buffering for high-cycle closed-loop operations.
Coagulants lead on scale; flocculants lead on momentum.
Application:
Regulatory stringency varies sharply across these use cases, with municipal discharge permits and industrial effluent standards creating divergent compliance cost structures.
- Municipal Treatment:Tertiary and advanced treatment stages for phosphorus removal and pathogen control. US EPA emerging contaminant rules for PFAS are mandating specialized coagulant blends at municipal outfalls.
- Industrial Effluent:Pre-treatment systems for manufacturing discharge compliance. Nordic pulp-and-paper clusters adopt polymer-enhanced hybrid formulations for dual-function charge neutralization.
- Oil & Gas:Cooling tower biocide programs and produced water treatment. Offshore platforms in the North Sea and Gulf of Mexico rely on chlorinated isothiazolinones for heat exchange protection.
- Mining:Tailings thickening and process water clarification. Chilean copper operations command price premiums for tailored flocculant architectures optimizing particle settling velocity.
Municipal treatment dominates procurement volume; mining applications command the steepest expansion trajectory.
End User:
Technical staffing levels and capital availability shape procurement modality across these buyer types, from performance-guaranteed service contracts to spot bulk purchasing.
- Municipalities:Public water and waste water utilities with constrained technical capacity. Great Lakes states are adopting bundled chemical supply and compliance reporting contracts under EPA phosphorus discharge consent decrees.
- Power Plants:Cooling tower and boiler water treatment operators pursuing zero-liquid-discharge targets. These facilities decouple from municipal paradigms, creating dedicated chemical streams for high-cycle closed-loop systems.
- Manufacturing Facilities:Metal-finishing, electronics, and chemical process plants. Asian facilities scale chemical-intensive pre-treatment capacity to meet stricter electroplating discharge protocols.
- Food Processing:Slaughterhouses, dairies, and beverage plants with high organic load effluent. These operators prioritize biocide alternatives compatible with food safety certifications.
Manufacturing facilities lead on volume growth; municipalities lead on contract innovation.
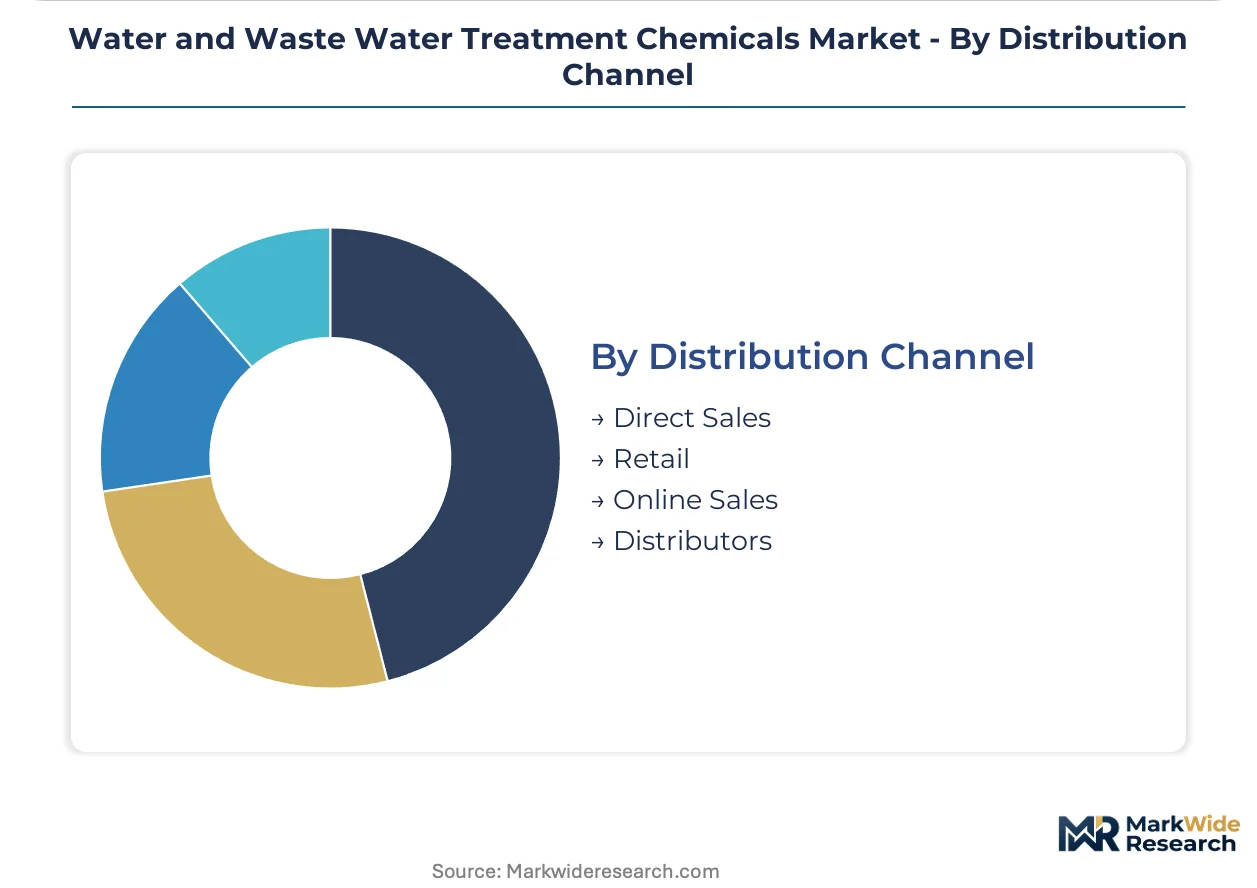
Distribution Channel:
Supply chain configuration reflects buyer scale, technical sophistication, and geographic concentration of demand.
- Direct Sales:Manufacturer-to-end-user relationships for large-volume industrial accounts. Mining and power sector buyers leverage direct channels for formulation customization and technical service integration.
- Distributors:Regional chemical wholesalers serving mid-sized municipal and industrial accounts. These intermediaries stock standard coagulant and biocide grades for rapid fulfillment.
- Retail:Packaged treatment chemicals for small commercial and residential systems. Limited to pH adjusters and basic biocides in standardized container sizes.
- Online Sales:E-procurement platforms for standardized formulations and replenishment ordering. Mid-sized utilities with automated inventory systems are piloting digital reordering workflows.
Direct sales lead on revenue concentration; distributor networks lead on geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of water and waste water treatment chemicals is gravitating toward jurisdictions with integrated chlor-alkali capacity and lower energy costs, as European REACH compliance burdens widen cost-of-compliance gaps with Asian manufacturing bases.
United States
Power plant zero-liquid-discharge retrofits and EPA consent decrees in Great Lakes states are expanding demand for specialized coagulant blends. The EPA's emerging contaminant rules for PFAS are mandating tertiary treatment chemistry at municipal outfalls. Industrial clusters in Texas and the Ohio River Valley are scaling chemical procurement for refinery and petrochemical effluent compliance.
Germany
ECHA's evaluation of cationic polymer ecotoxicity is compressing approved substance lists for flocculant formulations. REACH authorization timelines are forcing substitution of acrylamide-based monomers toward bio-based polysaccharide alternatives. The Ruhr industrial region and Bavarian chemical corridor are piloting pre-certified low-toxicity alternatives with documented biodegradation profiles.
China
The MEE's enforcement of GB surface water standards is forcing simultaneous upgrades across thousands of legacy municipal plants. Stricter electroplating discharge protocols are scaling chemical-intensive pre-treatment capacity in Yangtze River Delta manufacturing zones. Municipal procurement timelines are compressing, favoring suppliers with rapid-scale formulation capabilities in Jiangsu and Zhejiang provinces.
Chile
Copper mining tailings operations are commanding price premiums for tailored anionic flocculant architectures where particle settling velocity determines throughput economics. The Antofagasta and Atacama mining belts are expanding high-velocity thickening capacity. Suppliers are securing multi-year offtake agreements with state-owned copper majors for customized polymer chemistries.
Australia
Iron ore and lithium mining tailings treatment is driving demand for high-molecular-weight flocculants in Western Australia's Pilbara region. Water scarcity constraints are accelerating closed-loop process water systems requiring precise pH adjustment chemistry. The Queensland coal seam gas sector is sustaining biocide demand for produced water treatment infrastructure.
Water and Waste Water Treatment Chemicals Market Competitive Landscape
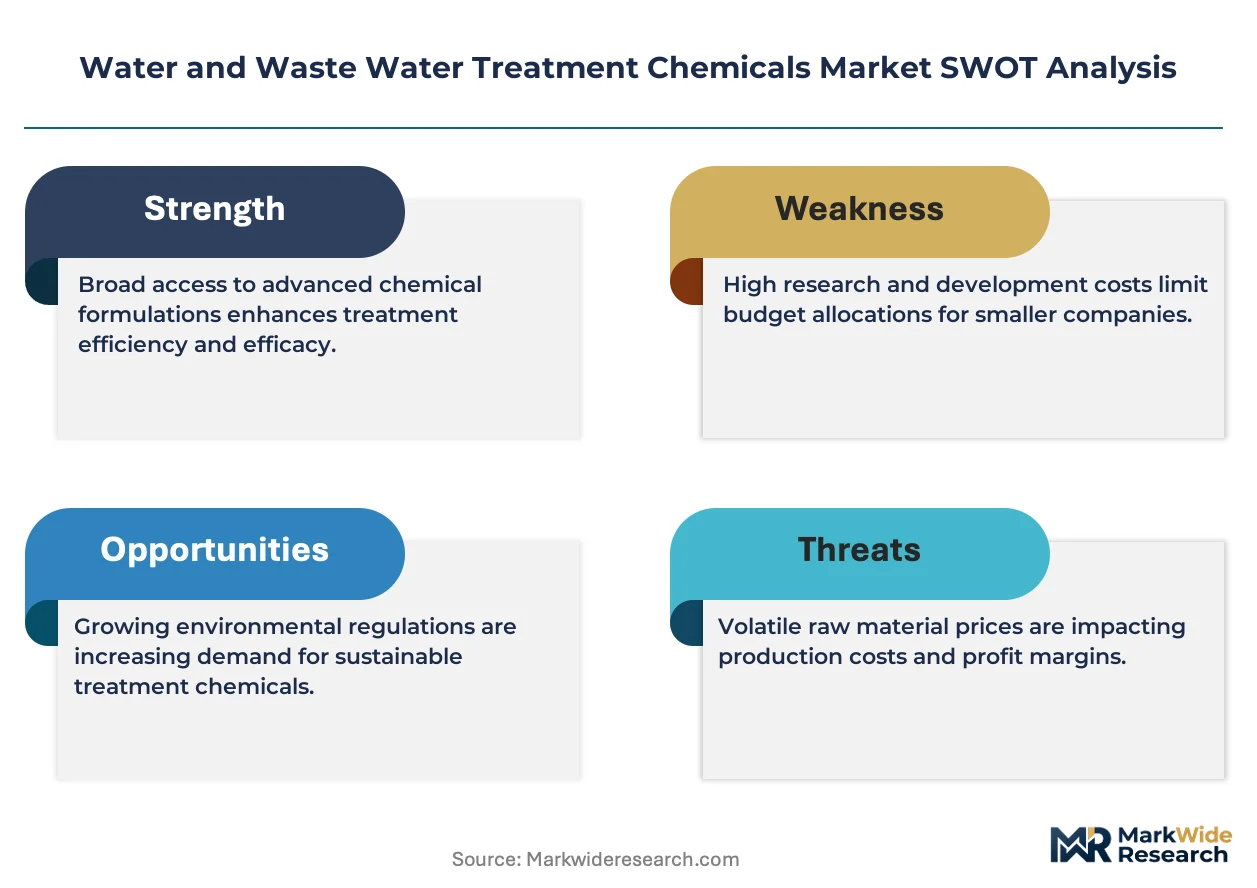
Branded specialists and contract manufacturers split share differently across segments, with formulation-integrated players capturing premium pricing in mining and oil and gas applications while commodity suppliers compete on volume in municipal coagulant procurement. The market structure concentrates around three strategic archetypes: integrated polymer chemistry platforms serving European industrial clusters, regional specialists anchoring Nordic pulp-and-paper effluent markets, and scale-driven suppliers with chlor-alkali backward integration. Dominant competitive moves include portfolio diversification into performance-guaranteed service contracts and geographic expansion through distributor network consolidation.
Within the integrated chemistry platform tier, BASF SE exemplifies the European industrial cluster anchor position, while Kemira occupies a specialized role in Nordic pulp-and-paper effluent markets. SNF Group represents the scale-driven archetype with polymer synthesis capabilities concentrated at dedicated research centers. These three entities illustrate how formulation expertise and regional regulatory navigation determine competitive positioning across divergent procurement modalities.
| Leading Market Players |
|---|
| BASF SE |
| Ecolab |
| Kemira |
| Dow Chemical |
| Solenis |
| Kurita Water Industries Ltd. |
| Nouryon |
| SUEZ |
| SNF Group |
| Others |
Value Network & Pricing Analysis
Captive chlor-alkali integration anchors both supply security and pricing power for major coagulant producers, insulating them from caustic soda volatility while enabling margin defense against spot-market competitors. This backward control over electrolysis inputs concentrates leverage among suppliers with dedicated membrane-cell capacity in energy-advantaged jurisdictions.
Pricing Analysis
Distributor margin layers compress pricing transparency for mid-sized municipal buyers lacking direct formulation expertise. Three-tier pricing structure across premium, standard, and economy levels separates mining-tailoring flocculant architectures from commodity coagulant grades. Pricing pressure stems from chlor-alkali input volatility tied to energy-intensive electrolysis economics. Municipal utilities exhibit highest price sensitivity; mining operators with throughput-dependent settling economics show lowest.
Supply Chain Analysis
Dual-sourcing requirements from European water utilities mandate multi-supplier qualification for polymer flocculants, fragmenting procurement across BASF, Kemira, and SNF. Supply concentrates in Germany, China, and the United States for chlor-alkali backward integration. Raw material dependencies include caustic soda, acrylamide monomers, and sulfuric acid. Single-source vulnerability persists for high-molecular-weight flocculant synthesis where specialized research centers concentrate expertise. Distribution runs through regional chemical wholesalers stocking standard grades for rapid fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder where regulatory tightening of discharge limits sustains steady replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Anticipate substitution pressure from UV and ozone disinfection systems by accelerating polymer-enhanced coagulant hybrid development. Defend position by deepening captive chlor-alkali integration in energy-advantaged production hubs. Prioritize certification investment for REACH-compliant bio-based polysaccharide alternatives ahead of ECHA authorization timelines.
For New Entrants and Emerging Players: The price-point gap between premium mining-tailored flocculants and economy municipal coagulants offers white-space targeting. Mid-sized North American municipalities with bundled service contract appetite represent the most penetrable segment. Pursue digital dosing convergence partnerships with sensor automation vendors as primary go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for regional specialists with Nordic pulp-and-paper or Chilean mining anchorage because customer switching costs embed multi-year offtake agreements. Long-term viability centers on formulation-integrated players capturing premium pricing in industrial effluent segments. Acquisition target archetype: mid-cap specialists with proven rapid-scale formulation capabilities. Monitor ECHA cationic polymer ecotoxicity evaluations as inflection indicator for substitution-driven M&A activity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali | Captive caustic soda supply insulates BASF and Dow from electrolysis cost volatility. |
| Performance-Guaranteed Service Contracts | Veolia subsidiaries lock multi-year municipal revenue under EPA phosphorus discharge consent decrees. |
| Bio-Based Polysaccharide R&D | REACH authorization timelines force substitution away from acrylamide monomers in European production. |
| Mining Tailings Formulation Partnerships | Customized anionic architectures command price premiums at Chilean state-owned copper operations. |
| Digital Dosing System Integration | Real-time turbidity sensor convergence expands into mid-sized utilities previously manual-dependent. |
Research Methodology
Multiple input streams — technical discussions with municipal plant operators and procurement leads, executive interviews with polymer R&D directors and distribution channel partners, and validation sessions with chlor-alkali production planners — were reconciled against customs trade data, ACC and Cefic industry reports, SEC 10-K chemical segment disclosures, and EPA enforcement action databases. Bottom-up volume modeling across treatment train configurations was cross-checked against top-down market sizing from identified supplier revenue disclosures.
Historical capacity expansion patterns were cross-referenced against panel input from water utility planning officers and mining process engineers to establish trajectory parameters across the projection horizon. Segmentation dimensions modeled include functional chemistry type, application intensity tier, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from slope analysis of identified demand drivers rather than mechanical extrapolation. Forecast inputs incorporated MEE enforcement intensity assessments for Chinese municipal upgrades and EPA emerging contaminant rule implementation pacing.
The model assumes a particular technology adoption path; alternative pathways for UV-ozone disinfection substitution would alter the outlook for chlorinated isothiazolinone demand. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and raw material cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Over the Top Devices and Services Market
Others
GCC Shisha Tobacco Market
Others
Europe Medical Simulation Market
Others
Pet Care Packaging Market
Others
India 3D Printing Construction Market
Others
IT Device Market
Others
North America Machine Vision Systems Market
Others
Augmented Reality (AR) in Warehousing and Logistics Market
Others
Aircraft Exterior Lighting Market
Others
Bitcoin Mining Servers Market
Others
Ceramic Machinery Market
Others
Lychee Market
Others
North America IT Device Market
Others
Global Luxury High End Furniture Market
Others
Bird Food Market
Others
Construction Fabrics Market