
 Global Smart Kitchen Market | 2026-2036
Global Smart Kitchen Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Kitchen Market Outlook
Chinese appliance manufacturing clusters is rebalancing capacity toward Wi-Fi-enabled cooking and refrigeration platforms. Samsung Electronics leverages vertical integration across semiconductor and display divisions to control smart oven component pipelines. LG Electronics anchors its position through AI-driven food management systems embedded in connected refrigerators. Whirlpool Corporation competes on brand equity and installer channel relationships across North American homebuilder networks.
Smart kitchens comprise networked cooking, preservation, and meal-planning appliances that exchange data via IoT protocols, typically operating on 2.4 GHz or 5 GHz wireless bands with cloud-based recipe optimization and energy monitoring functions. Their commercial purpose centers on reducing food waste, automating cooking workflows, and enabling remote appliance management. Smart refrigerators command the largest installed base among product categories, while smart cookware represents the fastest-expanding segment as induction-compatible sensors and app-guided temperature control gain traction. IoT technology underpins most installations, though voice assistant integration is becoming a standard feature rather than a premium differentiator.
The EU Ecodesign Directive and REACH framework impose energy labeling and material disclosure requirements that constrain market entry for uncertified suppliers. The FCC in the United States regulates wireless connectivity modules, creating pre-market testing obligations that extend product development timelines. Stakeholders must monitor how cybersecurity standards evolve for connected home devices, as regulatory fragmentation between CE marking and FCC certification could reshape global product architecture decisions.
Market Dynamics
Energy efficiency mandates across multiple jurisdictions are compressing product development cycles while simultaneously fragmenting certification requirements, forcing appliance manufacturers to maintain parallel compliance architectures for wireless connectivity modules and material disclosure frameworks.
Growth Catalysts
- EU Ecodesign Directive:Mandatory energy labeling for refrigeration and cooking appliances creates upgrade cycles across European residential households, pulling replacement demand forward by 3-5 years for connected product categories.
- Induction-compatible sensor platforms:Wi-Fi-enabled cookware with embedded temperature monitoring is penetrating mid-market consumer segments in China and South Korea, expanding addressable market beyond premium early adopters.
- Cloud-based recipe optimization:Subscription meal-planning services integrated with smart ovens are generating recurring revenue streams that subsidize hardware margins and extend customer lifetime value.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea dominate microcontroller and connectivity chip fabrication, creating vulnerability in smart appliance production schedules during foundry capacity constraints.
- FCC pre-market testing timelines:Wireless module certification adds 4-8 months to product launch schedules for manufacturers targeting US distribution, compressing competitive response windows.
- Legacy appliance substitution:Conventional refrigeration and cooking equipment with 15-20 year replacement cycles delays smart kitchen penetration in cost-sensitive housing segments.
Strategic Opportunities
- India residential electrification:Government appliance subsidy schemes under the UJALA program are creating first-time buyer markets for connected cooking platforms in tier-2 and tier-3 cities.
- Voice assistant convergence:Integration with Alexa, Google Assistant, and Tmall Genie ecosystems is becoming a baseline expectation rather than premium feature, opening standardization pathways for smaller OEMs.
- Food waste reduction mandates:France's AGEC law and similar extended producer responsibility frameworks in Italy and Spain incentivize AI-driven inventory management as compliance-enabling technology.
Industry Challenges
- Cybersecurity certification fragmentation:Divergent standards between CE marking requirements and FCC guidelines force manufacturers to maintain multiple firmware architectures, increasing QA overhead.
- Legacy electrical infrastructure:Older residential buildings in Germany, Japan, and the northeastern United States lack adequate circuit capacity for high-wattage induction cooking platforms, requiring costly retrofitting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Kitchen Market |
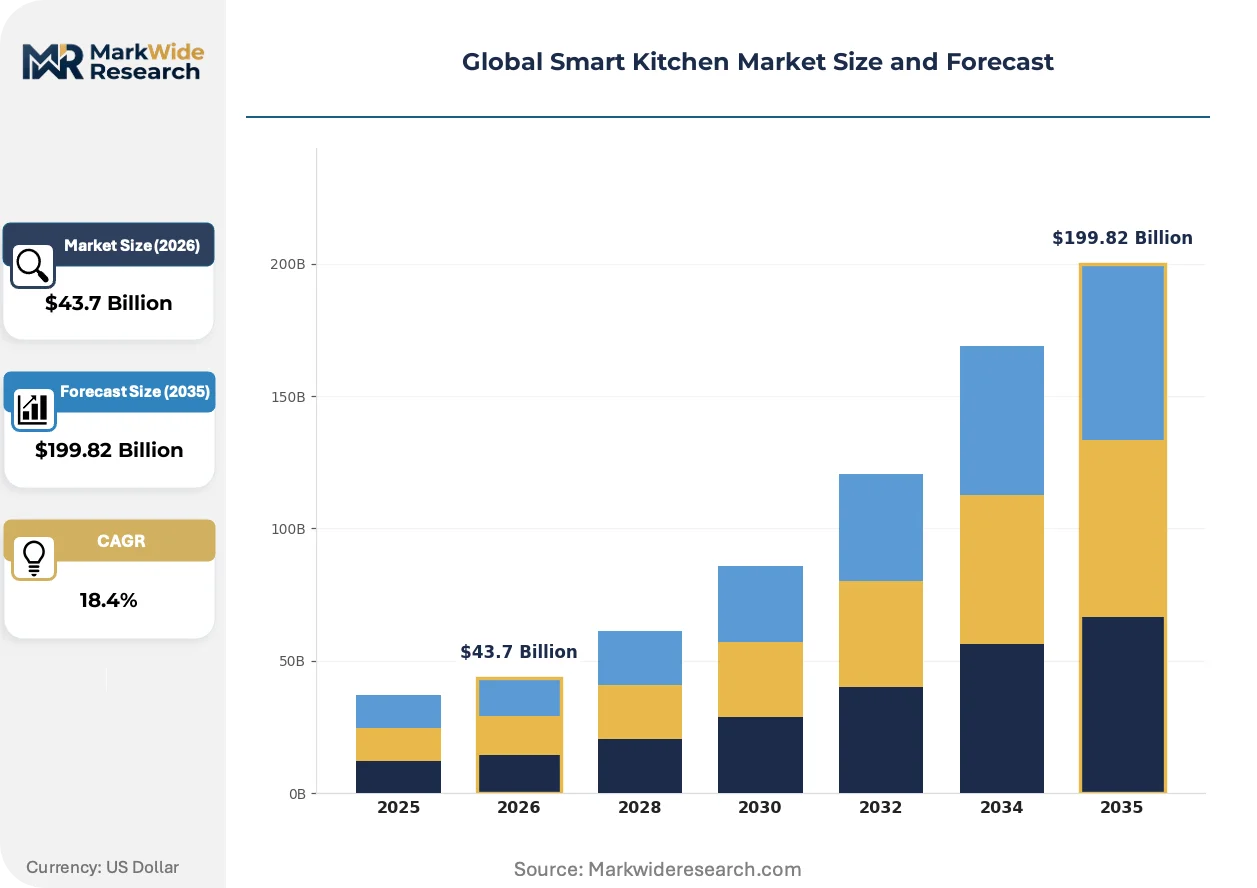
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $199.82 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Ovens, Smart Refrigerators, Smart Dishwashers, Smart Cookware Technology: IoT, AI, Voice Assistants, Wireless Connectivity End User: Residential, Commercial, Hospitality, Professional Chefs Application: Cooking, Food Preservation, Meal Preparation, Kitchen Management |
| Companies Covered | Samsung Electronics, LG Electronics, Whirlpool Corporation, Electrolux AB, Panasonic Corporation, Haier Group, BSH Hausgeräte GmbH, Miele & Cie. KG, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Kitchen Market Strategic Shifts
Sensor fusion across cooking and preservation appliances is compressing the gap between automated food preparation and manual intervention, while regulatory pressure on energy consumption and material sourcing accelerates hardware redesign cycles.
Induction heating with embedded magnetic field sensors is electrifying temperature control precision in residential cooking platforms. Mid-market buyers in China and South Korea are adopting app-guided cookware at twice the pace of Western markets. The technology is electrifying replacement demand for conventional gas and resistive electric ranges by embedding programmable cooking profiles that reduce operator attention requirements.
REACH framework substance restrictions are forcing reformulation of insulation foams and electronic component coatings in refrigeration manufacturing. European suppliers face 18-month compliance windows for newly listed SVHC candidates. Smart refrigerator OEMs serving Germany, France, and the Netherlands are accelerating supplier audits and material traceability system investments to maintain market access.
Builder channel specification contracts are consolidating purchasing authority for new residential construction across North America. Multi-family developers in Texas, Florida, and Arizona now bundle connected appliance packages as standard features rather than upgrades. The shift is most visible in master-planned communities where homebuilder procurement teams negotiate multi-year supply agreements with Whirlpool, LG, and Samsung distribution arms.
Global Smart Kitchen Market Segmentation
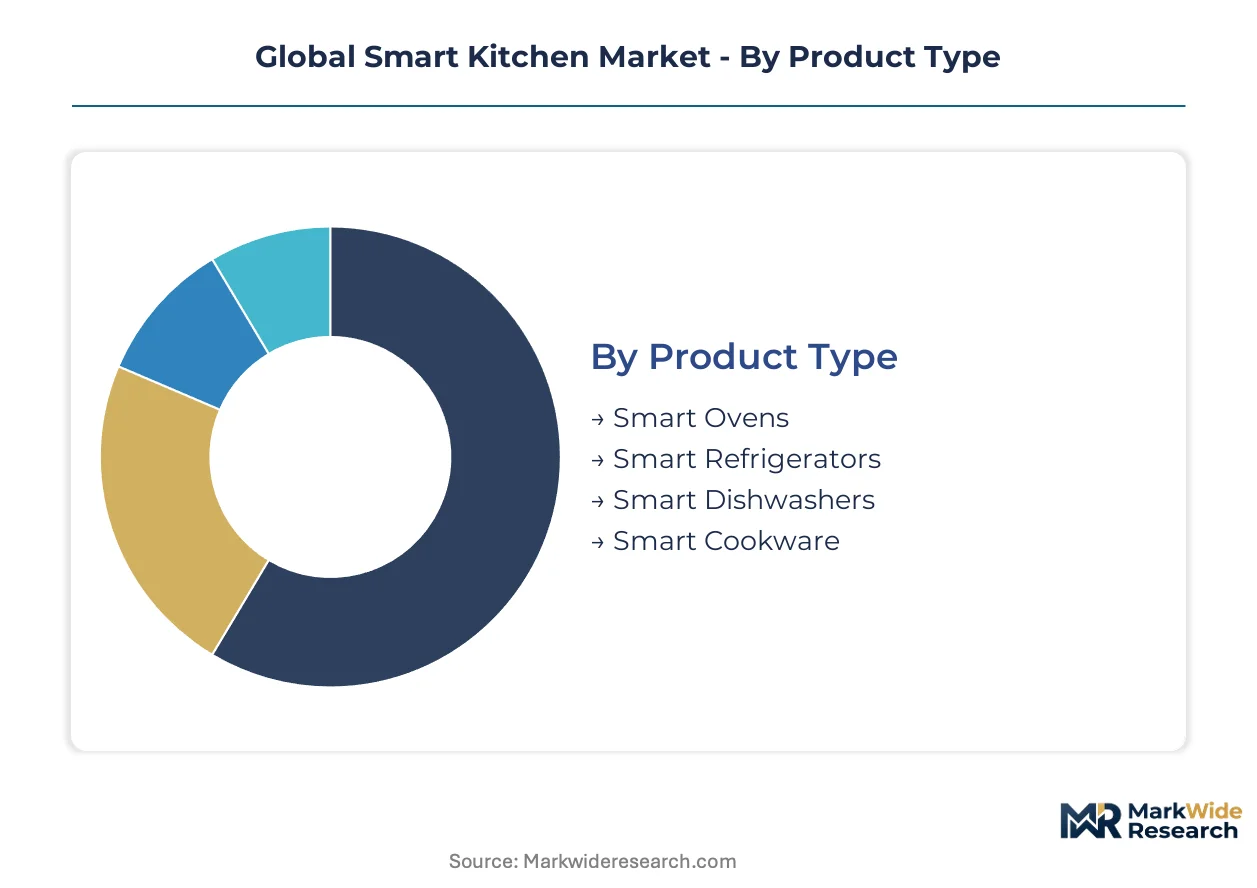
Smart kitchen segmentation reveals how hardware specifications, connectivity protocols, and user workflows determine purchasing authority and margin structures across residential and commercial channels. Manufacturers configure product architectures around these axes to align certification requirements with addressable demand pools.
Product Type:
Technology specifications differentiate thermal management systems, sensor arrays, and connectivity modules across cooking and preservation platforms.
- Smart Ovens:Convection and steam-assist heating elements integrate with Wi-Fi-enabled recipe databases and remote preheat functions. Residential demand concentrates in Germany and France where EU Ecodesign Directive mandates accelerate replacement cycles for energy-inefficient legacy units.
- Smart Refrigerators:Multi-zone cooling with embedded cameras and inventory tracking software commands the largest installed base. Chinese manufacturers scale production of Wi-Fi-enabled preservation platforms for domestic consumption and export markets across Southeast Asia.
- Smart Dishwashers:Water-usage sensors and cycle-optimization algorithms reduce consumption per load. Commercial kitchens in US metropolitan areas adopt connected dishwashing platforms to meet municipal water conservation ordinances.
- Smart Cookware:Induction-compatible vessels with embedded temperature probes enable app-guided precision cooking. South Korean and Chinese mid-market buyers adopt sensor-equipped pots and pans at penetration rates exceeding Western markets.
Smart refrigerators lead on scale; smart cookware leads on momentum.
Technology:
Cost tiers separate premium integrated platforms from modular retrofit solutions across consumer and commercial segments.
- IoT:Device-to-cloud data pipelines enable remote monitoring, energy tracking, and predictive maintenance alerts. FCC certification requirements in the United States and CE marking in Europe create parallel compliance architectures for wireless module firmware.
- AI:Computer vision for food recognition and predictive inventory management automates meal planning workflows. Hospitality operators in Japan deploy AI-driven kitchen management systems to optimize labor scheduling and ingredient procurement.
- Voice Assistants:Alexa, Google Assistant, and Tmall Genie integration shifts from premium differentiator to baseline expectation. Residential consumers in India and Brazil prioritize voice control accessibility over touchscreen interfaces.
- Wireless Connectivity:2.4 GHz and 5 GHz protocols support real-time data exchange between appliances and cloud services. Semiconductor supply concentration in Taiwan and South Korea creates vulnerability in production schedules during foundry capacity constraints.
IoT platforms anchor volume deployment; AI capabilities command premium pricing expansion.
End User:
Application intensity and procurement authority vary sharply between household decision-makers and institutional purchasing departments.
- Residential:Individual households prioritize convenience features and energy cost reduction. North American homebuilder networks bundle connected appliance packages as standard features in master-planned communities across Texas, Florida, and Arizona.
- Commercial:Restaurant chains and foodservice operators demand centralized fleet management and standardized cooking protocols. Multi-unit operators negotiate enterprise pricing based on volume procurement across distributed locations.
- Hospitality:Hotels and resorts integrate kitchen automation with property management systems for guest service optimization. European hospitality groups deploy connected cooking platforms to comply with France's AGEC law on food waste reduction.
- Professional Chefs:Culinary training institutions and high-end restaurants require precision temperature control and recipe reproducibility. Certification programs in Italy and Spain specify connected equipment for standardized skill assessment.
Residential channels dominate unit volume; hospitality segments sustain margin premiums.
Application:
Workflow automation depth determines hardware configuration and software subscription attach rates across use cases.
- Cooking:Automated temperature profiles and ingredient recognition reduce operator attention requirements. Induction heating with magnetic field sensors is electrifying replacement demand for gas and resistive electric ranges in German and Japanese residential markets.
- Food Preservation:Spoilage prediction algorithms and inventory visualization extend perishable shelf life. REACH framework substance restrictions force reformulation of insulation foams in refrigeration manufacturing for European market access.
- Meal Preparation:Integrated weighing, portioning, and nutritional analysis streamline pre-cooking workflows. Cloud-based recipe optimization services generate recurring revenue streams that subsidize hardware margins.
- Kitchen Management:Centralized monitoring dashboards consolidate energy usage, maintenance scheduling, and supply chain coordination. Commercial operators in South Korea deploy unified management platforms across multi-site restaurant portfolios.
Cooking applications capture the largest hardware revenue; kitchen management software expands fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China outpaces Germany in connected appliance manufacturing scale, while the United States concentrates premium demand through homebuilder channel consolidation. Regulatory divergence between FCC certification and CE marking protocols fragments product architecture decisions across major demand centers.
United States
Master-planned communities in Texas, Florida, and Arizona bundle connected appliance packages as standard features rather than upgrades. FCC pre-market testing timelines for wireless connectivity modules extend product launch schedules by 4-8 months. Atlanta and Dallas serve as distribution hubs where multi-family developers negotiate multi-year supply agreements with major appliance brands.
China
Domestic manufacturers scale Wi-Fi-enabled refrigerator and oven production for both domestic consumption and Southeast Asian export markets. MIIT certification requirements and GB standards for wireless home devices create parallel compliance pathways alongside international frameworks. Guangdong and Jiangsu province manufacturing clusters concentrate induction-compatible sensor platform assembly for mid-market buyers.
Germany
EU Ecodesign Directive mandates accelerate replacement cycles for energy-inefficient legacy cooking and refrigeration units. REACH framework substance restrictions force 18-month compliance windows for insulation foam reformulation in smart refrigerator manufacturing. Bavaria and North Rhine-Westphalia anchor industrial R&D facilities where OEMs develop predictive maintenance algorithms for connected kitchen platforms.
Japan
Hospitality operators deploy AI-driven kitchen management systems to optimize labor scheduling and ingredient procurement in Tokyo and Osaka metropolitan areas. METI efficiency standards for residential appliances drive demand for induction heating platforms with embedded magnetic field sensors. Nagoya manufacturing corridors supply precision temperature control modules for professional chef certification programs.
India
Government appliance subsidy schemes under the UJALA program create first-time buyer markets for connected cooking platforms in tier-2 and tier-3 cities. BIS certification requirements for electronic goods establish baseline safety protocols for Wi-Fi-enabled product entry. Maharashtra and Karnataka urban corridors concentrate installer channel development for mid-market residential electrification.
Global Smart Kitchen Market Competitive Environment
East Asian producers anchor one tier; European specialists hold premium positioning through certification-grade engineering. The vendor base organizes around three strategic archetypes: diversified electronics conglomerates with captive semiconductor supply, dedicated appliance manufacturers with installer channel dominance, and precision-engineering houses serving commercial hospitality segments. Competitive moves concentrate on backward integration into connectivity module design and geographic expansion through builder specification contracts.
Within the diversified electronics tier, Samsung Electronics and LG Electronics exemplify conglomerate structures leveraging in-house display and semiconductor divisions. Whirlpool Corporation occupies a position as the North American channel anchor through homebuilder network relationships. BSH Hausgeräte GmbH represents the European engineering archetype with certification-intensive product architectures. Haier Group anchors Chinese manufacturing scale for export-oriented smart refrigeration platforms.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Whirlpool Corporation |
| Electrolux AB |
| Panasonic Corporation |
| Haier Group |
| BSH Hausgeräte GmbH |
| Miele & Cie. KG |
| Koninklijke Philips N.V. |
| Others |
Value Chain & Pricing Dynamics
Builder procurement consolidation across Texas, Florida, and Arizona master-planned communities is compressing distributor margins and forcing appliance OEMs to absorb certification costs or cede shelf space to vertically integrated conglomerates with captive semiconductor supply.
Pricing Analysis
Retailer markup layers separate premium AI-enabled platforms from standard IoT-connected units and economy-grade voice-assistant-only configurations. Price differentiation hinges on certification grade—CE-marked and FCC-certified modules command hardware premiums—and volume scale through multi-year builder channel contracts. Cost compression in mid-market smart cookware is intensifying because Chinese manufacturers are scaling induction-compatible sensor platforms for domestic and Southeast Asian export markets. Residential homebuilder procurement teams exhibit the highest price sensitivity, while hospitality operators purchasing enterprise fleet management systems demonstrate the lowest.
Supply Chain Analysis
EU local-content thresholds under the Ecodesign Directive and REACH framework are reshaping sourcing patterns for insulation foams and electronic component coatings in refrigeration manufacturing. Semiconductor fabrication concentrates in Taiwan and South Korea, with microcontroller and connectivity chip supply feeding from foundry capacity in those jurisdictions. Raw material dependencies span rare earth magnets for induction heating modules, copper wiring for wireless connectivity, and specialized polymers for food-safe sensor housings. Single-source vulnerability in Taiwan-based foundry capacity creates production schedule risk during capacity constraints. Distribution runs through installer channel relationships in North American homebuilder networks and direct OEM partnerships in Chinese domestic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Ecodesign Directive operates as a regulatory compounder, accelerating replacement cycles for energy-inefficient legacy appliances and pulling forward demand for connected refrigeration and cooking platforms across European residential households.
For Market Incumbents: Extend backward integration into connectivity module firmware design to reduce FCC and CE marking compliance overhead and compress product development timelines. Consolidate installer channel relationships in North American homebuilder networks to defend against emerging Chinese OEMs scaling export-oriented production. Certification investment in REACH-compliant material traceability systems represents a critical lever for maintaining German, French, and Dutch market access.
For New Entrants and Emerging Players: Enter via India's tier-2 and tier-3 cities under UJALA subsidy schemes, where first-time buyer markets for connected cooking platforms remain underpenetrated by established global brands. Target mid-market residential electrification segments with voice-assistant-first product architectures that prioritize accessibility over touchscreen interfaces. A direct-to-installer go-to-market angle bypasses established retailer markup layers and captures margin otherwise captured by distributor intermediaries.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision-engineering houses serving commercial hospitality segments in Japan and Europe, where AI-driven kitchen management systems command sustained margin premiums. Long-term viability across the analysis window favors acquisition targets with captive certification-grade engineering capabilities and established relationships with multi-unit restaurant operators. Watch for inflection signals in semiconductor foundry capacity utilization rates, which dictate production schedule reliability across the entire smart appliance value chain.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Connectivity Modules | Samsung Electronics and LG Electronics leverage in-house semiconductor divisions to control smart oven component pipelines and reduce certification overhead. |
| Builder Channel Specification Contracts | Whirlpool Corporation negotiates multi-year supply agreements with multi-family developers in Texas, Florida, and Arizona master-planned communities. |
| AI-Driven Food Management Systems | LG Electronics anchors market position through predictive inventory algorithms embedded in connected refrigerators serving European compliance mandates. |
| Induction-Compatible Sensor Platform Scale-Up | Chinese manufacturers in Guangdong and Jiangsu provinces expand Wi-Fi-enabled cookware assembly for mid-market buyers in domestic and Southeast Asian markets. |
| REACH-Compliant Material Traceability Investment | BSH Hausgeräte GmbH accelerates supplier audits and insulation foam reformulation to maintain German market access under 18-month compliance windows. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with appliance OEM product managers, homebuilder procurement directors, hospitality fleet operators, semiconductor supply chain specialists, and regulatory affairs consultants. Secondary validation draws from FCC equipment authorization databases, EU Ecodesign Directive implementation reports, MIIT certification filings, customs trade data for connected appliance exports, and SEC 10-K disclosures from publicly traded appliance manufacturers. Bottom-up unit shipment estimates triangulate against top-down market value assessments derived from channel margin analysis.
Rate-of-change decomposition separates volume expansion from pricing trajectory across the modeling period, with analytical frameworks modeling product type, technology tier, end-user segment, and application intensity dimensions. CAGRs derive from fitted growth curves applied to replacement cycle acceleration under energy efficiency mandates and first-time buyer penetration in emerging electrification markets. Industry-specific forecast inputs include foundry capacity utilization projections from Taiwan and South Korea, and builder channel contract visibility in North American metropolitan development pipelines.
Inputs from FCC pre-market testing databases and EU Ecodesign Directive compliance registries were available through the study window; gaps in real-time semiconductor inventory positions and confidential builder contract terms introduce uncertainty bands around near-term shipment forecasts. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and foundry capacity expansion timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Molecular Spectroscopy Market
Others
Transportation Lighting Market
Others
Global Video Processing Platform Market
Others
Magnetic Stripe Readers Market
Others
Land Surveying Equipment Market
Others
Delumper Market
Others
Industrial Tablet PC Market
Others
Gesture Recognition for Smart TV Market
Others
Mobile Computer Cart Market
Others
India Home Automation Market
Others
Thiamethoxam Market
Others
Managed Video As a Service Market
Others
Thailand Commercial Vehicles Lubricants Market
Others
Asia-Pacific Social Media Management Market
Others
Europe Transportation Management Systems Market
Others
Vacuum Evaporators Market