
 Dried Fruit Extracts Market | 2026-2036
Dried Fruit Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Fruit Extracts Market Foresight
Multi-source procurement for raw fruit supply is realigning how extract processors manage cost volatility and quality consistency. Archer Daniels Midland Company leverages its global agricultural sourcing network to secure year-round fruit availability across temperate and tropical zones. Graceland Fruit anchors its position through deep vertical integration into Michigan-based tart cherry orchards, controlling cultivar selection through final extraction. AGRANA Beteiligungs-AG competes by concentrating its procurement on European apple and berry cooperatives, reducing transcontinental logistics exposure.
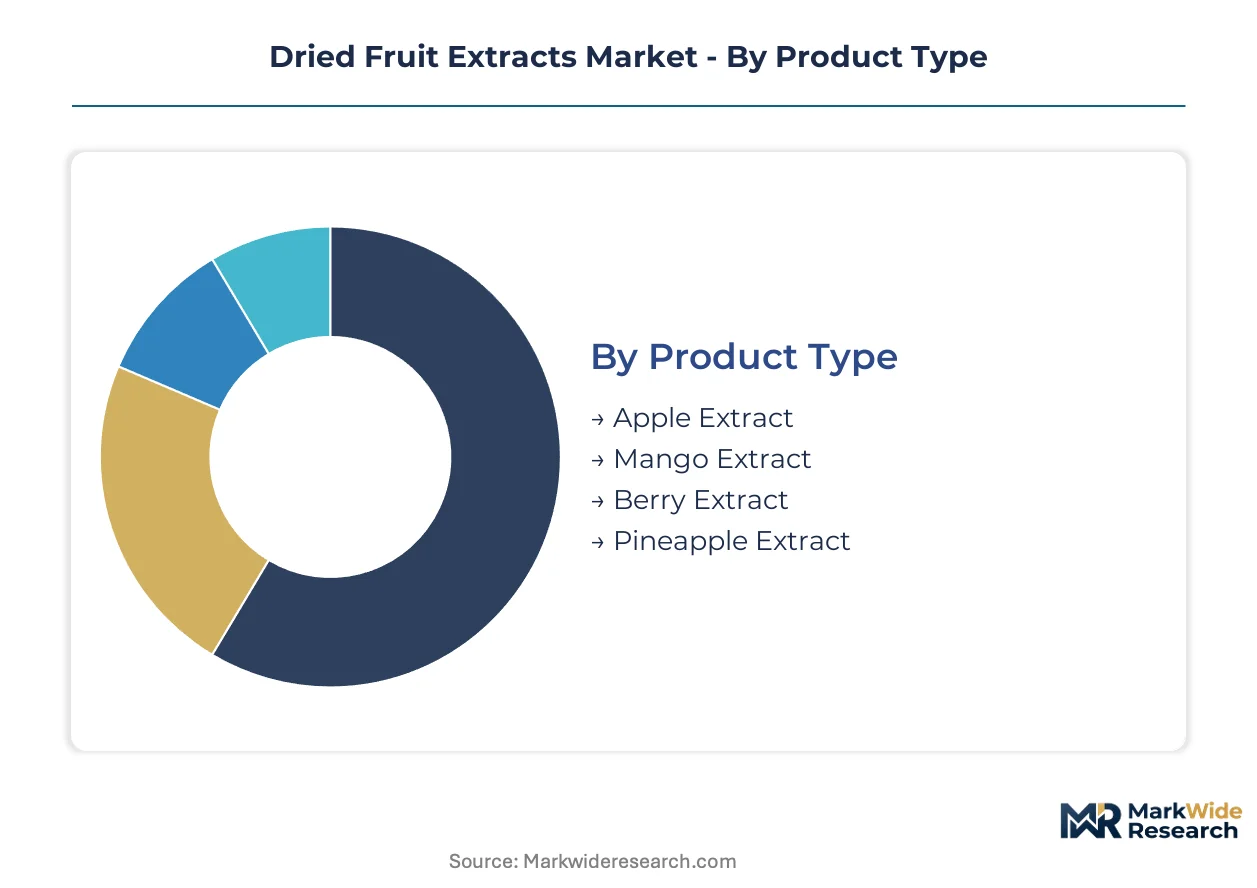
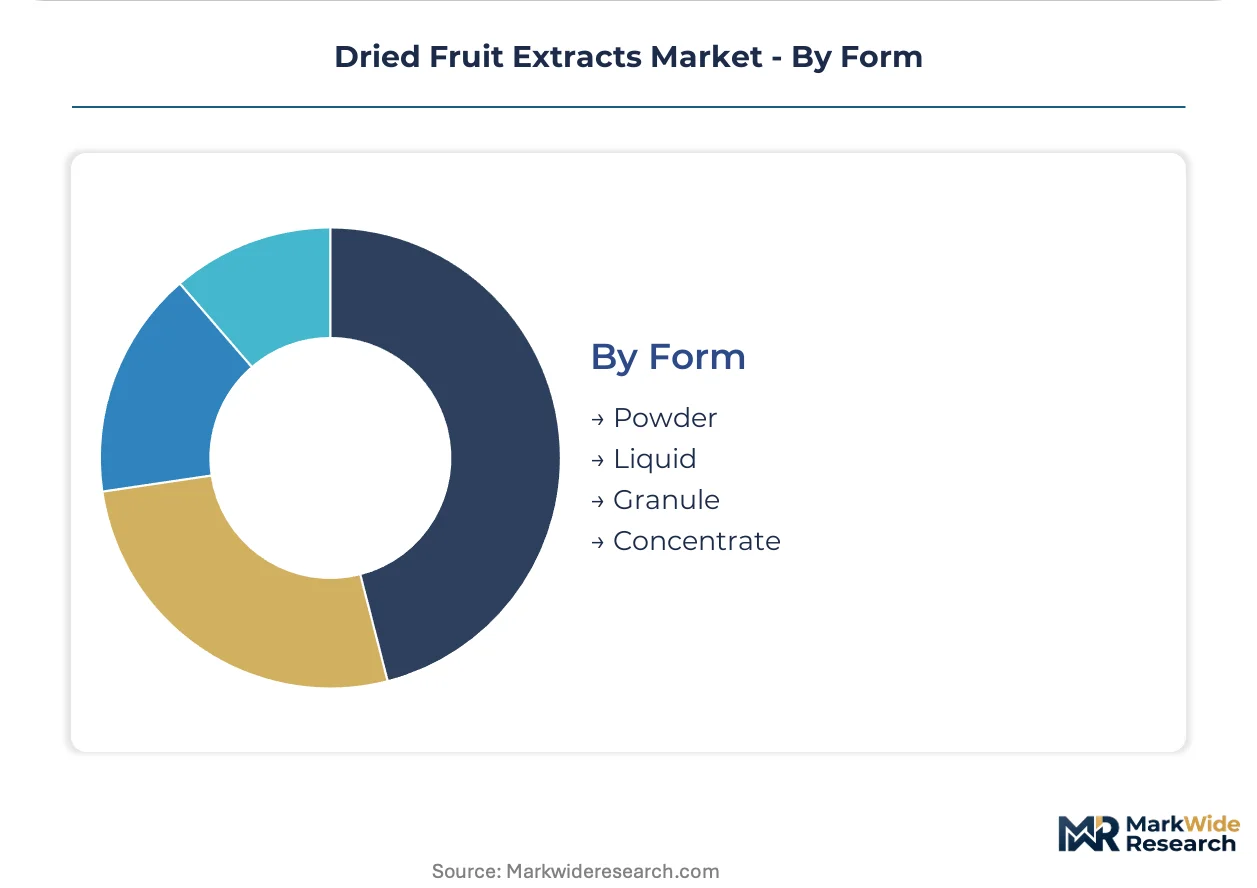
Dried fruit extracts are concentrated bioactive preparations obtained by dehydrating fruit matrices and subsequently extracting soluble compounds using aqueous, solvent, or supercritical CO2 methods, typically standardized to polyphenol, anthocyanin, or brix levels for batch consistency. These extracts serve primarily as natural flavoring agents, colorants, and functional sweeteners in formulated consumer products where synthetic additive replacement drives purchasing decisions. Berry extract commands premium positioning due to concentrated anthocyanin content and provenance-linked antioxidant claims that cosmetic brands and dietary supplement companies prize. Powder form dominates commercial volumes because of superior shelf stability and compatibility with dry-blend manufacturing lines in food and nutraceutical facilities. Liquid concentrate occupies specialized niches in beverage applications where rapid dissolution and precise dosing control matter.
EPA guidelines on agricultural pesticide residues directly constrain which fruit cultivars enter US-bound extract streams, while REACH compliance in Europe mandates full toxicological dossiers for novel extraction solvents. The EU Green Deal's farm-to-fork pesticide reduction targets are tightening allowable residue thresholds, forcing processors to validate organic and integrated pest management supply chains. Stakeholders must monitor how diverging transatlantic maximum residue limits reshape supplier qualification criteria and extraction technology investments.
Market Dynamics
The EU F-Gas Regulation is forcing extract processors to abandon conventional freeze-drying infrastructure in favor of heat-pump and microwave-assisted dehydration systems that slash energy intensity and refrigerant leakage.
Growth Catalysts
- Clean-label beverage reformulation:German and French beverage formulators are substituting monk fruit and berry extracts for synthetic sweeteners to meet EU Green Deal farm-to-fork targets on added sugar reduction.
- REACH-compliant solvent innovation:Supercritical CO2 extraction methods are gaining regulatory acceptance across European cosmetic applications, enabling anthocyanin recovery without toxicological dossier burdens.
- Polyphenol standardization protocols:Nutraceutical contract manufacturers in Switzerland and Austria now require batch-certified polyphenol levels, creating pull-through demand for standardized tart cherry and elderberry extracts.
Market Restraints
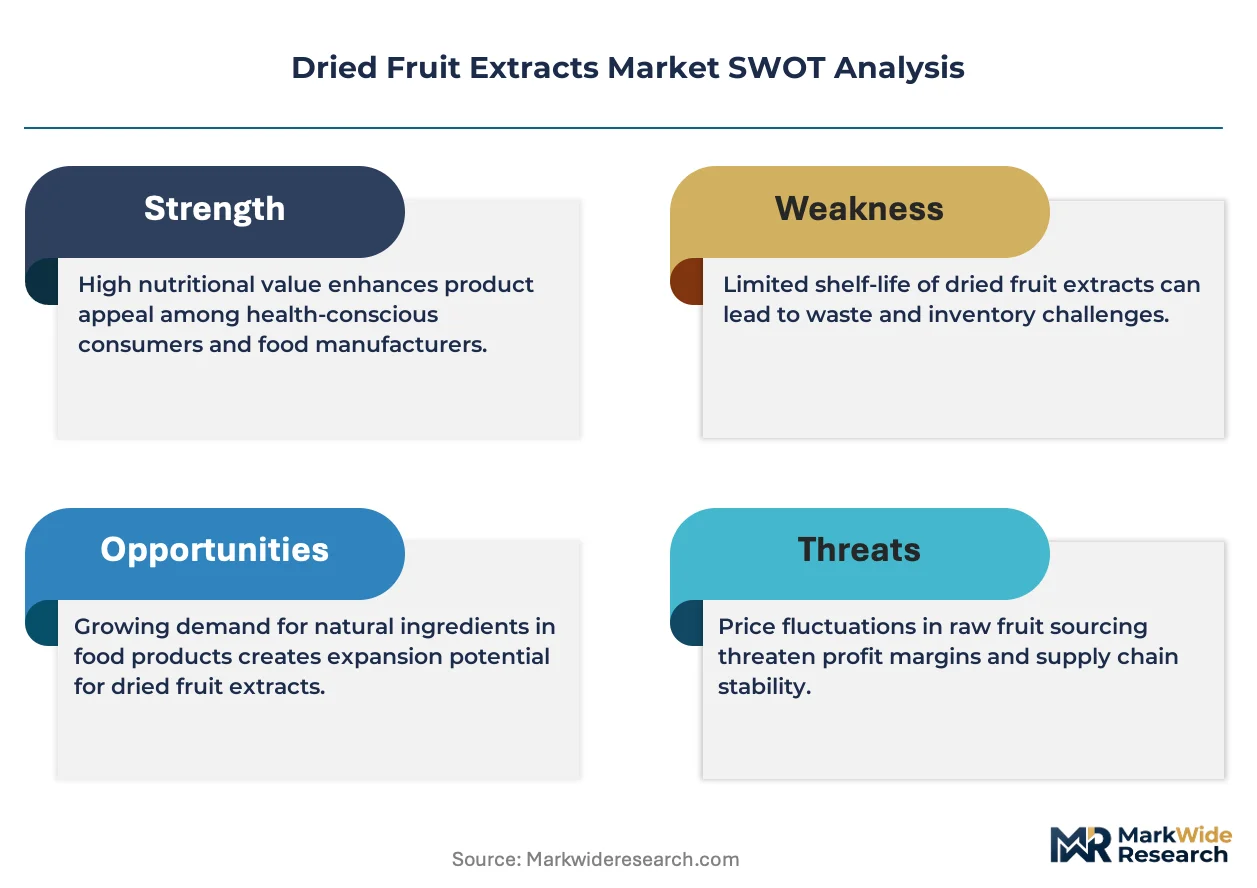
- Raw material cost volatility:Tart cherry and berry harvests in Poland and Ukraine face climate-induced yield fluctuations that compress processor margins during poor growing seasons.
- Supply concentration risk:Michigan-based tart cherry orchards control over 75% of North American raw supply, creating single-source vulnerability for extractors without diversified procurement.
- Substitution threat from fermentation-derived sweeteners:Precision-fermented stevia and allulose are capturing share in reduced-sugar beverage applications where cost-per-serving drives purchasing decisions.
Strategic Opportunities
- Underpenetrated organic certification:Spanish and Italian citrus peel extract segments remain below 15% organic penetration, creating white space for processors who validate integrated pest management supply chains ahead of EU pesticide threshold tightening.
- Cosmetic active ingredient pivot:Anthocyanin-rich berry extracts are displacing synthetic colorants in French and German dermocosmetic lines seeking provenance-linked antioxidant marketing claims.
- Heat-pump drying technology convergence:Integration of industrial heat pumps with pulsed electric field pre-treatment is enabling processors to market carbon-negative extraction credentials to CSRD-reporting food manufacturers.
Industry Challenges
- Specialized process engineering talent scarcity:Supercritical CO2 system operation and maintenance require rare combinations of chemical engineering and food safety expertise that command premium compensation in Basel and Munich labor markets.
- Organic certification timeline compression:Three-year conversion periods for orchard supply chains delay revenue recognition for processors pivoting to organic product lines under EU Green Deal procurement mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Fruit Extracts Market |
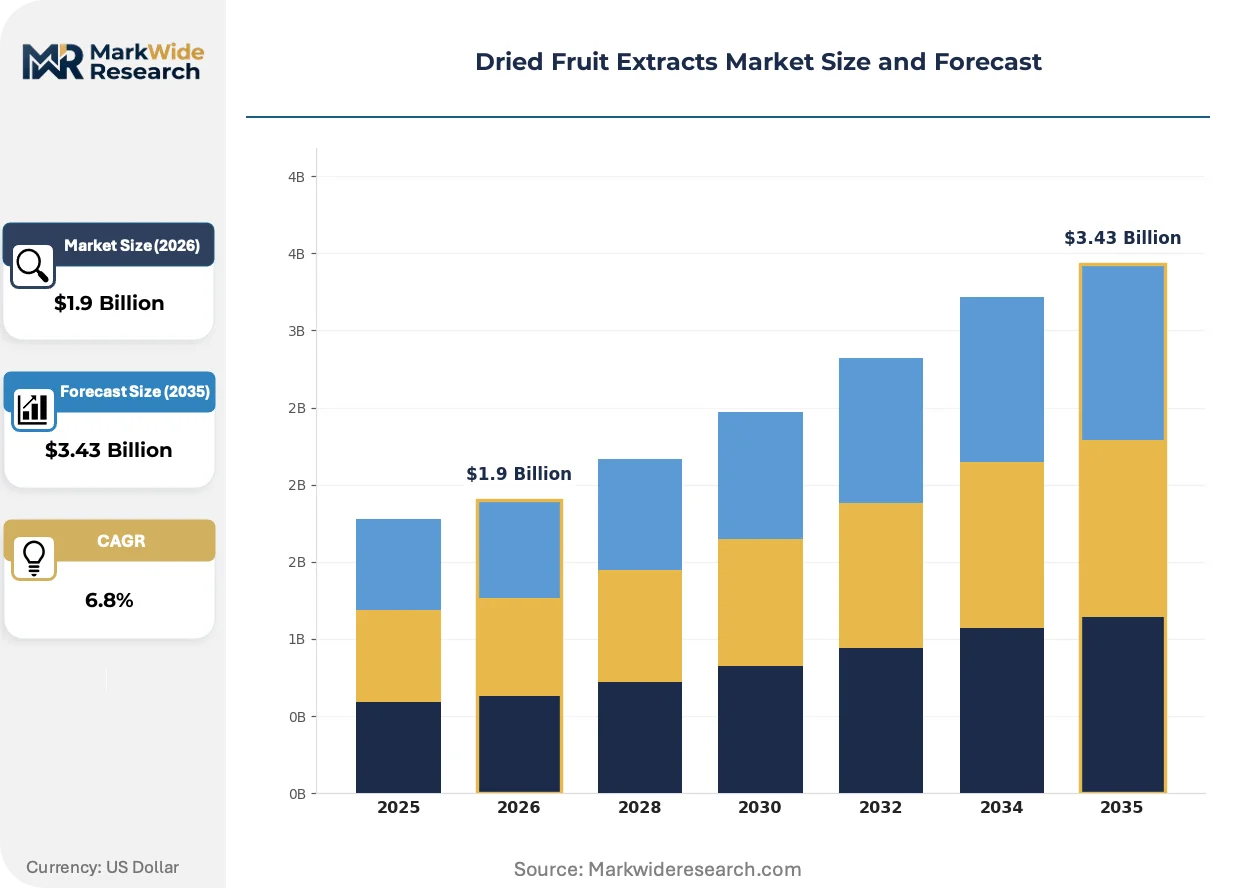
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $3.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apple Extract, Mango Extract, Berry Extract, Pineapple Extract Application: Food & Beverages, Nutraceuticals, Cosmetics, Pharmaceuticals End User: Food Manufacturers, Dietary Supplement Companies, Breweries, Cosmetic Brands Form: Powder, Liquid, Granule, Concentrate |
| Companies Covered | Monk Fruit Corp., Nikken International, Archer Daniels Midland Company, AGRANA Beteiligungs-AG, Chaucer Foods, Van Drunen Farms, Sweet Dried Fruit, Indus Farms, Graceland Fruit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Fruit Extracts Market Shifts & Advancements
Dehydration technology architectures and procurement specifications are fragmenting as energy costs, residue thresholds, and clean-label mandates force simultaneous upgrades across extraction, drying, and solvent recovery stages.
Industrial microwave-assisted drying is modularizing extraction facility design by enabling processors to scale dehydration capacity in 500-kilogram increments rather than committing to centralized freeze-drying investments. Beverage compounders in Bavaria and Baden-Württemberg are piloting these units for rapid berry extract production. The technology is modularizing capital deployment patterns, allowing mid-scale processors to match capacity additions to offtake agreements without stranded asset risk.
The EU F-Gas Regulation's phasedown schedule is accelerating refrigerant-dependent equipment obsolescence across European processing facilities. Processors face retrofit costs or replacement timelines that compress investment recovery periods. Heat-sensitive berry extract categories are most affected, driving adoption of alternative drying chemistries in Alsace and Piedmont production clusters.
Direct-procurement relationships between extract processors and organic orchard cooperatives are displacing traditional fruit broker intermediaries in supply chain configurations. German beverage manufacturers now require batch-level provenance documentation that brokers cannot provide. This pattern is most visible in Rhineland-Palatinate and Lower Saxony, where formulators source apple and elderberry extracts through cooperative partnerships rather than spot markets.
Dried Fruit Extracts Market Segmentation
Dried fruit extracts serve divergent functional requirements across end-use categories, from polyphenol standardization in nutraceuticals to rapid-dissolution demands in beverage manufacturing. Segmentation clarity enables processors to align extraction protocols, drying architectures, and certification investments with specific customer specifications.
Product Type:
Standalone extract categories command dedicated processing lines and provenance marketing, while blended formulations embed multiple fruit sources for compound functional claims.
- Berry Extract:Concentrated anthocyanin matrices standardized to specific polyphenol thresholds. German and French cosmetic brands drive premium procurement for provenance-linked antioxidant positioning in dermocosmetic lines. REACH-compliant supercritical CO2 extraction is displacing solvent-based methods for this segment.
- Apple Extract:Pectin-rich and polyphenol-standardized preparations derived from European cider and dessert cultivars. Swiss and Austrian nutraceutical contract manufacturers specify batch-certified chlorogenic acid levels for dietary supplement applications.
- Mango Extract:Carotenoid-concentrated preparations from Indian and Mexican processing clusters.
- Pineapple Extract:Bromelain-standardized enzyme preparations for digestive health formulations.
Berry extract leads volumes today; apple extract is gaining share fastest in standardized nutraceutical supply chains.
Application:
Cost tier stratification separates commodity flavoring applications from premium active ingredient positioning where certification and standardization command price multiples.
- Food & Beverages:Clean-label sweetener and natural flavoring deployments in reduced-sugar product lines. Bavarian and Baden-Württemberg beverage compounders pilot microwave-assisted drying for rapid berry extract production meeting EU Green Deal sugar reduction targets.
- Nutraceuticals:Polyphenol-standardized tart cherry and elderberry extracts for sleep and immune positioning. Swiss contract manufacturers now require batch-level provenance documentation that spot-market brokers cannot provide.
- Cosmetics:Anthocyanin colorants and antioxidant actives for French and German dermocosmetic brands.
- Pharmaceuticals:Extract preparations meeting pharmacopeial monograph specifications for active pharmaceutical ingredient applications.
Food and beverages dominates current offtake; nutraceuticals demonstrates steepest expansion trajectory as standardization protocols tighten.
End User:
Customer type determines procurement modality, with direct cooperative partnerships displacing spot-market intermediaries where provenance documentation is mandatory.
- Food Manufacturers:Large-scale dry-blend operations requiring powder-form extracts with superior shelf stability. German formulators in Rhineland-Palatinate and Lower Saxony source through direct cooperative partnerships rather than traditional fruit brokers.
- Dietary Supplement Companies:Batch-certified polyphenol and anthocyanin specifications for capsule and tablet manufacturing.
- Breweries:Flavor adjunct applications in craft and functional beverage production.
- Cosmetic Brands:Provenance-linked antioxidant marketing claims driving French and German dermocosmetic procurement.
Food manufacturers anchor procurement volumes today; dietary supplement companies are expanding most quickly as standardization requirements proliferate.
Form:
Supply concentration in powder processing reflects dry-blend manufacturing dominance, while liquid concentrate occupies specialized niches where dissolution speed determines operational efficiency.
- Powder:Shelf-stable preparations compatible with high-throughput dry-blend lines in food and nutraceutical facilities. Dominates commercial volumes due to logistics efficiency and handling compatibility.
- Liquid:Rapid-dissolution concentrates for beverage applications requiring precise dosing control.
- Granule:Intermediate flowability for tableting and encapsulation operations.
- Concentrate:High-brix preparations for dilution-dependent manufacturing processes.
Powder form leads volumes today; liquid concentrate is climbing the fastest in beverage reformulation applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavarian beverage compounders anchor European dried fruit extract demand through clean-label reformulation mandates. German processors pilot microwave-assisted drying systems for rapid berry extract production. Polish and Ukrainian tart cherry orchards face climate-induced yield fluctuations that compress margins.
United States
Michigan-based tart cherry orchards control over three-quarters of North American raw supply, creating single-source vulnerability for extractors lacking diversified procurement. EPA guidelines on agricultural pesticide residues constrain which fruit cultivars enter US-bound extract streams. Chicago-area nutraceutical contract manufacturers now require batch-level provenance documentation that traditional fruit brokers cannot provide.
Germany
Rhineland-Palatinate and Lower Saxony formulators source apple and elderberry extracts through direct cooperative partnerships rather than spot markets. The EU F-Gas Regulation forces processors to abandon conventional freeze-drying infrastructure in favor of heat-pump systems. Baden-Württemberg beverage compounders pilot modular microwave-assisted drying units for rapid berry extract production meeting EU Green Deal targets.
Switzerland
Swiss nutraceutical contract manufacturers specify batch-certified polyphenol and chlorogenic acid levels for dietary supplement applications. REACH compliance mandates full toxicological dossiers for novel extraction solvents. Basel-area processors face scarce supercritical CO2 system operation talent that commands premium compensation in tight labor markets.
France
French dermocosmetic brands drive premium procurement of anthocyanin-rich berry extracts for provenance-linked antioxidant marketing claims. The EU Green Deal's farm-to-fork pesticide reduction targets tighten allowable residue thresholds. Alsace production clusters accelerate adoption of alternative drying chemistries as refrigerant-dependent equipment faces obsolescence.
India
Mango extract processors in Maharashtra and Karnataka supply carotenoid-concentrated preparations to international nutraceutical formulators. FSSAI regulations govern food safety standards for extract exports. Indian processing clusters compete on cost efficiency while European buyers increasingly demand organic certification compliance.
Dried Fruit Extracts Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in organic certification and carbon-negative extraction credentials. Market structure fragments across three maturity tiers: multinational agricultural conglomerates with global sourcing networks, regional processors with captive orchard relationships, and specialized extract houses focused on standardization protocols. Two strategic archetypes dominate: backward-integrated orchard operators controlling cultivar selection through final extraction, and technology-forward processors marketing heat-pump and supercritical CO2 capabilities. Competitive intensity centers on M&A activity targeting orchard assets and strategic partnerships with beverage formulators seeking clean-label supply security.
Among North American specialists, Graceland Fruit exemplifies backward-integrated orchard control through Michigan-based tart cherry operations. Archer Daniels Midland Company anchors the multinational agricultural conglomerate tier with global sourcing networks spanning temperate and tropical zones. AGRANA Beteiligungs-AG represents European cooperative-focused procurement concentration, reducing transcontinental logistics exposure through deep relationships with apple and berry growers.
| Leading Market Players |
|---|
| Monk Fruit Corp. |
| Nikken International |
| Archer Daniels Midland Company |
| AGRANA Beteiligungs-AG |
| Chaucer Foods |
| Van Drunen Farms |
| Sweet Dried Fruit |
| Indus Farms |
| Graceland Fruit |
| Others |
Supply & Pricing Matrix
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by mandating heat-pump and microwave-assisted drying infrastructure upgrades that only capitalized processors can deploy. German beverage formulators now pay provenance premiums for batch-certified extracts from CSRD-compliant facilities while spot-market brokers lose pricing power.
Pricing Analysis
Input-cost pass-through from tart cherry and berry harvest volatility in Poland and Ukraine compresses processor margins during poor growing seasons. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant supercritical CO2 extracts from solvent-based preparations and unstandardized commodity grades. Price differentiation hinges on organic certification and batch-level polyphenol documentation. Food manufacturers exhibit highest price sensitivity due to volume scale, while Swiss nutraceutical contract manufacturers accept premium positioning for provenance-linked antioxidant claims.
Supply Chain Analysis
Warehouse-distribution layer consolidation centers on Rhineland-Palatinate and Lower Saxony regional hubs serving German beverage compounders with direct cooperative partnerships. Raw material supply draws from Michigan tart cherry orchards, Polish and Ukrainian berry cooperatives, and Maharashtra mango processing clusters. Single-source vulnerability in North American tart cherry supply creates structural risk for extractors lacking diversified procurement. Distribution runs through direct-procurement relationships displacing traditional fruit broker intermediaries where batch-level provenance documentation is mandatory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in heat-pump drying technology convergence and organic certification pivots that command premium-tier pricing from CSRD-reporting food manufacturers.
For Market Incumbents: Deploy heat-pump drying infrastructure to capture carbon-negative extraction credentials from German and French beverage formulators facing EU Green Deal procurement mandates. Secure captive orchard supply through cooperative partnerships in Rhineland-Palatinate and Lower Saxony to defend against precision-fermented sweetener substitution threats. Accelerate REACH-compliant supercritical CO2 capacity to maintain premium positioning in anthocyanin-rich berry extract segments. For New Entrants and Emerging Players: Direct-to-beverage-compounder digital platforms bypass traditional fruit broker intermediaries in Spanish and Italian citrus peel extract segments where organic penetration remains below fifteen percent. Target underpenetrated organic certification in Mediterranean orchard cooperatives ahead of EU pesticide threshold tightening. Lead with batch-level provenance documentation capabilities that spot-market brokers cannot provide. For Investors and Strategic Acquirers: Roll-up economics work for backward-integrated orchard operators because Michigan-based tart cherry supply concentration creates scarcity value for diversified processors. Long-term viability favors processors with validated integrated pest management supply chains and heat-pump drying technology portfolios. Watch for EU F-Gas Regulation compliance timelines as inflection indicator for stranded freeze-drying asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Drying Technology Deployment | Enables carbon-negative extraction credentials for CSRD-reporting German food manufacturers. |
| Organic Certification Pivot | Captures white space in Spanish and Italian citrus peel segments ahead of EU pesticide tightening. |
| Direct Cooperative Partnerships | Displaces fruit broker intermediaries in Rhineland-Palatinate and Lower Saxony supply configurations. |
| Supercritical CO2 Capacity Expansion | Secures REACH-compliant anthocyanin recovery for French and German dermocosmetic brands. |
| Backward Orchard Integration | Controls cultivar selection through final extraction in Michigan tart cherry supply-constrained environment. |
Research Methodology
Direct dialogue with extraction facility plant managers, procurement leads at German beverage compounders, organic orchard cooperative directors, and Swiss nutraceutical contract manufacturers grounded qualitative findings. Secondary validation drew from EFSA residue monitoring reports, EU F-Gas Regulation implementation timelines, customs trade data on fruit concentrate flows, and SEC filings from publicly traded agricultural processors. Bottom-up capacity modeling and top-down demand segmentation triangulated volume and value estimates.
Bottom-up analysis modeled installed dehydration capacity across Alsace, Piedmont, and Baden-Württemberg production clusters against utilization rates and yield assumptions. Segmentation dimensions included product type, application tier, end-user procurement modality, and form factor compatibility. CAGRs were derived from trend extrapolation of clean-label reformulation mandates and energy transition investment cycles. Forecast inputs incorporated EU Green Deal farm-to-fork target trajectories and REACH solvent approval timelines.
Climate-induced yield fluctuations in Polish and Ukrainian orchards, regulatory acceleration of EU pesticide threshold reductions, and substitution velocity of precision-fermented sweeteners are the dominant revision risks. Forecasts reflect documented assumptions on technology adoption curves and cooperative partnership formation rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Digital Mortgage Software Market
Others
China Automotive LED Lighting Market
Others
Europe Indoor LBS Market
Others
Level Measuring Instrument Market
Others
Bitcoin Mining Servers Market
Others
Smart Home Controller Market
Others
Receiving Scales Market
Others
Asia-Pacific Telecom Transformers Market
Others
Channel-In-A-Box (Ciab) Market
Others
Global Digital Caliper Market
Others
Heavy Duty Traps Market
Others
UK Cat Food Market
Others
Convenience Stores Market
Others
Security Envelopes Market
Others
Global Thermally Conductive Grease Market
Others
Germany 3D Printing Construction Market