
 Automotive Smart Lighting Market | 2026-2036
Automotive Smart Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Smart Lighting Market Outlook
The EU Green Deal is recalibrating supplier priorities across the Automotive Smart Lighting ecosystem, pushing energy-efficiency thresholds into contract specifications. Koito Manufacturing Co., Ltd. leverages its manufacturing scale to anchor supply agreements with Japanese OEMs seeking compliant exterior architectures. Hella GmbH & Co. KGaA differentiates through deep specialization in adaptive matrix systems for European premium brands. Marelli Holdings Co., Ltd. extends its vertical reach into software-controlled beam shaping, competing on integration depth rather than component cost alone.
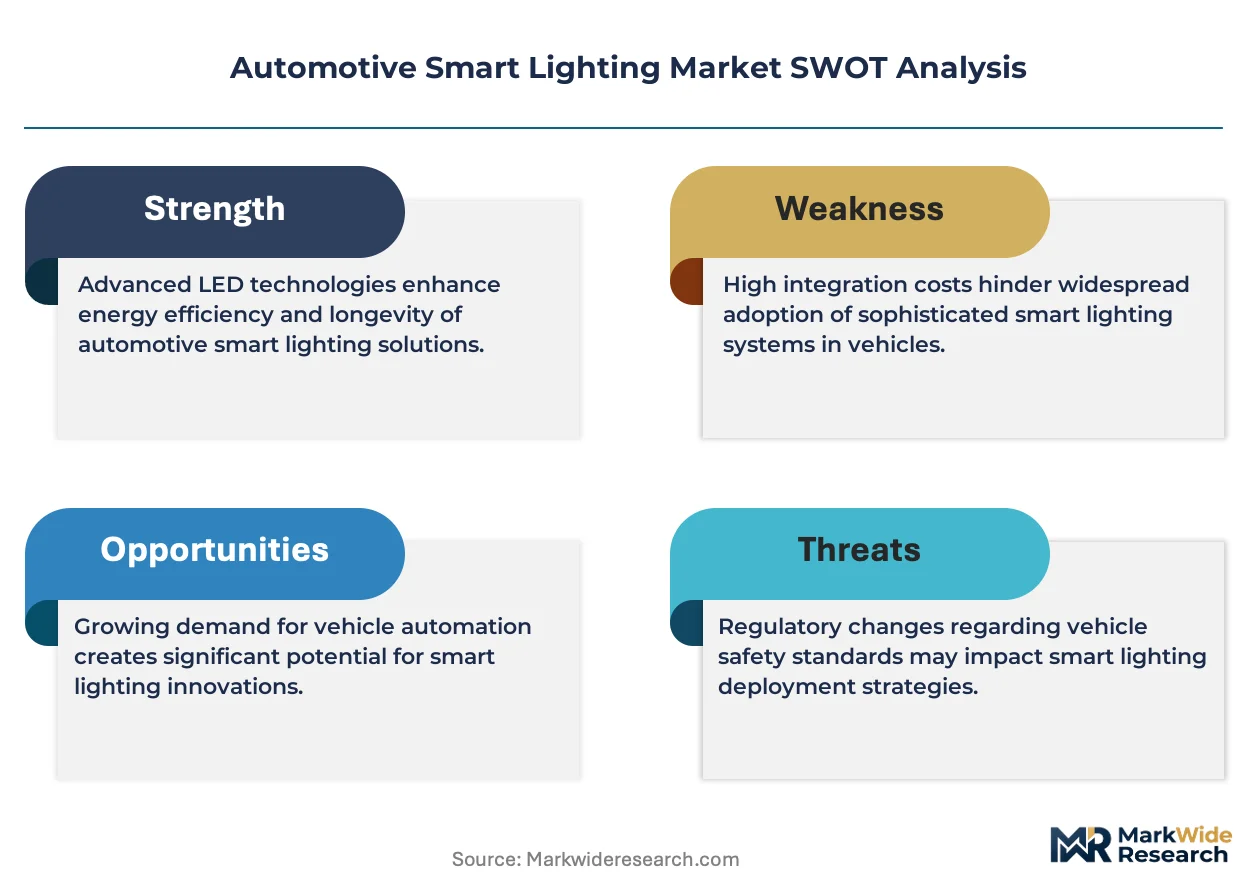
Automotive smart lighting encompasses electronically controlled illumination systems that modulate intensity, direction, and spectral output through sensor feedback and embedded algorithms, typically operating across color temperatures from 3000K to 6000K depending on road conditions and driver assistance integration. These systems serve dual commercial purposes: enhancing pedestrian and occupant safety through adaptive beam distribution while enabling brand-specific exterior styling signatures that influence purchase decisions. LED product types dominate installed value owing to thermal efficiency and lumen-per-watt performance, though OLED segments capture expanding share in interior ambient applications where surface-area illumination and design flexibility command premium positioning. Matrix LED technology leads growth velocity among technology segments, as its pixel-level beam control satisfies both ECE R48 compliance and consumer-facing safety ratings.
The European Commission's F-Gas Regulation and REACH chemical frameworks constrain material selection for sealing and thermal management components, while NHTSA Federal Motor Vehicle Safety Standard 108 shapes beam pattern requirements for US market access. ECE regulations administered under the United Nations Economic Commission for Europe harmonize type-approval procedures across Germany, France, and Italy, reducing retesting burdens for suppliers serving multiple national OEMs. China's GB standards for automotive lighting, enforced through MIIT certification, impose distinct photometric testing protocols that fragment compliance pathways for non-domestic suppliers. Stakeholders must monitor divergence between EU and Chinese regulatory timelines, as asynchronous implementation of adaptive driving beam permissions will reshape competitive access in the two largest volume markets.
Market Dynamics
Matrix LED beam-shaping systems are compressing supplier margins while fragmenting procurement authority between OEM chassis engineers and software integration teams. The technology's pixel-level control requirements force component vendors to absorb software development costs previously borne by tier-one integrators.
Growth Catalysts
- EU Green Deal energy-efficiency mandates:The framework's vehicle component thresholds are accelerating LED substitution for halogen architectures across German and French OEM lineups.
- Pedestrian safety ratings:Euro NCAP and IIHS scoring systems now weight adaptive beam performance heavily, forcing procurement priority upgrades in premium and mass-market segments alike.
- 3000K-6000K spectral modulation:Sensor-integrated color temperature adjustment enables compliance with varying national glare regulations while supporting driver assistance system integration.
Market Restraints
- Sealing material constraints:REACH chemical frameworks and the EU F-Gas Regulation limit fluoropolymer and silicone compound selection, narrowing thermal management options for high-lumen LED packages.
- MIIT certification fragmentation:China's GB standards impose photometric testing protocols distinct from ECE harmonization, forcing redundant engineering cycles for non-domestic suppliers.
- OLED thermal limitations:Surface-area illumination applications face heat dissipation ceilings that constrain lumen output in exterior ambient lighting roles.
Strategic Opportunities
- Interior OLED ambient expansion:Surface-area illumination commands premium positioning in cabin architecture as German and Japanese OEMs differentiate through customizable lighting signatures.
- ECE R48 adaptive driving beam permissions:Harmonized type-approval procedures across Germany, France, and Italy reduce retesting burdens for suppliers serving multiple national OEMs.
- Software-controlled beam shaping:Convergence of embedded algorithms with sensor feedback creates service revenue streams beyond hardware replacement cycles.
Industry Challenges
- Embedded software talent scarcity:Beam algorithm development requires optical engineering and machine learning competency combinations that outpace current automotive electronics hiring pipelines.
- Legacy halogen platform integration:Electrified vehicle architectures demand complete lighting system redesigns, straining supplier engineering bandwidth during model cycle transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Smart Lighting Market |
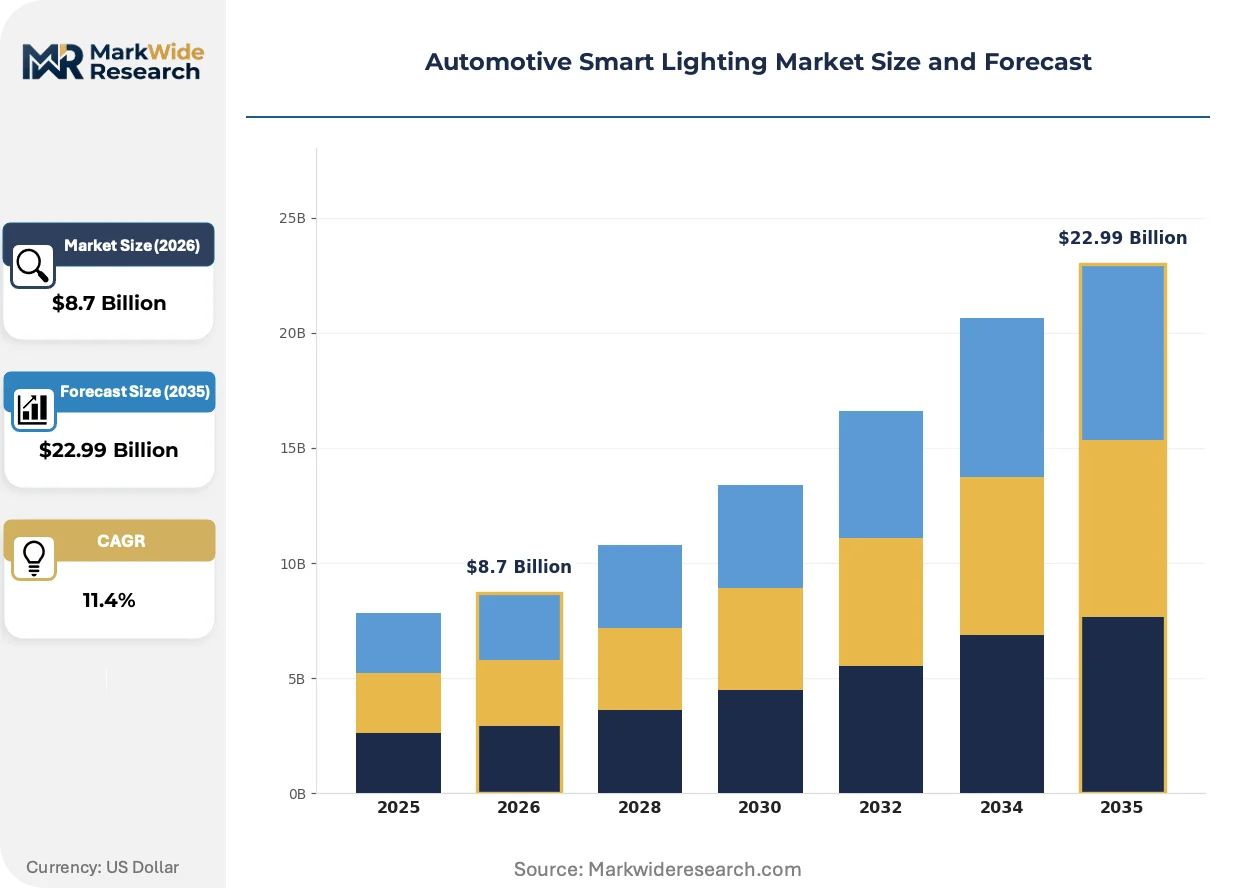
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Xenon, Halogen, OLED Technology: Adaptive Lighting, Matrix LED, Bi-LED, Laser Lighting Application: Interior Lighting, Exterior Lighting, Signal Lighting, Ambient Lighting End User: OEMs, Aftermarket Suppliers, Tier-1 Suppliers, Dealerships |
| Companies Covered | Marelli Holdings Co., Ltd., ZKW Group GmbH, Koito Manufacturing Co., Ltd., ams OSRAM AG, Varroc Engineering Limited, Hella GmbH & Co. KGaA, Stanley Electric Co., Ltd., Ficosa International, S.A.U., Valeo S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Smart Lighting Market Strategic Shifts
Active modulation of spectral output through sensor feedback is redrawing competitive boundaries between optical component suppliers and software integrators. Three developments are compressing traditional procurement hierarchies.
Micro-LED pixel arrays are absorbing the beam-shaping functions previously executed by mechanical shutters and physical masking layers. German premium OEMs are specifying these architectures for 2026 model year launches, forcing tier-one suppliers to internalize semiconductor packaging capabilities or cede margin to dedicated LED foundries. The technology is absorbing discrete component value into integrated optical engines.
NHTSA Federal Motor Vehicle Safety Standard 108 is diverging from ECE R48 beam pattern requirements on glare limitation thresholds. The regulatory friction forces suppliers serving both markets to maintain parallel optical designs rather than unified global platforms. US-market adaptive headlamp systems face longer homologation timelines, compressing first-mover advantages for technology introductions.
Fleet procurement departments are consolidating lighting specification authority previously dispersed across brand-level design studios. German commercial vehicle operators now mandate standardized beam performance metrics across manufacturer lineups, displacing styling-driven purchasing decisions. This concentration is most visible in long-haul trucking segments where total cost of ownership calculations dominate specification sheets.
Automotive Smart Lighting Market Segmentation
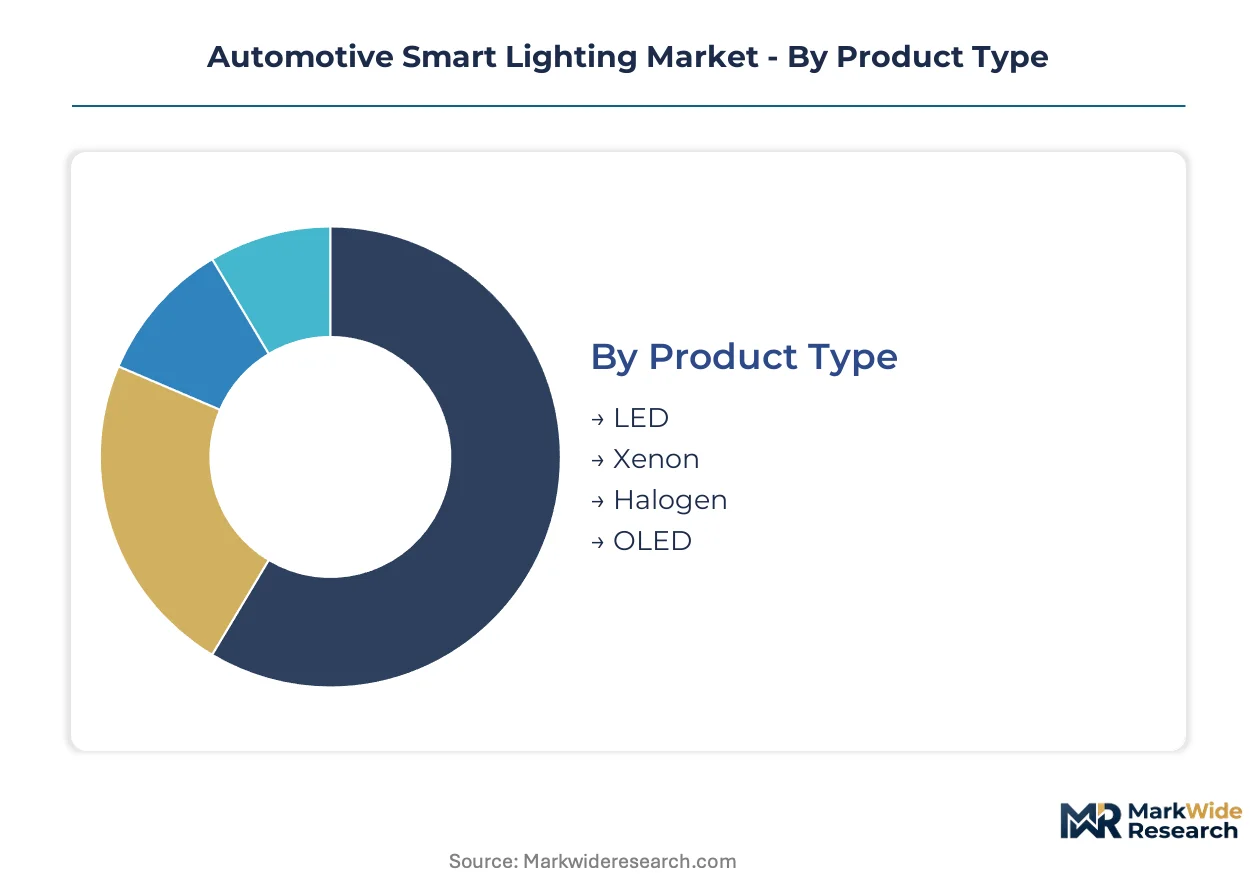
Automotive smart lighting segmentation reveals how procurement authority fragments across hardware, software, and integration layers. Technology choices determine supplier margin structures while application focus shapes regulatory compliance pathways.
Product Type:
Buyers differentiate by thermal efficiency thresholds and lumen-per-watt performance requirements rather than upfront component cost alone.
- LED:Dominates installed value through thermal efficiency and spectral stability across 3000K-6000K operating ranges. German and Japanese OEM procurement concentrates here as EU Green Deal energy-efficiency mandates accelerate halogen substitution.
- OLED:Surface-area illumination enables cabin architecture differentiation through customizable lighting signatures. Demand clusters in German premium segments where interior ambient applications command positioning premiums despite thermal dissipation constraints.
- Xenon:High-intensity discharge technology retains niche presence in retrofit markets and legacy platform support.
- Halogen:Conventional tungsten-halogen architectures face accelerated displacement under EU vehicle component efficiency thresholds.
Volume sits with LED; growth tilts toward OLED.
Technology:
Procurement teams now weight software integration depth equally with optical hardware specifications when selecting beam-shaping architectures.
- Matrix LED:Pixel-level beam control satisfies ECE R48 compliance while enabling consumer-facing safety ratings. Euro NCAP scoring systems weight adaptive beam performance heavily, forcing procurement priority upgrades across premium and mass-market segments.
- Adaptive Lighting:Sensor-feedback modulation of intensity and direction supports driver assistance system integration. German premium OEMs specify these architectures for exterior applications where pedestrian safety ratings influence purchase decisions.
- Bi-LED:Dual-function designs combine low and high beam capabilities within single optical modules for cost-optimized platforms.
- Laser Lighting:High-lumen density sources extend visible range in premium long-range headlamp applications.
Matrix LED captures the steepest expansion trajectory as beam algorithm development shifts cost structures toward software engineering.
Application:
Margin concentration follows where design differentiation authority resides—exterior styling studios versus interior cabin architects.
- Exterior Lighting:Headlamp and taillamp assemblies face ECE R48 and NHTSA Federal Motor Vehicle Safety Standard 108 compliance requirements. US-market systems face longer homologation timelines due to diverging glare limitation thresholds.
- Ambient Lighting:Surface-area illumination commands premium positioning as OEMs differentiate through customizable cabin signatures. German and Japanese manufacturers lead specification authority here.
- Interior Lighting:Instrument panel and functional illumination serves dual safety and ergonomic purposes across vehicle classes.
- Signal Lighting:Turn indicators and brake lamps face distinct photometric testing protocols under China's GB standards versus ECE harmonization.
Exterior applications anchor revenue scale; ambient lighting expands most quickly in average revenue per vehicle.
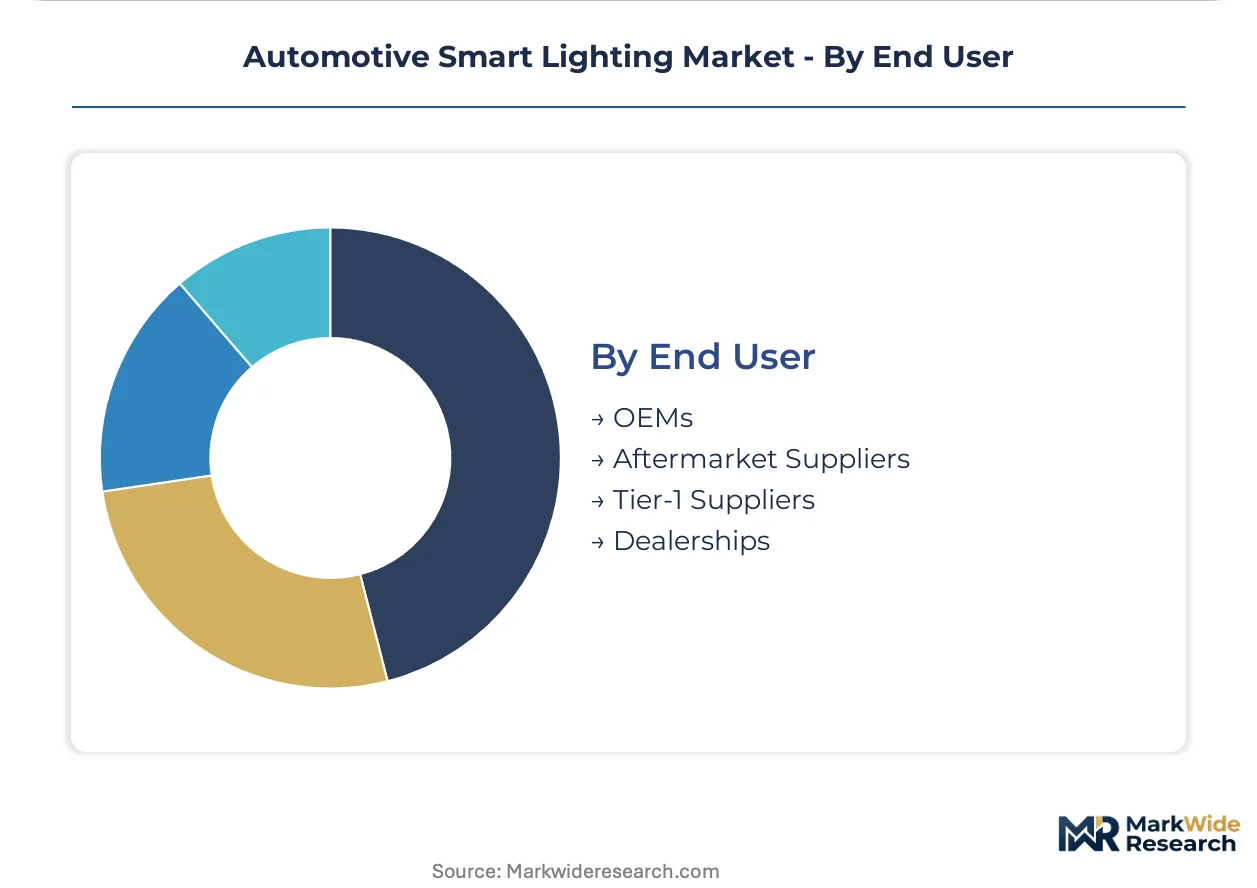
End User:
Specification authority concentrates where total cost of ownership calculations override styling-driven purchasing decisions.
- OEMs:German and Japanese manufacturers anchor demand as safety ratings and design differentiation command procurement priority. Fleet procurement departments increasingly consolidate lighting specification authority across brand lineups.
- Tier-1 Suppliers:Integration teams absorb software development costs previously borne by component vendors as matrix LED pixel control requirements reshape procurement hierarchies.
- Aftermarket Suppliers:Retrofit and replacement demand concentrates where legacy platform support extends product lifecycles.
- Dealerships:Accessory and upgrade sales channels serve consumer-facing customization demand in premium segments.
OEM procurement dominates volume; tier-1 supplier influence is climbing the fastest as embedded software requirements deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors smart lighting engineering density, housing development centers for German premium OEMs specifying matrix LED architectures for 2026 model year launches.
United States
NHTSA Federal Motor Vehicle Safety Standard 108 governs beam pattern requirements, creating compliance friction with ECE R48 standards. Michigan-based OEM engineering centers specify adaptive headlamp systems where pedestrian safety ratings influence procurement decisions. Longer homologation timelines compress first-mover advantages for technology introductions.
Germany
ECE R48 harmonized type-approval procedures reduce retesting burdens for suppliers serving multiple national OEMs. The EU Green Deal's vehicle component efficiency thresholds accelerate LED substitution across German manufacturer lineups. Bavaria concentrates supplier R&D facilities for matrix LED pixel control development.
Japan
METI oversees industrial standards coordination while JIS specifications shape domestic procurement protocols. Koito Manufacturing Co., Ltd. leverages manufacturing scale to anchor supply agreements with Japanese OEMs seeking compliant exterior architectures. Aichi Prefecture hosts concentrated production capacity for sensor-integrated lighting systems.
China
MIIT certification enforces GB standards with photometric testing protocols distinct from ECE harmonization. Redundant engineering cycles strain non-domestic suppliers serving both regulatory environments. Shanghai and Guangdong Province concentrate domestic lighting system integration capacity for local OEMs.
South Korea
MFDS coordinates with automotive regulators on component safety frameworks while domestic OEMs expand specification authority. Seoul Capital Area engineering centers drive LED package procurement for electrified vehicle platforms. Gyeonggi Province suppliers absorb software development costs for adaptive beam algorithms.
Automotive Smart Lighting Market Competitive Environment
Premium-margin players sit above commodity-margin players across software integration depth and thermal management specialization. The supplier base fragments between optical component vendors absorbing embedded algorithm costs and tier-one integrators consolidating specification authority. Three archetypes dominate: semiconductor packaging specialists, adaptive beam software developers, and full-system integrators. M&A activity concentrates on software competency acquisition while capacity expansion targets LED foundry partnerships.
Among Japanese and German fabricators, Koito Manufacturing Co., Ltd., Hella GmbH & Co. KGaA, and Marelli Holdings Co., Ltd. exemplify divergent strategic positioning. Koito occupies a scale-driven position anchoring supply relationships with domestic OEM procurement teams. Hella represents specialization in European premium brand adaptive systems. Marelli sits within the integration-depth tier, competing on software-controlled beam architecture rather than component cost alone.
| Leading Market Players |
|---|
| Marelli Holdings Co., Ltd. |
| ZKW Group GmbH |
| Koito Manufacturing Co., Ltd. |
| ams OSRAM AG |
| Varroc Engineering Limited |
| Hella GmbH & Co. KGaA |
| Stanley Electric Co., Ltd. |
| Ficosa International, S.A.U. |
| Valeo S.A. |
| Others |
Value Chain & Pricing Dynamics
OEM fleet procurement consolidation across German long-haul trucking operators is forcing component vendors to absorb software development costs previously borne by tier-one integrators, compressing margins and reshaping supplier tier relationships. This demand-side authority shift feeds directly into how pricing power distributes between optical hardware specialists and full-system integrators.
Pricing Analysis
Beam performance outcomes anchor value-based pricing for matrix LED architectures, with German and Japanese OEMs paying premiums for pixel-level control satisfying ECE R48 compliance and Euro NCAP scoring weightings. Price differentiation rests on software integration depth and thermal management certification tiers rather than lumen output alone. Cost compression in commodity LED packages is intensifying because semiconductor foundries are absorbing packaging capabilities previously held by tier-one suppliers. Fleet procurement departments show highest price sensitivity, while premium brand design studios remain least sensitive to unit cost when styling differentiation is at stake.
Supply Chain Analysis
Freight cost volatility for semiconductor substrates and rare-earth phosphors is amplifying margin pressure on LED package vendors serving dual regulatory environments. Supply concentration centers on Germany for matrix LED engineering, Japan for sensor-integrated module assembly, and China for domestic OEM integration capacity. The chain draws from gallium nitride wafers, silicone thermal compounds, and precision optical polymers as critical inputs. Single-source vulnerability in semiconductor packaging equipment creates structural exposure. Distribution runs through tier-one integrators consolidating specification authority, with direct OEM relationships climbing for software-intensive architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive smart lighting sector is becoming a vertical-integration race as beam algorithm development shifts cost structures toward software engineering and semiconductor packaging capabilities. Players are pursuing upstream control over LED foundry partnerships and downstream capture of OEM software integration roles to defend margin positions.
For Market Incumbents: Lock in exclusive supply agreements with Japanese and German OEM procurement teams before fleet standardization mandates consolidate specification authority further. Prioritize in-house production of micro-LED pixel arrays to prevent margin capture by dedicated semiconductor foundries. Acquire embedded software talent with optical engineering and machine learning competency combinations to address hiring pipeline gaps threatening algorithm development timelines.
For New Entrants and Emerging Players: Begin with interior OLED ambient lighting applications where surface-area illumination commands premium positioning and design differentiation authority resides with cabin architects rather than consolidated fleet procurement. Target German premium segments where customizable lighting signatures drive specification decisions independent of total cost of ownership calculations. Pursue partnership-based go-to-market models with tier-one integrators seeking software-controlled beam shaping capabilities without internal development investment.
For Investors and Strategic Acquirers: Re-rating potential sits with adaptive beam software developers given ECE R48 adaptive driving beam permission harmonization reducing retesting burdens and accelerating market access. Long-term viability over the next decade favors specialists with demonstrated integration depth across sensor feedback algorithms and thermal management architectures. Watch for divergence between EU and Chinese regulatory timelines on adaptive driving beam permissions as the critical inflection signal reshaping competitive access in the two largest volume markets.
| Strategic Initiative | Industry Significance |
|---|---|
| LED Foundry Partnership | Captures semiconductor packaging margins previously ceded to dedicated foundries serving German OEMs. |
| Beam Algorithm Acquisition | Addresses embedded software talent scarcity threatening development timelines for ECE R48-compliant architectures. |
| Thermal Management Certification | Satisfies EU F-Gas Regulation and REACH constraints narrowing material selection for high-lumen packages. |
| MIIT Certification Investment | Reduces redundant engineering cycles for suppliers serving both ECE-harmonized and Chinese GB standard markets. |
| Fleet Procurement Direct Relationship | Displaces styling-driven purchasing decisions as German commercial vehicle operators mandate standardized beam metrics. |
Study Parameters
Multi-period observation of vehicle production databases, OEM platform engineering timelines, and regulatory filing trajectories anchored the trend analysis, supplemented by interviews with tier-one supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations specialists. Secondary validation drew from IHS Markit registration data, ECE R48 type-approval records, NHTSA Federal Motor Vehicle Safety Standard 108 compliance filings, and MIIT certification databases. Bottom-up segment sizing triangulated against top-down market value estimates derived from content-per-vehicle analysis across propulsion architectures and OEM tiers.
Input-output matrices modeled relationships between LED and OLED product type penetration, matrix LED versus adaptive lighting technology adoption rates, exterior versus interior application splits, and OEM versus tier-one supplier end-user authority shifts across the projection horizon. Segmentation dimensions included vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs emerged from trend extrapolation of technology substitution curves and regulatory mandate implementation schedules, with EU Green Deal energy-efficiency thresholds and Euro NCAP scoring weightings serving as primary forecast drivers.
Underlying measurement precision varies by segment; LED product type estimates carry tighter precision than OLED given established production reporting, while software-controlled beam shaping revenue projections reflect greater assumption sensitivity. Forecasts reflect documented assumptions regarding regulatory timeline synchronization and technology cost reduction curves. Stakeholders should weight assumptions against their own operating context, particularly regarding divergence between EU and Chinese adaptive driving beam permission implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Japan Indoor LBS Market
Others
Fabric Based Computing Market
Others
Middle East and Africa Surface Analysis Market
Others
Process Instrumentation Equipment Market
Others
Gas Holders Market
Others
Ultra Mobile Devices (UMD) Market
Others
United States Indoor LBS Market
Others
Port Replicator Market
Others
China Online Gambling Market
Others
Nanomedicine for Drug Delivery Market
Others
Global Laser Defense Eyewear Market
Others
North America Healthcare Flexible Packaging Market
Others
Refractometer Market
Others
Shear Testing Equipment Market
Others
UK Automotive LED Lighting Market
Others
AC Switchgear Market