
 Latin America Fire Sprinklers Market | 2026-2036
Latin America Fire Sprinklers Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Fire Sprinklers Market Intelligence
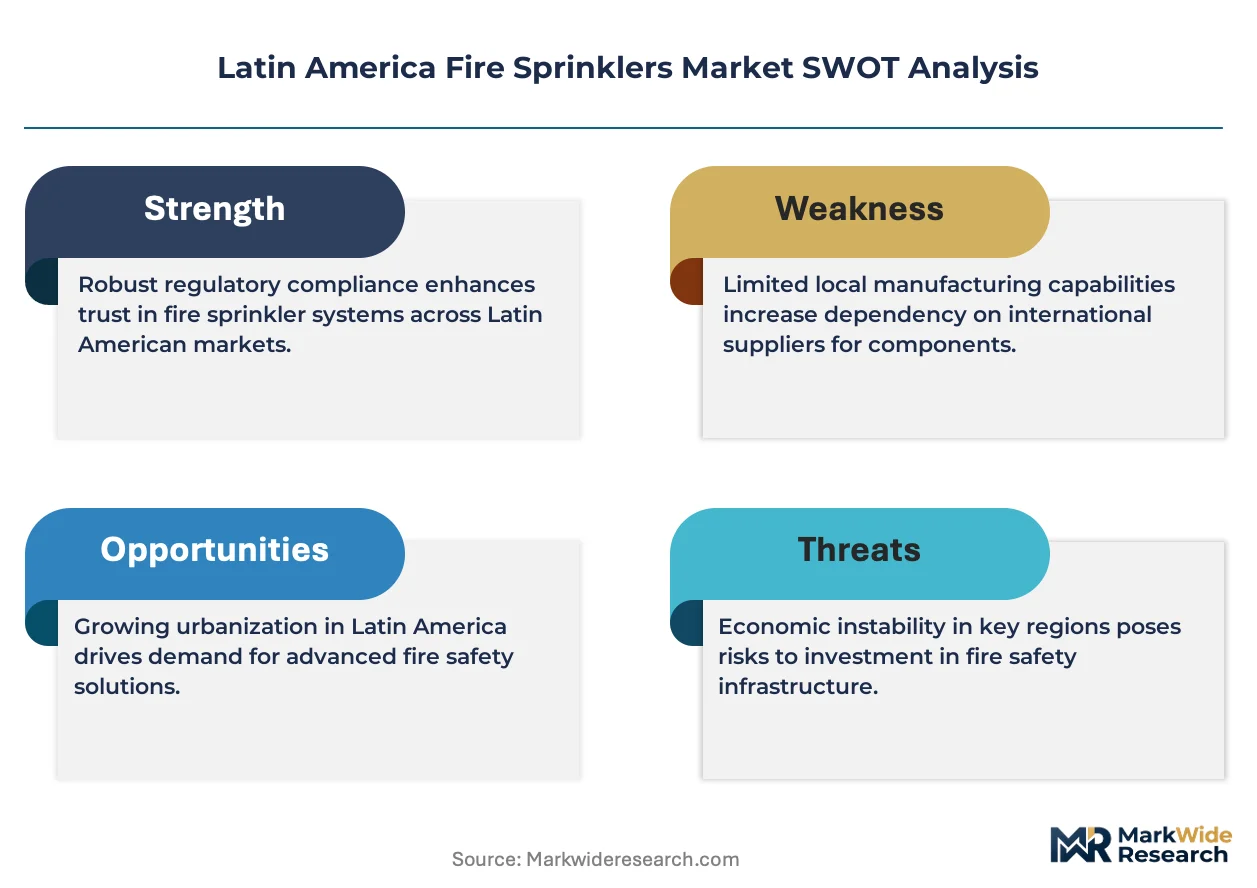
NFPA 13 certification is collapsing the supplier base as smaller fabricators struggle to meet testing and listing requirements for sprinkler heads and piping assemblies. Johnson Controls leverages its manufacturing footprint across Mexico and Brazil to sustain project delivery timelines for large commercial contracts. Viking Group anchors its regional position through specialized marine and high-hazard industrial sprinkler systems that navigate demanding specification environments.
Latin America fire sprinklers constitute automatic water-based suppression networks engineered to discharge at predetermined temperature thresholds, typically utilizing fusible alloy elements rated between 135°F and 286°F to protect structural and occupant assets. Wet pipe configurations dominate new installation activity given their mechanical simplicity and lower lifecycle cost profile across standard commercial buildings. Pre-action systems command premium positioning in data center and cultural heritage applications where accidental discharge carries catastrophic consequences, while retrofitting activity accelerates as aging infrastructure in São Paulo and Mexico City faces code-compliance deadlines.
Brazil's CBMT building codes and Mexico's NOM standards shape product certification requirements alongside NFPA harmonization efforts that govern cross-border project specifications. ANVISA in Brazil and local civil defense authorities across Argentina and Chile enforce installation compliance through inspection protocols that determine market access for foreign equipment suppliers. Stakeholders must monitor evolving municipal adoption of NFPA 13 versus local standards to calibrate product development and certification investments across fragmented national regulatory landscapes.
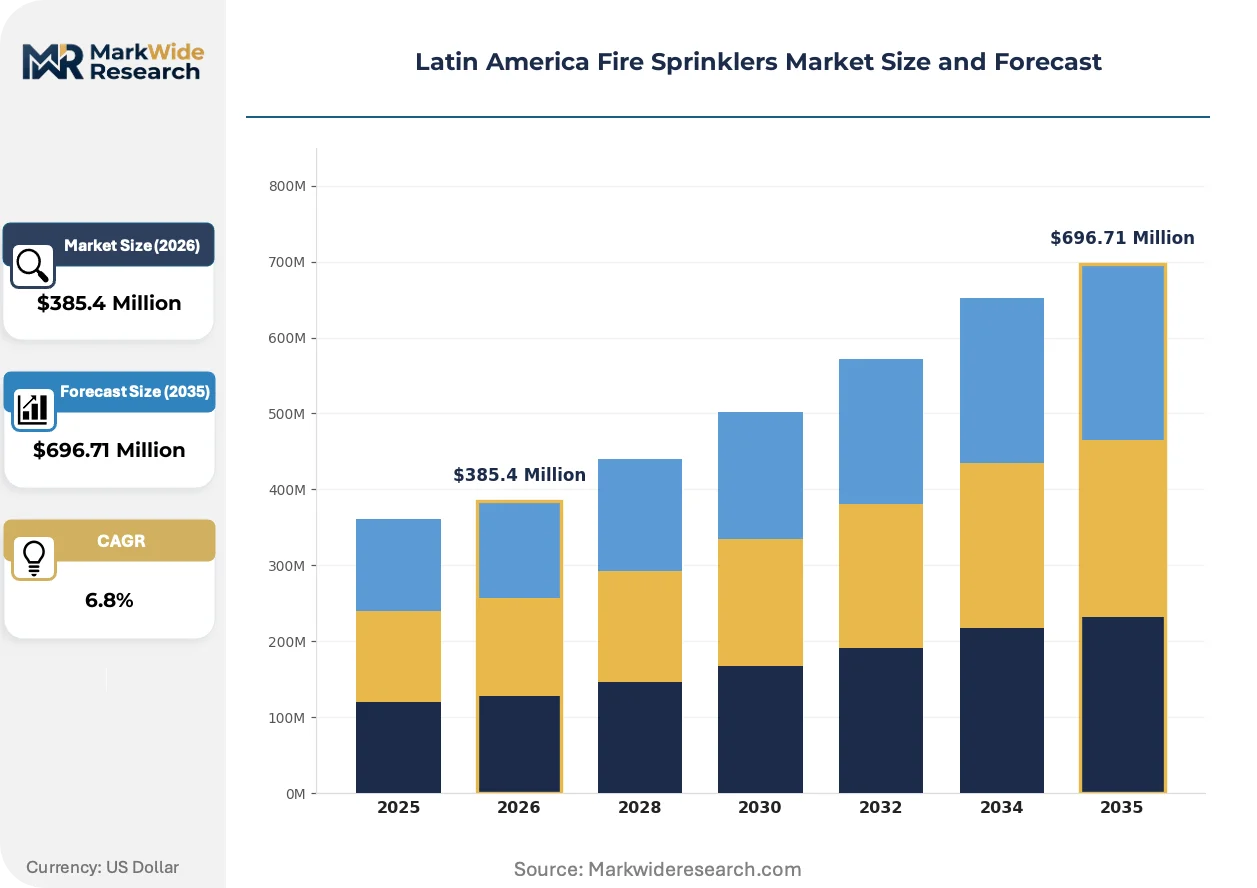
Market Dynamics
NFPA 13 certification requirements are collapsing the supplier base across Latin America, as smaller fabricators fail testing protocols and multinational manufacturers consolidate project pipelines through captive Mexican and Brazilian production footprints.
Growth Catalysts
- CBMT and NOM code harmonization:Brazil's updated building standards and Mexico's federal construction mandates now require active fire suppression in high-rise commercial structures, creating mandatory demand pull across São Paulo and Mexico City corridors.
- Wet pipe system standardization:Mechanical simplicity and lower lifecycle costs position wet pipe configurations as the default specification for new commercial construction, accelerating specification velocity among regional contractors.
- Argentina:Civil defense authorities in Buenos Aires and Córdoba are enforcing retroactive compliance deadlines on aging infrastructure, converting deferred maintenance into active replacement cycles.
Market Restraints
- Copper and steel input volatility:Sprinkler head alloys and piping assemblies face commodity price swings that compress fabricator margins and destabilize project bidding.
- Testing laboratory concentration:ANVISA-recognized certification bodies cluster in São Paulo and Mexico City, creating geographic bottlenecks for foreign equipment seeking market access.
- Pre-action system complexity:Electronic detection dependencies and pneumatic valve maintenance requirements limit adoption outside data center and museum applications where discharge sensitivity justifies premium engineering.
Strategic Opportunities
- Chilean mining infrastructure:High-hazard industrial sites in Antofagasta and Atacama remain underpenetrated by listed suppression systems, creating specification white space for marine-rated and corrosion-resistant assemblies.
- Pre-action convergence with IoT monitoring:Remote valve supervision and predictive maintenance algorithms are compressing insurance underwriting costs for cultural heritage and telecommunications facilities.
- Colombia:Bogotá's municipal adoption of NFPA 13-aligned standards opens first-mover positioning before federal harmonization spreads to Medellín and Cali construction markets.
Industry Challenges
- Certified hydraulic calculation specialists:Project engineering firms across Latin America face scarcity of technicians qualified to perform NFPA 13-compliant system design, extending bid-to-award timelines.
- Legacy galvanized steel integration:Retrofit contractors encounter compatibility failures when threading modern sprinkler heads into decades-old piping networks, forcing costly full-system replacements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Fire Sprinklers Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Pipe, Dry Pipe, Pre-Action, Deluge End User: Commercial Buildings, Residential Properties, Industrial Facilities, Educational Institutions Installation Type: New Installation, Retrofitting, Maintenance, Upgrades Distribution Channel: Direct Sales, Wholesale, Online Retail, Authorized Dealers |
| Companies Covered | Johnson Controls, Viking Group, Reliable Automatic Sprinkler, Tyco Fire Products, Honeywell International, Minimax, Victaulic, Siemens, Potter Electric Signal Company, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Fire Sprinklers Market Strategic Shifts & Innovations
Smart detection architectures and materials science advances are compressing system footprints while expanding application boundaries across Latin America's commercial and industrial verticals.
Fusible alloy elements rated between 135°F and 286°F are miniaturizing. Data center operators in Querétaro and São Paulo are specifying compact glass-bulb sprinklers with faster response times to protect rack-dense server environments. Johnson Controls and Viking Group are compressing head profiles to navigate cable tray congestion, enabling suppression coverage in previously inaccessible ceiling plenums.
ANVISA in Brazil is tightening medical-grade facility fire safety protocols, requiring listed suppression in pharmaceutical manufacturing and hospital expansion projects. The industrial consequence is a certification bottleneck as foreign suppliers queue for ANVISA-recognized laboratory testing. São Paulo's hospital construction pipeline is most affected, with project timelines extending to accommodate compliance documentation.
Buyers are unbundling installation from equipment procurement, forcing distributors to compete on specification support rather than bundled contractor margins. Engineering-procurement-construction firms in Mexico City and Monterrey are separating sprinkler head supply from hydraulic design services, compressing distributor markup capture. Brazil's commercial construction vertical exhibits this pattern most visibly, with CBMT-mandated third-party inspection requirements accelerating the shift toward transparent component sourcing.
Latin America Fire Sprinklers Market Segmentation
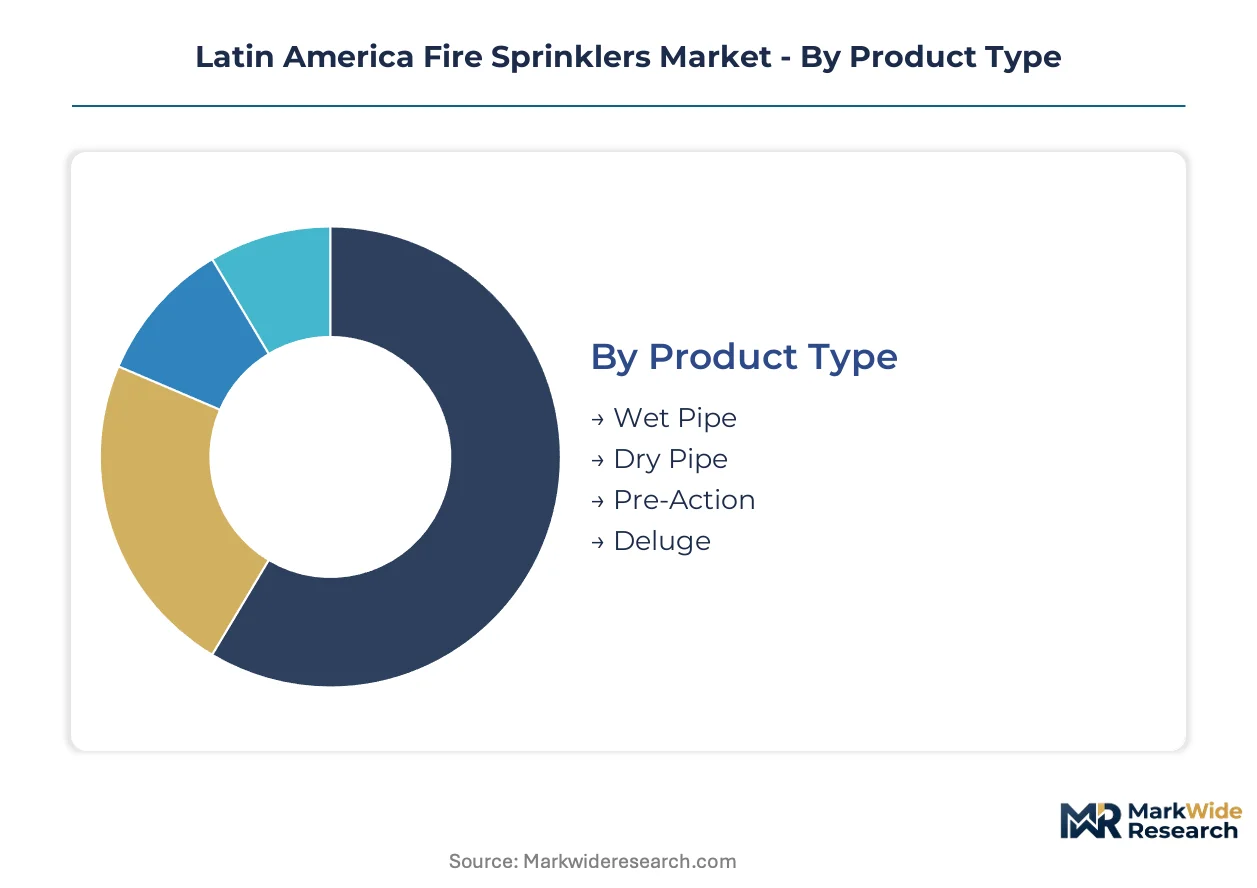
Segmentation across product type, end user, installation mode, and distribution channel reveals distinct margin architectures and competitive intensity zones. Wet pipe systems and commercial building contracts concentrate revenue pools, while retrofitting and direct sales channels command premium positioning through specification complexity.
Product Type:
Margin pools concentrate in pre-action and deluge systems where engineering complexity sustains pricing power, while wet pipe configurations dominate volume throughput.
- Wet Pipe:These systems maintain water-filled piping networks that discharge immediately upon sprinkler activation, utilizing fusible alloy elements rated between 135°F and 286°F. São Paulo and Mexico City commercial corridors drive specification velocity, with CBMT and NOM code harmonization mandating active suppression in high-rise structures. The dominant share belongs to Wet Pipe, while Pre-Action is closing the gap fastest.
- Pre-Action:Electronic-pneumatic hybrid architectures require dual-trigger confirmation before water release, eliminating accidental discharge risk. Data center operators in Querétaro and cultural heritage facilities in Buenos Aires specify these systems where discharge sensitivity justifies premium engineering and extended maintenance protocols.
- Dry Pipe:Pressurized air or nitrogen fills piping until activation, preventing freeze damage in unheated warehouses and logistics facilities across Argentina's Pampas region and Chilean mountain corridors.
- Deluge:Open-nozzle configurations flood entire zones simultaneously, protecting high-hazard industrial sites including petrochemical installations and mining processing plants in Antofagasta.
Wet pipe systems anchor volume deployment, though pre-action specifications are expanding most quickly in asset-sensitive verticals.
End User:
Application intensity varies sharply across building typologies, with commercial and industrial facilities presenting contrasting specification cycles and procurement authority structures.
- Commercial Buildings:High-rise office towers and retail complexes in Brazil and Mexico generate concentrated demand pull through updated national building codes. Wet pipe standardization accelerates contractor specification velocity, while third-party inspection requirements under CBMT and NOM standards separate equipment procurement from installation services.
- Industrial Facilities:Mining, manufacturing, and petrochemical sites require corrosion-resistant and marine-rated assemblies for demanding environments. Chilean mining infrastructure in Atacama remains underpenetrated by listed suppression systems, creating specification white space for specialized fabricators.
- Residential Properties:Mid-rise apartment construction in Bogotá and Medellín increasingly incorporates sprinkler protection as municipal standards align with NFPA 13 frameworks ahead of federal harmonization.
- Educational Institutions:University expansion projects and K-12 facility upgrades across Argentina face civil defense enforcement of retroactive compliance deadlines, converting deferred maintenance into active replacement cycles.
Commercial buildings retain the largest installed base, yet industrial facilities are gaining share fastest through high-hazard specification premiums.
Installation Type:
Customer lifecycle positioning determines margin capture, with new construction offering volume scale and retrofitting commanding technical premium through legacy system complexity.
- New Installation:Greenfield commercial and industrial projects in São Paulo and Mexico City corridors specify complete suppression networks during structural framing. Wet pipe standardization dominates these deployments given mechanical simplicity and lower lifecycle cost profiles.
- Retrofitting:Aging infrastructure in Buenos Aires, Córdoba, and São Paulo faces code-compliance deadlines that force full-system replacements when modern sprinkler heads fail compatibility with legacy galvanized steel piping networks.
- Maintenance:Annual inspection and component replacement cycles generate recurring revenue streams, particularly for facilities under ANVISA medical-grade protocols requiring listed suppression documentation.
- Upgrades:IoT-enabled valve supervision and predictive maintenance algorithms compress insurance underwriting costs for data center and telecommunications facilities seeking pre-action convergence with smart detection architectures.
New installation generates the highest absolute volume, though retrofitting exhibits the steepest expansion trajectory as municipal enforcement intensifies across aging urban cores.
Distribution Channel:
Channel configuration reflects procurement unbundling trends, with specification support capabilities displacing bundled contractor margins as the primary competitive differentiator.
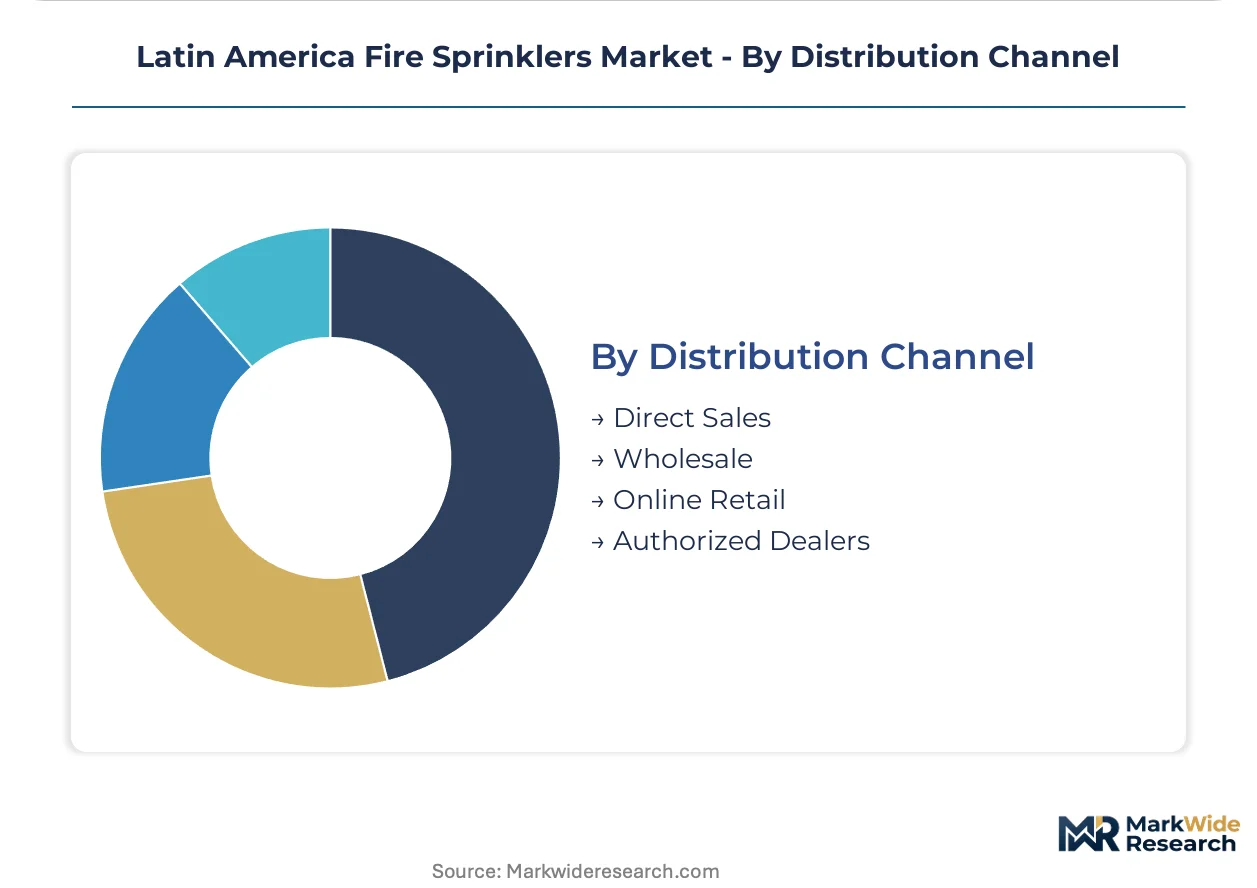
- Direct Sales:Engineering-procurement-construction firms in Mexico City and Monterrey increasingly source sprinkler heads directly from manufacturers, separating equipment supply from hydraulic design services. This pattern compresses traditional distributor markup capture while rewarding technical specification support.
- Authorized Dealers:NFPA 13 certification requirements favor established distribution networks with captive testing laboratory relationships, particularly for foreign equipment suppliers navigating ANVISA-recognized certification bottlenecks in São Paulo.
- Wholesale:Regional contractors in secondary Brazilian and Mexican markets rely on wholesale channels for standard commercial components where specification complexity remains low.
- Online Retail:Replacement heads and maintenance components for small-scale residential and light commercial applications migrate toward digital procurement, though code-mandated third-party inspection requirements limit penetration in regulated verticals.
Direct sales commands the dominant revenue position, while authorized dealers are climbing the fastest as certification barriers reshape channel access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering-procurement-construction firms and certified hydraulic specialists concentrate demand pull across São Paulo, Mexico City, and Buenos Aires corridors where code enforcement timelines compress project award cycles.
Brazil
CBMT building code updates mandate active fire suppression in high-rise commercial structures across São Paulo's financial district. ANVISA tightens medical-grade facility protocols, requiring listed suppression documentation for hospital expansion projects. Rio de Janeiro's port modernization and Belo Horizonte's logistics hub development drive wet pipe system specifications for new warehousing capacity.
Mexico
NOM federal construction standards now require sprinkler protection in commercial towers above twelve stories throughout Mexico City Metro. The civil defense authority enforces third-party inspection protocols that separate equipment procurement from installation services. Monterrey's industrial corridor and Querétaro's data center cluster generate concentrated demand for pre-action systems where discharge sensitivity commands premium engineering.
Argentina
Civil defense authorities in Buenos Aires enforce retroactive compliance deadlines on aging infrastructure built before 2010 fire safety overhauls. The national building code alignment with NFPA 13 frameworks accelerates specification migration toward listed foreign equipment. Córdoba's university expansion pipeline and Rosario's agribusiness processing facilities convert deferred maintenance into active replacement cycles for corroded galvanized steel networks.
Chile
High-hazard industrial sites in Antofagasta and Atacama mining regions remain underpenetrated by certified suppression systems, creating specification white space for corrosion-resistant assemblies. The national civil defense directorate harmonizes municipal adoption timelines with NFPA 13 testing requirements. Santiago's commercial retrofitting wave and Valparaíso port logistics upgrades anchor near-term installation velocity for standard wet pipe configurations.
Colombia
Bogotá's municipal adoption of NFPA 13-aligned standards opens first-mover positioning before federal harmonization spreads to secondary construction markets. The national fire safety council accelerates certification reciprocity negotiations with Brazilian ANVISA-recognized laboratories. Medellín's mid-rise residential boom and Cali's pharmaceutical manufacturing expansion generate pull for both standard commercial systems and medical-grade facility protection.
Latin America Fire Sprinklers Market Key Industry Players
Player mix skews toward multinational manufacturers with captive regional production footprints and specialized fabricators serving high-hazard verticals. The supplier base consolidates rapidly as NFPA 13 certification requirements eliminate smaller competitors lacking testing laboratory relationships. Three archetypes dominate: scale-driven multinationals with Mexican and Brazilian manufacturing assets, marine and industrial specialists commanding premium positioning in corrosion-resistant applications, and regional distributors pivoting toward specification support services. Competitive intensity centers on certification velocity and hydraulic engineering capabilities rather than price alone.
Among multinational manufacturers, Johnson Controls and Viking Group anchor the premium tier through established regional production infrastructure. Johnson Controls leverages its manufacturing footprint across Mexico and Brazil to sustain project delivery timelines for large commercial contracts. Viking Group occupies a specialized position through marine-rated and high-hazard industrial systems that navigate demanding specification environments in Chilean mining corridors and Brazilian port facilities. Reliable Automatic Sprinkler represents the mid-market fabricator archetype, competing on certification breadth and distributor network density across secondary Latin American markets.
| Leading Market Players |
|---|
| Johnson Controls |
| Viking Group |
| Reliable Automatic Sprinkler |
| Tyco Fire Products |
| Honeywell International |
| Minimax |
| Victaulic |
| Siemens |
| Potter Electric Signal Company |
| Others |
Cost & Logistics Intelligence
Project-based procurement with copper and steel indexation clauses locks in material cost visibility for Brazilian and Mexican contractors bidding CBMT and NOM-mandated high-rise installations. This contract architecture ties sprinkler head and piping assembly pricing to London Metal Exchange benchmarks, compressing margin volatility for fabricators while exposing buyers to commodity swings across São Paulo and Mexico City construction corridors.
Pricing Analysis
Cost-plus contracts with LME copper indexation dominate wet pipe system procurement for commercial high-rises. Three-tier pricing structure across NFPA 13-certified premium heads, standard commercial-grade assemblies, and economy retrofit components differentiates bids. Pricing pressure stems from ANVISA-recognized laboratory bottlenecks extending certification timelines and inflating compliance overhead. Mid-tier contractors exhibit highest price sensitivity, while data center operators purchasing pre-action systems prioritize discharge reliability over unit economics.
Supply Chain Analysis
Inventory buffers for fusible alloy elements and brass forging stock stretch lead times when São Paulo certification queues extend. Manufacturing concentrates in Mexico, Brazil, and the United States for NFPA 13-listed assemblies serving Latin American projects. Raw material feeds draw from Chilean copper cathode, Brazilian steel slab, and imported zinc for alloy tempering. Single-source vulnerability concentrates at ANVISA-recognized testing laboratories in São Paulo and Mexico City. Distribution runs through authorized dealer networks with captive laboratory relationships, bypassing wholesale channels for code-mandated commercial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NFPA 13 certification harmonization across Brazil, Mexico, and Colombia is compressing competitive access and consolidating procurement authority among listed multinational manufacturers. This regulatory inflection creates asymmetric growth windows for prepared stakeholders.
For Market Incumbents: Shield market position by deepening captive production footprints in Querétaro and São Paulo industrial corridors to outrun certification bottlenecks. Prioritize hydraulic engineering capability acquisition to address scarcity of NFPA 13-qualified system designers extending project timelines. For New Entrants and Emerging Players: Differentiate on marine-rated and corrosion-resistant assemblies for Chilean mining infrastructure in Antofagasta and Atacama, the most penetrable white space in regional high-hazard verticals. Target specification support services rather than equipment-only distribution to capture unbundled procurement trends in Mexico City engineering-procurement-construction firms. For Investors and Strategic Acquirers: Specialized fabricators with ANVISA-recognized testing relationships and established distributor networks in secondary Colombian and Argentine markets represent the most defensible acquisition archetype. Monitor Bogotá municipal NFPA 13 adoption velocity as the signal indicating federal harmonization timing across Medellín and Cali corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Laboratory Partnership | ANVISA-recognized testing access collapses time-to-market for foreign equipment suppliers. |
| Hydraulic Engineering Capability Buildout | NFPA 13-qualified design talent scarcity extends bid-to-award cycles and rewards in-house expertise. |
| Marine-Rated Product Line Extension | Corrosion-resistant assemblies capture specification premiums in Chilean mining and Brazilian port verticals. |
| Direct Sales Channel Investment | Unbundled procurement patterns in Mexico City compress traditional distributor margins and reward specification support. |
| IoT-Enabled Pre-Action Convergence | Remote valve supervision algorithms compress insurance underwriting costs for data center and cultural heritage facilities. |
Research Approach
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings across the Latin America fire sprinklers landscape. Conversations with fire protection engineers, CBMT compliance officers, ANVISA regulatory consultants, and civil defense inspection authorities in São Paulo, Mexico City, and Buenos Aires informed demand-side dynamics. Secondary sources include NFPA technical standards documentation, ANVISA medical-grade facility protocols, NOM federal construction mandates, and Brazilian customs import records for sprinkler head alloys. Bottom-up installation volume estimates triangulate against top-down construction permit data from national statistics institutes.
Sensitivity analysis around copper price volatility and certification timeline scenarios brackets the forecast range across the projection horizon. Segmentation dimensions modeled include product type architecture, end-user vertical, installation mode lifecycle positioning, and distribution channel configuration. CAGRs derive from regression analysis of historical installation permits against code adoption timelines, with medical-grade facility mandates and data center construction pipelines serving as industry-specific demand accelerators.
The analysis sits within stated boundaries; outcomes outside continued NFPA 13 harmonization momentum or sustained commodity price stability would require recalibration. Forecasts reflect documented assumptions regarding municipal enforcement intensity and laboratory capacity expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
High Frequency Vibrator Market
Others
Global Microcontroller Embedded Systems Market
Others
North America Halal Food and Beverage Market
Others
Global Telemetry Market
Others
Europe Battery Packaging Market
Others
Vo5g Market
Others
Wood Stoves Market
Others
Electric Pallet Jack Truck Market
Others
Global Alpha Cypermethrin Market
Others
Rope Market
Others
Global Smartphone ODM Market
Others
Cat Food Market
Others
Solar Lighting Tower Market
Others
Italy 3D Printing Construction Market
Others
Content Experience Platforms Market
Others
Rugged Tablet Market