
 Middle East Smart Home Market | 2026-2036
Middle East Smart Home Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Smart Home Market Insights
Hospitality sector adoption is restructuring demand patterns across the Middle East smart home landscape. Luxury hotel chains and serviced apartment operators now specify integrated building automation suites during construction, not retrofit. Honeywell International Inc. leverages its legacy in building management systems to anchor large-scale hospitality contracts across Dubai and Riyadh. Schneider Electric SE differentiates through edge-computing energy platforms that sustain operational efficiency targets for resort operators.
Middle East smart home systems comprise interconnected devices, sensors, controllers, and software platforms that automate climate, lighting, security, and appliance functions through centralized or distributed architectures, typically operating on mesh network protocols with sub-100 millisecond response times for real-time occupant interaction. Smart Security Systems currently dominate project specifications across Gulf commercial developments due to integrated access control requirements, while Smart Thermostats capture expanding margin pools as energy compliance mandates tighten. Wi-Fi technology leads residential penetration for its zero-infrastructure compatibility, though Zigbee gains traction in professional installations where multi-device reliability matters.
MOHAP in the UAE and Saudi Arabia's Saudi Standards, Metrology and Quality Organization shape product certification requirements for electrical safety and electromagnetic compatibility, directly determining which device families enter Gulf distribution channels. The EU AI Act creates indirect compliance pressure as European-origin platforms route through regional hubs. Stakeholders must monitor how evolving cybersecurity standards for IoT devices interact with existing building codes across jurisdictions.
Market Dynamics
Hospitality sector procurement now mandates IoT infrastructure at construction phase rather than retrofit, compressing vendor selection timelines and favoring building management system incumbents with pre-integrated platform architectures across Saudi Arabia and the UAE.
Growth Catalysts
- Saudi Building Code mandates:Energy-efficient building controls requirements accelerate smart thermostat and lighting integration in new commercial developments across the Kingdom.
- Hospitality procurement restructuring:Luxury hotel chains and serviced apartment operators specify integrated automation suites during construction, creating pull-through demand for full-stack solutions.
- Edge-computing convergence:Resort operators deploy localized energy platforms to sustain operational efficiency targets without cloud dependency in high-temperature environments.
Market Restraints
- Input cost volatility:Semiconductor component shortages and shipping rate fluctuations from Asian manufacturing hubs compress hardware margins for regional distributors.
- Certification friction:MOHAP electrical safety and electromagnetic compatibility requirements in the UAE create multi-month approval delays for non-compliant device families.
- Technical fragmentation:Incompatible mesh network protocols between Wi-Fi, Zigbee, and proprietary systems force redundant gateway investments in mixed-installation environments.
Strategic Opportunities
- Underpenetrated residential retrofit:Existing housing stock in Riyadh and Jeddah lacks automation infrastructure, creating whitespace for wireless retrofit solutions targeting rental property managers.
- Regulatory tailwind from Estidama:UAE's Pearl Rating System incentivizes smart water and energy monitoring in new developments, expanding addressable market beyond climate control.
- Technology convergence:Integration of AI-driven occupancy sensing with existing building management systems enables predictive maintenance contracts for commercial facility operators.
Industry Challenges
- Cybersecurity skill scarcity:Regional system integrators lack certified IoT security architects to harden device fleets against evolving threat vectors.
- Legacy infrastructure integration:Pre-digital commercial buildings in Dubai's older free zones require costly protocol bridges to connect pneumatic HVAC systems with modern controllers.
- Compliance timeline compression:Evolving Saudi Standards, Metrology and Quality Organization requirements force product redesign cycles that outpace hardware development lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Smart Home Market |
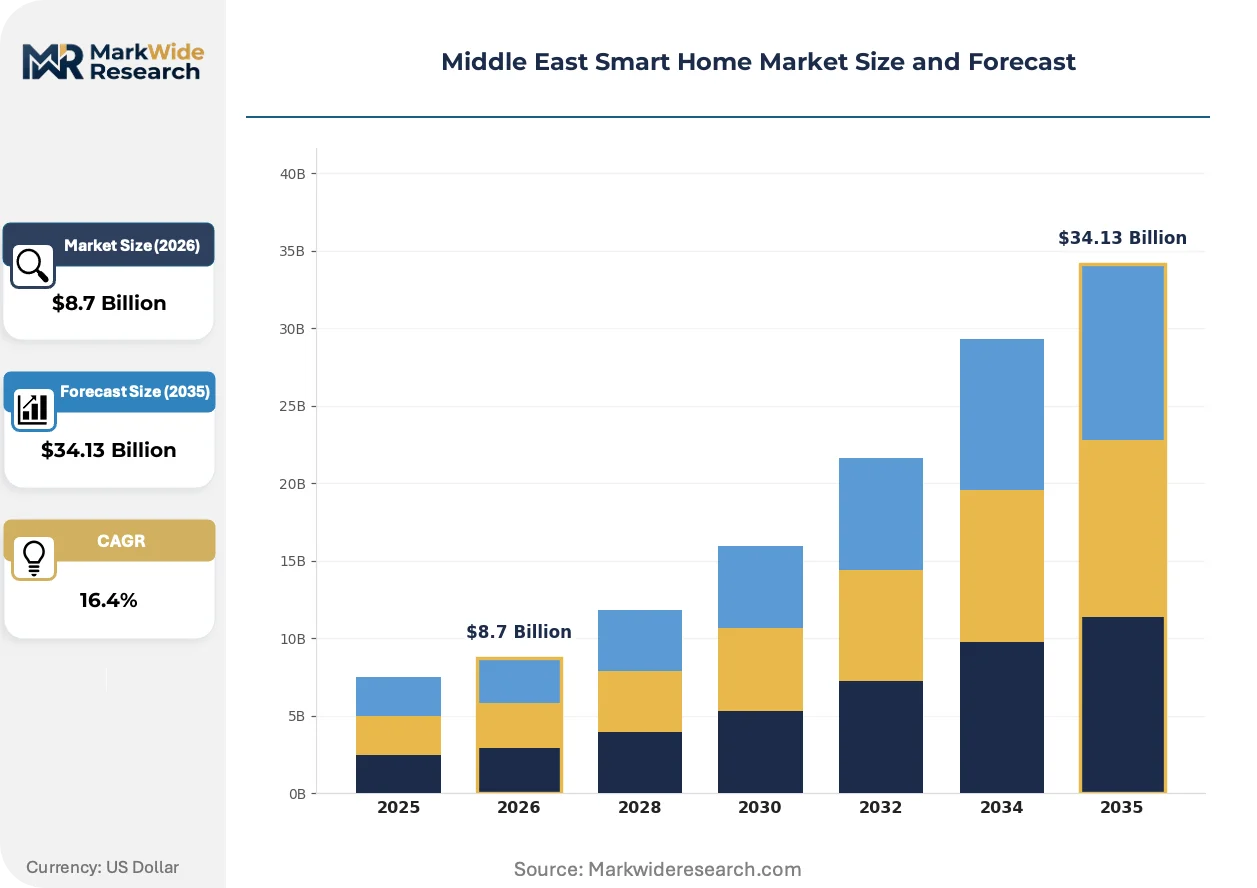
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Smart Thermostats, Smart Security Systems, Smart Appliances Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth Installation: DIY, Professional, Hybrid, Managed Services End User: Residential, Hospitality, Commercial, Retail |
| Companies Covered | Honeywell International Inc., ABB Ltd., Johnson Controls, Schneider Electric SE, Siemens AG, Emerson Electric Co., Google LLC (Nest), LG Electronics Inc., Legrand SA, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Smart Home Market Trends and Innovations
Building automation architectures are shifting from centralized control rooms to distributed edge nodes, enabling sub-100 millisecond response times while reducing bandwidth costs. This structural reconfiguration favors vendors with embedded computing capabilities over traditional gateway-dependent systems.
Occupancy-aware climate control is automating energy allocation in commercial developments. The technology uses millimeter-wave sensors and thermal imaging to detect presence and density in real time. Large-scale hospitality operators in Dubai and Riyadh are deploying these systems at construction phase to meet stringent efficiency mandates. The capability is automating demand-response participation, allowing buildings to shed load automatically during grid peak events without manual intervention.
MOHAP and Saudi Standards, Metrology and Quality Organization are tightening electromagnetic compatibility testing protocols for IoT devices entering Gulf distribution channels. The regulations now require third-party certification for radio frequency emissions in dense device environments. Smart security system manufacturers face the steepest compliance burden due to always-on transmission requirements. Vendors are responding by establishing local testing partnerships to compress approval timelines from twelve to six months.
Facility management procurement is consolidating vendor relationships around full-stack platform providers. Single-point solutions for lighting, climate, and access control are losing share to integrated suites that share data layers and dashboard interfaces. This consolidation is most visible in Saudi Arabia's mega-development projects, where master developers specify automation ecosystems at master planning stage rather than allowing subcontractor discretion. The shift compresses supplier counts per project from fifteen to three, raising barriers for point-product specialists.
Middle East Smart Home Market Segmentation
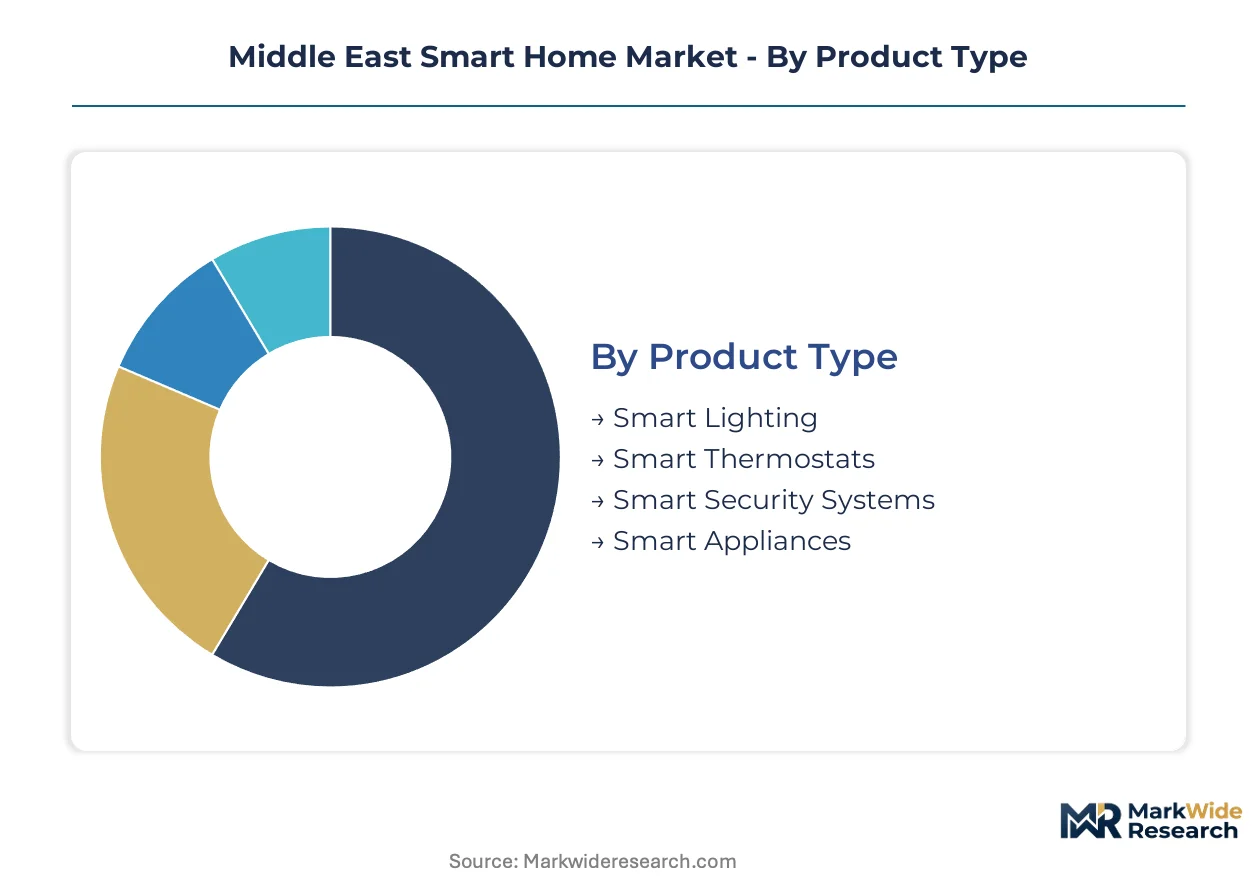
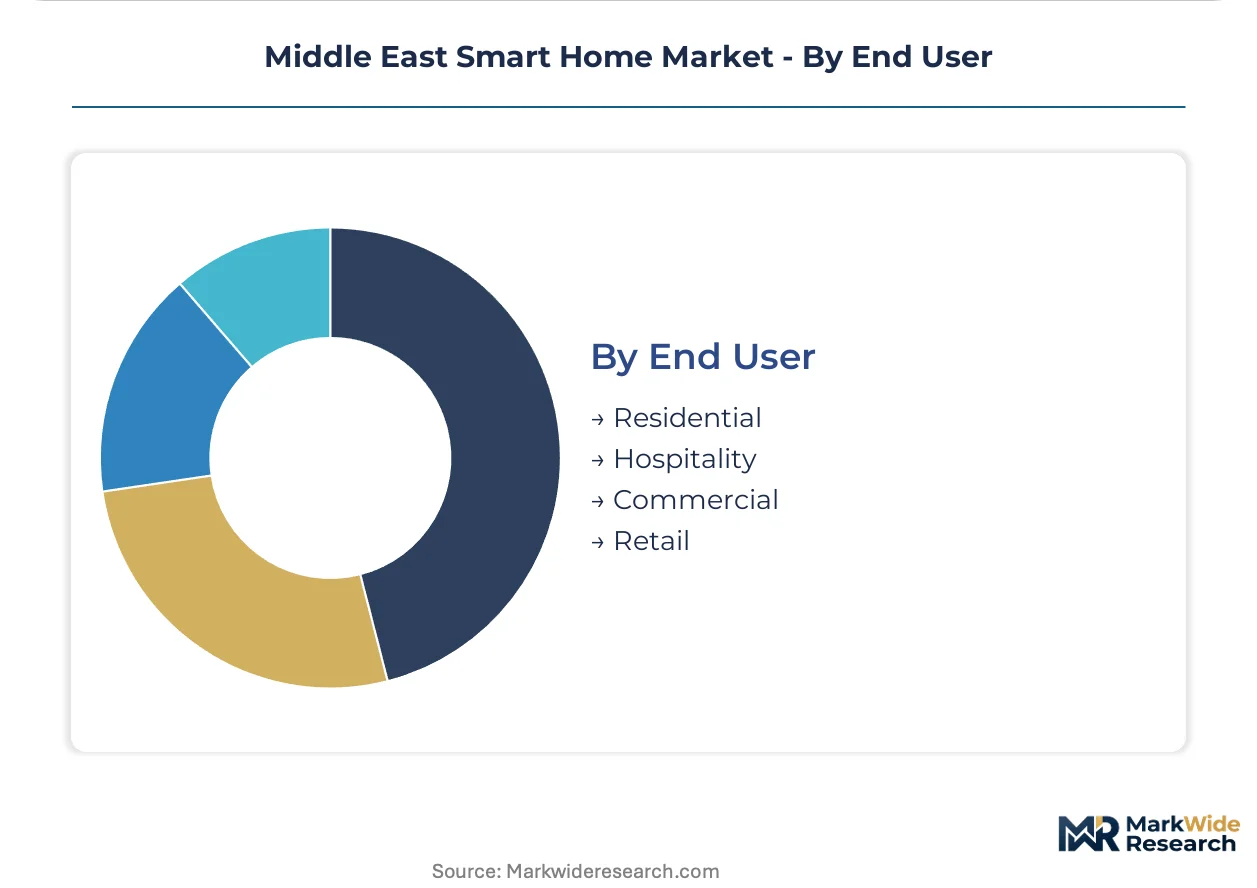
Smart home procurement in the Middle East diverges sharply between new-build mega-developments and existing housing stock. Upgrade cycles for hospitality and commercial properties now compress to construction-phase decisions, while residential retrofits follow replacement-driven timelines for aging HVAC and security infrastructure.
Product Type:
Replacement cycles vary dramatically across device categories, with climate and security systems commanding priority capital allocation in Gulf commercial developments.
- Smart Security Systems:Integrated access control, surveillance, and intrusion detection platforms dominate new-build specifications across Dubai and Riyadh hospitality projects. Saudi Building Code mandates for emergency response integration drive centralized procurement of multi-zone systems in Kingdom mega-developments.
- Smart Thermostats:Programmable climate controllers with occupancy sensing and grid-responsive load shedding capabilities capture expanding specification share. UAE Estidama Pearl Rating requirements for energy performance monitoring accelerate deployment in Abu Dhabi and Dubai commercial towers.
- Smart Lighting:LED-based automated illumination systems with daylight harvesting and circadian programming address municipal energy efficiency targets.
- Smart Appliances:Connected white goods with remote diagnostics and usage analytics remain nascent in Gulf markets due to limited interoperability standards.
Volume placements concentrate in Smart Security Systems; the faster expansion belongs to Smart Thermostats.
Technology:
Protocol selection directly determines infrastructure upgrade costs and device ecosystem lock-in for property developers.
- Wi-Fi:Ubiquitous residential penetration leverages existing router infrastructure without dedicated gateways. Zero-additional-hardware deployment suits rental property managers in Riyadh and Jeddah retrofit markets where tenant turnover discourages capital investment.
- Zigbee:Mesh network architecture with self-healing topology commands professional installation preference for multi-device commercial environments. Saudi mega-developments specify Zigbee backbones to ensure sub-100 millisecond response times across thousands of endpoints.
- Z-Wave:Sub-GHz frequency operation avoids 2.4 GHz congestion in dense device deployments.
- Bluetooth:Low-energy beacon protocols enable proximity-based automation for boutique hospitality deployments.
Wi-Fi claims the installed base crown; Zigbee posts the steepest specification climb in new construction.
Installation:
Service model selection reflects property ownership structures and technical workforce availability across Gulf jurisdictions.
- Professional:Certified integrator deployment with commissioning, calibration, and warranty coverage dominates hospitality and commercial procurement. Dubai master developers mandate professional installation to meet MOHAP electrical safety certification requirements for permanent building systems.
- Managed Services:Subscription-based monitoring, maintenance, and firmware management packages gain traction among resort operators seeking operational expenditure predictability. Schneider Electric and Honeywell anchor multi-year facility management contracts across UAE and Saudi hospitality portfolios.
- DIY:Consumer self-installation of standalone devices with smartphone configuration addresses price-sensitive residential segments.
- Hybrid:Professional backbone with user-expandable peripheral zones splits capital allocation between landlord and tenant.
Professional installation commands the revenue pool; Managed Services is climbing the fastest.
End User:
Demand concentration patterns split between construction-phase specification and replacement-driven retrofit opportunities.
- Hospitality:Luxury hotel chains and serviced apartment operators now embed full-stack automation during construction rather than retrofit. Procurement consolidation around three-vendor ecosystems compresses supplier counts from fifteen in legacy projects.
- Residential:Existing housing stock in Riyadh, Jeddah, and Dubai's older districts lacks automation infrastructure, creating whitespace for wireless retrofit solutions targeting rental property managers.
- Commercial:Office and mixed-use developments in Saudi giga-projects specify edge-computing energy platforms to sustain operational efficiency targets without cloud dependency.
- Retail:Shopping mall operators deploy occupancy-aware climate control and security integration for footfall analytics and loss prevention.
Hospitality anchors current procurement volume; Residential retrofit offers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for smart home devices remains anchored in East Asian electronics clusters, while deployment and systems integration concentrate in Gulf mega-developments. Saudi Arabia and the UAE absorb the dominant share of professional installation revenue.
Saudi Arabia
Giga-project construction across NEOM, Qiddiya, and the Red Sea coast embeds automation infrastructure from master planning phase. The Saudi Building Code mandates energy-efficient building controls that accelerate smart thermostat and lighting integration in commercial towers. Riyadh's King Abdullah Financial District exemplifies procurement consolidation around three-vendor automation ecosystems.
United Arab Emirates
Dubai's hospitality sector specifies full-stack building automation during construction rather than retrofit, compressing vendor selection timelines. MOHAP electrical safety and electromagnetic compatibility requirements determine which device families enter distribution channels. Abu Dhabi's Masdar City cluster deploys edge-computing energy platforms to sustain operational efficiency targets without cloud dependency.
Qatar
World Cup legacy infrastructure and Lusail City development sustain demand for integrated security and climate systems in commercial and hospitality assets. The Qatar General Organization for Standardization enforces electromagnetic compatibility testing that mirrors UAE protocols. Doha's West Bay district concentrates specification activity for luxury hotel automation suites.
Kuwait
Southern Al-Mutlaa and Silk City developments incorporate smart infrastructure specifications from construction phase. The Public Authority for Industry administers product conformity requirements for electrical devices entering Kuwaiti distribution. Kuwait City's commercial tower pipeline drives demand for centralized building management platforms.
Israel
Residential retrofit activity concentrates in Tel Aviv and Haifa metropolitan areas where aging housing stock lacks automation infrastructure. The Standards Institution of Israel mandates cybersecurity certification for IoT devices that exceeds baseline Gulf requirements. Tel Aviv's technology sector spurs demand for AI-driven occupancy sensing in boutique commercial developments.
Middle East Smart Home Market Competitive Landscape
Top-tier vendors anchor hospitality and commercial mega-projects, while mid-tier specialists compete for residential retrofit opportunities. The vendor base stratifies across building management incumbents, consumer electronics platforms, and regional system integrators. Three archetypes dominate: legacy automation conglomerates with pre-integrated architectures, consumer-facing platform providers with wireless ecosystems, and regional installation specialists with certification relationships. Competitive moves center on construction-phase specification capture and local testing partnership formation to compress regulatory approval timelines.
Within the building management tier, Honeywell International Inc. and Schneider Electric SE exemplify platform providers with hospitality sector anchoring positions. Johnson Controls occupies a position alongside Siemens AG among industrial automation conglomerates extending into smart infrastructure. Google LLC represents the consumer platform archetype through its Nest portfolio, competing for residential retrofit specifications.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| ABB Ltd. |
| Johnson Controls |
| Schneider Electric SE |
| Siemens AG |
| Emerson Electric Co. |
| Google LLC (Nest) |
| LG Electronics Inc. |
| Legrand SA |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between MOHAP-compliant professional systems and uncertified consumer devices manifests in both procurement premiums and sourcing complexity. Gulf distributors command price premiums for pre-certified device families while absorbing extended approval timelines that compress working capital cycles.
Pricing Analysis
Short-lead-time premiums for certified smart security systems reach substantial markups over spot-market alternatives in Dubai and Riyadh. Project-based pricing dominates hospitality procurement, with Estidama Pearl Rating tier and electromagnetic compatibility certification level as primary differentiation drivers. Cost compression in residential Wi-Fi devices is intensifying because semiconductor input volatility forces margin sacrifice for volume retention. Rental property managers in Jeddah exhibit highest price sensitivity; mega-development master developers show least.
Supply Chain Analysis
Workforce availability constraints in Shenzhen and Dongguan electronics clusters are forcing component manufacturers toward automated surface-mount lines. Device assembly draws from China, South Korea, and Taiwan; semiconductor sourcing rests on Malaysian packaging facilities and Taiwanese wafer foundries. Single-source vulnerability for Zigbee radio modules creates bottleneck exposure. Distribution runs through Dubai Jebel Ali free zone consolidation before final-mile deployment to Saudi giga-projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. Saudi Standards, Metrology and Quality Organization electromagnetic compatibility mandates create a barrier-to-entry moat for vendors with pre-established local testing partnerships.
For Market Incumbents: Hedge against certification timeline compression by securing redundant local testing partnerships across Riyadh and Dubai. Backward integration into edge-computing hardware production reduces exposure to semiconductor spot-market volatility. Anchor multi-year managed services contracts with hospitality operators to lock out point-product specialists. For New Entrants and Emerging Players: The price-point gap between Honeywell-tier premium platforms and consumer Wi-Fi retrofits offers whitespace for mid-market wireless solutions. Residential retrofit in Riyadh's aging districts presents the most penetrable geography. Target rental property managers with zero-infrastructure deployment models that transfer seamlessly between tenants. For Investors and Strategic Acquirers: Re-rating potential sits with regional system integrators holding MOHAP and Saudi Standards certification relationships given accelerating procurement consolidation. Long-term viability favors full-stack platform providers over point-product vendors. Watch hospitality procurement committee composition shifts as inflection indicator for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Local Certification Partnership Formation | Compresses MOHAP approval timelines from twelve to six months for device families. |
| Edge-Computing Platform Integration | Enables sub-100 millisecond response times for Saudi mega-development specifications. |
| Managed Services Contract Anchoring | Locks multi-year facility management relationships with UAE resort operators. |
| Wireless Retrofit Solution Launch | Captures Riyadh and Jeddah residential whitespace without construction-phase dependency. |
| AI-Driven Occupancy Sensing Development | Automates demand-response participation for Dubai commercial tower compliance. |
Research Methodology
Multi-period observation of hospitality procurement patterns and certification timeline evolution anchored the trend analysis, supplemented by interviews with building automation system integrators, MOHAP compliance officers, mega-development procurement directors, and semiconductor distribution specialists. Secondary validation drew from Saudi Standards regulatory filings, UAE construction project databases, customs import records, and SEC disclosures from listed automation conglomerates. Bottom-up device shipment estimates triangulated against top-down construction spend allocation.
Segment-weighting across product type, technology protocol, installation service model, and end-user vertical determined value distribution. Growth trajectories were derived through installation base expansion modeling and replacement cycle analysis across the projection horizon. Forecast inputs incorporated hospitality construction pipeline data and regulatory mandate implementation schedules.
Underlying measurement precision varies by segment; professional installation and hospitality end-use carry tighter precision than DIY residential given data availability. Forecasts reflect documented assumptions regarding construction timeline execution and regulatory enforcement consistency. Material deviation in Saudi giga-project completion rates or MOHAP certification protocol changes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Hydraulics Market
Others
Liposomes Market
Others
Gem Faceting Machine Market
Others
Fibert Market
Others
Global Smart Kitchen Market
Others
UK Cat Food Market
Others
Pollen Allergy Market
Others
Brazil Lime Market
Others
Exosome Technologies Market
Others
Rotary Dial Machine Market
Others
North America Video Conferencing Hardware Market
Others
Metal Air Battery Market
Others
Nonlinear Editing System Market
Others
High-End Servers Market
Others
AC Switchgear Market
Others
Global Process Equipment Market