
 Smartphone Gimbal Market | 2026-2036
Smartphone Gimbal Market Size, Share, and Industry Trends Forecast 2026-2036
Smartphone Gimbal Market Analytics
Brushless motor control architecture is fragmenting across proprietary and open-source implementations, forcing manufacturers to choose between custom silicon and modular off-the-shelf solutions. DJI leverages in-house gimbal algorithms and vertical manufacturing to dominate the premium tier. Zhiyun competes through aggressive R&D spending on compact foldable designs. Hohem anchors the entry-level segment with cost-optimized 3-axis stabilization for casual users.
A smartphone gimbal is an electromechanical stabilization device employing brushless DC motors and inertial measurement units to counteract hand tremor and motion across three rotational axes, delivering cinematic-grade footage from mobile cameras. The product serves commercial videography, live streaming, and amateur filmmaking where optical or electronic stabilization proves insufficient. Three-axis hardware leads in unit volume due to universal compatibility with flagship handsets, while the professional pricing tier captures disproportionate margin pools through carbon fiber construction and integrated follow-focus systems. Content creators and social media influencers represent the fastest-growing end-user cohort as platform monetization incentivizes production quality upgrades.
FCC certification governs radio frequency emissions from Bluetooth-connected gimbals in the United States, while China's GB standards mandate battery thermal runaway testing for lithium-powered stabilization devices. The EU's RoHS directive and CE marking restrict hazardous substances in motor windings and circuit boards, shaping supplier qualification requirements for European market access. Stakeholders must monitor how emerging AI-powered subject tracking features trigger software regulation under the EU AI Act and comparable frameworks elsewhere.
Market Dynamics
The smartphone gimbal market is compressing around brushless motor control fragmentation, as manufacturers face binding choices between proprietary silicon architectures and modular off-the-shelf implementations that reshape R&D allocation and margin structures.
Growth Catalysts
- GB Battery Standards:China's tightened thermal runaway testing for lithium-powered stabilization devices is accelerating certified product turnover and creating replacement demand cycles among existing owners.
- Live Streaming Vertical:Platform monetization incentives on TikTok, YouTube Shorts, and Instagram Reels are pulling production quality investments from amateur creators into hardware upgrades.
- Carbon Fiber Construction:Premium tier manufacturers are adopting aerospace-grade composites to reduce payload weight while maintaining rigidity, opening professional cinematography applications.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium price swings in Chinese mining regions directly compress motor manufacturing margins and destabilize component sourcing forecasts.
- Optical Stabilization Substitution:Sensor-shift and computational stabilization in flagship handsets from Apple and Samsung are eroding entry-level gimbal necessity among casual users.
- CE Marking Complexity:RoHS substance restrictions on motor windings and circuit boards extend European market entry timelines by 4-6 months for non-compliant suppliers.
Strategic Opportunities
- AI Subject Tracking Convergence:Computer vision algorithms married to brushless motor response curves are creating autonomous cinematography tools for solo creators.
- German Content Creator Density:Berlin and Munich's influencer economy remains underpenetrated by premium gimbal distributors relative to per-capita production activity.
- EU AI Act Positioning:Early compliance with algorithmic transparency requirements for tracking software creates regulatory moats against late-arriving competitors.
Industry Challenges
- Embedded Firmware Talent Scarcity:Kalman filter implementation and real-time motor control expertise concentrates in Shenzhen and Shenzhen-adjacent labor pools, constraining geographic diversification.
- FCC Certification Backlogs:Bluetooth radio emission testing queues at accredited labs are stretching product launch windows for connected gimbal models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smartphone Gimbal Market |
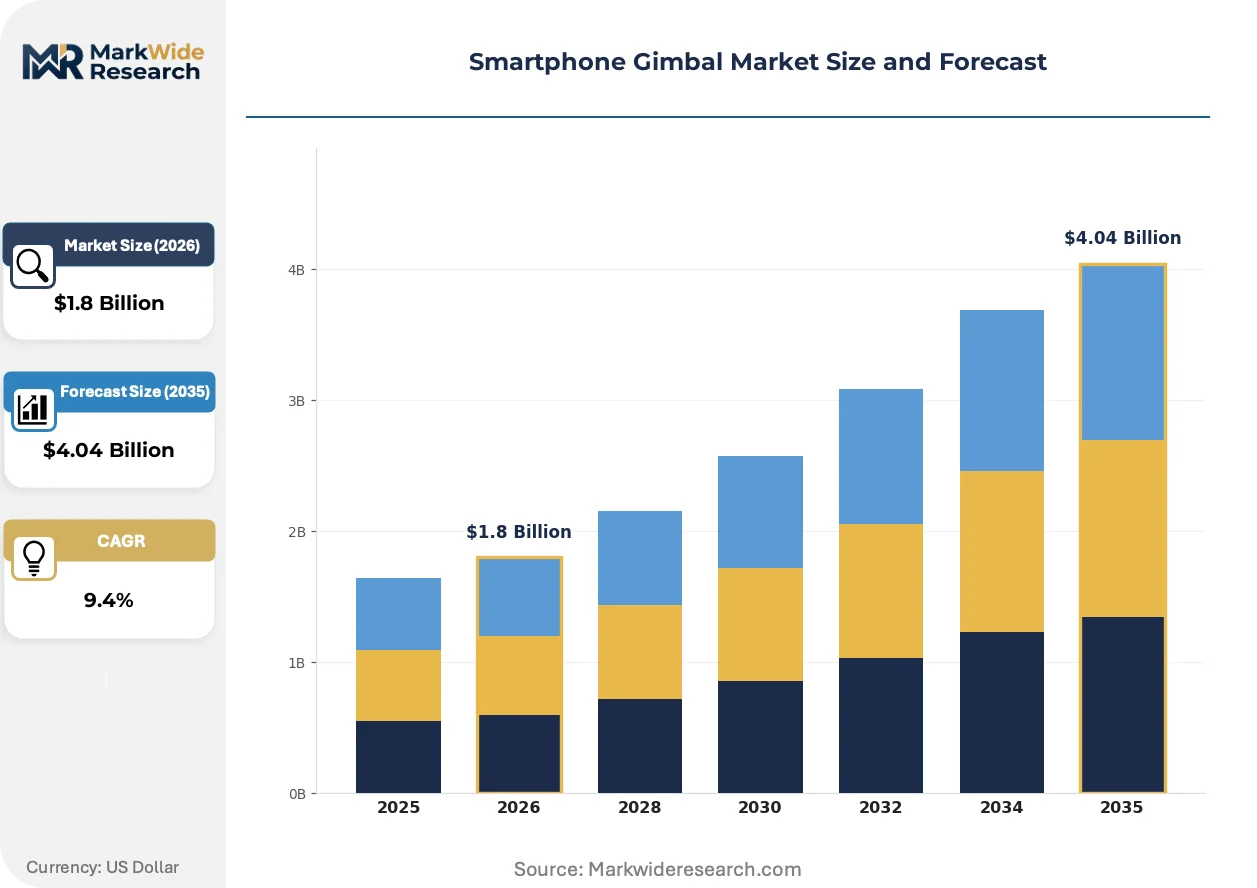
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3-Axis, 2-Axis, Smartphone Stabilizer, Accessory Mount End User: Content Creators, Filmmakers, Vloggers, Social Media Influencers Usage Scenario: Outdoor Events, Social Media, Professional Filming, Travel Pricing Model: Entry-Level, Mid-Range, Premium, Professional |
| Companies Covered | DJI, Hohem, Zhiyun, Insta360, Sony Group Corporation, Panasonic Corporation, Hangzhou Hikvision Digital Technology, Moment, Feiyu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smartphone Gimbal Market Evolving Landscape
Active stabilization hardware is absorbing computational photography capabilities while regulatory frameworks for embedded AI reshape competitive positioning across certification-sensitive geographies.
Magnetic encoder feedback systems are hybridizing with traditional Hall-effect sensors in next-generation brushless motor controllers. Professional videographers and commercial livestream operators are adopting these hybrid architectures fastest, compressing price-performance thresholds that previously separated premium and standard tier products. The technology fusion is forcing mid-market manufacturers to abandon single-sensor designs or retreat to entry-level positioning.
EU AI Act algorithmic transparency requirements are triggering software architecture redesigns for subject-tracking gimbals sold in European markets. Manufacturers must now document decision pathways for automated framing and motion prediction, extending development cycles and privileging vendors with established compliance infrastructure. Premium-tier products with integrated AI features face the steepest documentation burdens, while basic stabilization-only models gain relative regulatory simplicity.
Creator economy procurement patterns are fragmenting across direct-to-consumer, platform-integrated, and rental-channel pathways. Aspiring influencers in China and the United States increasingly access gimbals through short-term subscription models or bundled smartphone packages rather than standalone retail purchases. This channel rotation is compressing traditional distributor margins and forcing hardware brands to build platform partnerships or owned rental infrastructure.
Smartphone Gimbal Market Segmentation
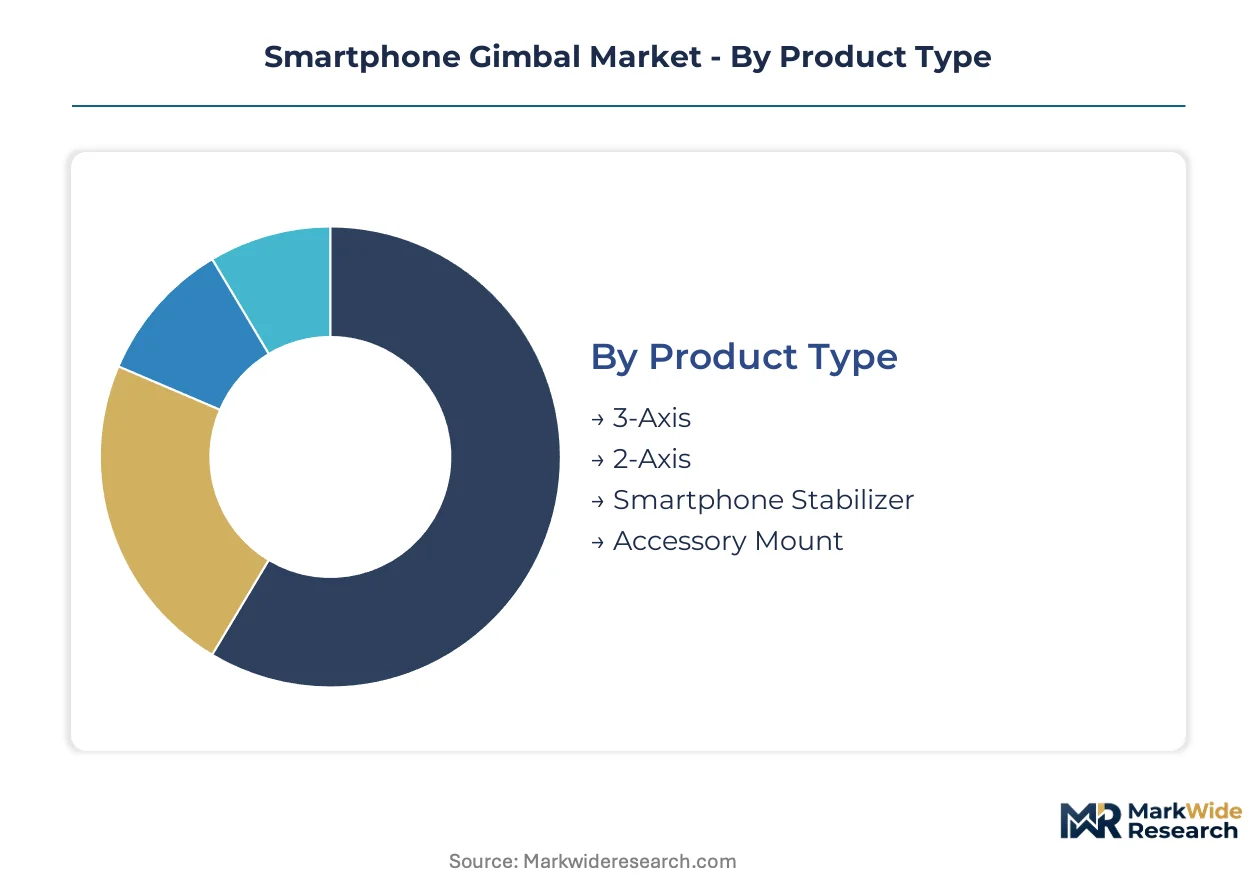
Segmentation in smartphone gimbals reveals how stabilization hardware fragments across user sophistication levels and production contexts. Product architecture, end-user workflows, and pricing tiers each create distinct competitive battlegrounds with different margin profiles and replacement cycles.
Product Type:
3-Axis hardware turns over slowest due to durability and flagship handset compatibility, while Accessory Mounts cycle fastest as smartphone form factors evolve. 2-Axis and Smartphone Stabilizer categories occupy intermediate replacement rhythms shaped by motor technology maturation.
- 3-Axis:Employs brushless DC motors across pan, tilt, and roll axes with inertial measurement units delivering cinematic-grade stabilization. Demand concentrates among commercial videographers in China and the United States where platform monetization justifies production quality investments. Neodymium magnet price volatility in Chinese mining regions compresses manufacturing margins unpredictably.
- 2-Axis:Stabilizes across pan and tilt axes only, sacrificing roll correction for reduced weight and cost. Compact designs from Shenzhen manufacturers serve travel vloggers prioritizing portability over full-axis control. China's GB battery standards for thermal runaway testing accelerate certified product turnover.
- Smartphone Stabilizer:Integrated handle-and-motor units with native app ecosystems for automated tracking.
- Accessory Mount:Modular clamp systems adapting third-party stabilization to specific handset dimensions.
3-Axis dominates installed base. 2-Axis is where expansion concentrates among weight-conscious creators.
End User:
Cost tier separation runs deepest here, with Social Media Influencers and Vloggers clustering at entry-to-mid pricing while Filmmakers anchor premium tiers. Content Creators span the full spectrum depending on monetization stage and platform revenue share.
- Content Creators:Encompasses amateur through semi-professional producers monetizing across TikTok, YouTube Shorts, and Instagram Reels. Procurement in China and the United States increasingly shifts to subscription rental models rather than standalone retail. Platform partnership requirements from ByteDance and Meta reshape hardware specification demands.
- Social Media Influencers:Platform-native creators whose follower economics drive rapid hardware upgrade cycles. Berlin and Munich's influencer economy remains underpenetrated by premium distributors relative to per-capita production activity. EU AI Act algorithmic transparency requirements for tracking software extend procurement evaluation timelines.
- Filmmakers:Narrative and documentary producers requiring broadcast-acceptable output from mobile cameras.
- Vloggers:Solo operators prioritizing single-handed operation and extended battery runtime.
Filmmakers dominate installed base. Social Media Influencers are climbing the fastest as platform monetization incentives deepen.
Usage Scenario:
Volume concentration separates predictable indoor contexts from weather-exposed outdoor deployment, with Professional Filming commanding lowest unit volumes but highest per-unit margins. Travel and Social Media scenarios drive bulk shipment scale.
- Professional Filming:Commercial productions, broadcast journalism, and corporate videography demanding broadcast-acceptable output. Carbon fiber construction from aerospace-grade composites reduces payload weight while maintaining rigidity for extended handheld operation. FCC certification backlogs for Bluetooth-connected models stretch product launch windows at accredited US labs.
- Social Media:Short-form content optimized for vertical platforms with automated subject tracking and gesture control. Live streaming vertical expansion on TikTok and Instagram Reels pulls production quality investments from amateur creators into hardware upgrades. Kalman filter implementation expertise concentrates in Shenzhen labor pools, constraining geographic diversification.
- Outdoor Events:Music festivals, sports coverage, and documentary fieldwork requiring weather sealing.
- Travel:Tourism documentation prioritizing compact foldable designs and airline carry-on compliance.
Social Media dominates installed base. Professional Filming is where margin expansion concentrates.
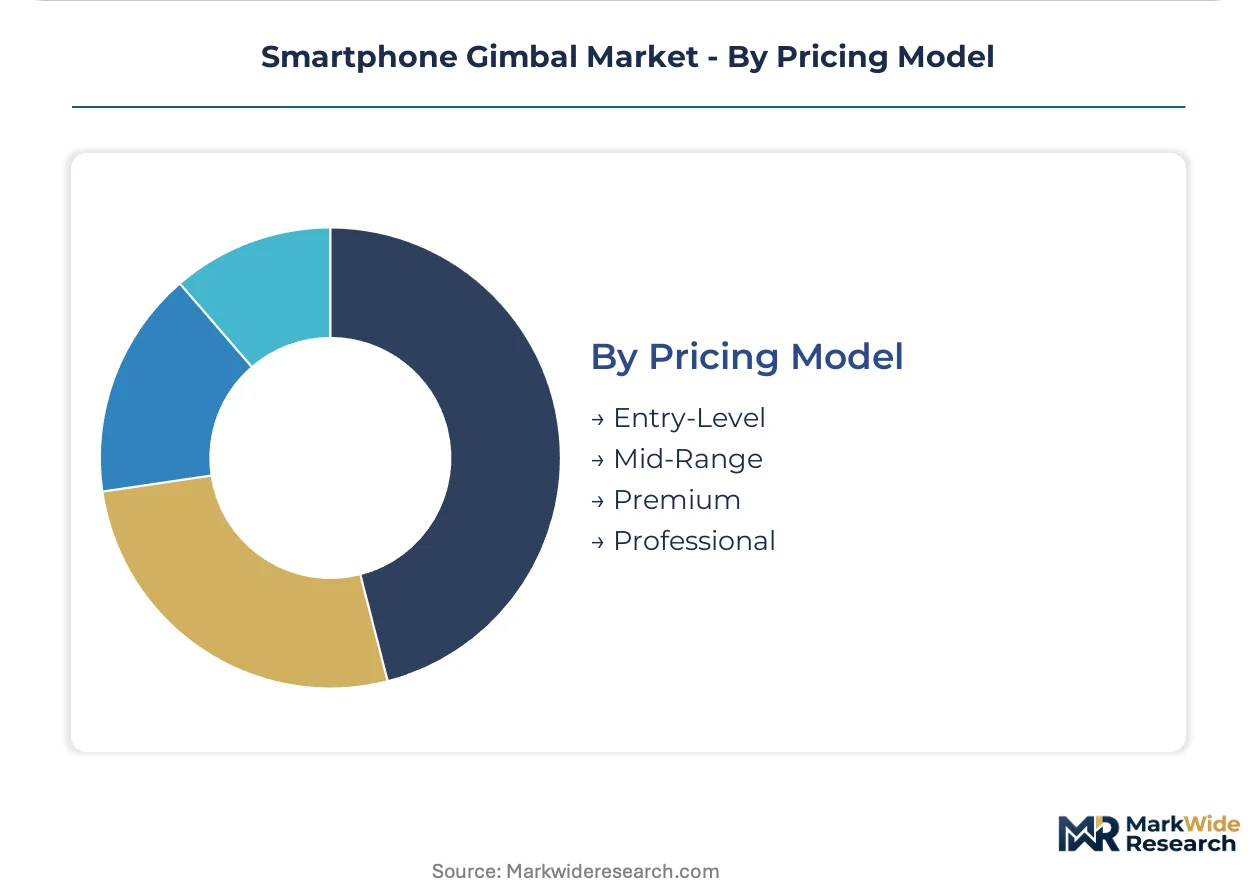
Pricing Model:
Margin structure inverts across this dimension, with Entry-Level capturing volume through Shenzhen manufacturing scale while Professional tier monetizes carbon fiber construction and integrated follow-focus systems. Mid-Range and Premium segments face compression from optical stabilization substitution in flagship handsets.
- Entry-Level:Cost-optimized 3-axis stabilization for casual users with basic app integration and plastic construction. Hohem and comparable Shenzhen manufacturers anchor this segment through aggressive BOM cost management. Apple's sensor-shift stabilization in iPhone Pro models erodes necessity among casual users.
- Professional:Carbon fiber construction, integrated follow-focus, and multi-operator wireless control for broadcast productions. DJI's in-house gimbal algorithms and vertical manufacturing defend this tier against modular competitors. CE marking complexity from RoHS substance restrictions extends European market entry timelines.
- Mid-Range:Metal construction with advanced tracking features for committed amateurs.
- Premium:Aerospace-grade materials with cinema-grade motor response curves.
Entry-Level dominates installed base. Professional is where margin defense concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Content creators and social media influencers concentrate most heavily in China, followed by the United States and Germany, with platform monetization incentives driving hardware upgrade cycles across these three core demand centers.
China
ByteDance's TikTok ecosystem and Kuaishou's creator programs generate sustained gimbal procurement from amateur through professional tiers. MIIT's GB standards for electronic stabilization equipment and lithium battery safety tighten product certification requirements, accelerating certified product turnover. Shenzhen's brushless motor control talent pools concentrate Kalman filter implementation expertise, constraining geographic diversification for firmware development.
United States
YouTube Shorts and Instagram Reels monetization pull production quality investments from creators into hardware upgrades across entry through premium tiers. FCC certification governs radio frequency emissions from Bluetooth-connected gimbals, with testing queues at accredited labs stretching product launch windows. Los Angeles and New York's influencer economies drive premium-tier demand for carbon fiber construction and integrated follow-focus systems.
Germany
Berlin and Munich's content creator density remains underpenetrated by premium gimbal distributors relative to per-capita production activity. CE marking requirements under RoHS restrict hazardous substances in motor windings and circuit boards, extending market entry timelines for non-compliant suppliers. Bavaria's commercial videography sector anchors professional-tier demand for broadcast-acceptable mobile output.
Japan
Meta's platform partnerships and domestic live streaming verticals drive mid-range gimbal adoption among solo vloggers prioritizing single-handed operation. METI standards shape electrical safety compliance for lithium-powered stabilization devices sold through domestic retail channels. Tokyo's creator economy clusters around compact foldable designs optimized for airline carry-on compliance.
South Korea
Naver's content creator incentives and Kakao's platform monetization programs stimulate hardware upgrade cycles among mobile-first producers. MFDS oversight intersects with radio equipment certification for Bluetooth-enabled stabilization hardware. Seoul's influencer marketing agencies increasingly specify gimbal compatibility in brand campaign equipment packages.
Smartphone Gimbal Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where premium, mid-range, and entry-level positions each sustain distinct margin profiles. Shenzhen-based manufacturers anchor the entry-level segment through aggressive bill-of-materials cost management, while vertically integrated specialists defend premium tiers through in-house algorithm development. Three strategic archetypes dominate: algorithm-led premium defenders, compact-design innovators, and cost-optimized volume producers. Competitive moves concentrate on strategic partnerships with platform operators and portfolio diversification into rental-channel infrastructure.
Among Chinese specialists, DJI and Zhiyun occupy positions exemplifying contrasting strategic approaches to the premium and mid-range tiers. Hohem anchors the entry-level segment as a cost-optimized volume producer. These three Shenzhen-adjacent entities collectively represent the geographic concentration of brushless motor control expertise that shapes global competitive dynamics.
| Leading Market Players |
|---|
| DJI |
| Hohem |
| Zhiyun |
| Insta360 |
| Sony Group Corporation |
| Panasonic Corporation |
| Hangzhou Hikvision Digital Technology |
| Moment |
| Feiyu |
| Others |
Value Network & Pricing Analysis
Shenzhen's concentration of brushless motor control talent and neodymium magnet processing capacity concentrates upstream margin capture in Chinese manufacturing clusters, while downstream pricing power fragments across platform-integrated subscription models and traditional retail channels serving creator economy procurement.
Pricing Analysis
Cost-plus contracts with neodymium price indexation dominate component sourcing agreements between motor manufacturers and rare earth suppliers. Three-tier pricing structure across premium, standard, and economy levels separates carbon fiber professional rigs from aluminum mid-range units and plastic entry-level stabilizers. Pricing pressure stems from optical stabilization substitution in Apple and Samsung flagship handsets eroding casual user necessity. Entry-level buyers exhibit highest price sensitivity, while professional filmmakers prioritize motor response precision over unit cost.
Supply Chain Analysis
US export controls on advanced semiconductor manufacturing equipment constrain brushless motor controller chip flows to Chinese gimbal producers. Manufacturing concentrates in China, Vietnam, and Taiwan, with Shenzhen housing firmware development and Ho Chi Minh City hosting final assembly for cost-optimized units. Supply chains draw from Japanese inertial measurement units, South Korean lithium cells, and Chinese rare earth magnets. Single-source vulnerability sits with Kalman filter implementation expertise concentrated in Shenzhen labor pools. Distribution runs through platform-integrated subscription channels, direct-to-consumer storefronts, and traditional electronics retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smartphone gimbal demand sits in early-cycle expansion as platform monetization on TikTok, YouTube Shorts, and Instagram Reels pulls production quality investments from amateur creators into hardware upgrades.
For Market Incumbents: Build algorithmic moats through in-house gimbal control firmware and vertical manufacturing integration to defend against modular off-the-shelf motor controller substitution. Invest in EU AI Act compliance infrastructure for subject-tracking software documentation requirements. Secure platform partnership agreements with ByteDance and Meta to embed hardware specifications in creator program equipment packages.
For New Entrants and Emerging Players: Pursue Berlin and Munich's underpenetrated premium gimbal distributor gaps relative to per-capita influencer production activity. Target subscription rental channel infrastructure buildout in China and the United States where procurement shifts away from standalone retail purchases. Develop compact foldable designs optimized for airline carry-on compliance to capture travel vlogger white space.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier stabilizer brands lacking AI tracking capabilities and platform integration infrastructure. Five-to-ten year viability hinges on regulatory compliance infrastructure and creator economy channel control rather than pure hardware margin extraction. Watch FCC certification backlog resolution at accredited US labs as signal for connected gimbal model launch velocity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Subject Tracking Integration | EU AI Act algorithmic transparency requirements reshape software architecture for European market access. |
| Platform Partnership Development | ByteDance and Meta creator program equipment specifications drive hardware upgrade cycles among influencers. |
| Carbon Fiber Construction Adoption | Aerospace-grade composites reduce payload weight for broadcast-acceptable mobile cinematography applications. |
| Rental Channel Infrastructure Buildout | Subscription models in China and the United States compress traditional distributor margins and shift procurement patterns. |
| GB Battery Certification Investment | China's tightened thermal runaway testing accelerates certified product turnover and replacement demand cycles. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with product managers at stabilization hardware manufacturers, firmware engineers specializing in Kalman filter implementation, platform partnership directors at ByteDance and Meta, and creator economy procurement leads; and secondary validation through MIIT GB standard filings, FCC equipment authorization databases, EU AI Act implementation guidance, SEC 10-K disclosures from listed electronics manufacturers, and trade flow data from Chinese customs records. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing.
Forecast inputs span product type segmentation across 3-axis, 2-axis, and accessory mount categories; end-user archetypes from social media influencers through professional filmmakers; pricing tier dynamics from entry-level plastic construction through carbon fiber professional rigs; and regional adoption patterns across China, the United States, and Germany. CAGRs derive from regression analysis against platform monetization expansion rates and creator economy participation growth. Neodymium price volatility curves and FCC certification queue lengths inform supply-side constraint modeling.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending on electronics and platform advertising revenue share payouts to creators would shift the trajectory. Forecasts reflect assumptions around GB battery standard enforcement timelines and EU AI Act algorithmic transparency implementation phases. Material shifts in rare earth export restrictions or optical stabilization computational photography breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Process Equipment Market
Others
Japan Smart Home Market
Others
Digital Signage Media Player Market
Others
PCB Laminate Market
Others
Channel-In-A-Box (Ciab) Market
Others
Ammeters Market
Others
Molybdenum-99 Market
Others
Augmented Shopping Market
Others
Global Geotechnical Instrumentation and Monitoring Market
Others
Asia-Pacific Camping and Caravanning Market
Others
Global Simulation in Healthcare Market
Others
Wingboards Market
Others
Asia Pacific Foodservice Paper Packaging Market
Others
One-Way Degassing Valve Market
Others
Safety Critical Software Testing Market
Others
China Automotive LED Lighting Market