
 India Automotive LED Lighting Market | 2026-2036
India Automotive LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive LED Lighting Market Insights
Aftermarket distributors is unwinding share toward OEMs as vehicle manufacturers tighten specification control over lighting systems. Fiem Industries Ltd leverages captive manufacturing in Haryana to supply domestic passenger car programs. Lumax Industries anchors its position through backward integration into lamp housing and electronics. OSRAM GmbH competes on technology leadership in adaptive LED modules for premium vehicle platforms.
India Automotive LED Lighting comprises solid-state semiconductor devices emitting visible light when electrical current passes through a p-n junction, typically operating at 2-4 volts DC with luminous efficacy exceeding 100 lumens per watt, designed for exterior and interior vehicle illumination. The primary purpose is to enhance road safety through faster response times and superior beam control while reducing vehicle electrical load. Headlights command the largest value pool among product types as matrix LED configurations penetrate mid-range passenger cars. Electric vehicles represent the fastest-expanding vehicle type segment as battery-powered architectures prioritize energy-efficient lighting to preserve range.
BIS mandates CMVR certification for all automotive lighting assemblies sold in India, while the Ministry of Road Transport enforces AIS standards that specify photometric performance and durability testing. The PLI scheme for automobile and auto component manufacturing subsidizes capital investment in advanced lighting technology, directly expanding domestic production capacity. Stakeholders must monitor how AIS amendments incorporate adaptive driving beam requirements and whether state-level EV policies in Gujarat and Tamil Nadu mandate specific LED specifications for subsidy eligibility.
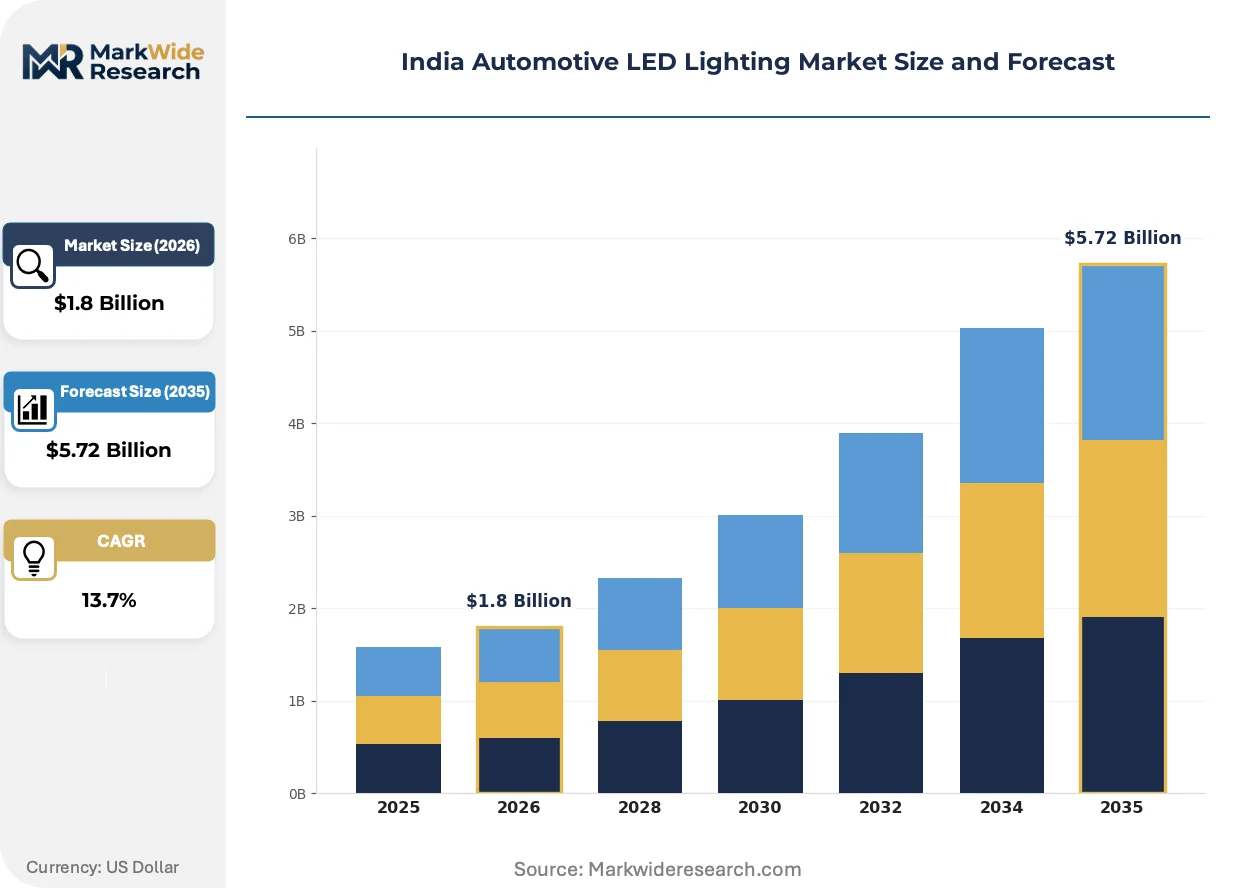
Market Dynamics
Electric vehicle platforms are rewiring specification hierarchies as battery architectures demand lighting systems that maximize energy efficiency while enabling advanced driver-assistance integration.
Growth Catalysts
- BIS CMVR certification mandates:The Bureau of Indian Standards enforces stricter photometric testing and durability protocols, eliminating substandard imports and consolidating demand around qualified domestic suppliers.
- Maharashtra-Pune manufacturing corridor:Concentrated automotive assembly capacity in this western belt generates localized procurement volumes that reduce logistics costs for tier-one lighting integrators.
- Matrix LED module adoption:Mid-range passenger car platforms are specifying adaptive beam configurations previously reserved for luxury segments, expanding addressable volume for advanced semiconductor packages.
Market Restraints
- Epitaxial wafer import dependence:Gallium nitride substrate supply concentrates among Taiwanese and Korean foundries, exposing domestic assemblers to currency volatility and shipping disruptions.
- AIS amendment lag:Automotive Industry Standards updates for adaptive driving beam specifications trail European UNECE regulations by multiple revision cycles, complicating platform export compatibility.
- Thermal management material costs:Aluminum-copper composite heat sinks and ceramic substrates face price pressure from competing electric motor and battery thermal applications.
Strategic Opportunities
- Tamil Nadu EV policy mandates:State-level electric vehicle subsidy eligibility criteria are incorporating specific LED efficacy thresholds, creating preferential procurement channels for certified suppliers.
- Two-wheeler underpenetration:Scooter and motorcycle segments retain significant halogen and CFL penetration, offering conversion runway as cost curves compress LED module pricing toward parity.
- LiDAR-LED convergence:Solid-state lighting arrays are integrating with optical sensing modules for autonomous navigation, opening adjacent revenue streams beyond illumination functionality.
Industry Challenges
- Optical design engineering scarcity:Specialized competence in free-form lens simulation and ray-tracing software remains concentrated among a limited pool of practitioners, constraining product development velocity.
- PLI scheme compliance complexity:Production-linked incentive documentation for automotive component qualification demands extensive localization proof and capital expenditure verification, extending approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive LED Lighting Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlights, Taillights, Fog Lights, Turn Signal Lights End User: OEMs, Aftermarket Distributors, Vehicle Manufacturers, Repair Workshops Technology: Matrix LED, Adaptive LED, Halogen, Xenon Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Electric Vehicles |
| Companies Covered | Fiem Industries Ltd, HELLA GmbH & Co KGaA, HYUNDAI MOBIS, Lumax Industries, Marelli Holdings Co Ltd, Neolite ZKW Lightings Pvt Ltd, OSRAM GmbH, Uno Minda Limited, Valeo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive LED Lighting Market Trends and Innovations
Lighting system architectures are fragmenting into distinct performance tiers as electric vehicle differentiation pressures force choices between cost-optimized and feature-rich configurations.
Adaptive driving beam technology is bifurcating the headlamp market into discrete segments. Matrix LED arrays with pixel-level control enable glare-free high beam operation through camera-fed dynamic masking. Maruti Suzuki and Hyundai Motor India are deploying these modules in mid-range SUVs as standard fitment. This capability compression is forcing halogen suppliers toward commercial vehicle niches while premium adaptive systems migrate downmarket.
BIS has tightened CMVR Type Approval procedures for LED retrofits and replacement assemblies, mandating electromagnetic compatibility testing and thermal cycle validation previously exempted for aftermarket products. The regulation disqualifies uncertified imports from e-commerce channels. Two-wheeler lighting suppliers face the steepest compliance adjustment, as their historical cost structures assumed minimal regulatory overhead.
Fleet operators and ride-hailing platforms are consolidating procurement decisions at the national level, bypassing traditional state-level distributor networks. Ola Electric and Ather Energy specify lighting modules directly through vendor-managed inventory arrangements with tier-one electronics manufacturers. This channel compression is most visible in Karnataka and Telangana, where electric two-wheeler registration density supports centralized sourcing scale.
India Automotive LED Lighting Market Segmentation
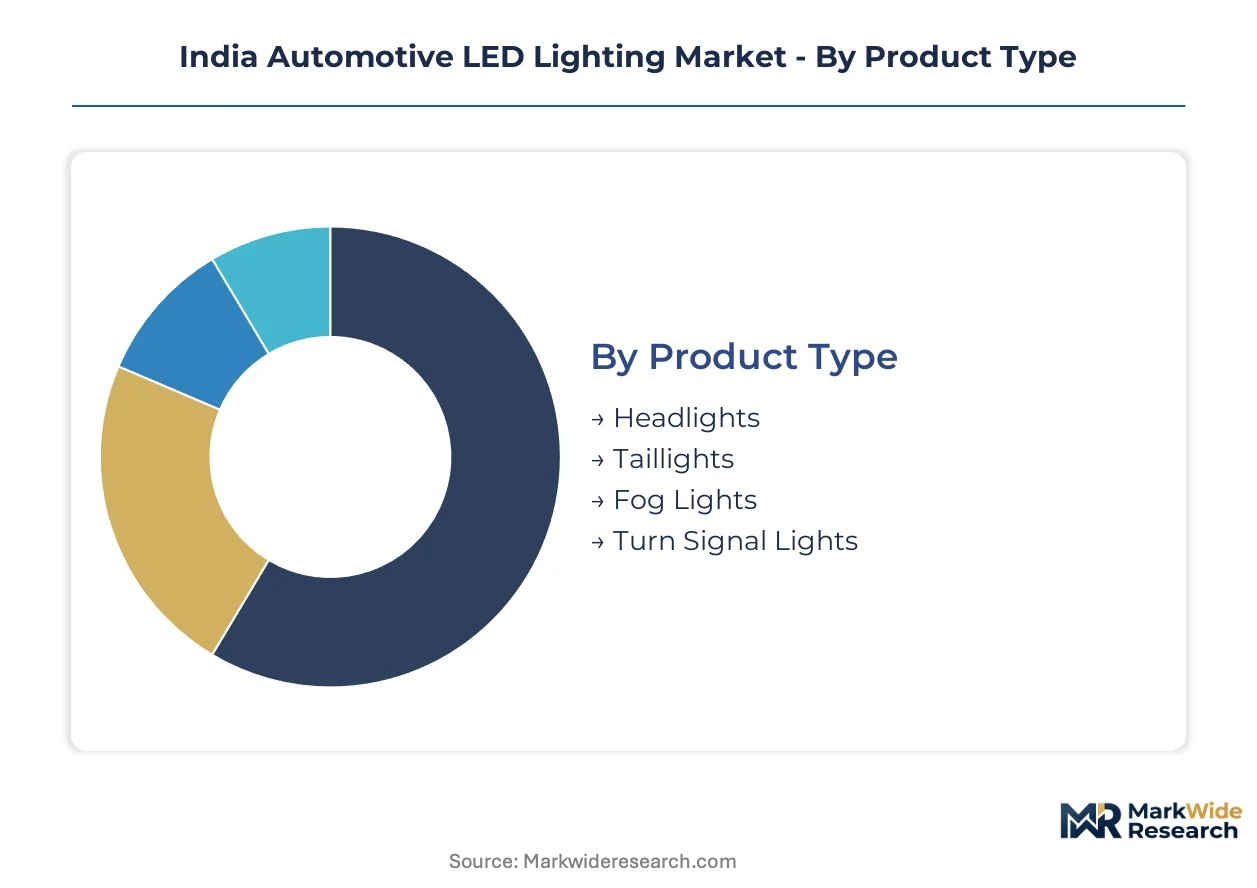
Segmentation reveals how specification control, certification requirements, and platform electrification are redistributing value across India's automotive lighting supply chain. Each dimension exposes different competitive moats and procurement vulnerabilities.
Product Type:
Headlights and taillights dominate domestic manufacturing capacity in Maharashtra and Tamil Nadu, while fog lights and turn signals retain higher import dependence from Southeast Asian assembly operations.
- Headlights:Matrix LED configurations with pixel-level beam control now penetrate mid-range SUVs from Maruti Suzuki and Hyundai Motor India. Maharashtra's tier-one integrators concentrate capacity here due to higher localization requirements under PLI schemes.
- Taillights:Sequential and animated rear lamp designs differentiate electric vehicle platforms from Ola Electric and Ather Energy. Tamil Nadu EV policy mandates specific LED efficacy thresholds that favor domestic certified suppliers over uncertified imports.
- Fog Lights:Lower specification tier with halogen-to-LED conversion runway in commercial vehicle retrofits.
- Turn Signal Lights:Regulatory minimums under CMVR certification; fastest response time specifications differentiate premium offerings.
Headlights hold the largest share; momentum sits with taillights as EV platforms prioritize rear signature differentiation.
End User:
Procurement authority is centralizing as vehicle manufacturers tighten specification control, compressing traditional distributor margins and favoring direct vendor-managed inventory arrangements.
- OEMs:Direct sourcing from tier-one electronics manufacturers now dominates electric two-wheeler programs in Karnataka and Telangana. Ola Electric and Ather Energy specify modules through captive supply arrangements that bypass state-level distributor networks.
- Vehicle Manufacturers:Passenger car assemblers in Pune and Chennai mandate BIS CMVR certification as non-negotiable entry criteria, disqualifying uncertified imports from e-commerce channels.
- Aftermarket Distributors:Share erosion accelerates as BIS tightens Type Approval for LED retrofits with electromagnetic compatibility testing.
- Repair Workshops:Consolidation into national fleet operator procurement programs reduces fragmented state-level demand.
Vehicle manufacturers command volume concentration; aftermarket distributors face the steepest structural compression.
Technology:
Cost curves and certification complexity are stratifying the technology landscape into three distinct performance tiers with minimal overlap in procurement channels.
- Matrix LED:Pixel-level glare-free high beam operation requires camera integration and specialized optical design engineering scarce in domestic talent pools. Premium mid-range SUV penetration forces halogen suppliers toward commercial vehicle niches.
- Adaptive LED:Dynamic beam adjustment for curved road illumination; AIS amendment lag versus UNECE regulations complicates platform export compatibility for European-bound vehicles.
- Halogen:Retained in price-sensitive two-wheeler segments and commercial vehicle retrofits where thermal management material costs pressure LED parity timelines.
- Xenon:Declining fitment as LED efficacy exceeds 100 lumens per watt at comparable cost structures.
Matrix LED captures premium positioning; adaptive LED represents the steepest expansion trajectory as mid-range platforms specification-up.
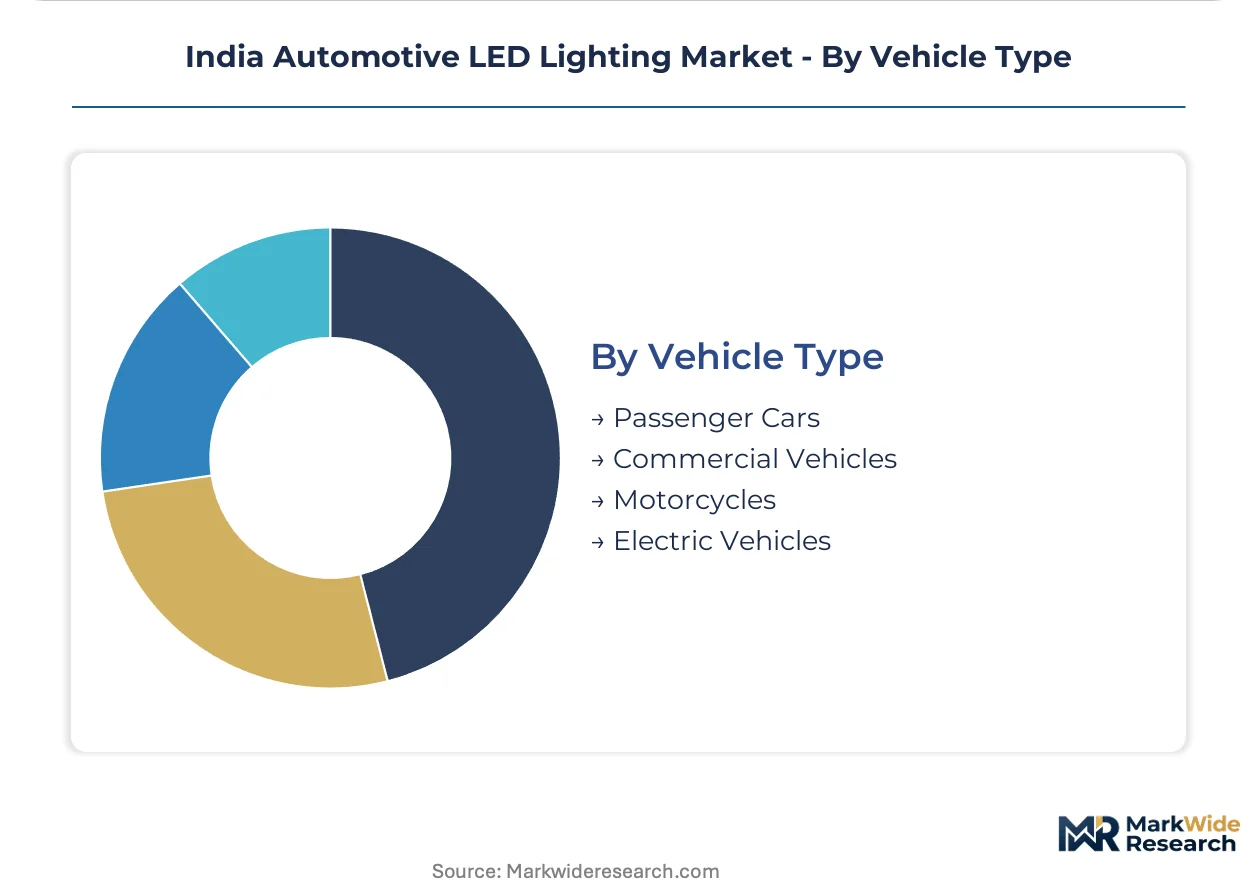
Vehicle Type:
Platform electrification is rewiring demand concentration toward battery architectures that prioritize energy-efficient lighting to preserve range.
- Electric Vehicles:Fastest-climbing segment as state-level policies in Gujarat and Tamil Nadu mandate LED specifications for subsidy eligibility. Battery thermal management competes for aluminum-copper composite heat sink supply.
- Passenger Cars:Mid-range SUV volume anchors matrix LED module adoption with standard fitment becoming specification baseline.
- Commercial Vehicles:Regulatory-driven retrofit demand from fleet operators consolidating procurement nationally.
- Motorcycles:Significant halogen and CFL penetration remains; cost curve compression toward LED parity drives conversion timing.
Passenger Cars anchor current volume; Electric Vehicles gain share fastest as platform launches accelerate through 2035.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic LED module assembly clusters around Maharashtra and Tamil Nadu, with tier-one integrators positioning captive facilities near passenger car and electric two-wheeler assembly plants. BIS certification requirements and PLI scheme incentives are redrawing procurement boundaries toward qualified domestic suppliers.
Maharashtra
Passenger car manufacturers in Pune and Mumbai generate concentrated demand for matrix LED headlamp modules. The state's automotive manufacturing belt hosts tier-one electronics integrators supplying Maruti Suzuki and Hyundai Motor India programs. BIS CMVR Type Approval enforcement has eliminated uncertified import channels for replacement assemblies.
Tamil Nadu
Electric vehicle policy mandates specific LED efficacy thresholds for subsidy eligibility, directing procurement toward certified domestic suppliers. Ola Electric and Ather Energy specify lighting modules through direct vendor-managed inventory arrangements. Chennai's electronics manufacturing corridor anchors backend assembly for rear lamp and interior illumination systems.
Karnataka
Electric two-wheeler registration density in Bengaluru supports centralized sourcing scale for national fleet operators. Ride-hailing platforms consolidate procurement decisions, bypassing traditional state-level distributor networks. The state's EV policy framework influences specification standards adopted by adjacent markets.
Haryana
Fiem Industries Ltd leverages captive manufacturing facilities to supply domestic passenger car programs with localized content meeting PLI scheme requirements. The National Capital Region proximity enables logistics efficiency for northern India vehicle assembly operations. Component suppliers face thermal management material cost pressure from competing battery and electric motor applications.
Gujarat
State-level electric vehicle policies mandate LED specifications for commercial subsidy programs, creating preferential procurement channels. The western corridor's port infrastructure supports import of epitaxial wafer substrates from Taiwanese and Korean foundries. Currency volatility exposure concentrates among assemblers dependent on gallium nitride supply.
India Automotive LED Lighting Market Competitive Landscape
Concentration sits with diversified automotive electronics conglomerates possessing captive lighting divisions and tier-one supplier status with major vehicle manufacturers. The market structure tiers into three archetypes: integrated lamp manufacturers controlling housing and electronics production, technology licensors supplying semiconductor packages and adaptive beam software, and regional specialists serving cost-optimized two-wheeler and commercial vehicle segments. Dominant competitive moves include backward integration into lamp housing manufacturing and strategic positioning for PLI scheme qualification through localization proof documentation.
Among India-based integrated manufacturers, Fiem Industries Ltd and Lumax Industries occupy positions representing the captive production archetype, while OSRAM GmbH anchors the technology licensing tier for premium adaptive LED modules. These three exemplify how competitive positioning stratifies across certification compliance, manufacturing scale, and semiconductor package sophistication.
| Leading Market Players |
|---|
| Fiem Industries Ltd |
| HELLA GmbH & Co KGaA |
| HYUNDAI MOBIS |
| Lumax Industries |
| Marelli Holdings Co Ltd |
| Neolite ZKW Lightings Pvt Ltd |
| OSRAM GmbH |
| Uno Minda Limited |
| Valeo |
| Others |
Pricing and Supply Chain Analysis
BIS CMVR certification operates as the primary gating mechanism for both supply qualification and price differentiation, bifurcating the market into certified domestic suppliers commanding premium positioning and uncertified imports competing on cost alone.
Pricing Analysis
BIS CMVR certification dictates the pricing tier structure across India's automotive LED lighting landscape. Three-tier pricing structure across premium, standard, and economy levels separates matrix LED modules with adaptive beam control from conventional LED assemblies and halogen replacements. Cost compression in the economy tier is intensifying because two-wheeler manufacturers resist specification upgrades. Fleet operators and commercial vehicle buyers exhibit highest price sensitivity, while premium passenger car OEMs prioritize performance metrics over unit economics.
Supply Chain Analysis
Vendor-managed inventory arrangements now compress lead times for tier-one integrators supplying electric vehicle programs in Karnataka and Telangana. Epitaxial wafer supply concentrates in Taiwan and South Korea, while lamp housing and electronics assembly clusters in Maharashtra and Tamil Nadu. Gallium nitride substrate dependence exposes domestic assemblers to currency volatility and shipping disruptions. Distribution runs through direct OEM procurement channels that bypass traditional state-level distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's automotive LED lighting sector represents a high-growth disruption as electric vehicle platform launches and BIS certification tightening simultaneously reshape competitive boundaries and procurement authority.
For Market Incumbents: Compound defensive positioning through backward integration into lamp housing manufacturing and accelerated PLI scheme qualification documentation. Matrix LED capability gaps among emerging competitors create temporary moats, though thermal management material cost pressure from battery and electric motor applications demands upstream control over aluminum-copper composite heat sink supply. For New Entrants and Emerging Players: Aftermarket retrofit certification backlogs present service-layer gaps where incumbents under-serve independent repair workshops struggling with BIS electromagnetic compatibility testing requirements. Two-wheeler halogen-to-LED conversion runway offers the most penetrable volume segment. Pursue white-label manufacturing partnerships with Tamil Nadu and Gujarat EV policy-certified suppliers to bypass direct certification timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed tier-two electronics assemblers possessing BIS certification but lacking matrix LED optical design engineering competence. Five-to-ten year viability hinges on adaptive driving beam specification migration downmarket. Monitor AIS amendment cycles for adaptive driving beam alignment with UNECE regulations as the critical inflection signal for export-compatible platform investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lamp Housing | Lumax Industries and Fiem Industries anchor margins through captive housing production meeting PLI localization thresholds. |
| Matrix LED Module Localization | Domestic pixel-level beam control assembly reduces import dependence for Maruti Suzuki and Hyundai Motor India programs. |
| PLI Scheme Qualification Acceleration | Extensive documentation of capital expenditure and localization proof extends approval timelines for tier-two suppliers. |
| Vendor-Managed Inventory Partnerships | Ola Electric and Ather Energy bypass distributor networks through direct tier-one electronics manufacturer arrangements. |
| Optical Design Engineering Acquisition | Free-form lens simulation and ray-tracing software competence remains scarce, constraining product development velocity. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with tier-one supplier procurement officers, OEM platform engineers, aftermarket distributors, and BIS certification specialists; and secondary validation through vehicle production databases, IHS Markit registration data, PLI scheme disclosure filings, and AIS amendment documentation. Bottom-up and top-down triangulation cross-referenced module-level pricing intelligence against aggregate vehicle segment forecasts.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from trend extrapolation of electric vehicle platform launch schedules and matrix LED specification migration patterns. Industry-specific forecast inputs incorporated BIS CMVR certification pipeline velocities and state-level EV policy efficacy threshold adjustments.
Forecasts assume regulatory continuity in BIS CMVR certification regimes and PLI scheme incentive structures; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Electric Vehicle High-Voltage Cables Market
Automotive Electrical & Electronics
Automotive Pressure Sensors Market
Automotive Electrical & Electronics
Europe Electric Power Steering Market
Automotive Electrical & Electronics
Automotive UPS (in Vehicle UPS) Market
Automotive Electrical & Electronics
Steering Wheel Switches Market
Automotive Electrical & Electronics
Automotive Ultracapacitor Market
Automotive Electrical & Electronics
South Korea Automotive Electric Actuators Market
Automotive Electrical & Electronics
Africa and Middle East Automotive Tpms Market
Automotive Electrical & Electronics
Japan X by Wire Systems Market
Automotive Electrical & Electronics
Japan Automotive EPS Market
Automotive Electrical & Electronics
Automotive Speed Sensor Market
Automotive Electrical & Electronics
Global Automotive Engine Coolant Temperature Sensor Market
Automotive Electrical & Electronics
China Automotive Electric Power Steering (EPS) Market
Automotive Electrical & Electronics
Automotive Esim Market
Automotive Electrical & Electronics
Jump Starter Market
Automotive Electrical & Electronics
India Automotive Camera Market