
 Global Magnetic Flow Meters Market | 2026-2036
Global Magnetic Flow Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Magnetic Flow Meters Market Outlook
Project finance for smart water infrastructure is narrowing the competitive field to firms with balance-sheet capacity for long-dated utility contracts. Siemens AG leverages its electromechanical manufacturing scale to bid on integrated plant automation packages that bundle magnetic flow meters with SCADA systems. Endress+Hauser AG anchors its position through dense calibration service networks that lock in replacement cycles across European chemical clusters. Krohne Group competes on marine-certified designs that dominate ballast water treatment retrofits for oceangoing vessels.
A magnetic flow meter measures conductive fluid velocity via Faraday's law of electromagnetic induction, with typical accuracy of ±0.2% and no moving parts, making it ideal for corrosive slurries and untreated wastewater. Inline installations sustain the largest revenue pool due to permanent placement in treatment plant mains and refinery process lines. Battery-operated wireless units represent the fastest-expanding technology segment as oilfield operators and remote water districts abandon trenching costs for signal cabling. Multi-parameter configurations that combine flow, temperature, and conductivity sensing command premium positioning in pharmaceutical and food-grade applications where single-instrument validation reduces audit burden.
The EPA enforces Clean Water Act discharge limits that mandate continuous flow monitoring at municipal outfalls, while the EU Urban Wastewater Treatment Directive drives replacement of mechanical meters with electromagnetic alternatives across member states. IEC 62053 and OIML R49 certification requirements create compliance barriers that favor established laboratories with accredited test facilities. Stakeholders must weigh the capital cost of full-bore electromagnetic replacements against the operational savings from eliminated strainer maintenance and extended calibration intervals.
Market Dynamics
Wireless telemetry integration is compressing replacement cycles across municipal water districts and upstream oilfield operations, forcing incumbent suppliers to reconfigure service revenue models around predictive maintenance rather than periodic calibration visits.
Growth Catalysts
- EPA Clean Water Act mandates:Continuous discharge monitoring requirements at municipal outfalls in the United States are accelerating electromagnetic meter retrofits in legacy treatment infrastructure.
- Permian Basin wireless deployments:Battery-powered units eliminate trenching costs for signal cabling across remote wellpad gathering systems, cutting installed cost by half versus conventional hardwired configurations.
- EU Urban Wastewater Treatment Directive:Mechanical meter phase-out deadlines in Germany, France, and the Netherlands are pulling forward replacement demand across combined sewer networks.
Market Restraints
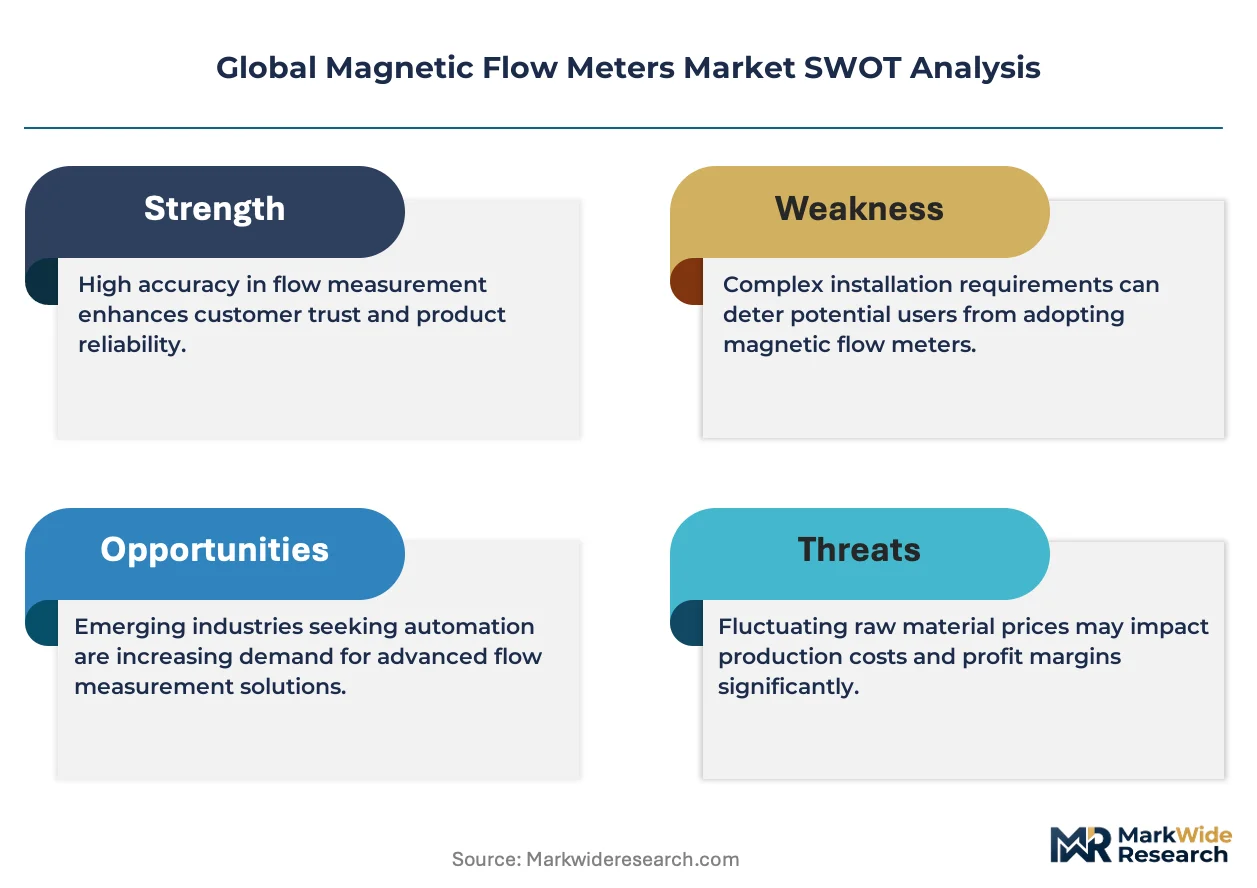
- Copper and rare-earth magnet cost volatility:Fluctuations in neodymium prices and copper conductor costs compress gross margins for manufacturers unable to pass through material swings via indexed contracts.
- Calibration laboratory concentration:IEC 62053 and OIML R49 accreditation is concentrated among established European and North American test facilities, creating bottlenecks for new market entrants seeking certification.
- Ultrasonic flow meter substitution:Clamp-on ultrasonic alternatives are capturing share in clean fluid applications where conductivity requirements exclude electromagnetic technology.
Strategic Opportunities
- India municipal water automation:Smart city initiatives under the AMRUT scheme are opening tender opportunities for integrated flow monitoring across distribution networks in Bangalore, Chennai, and Pune.
- Multi-parameter sensor convergence:Combined flow-temperature-conductivity instruments are commanding premium positioning in pharmaceutical clean-in-place validation where single-instrument qualification reduces audit burden.
- Marine ballast water treatment retrofits:IMO D-2 compliance deadlines are driving demand for marine-certified electromagnetic designs in shipyards across South Korea and Japan.
Industry Challenges
- Field calibration technician scarcity:Specialized expertise in electromagnetic meter verification against gravimetric standards is concentrated among aging workforces in European chemical clusters.
- Legacy SCADA protocol fragmentation:Integration with proprietary automation architectures in refinery and chemical plant environments requires costly custom gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Magnetic Flow Meters Market |
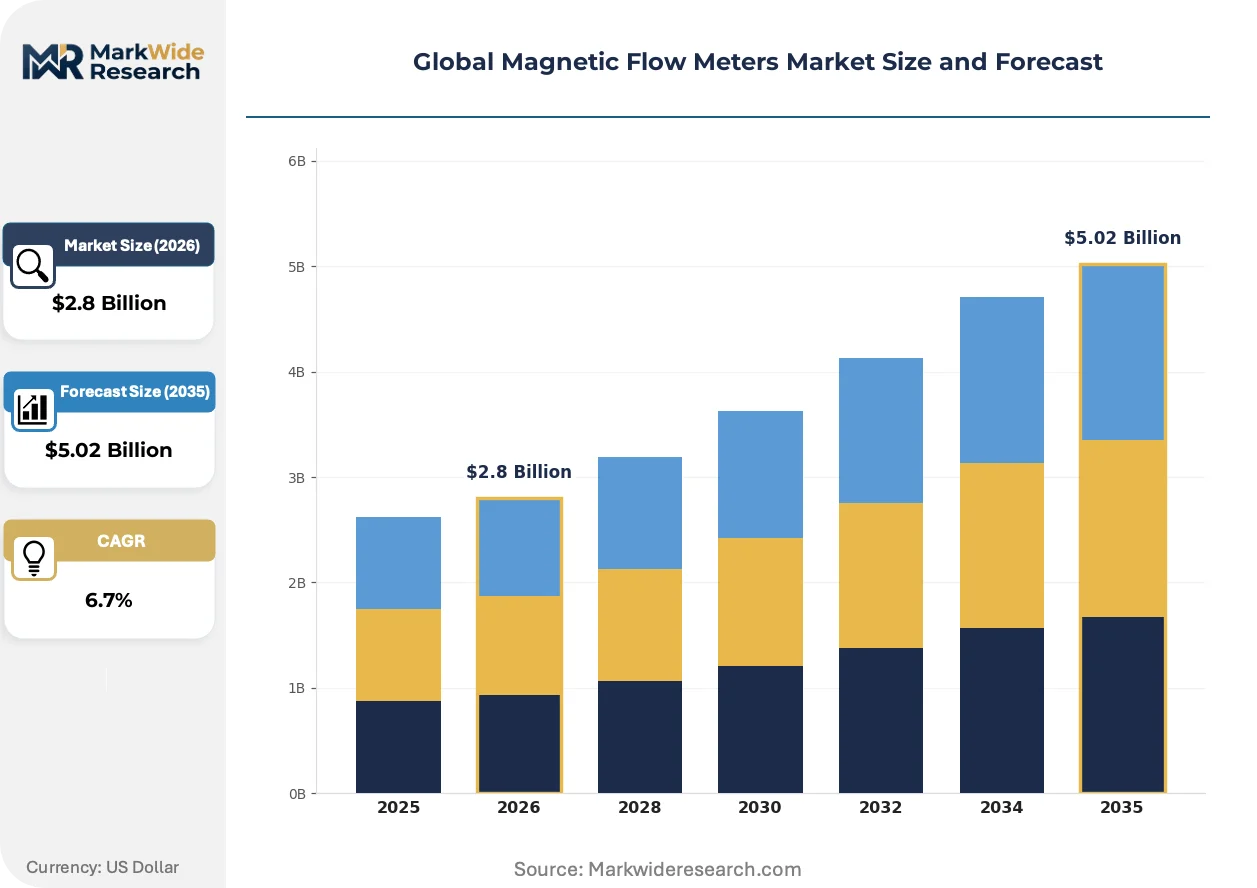
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Inline, Compact, Multi-Parameter End User: Water & Wastewater, Oil & Gas, Chemical, Food & Beverage Installation Type: Vertical, Horizontal, Flush Mount, Submersible Technology: Battery Operated, Electromagnetic, Wireless, Analog |
| Companies Covered | ABB Ltd, Emerson Electric Co., Endress+Hauser AG, Siemens AG, Yokogawa Electric Corporation, Honeywell International Inc., Krohne Group, Badger Meter, Inc., Azbil Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Magnetic Flow Meters Market Strategic Shifts
Edge computing architectures are embedding diagnostic intelligence directly into transmitter electronics, enabling shift from reactive maintenance schedules toward condition-based intervention triggers.
Digital twin calibration is digitizing field verification workflows by comparing live sensor outputs against physics-based flow models, reducing technician dispatch requirements. Water utilities in Denmark and Singapore are deploying these virtual reference systems across district metering areas. The approach compresses calibration intervals from annual to event-triggered while maintaining regulatory traceability.
REACH substance restrictions on electronic component chemistries are forcing reformulation of potting compounds and conformal coatings used in submersible transmitter housings. European meter manufacturers are qualifying alternative epoxy systems ahead of sunset dates for legacy flame retardants. The transition is lengthening new product qualification cycles by six to nine months for instruments destined for EU member states.
Asset-as-a-service contracting is restructuring capital deployment patterns among North American municipal utilities facing rate-case limitations. Third-party ownership models bundle hardware, installation, and maintenance into per-gallon charges that bypass traditional debt capacity constraints. The structure is penetrating fastest among smaller water districts in Texas and Arizona with limited bonding authority.
Global Magnetic Flow Meters Market Segmentation
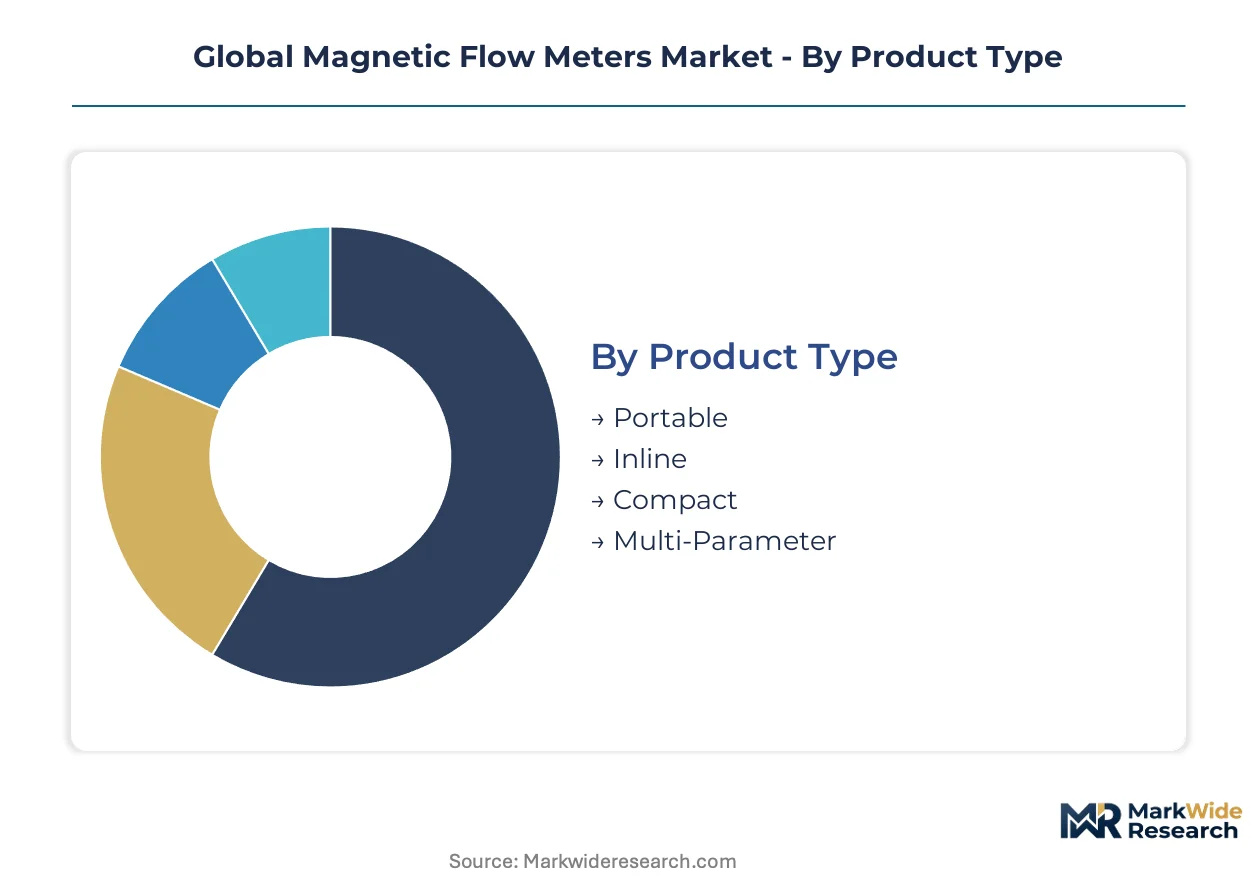
Magnetic flow meter procurement cycles vary dramatically across product architectures, with permanent infrastructure installations demanding decade-long capital planning while portable and wireless units refresh on compressed timelines driven by field obsolescence and telemetry upgrades.
Product Type:
Replacement velocity separates permanent plant infrastructure from mobile instrumentation, with some configurations requiring full process shutdowns while others swap in minutes.
- Inline:Full-bore flanged meters integrate permanently into treatment plant mains and refinery process headers. German municipal utilities under EU Urban Wastewater Treatment Directive mandates are replacing legacy mechanical units with electromagnetic inline designs across combined sewer networks.
- Portable:Clamp-on verification units enable spot-check auditing without pipe penetration. Water districts in Texas and Arizona deploy these for temporary flow surveys during rate-case validation studies.
- Compact:Short-face-to-face designs fit constrained skid packages and OEM equipment. Chemical OEMs in the Permian Basin specify these for modular wellpad treatment systems.
- Multi-Parameter:Combined flow-temperature-conductivity instruments reduce sensor count in pharmaceutical clean-in-place loops.
Inline configurations anchor the volume base while portable units gain share at the steepest rate as verification-as-a-service contracts proliferate.
End User:
Regulatory enforcement intensity creates divergent procurement patterns, with effluent-monitored sectors pulling forward replacement demand while process industries extend calibration intervals.
- Water & Wastewater:Municipal utilities face EPA Clean Water Act continuous monitoring mandates at discharge outfalls. United States treatment plants are retrofitting electromagnetic meters into legacy headworks and effluent channels.
- Oil & Gas:Upstream operators prioritize battery-powered wireless units for remote gathering systems. North Sea platforms and Permian Basin wellpads eliminate trenching costs through self-contained telemetry.
- Chemical:Corrosive slurry handling favors electromagnetic designs over mechanical alternatives in European chemical clusters.
- Food & Beverage:Sanitary-grade meters with tri-clamp connections serve clean-in-place validation requirements in dairy and brewing applications.
Water and wastewater anchors the volume base while oil and gas gains share at the steepest rate as wireless field instrumentation displaces hardwired legacy.
Installation Type:
Orientation constraints drive specification divergence between gravity-fed networks and pressurized process circuits, with mounting geometry directly affecting electrode fouling risk and maintenance accessibility.
- Horizontal:Standard pipeline orientation dominates municipal distribution and industrial process lines. Full-bore designs in this configuration sustain the largest replacement parts revenue pool.
- Vertical:Upward flow orientation prevents air pocket accumulation in partially filled pipes. Wastewater lift stations in the Netherlands specify vertical meters for variable-level wet well applications.
- Flush Mount:Recessed installations protect electrodes from abrasive mining slurries and dredging operations.
- Submersible:IP68-rated transmitters withstand permanent immersion in open channel and sump applications.
Horizontal installations anchor the volume base while vertical configurations gain share at the steepest rate as combined sewer overflow monitoring expands.
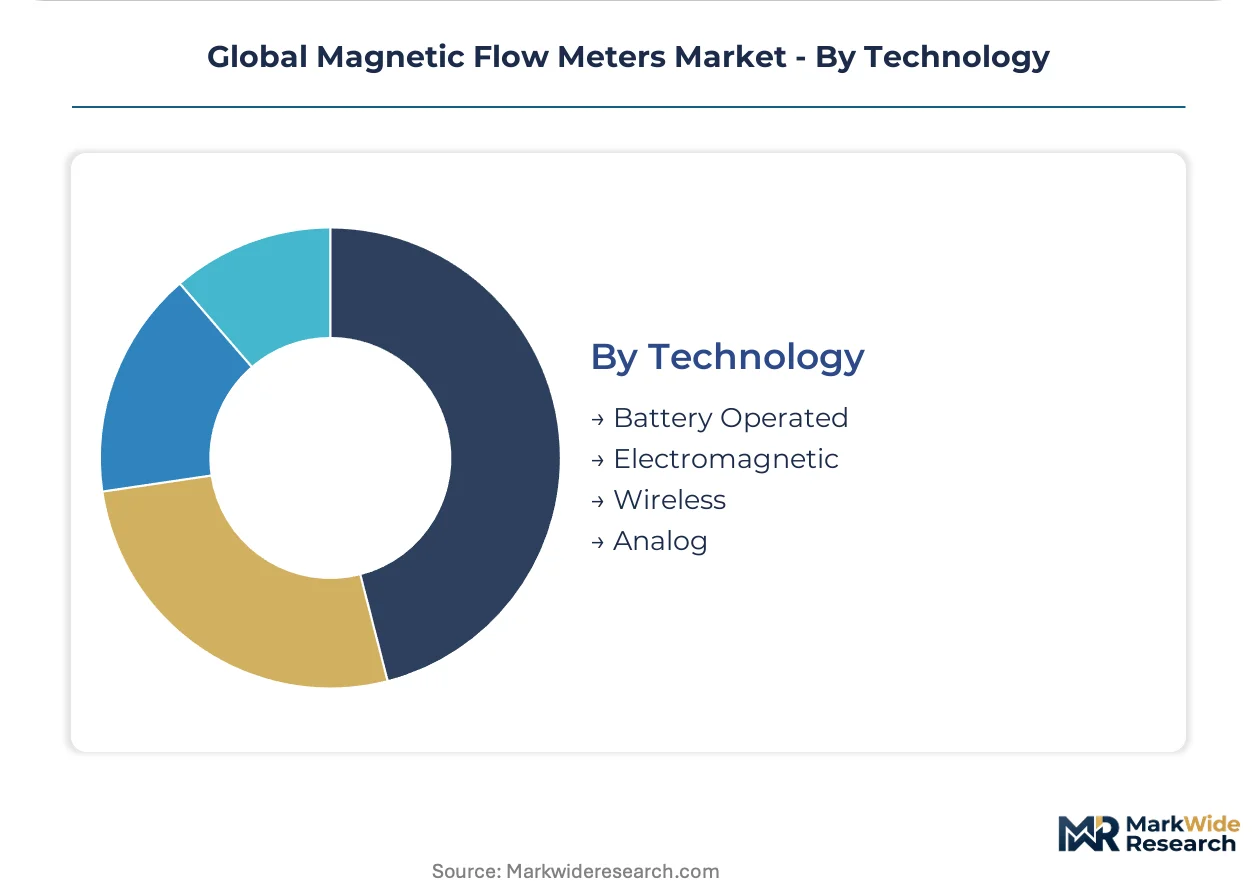
Technology:
Power and signal architecture choices determine total installed cost, with trenching and cabling expenses often exceeding hardware acquisition in remote deployments.
- Electromagnetic:Faraday induction measurement achieves ±0.2% accuracy without moving parts. This core technology dominates corrosive and abrasive fluid applications across municipal and industrial sectors.
- Wireless:Battery-powered telemetry eliminates signal cable infrastructure. Oilfield operators in the Permian Basin cut installed costs substantially versus conventional hardwired configurations.
- Battery Operated:Self-contained power enables deployment where grid access is unavailable. Remote water districts in Texas favor these for transmission main monitoring.
- Analog:4-20mA output signals persist in legacy SCADA integrations requiring minimal protocol translation.
Electromagnetic technology anchors the volume base while wireless configurations gain share at the steepest rate as predictive maintenance platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Urban Wastewater Treatment Directive mandates and EPA Clean Water Act enforcement are accelerating electromagnetic meter retrofits across municipal utilities, while battery-powered wireless units gain traction in remote oilfield and offshore applications.
United States
EPA discharge monitoring requirements at municipal outfalls drive continuous flow instrumentation upgrades. The Clean Water Act mandates push treatment plants in Texas and Arizona toward electromagnetic replacements of legacy mechanical units. Permian Basin operators deploy battery-operated wireless meters to eliminate trenching costs across remote wellpad gathering systems.
Germany
Combined sewer network modernization under EU directive deadlines concentrates demand in industrial municipalities. REACH substance restrictions on electronic component chemistries extend qualification cycles for submersible transmitter housings. Chemical clusters in North Rhine-Westphalia anchor replacement demand for corrosive slurry handling applications.
China
Smart city water automation initiatives expand distribution network monitoring in major metropolitan areas. National standards for wastewater treatment plant upgrading accelerate electromagnetic meter adoption. Yangtze River Delta municipalities pilot digital twin calibration systems across district metering areas.
India
AMRUT scheme smart city tenders open integrated flow monitoring opportunities in Bangalore, Chennai, and Pune. Central Electricity Authority guidelines influence telemetry architecture specifications for municipal automation projects. Maharashtra and Gujarat industrial corridors drive demand for process-grade electromagnetic instrumentation.
Japan
Shipyards in South Korea and Japan face IMO D-2 compliance deadlines for marine ballast water treatment retrofits. METI industrial efficiency programs encourage predictive maintenance platforms in chemical and refining operations. Osaka-Kobe manufacturing belt sustains demand for high-accuracy process instrumentation.
Global Magnetic Flow Meters Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent procurement pathways. Project finance for smart water infrastructure narrows the competitive field to firms with balance-sheet capacity for long-dated utility contracts. Three archetypes dominate: electromechanical conglomerates bundling meters with automation systems, calibration-service specialists locking replacement cycles, and marine-certified designers capturing vessel retrofit demand. Consolidation pressure intensifies through strategic partnerships and geographic expansion moves.
Among European-headquartered electromechanical groups, Siemens AG exemplifies the integrated automation archetype, while Endress+Hauser AG occupies the service-network specialist position. Krohne Group represents the marine-certified design tier. These three anchors illustrate how competitive positioning fragments across bundled system sales, recurring calibration revenue, and compliance-driven retrofit specifications.
| Leading Market Players |
|---|
| ABB Ltd |
| Emerson Electric Co. |
| Endress+Hauser AG |
| Siemens AG |
| Yokogawa Electric Corporation |
| Honeywell International Inc. |
| Krohne Group |
| Badger Meter, Inc. |
| Azbil Corporation |
| Others |
Value Chain & Pricing Dynamics
Neodymium magnet production concentrated in China and rare-earth processing facilities in Inner Mongolia directly determine margin allocation between transmitter manufacturers and downstream system integrators bidding on municipal automation contracts.
Pricing Analysis
Certification level creates the primary spread between premium IEC 62053-accredited units and economy-grade alternatives lacking OIML R49 traceability. Three-tier pricing structure across premium, standard, and economy levels reflects calibration laboratory proximity and bundled service terms. Cost compression in the economy tier is intensifying because copper conductor volatility erodes fixed-price contract profitability. Municipal utilities with rate-case constraints exhibit highest price sensitivity, while pharmaceutical clean-in-place applications tolerate premium positioning for single-instrument validation.
Supply Chain Analysis
Copper conductor feedstock draws from Chilean mining operations and Chinese smelting capacity, while neodymium magnets hinge on rare-earth extraction in Inner Mongolia and separation facilities across Jiangxi province. Electronics-grade epoxy potting compounds source from German and Japanese specialty chemical producers. Single-source vulnerability concentrates in IEC 62053 test facility accreditation, where European and North American laboratories control certification throughput. Distribution runs through authorized instrumentation distributors serving municipal procurement offices and industrial OEM specification teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal utility consolidation into regional water authorities is shifting procurement leverage toward buyers with multi-year framework contract capacity, compressing vendor margins and favoring balance-sheet-heavy suppliers.
For Market Incumbents: Harden calibration service network density around European chemical clusters to lock replacement cycles against ultrasonic substitution threats. Deepen backward integration into neodymium magnet supply through long-term offtake agreements with Chinese rare-earth processors, insulating margin from commodity swings that erode fixed-price municipal contract profitability. For New Entrants and Emerging Players: Build out marine-certified electromagnetic designs targeting IMO D-2 retrofit demand at South Korean and Japanese shipyards, where incumbent capacity constraints create specification gaps. Target India's AMRUT smart city tenders through localized assembly partnerships that bypass IEC 62053 accreditation bottlenecks for initial market entry. For Investors and Strategic Acquirers: Capital is best deployed toward calibration-service specialists with dense European laboratory networks, as predictive maintenance platforms extend replacement intervals and concentrate recurring revenue in verification capabilities. Watch wireless telemetry adoption curves in Permian Basin oilfield deployments as inflection indicator for technology shift timing.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | Dense laboratory accreditation locks municipal replacement cycles against ultrasonic competitors in German chemical clusters. |
| Wireless Telemetry Platform Development | Battery-powered units eliminate trenching costs for Permian Basin operators and remote water districts. |
| Marine Certification Investment | IMO D-2 compliance deadlines at South Korean shipyards create specification-driven retrofit demand. |
| Digital Twin Calibration Deployment | Virtual reference systems compress technician dispatch requirements for Denmark and Singapore utilities. |
| Asset-as-a-Service Contracting | Third-party ownership models bypass rate-case limitations for Texas and Arizona water districts. |
Study Parameters
Desk research of customs trade data, SEC instrument manufacturer filings, and EPA enforcement databases preceded structured interviews with municipal water utility procurement directors, industrial plant engineers, calibration laboratory technicians, and oilfield automation specialists. Primary fieldwork with OEM specification teams and aftermarket service heads validated secondary estimates of replacement cycle timing. Bottom-up unit shipment modeling triangulated against top-down project pipeline aggregation across documented municipal tender awards.
Fixed regulatory enforcement intensity held constant across the projection horizon, while wireless telemetry adoption curves and copper price trajectories were varied in sensitivity scenarios. Segmentation dimensions spanned product architecture, end-use sector, installation orientation, and power architecture. CAGRs were derived from fitted logistic curves on technology substitution patterns, with neodymium price forecasts and municipal capital expenditure cycles as key variable inputs.
Sensitivities concentrate around EPA enforcement intensity variations, EU Urban Wastewater Treatment Directive deadline shifts, and rare-earth export policy changes from Chinese regulators. Cross-checking against documented municipal tender award values and instrument manufacturer order backlog disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Qatar Smartphone Market
Others
Pin Mills Market
Others
Industrial PC Market
Others
Liposomes Market
Others
China Automotive LED Lighting Market
Others
Saudi Arabia Laser Hair Removal Market
Others
Baking Paper Market
Others
Cat Food Market
Others
Smart Plug Market
Others
China Smart Home Market
Others
Retail Media Platform Market
Others
Underwater Communication System Market
Others
Asia-Pacific Medium-Density Fiberboard Market
Others
Aircraft Exterior Lighting Market
Others
Voice Controlled Devices Market
Others
Video-As-A-Service (Vaas) Market