
 Connected TV Market | 2026-2036
Connected TV Market Size, Share, and Industry Trends Forecast 2026-2036
Connected TV Market Analysis
Programmatic advertising integration is reconfiguring how content monetization layers onto hardware ecosystems. Samsung Electronics leverages its display manufacturing scale to control silicon-to-screen value chains. Amazon anchors living-room commerce through voice-activated purchasing interfaces. Roku competes by sustaining an OS-agnostic platform that aggregates fragmented streaming subscriptions.
A Connected TV denotes an internet-enabled display or peripheral device capable of receiving, decoding, and rendering digital video streams through embedded processors, typically supporting resolutions from HD through 8K with HDR color gamuts, and designed primarily for consumer entertainment and commercial signage applications. Smart TVs dominate unit economics due to integrated processing and declining panel costs, while streaming devices capture upgrade cycles in legacy display installed bases. Subscription services concentrate margin pools through recurring revenue structures, though ad-supported content is expanding fastest among price-sensitive cohorts.
The FCC governs broadband infrastructure standards that underpin streaming quality of service, while the EU AI Act and GDPR constrain automated content recommendation and viewer data harvesting practices. Brazil's ANVISA and national telecom regulator shape device certification and over-the-top bandwidth allocation in Latin America's largest addressable market. Stakeholders must monitor how fragmented privacy enforcement across jurisdictions fragments addressable advertising inventory and forces platform-level compliance investments.
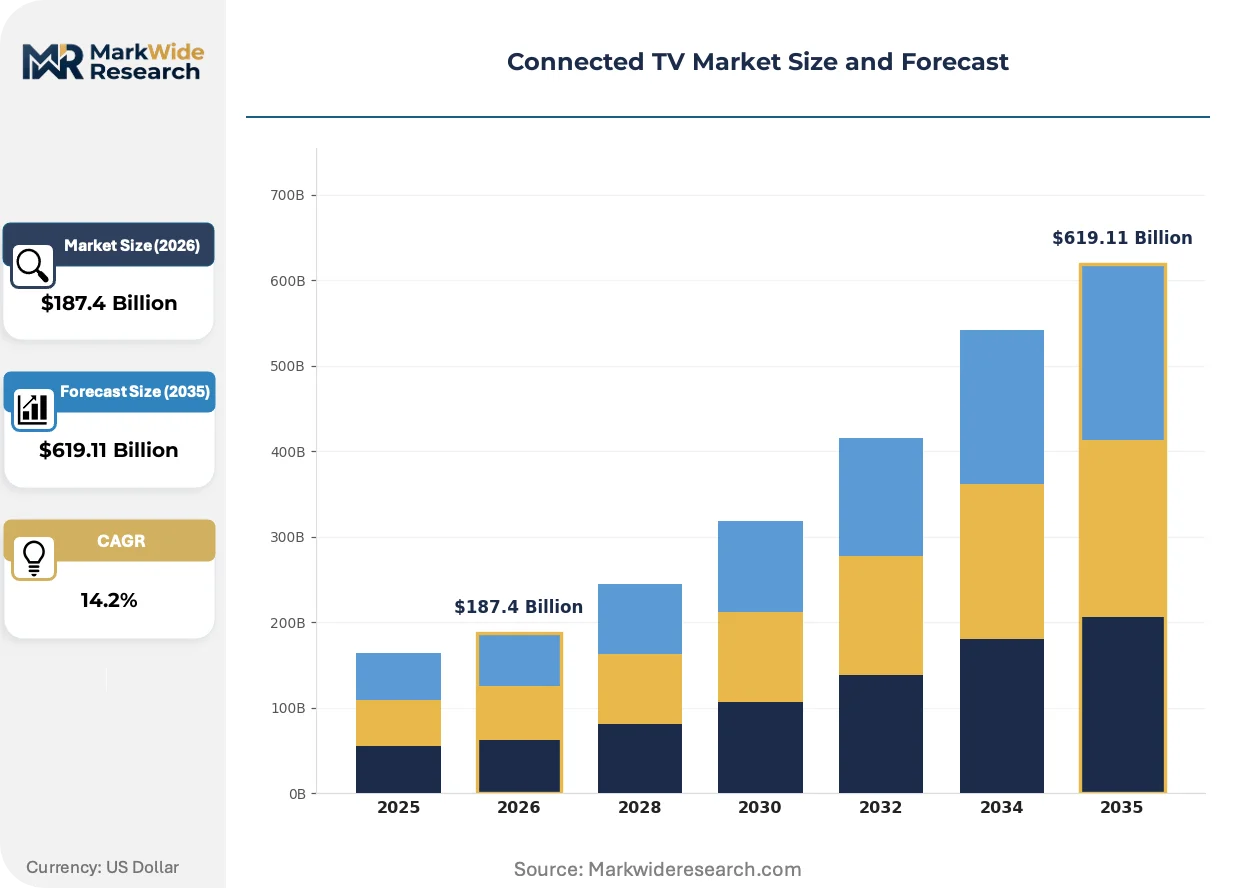
Market Dynamics
Programmatic advertising integration is compressing traditional sales cycles and forcing hardware manufacturers to build real-time bidding infrastructure directly into television operating systems.
Growth Catalysts
- Ad-Supported Video on Demand (AVOD) Expansion:Price-sensitive viewers across Brazil, India, and Southeast Asia are migrating from subscription fatigue toward free streaming tiers. AVOD inventory commands premium CPMs as advertisers chase cord-cutting audiences.
- FCC Broadband Infrastructure Investment:The US regulator's quality-of-service mandates are expanding fiber-to-the-home penetration. Streaming reliability improvements reduce subscriber churn for over-the-top platforms.
- 8K Panel Cost Curves:Display manufacturing scale in South Korea and Taiwan is collapsing premium-tier pricing. Consumer upgrade cycles compress as resolution differentiation becomes accessible.
Market Restraints
- GDPR and EU AI Act Compliance Costs:European privacy frameworks impose granular consent mechanisms for viewer data harvesting. Platform engineering teams must rebuild recommendation algorithms around anonymized cohorts rather than individual profiles.
- Silicon Supply Concentration in Taiwan:System-on-chip fabrication for smart TV processors clusters with TSMC and MediaTek. Geopolitical friction or capacity constraints propagate directly into hardware shipment delays.
- Linear Broadcast Substitution Ceiling:Sports and live news programming retain exclusive carriage agreements with traditional distributors. Streaming fragmentation forces households to maintain multiple subscriptions or revert to antenna-based reception.
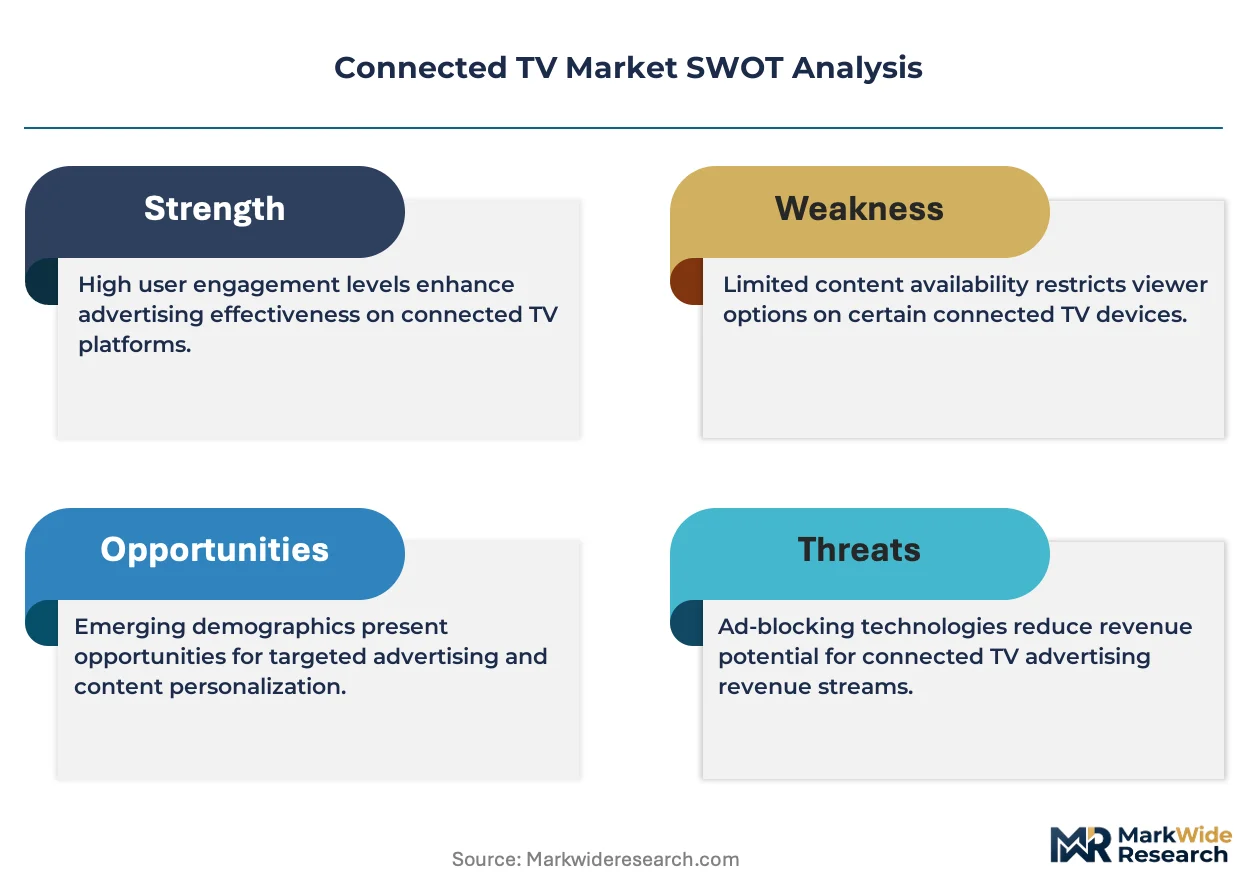
Strategic Opportunities
- Voice-Activated Commerce Integration:Living-room purchasing interfaces merge television viewing with frictionless checkout. Retail platforms capture impulse conversion from product placement and interactive advertising.
- ANVISA Device Certification Pathways in Brazil:Latin America's largest addressable market streamlines hardware approval timelines. First-movers establish platform dominance before regulatory harmonization spreads regionally.
- Hybrid Broadcast-Broadband (HbbTV) Standardization:European broadcasters merge terrestrial signal reliability with internet-delivered interactivity. The convergence creates addressable advertising inventory within traditional channel bundles.
Industry Challenges
- Cross-Platform Measurement Standardization:Advertisers demand unified viewership metrics across linear, connected TV, and mobile video. Industry consortiums fragment between Nielsen, Comscore, and platform-specific analytics, complicating media planning.
- Legacy Display Upgrade Cycle Compression:Consumers extend replacement timelines as 4K panels satisfy viewing needs. Streaming device manufacturers must innovate on software experience rather than hardware specification leaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected TV Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $619.11 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart TVs, Streaming Devices, Set-top Boxes, Blu-ray Players Content Type: Video-on-Demand, Live Streaming, Subscription Services, Ad-supported Content Technology: LED, OLED, QLED, LCD End User: Residential, Commercial, Hospitality, Educational Institutions |
| Companies Covered | Hisense, Amazon, Samsung Electronics, Roku, Google, LG Electronics, Sony Corporation, Disney, TCL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected TV Market Emerging Trajectories
Artificial intelligence inference at the edge is transforming how content discovery and advertising personalization execute without cloud dependency.
On-device machine learning chips are embedding directly into television processors. Premium manufacturers are shipping neural processing units capable of real-time content analysis and viewer attention tracking. This silicon migration is rendering obsolete the latency-prone cloud inference architectures that dominated first-generation smart TV platforms.
The EU AI Act's risk-based classification system is imposing documentation burdens on automated recommendation engines. Platforms must maintain algorithmic audit trails and human oversight mechanisms for content ranking decisions. French regulator CNIL has initiated enforcement actions against opaque profiling practices, forcing publishers to deploy explainable AI frameworks or face operational suspensions.
Subscription fatigue is fragmenting household spending across eight to twelve discrete streaming services. Brazilian and Indian consumers are demonstrating highest propensity to churn, cycling through free trials rather than committing to annual contracts. Ad-supported tiers are capturing this liquidity through lower entry price points and reduced cancellation friction.
Connected TV Market Segmentation
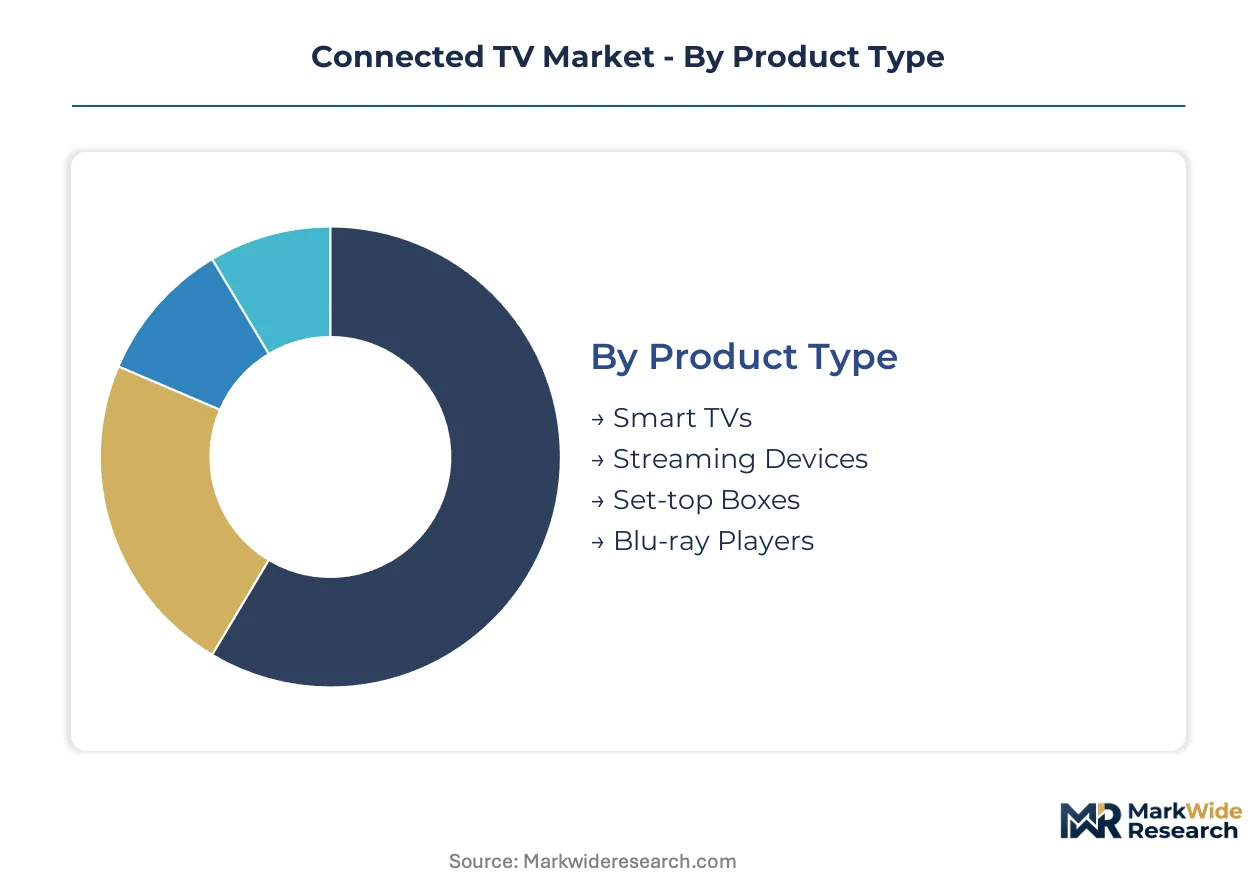
Connected TV market segmentation reveals how hardware form factors, content delivery models, display technologies, and deployment environments each concentrate margin pools differently. Understanding these divides exposes where silicon investments, licensing negotiations, and advertising inventory compete for capital allocation.
Product Type:
Mature integrated displays dominate volume economics while peripheral attachment devices serve upgrade cycles in legacy installed bases.
- Smart TVs:Internet-enabled displays embed processors, connectivity modules, and streaming operating systems within panel assemblies. Residential demand concentrates in Brazil and India where declining LCD costs compress replacement timelines for aging 1080p sets.
- Streaming Devices:HDMI-connected peripherals retrofit internet video capabilities to non-smart displays. Commercial hospitality deployments in the US and Germany drive attach rates as property managers avoid full display refresh cycles.
- Set-top Boxes:Operator-controlled decoders manage conditional access for cable and satellite hybrid services. Pay-TV providers in France and Japan bundle these to retain subscribers amid cord-cutting pressure.
- Blu-ray Players:Optical disc hardware with network connectivity supports physical media libraries and streaming apps. Niche demand persists among archival collectors and regions with inconsistent broadband infrastructure.
Smart TVs handle the majority of throughput; streaming devices are gaining share fastest as hospitality and education sectors extend display lifespans.
Content Type:
Revenue model differentiation separates recurring subscription pools from advertising-supported liquidity and transactional immediacy.
- Video-on-Demand:Library-based streaming enables asynchronous consumption of licensed and original programming. Indian and Southeast Asian viewers demonstrate highest engagement with regional language catalogs.
- Live Streaming:Real-time video delivery replicates broadcast immediacy over internet protocols. Sports rights holders in the UK and Brazil deploy these platforms to bypass traditional carriage fees.
- Subscription Services:Recurring fee structures generate predictable revenue and finance original content production. Households in Germany and South Korea show lowest churn tolerance, locking in annual commitments.
- Ad-supported Content:Free tiers monetize viewership through programmatic advertising insertion. Brazilian consumers exhibit steepest expansion trajectory here as price sensitivity overrides content breadth preferences.
Subscription services command the revenue concentration; ad-supported content is climbing the fastest as emerging market price sensitivity reshapes platform strategies.
Technology:
Panel chemistry and backlight architecture determine power consumption, color accuracy, and manufacturing cost curves across price tiers.
- LED:Edge-lit and full-array backlighting behind LCD substrates delivers brightness efficiency at mass-market price points. Chinese and Vietnamese manufacturing scale anchors global supply for residential volume segments.
- OLED:Organic compound emissive layers enable per-pixel illumination and infinite contrast ratios. South Korean fabrication concentration limits supply elasticity for premium residential and commercial signage applications.
- QLED:Quantum dot enhancement layers expand color gamut on LCD backplanes without OLED burn-in risk. Samsung's display division controls vertical supply for this mid-premium positioning.
- LCD:Mature liquid crystal technology with CCFL or LED backlighting serves cost-constrained educational and hospitality procurement. Extended replacement cycles in these sectors sustain demand despite technical obsolescence.
LED panels move the volume base; OLED is expanding most quickly as 8K production yields improve and prices compress toward premium mainstream.
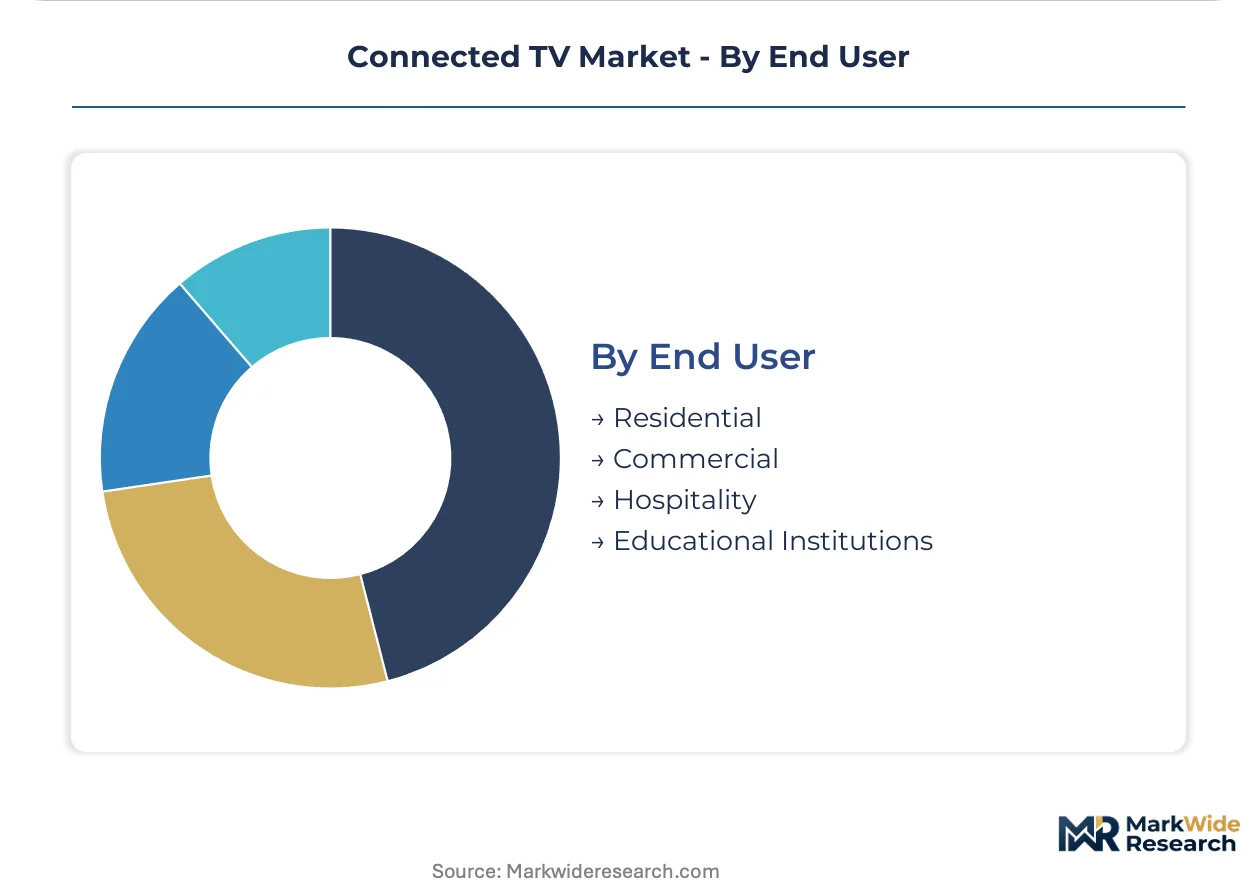
End User:
Deployment environment dictates durability requirements, content curation needs, and monetization mechanism selection.
- Residential:Consumer living-room installations prioritize content breadth and voice interface convenience. US and Brazilian households drive replacement demand as streaming subscription stacking reshapes entertainment budgets.
- Commercial:Retail and corporate deployments emphasize digital signage, wayfinding, and internal communications. German and Japanese facility managers specify 24/7 operational ratings and remote fleet management.
- Hospitality:Hotel and cruise ship installations require guest-facing streaming integration with property management systems. ANVISA certification requirements in Brazil create compliance barriers for international hardware vendors.
- Educational Institutions:K-12 and university deployments balance interactive whiteboard integration with video conferencing capabilities. Indian government procurement programs concentrate volume through centralized tender processes.
Residential captures the dominant revenue share; hospitality is gaining momentum fastest as post-pandemic travel recovery accelerates property technology refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Connected TV trade flows reflect concentrated panel manufacturing in East Asia against consumption gravity shifting toward Brazil and India. Import dependency for finished displays characterizes most Western markets, while South Korea and China maintain net export positions in display technology.
United States
FCC broadband infrastructure mandates accelerate fiber-to-the-home deployment, expanding addressable streaming households. The regulator's quality-of-service standards reduce buffering-related subscriber churn for over-the-top platforms. Silicon Valley and Seattle anchor software platform development, where Amazon and Google refine voice-activated commerce interfaces.
Brazil
ANVISA device certification requirements create compliance barriers that first-movers exploit to establish platform dominance. The national telecom regulator shapes over-the-top bandwidth allocation across Latin America's largest addressable market. São Paulo concentrates demand for ad-supported tiers as price-sensitive viewers abandon subscription stacking.
Germany
GDPR and the EU AI Act impose granular consent mechanisms for viewer data harvesting, forcing algorithmic rebuilds around anonymized cohorts. The country's national media regulator enforces transparency requirements for automated content recommendations. Berlin and Munich host engineering teams adapting recommendation engines to risk-based classification systems.
India
TRAI over-the-top regulations and government procurement programs concentrate educational display volume through centralized tender processes. BIS certification requirements shape hardware import flows for cost-constrained residential segments. Maharashtra and Karnataka manufacturing clusters assemble LED panels for domestic consumption and regional export.
South Korea
MFDS and national standards bodies govern electromagnetic compatibility for display processors fabricated by domestic semiconductor leaders. Samsung and LG leverage captive OLED and QLED supply chains to control premium-tier pricing. Seoul metropolitan fabrication centers supply neural processing units for edge-based content analysis.
Connected TV Market Vendor Landscape
On the supply side, the industry is consolidating around display manufacturers with captive semiconductor capabilities and platform operators with aggregated content ecosystems. Tiered competition separates integrated hardware-software stacks from OS-agnostic aggregators and streaming-native content platforms. Dominant competitive moves include backward integration into panel fabrication and strategic partnerships bundling hardware with subscription services.
Among East Asian display fabricators, Samsung Electronics, LG Electronics, and Sony Corporation exemplify the integrated hardware-software archetype, leveraging proprietary operating systems and captive supply chains. Amazon and Google occupy positions as platform-native entrants, while Roku represents the OS-agnostic aggregation model. TCL and Hisense anchor the volume-tier manufacturing segment, competing through cost-optimized LED panel sourcing.
| Leading Market Players |
|---|
| Hisense |
| Amazon |
| Samsung Electronics |
| Roku |
| LG Electronics |
| Sony Corporation |
| Disney |
| TCL |
| Others |
Supply Flow & Price Mechanics
Panel overcapacity in Chinese and Vietnamese fabrication facilities is compressing component costs while simultaneously eroding supplier pricing power across mid-tier display segments. This utilization dynamic forces manufacturers to absorb margin compression or accelerate premium-tier differentiation through OLED and QLED transitions.
Pricing Analysis
Residential consumers anchor a three-tier pricing structure across premium, standard, and economy levels in the Connected TV market. Price differentiation rests on display technology tier and content ecosystem bundling, with OLED panels commanding substantial premiums over LED alternatives. Cost compression in 8K LCD production is intensifying because South Korean and Taiwanese scale economies are collapsing yield-curve premiums. Brazilian and Indian households exhibit steepest price sensitivity, while German and US consumers demonstrate lowest elasticity for integrated smart platform features.
Supply Chain Analysis
Extended payment terms from display assemblers to panel suppliers are restructuring working capital requirements throughout the value chain. System-on-chip fabrication concentrates in Taiwan and South Korea, with MediaTek and Samsung silicon feeding downstream integration in Vietnam and Mexico. Raw material dependencies span rare earth phosphors for quantum dot enhancement, copper-laminated substrates for printed circuit boards, and specialized glass for panel substrates. Single-source vulnerability around TSMC advanced node capacity represents the dominant structural risk. Distribution runs through electronics retail chains, direct-to-consumer platform channels, and hospitality procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Connected TV market is approaching a platform-economics inflection where operating system interoperability determines ecosystem lock-in and advertising inventory liquidity. Voice-activated commerce integration and cross-platform measurement standardization are reshaping competitive positioning.
For Market Incumbents: Insulate proprietary silicon-to-screen value chains through captive OLED and neural processing unit production in South Korean fabrication centers. Deepen content ecosystem bundling to raise switching costs for subscription-stacking households. Samsung and LG must defend against OS-agnostic aggregators by accelerating Tizen and webOS developer recruitment.
For New Entrants and Emerging Players: Build out ad-supported tier specialization targeting Brazilian price-sensitive cohorts where ANVISA certification barriers filter weaker competitors. Exploit hospitality sector refresh cycles in post-pandemic travel recovery markets. Pursue white-label manufacturing partnerships with TCL or Hisense to bypass capital-intensive panel fabrication.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across streaming device peripherals as software experience displaces hardware specification competition. Acquisition targets should concentrate on edge-AI inference chip designers and programmatic advertising infrastructure specialists. Watch for GDPR enforcement actions against opaque recommendation algorithms as a signal for compliance-technology investment windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Panel Fabrication | Samsung and LG control OLED supply chains to defend premium-tier pricing against Chinese LED competition. |
| Voice-Activated Commerce Platform Launch | Amazon anchors living-room purchasing interfaces that merge product placement with frictionless checkout conversion. |
| OS-Agnostic Aggregation Partnership | Roku sustains platform neutrality to capture fragmented streaming subscription management across hardware ecosystems. |
| ANVISA Certification Fast-Track | First-movers in Brazil establish hardware approval advantages before regulatory harmonization spreads regionally. |
| Edge-AI Inference Chip Deployment | Neural processing units embedded in television processors enable real-time content analysis without cloud dependency latency. |
Methodological Framework
Initial hypotheses were tested against primary input from display manufacturing executives, streaming platform strategy leads, programmatic advertising technology directors, and hospitality procurement managers and refined through secondary validation. Sources included FCC broadband infrastructure filings, EU AI Act implementation guidance, ANVISA device certification databases, and SEC disclosures from publicly traded hardware manufacturers. Bottom-up demand modeling triangulated against top-down market sizing across geographic clusters.
Demand-supply-balance framing anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled encompassed hardware form factor, content delivery monetization model, display technology tier, and deployment environment. CAGRs were derived from installed base replacement cycle analysis, broadband penetration curves, and advertising inventory growth trajectories. Forecast inputs incorporated panel cost curve projections and regulatory compliance cost burdens.
Stress conditions across silicon supply concentration, GDPR enforcement intensity, and emerging market currency volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about streaming substitution rates and advertising CPM trajectories. Macroeconomic contraction, geopolitical disruption to Taiwan semiconductor fabrication, or fundamental shifts in privacy regulation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Air Separation Unit Market
Others
Linseed Oil Market
Others
Cellular-Connected Laptops Market
Others
Belt Press Filter Market
Others
North America Agricultural Enzymes Market
Others
Conditional Access System (CAS) Market
Others
Global Wireless Asset Management Market
Others
Reduced-Risk Products (Rrps) Market
Others
Augmented Shopping Market
Others
Global ESD Protection Devices Market
Others
IoT Testing Market
Others
Hardwood Market
Others
Water and Waste Water Treatment Chemicals Market
Others
Smart Card Contactless Ticketing Market
Others
Asia-Pacific Eyelash Serum Market
Others
Global Telemetry Market