
 Communication Base Station Body Market | 2026-2036
Communication Base Station Body Market Size, Share, and Industry Trends Forecast 2026-2036
Communication Base Station Body Market Insights
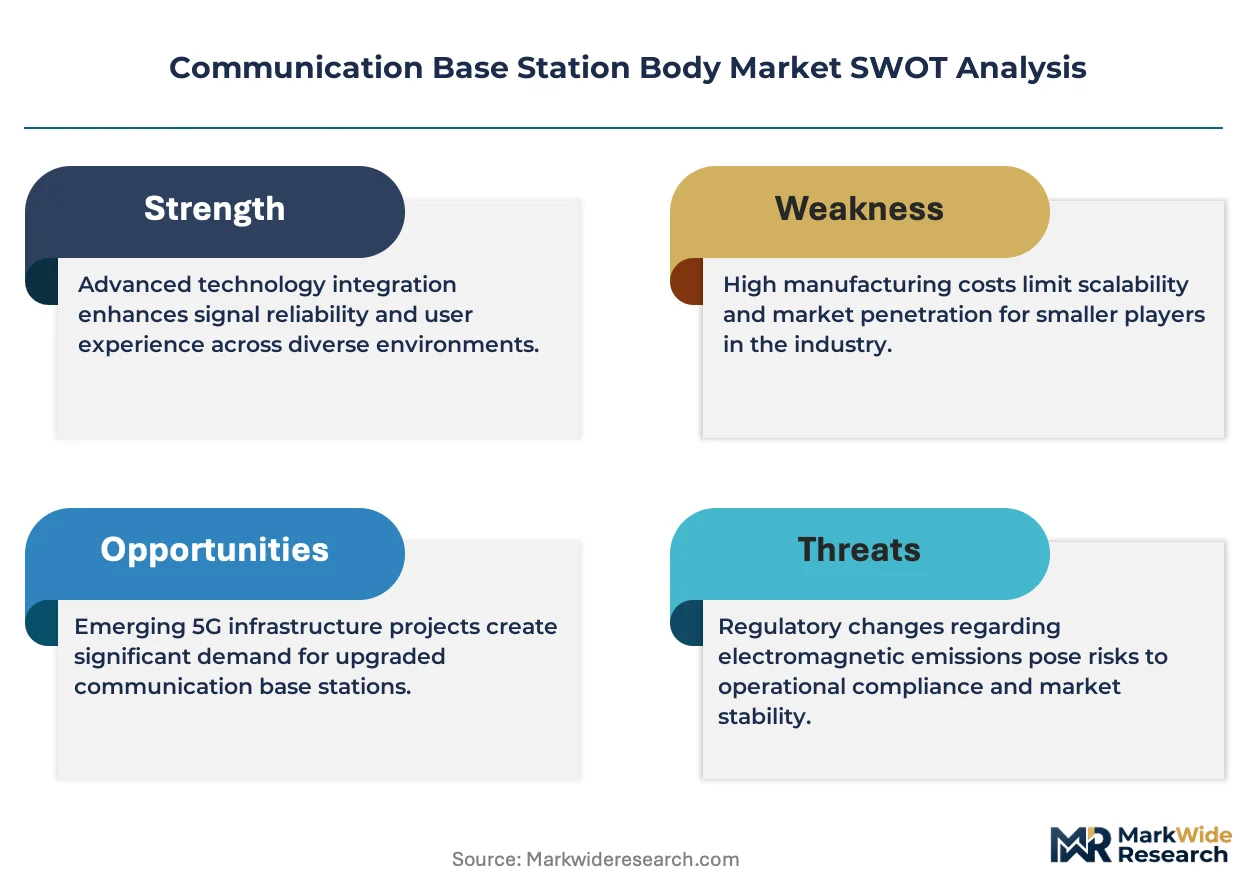
A widening capital-intensity gap between integrated tower manufacturers and component assemblers is rotating competitive advantage toward firms with in-house die-casting and thermal management capabilities. Huawei Technologies Co., Ltd. leverages captive foundry capacity to control enclosure lead times across Southeast Asian supply chains. Ericsson anchors European demand through localized forging partnerships that bypass raw material import bottlenecks. Nokia Corporation differentiates via composite-hybrid body designs that reduce site installation weight by half versus traditional galvanized steel.
The communication base station body comprises the structural enclosure, mounting frame, and environmental sealing system that houses radio units, power distribution, and thermal management hardware for wireless transmission sites, typically fabricated from aluminum alloys, galvanized steel, or fiber-reinforced polymers with IP65+ ingress protection and passive cooling fin arrays. Macro cells dominate volume due to 5G mid-band rollout density requirements, while small cells capture margin expansion as municipalities tighten zoning for pole-mounted and rooftop installations. Satellite-linked bodies remain nascent but attract R&D allocation from defense and maritime connectivity programs.
FCC structural and RF exposure rules in the United States, combined with EU Green Deal embodied-carbon tracking and China's MEE dual carbon enforcement, are elevating recycled aluminum content thresholds and lifecycle documentation requirements for market access. Tower operators now face parallel compliance with CE marking, GB standards, and OSHA fall-protection anchorage specifications depending on deployment geography. Stakeholders must weigh regional certification costs against modular platform designs that can accept localized thermal and seismic adaptations without full retooling.
Market Dynamics
5G mid-band densification is compressing enclosure lead times while China's MEE dual carbon enforcement tightens aluminum sourcing requirements, forcing tower manufacturers to retool thermal management architectures.
Growth Catalysts
- PLI scheme acceleration:India's production-linked incentive scheme for telecom equipment is accelerating rural tower densification, creating pull-through demand for lightweight galvanized steel enclosures.
- FCC RF exposure rules:Updated FCC structural and RF exposure mandates in the United States are mandating redesigned mounting frames with integrated passive cooling, expanding replacement cycles.
- Die-casting automation:Advanced robotic die-casting lines are compressing enclosure production cycles for aluminum alloy bodies, reducing per-unit labor content.
Market Restraints
- Primary aluminum volatility:LME aluminum price swings are compressing margin buffers for enclosure fabricators locked into fixed-price tower operator contracts.
- Southeast Asian supply concentration:Captive foundry capacity concentrated in Vietnam and Thailand creates geographic vulnerability to monsoon-related logistics disruptions.
- Composite material cost premium:Fiber-reinforced polymer enclosures carry 40-60% raw material cost premiums versus galvanized steel, limiting adoption in price-sensitive emerging markets.
Strategic Opportunities
- Maritime satellite-linked bodies:Defense and offshore energy connectivity programs are funding R&D for corrosion-resistant enclosures with integrated satellite backhaul.
- EU Green Deal embodied-carbon tracking:CE marking requirements for lifecycle documentation create first-mover advantage for manufacturers with certified recycled aluminum supply chains.
- Edge computing convergence:Base station bodies with integrated edge compute thermal zones are supplanting separate shelter deployments at 5G macro sites.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous CE marking, GB standards, and OSHA fall-protection compliance is extending product validation cycles by 8-14 months.
- Thermal engineer scarcity:Passive cooling fin array design expertise is concentrated among legacy automotive HVAC specialists, creating recruitment bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Communication Base Station Body Market |
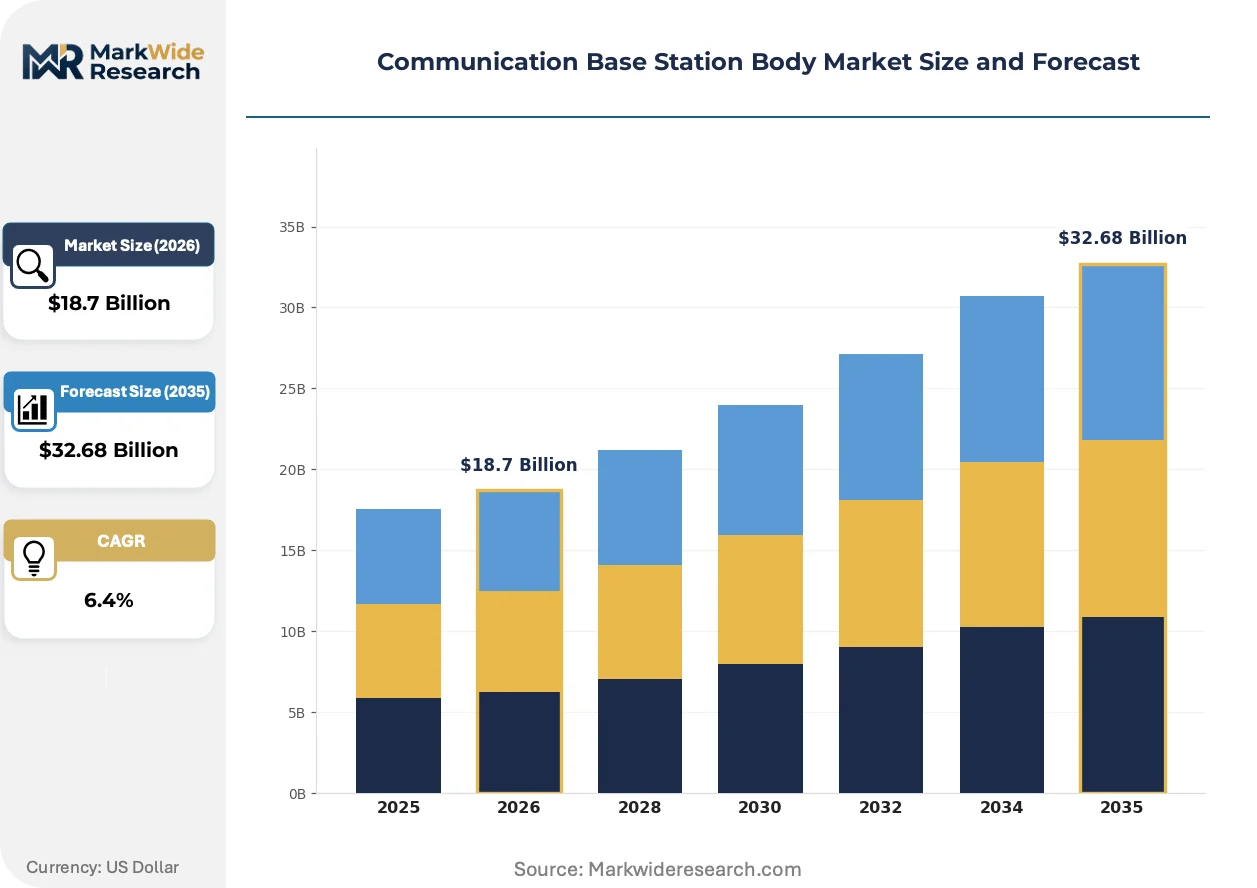
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Cells, Macro Cells, Distributed Antenna Systems, Repeaters Technology: LTE, 5G, Wi-Fi, Satellite End User: Telecommunications Providers, Government, Enterprises, Transport Installation Type: Indoor, Outdoor, Rooftop, Pole-Mounted |
| Companies Covered | Huawei Technologies Co., Ltd., Ericsson, Nokia Corporation, ZTE Corporation, Samsung, CommScope, American Tower, Crown Castle, SBA Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Communication Base Station Body Market Trends and Innovations
Material substitution and regulatory traceability requirements are restructuring competitive advantage around captive recycling streams and modular thermal architectures.
Die-cast aluminum alloy enclosures with integrated vapor chamber cooling are supplanting traditional bolted-fin galvanized steel designs. Tower operators in Germany and South Korea are specifying these units for 5G massive MIMO deployments. The shift is compressing supplier margins on legacy stamping operations while rewarding foundry-integrated manufacturers.
China's MEE dual carbon enforcement is mandating recycled aluminum content thresholds and full lifecycle carbon documentation for market access. GB standards now require embodied-carbon declarations for structural enclosures used in state-backed 5G rollout contracts. Domestic tower manufacturers are responding by locking multi-year scrap supply agreements with regional recyclers.
Tower operators are consolidating procurement around platform suppliers capable of localized thermal and seismic adaptations without full retooling. Municipal zoning for pole-mounted small cells in Japan and France is fragmenting order volumes while demanding faster customization turnaround. This pattern favors mid-size fabricators with parametric design capabilities over high-volume stamping specialists.
Communication Base Station Body Market Segmentation
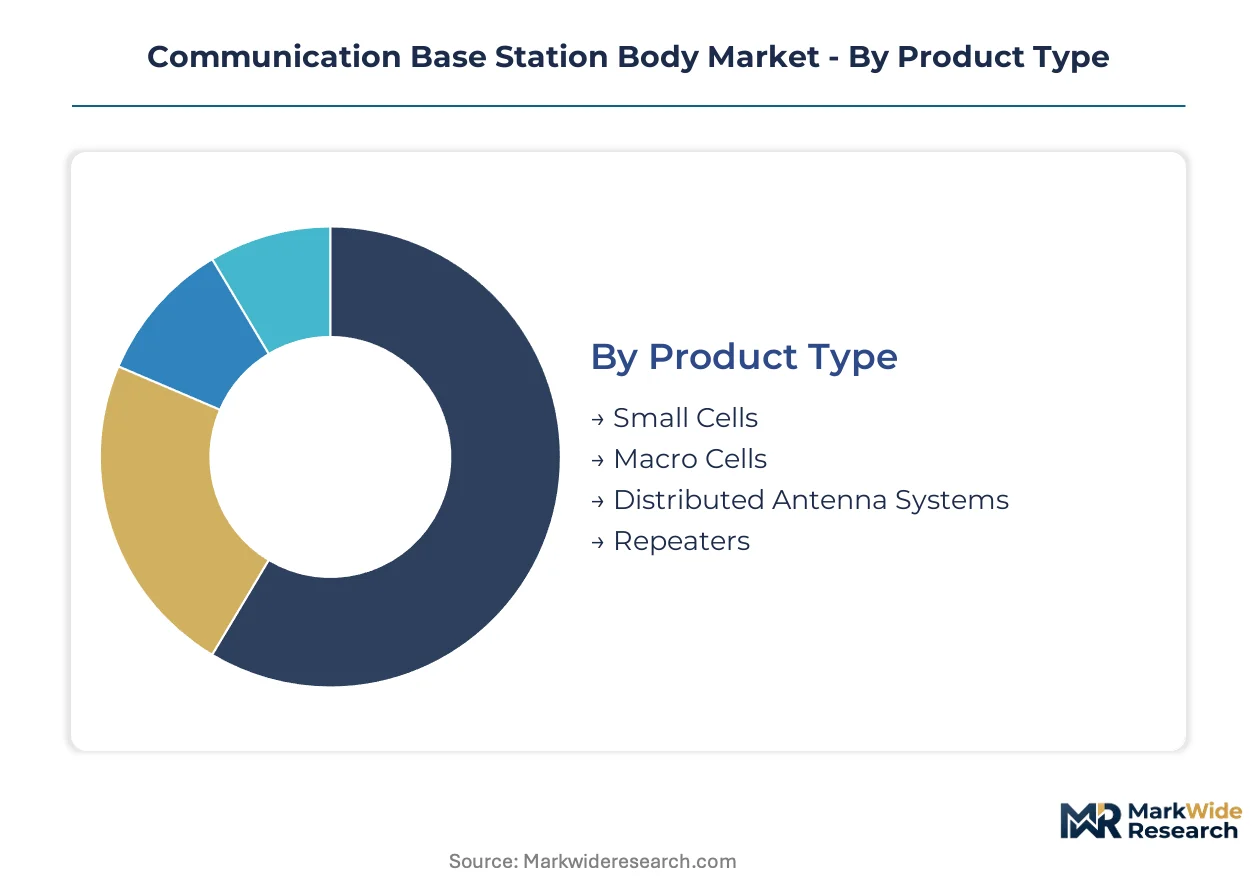
Segmentation in the communication base station body market reveals how regulatory pressure and deployment physics reshape procurement priorities. Tower operators now select enclosure specifications against a matrix of RF exposure rules, carbon disclosure mandates, and site-specific thermal constraints rather than unit cost alone.
Product Type:
FCC structural mandates and China's MEE dual carbon enforcement differentiate enclosure specifications by deployment scale and thermal load.
- Macro Cells:These enclosures integrate passive cooling fin arrays and IP65+ sealing for high-power radio units in galvanized steel or aluminum alloy configurations. Demand concentrates in Germany and South Korea where 5G massive MIMO densification mandates rapid site activation timelines under national broadband targets.
- Small Cells:Lightweight composite-hybrid or die-cast aluminum designs reduce pole-mount structural loads and accelerate municipal zoning approvals. Municipalities in Japan and France are tightening rooftop and street-furniture aesthetic standards, fragmenting order volumes while demanding faster customization turnaround.
- Distributed Antenna Systems:Split-body architectures with distributed RF pathways serve stadiums and transit corridors under OSHA fall-protection anchorage specifications.
- Repeaters:Compact sealed units bridge coverage gaps in terrain-challenged regions with simplified thermal management.
Established volume favors Macro Cells; emerging adoption favors Small Cells.
Technology:
Cost tier stratification separates legacy network maintenance from next-generation deployment cycles.
- 5G:Mid-band massive MIMO deployments require vapor chamber cooling integration and compressed lead times for die-cast aluminum enclosures. India's PLI scheme is accelerating rural tower densification, creating pull-through demand for thermally optimized bodies.
- LTE:Replacement cycles extend as operators defer capital toward 5G overlay, sustaining demand for standardized galvanized steel enclosures with minimal customization.
- Wi-Fi:Enterprise and venue deployments favor plastic-composite indoor enclosures with simplified IP ratings.
- Satellite:Maritime and defense connectivity programs fund corrosion-resistant designs with integrated backhaul thermal zones.
Capital deployment intensity distinguishes 5G from legacy LTE procurement patterns.
End User:
Customer type determines certification burden and lifecycle documentation requirements.
- Telecommunications Providers:Tower operators face parallel compliance with CE marking, GB standards, and OSHA specifications across multi-jurisdiction footprints. Procurement concentrates around platform suppliers capable of localized thermal and seismic adaptations without full retooling.
- Government:Defense and emergency communications programs mandate enhanced electromagnetic shielding and tamper-evident sealing under country-specific security protocols.
- Enterprises:Private 5G networks for manufacturing and logistics favor modular enclosures with edge compute thermal zones.
- Transport:Railway and highway corridors specify vibration-resistant mounting frames with integrated power distribution.
Procurement scale favors Telecommunications Providers; margin expansion favors Government and Enterprise verticals.
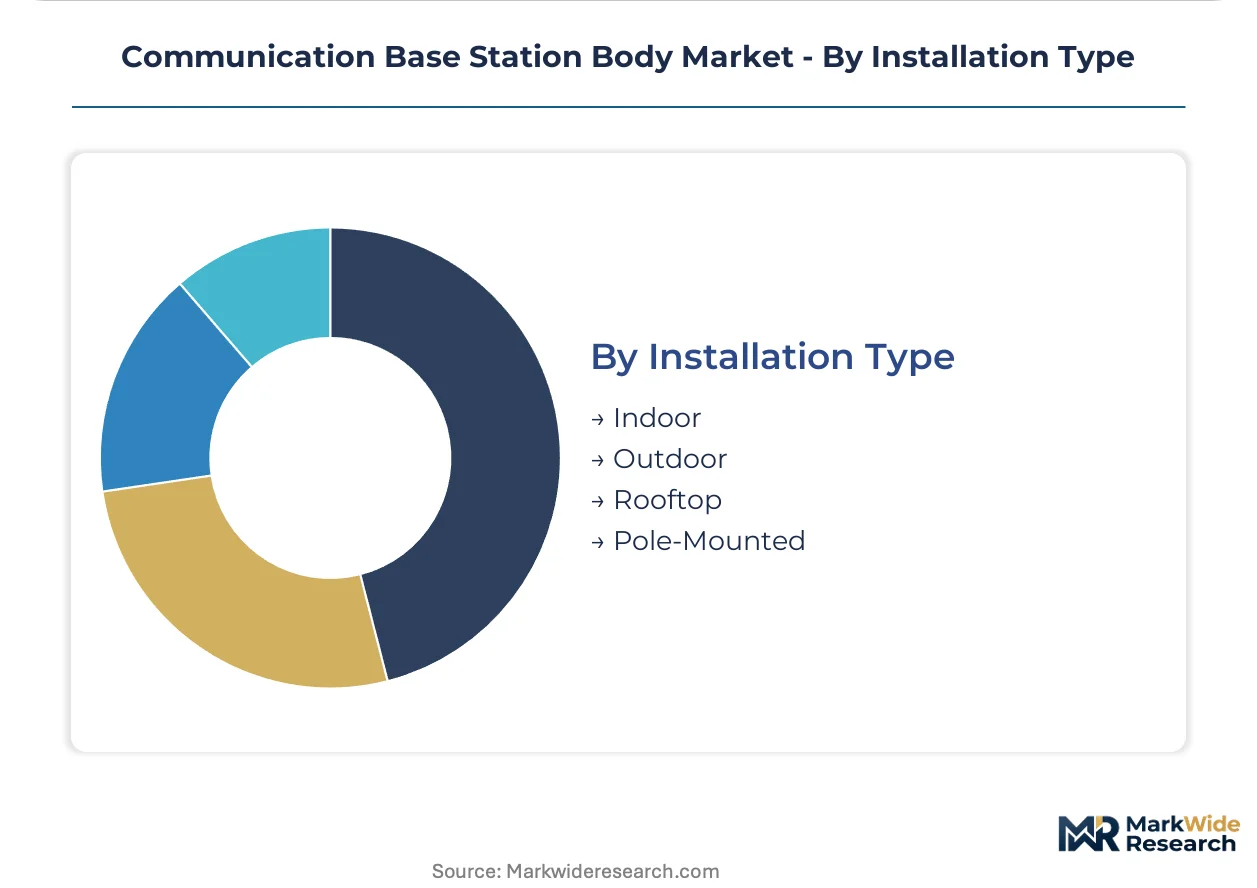
Installation Type:
Site physics and zoning jurisdiction dictate material selection and labor content.
- Outdoor:Ground-mounted macro enclosures in aluminum or galvanized steel dominate volume under EU Green Deal embodied-carbon tracking and China's recycled content thresholds.
- Rooftop:Weight-constrained installations in dense urban corridors favor composite-hybrid designs that reduce structural reinforcement costs.
- Pole-Mounted:Aesthetic and wind-loading regulations in Japanese and French municipalities drive demand for compact, parametrically customizable small cell housings.
- Indoor:Simplified IP ratings and passive cooling suffice for enterprise DAS and Wi-Fi deployments with minimal environmental sealing.
Regulatory complexity favors Outdoor and Rooftop specifications; standardization favors Indoor deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands premium margins for die-cast aluminum enclosures, while Indian fabricators absorb cost compression under fixed-price PLI contracts. This asymmetry fragments procurement strategies across deployment geographies.
United States
FCC structural mandates and OSHA fall-protection specifications drive enclosure redesign cycles for 5G massive MIMO deployments. Tower operators in Texas and California face extended validation timelines under multi-jurisdiction compliance requirements. Dallas-Fort Worth anchors domestic manufacturing clusters serving rural broadband expansion programs.
China
MEE dual carbon enforcement tightens recycled aluminum content thresholds for state-backed 5G rollout contracts. GB standards now mandate full lifecycle carbon documentation for structural enclosures. Yangtze River Delta foundries lock multi-year scrap supply agreements to secure market access.
Germany
EU Green Deal embodied-carbon tracking elevates CE marking requirements for tower operator procurement. Vapor chamber cooling specifications concentrate demand around Stuttgart and Munich industrial zones. Localized forging partnerships bypass raw material import bottlenecks for European supply security.
India
TRAI rural broadband targets and PLI scheme incentives accelerate tower densification across Maharashtra and Gujarat. Galvanized steel enclosures dominate price-sensitive procurement under government subsidy frameworks. Tower operators in Telangana consolidate orders around fabricators with parametric customization capabilities.
Japan
METI municipal zoning standards tighten aesthetic and wind-loading regulations for pole-mounted small cell deployments. Compact enclosure designs fragment order volumes while demanding faster customization turnaround. Nagoya and Osaka industrial corridors specialize in lightweight composite-hybrid body production.
Communication Base Station Body Market Competitive Landscape
Concentration sits with integrated tower manufacturers possessing captive die-casting and thermal management capabilities. Component assemblers without upstream foundry access face margin compression under aluminum price volatility. Three archetypes dominate: foundry-integrated platform suppliers, regional stamping specialists, and composite-hybrid design houses. Strategic moves center on multi-year scrap supply agreements and parametric design automation for municipal zoning compliance.
Among Asia-Pacific equipment vendors, Huawei Technologies Co., Ltd. exemplifies the foundry-integrated archetype through captive production capacity. Ericsson anchors European positioning through localized supply chain partnerships. Nokia Corporation occupies the composite-hybrid specialization tier with reduced-weight enclosure architectures.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Ericsson |
| Nokia Corporation |
| ZTE Corporation |
| Samsung |
| CommScope |
| American Tower |
| Crown Castle |
| SBA Communications |
| Others |
Pricing and Supply Chain Analysis
Die-cast aluminum alloy enclosures displacing galvanized steel bolted-fin designs simultaneously concentrates supply geography around Yangtze River Delta foundries and compresses pricing power for legacy stamping specialists locked into fixed-price tower operator contracts.
Pricing Analysis
The customization-premium spread separates parametrically configurable small cell housings for Japanese municipal zoning compliance from standardized macro cell enclosures for Indian PLI-scheme rural deployments. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal management complexity and certification grade. Cost compression in the standard tier intensifies because LME aluminum volatility erodes margin buffers under long-term offtake agreements. Indian tower operators exhibit highest price sensitivity; German carriers purchasing vapor chamber-cooled units show lowest.
Supply Chain Analysis
Inbound logistics costs through Shanghai-Ningbo and Port Klang corridors determine landed cost competitiveness for Southeast Asian foundry output serving European CE-marking requirements. Primary aluminum smelting concentrates in China, Russia, and Canada; die-casting fabrication clusters in Vietnam, Thailand, and Malaysia. The supply chain rests on bauxite refining, primary ingot, and scrap aluminum circularity. Single-source vulnerability concentrates in Yangtze River Delta captive foundries. Distribution runs through tower operator direct procurement and regional system integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The communication base station body market sits in a cyclical recovery phase as 5G mid-band densification capital cycles replace deferred LTE maintenance spending.
For Market Incumbents: Fortify foundry-integrated positioning through multi-year scrap supply agreements with Yangtze River Delta recyclers, locking MEE dual carbon compliance. Add parametric design automation capacity in Telangana to capture Indian PLI-scheme rural densification demand. Aluminum price volatility threatens margin buffers; thermal engineer scarcity constrains vapor chamber cooling expansion. For New Entrants and Emerging Players: Rapid customization turnaround for Japanese and French municipal small cell zoning represents the most penetrable service-layer gap. Target composite-hybrid design specialization for rooftop weight-constrained installations where Nokia's reduced-weight architectures command premium positioning. Pursue maritime satellite-linked body R&D partnerships with defense connectivity programs as entry credential. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional stamping specialists lacking upstream die-casting integration. The 5-10 year viability window favors acquisition of mid-size fabricators with parametric capabilities and certified recycled aluminum supply chains. Monitor India's PLI scheme disbursement velocity as inflection indicator for rural tower densification capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Integration | Huawei's captive Yangtze River Delta capacity controls enclosure lead times against Southeast Asian logistics disruptions. |
| Recycled Aluminum Supply Lock | Multi-year scrap agreements with regional recyclers secure MEE dual carbon market access for state-backed 5G contracts. |
| Parametric Design Automation | Mid-size fabricators in Telangana accelerate customization turnaround for Japanese municipal small cell zoning fragmentation. |
| Vapor Chamber Cooling R&D | German Stuttgart industrial zone specialists capture EU Green Deal premium positioning for massive MIMO thermal loads. |
| Maritime Corrosion-Resistant Enclosure Development | Defense and offshore energy connectivity programs fund satellite backhaul integration for niche margin expansion. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with tower procurement directors, thermal engineering leads, foundry operations managers, and municipal zoning compliance officers; and secondary validation through customs trade databases, FCC equipment authorization filings, GB standards documentation, and tower operator capex disclosures. Bottom-up enclosure shipment triangulation against top-down 5G deployment capital flow analysis anchored volume estimates.
The projection horizon spans the full analysis window across product type, technology generation, end-user vertical, and installation configuration dimensions. CAGRs were derived from segmented deployment velocity modeling incorporating TRAI rural broadband targets, EU Green Deal embodied-carbon compliance timelines, and MEE dual carbon enforcement trajectories. Forecast inputs include aluminum LME forward curves, PLI scheme disbursement schedules, and municipal small cell zoning permit issuance patterns.
Underlying assumptions cover sustained 5G mid-band densification capital commitment, with deviation risk concentrated in primary aluminum price volatility and multi-jurisdiction certification timeline extensions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Refrigerated Display Cases Market
Others
Smart Home Platforms Market
Others
Solar Animal Repeller Market
Others
Deep Sea Mining Market
Others
Badminton Apparel Market
Others
Japan Coal Market
Others
Liposomes Market
Others
Global Contactless Biometrics Technology Market
Others
LAMEA Astrology Market
Others
Security Bottles Market
Others
Port Replicator Market
Others
US Camping and Caravanning Market
Others
Augmented Reality (AR) in Manufacturing Market
Others
Middle East and Africa Halal Food & Beverage Market
Others
Retail Digital Signage Market
Others
Rotary Dial Machine Market