
 North America Feed Prebiotics Market | 2026-2036
North America Feed Prebiotics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Feed Prebiotics Market Analytics
A capital-intensity divergence between integrated multinationals and specialty ingredient houses is reorganizing competitive tiers in North America feed prebiotics. Cargill Incorporated leverages its captive grain origination and fermentation infrastructure to backward-integrate into inulin and fructooligosaccharide production. DSM-Firmenich AG sustains premium positioning through precision fermentation capabilities and human-grade quality certifications that transfer into animal nutrition. Alltech Incorporated anchors its defensibility in yeast-derived mannan oligosaccharide expertise honed across Kentucky manufacturing complexes.
Feed prebiotics comprise non-digestible carbohydrate compounds—principally oligosaccharides, inulin, and mannan oligosaccharides—that selectively stimulate beneficial gut microbiota in monogastric and ruminant species, typically administered at inclusion rates of 0.1% to 0.5% of total ration mass. Their primary commercial purpose centers on improving feed conversion ratios, reducing pathogen colonization, and satisfying antibiotic-free production pledges across integrated supply chains. Oligosaccharides command the dominant volume position due to established supply chains and cost-efficient extraction from plant feedstocks, though mannan oligosaccharides capture disproportionate margin pools in premium poultry and aquaculture segments where mortality reduction justifies higher unit pricing. Poultry application leads absolute consumption across North America, while aquaculture represents the fastest-expanding category as land-based recirculating systems in Ontario and Maine adopt intensive gut-health protocols.
The FDA Veterinary Feed Directive and USDA Organic standards collectively constrain antibiotic growth promoter use, directly elevating prebiotic substitution demand across federally inspected facilities. CFIA oversight of cross-border feed ingredient trade between Canada and the United States imposes additional documentation burdens that favor suppliers with established North American manufacturing footprints over import-dependent competitors. Stakeholders must monitor evolving state-level cage-free and antibiotic-free mandates, as California's Proposition 12 compliance deadlines and similar measures in Massachusetts and Michigan will cascade into revised prebiotic formulation specifications across regional broiler and layer operations.
Market Dynamics
Antibiotic withdrawal mandates across federally inspected facilities are compressing formulation cycles and forcing rapid substitution toward microbiome-modulating ingredients, with procurement departments now embedding gut-health specifications directly into supplier scorecards.
Growth Catalysts
- FDA Veterinary Feed Directive:Mandatory veterinary oversight of medically important antibiotics in feed drives immediate prebiotic adoption across integrated pork and poultry operations seeking compliance pathways.
- Yeast-derived mannan oligosaccharides:Proven mortality reduction in premium broiler segments justifies inclusion rate increases to 0.3-0.5% of ration mass, expanding addressable volume pools.
- Iowa procurement concentration:Integrated packers in the Corn Belt negotiate multi-year oligosaccharide supply agreements, creating demand anchors that stabilize regional fermentation capacity investments.
Market Restraints
- Chicory root supply volatility:Inulin extraction depends on European and North American chicory harvests exposed to drought-induced yield compression and price spikes.
- CFIA documentation burdens:Cross-border feed ingredient trade between Canada and the United States imposes batch-level certification requirements that delay just-in-time delivery schedules.
- Enzymatic hydrolysis limitations:Current processing technology cannot cost-effectively produce specific chain-length fructooligosaccharides below food-grade purity thresholds.
Strategic Opportunities
- Land-based recirculating aquaculture in Ontario:Closed-containment salmon and trout operations adopt intensive gut-health protocols as density increases pathogen pressure, creating new application verticals.
- California Proposition 12 compliance deadlines:Cage-free layer mandates cascade into revised prebiotic specifications for intestinal health management in alternative housing systems.
- Precision fermentation convergence with synthetic biology:Engineered microbial strains enable novel oligosaccharide structures with targeted bifidogenic selectivity unavailable from plant extraction.
Industry Challenges
- Microbiome assay standardization:Absence of harmonized protocols for measuring prebiotic efficacy across species and facilities complicates supplier qualification and performance guarantees.
- Fermentation capex intensity:Commercial-scale mannan oligosaccharide production requires dedicated bioreactor trains with multi-year depreciation horizons that strain mid-cap balance sheets.
- Organic certification alignment:USDA Organic feed standards impose conflicting restrictions on substrate sources and processing aids that limit formulation flexibility for dual-certified products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Feed Prebiotics Market |
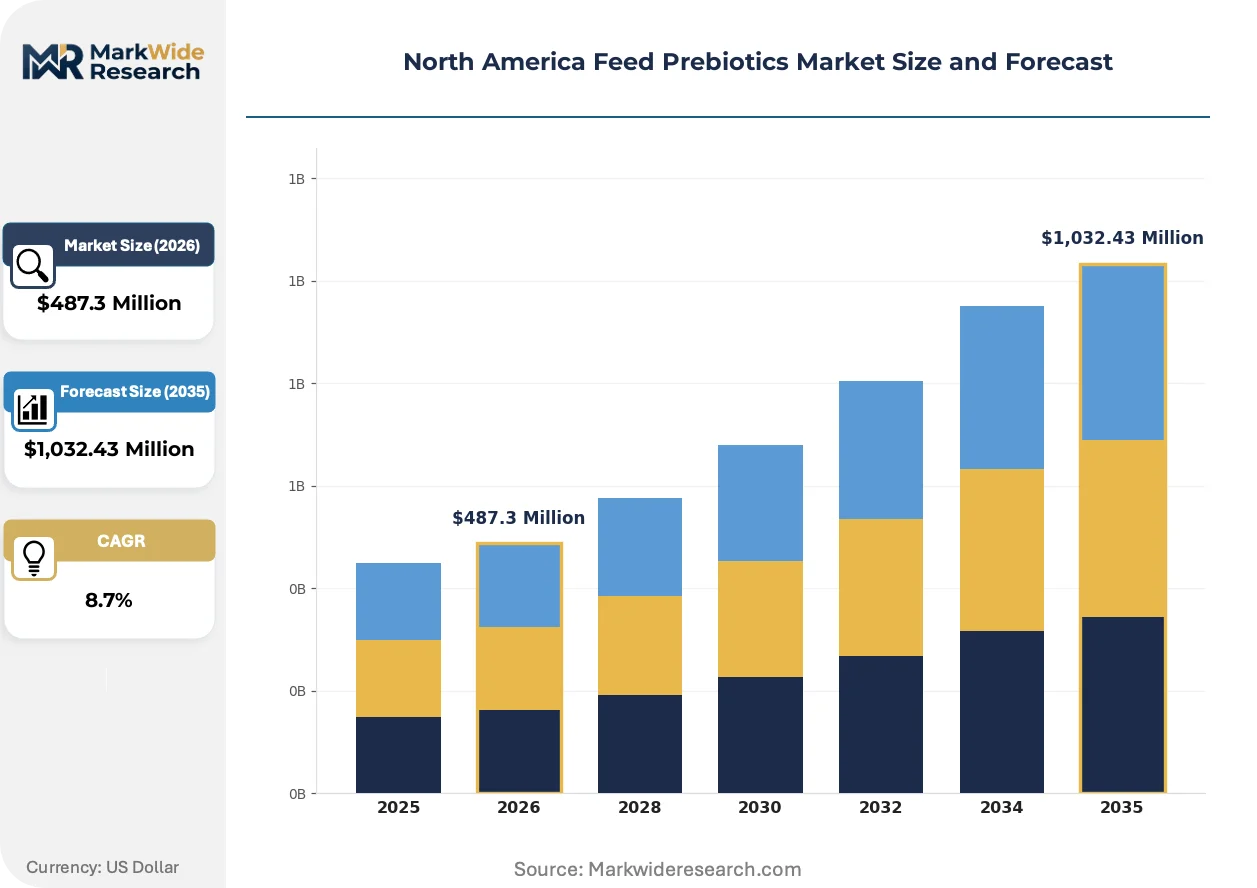
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oligosaccharides, Inulin, Mannan Oligosaccharides, Fructooligosaccharides Application: Swine, Poultry, Ruminants, Aquaculture End User: Farmers, Feed Manufacturers, Veterinary Clinics, Research Institutions Distribution Channel: Online, Offline, Direct Sales, Wholesale |
| Companies Covered | Cargill Incorporated, DSM-Firmenich AG, Alltech Incorporated, Nutreco N.V., Land O'Lakes Incorporated, BENEO GmbH, Roquette, Ingredion, FrieslandCampina, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Feed Prebiotics Market Evolving Landscape
Active ingredient diversification is fragmenting the historical dominance of plant-extracted oligosaccharides, with novel substrates and production methods competing for inclusion in next-generation formulations.
Postbiotic metabolites—short-chain fatty acids and bioactive peptides derived from controlled fermentation—are fragmenting the prebiotic category boundary. Layer and broiler integrators in the southeastern United States trial these compounds as direct microbiome modulators bypassing substrate fermentation variability. The distinction between prebiotic, probiotic, and postbiotic applications is compressing as suppliers bundle multifunctional gut-health solutions.
The FDA's phased enforcement of antimicrobial sales reporting under the Animal Drug User Fee Act amendments tightens accountability for growth promoter use. Feed mills serving federally inspected facilities now document prebiotic substitution ratios in regulatory submissions. Midwest pork operations respond by consolidating supplier relationships with firms offering dual technical and compliance support.
Buyer consolidation among integrated protein packers concentrates procurement leverage into fewer hands. Direct contracting between Iowa and North Carolina poultry integrators and fermentation houses displaces distributor intermediaries. This channel compression rewards suppliers with captive manufacturing footprints and technical service capabilities aligned to species-specific nutrition teams.
North America Feed Prebiotics Market Segmentation
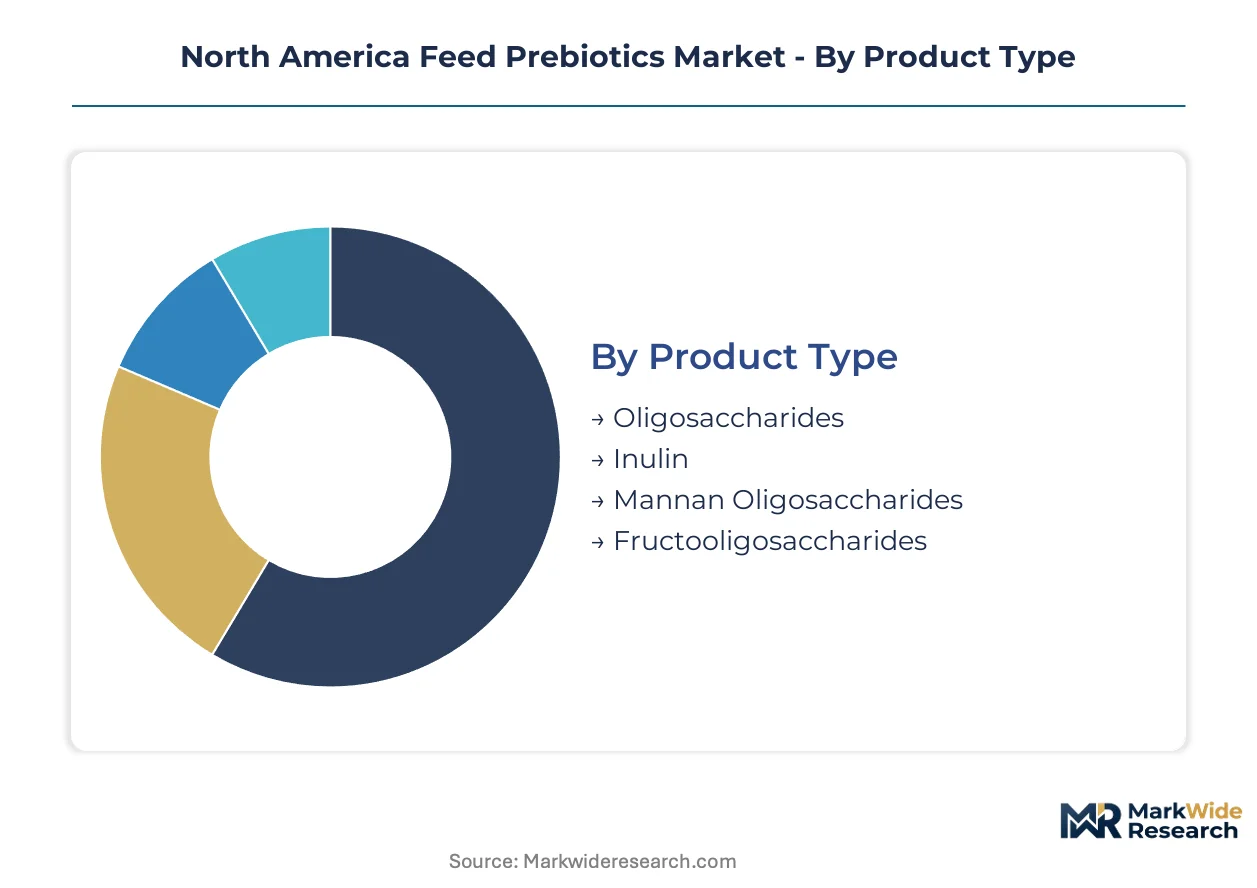
Prebiotic suppliers configure production assets around margin concentration points rather than volume maxima. Category boundaries in this market reflect where formulation expertise commands pricing power versus where commodity extraction economics dominate procurement decisions.
Product Type:
Mannan oligosaccharides capture the widest margin spreads due to mortality reduction guarantees in premium poultry contracts, while oligosaccharides compete on feedstock arbitrage and scale efficiencies.
- Oligosaccharides:Plant-derived non-digestible carbohydrates extracted from soybean meal and wheat bran. Demand concentrates in Iowa pork operations where inclusion rates of 0.1-0.2% satisfy FDA Veterinary Feed Directive compliance at lowest unit cost.
- Inulin:Soluble fiber polymer from chicory root with prebiotic fermentation selectivity for bifidobacteria species. Chicory supply volatility from European drought exposure compresses margin stability for North American compounders dependent on imported raw material.
- Mannan Oligosaccharides:Yeast cell wall derivatives with established pathogen agglutination properties.
- Fructooligosaccharides:Short-chain prebiotic substrates produced through enzymatic or fermentation routes.
Oligosaccharides hold installed capacity across Midwest grain processing corridors. Mannan oligosaccharides are rotating up the share rankings in antibiotic-free layer contracts.
Application:
Poultry absorbs the largest absolute volume, yet aquaculture generates the steepest expansion trajectory as recirculating density intensifies gut-health protocol adoption.
- Poultry:Broiler and layer operations deploy prebiotics to offset antibiotic growth promoter withdrawal under FDA enforcement. Midwest integrators negotiate multi-year supply agreements tying inclusion rates to feed conversion ratio guarantees.
- Aquaculture:Land-based recirculating systems in Ontario and Maine face amplified pathogen pressure at stocking densities above open-water norms. Prebiotic protocols here command premium pricing justified by mortality reduction in high-value salmon and trout production.
- Swine:Nursery and grow-finish phases utilize prebiotics to stabilize gut microbiota during diet transitions.
- Ruminants:Dairy and beef cattle applications focus on rumen fermentation modulation and acidosis prevention.
Poultry commands the volume base. Aquaculture is climbing the fastest as closed-containment infrastructure scales.
End User:
Feed manufacturers intermediate the largest procurement volumes, though direct farmer contracting accelerates where technical service requirements exceed distributor capabilities.
- Feed Manufacturers:Integrated compounders in the Corn Belt source prebiotics as formulation inputs for branded gut-health lines. These buyers consolidate supplier relationships around dual technical and regulatory compliance support.
- Farmers:Large-scale pork and poultry operations in Iowa and North Carolina bypass distributors to contract directly with fermentation houses. Direct procurement captures price advantages at volume thresholds above 500 metric tons annually.
- Veterinary Clinics:Specialty practitioners prescribe prebiotic interventions for individual animal digestive disorders.
- Research Institutions:Universities and extension services evaluate novel prebiotic structures and efficacy protocols.
Feed manufacturers hold the procurement volume anchor. Farmers are rotating up the share rankings through channel compression.
Distribution Channel:
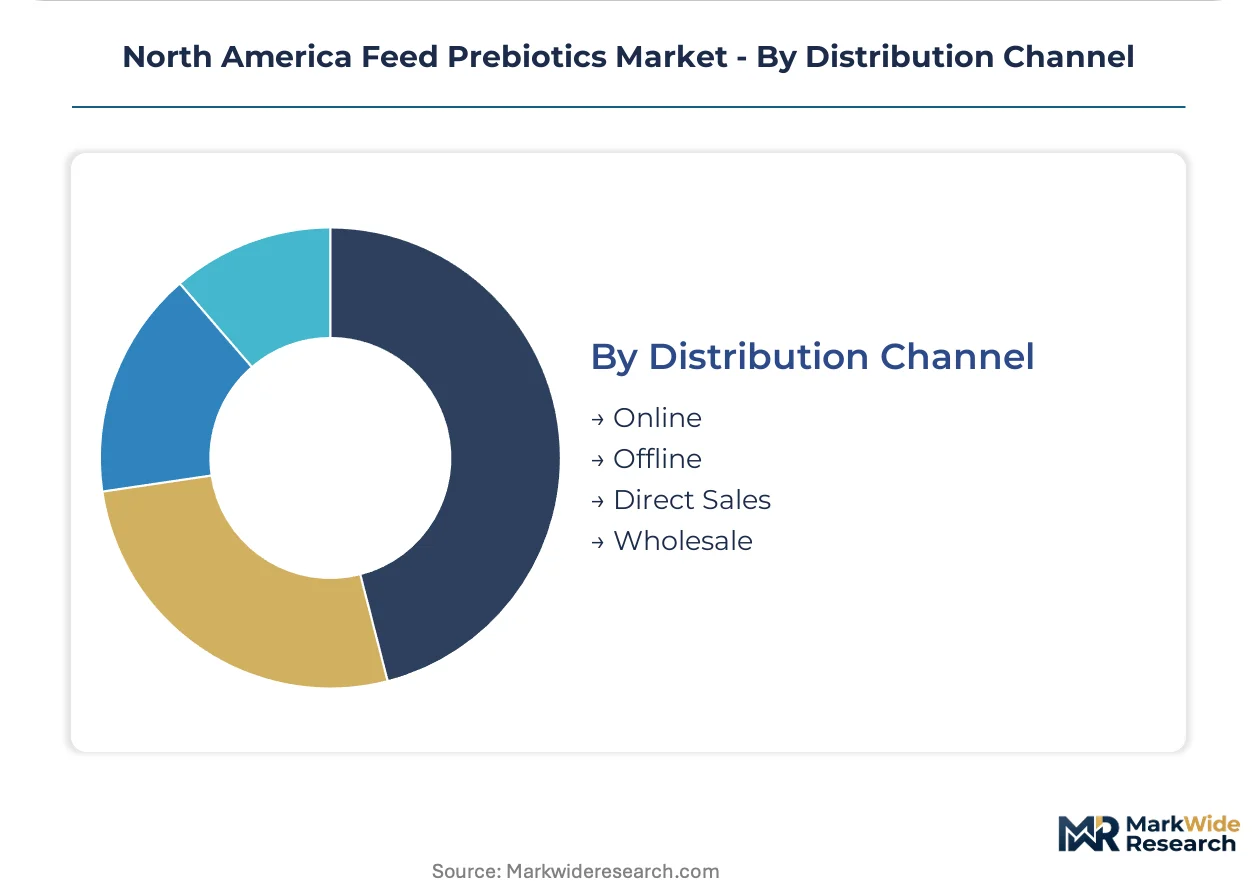
Direct sales capture the highest-value transactions, while wholesale intermediaries retain relevance in fragmented dairy and smaller livestock segments.
- Direct Sales:Fermentation houses and integrated ingredient suppliers deploy technical service teams to support species-specific formulation. Iowa and North Carolina poultry integrators exclusively source through direct channels requiring on-farm microbiome assay support.
- Wholesale:Regional distributors serve mid-scale pork and dairy operations with standardized oligosaccharide grades. CFIA documentation burdens for cross-border trade favor wholesalers with established Canada-United States compliance infrastructure.
- Online:Digital procurement platforms aggregate spot market availability for smaller volume buyers.
- Offline:Traditional field sales relationships persist in ruminant segments with lower prebiotic penetration.
Direct sales hold the relationship-intensive premium tier. Wholesale is rotating up the share rankings as documentation complexity favors established intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Iowa and North Carolina procurement clusters, while Canadian operations absorb documentation cost premiums under CFIA cross-border protocols. Mexico's aquaculture expansion creates a secondary demand node with distinct regulatory requirements.
United States
Integrated pork and poultry packers in Iowa negotiate multi-year oligosaccharide supply agreements that anchor regional fermentation capacity. The FDA Veterinary Feed Directive mandates veterinary oversight for medically important antibiotics, compressing formulation cycles toward prebiotic substitution. North Carolina broiler integrators source mannan oligosaccharides directly from fermentation houses, bypassing distributor intermediaries entirely.
Canada
Land-based recirculating aquaculture systems in Ontario adopt intensive gut-health protocols as salmon and trout stocking densities intensify pathogen pressure. CFIA batch-level certification requirements for cross-border feed ingredient trade delay just-in-time delivery schedules and favor suppliers with established North American manufacturing footprints. Quebec dairy operations utilize prebiotics for rumen fermentation modulation under provincial sustainability programs.
Mexico
Poultry integration in Guanajuato and Jalisco scales antibiotic-free production pledges to maintain access to US export markets under USDA inspection standards. SENASICA oversight of feed safety aligns with FDA-equivalent protocols for medicated feed formulations. Baja California shrimp aquaculture operations trial prebiotic protocols to reduce mortality in intensive pond systems.
California
Proposition 12 cage-free layer mandates cascade into revised prebiotic specifications for intestinal health management in alternative housing systems. The California Department of Food and Agriculture enforces antibiotic-free production standards that exceed federal baselines. Central Valley layer operations consolidate supplier relationships around firms offering dual technical and compliance support.
North America Feed Prebiotics Market Competitive Landscape
Concentration sits with integrated multinationals possessing captive grain origination and fermentation infrastructure. The market structure organizes into three tiers: global ingredient houses with backward-integrated supply chains, specialty fermentation houses focused on yeast-derived substrates, and regional compounders dependent on toll manufacturing. Dominant competitive moves include capacity expansion in Midwest grain corridors and strategic partnerships linking microbiome assay services to direct procurement contracts.
Among North American integrated ingredient suppliers, Cargill Incorporated anchors the scale-driven tier through captive origination assets. DSM-Firmenich AG occupies a position exemplifying premium-tier positioning through precision fermentation capabilities and quality certifications. Alltech Incorporated represents the specialty fermentation archetype with concentrated expertise in yeast-derived substrates. These three entities collectively illustrate how competitive positioning fragments across integration depth, certification grade, and substrate specialization.
| Leading Market Players |
|---|
| Cargill Incorporated |
| DSM-Firmenich AG |
| Alltech Incorporated |
| Nutreco N.V. |
| Land O'Lakes Incorporated |
| BENEO GmbH |
| Roquette |
| Ingredion |
| FrieslandCampina |
| Others |
Value Network & Pricing Analysis
Fermentation capacity utilization rates above 85% in Iowa and North Carolina grain corridors create scale-driven price floors that squeeze mid-cap compounders lacking captive bioreactor infrastructure. This capacity concentration rewards integrated multinationals with backward-integrated oligosaccharide production while forcing specialty houses toward premium mortality-guarantee pricing to defend margin structures.
Pricing Analysis
Configured-to-order mannan oligosaccharide contracts with species-specific mortality guarantees command 40-60% premiums over standard oligosaccharide grades sold on feed conversion ratio specifications alone. Three-tier pricing structure across premium, standard, and economy levels separates yeast-derived substrates with pathogen agglutination certification from plant-extracted grades and commodity inulin. Cost compression in standard oligosaccharide tiers is intensifying because Iowa pork integrators negotiate multi-year offtake agreements exceeding 500 metric tons annually. Feed manufacturers represent the most price-sensitive buyer segment due to formulation cost pass-through constraints, while aquaculture operations in Ontario and Maine exhibit lowest sensitivity as mortality reduction justifies premium inclusion rates.
Supply Chain Analysis
Container availability constraints on European chicory root inbound lanes to North Atlantic ports compress just-in-time delivery windows for inulin-dependent compounders. Supply concentration centers on the United States for fermentation-derived mannan oligosaccharides, Belgium and France for chicory-sourced inulin, and China for enzymatic fructooligosaccharide intermediates. Raw material dependencies include yeast cell wall substrates, chicory root pulp, and food-grade sucrose for enzymatic conversion. Single-source vulnerability runs through European chicory harvests exposed to drought-induced yield compression. Distribution runs through direct technical-service channels for integrated poultry packers and wholesale intermediaries serving fragmented dairy operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as microbiome assay interoperability standards enable supplier-agnostic performance benchmarking across integrated protein packers. This ecosystem shift rewards firms bundling fermentation output with diagnostic services.
For Market Incumbents: Secure captive chicory origination contracts or alternative inulin feedstock partnerships before European harvest volatility triggers raw material shortages. Expand fermentation capacity in Iowa grain corridors to anchor multi-year supply agreements with pork integrators facing FDA Veterinary Feed Directive compliance deadlines. This capacity positioning defends against emerging precision fermentation entrants with synthetic biology-derived oligosaccharide structures. For New Entrants and Emerging Players: Technical service gaps in on-farm microbiome assay support create entry pathways beneath incumbent technical teams focused on volume accounts. Target Ontario land-based recirculating aquaculture systems where intensive gut-health protocol adoption outpaces established supplier coverage. Deploy subscription-based diagnostic bundling to capture recurring revenue streams absent from transactional prebiotic sales. For Investors and Strategic Acquirers: Specialty fermentation houses with yeast-derived substrate expertise and existing CFIA cross-border compliance infrastructure represent priority acquisition targets. Long-term viability hinges on defensible positioning in antibiotic-free production pledge fulfillment rather than commodity extraction economics. Monitor California Proposition 12 compliance deadline adherence as an inflection indicator for cage-free layer prebiotic specification demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chicory Origination | Captive raw material supply insulates margin stability against European drought-induced price spikes. |
| Precision Fermentation Capacity Expansion | Engineered microbial strains enable novel oligosaccharide structures with targeted bifidogenic selectivity. |
| Microbiome Assay Service Bundling | Diagnostic interoperability standards create platform stickiness beyond commodity substrate sales. |
| CFIA Compliance Infrastructure Investment | Batch-level certification capabilities capture Canada-United States cross-border trade advantages. |
| Land-Based Aquaculture Technical Partnership | Ontario and Maine recirculating systems require intensive gut-health protocols at premium pricing. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fermentation house technical directors, Iowa pork procurement leads, North Carolina poultry nutritionists, and CFIA compliance officers; and secondary validation through FDA Veterinary Feed Directive enforcement records, USDA Organic feed standard filings, and American Feed Industry Association trade data. Bottom-up triangulation cross-referenced facility-level capacity disclosures against top-down demand modeling from integrated packer procurement volumes.
Across the projection horizon, the analytical framework modeled value and volume trajectories by product type, application species, end-user procurement channel, and regional regulatory cluster. CAGRs were derived from segmented growth rate reconciliation against macro protein production forecasts. Key inputs included FDA antimicrobial sales reporting trends under Animal Drug User Fee Act amendments and state-level cage-free mandate implementation schedules.
Forecasts assume regulatory continuity in FDA Veterinary Feed Directive enforcement and USDA Organic feed standards; material policy shifts would require re-modeling. Specific risk factors include chicory root supply disruption from European climate volatility and CFIA documentation burden intensification. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
South America Agricultural Microbials Market
Agricultural Biologicals
Global Agri Natural Enemy Pest Control Market
Agricultural Biologicals
Asia-Pacific Agricultural Microbial Market
Agricultural Biologicals
Global Organic Trace Minerals for Animal Feeds Market
Agricultural Biologicals
Global Inoculants Market
Agricultural Biologicals
Feed Mycotoxin Binders Market
Agricultural Biologicals
Baobab Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
Agricultural Adjuvants Market
Agricultural Biologicals
Asia Pacific Silage Inoculant Market
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
North America Animal Feed Additives Market
Agricultural Biologicals
South America Biostimulants Market
Agricultural Biologicals
North America Amino Acids Market
Agricultural Biologicals
Agricultural Biofungicides Market
Agricultural Biologicals
Animal Feed Additives Market