
 Agricultural Microbials Market | 2026-2036
Agricultural Microbials Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Microbials Market Intelligence
Precision agronomy software, bundled with microbial products, is consolidating the value proposition beyond simple product sales. Bayer AG leverages its digital farming platform to integrate microbial solutions with its crop protection portfolio. Novonesis Group specializes in microbial strain discovery and large-scale fermentation. Koppert Biological Systems differentiates through its exclusive focus on biological control and natural pollination systems.
Agricultural microbials are formulations containing beneficial microorganisms, such as bacteria, fungi, or viruses. These products function by enhancing nutrient uptake, suppressing pathogens, or improving soil structure, thereby increasing crop yield and long-term farm resilience. Biopesticides represent the fastest-growing product type, driven by consumer demand for residue-free produce. Soil health applications are gaining share over traditional crop protection methods as farmers focus on regenerative agriculture principles.
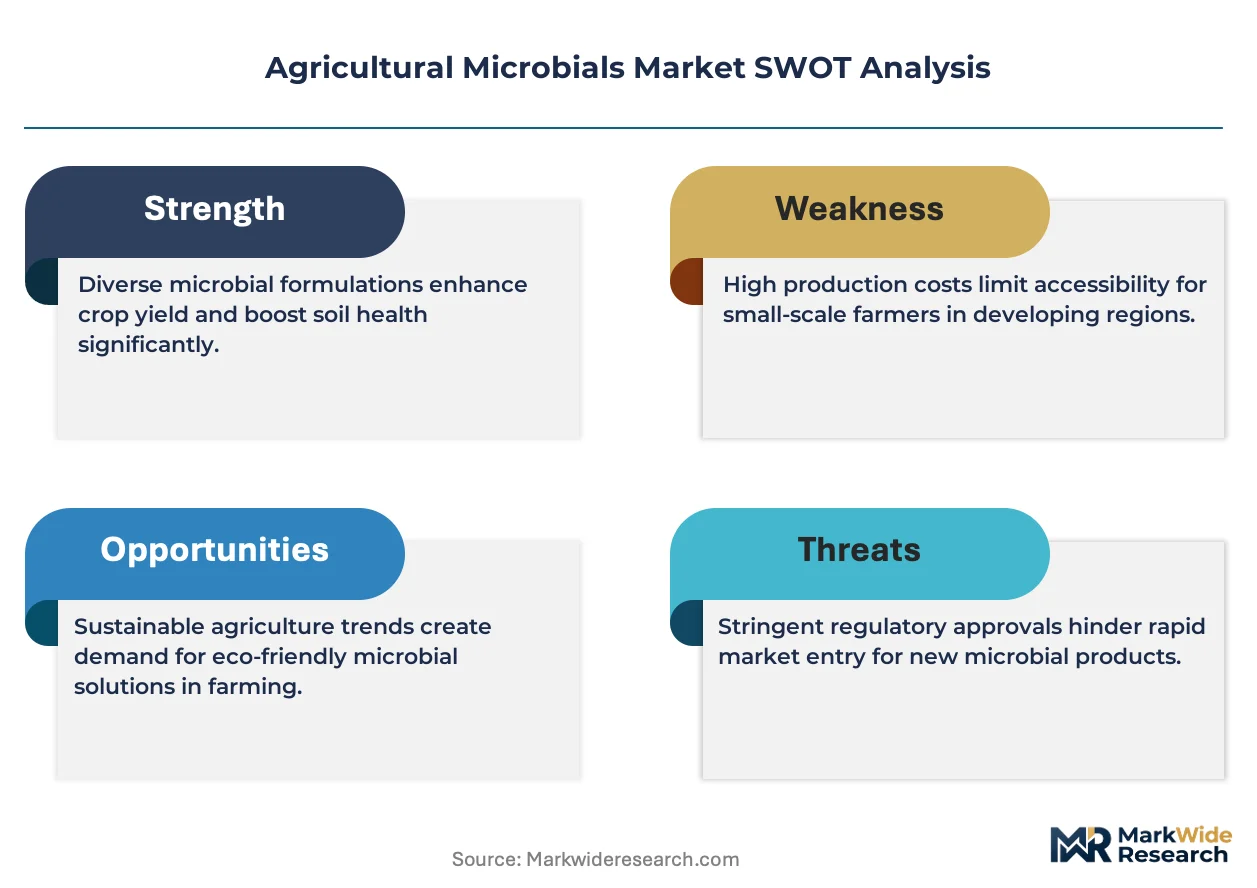
Regulatory frameworks from the US Environmental Protection Agency (EPA) and the European Food Safety Authority (EFSA) govern product registration and safety standards. These differing and lengthy approval processes create significant market access challenges. Future success depends on navigating complex regional regulatory landscapes while demonstrating clear, quantifiable return on investment for farmers and agricultural cooperatives.
Market Dynamics
The central force shaping the agricultural microbials market is the direct policy pressure from governments to reduce chemical pesticide and fertilizer use, exemplified by the EU Green Deal, which is compelling a systemic shift toward biological alternatives across global food supply chains.
Growth Catalysts
- Regulatory Mandates:The EU's Farm to Fork strategy and similar policies create a direct incentive for farmers to substitute conventional chemical inputs with microbial products to meet sustainability targets and maintain market access.
- Technology Integration:The bundling of microbial products with precision agronomy software provides farmers with data-driven application protocols, improving efficacy and demonstrating a clear return on investment.
- Demand Concentration:Adoption is intensifying in large-scale agricultural economies like Brazil and Argentina, particularly for high-value fruit, vegetable, and row crop cultivation where residue limits are strict.
Market Restraints
- Regulatory Asymmetry:Divergent and lengthy registration pathways between the US Environmental Protection Agency (EPA) and the European Food Safety Authority (EFSA) create significant barriers and costs for market access.
- Product Viability:The inherent sensitivity of live microorganisms to environmental factors like temperature and UV radiation leads to inconsistent field performance, which can hinder farmer confidence and repeat purchases.
- High R&D Costs:The significant investment required for microbial strain discovery, characterization, and large-scale fermentation process development limits market entry and competitive pricing from smaller innovators.
Strategic Opportunities
- Geographic Expansion:There is significant opportunity in Southeast Asia's intensive agriculture systems, such as for rice and palm oil, which are currently underpenetrated by advanced microbial solutions.
- Carbon Market Linkages:Developing microbial products specifically proven to enhance soil carbon sequestration can unlock new revenue streams for farmers participating in emerging carbon credit markets.
- Strain Enhancement:The application of CRISPR and other gene-editing tools to optimize microbial traits for specific climates, soil types, or target pests offers a path to next-generation product efficacy.
Industry Challenges
- Efficacy Standardization:A lack of universally accepted protocols for testing and verifying the field performance of microbial products makes it difficult for growers to compare offerings and make informed purchasing decisions.
- Logistical Complexity:Maintaining the viability of live biological products through the supply chain requires specialized handling, including cold chain logistics, which adds cost and complexity compared to shelf-stable chemicals.
- Specialized Talent Scarcity:The industry faces a shortage of professionals with combined expertise in microbiology, agronomy, and data science needed to develop and support integrated biological programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Microbials Market |
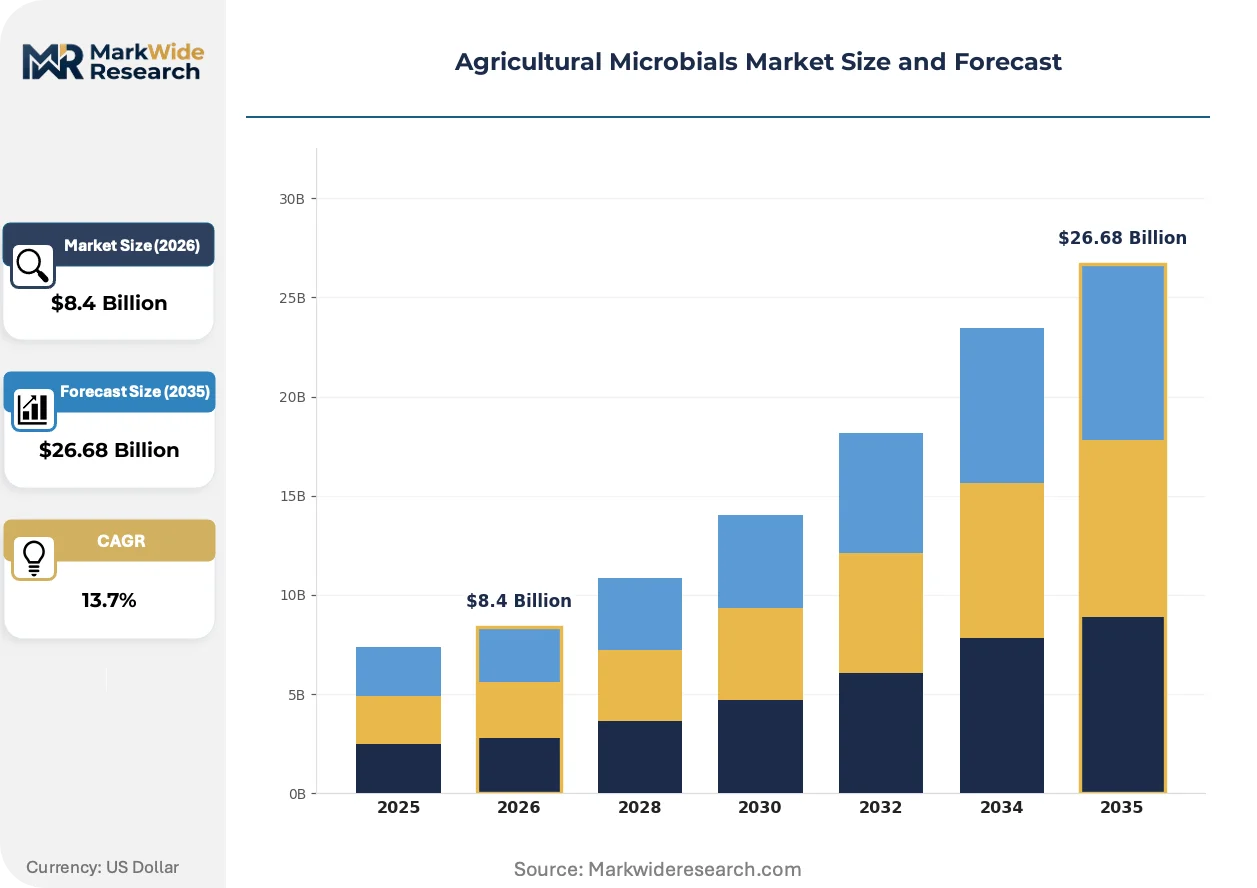
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biofertilizers, Biopesticides, Soil Amendments, Inoculants Application: Crop Protection, Soil Health, Seed Treatment, Foliar Application End User: Farmers, Agricultural Cooperatives, Distributors, Research Institutions Distribution Channel: Direct Sales, Retail, E-commerce, Wholesale |
| Companies Covered | BASF SE, Bayer AG, Corteva, Syngenta Group, UPL, FMC Corporation, Sumitomo Chemical Co., Ltd., Koppert Biological Systems, Novonesis Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Microbials Market Strategic Shifts & Innovations
Innovation in the agricultural microbials sector is pivoting from product discovery alone toward ensuring performance reliability in the field. The market is evolving from selling standalone inoculants to providing integrated systems that combine biology, digital tools, and agronomic advice to deliver predictable outcomes.
Advanced formulation science, including encapsulation and polymer coatings, protects live microbes from environmental stressors. Commercial growers in the US Midwest and Brazil are adopting these next-generation formulations to improve compatibility with existing farm equipment and application windows. This formulation technology is absorbing the performance variability risk that previously limited farmer trust in liquid biologicals.
Regulatory frameworks are actively encouraging soil health as a public good. The United States Department of Agriculture (USDA) is promoting carbon farming and regenerative practices through its conservation and climate-smart commodity programs. This policy direction creates direct financial incentives for adopting products like microbial soil amendments, prompting manufacturers to focus R&D on quantifiable soil health benefits.
A notable behavioral shift is occurring in how large agricultural cooperatives procure biologicals, moving away from simple transactional purchases. They are increasingly entering into performance-based agreements with microbial suppliers that tie payment to demonstrated yield improvements or pest reduction. This trend, most visible in North America, favors suppliers who can provide extensive data analytics and in-field agronomic support.
Agricultural Microbials Market Segmentation
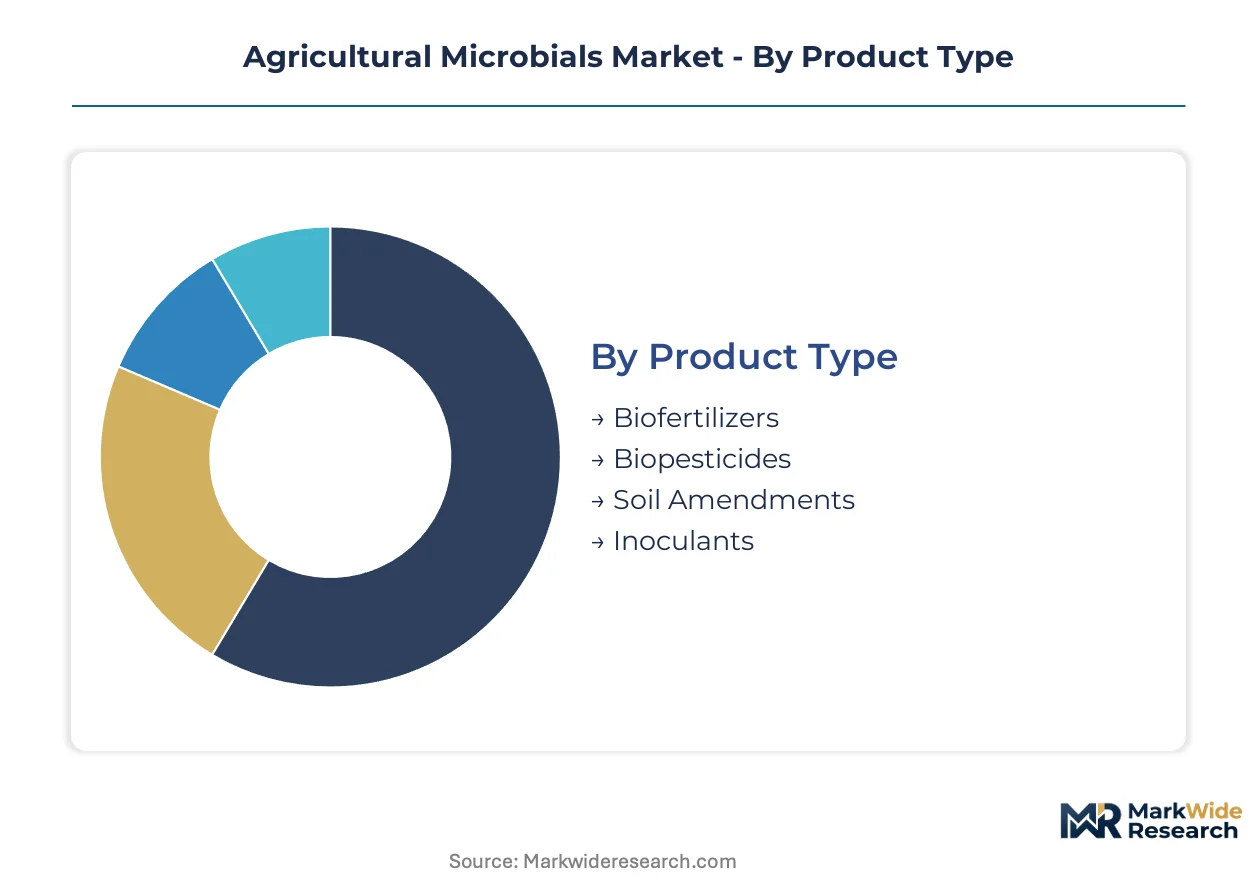
The agricultural microbials market delineates into distinct segments, each presenting unique development trajectories and investment requirements. Understanding these divisions allows stakeholders to identify optimal entry points and tailor product strategies effectively. Market segmentation reveals where innovation and demand converge.
Product Type:
The capital-intensive nature of product development varies significantly across microbial product types, particularly in the extensive R&D required for novel strain identification and large-scale manufacturing processes.
- Biopesticides:These formulations contain microorganisms or their metabolites that control agricultural pests, including insects, nematodes, and plant pathogens. Demand is concentrating in high-value fruit and vegetable cultivation in Brazil, driven by consumer preference for residue-free produce.
- Biofertilizers:These products enhance plant nutrition by fixing atmospheric nitrogen, solubilizing soil phosphorus, or stimulating plant growth through various microbial processes. Commercial growers in the US Midwest are increasingly adopting biofertilizers to improve nutrient use efficiency and reduce synthetic fertilizer dependence.
- Soil Amendments:Microbial soil amendments improve soil structure and fertility, supporting long-term farm resilience.
- Inoculants:These products introduce beneficial microbes to seeds or soil, promoting early plant growth and root development.
Biopesticides absorb the bulk of installed capacity; Soil Amendments are expanding most quickly.
Application:
Applications for agricultural microbials differentiate based on their primary functional benefit to the crop or soil ecosystem, influencing farmer adoption and product positioning.
- Soil Health:These applications focus on improving soil structure, nutrient cycling, and microbial diversity, directly supporting regenerative agriculture principles. Farmers in Argentina are increasingly utilizing soil health applications to enhance long-term productivity and carbon sequestration.
- Crop Protection:Microbial products in crop protection suppress specific plant diseases or pests, offering a biological alternative to chemical pesticides. Adoption is intensifying in European markets due to stringent regulatory mandates against synthetic chemicals.
- Seed Treatment:Microbials applied to seeds provide early-season protection and growth enhancement, establishing strong plant stands.
- Foliar Application:These methods involve spraying microbial solutions directly onto plant leaves for nutrient uptake or pest control.
Soil Health applications receive significant R&D investment; Crop Protection applications are gaining share fastest.
End User:
End-user segments exhibit distinct procurement patterns and decision-making criteria, reflecting their operational scale and strategic objectives within the agricultural value chain.
- Farmers:Individual farmers represent the direct consumers of microbial products, making purchasing decisions based on perceived return on investment and ease of integration with existing practices. Small and medium-sized farms in the US are gradually increasing their use of biologicals to comply with changing market demands.
- Agricultural Cooperatives:These organizations aggregate demand from multiple farmers, often negotiating bulk purchases and seeking performance-based agreements with suppliers. Large cooperatives in North America are driving the shift towards integrated biological solutions bundled with agronomic support.
- Distributors:Distributors serve as intermediaries, managing logistics and regional market access for microbial product manufacturers.
- Research Institutions:These entities focus on advancing microbial science and product validation, influencing future market development.
Farmers constitute the largest volume segment; Agricultural Cooperatives are driving procurement innovation.
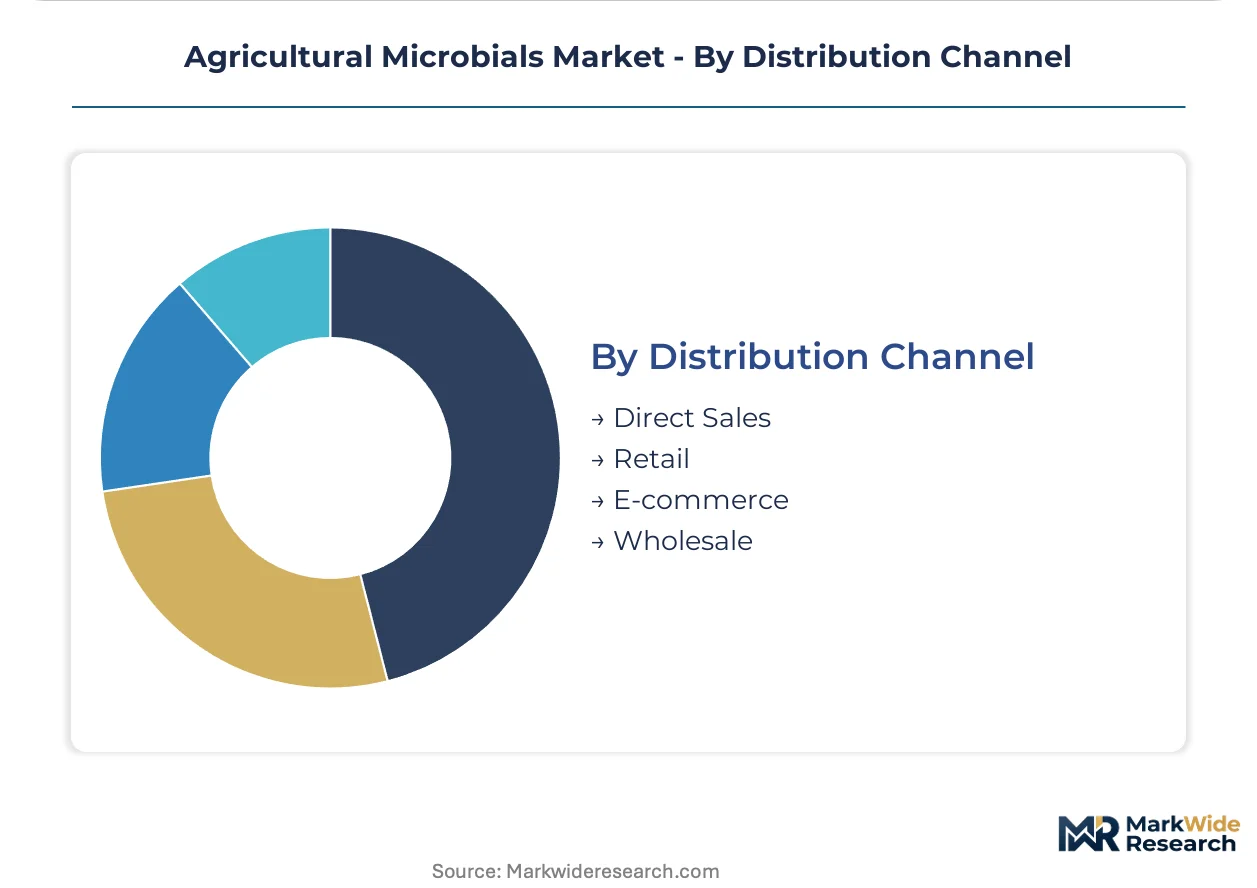
Distribution Channel:
Distribution channels define the reach and market penetration strategies for agricultural microbial products, influencing accessibility and customer engagement across diverse agricultural regions.
- Wholesale:This channel involves selling large volumes of microbial products to agricultural input suppliers, regional distributors, or large farm groups. Wholesale networks enable broad market penetration, particularly in established agricultural economies like the US Midwest.
- Direct Sales:Manufacturers engage directly with farmers or large agricultural enterprises, often providing specialized technical support and customized solutions. Direct sales are crucial for complex biological products requiring extensive grower education and tailored application protocols.
- Retail:Agricultural retail stores offer microbial products alongside other farm inputs, catering to a wide base of smaller growers.
- E-commerce:Online platforms provide a growing avenue for purchasing microbial products, particularly for specialty or niche applications.
Wholesale channels facilitate the broadest market reach; Direct Sales channels ensure specialized product support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A significant divide exists between regions focused on large-scale agricultural production and those prioritizing sustainable consumption. Major agricultural economies drive demand for microbial solutions to enhance crop resilience and reduce chemical inputs. This market dynamic influences product development and regulatory alignment across diverse geographies.
United States
Demand for biofertilizers and soil amendments is strong in the US Midwest, driven by farmer interest in nutrient use efficiency. The United States Department of Agriculture (USDA) promotes carbon farming and regenerative practices through conservation programs. Midwestern agricultural hubs, like those in Iowa and Illinois, see increased adoption of microbial products for row crops.
Brazil
High-value fruit and vegetable cultivation in Brazil creates significant demand for biopesticides, driven by consumer preference for residue-free produce. Brazil's regulatory body, ANVISA, is streamlining approval processes for biological inputs to support sustainable agriculture. The agricultural regions of São Paulo and Paraná are experiencing rapid growth in microbial product use for specialty crops.
Argentina
Farmers in Argentina increasingly utilize soil health applications to enhance long-term productivity and carbon sequestration. Government initiatives in Argentina support regenerative agriculture principles, encouraging biological input adoption. The Pampas region, a major agricultural area, is a key adopter of microbial soil amendments to improve soil structure.
Germany
Germany, as a key European market, sees strong demand for microbial crop protection products due to stringent regulatory mandates against synthetic chemicals. The EU Green Deal and its Farm to Fork strategy compel farmers to seek biological alternatives. Agricultural centers in Bavaria and North Rhine-Westphalia are at the forefront of adopting advanced biological solutions.
India
India's intensive agriculture systems, particularly for rice and other staple crops, present significant opportunities for microbial solutions to improve yields and reduce chemical dependency. The Indian government promotes organic farming and sustainable agricultural practices through various schemes. States like Maharashtra and Uttar Pradesh are seeing increased interest in biofertilizers and inoculants for improved crop performance.
Agricultural Microbials Market Key Industry Players
Capital-heavy producers with extensive chemical portfolios compete with asset-light biotech specialists focused on microbial innovation. The market structure exhibits a tiered consolidation, with large agricultural science companies at the top. Strategic archetypes include diversified input providers, pure-play biologicals firms, and niche technology developers. M&A activity and strategic partnerships characterize competitive moves as companies seek to expand product portfolios and market reach.
Within the diversified agricultural science archetype, companies like Bayer AG anchor broad portfolios, integrating microbial solutions with established chemical crop protection offerings. Novonesis Group exemplifies specialized expertise in microbial strain discovery and large-scale fermentation, representing firms focused on core biological R&D and manufacturing capabilities. Koppert Biological Systems, on the other hand, represents a pure-play biologicals firm, emphasizing natural control and pollination systems through a dedicated biological approach to sustainable agriculture. These archetypes reflect varied strategic priorities across the market.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Corteva |
| Syngenta Group |
| UPL |
| FMC Corporation |
| Sumitomo Chemical Co., Ltd. |
| Koppert Biological Systems |
| Novonesis Group |
| Others |
Cost & Logistics Intelligence
Vertical integration by large agricultural science companies anchors both the supply position and the pricing power within the agricultural microbials market. This strategic choice allows firms to control microbial strain development, fermentation, and distribution, influencing product availability and cost structures.
Pricing Analysis
Margin tightening in the biologicals segment reflects inconsistent field performance and high R&D investment for novel strains. Hybrid transactional and performance-based models are gaining traction, especially with agricultural cooperatives. Pricing stratifies across premium, standard, and economy tiers based on digital integration and agronomic support. Farmers exhibit higher price sensitivity compared to large agricultural cooperatives seeking guaranteed performance outcomes.
Supply Chain Analysis
Specialized freight requirements, including cold chain logistics, elevate costs across the agricultural microbials supply chain. Supply concentrates in regions with advanced fermentation capabilities, such as parts of Europe and North America, drawing from global microbial strain banks. Single-source vulnerability for specific high-performing strains presents a structural risk. Distribution runs through a combination of wholesale networks and direct sales channels to farmers and cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained story, where the lengthy and capital-intensive microbial strain discovery and large-scale fermentation processes create a capacity bottleneck propping pricing.
For Market Incumbents: Anchor broad product portfolios by integrating microbial solutions with established chemical offerings. Invest heavily in advanced formulation science to protect live microbes, addressing performance variability and farmer trust issues. Leverage existing digital farming platforms to bundle microbial products with precision agronomy software, demonstrating clear return on investment against regulatory shifts like the EU Green Deal.
For New Entrants and Emerging Players: Begin with targeted solutions for underpenetrated geographies like Southeast Asia's intensive agriculture systems, focusing on specific crops like rice or palm oil. Develop products specifically proven for soil carbon sequestration to unlock new revenue streams from emerging carbon credit markets. Go-to-market strategies should emphasize data-driven efficacy and integrated agronomic support for specific soil health applications.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized biotech firms and pure-play biologicals companies with strong intellectual property in microbial strain discovery. The long-term viability of the market is anchored by global policy pressure to reduce chemical inputs and consumer demand for residue-free produce. A critical signal to watch is the regulatory harmonization of approval processes across major agricultural economies like the US and EU.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Formulation Development | Protects live microbes from environmental stressors, improving field performance and farmer confidence. |
| Digital Platform Integration | Bundles microbial products with precision agronomy software for data-driven application protocols. |
| Regulatory Pathway Acceleration | Navigates US EPA and European EFSA approval processes, reducing market access barriers. |
| CRISPR-based Strain Enhancement | Optimizes microbial traits for specific climates and soil types, boosting product efficacy. |
| Carbon Sequestration Product Development | Unlocks new revenue streams for farmers participating in emerging carbon credit markets. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for market sizing and trend identification. Primary interviews with agronomists, R&D directors, and farm cooperative managers provided qualitative insights. This approach triangulated bottom-up market intelligence with top-down industry perspectives. Secondary sources included USDA reports, EFSA publications, and company annual reports.
Data stream reconciliation integrated historical market performance with future growth projections across the analysis window. The analytical framework modeled product type, application, end user, distribution channel, and regional policy environment. Compound annual growth rates were derived from a multi-factor regression model. Regulatory mandate timelines and farmer adoption rates in high-value crops served as key forecast inputs.
Underlying measurement precision varies by segment; biopesticides and biofertilizers carry tighter precision than soil amendments. Forecasts reflect assumptions regarding regulatory evolution and technological advancements. Field performance variability and R&D success rates remain critical risk factors. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Silybum Marianum Market
Agricultural Biologicals
United States Animal Feed Additives Market
Agricultural Biologicals
Monolaurin for Feed Market
Agricultural Biologicals
Edible Fungus Market
Agricultural Biologicals
Latin America Animal Feed Additives Market
Agricultural Biologicals
North America Feed Prebiotics Market
Agricultural Biologicals
Agricultural Adjuvants Market
Agricultural Biologicals
South America Beta-Glucan Market
Agricultural Biologicals
Asia Pacific Silage Inoculant Market
Agricultural Biologicals
Middle East and Africa Bio-Stimulants Market
Agricultural Biologicals
Agricultural Activator Adjuvants Market
Agricultural Biologicals
Animal Feed Additives Market
Agricultural Biologicals
Agricultural Biofungicides Market
Agricultural Biologicals
Chitosan for Agriculture Market
Agricultural Biologicals
North America Amino Acids Market
Agricultural Biologicals
Global Organic Trace Minerals for Animal Feeds Market