
 South America Biostimulants Market | 2026-2036
South America Biostimulants Market Size, Share, and Industry Trends Forecast 2026-2036
South America Biostimulants Market Analytics
CE marking alignment under EU Green Deal spillover standards is unwinding competitive access for non-compliant suppliers across South American export corridors. BASF SE leverages its microbial fermentation infrastructure to anchor supply security for Brazilian soybean cooperatives. Valagro SpA specializes in seaweed extract formulations calibrated for tropical humidity regimes. Koppert Biological Systems Inc. competes through integrated biological crop protection portfolios that bundle biostimulants with biocontrol agents.
Biostimulants comprise organic and biological substances that enhance plant metabolic processes, nutrient uptake efficiency, and stress tolerance without direct fertilization or pesticidal action. These inputs typically contain humic acids, seaweed extracts, amino acids, or microbial consortia applied at grams-to-kilograms per hectare rates to modulate phytohormone signaling and root exudation patterns. Humic acids dominate volume flows due to established extraction infrastructure and compatibility with existing liquid fertilizer injection systems. Seaweed extracts command premium positioning among horticultural crop exporters serving European retail chains. Microbial products represent the fastest-expanding category as Brazilian research stations validate rhizobia and mycorrhizal inoculants for phosphorus-deficient Cerrado soils.
ANVISA governs biological input registration timelines in Brazil, while Argentina's national agricultural technology institute (INTA) sets field efficacy validation protocols that filter unsubstantiated product claims. REACH-equivalent chemical safety assessments under Mercosur harmonization discussions are raising formulation disclosure requirements for imports. Stakeholders must track regulatory divergence between Brazilian state-level organic certification bodies and federal biostimulant classification standards to anticipate compliance cost shifts.
Market Dynamics
ANVISA's streamlined registration pathways for biological inputs are compressing product launch timelines, allowing foreign microbial consortia suppliers to bypass the historical 18-24 month backlog that previously protected domestic incumbents.
Growth Catalysts
- EU Green Deal spillover:CE marking alignment requirements for agricultural exports to European retail chains are compelling Brazilian soybean cooperatives to adopt certified biostimulant protocols.
- Phosphorus-deficient Cerrado soils:Brazilian research stations have validated mycorrhizal inoculants for nutrient uptake in the nation's dominant soybean belt, creating pull-through demand for microbial formulations.
- Argentina's INTA field protocols:Standardized efficacy validation frameworks are filtering unsubstantiated product claims, improving buyer confidence among Pampas wheat farmers.
Market Restraints
- Seaweed extract supply concentration:Premium-grade Ascophyllum nodosum harvesting remains concentrated in Atlantic coastal zones, exposing formulators to raw material bottlenecks.
- Mercosur REACH-equivalent negotiations:Proposed chemical safety assessment harmonization is raising formulation disclosure requirements that threaten proprietary microbial strain protections.
- Humic acid price volatility:Leonardite mining output fluctuations in Brazil's Minas Gerais state are compressing margins for volume-dependent liquid fertilizer co-packers.
Strategic Opportunities
- Biocontrol-biostimulant bundling:Integrated biological crop protection portfolios are opening channel access through Argentine distributor networks previously closed to standalone input suppliers.
- State-level organic certification divergence:Fragmented standards between Brazilian federal biostimulant classifications and state organic bodies create arbitrage openings for compliance-specialist formulators.
- Tropical humidity calibration:Seaweed extract formulations optimized for high-moisture storage conditions address a technical gap in existing European-imported products.
Industry Challenges
- Microbial strain banking infrastructure:Limited domestic cryopreservation capacity forces Brazilian suppliers to rely on overseas culture collections, extending R&D iteration cycles.
- Fermentation scale-up expertise:Scarcity of industrial bioprocess engineers familiar with agricultural microbial production is constraining capacity expansion at domestic manufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Biostimulants Market |
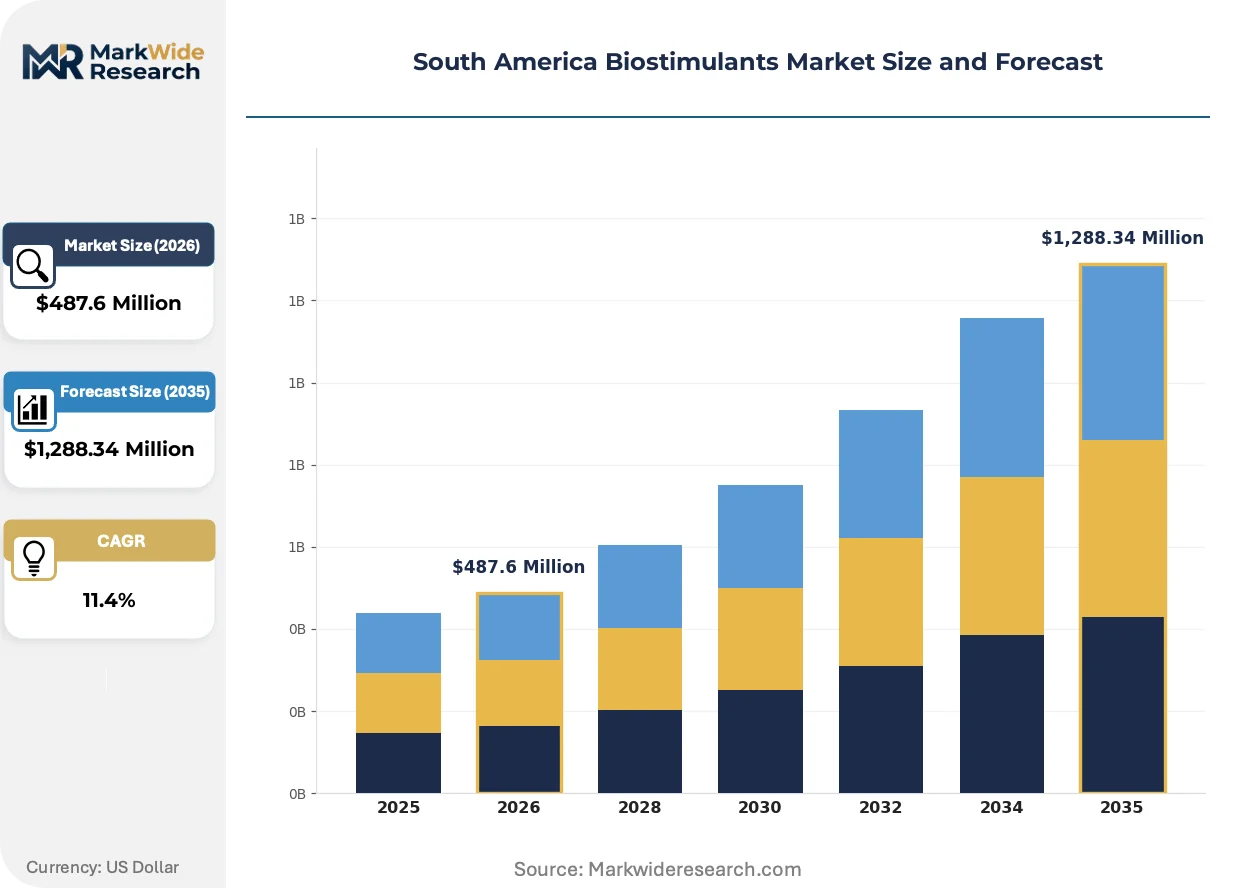
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Humic Acids, Seaweed Extracts, Amino Acids, Microbial Products Application: Agricultural Crops, Horticultural Crops, Turf, Ornamentals End User: Farmers, Agricultural Cooperatives, Distributors, Retailers Delivery Mode: Liquid, Granular, Powder, Foliar Spray |
| Companies Covered | Biolchim SpA, Humic Growth Solutions Inc., Koppert Biological Systems Inc., Trade Corporation International, Vittia Group, UPL, Syngenta, BASF SE, Valagro SpA, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Biostimulants Market Evolving Landscape
Formulation science and regulatory disclosure requirements are actively restructuring competitive advantage in South American biostimulants, compressing the window between laboratory validation and field-scale deployment.
Microbial consortia development is bifurcating between single-strain precision products and multi-species soil conditioning blends. Large-scale soybean operations in Brazil's Mato Grosso are adopting consortium formulations at accelerating rates. This technology divergence is enabling tiered pricing architectures that separate premium inoculant segments from commodity humic acid markets.
ANVISA's biological input registration reforms are mandating accelerated stability data submission timelines. Foreign suppliers now face compressed documentation requirements that previously delayed market entry. Argentine exporters serving EU-bound horticultural channels are responding by front-loading registration investments to capture first-mover positioning under Mercosur harmonization discussions.
Cooperative procurement consolidation is restructuring input acquisition patterns across the Brazilian Cerrado. Regional soybean cooperatives are displacing independent distributor relationships with direct manufacturer negotiations. This channel compression is most visible in Mato Grosso do Sul, where three purchasing cooperatives now control the majority of microbial inoculant volume.
South America Biostimulants Market Segmentation
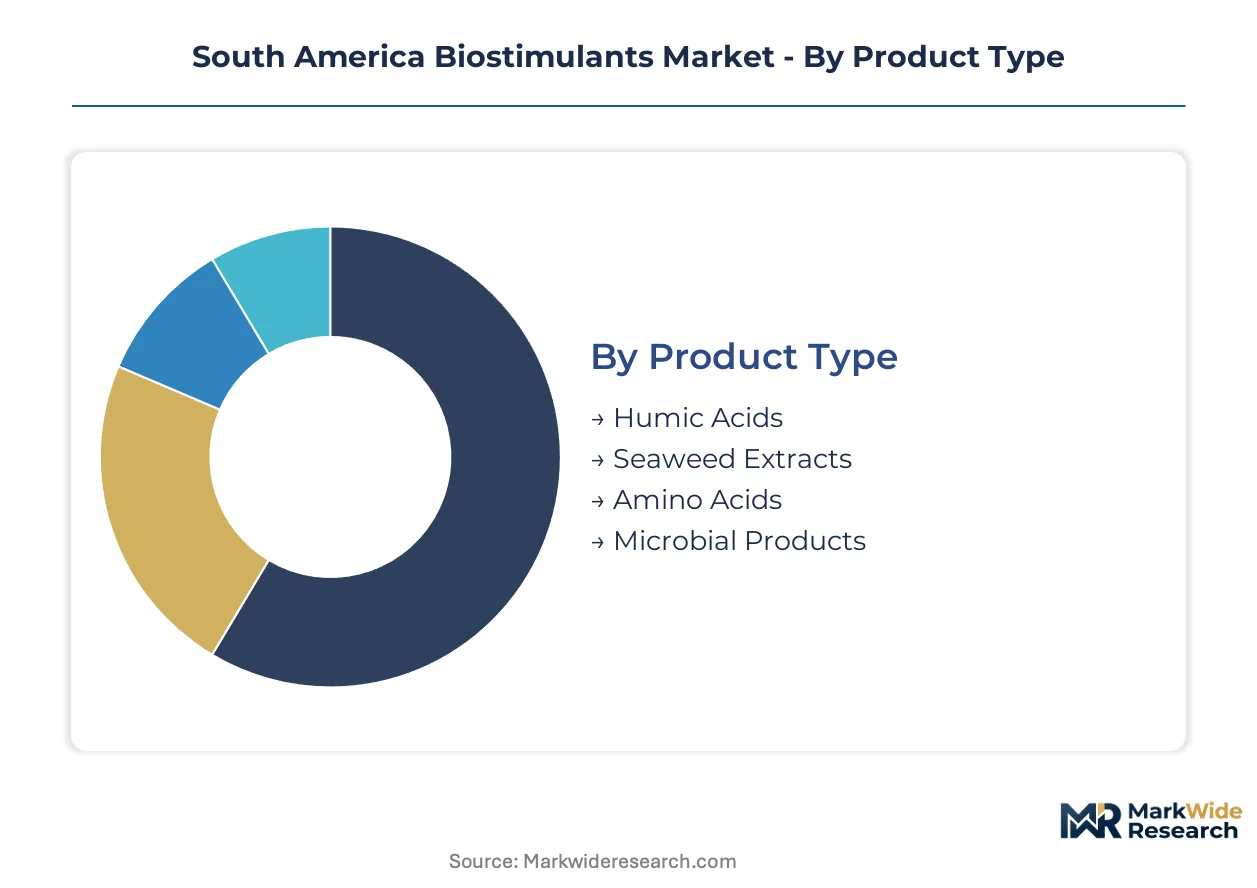
Biostimulant segmentation in South America reflects divergent agronomic requirements across Brazil's Cerrado soybean belt and Argentina's Pampas wheat corridor. Product formulators must align technical specifications with state-level organic certification standards and cooperative procurement consolidation patterns.
Product Type:
Humic acid formulations face substitution pressure from microbial consortia as phosphorus-deficient soil conditions in Mato Grosso drive biological alternatives.
- Humic Acids:Leonardite-derived formulations dominate volume flows through compatibility with existing liquid fertilizer injection infrastructure. Demand concentrates among Brazilian soybean cooperatives seeking cost-efficient soil conditioning for extensive Cerrado operations, though leonardite mining fluctuations in Minas Gerais create margin compression.
- Microbial Products:Rhizobia and mycorrhizal inoculants command accelerating adoption following ANVISA registration streamlining. Brazilian research stations validated phosphorus uptake efficacy for Cerrado soils, pulling through demand from Mato Grosso purchasing cooperatives now controlling majority inoculant volume.
- Seaweed Extracts:Premium Ascophyllum nodosum formulations serve horticultural exporters to EU retail chains requiring CE marking alignment.
- Amino Acids:Protein hydrolysate products address stress tolerance applications in Argentina's Pampas wheat corridor under INTA field protocol validation.
Humic acids anchor the volume base while microbial products gain share at the steepest rate.
Application:
Cost tier differentiation separates commodity row crop inputs from premium horticultural formulations serving export certification requirements.
- Agricultural Crops:Soybean and wheat applications absorb the majority of microbial inoculant volume across Brazil's Cerrado and Argentina's Pampas. Cooperative procurement consolidation in Mato Grosso do Sul has compressed distributor margins while accelerating direct manufacturer negotiations.
- Horticultural Crops:Seaweed extract and amino acid formulations command premium positioning for EU-bound export channels. Argentine producers serving European retail chains front-load registration investments to capture positioning under Mercosur harmonization discussions.
- Turf:Specialized formulations address golf course and sports field maintenance in Brazil's southeastern urban corridors.
- Ornamentals:Nursery applications concentrate in São Paulo state's floriculture export zones.
Agricultural crops absorb the dominant volume share while horticultural applications expand most quickly on certification-premium pricing.
End User:
Customer type restructuring is displacing traditional distributor relationships as cooperative procurement consolidation accelerates across the Brazilian Cerrado.
- Farmers:Individual operators in Argentina's Pampas wheat corridor rely on INTA-validated product claims to filter unsubstantiated microbial formulations. Smaller Brazilian holdings access biostimulants through state-level organic certification arbitrage opportunities.
- Agricultural Cooperatives:Three purchasing cooperatives in Mato Grosso do Sul now control majority microbial inoculant volume, displacing independent distributor channels. Direct manufacturer negotiations compress margin structures while securing supply security for large-scale soybean operations.
- Distributors:Argentine networks previously closed to standalone suppliers now open through biocontrol-biostimulant bundling strategies.
- Retailers:Input retailers face channel compression as cooperative procurement consolidation accelerates.
Agricultural cooperatives anchor the volume base while distributor relationships contract fastest under channel restructuring.
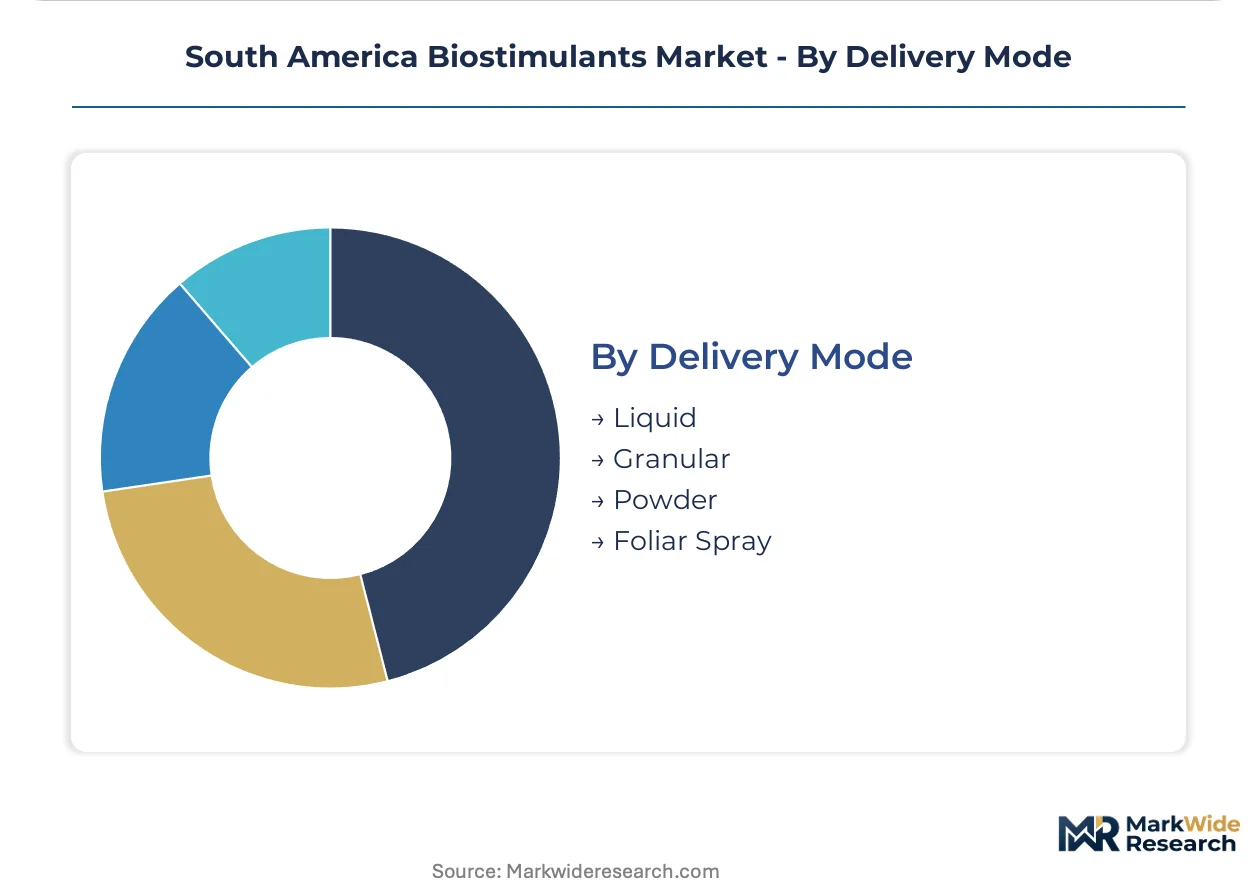
Delivery Mode:
Supply concentration in liquid formulation infrastructure shapes competitive access for granular and powder alternatives.
- Liquid:Humic acid and microbial inoculant formulations dominate through compatibility with existing fertilizer injection systems. Brazilian liquid fertilizer co-packers in Minas Gerais face margin pressure from leonardite price volatility.
- Foliar Spray:Seaweed extract and amino acid applications concentrate in horticultural export zones requiring precise timing for EU certification compliance. Argentine producers optimize spray protocols under INTA field efficacy validation frameworks.
- Granular:Soil-applied microbial products address phosphorus-deficient Cerrado conditions through direct root zone placement.
- Powder:Dry formulations serve storage efficiency requirements in high-humidity tropical conditions.
Liquid delivery anchors the volume base while foliar spray gains share fastest on horticultural premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cooperative procurement consolidation across the Brazilian Cerrado and export-certification pressures on Argentine horticultural producers are concentrating buyer power among large-scale agricultural operations. ANVISA registration reforms and INTA field protocols are filtering market access for foreign suppliers while elevating compliance costs for unsubstantiated formulations.
Brazil
Mato Grosso purchasing cooperatives now control majority microbial inoculant volume, displacing traditional distributor channels through direct manufacturer negotiations. ANVISA's streamlined biological input registration compresses product launch timelines for foreign microbial consortia suppliers. São Paulo state's floriculture export zones concentrate nursery applications for ornamental biostimulant formulations.
Argentina
Pampas wheat farmers rely on INTA-validated product claims to filter unsubstantiated microbial formulations, improving buyer confidence in biological inputs. Field efficacy validation frameworks under national agricultural technology institute protocols raise formulation disclosure requirements for imports. Buenos Aires province horticultural exporters front-load registration investments to capture positioning under Mercosur harmonization discussions.
Chile
Central Valley fruit exporters serving European retail chains adopt CE marking-aligned biostimulant protocols to maintain market access. The country's national agricultural regulator enforces chemical safety assessments that parallel REACH-equivalent standards under regional harmonization. Metropolitan Santiago distribution networks channel premium seaweed extract formulations to table grape and cherry operations.
Colombia
Coffee cooperatives in the Zona Cafetera integrate microbial biostimulants into renovation programs for aging plantation stock. The national agricultural health institute oversees biological input registration with timelines shorter than historical Brazilian backlogs. Antioquia department input distributors bundle biocontrol agents with biostimulants to access previously closed cooperative procurement channels.
Uruguay
Pasture improvement programs drive humic acid demand among extensive livestock operations seeking cost-efficient soil conditioning. Mercosur regulatory harmonization discussions expose domestic formulators to elevated formulation disclosure requirements. Montevideo metropolitan area technical service providers calibrate seaweed extract applications for high-humidity storage conditions.
South America Biostimulants Market Competitive Landscape
Player mix skews toward multinational agrochemical conglomerates with microbial fermentation infrastructure and specialized biological input formulators with tropical calibration expertise. Market structure exhibits tiered consolidation around three purchasing cooperatives in Mato Grosso do Sul controlling dominant inoculant volume. Strategic archetypes include integrated biological crop protection bundlers, seaweed extract tropical formulation specialists, and microbial strain banking operators. Dominant competitive moves encompass direct cooperative negotiation displacing distributor channels and accelerated ANVISA registration investments capturing first-mover positioning.
Among Italian-origin formulators, Biolchim SpA and Valagro SpA exemplify the premium-tier specialization archetype focused on seaweed extract and amino acid formulations. BASF SE anchors the multinational conglomerate tier with microbial fermentation infrastructure securing supply relationships with Brazilian soybean cooperatives. Koppert Biological Systems Inc. occupies a position within the integrated biological crop protection segment, representing the bundling strategy that opens Argentine distributor networks through combined biostimulant and biocontrol portfolios.
| Leading Market Players |
|---|
| Biolchim SpA |
| Humic Growth Solutions Inc. |
| Koppert Biological Systems Inc. |
| Trade Corporation International |
| Vittia Group |
| UPL |
| Syngenta |
| BASF SE |
| Valagro SpA |
| Others |
Value Network & Pricing Analysis
CE marking alignment under EU Green Deal spillover standards gates both supply qualification for Argentine horticultural exporters and price differentiation between certified and uncertified biostimulant tiers. ANVISA registration reforms simultaneously compress documentation timelines for foreign suppliers while raising compliance cost floors that stratify pricing across microbial consortia categories.
Pricing Analysis
Cost-plus contracts with leonardite indexation dominate humic acid procurement for Brazilian liquid fertilizer co-packers. Three-tier pricing structure across premium microbial inoculants, standard seaweed extracts, and economy humic acids reflects certification grade and volume scale differentials. Pricing pressure stems from cooperative procurement consolidation in Mato Grosso do Sul, where direct manufacturer negotiations compress distributor margins. Agricultural cooperatives exhibit lowest price sensitivity due to supply security priorities, while independent retailers face acute margin compression.
Supply Chain Analysis
Strategic stockpiling of Ascophyllum nodosum raw material dominates over just-in-tim preferences due to Atlantic coastal harvesting concentration and seasonal availability constraints. Supply draws from Brazil's Minas Gerais leonardite mines, Chilean seaweed processing facilities, and European microbial culture collections. Raw material dependencies center on phosphorus-deficient Cerrado soil amendments, tropical humidity-stabilized formulations, and cryopreserved strain banks. Single-source vulnerability runs through overseas culture collection dependencies for Brazilian microbial suppliers. Distribution runs through Mato Grosso purchasing cooperatives displacing traditional independent distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America biostimulants market is recovering from registration backlog cyclicality as ANVISA streamlining compresses product launch timelines and pulls forward demand from phosphorus-deficient Cerrado soybean operations.
For Market Incumbents: Compound defensive positioning through backward integration into leonardite mining assets in Minas Gerais and accelerated ANVISA registration investments capturing first-mover positioning under Mercosur harmonization discussions. Threat substitution from microbial consortia demands fermentation capacity expansion and cryopreservation infrastructure buildout to secure strain banking autonomy. For New Entrants and Emerging Players: ANVISA's biological input fast-track creates entry arbitrage for foreign microbial consortia suppliers previously blocked by 18-24 month backlogs. White-space targets concentrate in tropical humidity-calibrated seaweed extracts for Brazilian storage conditions and biocontrol-biostimulant bundling for Argentine distributor networks. Go-to-market execution should prioritize direct cooperative negotiations in Mato Grosso do Sul over traditional distributor channel development. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across microbial fermentation infrastructure as Brazilian research station validation pulls through demand for rhizobia and mycorrhizal inoculants. Long-term viability over the next decade rests on regulatory compliance capabilities and tropical formulation expertise. Acquisition targets should emphasize ANVISA-registered product portfolios and established culture collection relationships. The signal to watch is Mercosur REACH-equivalent negotiation outcomes affecting proprietary strain disclosure requirements.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Fast-Track Investment | Compresses market entry timelines for foreign microbial consortia suppliers previously facing backlog protection. |
| Backward Integration into Leonardite Mining | Secures raw material cost control for humic acid formulators exposed to Minas Gerais output volatility. |
| Tropical Humidity Formulation Development | Addresses technical gaps in European-imported seaweed extracts for Brazilian high-moisture storage conditions. |
| Biocontrol-Biostimulant Bundling | Opens Argentine distributor networks previously closed to standalone input suppliers through integrated portfolios. |
| Cooperative Direct Negotiation | Captures volume concentration as three Mato Grosso do Sul purchasing cooperatives displace independent channels. |
Research Methodology
A standing panel of ANVISA regulatory affairs specialists, INTA field protocol researchers, Mato Grosso cooperative procurement managers, Argentine horticultural export compliance officers, and Brazilian liquid fertilizer co-packer operations directors provided ongoing calibration. Primary interviews combined with secondary validation from ANVISA registration databases, INTA efficacy trial publications, Mercosur harmonization discussion records, and Brazilian customs trade data. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and delivery mode dimensions.
Consistency checks validated volume and value outputs against external benchmarks including cooperative procurement volume disclosures, import registration filings, and research station adoption surveys. Segmentation modeling captured product type, application, end user, and delivery mode dimensions with regional regulatory cluster overlays. CAGRs were derived from trend extrapolation anchored to ANVISA registration timeline compression and Cerrado soil validation milestones. Industry-specific inputs included phosphorus deficiency severity indices and tropical humidity degradation rates for formulation stability assessment.
Underlying assumptions cover ANVISA registration reform continuity, Mercosur harmonization progression, and Cerrado soybean planting area stability, with deviation risk concentrated in leonardite mining output fluctuations and EU Green Deal certification requirement stringency shifts. Revision becomes warranted when Mercosur REACH-equivalent disclosure mandates cross thresholds threatening proprietary microbial strain protections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
India Feed Enzymes Market
Agricultural Biologicals
Soil Inoculants Market
Agricultural Biologicals
Agricultural Biofungicides Market
Agricultural Biologicals
Global Silage Inoculants Market
Agricultural Biologicals
Middle East and Africa Bio-Stimulants Market
Agricultural Biologicals
Asia Pacific Silage Inoculant Market
Agricultural Biologicals
North America Silage Inoculant Market
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
Baobab Market
Agricultural Biologicals
Europe Silage Inoculant Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
Animal Feed Additives Market
Agricultural Biologicals
North America Animal Feed Additives Market
Agricultural Biologicals
Feed Mycotoxin Binders Market
Agricultural Biologicals
Monolaurin for Feed Market
Agricultural Biologicals
Microbial Agricultural Inoculants Market