
 North America Feed Mycotoxin Detoxifiers Market | 2026-2036
North America Feed Mycotoxin Detoxifiers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Feed Mycotoxin Detoxifiers Market Analytics
Pharmaceutical-grade mycotoxin binder certification is rotating from niche premium to baseline procurement standard across North American feed compounders. Cargill leverages its integrated grain-handling network to pre-screen inbound corn for aflatoxin and DON contamination before blending. Alltech anchors its position through R&D intensity in yeast-cell-wall extraction protocols. BASF competes on manufacturing scale for modified aluminosilicate clays serving the layer-hen segment.
Feed mycotoxin detoxifiers comprise adsorbent, transformative, and biological agents engineered to sequester or degrade fungal metabolites including aflatoxin B1, zearalenone, and fumonisin in animal rations, with binding capacity typically measured at pH 6.5-7.0 to simulate intestinal conditions. Clay-based products occupy the largest volume share due to low cost-per-ton and established inclusion rates in ruminant diets. Biological detoxifiers represent the fastest-expanding category as enzymatic inactivation of trichothecenes gains validation from USDA-supported field trials. Yeast extracts concentrate margin pools in poultry applications where beta-glucan binders command specification premiums from integrators supplying antibiotic-free programs.
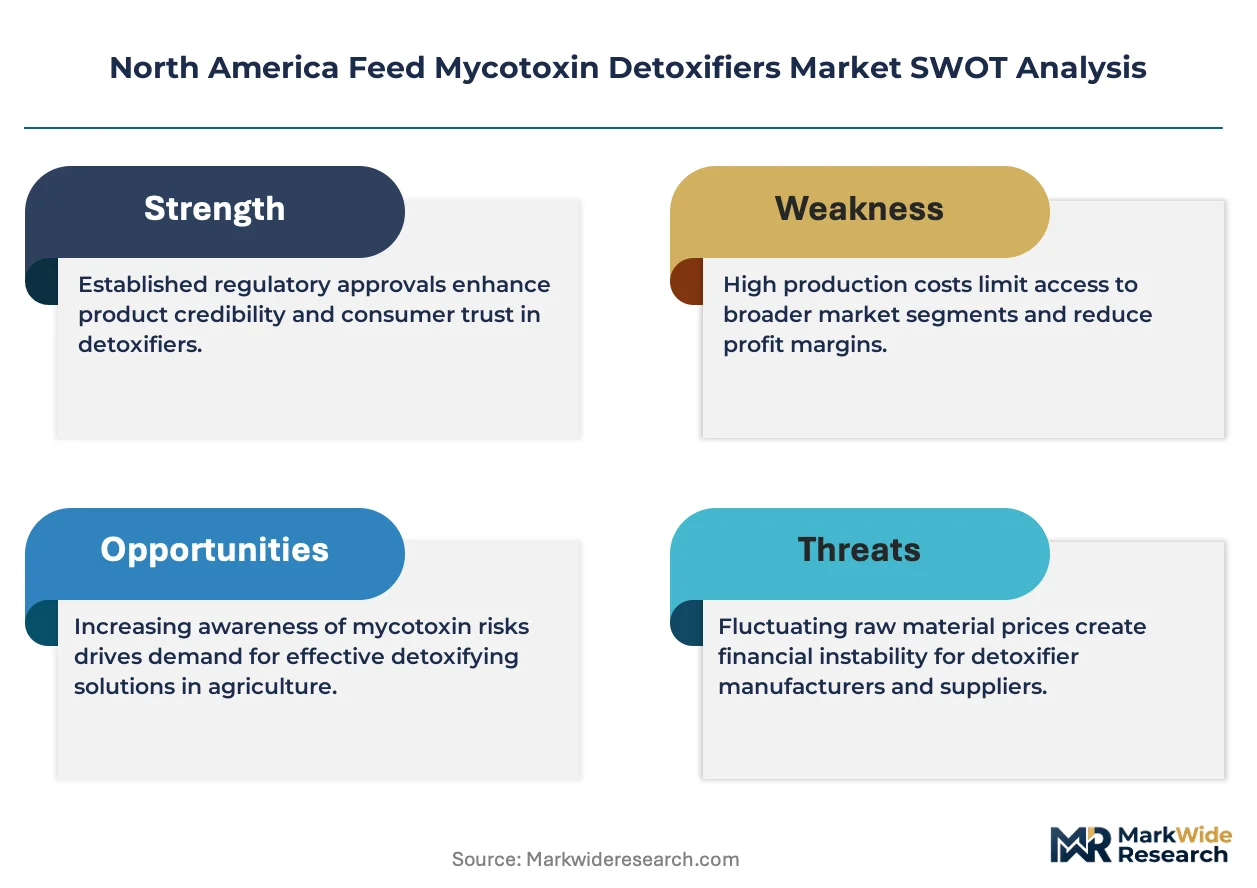
The FDA's Center for Veterinary Medicine enforces mycotoxin action levels in interstate feed shipments, while CFIA's Safe Feed for Animals Regulations mandate hazard analysis for Canadian mills importing U.S. grain. EPA biopesticide registration pathways for enzymatic detoxifiers create dual compliance obligations for biological product developers. Stakeholders must monitor whether FDA advances mandatory certificate-of-analysis requirements for mycotoxin binders sold into dairy channels, as this would reshape supplier qualification criteria and testing spend allocation across the value chain.
Market Dynamics
Climate-driven aflatoxin volatility in U.S. corn belts is forcing integrators to embed mycotoxin risk management into procurement workflows rather than treating it as a reactive quality control step.
Growth Catalysts
- FDA Dairy Feed Protocols:Expanded mycotoxin testing mandates for interstate dairy shipments are compelling compounders to specify validated binder technologies with certificate-of-analysis documentation.
- Enzymatic Detoxification:USDA-supported field trials validating trichothecene inactivation are accelerating biological detoxifier adoption among Midwest poultry integrators.
- Canadian Import Surveillance:CFIA's Safe Feed for Animals Regulations require hazard analysis for mills importing U.S. grain, creating cross-border demand for pre-certified detoxifier products.
Market Restraints
- Aluminosilicate Input Concentration:Modified clay feedstock supply concentrates among Wyoming and Georgia mining operations, exposing formulators to regional weather disruption risk.
- EPA Dual Registration Burden:Biological detoxifiers face parallel FDA food additive and EPA biopesticide compliance pathways, extending commercialization timelines by 18-24 months.
- Yeast Extract Supply Tightness:Beta-glucan binder production competes with human nutraceutical and pharmaceutical demand for Saccharomyces cerevisiae cell wall derivatives.
Strategic Opportunities
- Antibiotic-Free Poultry Specification:Beta-glucan binders command procurement premiums from integrators supplying retail antibiotic-free programs, concentrating margin pools in yeast-derived products.
- Layer-Hen Segment Specialization:Modified aluminosilicate clays with optimized binding capacity at pH 6.5-7.0 remain underpenetrated in cage-free egg production systems.
- Pre-Screening Service Integration:Grain-handling networks embedding mycotoxin detection before blending create bundled service opportunities for detoxifier suppliers with analytical capabilities.
Industry Challenges
- Field Validation Capacity Bottlenecks:Biological detoxifier developers face scarcity of qualified toxicology facilities capable of conducting species-specific efficacy trials under GLP standards.
- Certificate-of-Analysis Standardization:Absence of harmonized binding capacity testing protocols between FDA and CFIA creates duplicate analytical spend for suppliers serving both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Feed Mycotoxin Detoxifiers Market |
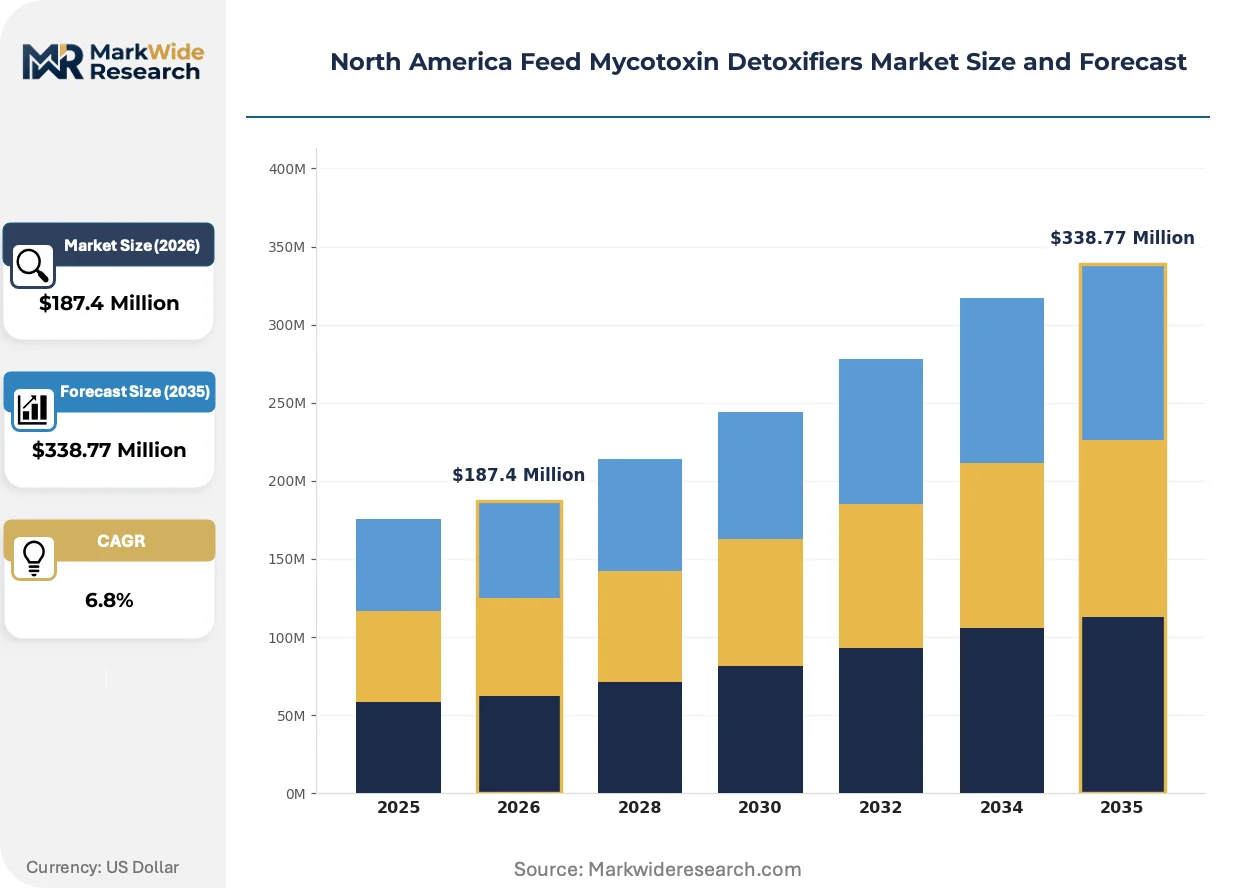
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clay-Based, Chemical Detoxifiers, Biological Detoxifiers, Yeast Extracts End User: Livestock, Poultry, Aquaculture, Pet Food Application: Prevention, Treatment, Feed Preservatives, Nutritional Supplements Distribution Channel: Direct Sales, Online Retail, Distributors, Agro Dealers |
| Companies Covered | Cargill, Alltech, Adisseo, DSM Nutritional Products, BASF, ADM, Kemin Industries, Impextraco, Biomin, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Feed Mycotoxin Detoxifiers Market Evolving Landscape
Biological detoxification technologies are compressing the historical dominance of clay-based binders through enzymatic inactivation pathways validated under field conditions.
Enzymatic trichothecene degradation systems utilizing epoxidase and esterase pathways are supplanting adsorbent-only approaches in swine and poultry rations. Midwest integrators running antibiotic-free operations specify these biological agents at inclusion rates below traditional clay binders. The shift is compressing volume share for unmodified aluminosilicate products while expanding margin pools for fermentation-derived technologies.
FDA's Center for Veterinary Medicine is advancing mandatory certificate-of-analysis requirements for mycotoxin binders entering dairy feed channels. This regulatory trajectory is elevating analytical validation costs for supplier qualification. Compounders serving fluid milk markets are responding by consolidating vendor bases toward integrated grain-handling networks with captive laboratory infrastructure.
Specification-driven procurement is displacing spot-market purchasing for mycotoxin detoxifiers among large integrators. Buyers now embed binding capacity guarantees and lot-traceability requirements into multi-year supply agreements. This behavioral shift concentrates contract volume with suppliers possessing validated manufacturing scale and third-party certification, compressing opportunities for regional formulators lacking accreditation depth.
North America Feed Mycotoxin Detoxifiers Market Segmentation
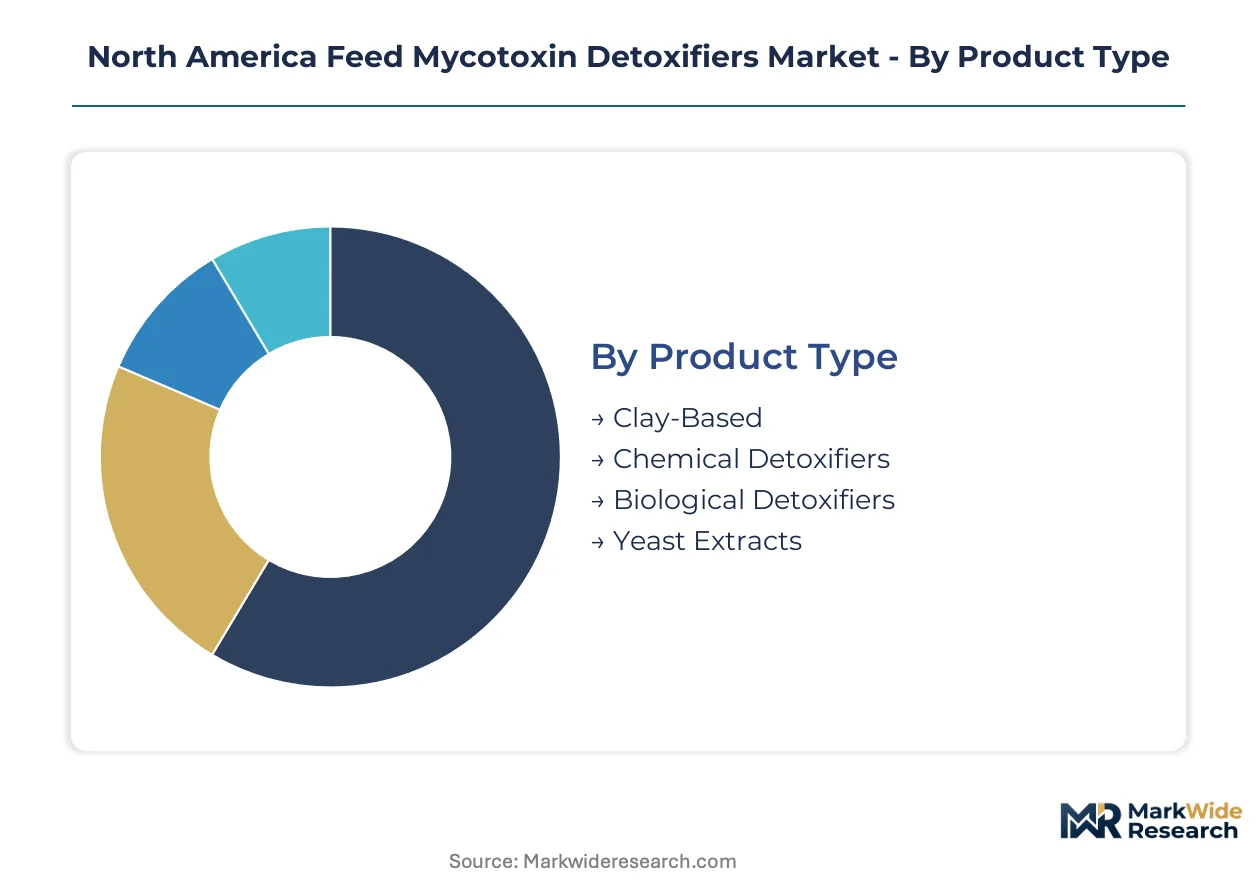
Product differentiation across detoxifier technologies determines procurement patterns among compounders facing divergent regulatory pressures and species-specific efficacy requirements. Segment boundaries blur as suppliers bundle analytical services with core products to defend margin pools.
Product Type:
Biological detoxifiers face the most intense substitution pressure as enzymatic technologies displace legacy clay binders in premium ration formulations.
- Clay-Based:Modified aluminosilicate formulations dominate ruminant applications due to established inclusion economics and proven aflatoxin sequestration at pH 6.5-7.0. Midwest integrators specify Wyoming-mined bentonite for cost-sensitive beef finishing operations where binding capacity validation remains secondary to tonnage pricing.
- Biological Detoxifiers:Epoxidase and esterase enzyme systems degrade trichothecenes rather than adsorbing them, commanding specification premiums from antibiotic-free poultry integrators. USDA-supported field trials in Iowa and North Carolina are accelerating adoption as FDA certificate-of-analysis requirements elevate analytical validation standards.
- Chemical Detoxifiers:Oxidative agents including ammoniation and ozonation modify mycotoxin structures in stored grain, though residual compound concerns limit penetration in dairy channels.
- Yeast Extracts:Saccharomyces cerevisiae cell wall derivatives concentrate in layer-hen and breeder operations where beta-glucan binders support immune modulation alongside toxin binding.
Clay-based products anchor the volume base while biological detoxifiers gain share at the steepest rate.
End User:
Species-specific metabolism drives divergence in detoxifier efficacy requirements and regulatory scrutiny intensity across customer segments.
- Livestock:Dairy cattle operations concentrate demand for validated binders meeting FDA action levels for aflatoxin M1 in fluid milk. Wisconsin and California compounders embed certificate-of-analysis documentation into procurement workflows to satisfy interstate shipment mandates.
- Poultry:Antibiotic-free broiler and layer integrators specify yeast-derived binders at premium inclusion rates, with beta-glucan products commanding specification premiums from retailers sourcing cage-free egg programs.
- Aquaculture:Salmon and trout producers in British Columbia and Maine apply specialized clay formulations to mitigate DON accumulation in grain-based feeds, though species-specific toxicity thresholds remain less standardized than terrestrial livestock.
- Pet Food:Premium companion animal brands drive demand for low-inclusion yeast extracts as humanization trends elevate ingredient transparency requirements.
Poultry applications generate the steepest margin expansion while livestock maintains absolute volume dominance.
Application:
Prevention-oriented deployment is displacing reactive treatment as climate volatility elevates mycotoxin risk forecasting into core procurement functions.
- Prevention:Pre-harvest fungal control and post-harvest grain conditioning reduce downstream binder dependency, though climate-driven aflatoxin spikes in Texas and Georgia corn belts sustain parallel demand for adsorbent protection.
- Treatment:Curative applications spike during high-mycotoxin years, with Midwest elevators contracting detoxifier suppliers for emergency blending services when inbound corn exceeds FDA action levels.
- Feed Preservatives:Mold inhibitors including organic acids and propionates suppress fungal growth during storage, complementing rather than replacing toxin-specific binders in complete feeds.
- Nutritional Supplements:Standalone mycotoxin binder premixes allow integrators to adjust inclusion rates seasonally, particularly in swine operations facing variable fumonisin loads from regional corn sourcing.
Prevention commands the largest absolute spend while treatment applications exhibit the highest volatility coefficient.
Distribution Channel:
Channel selection reflects compounder scale and analytical capability requirements rather than pure cost optimization.
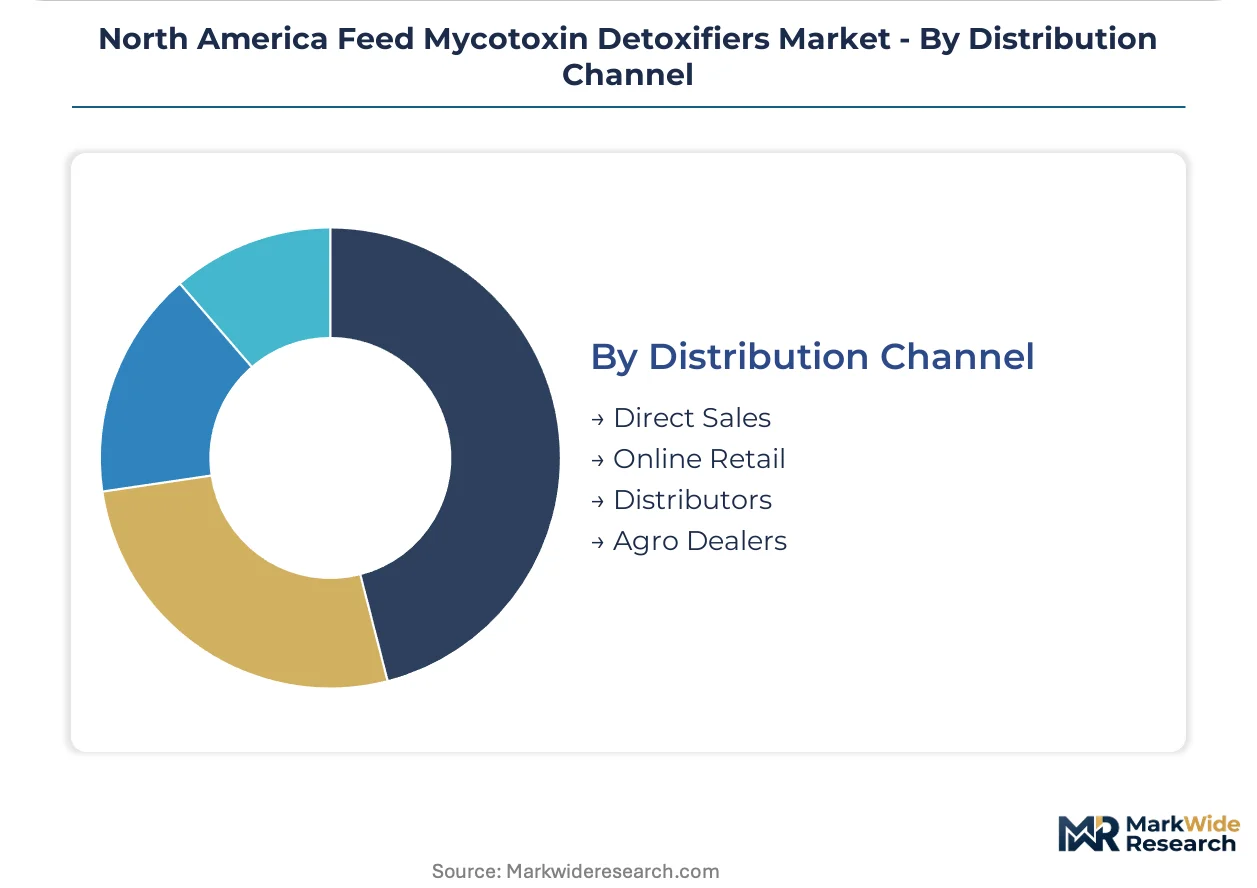
- Direct Sales:Integrated grain-handling networks including Cargill's captive distribution embed pre-screening and detoxifier blending as bundled services, consolidating volume with suppliers possessing validated manufacturing scale.
- Distributors:Regional feed ingredient distributors serve mid-size compounders lacking laboratory infrastructure, though FDA certificate-of-analysis requirements are compressing vendor bases toward accredited suppliers.
- Agro Dealers:Farm supply cooperatives in the U.S. Midwest and Canadian Prairies deliver clay-based binders to smaller livestock operations, with seasonal demand peaking during harvest moisture stress years.
- Online Retail:E-commerce penetration remains limited to specialty yeast extracts for niche pet food and hobby farm segments, constrained by bulk logistics and regulatory documentation requirements.
Direct sales capture the steepest share gains while distributors retain the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wyoming and Georgia mining operations anchor aluminosilicate clay supply for North American formulators, while FDA and CFIA protocols drive cross-border demand for certified detoxifier products. Climate volatility across the U.S. grain belt concentrates procurement risk in Midwest integrators managing simultaneous export and domestic compliance obligations.
United States
Iowa and North Carolina poultry integrators specify enzymatic detoxifiers following USDA-supported field trials validating trichothecene inactivation. FDA's Center for Veterinary Medicine enforces mycotoxin action levels for interstate dairy feed shipments, compelling Wisconsin and California compounders to embed certificate-of-analysis documentation into procurement workflows. The Midwest grain belt from Illinois through Nebraska faces acute aflatoxin pressure during harvest moisture stress years, driving emergency blending service contracts with regional elevators.
Canada
CFIA's Safe Feed for Animals Regulations mandate hazard analysis for mills importing U.S. grain, creating demand for pre-certified detoxifier products across Ontario and Quebec feed compounders. British Columbia salmon and trout producers apply specialized clay formulations to mitigate DON accumulation in grain-based aquaculture feeds. Prairie Provinces livestock operations concentrate procurement of cost-sensitive bentonite products for beef finishing rations where binding capacity validation remains secondary to tonnage economics.
Mexico
SENASICA oversight of imported feed ingredients drives specification requirements for Uflatoxin-tested corn shipments from U.S. Gulf ports into Veracruz and Tamaulipas poultry operations. Central Mexico dairy clusters around Querétaro and Jalisco face tightening residue monitoring for aflatoxin M1 in fluid milk destined for domestic retail and U.S. export channels. Northern border states concentrate demand for dual-certified detoxifiers satisfying both FDA dairy protocols and Mexican agricultural sanitation mandates.
North America Feed Mycotoxin Detoxifiers Market Competitive Landscape
Concentration sits with integrated grain-handling networks and specialized fermentation technology developers rather than fragmented regional formulators. Three structural tiers define competitive positioning: captive laboratory infrastructure operators, validated manufacturing scale players, and mid-size distributors lacking accreditation depth. Consolidation pressure intensifies as FDA certificate-of-analysis requirements compress vendor bases toward suppliers with third-party certification. Strategic moves center on backward integration into pre-screening services and upstream control over aluminosilicate mining operations.
Within the integrated supply chain tier, Cargill anchors positioning through captive grain-handling networks embedding mycotoxin detection before blending. Alltech occupies a position among fermentation-derived technology specialists leveraging R&D intensity in yeast-cell-wall extraction protocols. BASF exemplifies the manufacturing scale archetype for modified aluminosilicate clay production serving species-specific formulation requirements.
| Leading Market Players |
|---|
| Cargill |
| Alltech |
| Adisseo |
| DSM Nutritional Products |
| BASF |
| ADM |
| Kemin Industries |
| Impextraco |
| Biomin |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Wyoming bentonite miners and Midwest feed compounders lock in supply access while capping price volatility for clay-based detoxifiers. These arrangements concentrate procurement power among integrators with volume guarantees, squeezing regional formulators into spot-market exposure during aflatoxin spike years.
Pricing Analysis
FDA certificate-of-analysis requirements dictate the pricing tier structure across North American feed mycotoxin detoxifiers. Three-tier pricing structure across pharmaceutical-grade certified, validated-standard, and unaccredited-economy levels separates dairy-channel suppliers from poultry integrators and cost-sensitive ruminant operations. Cost compression in the economy tier is intensifying because Wyoming mining consolidation limits alternative aluminosilicate sourcing. Dairy compounders in Wisconsin and California exhibit the lowest price sensitivity due to regulatory non-compliance exposure, while Prairie Provinces beef finishers prioritize tonnage economics over binding capacity validation.
Supply Chain Analysis
Inventory cycles for modified aluminosilicate clays extend through six-month harvest-to-blending windows, creating working capital intensity for formulators managing climate-driven demand spikes. Wyoming bentonite deposits and Georgia kaolin operations anchor North American supply, with fermentation-derived biological detoxifiers drawing from Midwest yeast production hubs. Single-source vulnerability concentrates in Wyoming mining operations exposed to regional weather disruption. Distribution runs through integrated grain-handling networks embedding pre-screening services, consolidating volume away from independent distributors lacking captive laboratory infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated grain-handling networks and large poultry integrators, compressing vendor bases toward suppliers with validated manufacturing scale and third-party certification depth.
For Market Incumbents: Shield margin pools in yeast-derived biological detoxifiers through backward integration into Saccharomyces cerevisiae cell wall supply and captive fermentation capacity expansion. Enzymatic trichothecene inactivation technologies from emerging fermentation specialists threaten clay-based volume share; FDA certificate-of-analysis requirements elevate analytical validation as the priority defensive lever. For New Entrants and Emerging Players: Differentiate on species-specific efficacy validation for cage-free layer-hen operations, where modified aluminosilicate clays remain underpenetrated relative to antibiotic-free poultry channels. The most penetrable white space sits in British Columbia and Maine aquaculture, where DON toxicity thresholds lack standardization. A go-to-market angle bundling analytical pre-screening with detoxifier supply bypasses distributor gatekeepers. For Investors and Strategic Acquirers: Capital is best deployed toward fermentation technology developers with USDA-validated field trial portfolios and dual FDA-EPA registration progress. Long-term viability hinges on biological detoxifier adoption curves displacing clay-based volume over the coming decade. The signal to watch is FDA advancement of mandatory certificate-of-analysis requirements, which would accelerate vendor base consolidation and reward accredited manufacturing scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yeast Fermentation | Captive Saccharomyces cerevisiae supply secures beta-glucan binder margins against nutraceutical competition. |
| USDA Field Trial Validation Program | Species-specific efficacy documentation accelerates biological detoxifier adoption among Iowa poultry integrators. |
| Dual FDA-EPA Registration Investment | Parallel compliance pathways for enzymatic products compress commercialization timelines by 12-18 months. |
| Pre-Screening Service Bundling | Grain-handling networks embedding mycotoxin detection create sticky supplier relationships with Midwest elevators. |
| Cage-Free Layer-Hen Segment Specialization | Modified aluminosilicate formulations optimized for pH 6.5-7.0 binding access underpenetrated egg production systems. |
Research Methodology
A standing panel of feed compounder procurement directors, FDA regulatory affairs specialists, yeast fermentation R&D leads, and Midwest grain elevator operators provided ongoing calibration across the research cycle. Primary interviews with these stakeholders combined with secondary validation from FDA Center for Veterinary Medicine guidance documents, CFIA Safe Feed for Animals Regulations, USDA Agricultural Research Service field trial databases, and SEC filings from integrated grain-handling networks. Bottom-up volume modeling across product type, end user, application, and distribution channel segments triangulated against top-down industry spend estimates.
Consistency checks against external benchmarks validated analytical framework outputs across the projection horizon. Segmentation dimensions modeled include detoxifier technology type, livestock species category, deployment mode (prevention versus treatment), and channel structure. CAGRs derived from fitted growth curves incorporated climate volatility indices for U.S. corn belt aflatoxin risk, FDA regulatory trajectory assumptions, and biological detoxifier adoption rate sensitivity.
Material uncertainties — regulatory timing for mandatory certificate-of-analysis requirements, climate-driven harvest moisture stress frequency, and yeast extract supply competition from human nutraceutical markets — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision as these factors evolve. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Asia-Pacific Agricultural Microbial Market
Agricultural Biologicals
Microbial Agricultural Inoculants Market
Agricultural Biologicals
Feed Mycotoxin Binders Market
Agricultural Biologicals
Silybum Marianum Market
Agricultural Biologicals
North America Amino Acids Market
Agricultural Biologicals
South America Beta-Glucan Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
Agricultural Activator Adjuvants Market
Agricultural Biologicals
Chitosan for Agriculture Market
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
Global Agricultural Enzymes Market
Agricultural Biologicals
Global Agricultural Inoculant Market
Agricultural Biologicals
South America Agricultural Microbials Market
Agricultural Biologicals
North America Agricultural Microbials Market
Agricultural Biologicals
Africa Feed Enzymes Market
Agricultural Biologicals
Humic-Based Biostimulants Market