
 Middle East and Africa Bio-Stimulants Market | 2026-2036
Middle East and Africa Bio-Stimulants Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Bio-Stimulants Market Foresight
Premium seaweed-derived formulations and commodity humic acid blends is decoupling across the Middle East and Africa as irrigation water quality deteriorates and export buyers tighten residue protocols. Haifa Group leverages its integrated Dead Sea mineral extraction infrastructure to supply consistent potassium-humate feedstock for regional blenders. Koppert Biological Systems specializes in microbial consortia tailored to desert soil microbiome rehabilitation, particularly in UAE greenhouse operations. Valagro SpA anchors the premium tier through proprietary extraction technologies that concentrate bioactive gibberellins and cytokinins from Ascophyllum nodosum.
Bio-stimulants comprise organic or microbially-derived substances and inoculants applied to plants, seeds, or rhizospheres to enhance nutrient uptake efficiency, abiotic stress tolerance, or metabolic pathways without direct fertilization, typically formulated with guaranteed minimums of humic substances exceeding 12% carbon content or viable colony counts above 10^8 CFU per gram for microbial products. Their primary commercial purpose centers on yield stabilization in high-value export crops where synthetic agrochemical restrictions limit conventional protection options. Seaweed extracts command margin concentration due to extraction complexity and limited regional kelp sourcing, while microbial inoculants represent the fastest-expanding category as controlled-environment agriculture spreads across Gulf states. Liquid formulations dominate volume through fertigation compatibility, though granular products sustain stronger pricing in rain-fed Moroccan cereal zones where equipment limitations preclude precision application.
South Africa's Department of Agriculture, Land Reform and Rural Development enforces fertilizer registration under Fertilizers, Farm Feeds, Seeds and Remedies Act standards that classify bio-stimulants separately from fertilizers, creating distinct compliance pathways for microbial versus extract-based products. The EU Green Deal and REACH-aligned residue protocols shape demand as Moroccan and Egyptian exporters must certify bio-stimulant inputs against maximum residue thresholds for European supermarket chains. Stakeholders must monitor how Saudi Arabia's SFDA and national food security initiatives integrate bio-stimulants into subsidized input packages for wheat self-sufficiency programs, as this regulatory alignment will determine whether microbial inoculant demand concentrates in government-procured channels or remains fragmented across private distributor networks.
Market Dynamics
The EU Green Deal's residue standards are compressing input choice sets for Moroccan and Egyptian exporters, forcing rapid substitution of synthetic agrochemicals with certified bio-stimulant formulations across citrus and tomato supply chains.
Growth Catalysts
- Salinity-induced yield loss:Row crop producers across South Africa and Egypt are expanding bio-stimulant application to combat soil degradation and stabilize productivity in water-stressed regions.
- EU Green Deal compliance:Export-oriented agribusinesses in Morocco face tightening maximum residue thresholds, accelerating demand for residue-compliant biological inputs.
- Controlled-environment agriculture:UAE greenhouse operators are deploying microbial consortia for desert soil microbiome rehabilitation, creating concentrated demand nodes in Gulf states.
Market Restraints
- Kelp sourcing concentration:Seaweed extract production depends on limited regional Ascophyllum nodosum supply, constraining margin expansion for premium formulations.
- Registration pathway fragmentation:South Africa's Fertilizers, Farm Feeds, Seeds and Remedies Act creates distinct compliance burdens for microbial versus extract-based products, lengthening market entry timelines.
- Irrigation water quality deterioration:Rising salinity and alkalinity in Nile Delta and Western Cape irrigation systems degrade bio-stimulant efficacy, forcing higher application rates.
Strategic Opportunities
- Saudi wheat self-sufficiency programs:SFDA integration of bio-stimulants into subsidized input packages could concentrate microbial inoculant demand through government procurement channels.
- Agadir-Larache greenhouse corridor:Morocco's citrus and tomato production zones present concentrated adoption potential for premium seaweed-derived formulations serving export markets.
- Fertigation compatibility innovation:Liquid formulation optimization for drip irrigation systems addresses equipment limitations in rain-fed Moroccan cereal zones where granular products currently dominate.
Industry Challenges
- Microbial viability maintenance:Desert heat exposure during transport and storage degrades colony counts in microbial products, requiring cold chain investments that strain distributor margins.
- Extraction technology gaps:Regional blenders lack proprietary concentration capabilities for bioactive gibberellins and cytokinins, forcing dependence on imported premium feedstock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Bio-Stimulants Market |
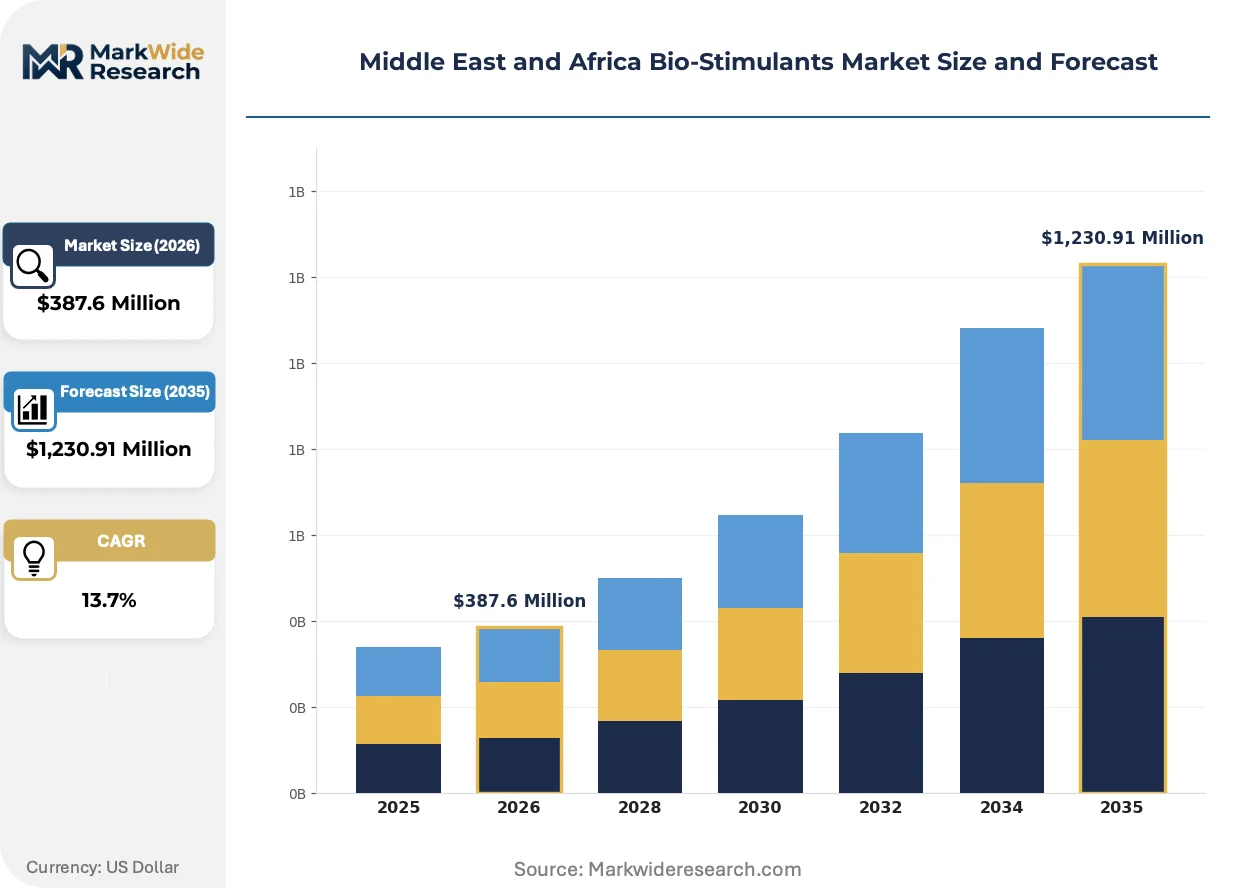
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,230.91 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Humic Acids, Fulvic Acids, Microbial Inoculants, Seaweed Extracts Application: Agricultural Crops, Horticultural Crops, Turf and Ornamental Plants, Greenhouse Crops Form: Granular, Liquid, Powder, Pelleted Distribution Channel: Direct Sales, Online Sales, Retail Stores, Distributors |
| Companies Covered | Haifa Group, Fertiplus, Trade Corporation International, Koppert Biological Systems, Syngenta, Valagro SpA, Biolchim SPA, Biostadt India Limited, Agrinos, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Bio-Stimulants Market Shifts & Advancements
Formulation science and regulatory alignment are reshaping competitive positioning across Middle East and Africa bio-stimulant markets, with extraction complexity and residue certification emerging as primary differentiation vectors.
Precision fermentation-derived microbial inoculants is converging with traditional compost tea production, enabling UAE greenhouse operators to achieve consistent colony counts above 10^8 CFU per gram at commercial scale. Large-scale protected agriculture investors in Dubai and Abu Dhabi are adopting these hybrid formulations within eighteen-month renovation cycles. This convergence is compressing price premiums for conventional microbial products while elevating technical service requirements for suppliers.
EU Green Deal residue protocols are forcing Moroccan and Egyptian exporters to certify bio-stimulant inputs against European supermarket chain standards, creating compliance documentation burdens that favor suppliers with integrated quality assurance systems. The regulation is segmenting the market between certified premium tiers and uncertified commodity blends. Citrus and tomato exporters near Agadir and the Nile Delta are consolidating supplier relationships to reduce audit complexity.
Buyer concentration among European supermarket procurement departments is shortening switching cycles for Moroccan and Egyptian agribusinesses, compressing traditional three-year input supplier contracts into annual certification-dependent renewals. This pattern is displacing long-term distributor relationships with transaction-based sourcing platforms. The shift is most visible in Morocco's greenhouse corridors, where export cooperatives now pool purchasing to negotiate volume-based residue certification guarantees.
Middle East and Africa Bio-Stimulants Market Segmentation
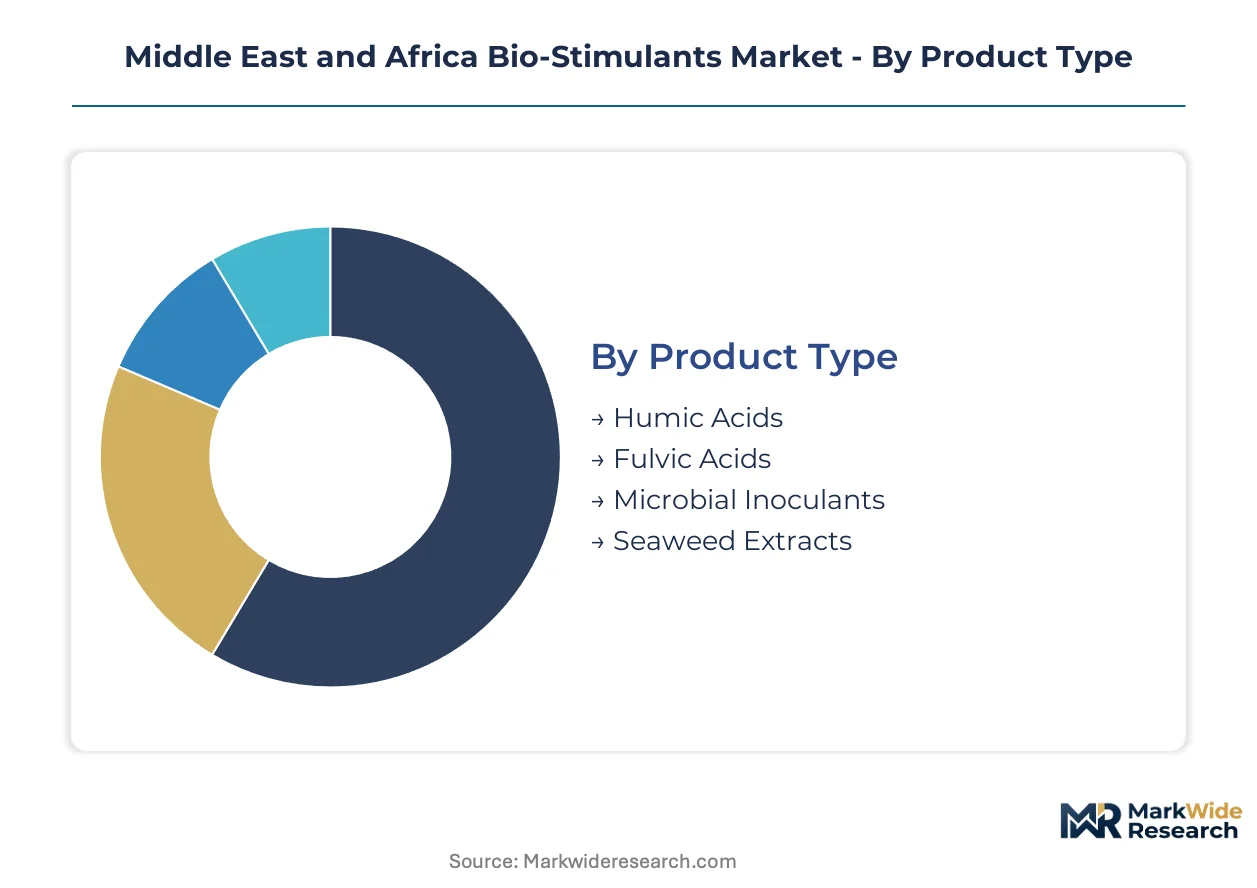
Segmentation in the Middle East and Africa bio-stimulants market reveals how certification burdens, irrigation infrastructure, and export compliance requirements reshape demand patterns across product categories. Understanding these divisions exposes where margin concentration aligns with regulatory complexity and where volume scales through commodity channels.
Product Type:
EU Green Deal residue protocols and South Africa's Fertilizers, Farm Feeds, Seeds and Remedies Act create divergent compliance pathways—microbial products face viability testing requirements while seaweed extracts confront extraction standard verification.
- Humic Acids:Potassium-humate formulations with carbon content exceeding 12% dominate commodity blending operations. Egyptian and South African row crop producers apply these through fertigation systems to combat salinity-induced yield degradation in Nile Delta and Western Cape irrigation districts.
- Microbial Inoculants:Formulations requiring viable colony counts above 10^8 CFU per gram demand cold chain maintenance through desert logistics corridors. UAE greenhouse operators near Dubai and Abu Dhabi deploy these consortia for desert soil microbiome rehabilitation in controlled-environment agriculture expansion.
- Fulvic Acids:Lower molecular weight fractions penetrate plant membranes faster than humic counterparts, finding application in foliar spray programs across Moroccan citrus orchards.
- Seaweed Extracts:Ascophyllum nodosum-derived concentrates command premium positioning through proprietary gibberellin and cytokinin extraction, serving export-oriented greenhouse corridors near Agadir and Larache.
Leading the category by volume: Humic Acids. Growing fastest: Microbial Inoculants.
Application:
Margin structure across applications tracks export certification intensity—European supermarket chain residue thresholds concentrate premium pricing in horticultural segments while domestic food security programs commoditize agricultural crop inputs.
- Horticultural Crops:Citrus and tomato production near Morocco's Agadir-Larache corridor drives concentrated demand for certified seaweed-derived formulations. EU Green Deal compliance requirements force rapid substitution of synthetic agrochemicals with residue-compliant biological inputs, shortening supplier contracts to annual certification-dependent renewals.
- Greenhouse Crops:Protected agriculture investors across UAE emirates integrate microbial inoculants within eighteen-month renovation cycles, achieving consistent colony counts through precision fermentation hybridization with traditional compost tea methods.
- Agricultural Crops:Wheat self-sufficiency programs in Saudi Arabia channel subsidized input procurement through SFDA-aligned distribution networks, concentrating microbial inoculant demand in government channels.
- Turf and Ornamental Plants:Golf course and landscaping maintenance in Gulf state urban centers sustains steady demand for foliar-applied liquid formulations with immediate visual response characteristics.
Horticultural Crops generate the highest margin per hectare applied. Greenhouse Crops are expanding most quickly through Gulf state capital deployment.
Form:
Equipment penetration and water quality conditions determine formulation preference—drip irrigation compatibility favors liquids while rain-fed cereal zones sustain granular pricing power through application infrastructure constraints.
- Liquid:Fertigation-compatible formulations dominate volume through compatibility with precision irrigation infrastructure. Moroccan tomato greenhouse operators and UAE hydroponic facilities standardize on liquid delivery for nutrient integration efficiency.
- Granular:Rain-fed Moroccan cereal zones in the Saïss and Tadla plains maintain stronger pricing for granular products where equipment limitations preclude precision application systems.
- Powder:Concentrated dry formulations reduce transport costs across long distribution corridors into Egyptian Western Desert and Sudanese irrigation schemes.
- Pelleted:Slow-release matrix formulations target high-value permanent crops including date palm plantations in Saudi Arabia's Al-Qassim region.
Liquid formulations capture the largest volume share. Granular products retain the strongest unit pricing in infrastructure-constrained segments.
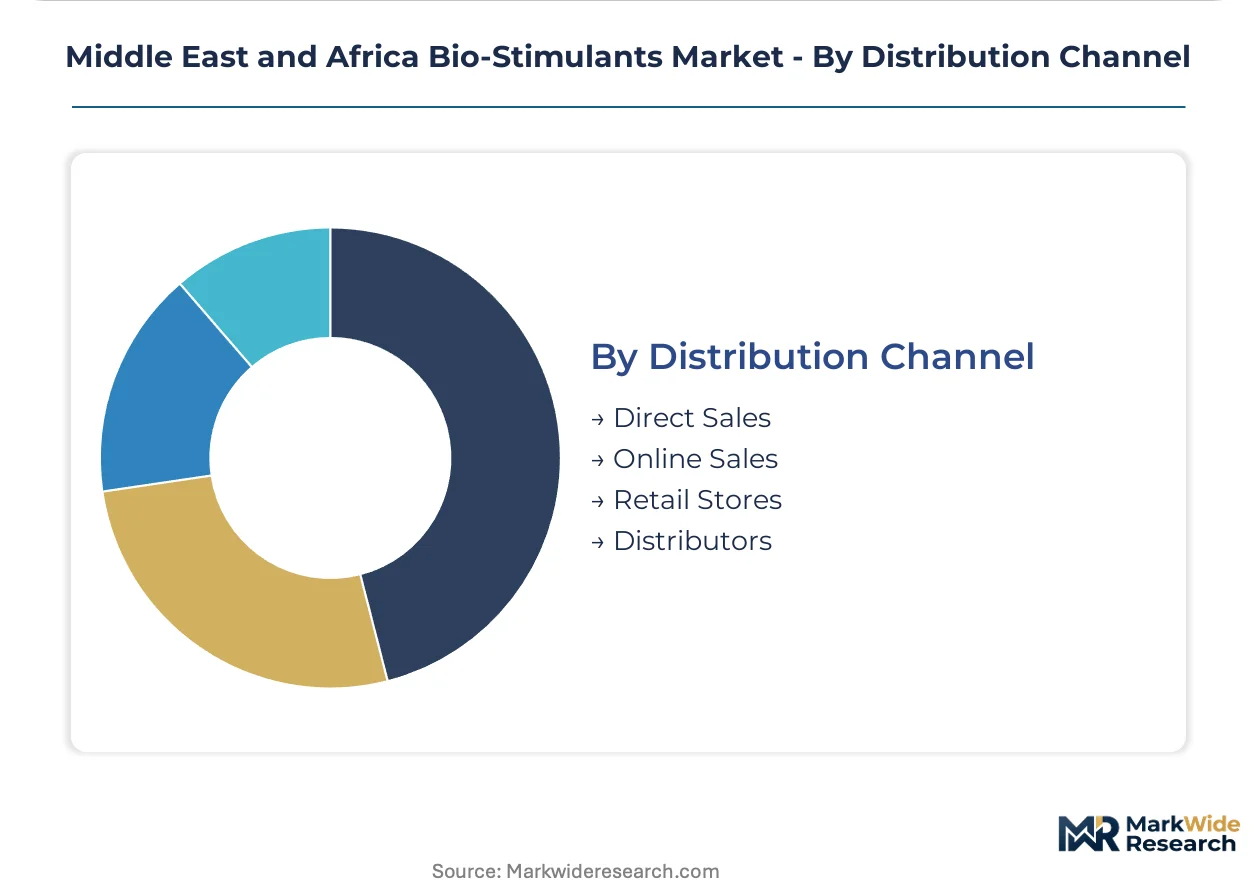
Distribution Channel:
Buyer consolidation among export cooperatives is shortening switching cycles and displacing traditional distributor relationships with transaction-based sourcing platforms that pool purchasing for volume-based residue certification guarantees.
- Distributors:Regional blending networks across Morocco and Egypt aggregate commodity humic acid feedstock with technical service capabilities for residue documentation. These intermediaries face margin compression as export cooperatives consolidate purchasing power.
- Direct Sales:Premium seaweed extract suppliers including Valagro SpA bypass distribution tiers to secure annual certification-dependent contracts with Moroccan citrus export cooperatives, reducing audit complexity through integrated quality assurance systems.
- Retail Stores:Smallholder channels in South Africa's Western Cape and Egypt's Nile Delta sustain fragmented demand for packaged microbial products with basic storage condition labeling.
- Online Sales:Emerging procurement platforms serve urban greenhouse operators in Dubai and Riyadh with technical specification transparency and batch certification documentation.
Distributors currently move the largest product volumes. Direct Sales channels are gaining share fastest through certification bundling requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agadir anchors bio-stimulant demand concentration across the Middle East and Africa, with Morocco's citrus and tomato greenhouse corridors driving premium formulation procurement for EU export compliance.
Morocco
Citrus and tomato producers near Agadir and Larache deploy seaweed-derived formulations to meet EU Green Deal residue thresholds for European supermarket chains. The country's export cooperatives consolidate purchasing power through pooled procurement platforms. Annual certification-dependent supplier contracts now displace traditional three-year distributor relationships across the greenhouse corridor.
South Africa
Western Cape row crop producers expand humic acid application through fertigation systems to combat salinity-induced yield degradation in irrigation districts. The Department of Agriculture, Land Reform and Rural Development enforces Fertilizers, Farm Feeds, Seeds and Remedies Act registration standards that classify bio-stimulants separately from fertilizers. Cape Winelands and Grabouw fruit clusters sustain concentrated demand for microbial inoculants with cold chain distribution capabilities.
Egypt
Nile Delta agricultural operations face tightening irrigation water quality that degrades bio-stimulant efficacy and forces higher application rates. Export-oriented agribusinesses certify inputs against EU maximum residue thresholds for European market access. Kafr El Sheikh and Beheira governorates concentrate tomato and citrus production serving supermarket chain procurement departments.
UAE
Dubai and Abu Dhabi greenhouse operators integrate microbial consortia within eighteen-month renovation cycles for desert soil microbiome rehabilitation. MOHAP and municipal food security initiatives channel demand through controlled-environment agriculture expansion programs. Precision fermentation hybridization with traditional compost tea methods achieves consistent colony counts above regulatory thresholds.
Saudi Arabia
SFDA regulatory alignment with national food security initiatives determines whether microbial inoculant demand concentrates in government-procured channels or fragments across private networks. Wheat self-sufficiency programs in Al-Qassim and Eastern Province integrate subsidized bio-stimulant inputs for yield stabilization. Date palm plantations sustain demand for slow-release pelleted formulations in permanent crop zones.
Middle East and Africa Bio-Stimulants Market Competitive Landscape
Premium-margin players sit above commodity-margin players across extraction complexity and residue certification capabilities. The vendor base stratifies between integrated mineral extractors, proprietary technology specialists, and regional blending networks. Three archetypes dominate: Dead Sea mineral integrators supplying consistent potassium-humate feedstock; microbial consortia specialists targeting controlled-environment rehabilitation; and premium seaweed extractors with proprietary bioactive concentration. Competitive moves concentrate on backward integration into captive mineral supply and technology licensing for regional formulation standardization.
Among Israel-based integrated extractors, Haifa Group occupies a position exemplifying mineral feedstock security through Dead Sea infrastructure control. Within the microbial rehabilitation tier, Koppert Biological Systems and Netherlands-based specialists represent archetypes of desert soil microbiome targeting. On the premium extraction vector, Valagro SpA anchors positioning through proprietary Ascophyllum nodosum processing capabilities. These three entities collectively illustrate how supply security, technical specialization, and extraction complexity define tier boundaries.
| Leading Market Players |
|---|
| Haifa Group |
| Fertiplus |
| Trade Corporation International |
| Koppert Biological Systems |
| Syngenta |
| Valagro SpA |
| Biolchim SPA |
| Biostadt India Limited |
| Agrinos |
| Others |
Supply & Pricing Matrix
Export cooperatives in Morocco's Agadir-Larache corridor command substantial pricing leverage through pooled procurement platforms that certify inputs against EU Green Deal residue thresholds. This buyer concentration forces suppliers to absorb cold chain logistics costs while maintaining premium positioning for seaweed-derived formulations.
Pricing Analysis
Yield-stabilization outcomes anchor value-based pricing for premium bio-stimulant tiers serving European supermarket supply chains. Three-tier pricing structure across premium, standard, and economy levels separates Ascophyllum nodosum extracts with proprietary gibberellin concentration from commodity potassium-humate blends and basic microbial inoculants. Cost compression in the standard tier is intensifying because regional blenders lack extraction technology capabilities and must import concentrated feedstock. Government procurement channels in Saudi Arabia exhibit lowest price sensitivity, while South African smallholders through retail stores demonstrate highest elasticity.
Supply Chain Analysis
Product returns and viability failures in microbial consortia drive reverse-logistics investments across desert distribution corridors, with degraded colony counts triggering replacement shipments and margin erosion. Supply concentrates in Israel for Dead Sea mineral extraction, Norway for Ascophyllum nodosum harvesting, and the Netherlands for microbial strain development. Formulation inputs draw from potassium-humate feedstock, precision-fermentation derived inoculants, and kelp biomass. Single-source vulnerability in regional kelp sourcing constrains premium formulation expansion. Distribution runs through Moroccan and Egyptian blending networks that aggregate feedstock with technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Limited regional Ascophyllum nodosum supply creates a structural capacity bottleneck that props pricing for premium seaweed extract tiers. This constraint favors incumbents with captive sourcing agreements.
For Market Incumbents: Deploy backward integration into Dead Sea mineral extraction or Norwegian kelp harvesting to secure feedstock continuity against emerging regional blenders. Invest in integrated quality assurance systems that reduce audit complexity for EU Green Deal certification. Channel control through direct sales relationships with Moroccan export cooperatives defends margin position against transaction-based sourcing platforms.
For New Entrants and Emerging Players: Distributor partnerships in South Africa's Western Cape offer the most penetrable entry point given fragmented retail channels and limited technical service coverage. Target rain-fed Moroccan cereal zones in the Saïss and Tadla plains where granular product demand exceeds precision application infrastructure. A fertigation compatibility specialization addresses equipment gaps while avoiding direct competition with liquid formulation incumbents.
For Investors and Strategic Acquirers: The window for entry favors proprietary extraction technology specialists with demonstrated EU residue certification capabilities. Long-term viability hinges on regulatory alignment with Saudi SFDA integration into subsidized input packages. Monitor SFDA procurement channel decisions as the inflection signal determining whether microbial inoculant demand concentrates through government networks or fragments across private distribution.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kelp Sourcing | Captive Ascophyllum nodosum supply secures premium tier margin concentration against import-dependent competitors. |
| EU Green Deal Certification Investment | Integrated quality assurance systems reduce audit complexity for Moroccan citrus export cooperatives. |
| Cold Chain Distribution Partnership | Desert logistics capabilities maintain microbial viability above 10^8 CFU thresholds for UAE greenhouse operators. |
| Precision Fermentation Scale-Up | Hybrid compost tea methods achieve consistent colony counts for controlled-environment agriculture expansion. |
| Direct Sales Channel Expansion | Bypassing distributor tiers captures annual certification-dependent contracts with consolidated export cooperatives. |
Research Methodology
Trade databases, EU regulatory filings, and agricultural input customs records formed the secondary backbone, cross-referenced with primary interviews involving crop protection executives at regional blending operations, procurement leads at Moroccan export cooperatives, SFDA regulatory affairs specialists, and UAE greenhouse operations managers. Bottom-up volume estimates from product registration databases combined with top-down value assessments through distributor revenue proxies to establish market sizing. Triangulation across these sources validated segmentation splits by product type, application, and formulation.
Historical trendline analysis examined adoption patterns across irrigation infrastructure development cycles and export compliance requirement shifts. The modeling framework segmented by humic acid, microbial inoculant, fulvic acid, and seaweed extract categories; further disaggregated by horticultural crops, greenhouse crops, agricultural crops, and turf applications; and incorporated form factors including liquid, granular, powder, and pelleted variants. CAGRs were derived from regression analysis against salinity degradation indices and controlled-environment agriculture capital deployment trajectories.
Caveats apply where SFDA procurement policy revisions, EU residue threshold adjustments, or regional kelp harvest disruptions could materially shift the outlook. Practitioners should monitor Saudi government input subsidy announcements and Norwegian biomass harvest yields for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Monolaurin for Feed Market
Agricultural Biologicals
Africa Feed Enzymes Market
Agricultural Biologicals
Europe Silage Inoculant Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
Edible Fungus Market
Agricultural Biologicals
Microbial Agricultural Inoculants Market
Agricultural Biologicals
Acetoin Natural Market
Agricultural Biologicals
United States Animal Feed Additives Market
Agricultural Biologicals
Global Agri Natural Enemy Pest Control Market
Agricultural Biologicals
Baobab Market
Agricultural Biologicals
Silybum Marianum Market
Agricultural Biologicals
Global Silage Inoculants Market
Agricultural Biologicals
Feed Mycotoxin Binders Market
Agricultural Biologicals
Soil Inoculants Market
Agricultural Biologicals
Agricultural Biofungicides Market
Agricultural Biologicals
North America Amino Acids Market