
 South America Agricultural Microbials Market | 2026-2036
South America Agricultural Microbials Market Size, Share, and Industry Trends Forecast 2026-2036
South America Agricultural Microbials Market Analytics
Project finance for biological input manufacturing facilities is rewriting competitive entry dynamics in the South America agricultural microbials sector. BASF SE leverages its existing fermentation infrastructure to reduce capital barriers for regional biological production. Bayer AG anchors its position through integrated seed-treatment-microbe bundling that locks in grower loyalty across Brazilian soybean belts. Koppert specializes in beneficial insect and microbe combinations that differentiate its portfolio from pure chemistry competitors.
Agricultural microbials comprise living organisms including bacteria, fungi, viruses, and protozoa formulated into crop inputs that colonize plant rhizospheres, suppress pathogens, or fix atmospheric nitrogen through enzymatic conversion. These biological agents function at cellular scales with colony-forming unit counts typically exceeding 10^8 CFU per gram to ensure field efficacy under variable soil conditions. Bacterial formulations dominate current revenue flows due to established Bacillus-based manufacturing pipelines and broad-spectrum disease suppression applications. Soil Enhancement applications exhibit the fastest structural expansion as degraded pasture conversions in Brazil and Argentina drive biological amendment demand. Direct Sales channels capture premium margin pools by embedding technical agronomy services that justify price premiums over commodity distributor networks.
Brazil's national agricultural regulator and ANVISA shape product registration timelines and residue tolerance thresholds that determine which microbial strains achieve commercial scale across Mercosur trade corridors. Argentina's SENASA enforces import equivalency standards that filter which international biological formulations enter domestic distribution. Stakeholders must monitor how evolving biocontrol registration harmonization between Brazil and Argentina reshapes cross-border manufacturing location decisions and strain patent strategies.
Market Dynamics
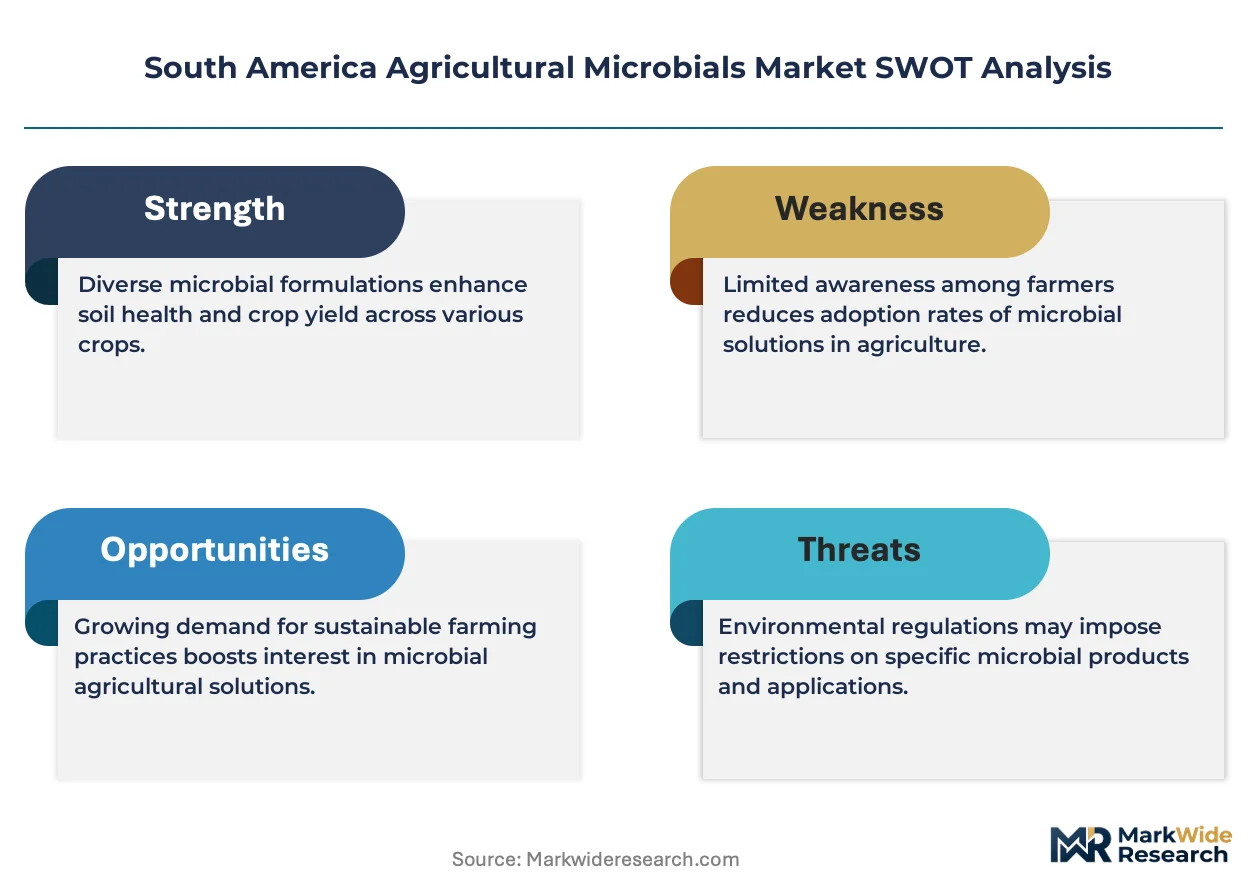
ANVISA's tightening pesticide residue thresholds are accelerating biological input substitution across Brazilian soybean belts, while Argentina's SENASA import equivalency standards filter which microbial strains achieve commercial scale in Mercosur corridors.
Growth Catalysts
- Cerrado Expansion Zones:Brazil's agricultural frontier is converting degraded pasture into high-intensity row-crop systems where biological nitrogen fixation reduces synthetic fertilizer dependency.
- ANVISA Registration Pathways:Accelerated biocontrol approval timelines for Bacillus-based formulations are compressing product commercialization cycles relative to conventional chemistry.
- Seed-Treatment Integration:Biological inoculant coating at processing facilities is embedding microbial inputs into standard planting protocols across Argentine wheat belts.
Market Restraints
- Fermentation Input Volatility:Molasses and soybean meal feedstock costs fluctuate with Brazilian sugar ethanol arbitrage and crushing margins, squeezing production economics.
- Strain Patent Concentration:Proprietary Bacillus thuringiensis and Trichoderma harzianum lineages concentrate in North American and European germplasm banks, limiting regional formulation autonomy.
- Shelf-Life Technical Ceiling:Viable colony-forming unit degradation during tropical storage and transport constrains distribution radius from manufacturing nodes.
Strategic Opportunities
- Uruguay Pasture Rehabilitation:Underpenetrated beef-forage systems present biological amendment demand as degraded grassland conversions accelerate under climate-smart livestock programs.
- Direct-to-Farm Digital Channels:Agronomy-as-a-service platforms are bypassing traditional distributor markups by embedding microbial prescriptions into precision agriculture subscriptions.
- Chilean Fruit Export Compliance:Maximum residue limits in EU and US destination markets are mandating biological disease suppression in table grape and blueberry production valleys.
Industry Challenges
- Microbial Formulation Expertise Gap:Qualified fermentation technologists and rhizosphere microbiologists remain scarce in regional talent pools, constraining scale-up capacity.
- Multi-Year Field Trial Requirements:SENASA and ANVISA efficacy validation protocols demand extensive agronomic data collection across diverse edaphic zones before registration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Agricultural Microbials Market |
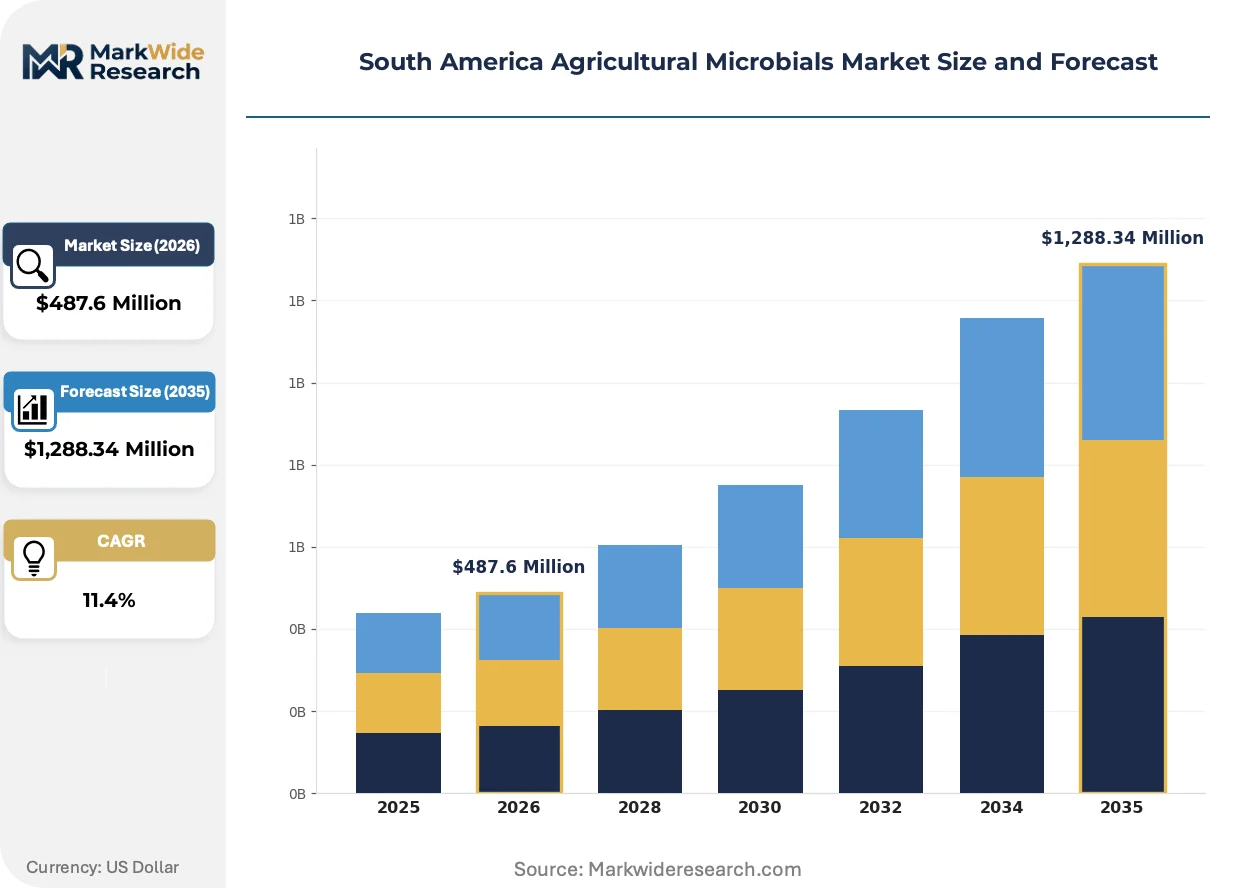
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacteria, Fungi, Virus, Protozoa Application: Crop Protection, Soil Enhancement, Plant Growth Promotion, Nutrient Management End Use Industry: Agronomy, Horticulture, Turf Management, Organic Farming Distribution Channel: Direct Sales, Retail, Distributors, Online Sales |
| Companies Covered | BASF SE, Bayer AG, UPL Ltd, Corteva Agriscience, Syngenta AG, FMC Corporation, Nufarm, Sumitomo Chemical Co., Ltd., Koppert, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Agricultural Microbials Market Evolving Landscape
Biological input manufacturing is converging with precision fermentation and digital agronomy, compressing development timelines while expanding addressable acreage beyond traditional high-value crop domains.
RNA-interference biocontrol formulations targeting specific pathogen genotypes are rendering obsolete broad-spectrum chemical fumigation in Brazilian potato and tomato protected cultivation. Grower cooperatives in Minas Gerais and São Paulo states are piloting these sequence-specific interventions ahead of regulatory codification. The technology is rendering obsolete calendar-based spraying schedules by enabling pathogen-presence-triggered application.
ANVISA's biocontrol registration harmonization negotiations with Argentina's SENASA are creating unified strain approval pathways across Mercosur trade corridors. Manufacturers are consolidating production location decisions around single facilities serving both markets. Brazilian Cerrado soybean operators and Argentine Pampas wheat producers are the primary beneficiaries of accelerated cross-border product availability.
Outcome-based biological performance contracts are displacing per-liter input pricing across large-scale farming operations in Mato Grosso and Goiás. Agronomy service providers guarantee yield deltas or pest suppression thresholds, aligning microbial supplier incentives with grower outcomes. This contractual evolution is most visible in 10,000-plus hectare operations where risk transfer complexity justifies premium service bundling.
South America Agricultural Microbials Market Segmentation
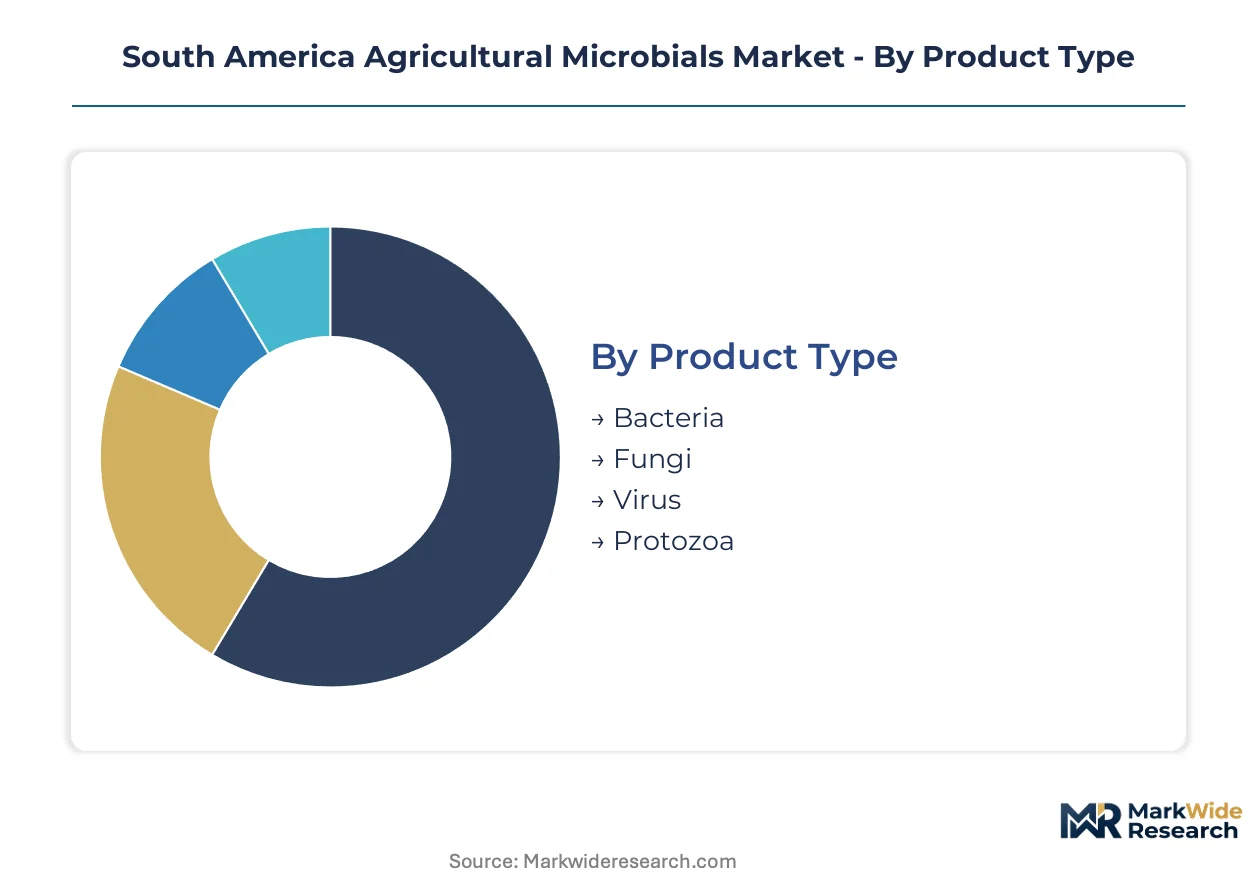
Agricultural microbials in South America fragment across organism type, application intensity, and channel economics. Each dimension carries distinct margin profiles and technical barriers that determine competitive positioning across Brazil's Cerrado, Argentina's Pampas, and Uruguay's pasture belt.
Product Type:
Bacterial and fungal formulations span commodity nitrogen fixation to precision biocontrol, with organism selection dictating manufacturing complexity and field persistence requirements.
- Bacteria:Bacillus-based formulations dominate commercial volumes through established fermentation infrastructure and broad-spectrum disease suppression. Demand concentrates in Brazil's Cerrado soybean belts where Bradyrhizobium inoculants reduce synthetic nitrogen dependency amid rising urea import costs.
- Fungi:Trichoderma and mycorrhizal strains colonize root systems to enhance phosphorus uptake and suppress soil-borne pathogens. Adoption accelerates in Argentina's wheat corridors where SENASA registration pathways for biocontrol fungi have compressed approval timelines relative to bacterial alternatives.
- Virus:Baculovirus and nucleopolyhedrovirus preparations target specific lepidopteran pests in high-value vegetable systems. Chilean table grape exporters deploy these agents to meet EU maximum residue limits.
- Protozoa:Predatory protozoa formulations suppress nematode populations in protected cultivation. Brazilian tomato producers in Minas Gerais integrate these agents into substrate-based systems.
Established volume favors Bacteria; emerging adoption favors Fungi.
Application:
Functional positioning ranges from reactive pest suppression to proactive soil conditioning, with application type determining reapplication frequency and service bundling potential.
- Crop Protection:Biocontrol agents suppress fungal, bacterial, and viral pathogens through competitive exclusion and antibiosis. Argentine soybean operators deploy Bacillus subtilis formulations against Asian soybean rust amid tightening fungicide resistance.
- Soil Enhancement:Microbial amendments restore biological activity in degraded pasture conversions across Brazil's agricultural frontier. This segment climbs the fastest as degraded Cerrado soils require biological priming before intensive row-crop establishment.
- Plant Growth Promotion:Phytohormone-producing bacteria and fungi stimulate root elongation and stress tolerance. Chilean blueberry producers apply these agents to extend harvest windows for export synchronization.
- Nutrient Management:Nitrogen-fixing and phosphate-solubilizing microbes reduce synthetic fertilizer rates. Uruguayan beef-forage systems adopt these inputs under climate-smart livestock program incentives.
Revenue concentration sits with Crop Protection; steepest expansion trajectory belongs to Soil Enhancement.
End Use Industry:
Customer sophistication varies from precision agronomy operations to commodity field cropping, with technical service requirements scaling accordingly.
- Agronomy:Large-scale row-crop operations demand microbial inputs integrated with precision planting and variable-rate application. Brazilian soybean cooperatives in Mato Grosso negotiate outcome-based performance contracts.
- Horticulture:Protected cultivation systems require pathogen-specific biocontrol with zero pre-harvest intervals. Chilean blueberry and table grape exporters prioritize residue compliance for EU and US destination markets.
- Turf Management:Sports field and golf course maintenance deploys fungal suppressants against dollar spot and brown patch. Brazilian São Paulo metropolitan area drives regional demand.
- Organic Farming:Certified operations rely exclusively on microbial inputs for pest and disease management. Argentina's expanding organic wheat and soybean hectares anchor adoption.
Input intensity peaks in Horticulture; acreage scale favors Agronomy.
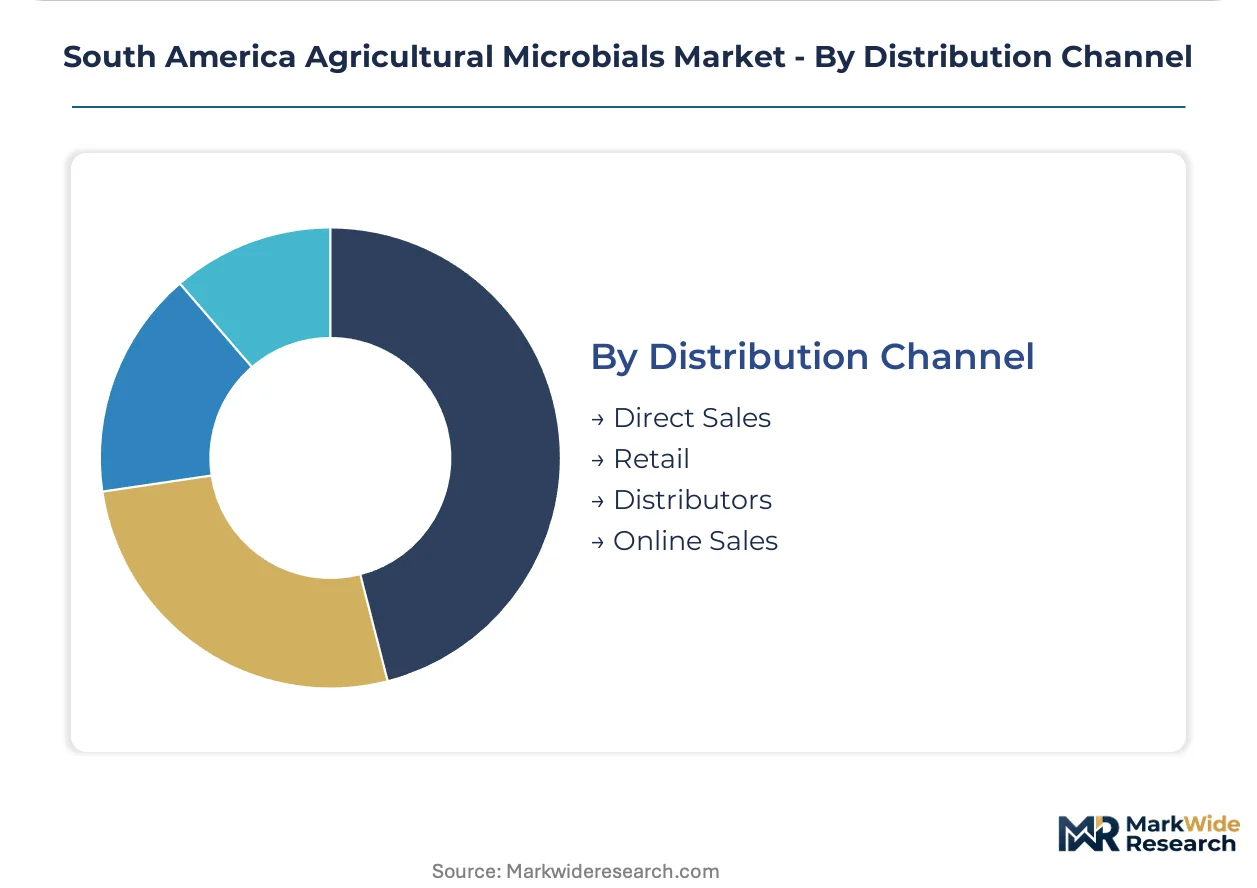
Distribution Channel:
Channel selection determines margin capture, technical service embedding, and geographic reach into fragmented farming operations.
- Direct Sales:Manufacturer agronomists embed microbial prescriptions into precision agriculture subscriptions. Large Mato Grosso and Goiás operations justify premium pricing through guaranteed yield deltas.
- Retail:Agricultural supply stores serve small and mid-scale producers with standardized formulations. Brazil's interior states rely on this channel for Bacillus-based inoculants.
- Distributors:Regional networks aggregate demand across dispersed farming communities. Argentine Pampas wheat belts access microbial inputs through established agrochemical distributor relationships.
- Online Sales:Digital platforms bypass traditional markups for tech-adopting producers. Brazilian grower cooperatives pilot direct-to-farm channels for specialized fungal amendments.
Margin retention favors Direct Sales; geographic penetration relies on Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's accelerated biocontrol registration pathways and Argentina's SENASA import equivalency reforms are reshaping cross-border microbial product availability across Mercosur corridors.
Brazil
Cerrado expansion zones drive Bradyrhizobium inoculant demand as degraded pasture conversions intensify. ANVISA compresses Bacillus-based formulation approval timelines relative to conventional chemistry. Mato Grosso soybean cooperatives negotiate outcome-based performance contracts with embedded microbial prescriptions.
Argentina
Pampas wheat belts adopt seed-treatment microbial coatings at processing facilities as standard planting protocol. SENASA enforces strain-specific import standards that filter which international formulations enter domestic distribution. Buenos Aires province anchors biocontrol fungi adoption amid compressed registration timelines.
Chile
Table grape and blueberry exporters deploy baculovirus preparations to meet EU and US maximum residue limits. The country's national agricultural regulator mandates biological disease suppression in export-oriented fruit valleys. Central Valley production clusters integrate pathogen-specific biocontrol into protected cultivation systems.
Uruguay
Climate-smart livestock programs incentivize biological amendments in degraded beef-forage systems. National agricultural extension services promote microbial nitrogen fixation to reduce synthetic fertilizer dependency. Northern pasture rehabilitation projects present underpenetrated demand for soil enhancement applications.
Paraguay
Soybean frontier expansion creates biological input demand amid tightening pesticide residue scrutiny. Mercosur trade alignment facilitates cross-border microbial product access from Brazilian manufacturing nodes. Eastern agricultural districts adopt bacterial inoculants through distributor networks serving mid-scale producers.
South America Agricultural Microbials Market Competitive Landscape
On the supply side, the industry is consolidating around integrated agrochemical conglomerates with captive fermentation infrastructure and specialized biological input pure-plays. Strategic archetypes include diversified chemistry-to-biology portfolios, seed-treatment-microbe bundling platforms, and beneficial organism combination specialists. Dominant competitive moves encompass backward integration into fermentation capacity and geographic expansion through registration harmonization across Mercosur corridors.
Within the diversified conglomerate tier, BASF SE and Bayer AG exemplify scale-driven positions anchored by existing manufacturing infrastructure and integrated distribution networks. Bayer AG occupies a distinctive position through seed-treatment bundling that embeds microbial inputs into standard planting protocols. Koppert sits within the specialized biological pure-play segment, representing the beneficial organism combination archetype that differentiates from chemistry-integrated competitors.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| UPL Ltd |
| Corteva Agriscience |
| Syngenta AG |
| FMC Corporation |
| Nufarm |
| Sumitomo Chemical Co., Ltd. |
| Koppert |
| Others |
Value Network & Pricing Analysis
São Paulo state's fermentation corridor anchors South American microbial production capacity, with molasses-fed Bacillus fermentation lines determining baseline input economics for downstream biological inoculant pricing across Brazilian Cerrado and Argentine Pampas markets. Capacity utilization at these nodes directly shapes margin capture for manufacturers serving ANVISA-registered product tiers versus commodity distributor channels.
Pricing Analysis
Certification level creates the primary spread between ANVISA-registered biocontrol formulations and unregistered commodity inoculants, with registered products commanding substantial premia through guaranteed efficacy validation and residue compliance documentation. Pricing stratifies across premium, standard, and economy tiers based on CFU concentration guarantees and shelf-life stability metrics. Cost compression in the economy tier is intensifying because Brazilian sugar ethanol arbitrage squeezes molasses feedstock availability. Small-scale producers in Paraguay's eastern districts exhibit highest price sensitivity, while Mato Grosso soybean cooperatives negotiating outcome-based contracts show lowest sensitivity due to yield guarantee structures.
Supply Chain Analysis
Molasses, soybean meal, and specialized nitrogen sources constitute the upstream feedstock base, with Brazilian sugarcane mills and Argentine crushing facilities serving as primary supply nodes. Manufacturing concentrates in Brazil, Argentina, and select Chilean biotechnology clusters. Single-source vulnerability runs through Brazilian molasses supply, which hinges on sugar ethanol market arbitrage decisions. Distribution runs through three parallel channels: direct manufacturer agronomist teams for large operations, regional distributor networks for mid-scale producers, and agricultural retail for standardized inoculants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biological input markets increasingly reward service-attach models where agronomy-as-a-service subscriptions expand faster than standalone microbial product sales, embedding technical prescription into recurring revenue relationships.
For Market Incumbents: Pre-empt proprietary strain obsolescence by accelerating backward integration into captive fermentation capacity in São Paulo and Paraná states. Patent concentration around North American Bacillus thuringiensis germplasm threatens formulation autonomy; secure regional strain development partnerships with Brazilian agricultural research institutes. Channel control through seed-treatment bundling at processing facilities locks in grower loyalty before generic competitors achieve ANVISA registration parity.
For New Entrants and Emerging Players: Establish a beachhead in Uruguay's underpenetrated beef-forage rehabilitation segment, where climate-smart livestock incentives create biological amendment demand without incumbent saturation. Direct-to-farm digital channels bypass traditional distributor markups and enable precision agriculture subscription integration. Target northern Uruguayan pasture districts through agronomy-as-a-service platforms rather than commodity product competition.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized biological pure-plays with beneficial organism combination capabilities over diversified chemistry conglomerates. Long-term viability rests on fermentation technologist talent pipelines and strain patent portfolios rather than manufacturing scale alone. Watch ANVISA-SENASA biocontrol registration harmonization progress as the inflection indicator for cross-border manufacturing consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive molasses processing at São Paulo facilities insulates margin from sugar ethanol arbitrage volatility. |
| Seed-Treatment Bundling at Processing Facilities | ANVISA-registered microbial coatings embedded into standard Argentine wheat planting protocols lock in grower loyalty. |
| Direct-to-Farm Digital Channel Development | Agronomy-as-a-service platforms bypass distributor markups and enable precision prescription in Mato Grosso cooperatives. |
| Strain Patent Portfolio Expansion | Regional Bacillus and Trichoderma germplasm development reduces dependency on North American proprietary lineages. |
| Cross-Border Registration Harmonization | Unified ANVISA-SENASA approval pathways enable single-facility supply across Mercosur trade corridors. |
Research Methodology
Desk research of ANVISA registration databases, SENASA import equivalency filings, and Mercosur trade flow records preceded structured interviews with fermentation plant managers, biological input R&D directors, Argentine wheat cooperative agronomists, Brazilian distributor procurement leads, and Chilean fruit export compliance officers. Secondary validation drew from customs trade statistics, agricultural extension service reports, and SEC filings of diversified agrochemical conglomerates. Bottom-up strain-level demand estimates and top-down regional acreage projections were triangulated against manufacturer shipment data.
Assumptions around ANVISA approval timeline compression, molasses feedstock cost trajectories, and Cerrado pasture conversion rates were held fixed across baseline scenarios while stress-testing sensitivity to regulatory harmonization delays and sugar ethanol market shocks. Segmentation modeling incorporated organism type, application function, end-use industry sophistication, and channel economics dimensions. CAGRs were derived from curve-fitting historical adoption patterns against projected acreage expansion and penetration rate assumptions, with nitrogen fixation efficacy data and biocontrol field trial outcomes serving as industry-specific validation inputs.
Stress conditions across ANVISA regulatory backlog severity, Argentine peso import financing availability, and Brazilian ethanol policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and acknowledge that strain patent litigation or sudden residue tolerance tightening could materially revise projections. Cross-checking against Brazilian agricultural census data and ANVISA commercial registration releases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Baobab Market
Agricultural Biologicals
South America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Microbial Agricultural Inoculants Market
Agricultural Biologicals
Agricultural Activator Adjuvants Market
Agricultural Biologicals
Feed Mycotoxin Binders Market
Agricultural Biologicals
Global Inoculants Market
Agricultural Biologicals
Silybum Marianum Market
Agricultural Biologicals
Global Silage Inoculants Market
Agricultural Biologicals
Edible Fungus Market
Agricultural Biologicals
Agricultural Biofungicides Market
Agricultural Biologicals
North America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Monolaurin for Feed Market
Agricultural Biologicals
Global Organic Trace Minerals for Animal Feeds Market
Agricultural Biologicals
Soil Inoculants Market
Agricultural Biologicals
South America Biostimulants Market
Agricultural Biologicals
Global Agricultural Enzymes Market