
 Agricultural Adjuvants Market | 2026-2036
Agricultural Adjuvants Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Adjuvants Market Analysis
Specialized formulation chemists with expertise in green surfactant chemistry is reorganizing how adjuvant manufacturers staff their technical centers. BASF SE leverages its integrated surfactant supply chain to control raw material quality from petrochemical feedstock through finished tank-mix products. Croda International Plc anchors its position through bio-based ester chemistry derived from renewable feedstocks. Evonik Industries AG competes via silicone superwetter technology that dominates specialty crop applications in high-value horticulture.
Agricultural adjuvants are functional co-formulants or tank-mix additives designed to modify the physical properties of spray solutions, typically comprising surfactants, oils, emulsifiers, or inorganic salts that reduce surface tension, improve droplet retention, or enhance active ingredient penetration through plant cuticles. Their primary commercial purpose is to maximize biological performance of crop protection products while enabling lower active ingredient rates per hectare. Surfactants command the largest product type position due to universal compatibility with herbicide and fungicide formulations, while oils represent the fastest-growing category as methylated seed oils displace petroleum distillates under environmental pressure. Liquid formulations dominate the form dimension because of ease of tank-mix handling and metering accuracy, though granular adjuvants sustain niche demand in aerial application and controlled-release fertilizer coating.
The EPA regulates adjuvant labeling and claims under FIFRA, while the EU REACH framework governs surfactant chemical registration and environmental fate testing across member states. Brazil's national environmental regulator, IBAMA, enforces spray drift buffer requirements that directly shape adjuvant selection for soybean and cotton applications. Stakeholders must monitor how evolving per- and polyfluoroalkyl substance restrictions in the EU and US will force reformulation of certain wetting agents before the next product registration cycle.
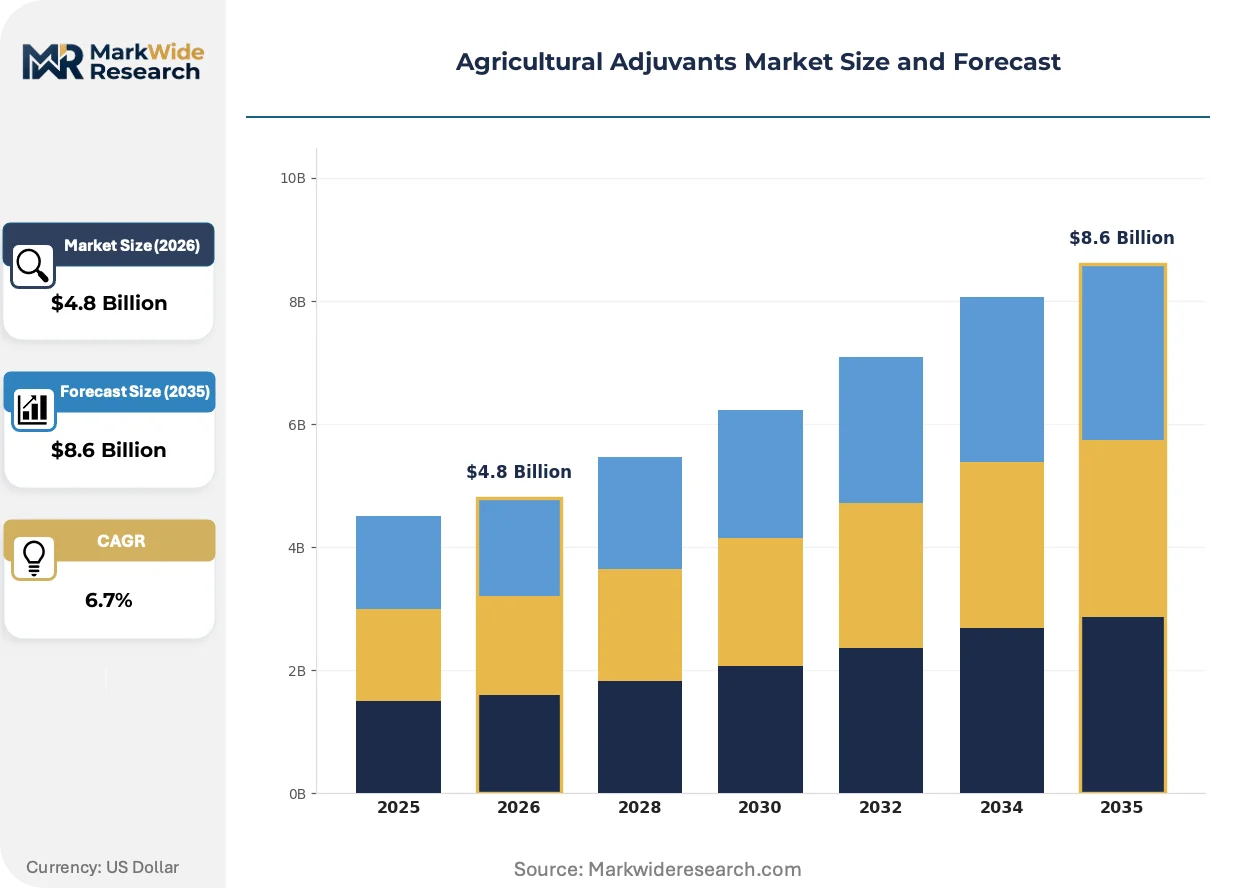
Market Dynamics
Specialty crop growers in California and Florida are expanding adjuvant use to improve pesticide efficacy under tighter water restrictions, while Brazil's Cerrado region drives demand as no-till farming expands. The EPA's updated spray drift regulations are pushing formulators toward low-volatility methylated seed oil replacements, reorganizing technical staffing requirements across manufacturer R&D centers.
Growth Catalysts
- Water restriction compliance:California's Sustainable Groundwater Management Act mandates reduced agricultural water use, driving adoption of drift-reduction adjuvants that enable lower spray volumes without sacrificing coverage uniformity.
- REACH framework evolution:The EU's tightening per- and polyfluoroalkyl substance restrictions are forcing reformulation timelines that favor bio-based ester chemistry suppliers with pre-validated environmental fate data.
- No-till expansion:Brazil's Cerrado region is converting millions of hectares to continuous no-till systems where methylated seed oil adjuvants improve herbicide performance on high-residue surfaces.
Market Restraints
- Petrochemical feedstock volatility:Surfactant manufacturers face margin compression from ethylene oxide and fatty alcohol price swings that resist full pass-through to tank-mix formulators.
- Registration timeline friction:Brazil's IBAMA enforces spray drift buffer requirements that extend product validation cycles by 18-24 months for new adjuvant chemistries.
- Petroleum distillate displacement limits:Legacy crop oil concentrate formulations retain cost advantages in commodity grain applications, slowing methylated seed oil penetration in price-sensitive segments.
Strategic Opportunities
- Controlled-release fertilizer coating:Granular adjuvant formulations are penetrating aerial application markets where liquid handling logistics constrain operational flexibility.
- Silicone superwetter convergence:High-value horticulture in Spain and Italy is adopting organosilicone surfactants for specialty crop protection, opening premium pricing tiers.
- Green surfactant chemistry:Bio-based alkyl polyglucosides derived from renewable feedstocks qualify for EU Green Deal procurement preferences in public agricultural extension programs.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in green surfactant synthesis and cuticle penetration modeling commands premium compensation that mid-tier manufacturers struggle to fund.
- Integrated supply chain complexity:Captive production of petrochemical feedstocks through finished tank-mix products requires capital allocation that conflicts with R&D investment priorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Adjuvants Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surfactants, Oils, Emulsifiers, Salts Application: Pesticides, Herbicides, Fertilizers, Biostimulants Form: Liquid, Granular, Powder, Cream End User: Agronomists, Farmers, Cooperatives, Distributors |
| Companies Covered | BASF SE, Corteva Agriscience, Croda International Plc, Solvay, Evonik Industries AG, Clariant AG, Nufarm Limited, Helena Agri-Enterprises, Stepan Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Adjuvants Market Emerging Trajectories
Formulation chemistry is pivoting toward bio-based and low-volatility alternatives as regulatory pressure intensifies across multiple jurisdictions. Technical staffing models and supply chain architectures are reorganizing around these material transitions.
Organosilicone superwetters are supplanting conventional nonionic surfactants in specialty crop applications. High-value horticulture operations in Spain, Italy, and California's Central Valley are adopting these materials for their superior spreading coefficients on waxy leaf surfaces. This chemistry is supplanting legacy ethoxylated alcohol formulations in premium segments while compressing margins for commodity surfactant suppliers.
REACH per- and polyfluoroalkyl substance restrictions are accelerating reformulation cycles for fluorosurfactant-based wetting agents. The EU's 2025 restriction timeline forces manufacturers to validate bio-based replacements before the next product registration cycle. Adjuvant formulators serving European specialty crop markets are prioritizing alkyl polyglucoside and sucrose ester chemistries to maintain label claims.
Buyer concentration among large-scale agricultural cooperatives is consolidating procurement leverage. Midwestern US grain operations and Mato Grosso soybean producers are negotiating direct supply agreements that displace traditional distributor networks. This pattern is most visible in Brazil's Cerrado, where no-till farming cooperatives specify adjuvant performance standards in multi-year crop protection bundles.
Agricultural Adjuvants Market Segmentation
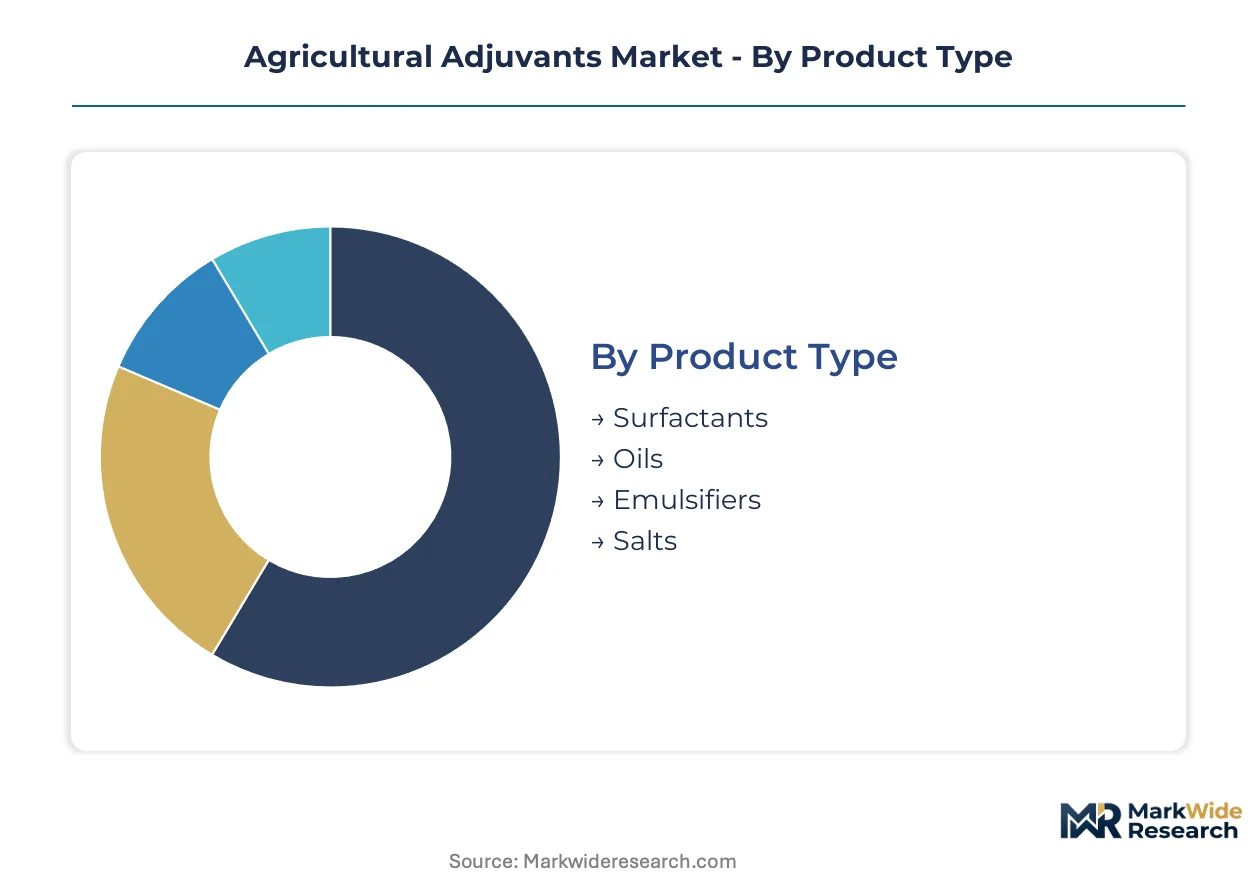
Agricultural adjuvant purchasing decisions pivot on formulation chemistry compatibility, application method constraints, and end-user operational scale. Segmentation reveals where bio-based substitutes are displacing legacy petrochemical formulations.
Product Type:
Surfactants face the most acute substitution pressure as REACH per- and polyfluoroalkyl substance restrictions force reformulation of fluorosurfactant-based wetting agents.
- Surfactants:Nonionic and organosilicone chemistries reduce surface tension to improve droplet spreading on waxy leaf cuticles. Demand concentrates in California specialty crop operations where drift-reduction mandates favor low-foam ethoxylated alcohol formulations.
- Oils:Methylated seed oils and modified vegetable oils enhance herbicide penetration through plant cuticles while displacing petroleum distillates under EPA volatility regulations. Brazil's Cerrado no-till cooperatives specify these for soybean pre-emergence applications on high-residue fields.
- Emulsifiers:Enable stable oil-water dispersion in tank-mix combinations.
- Salts:Inorganic ammonium sulfate formulations adjust spray solution pH and hardness.
Surfactants anchor the volume base while oils gain share at the steepest rate.
Application:
Cost tier differentiation separates premium crop protection bundles from commodity input purchasing.
- Pesticides:Adjuvants maximize insecticide and fungicide efficacy through improved cuticular penetration and rainfastness. Spain and Italy's high-value horticulture sectors specify organosilicone superwetters for integrated pest management programs.
- Herbicides:Glyphosate and dicamba tank-mixes depend on surfactant systems to overcome weed resistance mechanisms. Midwestern US grain operations negotiate direct supply agreements for drift-reduction adjuvants under EPA buffer zone requirements.
- Fertilizers:Granular adjuvant coatings enable controlled-release nutrient delivery in aerial application scenarios.
- Biostimulants:Compatibility agents ensure microbial inoculant viability in combined spray solutions.
Pesticide applications generate the largest absolute demand while herbicide adjuvants expand most quickly under resistance management protocols.
Form:
Customer handling logistics determine format selection across operational scales.
- Liquid:Dominates tank-mix applications where metering accuracy and rapid dispersion are critical. California's Sustainable Groundwater Management Act compliance drives adoption of low-volume spray systems that favor liquid handling precision.
- Granular:Sustains demand in aerial application markets where liquid logistics constrain operational flexibility and controlled-release fertilizer coating requires solid-phase delivery.
- Powder:Dry flowable formulations serve specialty crop sectors with limited on-farm mixing infrastructure.
- Cream:High-viscosity emulsions target specific compatibility challenges with suspension concentrate herbicides.
Liquid formulations command the installed base while granular formats climb the fastest in precision agriculture deployment.
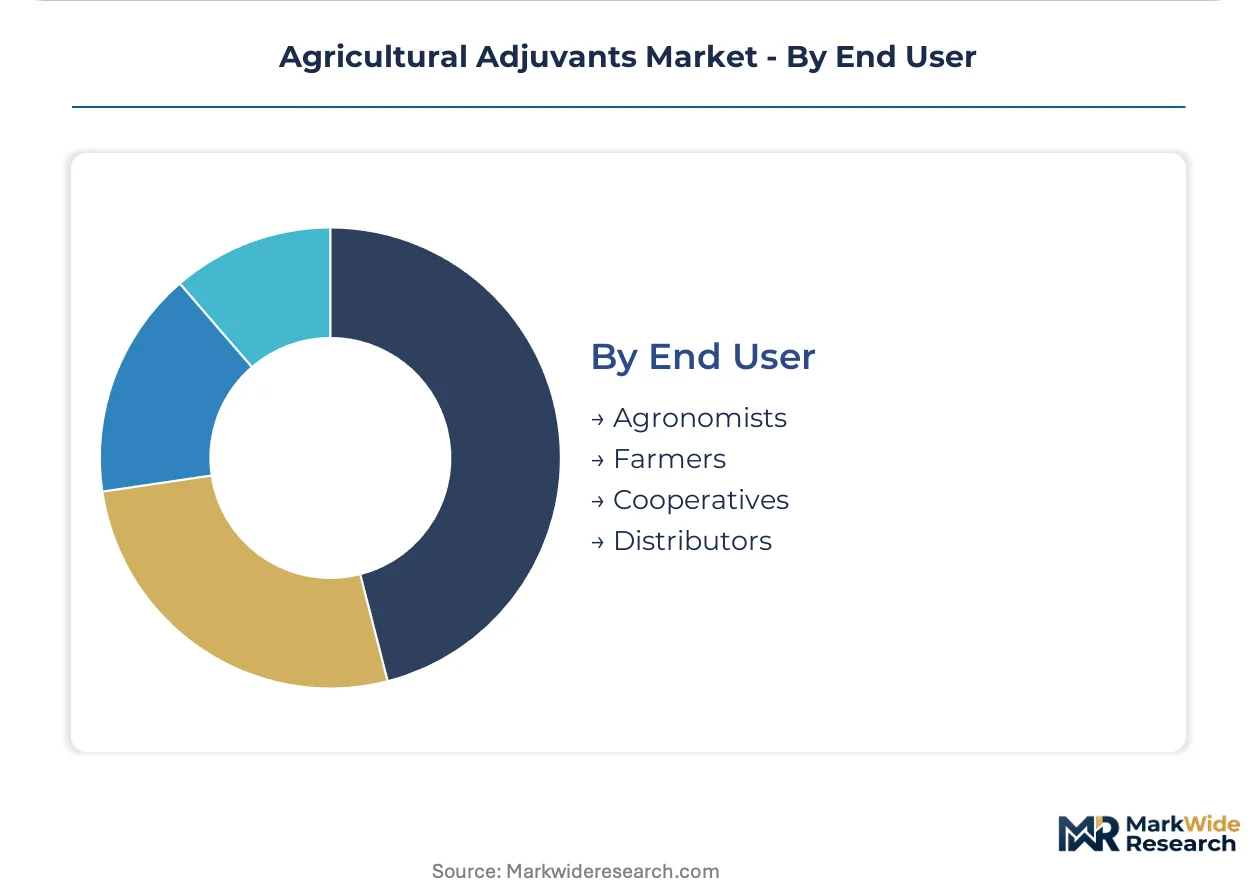
End User:
Procurement concentration is shifting toward large-scale operators with direct manufacturer negotiation leverage.
- Farmers:Individual growers in price-sensitive commodity grain segments retain legacy petroleum distillate formulations where cost per hectare dominates selection criteria.
- Cooperatives:Mato Grosso soybean cooperatives and Midwestern US grain operations consolidate purchasing power through multi-year crop protection bundles with specified adjuvant performance standards.
- Agronomists:Technical advisors influence specification decisions for specialty crop producers seeking optimized application protocols.
- Distributors:Traditional channel intermediaries face margin compression as direct supply agreements displace their historical role in Brazil's Cerrado and US Corn Belt regions.
Cooperatives anchor the volume base while agronomist-specified applications gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA spray drift regulations and California water restrictions anchor North American adjuvant demand, while EU REACH chemical frameworks and Brazil's IBAMA buffer requirements reshape procurement patterns across agricultural value chains.
United States
California's Sustainable Groundwater Management Act drives drift-reduction adjuvant adoption in specialty crop operations facing mandatory water use cuts. EPA updated volatility regulations for methylated seed oil formulations reshape tank-mix specifications in Midwest grain belts. Fresno County and Florida's Lake Okeechobee watershed concentrate horticulture adjuvant demand where coverage uniformity mandates intersect with environmental compliance.
Brazil
Expansion of no-till farming across Mato Grosso and the Cerrado region generates methylated seed oil demand for pre-emergence herbicide applications on high-residue fields. IBAMA enforces spray drift buffer requirements that extend product validation cycles for new adjuvant chemistries. Rondonópolis and Lucas do Rio Verde anchor cooperative procurement concentration where direct manufacturer agreements displace traditional distributor networks.
Germany
EU REACH per- and polyfluoroalkyl substance restrictions force reformulation timelines for fluorosurfactant-based wetting agents before the 2025 restriction deadline. ECHA environmental fate testing requirements favor suppliers with pre-validated bio-based ester chemistry data. Leverkusen and Ludwigshafen industrial clusters concentrate integrated surfactant manufacturing from petrochemical feedstock through finished formulations.
Spain
High-value horticulture operations in Almería and Murcia adopt organosilicone superwetters for integrated pest management programs targeting waxy leaf cuticles. EU Green Deal procurement preferences channel public agricultural extension funding toward bio-based alkyl polyglucoside formulations. Valencia's citrus cooperative networks specify adjuvant performance standards in multi-year crop protection bundles.
China
Domestic glyphosate formulation scale drives surfactant adjuvant consumption in Shandong and Jiangsu provinces. MEE environmental compliance inspections tighten manufacturing discharge standards for ethoxylated alcohol production. Yangtze River Delta chemical parks concentrate nonionic surfactant capacity serving both domestic tank-mix formulators and export markets.
Agricultural Adjuvants Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the agricultural adjuvants market. Integrated petrochemical conglomerates with captive surfactant supply chains compete against specialty bio-based chemistry houses focused on renewable feedstock validation. Three archetypes dominate: multinational chemical majors with backward integration into ethylene oxide and fatty alcohol production, mid-tier formulators sourcing merchant surfactants for regional tank-mix markets, and niche silicone superwetter specialists serving premium horticulture segments. Competitive moves concentrate on M&A to secure bio-based ester technology portfolios and strategic partnerships with agricultural cooperatives to bypass distributor channels.
Among European-based chemical majors, BASF SE, Evonik Industries AG, and Croda International Plc occupy positions spanning integrated petrochemical supply chains through finished adjuvant formulations. BASF SE exemplifies the integrated archetype with control from feedstock through tank-mix products. Evonik Industries AG represents silicone superwetter specialization targeting high-value horticulture applications. Croda International Plc anchors the bio-based chemistry vector with renewable feedstock-derived ester platforms qualifying for EU Green Deal procurement preferences.
| Leading Market Players |
|---|
| BASF SE |
| Corteva Agriscience |
| Croda International Plc |
| Solvay |
| Evonik Industries AG |
| Clariant AG |
| Nufarm Limited |
| Helena Agri-Enterprises |
| Stepan Company |
| Others |
Supply Flow & Price Mechanics
EPA volatility regulations and EU REACH chemical registration tiers gate both raw material qualification and end-product price positioning across agricultural adjuvant markets. Formulators must clear environmental fate testing thresholds before accessing premium pricing tiers, while commodity surfactant suppliers compete on volume scale without certification premiums.
Pricing Analysis
Brazilian methylated seed oil formulations trade at 15-25% premiums over US Midwest grain belt equivalents due to IBAMA validation costs and logistics complexity. Three-tier pricing structure across premium organosilicone, standard nonionic surfactant, and economy petroleum distillate levels reflects formulation chemistry and registration tier. Cost compression in commodity surfactants is intensifying because ethylene oxide feedstock volatility resists full pass-through. Individual farmers in price-sensitive grain segments exhibit highest price sensitivity; high-value horticulture cooperatives in Spain and California show lowest.
Supply Chain Analysis
Inventory cycles for fatty alcohol feedstocks stretch 8-12 weeks due to ethylene oxide production scheduling at German and US Gulf Coast petrochemical complexes. Supply concentrates in Germany, China, and Brazil where integrated surfactant manufacturing clusters serve regional tank-mix formulators. Raw material flows draw from palm kernel oil plantations in Southeast Asia, rapeseed methyl ester streams in European biodiesel networks, and petrochemical ethylene oxide derivatives. Single-source vulnerability runs through specialty silicone superwetter precursors concentrated at Evonik's German production sites. Distribution runs through agricultural cooperative procurement offices displacing traditional distributor networks in Brazil's Cerrado and US Corn Belt regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agricultural adjuvant markets are approaching a platform-economics inflection where cooperative procurement standardization creates winner-take-most dynamics around validated bio-based chemistry portfolios. Interoperability between adjuvant performance databases and precision agriculture spray systems is consolidating specification authority.
For Market Incumbents: Compound backward integration into renewable feedstock supply through partnerships with European biodiesel producers securing rapeseed methyl ester streams. Deepen captive surfactant capacity in Brazil's Rondonópolis corridor to serve Cerrado cooperative demand without distributor margin loss. Defend against silicone superwetter substitution in horticulture by accelerating organosilicone R&D investment.
For New Entrants and Emerging Players: Differentiate on bio-based ester chemistry with pre-validated EU REACH environmental fate data to bypass 18-24 month registration delays facing petrochemical newcomers. Target granular adjuvant formulations for aerial application markets where liquid logistics constraints create procurement friction for incumbents. Pursue direct supply agreements with Mato Grosso soybean cooperatives specifying performance standards in multi-year bundles.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across bio-based surfactant synthesis as continuous processing replaces batch manufacturing. Long-term viability favors platforms with integrated renewable feedstock access and cooperative channel relationships rather than distributor-dependent models. Monitor silicone superwetter patent expiration schedules as inflection indicator for generic substitution pressure in premium horticulture segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Feedstocks | Secures rapeseed methyl ester supply for EU Green Deal qualification. |
| Cooperative Direct Supply Agreements | Bypasses distributor networks in Brazil's Cerrado and US Midwest grain belts. |
| Green Surfactant Chemistry R&D Investment | Positions for REACH per- and polyfluoroalkyl substance restriction compliance. |
| Granular Formulation Capacity Expansion | Captures aerial application markets where liquid logistics constrain operations. |
| Silicone Superwetter Patent Portfolio Acquisition | Consolidates premium horticulture positioning against generic substitution. |
Methodological Framework
Two parallel data streams informed the analysis: structured interviews with formulation chemists, agricultural cooperative procurement managers, and regulatory affairs specialists at tank-mix manufacturers, combined with secondary validation against EPA registration databases, IBAMA environmental compliance filings, and EU ECHA substance restriction timelines. Primary fieldwork captured operational practices across California specialty crop operations, Brazil's Cerrado no-till cooperatives, and Spanish horticulture clusters. Bottom-up volume estimates from adjuvant consumption rates per hectare were triangulated against top-down chemical industry production data.
Across the analysis window, forecasts model product type substitution dynamics, application method evolution, and cooperative procurement concentration as core segmentation dimensions. CAGRs derive from regression analysis of historical formulation chemistry shifts correlated with regulatory implementation timelines. Industry-specific inputs include EPA spray drift buffer expansion scenarios, EU REACH substance restriction phase-in schedules, and no-till farming adoption curves in Brazilian soybean regions.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of environmental fate standards or cooperative procurement consolidation would require recalibration. Forecasts reflect documented assumptions around bio-based chemistry cost parity achievement and petrochemical feedstock volatility patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Europe Agricultural Microbials Market
Agricultural Biologicals
Microbial Agricultural Inoculants Market
Agricultural Biologicals
Middle East and Africa Bio-Stimulants Market
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
South America Agricultural Microbials Market
Agricultural Biologicals
Baobab Market
Agricultural Biologicals
Global Organic Trace Minerals for Animal Feeds Market
Agricultural Biologicals
North America Amino Acids Market
Agricultural Biologicals
North America Animal Feed Additives Market
Agricultural Biologicals
Africa Feed Enzymes Market
Agricultural Biologicals
Chitosan for Agriculture Market
Agricultural Biologicals
North America Agricultural Microbials Market
Agricultural Biologicals
Global Agricultural Enzymes Market
Agricultural Biologicals
Edible Fungus Market
Agricultural Biologicals
India Feed Enzymes Market
Agricultural Biologicals
Global Agricultural Inoculant Market