
 Insect Feed Market | 2026-2036
Insect Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Insect Feed Market Intelligence
Buyer concentration among aquaculture firms is recalibrating as salmon and shrimp producers diversify protein sourcing away from volatile fishmeal supply chains. Protix leverages its Dutch industrial campus to supply consistent black soldier fly larvae volumes to European aquafeed blenders. InnovaFeed sustains vertical control from egg breeding to lipid extraction, anchoring its position in high-grade aquaculture nutrition.
Insect feed comprises processed larvae, crickets, mealworms, and grasshoppers milled into protein meals, oils, and whole-dried formats for animal nutrition, with black soldier fly larvae typically containing 40-45% crude protein and 30-35% fat on a dry matter basis. Larvae dominates current production volumes due to short rearing cycles and high bioconversion efficiency on organic waste substrates. Aquaculture applications attract the fastest capacity expansion as marine ingredient substitution intensifies, while pet food commands premium pricing from urban consumers seeking sustainable protein claims.
The EU's EFSA and the EU Commission's Novel Food and Feed regulations govern insect protein approval and inclusion rates across species categories, with recent amendments expanding poultry and porcine feed permissions beyond prior aquaculture-only allowances. The FDA in the United States maintains state-level variance for insect feed in pet food and poultry, creating fragmented market access conditions. Stakeholders must monitor regulatory divergence between jurisdictions to optimize facility placement and species registration strategies.
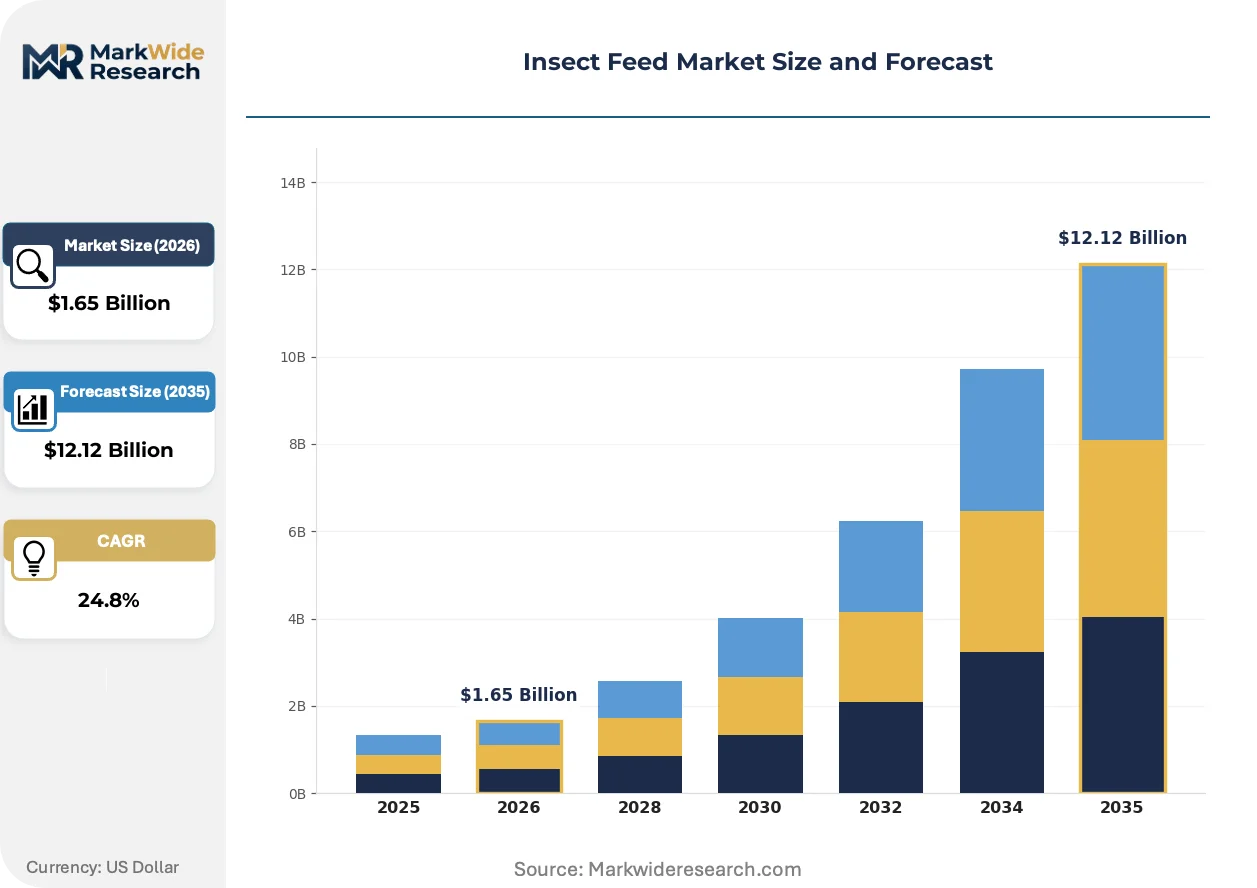
Market Dynamics
Fishmeal price volatility is forcing aquaculture feed formulators to restructure protein sourcing strategies, triggering capital flows into industrial insect farming infrastructure across multiple jurisdictions.
Growth Catalysts
- EU 2017/893 Regulation Expansion:The European Commission's amendment permitting insect protein in poultry and pig feed removes prior aquaculture-only constraints, unlocking commercial scale for Dutch and French producers.
- Salmonid Feed Blenders:Norwegian and Scottish salmon producers are diversifying marine ingredient portfolios as Peruvian anchovy quotas tighten, creating pull-through demand for black soldier fly meal.
- Automated Rearing Systems:Climate-controlled vertical farming technology is compressing larval development cycles to 14 days, enabling consistent year-round output regardless of ambient conditions.
Market Restraints
- Organic Substrate Cost Volatility:Pre-consumer food waste streams face competing demand from anaerobic digestion facilities subsidized under national renewable energy credits, pressuring input margins.
- Single-Region Production Concentration:Over 60% of industrial-scale black soldier fly capacity sits within 200 kilometers of Rotterdam, creating geographic risk exposure for European feed supply chains.
- Protein Quality Variability:Larval meal amino acid profiles fluctuate based on substrate composition, requiring blending standardization that soy and fishmeal suppliers have already solved.
Strategic Opportunities
- US State-Level Pet Food Variance:FDA's delegated authority creates patchwork approval pathways where Oregon and Washington permit insect protein while Texas and Florida maintain prohibitions, rewarding targeted facility placement.
- Layer Hen Nutrition:Post-molt recovery diets and omega-3 enriched egg programs represent untapped demand for black soldier fly oil as a sustainable lipid source.
- Carbon Accounting Integration:EU Green Deal farm-to-fork reporting requirements are creating premium pricing tiers for feed ingredients with verified Scope 3 emissions reductions.
Industry Challenges
- Entomology Talent Scarcity:Industrial-scale facilities require specialized expertise in dipteran reproductive physiology that conventional agriculture programs do not produce.
- Multi-Jurisdiction Species Registration:Each EU member state maintains separate approval timelines for novel feed materials, fragmenting market access despite harmonized safety standards.
- Downstream Blending Infrastructure:Aquafeed mills require dedicated handling lines to prevent cross-contamination with conventional proteins, demanding retrofit capital that mid-tier operators struggle to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insect Feed Market |
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $12.12 Billion |
| CAGR (2026 – 2036) | 24.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feed Type: Larvae, Crickets, Mealworms, Grasshoppers Application: Aquaculture, Poultry Feed, Pet Food, Organic Fertilizer End User: Farmers, Feed Manufacturers, Pet Owners, Aquaculture Firms Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesalers |
| Companies Covered | Ÿnsect, Protix, InnovaFeed, EnviroFlight, HiProMine, Entofood, Hexafly, Aspire Food Group, Entomo Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insect Feed Market Strategic Shifts & Innovations
Automation and regulatory normalization are converging to transform insect feed from experimental ingredient to standardized commodity, with production technology and policy frameworks advancing in parallel.
Precision environmental control systems are absorbing capital investment across industrial facilities. These sensor-networked climate systems maintain optimal temperature, humidity, and gas composition for larval density maximization. Salmon feed manufacturers in Norway and Chile are qualifying output from automated facilities at accelerated rates. This technology is absorbing uncertainty from biological production variables, compressing the risk premium that feed blenders previously applied to insect meal.
EFSA's 2021 safety opinion on farmed insect species established the scientific foundation for broader EU regulatory expansion. The European Commission's subsequent delegated acts are harmonizing maximum inclusion rates across member states. Poultry compound feed producers in France and Germany are reformulating starter and grower rations to incorporate 5-8% insect meal ahead of anticipated further relaxations.
Direct contracting between insect farms and aquaculture integrators is displacing spot-market purchasing. Norwegian salmon producers are negotiating multi-year offtake agreements with fixed volume and quality specifications. This behavior concentrates procurement authority with species-specific nutrition teams rather than commodity traders. The Netherlands and Denmark exhibit the most advanced contracting structures, with pricing indexed to fishmeal futures rather than spot larvae markets.
Insect Feed Market Segmentation
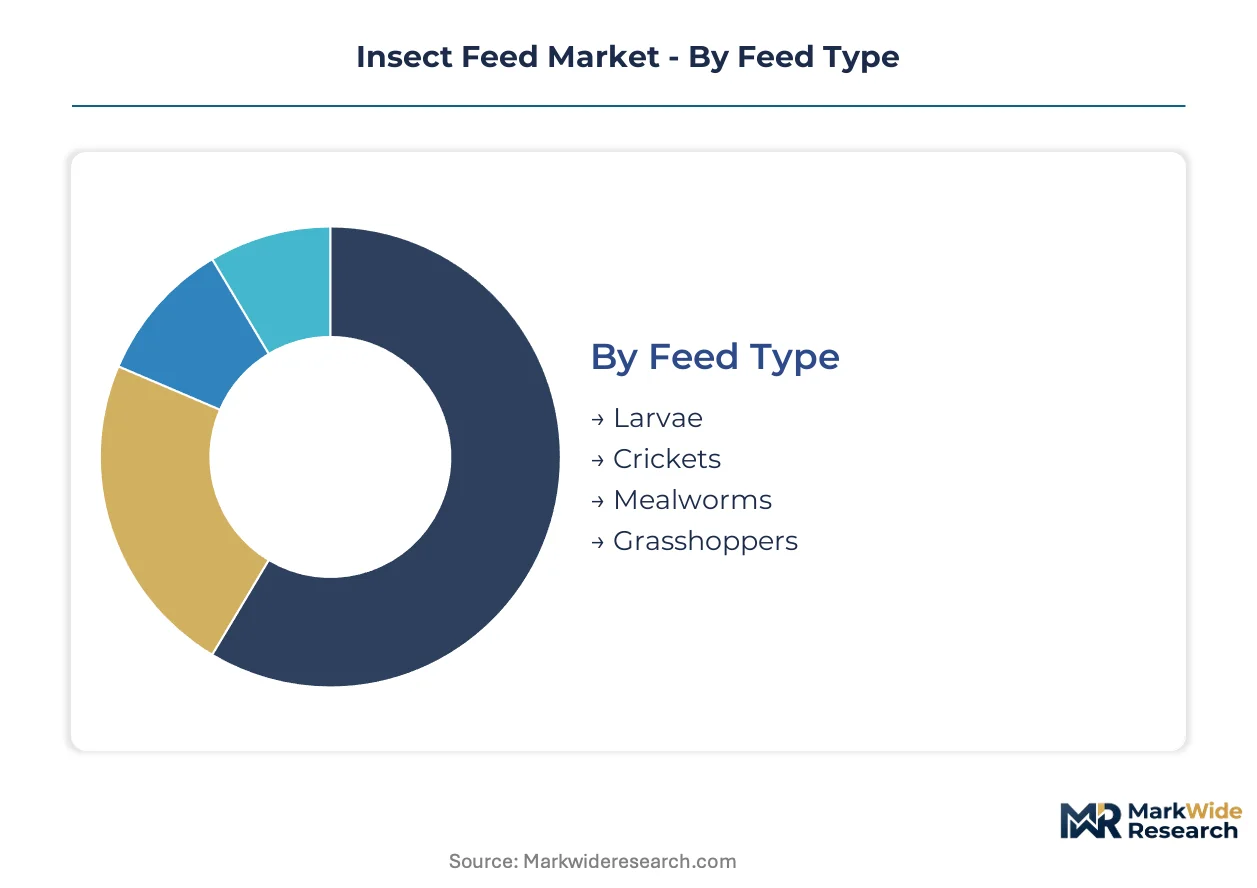
Insect feed segmentation reveals divergent margin structures across species and channels. Larvae-based products dominate industrial procurement volumes while premium retail formats command higher per-kilogram pricing through specialty distribution.
Feed Type:
Volume concentration favors short-cycle species with established rearing protocols, while premium positioning accrues to novel protein formats with consumer-facing sustainability claims.
- Larvae:Black soldier fly larvae yield 40-45% crude protein and 30-35% fat on dry matter basis, processed into meal, oil, and whole-dried formats. Dutch and French industrial facilities supply salmon feed blenders in Norway and Scotland seeking fishmeal alternatives as Peruvian anchovy quotas tighten.
- Mealworms:Tenebrio molitor delivers consistent amino acid profiles with lower fat content than larvae, suited to poultry starter rations and high-protein pet food applications. German and Polish producers are expanding climate-controlled rearing capacity to serve compound feed manufacturers.
- Crickets:Gryllus species offer complete protein with favorable digestibility scores for premium pet nutrition and human-grade crossover products. Production remains artisanal-scale across most of Europe with limited industrial standardization.
- Grasshoppers:Locusta migratoria and related species provide lean protein concentrate for niche aquaculture and reptile feed segments. Wild-harvest regulatory constraints restrict commercial scaling outside controlled farming jurisdictions.
Mature deployment sits with larvae. Newer deployment is concentrated in mealworms.
Application:
End-use segmentation tracks regulatory approval sequencing, with aquaculture maintaining first-mover status and poultry feed accelerating following EU 2017/893 amendments.
- Aquaculture:Salmonid and shrimp feed formulators integrate black soldier fly meal at 5-15% inclusion rates to reduce marine ingredient dependency. Norwegian producers negotiate multi-year offtake agreements with fixed volume specifications indexed to fishmeal futures.
- Poultry Feed:Layer and broiler rations incorporate insect protein for post-molt recovery and omega-3 enriched egg programs. French and German compounders are reformulating starter and grower rations ahead of anticipated further EU regulatory relaxations.
- Pet Food:Urban consumers seeking sustainable protein claims drive premium pricing for insect-based dog and cat nutrition. Oregon and Washington state approvals enable US market access while Texas and Florida maintain prohibitions.
- Organic Fertilizer:Larval frass and processing residuals convert to high-nitrogen soil amendments for horticulture and specialty crop operations. Dutch producers bundle frass sales with larvae offtake contracts to improve facility economics.
Commercial scale concentrates in aquaculture. Regulatory expansion is reshaping poultry feed.
End User:
Customer type determines procurement structure, with institutional buyers demanding consistent specification batches and individual purchasers accepting higher unit costs for retail convenience.
- Feed Manufacturers:Aquafeed and poultry compounders require dedicated handling lines to prevent cross-contamination, demanding retrofit capital that mid-tier operators struggle to deploy. Direct contracting with insect farms is displacing spot-market purchasing across the Netherlands and Denmark.
- Aquaculture Firms:Salmon and shrimp producers diversify protein sourcing away from volatile fishmeal supply chains through backward integration partnerships with larvae producers.
- Farmers:Backyard poultry and small livestock operations purchase whole-dried insects through agricultural cooperatives and specialty distributors.
- Pet Owners:Urban consumers in premium demographic segments purchase branded insect protein products through veterinary clinics and specialty retail channels.
Procurement authority concentrates with feed manufacturers. Direct farm purchasing is gaining share fastest.
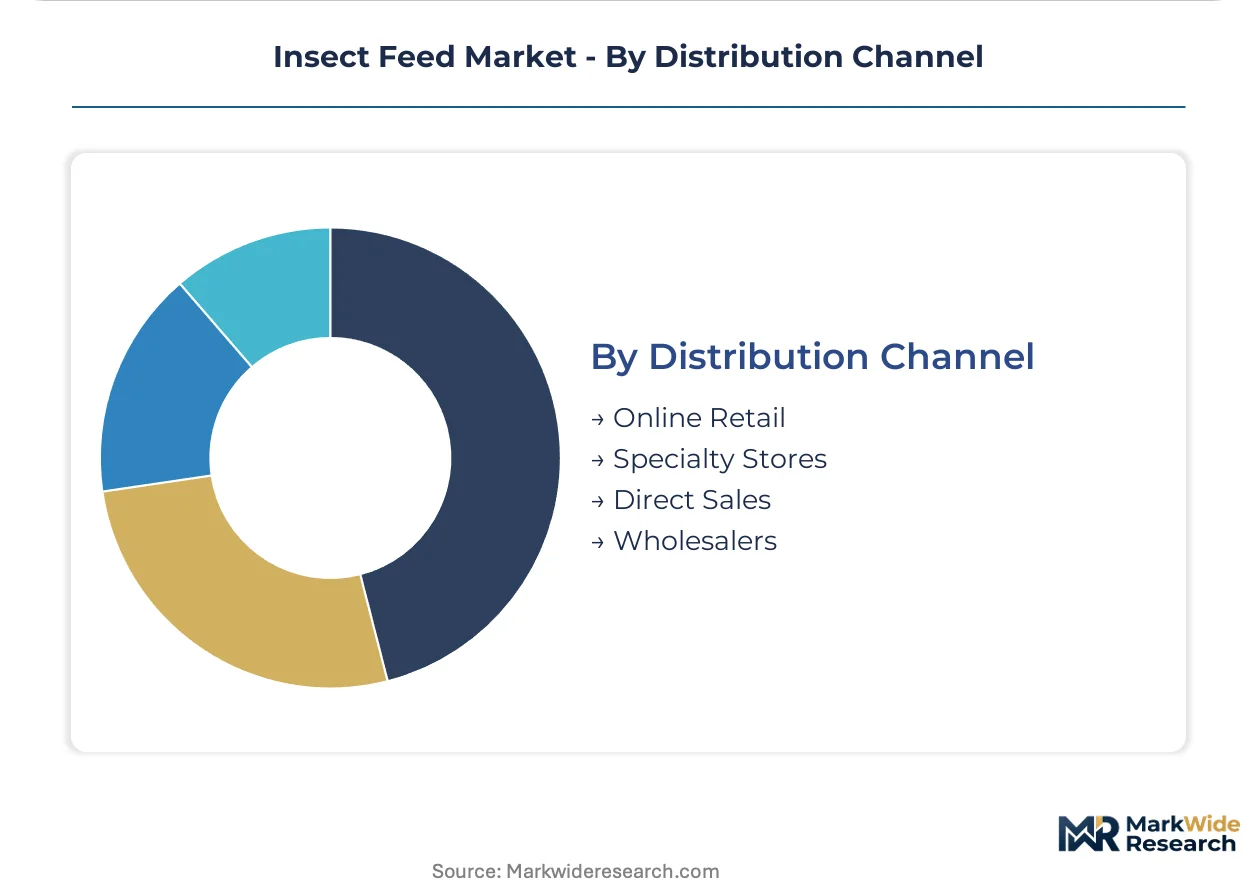
Distribution Channel:
Channel selection reflects batch size requirements and specification sensitivity, with industrial volumes flowing through direct relationships and consumer products requiring retail intermediaries.
- Direct Sales:Multi-year supply agreements between insect farms and aquaculture integrators specify protein content, moisture limits, and contaminant thresholds. Norwegian salmon producers anchor this channel with contracted volume commitments.
- Wholesalers:Regional distributors aggregate larvae meal from multiple producers to supply mid-tier compound feed operations lacking direct sourcing relationships.
- Specialty Stores:Pet food retailers and agricultural supply cooperatives serve hobby farmers and premium pet owners with packaged whole-dried and formulated products.
- Online Retail:Direct-to-consumer platforms reach urban pet owners and small-scale poultry keepers with subscription-based replenishment models.
Institutional volume flows through direct sales. Online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority concentrates with aquaculture integrators in Northern Europe, where fishmeal substitution pressures intersect with permissive feed regulations. Industrial-scale facilities cluster within logistics corridors serving salmon feed blenders.
Netherlands
Rotterdam's industrial corridor hosts the densest concentration of black soldier fly production capacity in Europe. EFSA's safety opinions on farmed insect species enabled the EU 2017/893 regulatory expansion that Dutch producers leveraged first. Protix operates industrial-scale facilities supplying consistent larvae volumes to Norwegian aquafeed manufacturers.
France
Poultry compound feed producers in northern France are reformulating starter and grower rations to incorporate insect protein ahead of further EU regulatory relaxations. The country's national feed safety authority aligns with EFSA harmonization timelines for novel feed materials. InnovaFeed maintains vertical control from egg breeding to lipid extraction at its northern industrial campus.
Norway
Salmon producers negotiate multi-year offtake agreements with fixed volume specifications indexed to fishmeal futures. The Norwegian Food Safety Authority implements EU feed regulations with accelerated approval pathways for aquaculture applications. Bergen and Trondheim serve as procurement decision centers where marine ingredient diversification strategies concentrate.
Germany
Mealworm producers in Lower Saxony and North Rhine-Westphalia expand climate-controlled rearing capacity to serve compound feed manufacturers. The Federal Office of Consumer Protection and Food Safety coordinates with EFSA on species registration timelines. Leipzig's logistics hub aggregates larvae meal for distribution to mid-tier poultry operations lacking direct sourcing relationships.
United States
Oregon and Washington state approvals enable West Coast market access for insect protein in pet food while Texas and Florida maintain prohibitions. FDA's delegated authority creates patchwork regulatory conditions rewarding targeted facility placement. Aspire Food Group and EnviroFlight anchor production decisions in permissive jurisdictions.
Insect Feed Market Key Industry Players
Dutch and French producers anchor the integrated-tier segment; North American specialists hold positions in pet food and state-level regulatory arbitrage. The vendor base separates into three strategic archetypes: vertically integrated industrial operators controlling breeding through processing, regional specialists exploiting substrate access advantages, and technology licensors exporting rearing systems. Capacity expansion and direct contracting with aquaculture integrators constitute the dominant competitive moves displacing spot-market purchasing.
Within the European integrated tier, Protix and InnovaFeed exemplify industrial-scale archetypes with captive supply chains serving salmon feed blenders. Among North American fabricators, EnviroFlight and Aspire Food Group occupy positions shaped by FDA's state-level variance, with facility placement decisions reflecting regulatory patchwork conditions. Ÿnsect represents the French specialization in mealworm production for poultry and pet nutrition applications.
| Leading Market Players |
|---|
| Ÿnsect |
| Protix |
| InnovaFeed |
| EnviroFlight |
| HiProMine |
| Entofood |
| Hexafly |
| Aspire Food Group |
| Entomo Farms |
| Others |
Cost & Logistics Intelligence
Aquafeed blenders in Norway and Scotland concentrate procurement authority through multi-year offtake agreements, anchoring contract-based pricing indexed to fishmeal futures rather than spot larvae markets. This buyer concentration compresses margin variability for Dutch and French producers while rewarding volume scale with pricing stability.
Pricing Analysis
Volume-mass larvae meal trades at commodity-equivalent rates while premium-grade black soldier fly oil commands 40-60% uplifts for omega-3 enrichment applications. Price differentiation hinges on protein content certification and EFSA-compliant substrate traceability, with pet food blenders in Oregon and Washington absorbing the highest premiums. Cost compression in standard-grade meal is intensifying as automated rearing systems expand Dutch capacity. Salmon feed manufacturers exhibit lowest price sensitivity due to marine ingredient substitution mandates, while mid-tier poultry compounders in Germany face acute margin pressure from soy meal competition.
Supply Chain Analysis
Entomology talent scarcity in the Netherlands, France, and Belgium constrains facility expansion despite capital availability for climate-controlled infrastructure. Raw material flows draw from pre-consumer food waste streams, organic agricultural residuals, and brewery spent grains, with substrate quality variability propagating into protein profile inconsistency. Single-region production concentration within 200 kilometers of Rotterdam creates geographic risk exposure for European feed supply chains. Distribution runs through direct sales agreements with aquaculture integrators, supplemented by regional wholesalers aggregating volumes for mid-tier compounders lacking captive sourcing relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
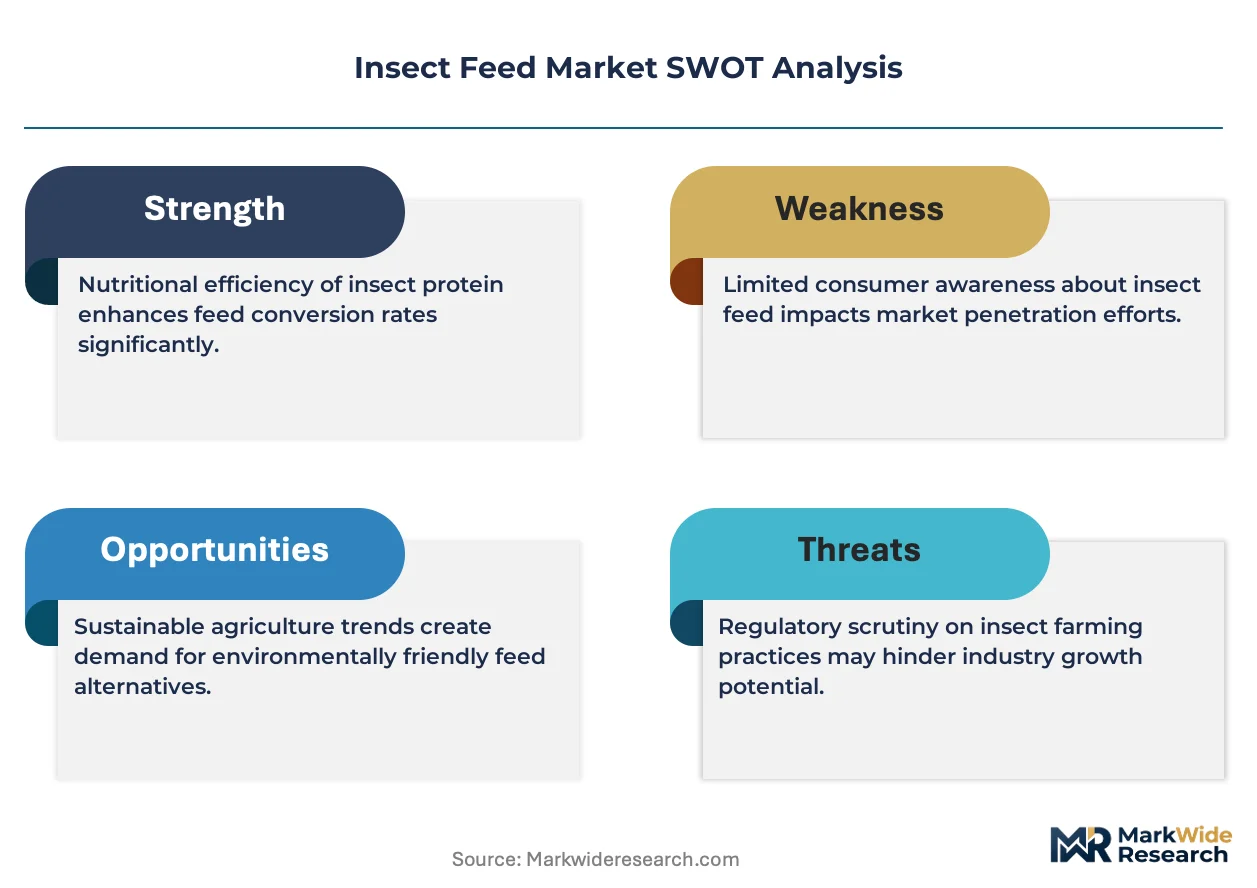
EU 2017/893 regulatory expansion erects a cost-of-compliance moat where EFSA species registration timelines and member-state approval fragmentation favor incumbent capital deployment over rapid entrant scaling.
For Market Incumbents: Extend captive supply relationships with Norwegian salmon producers through dedicated lipid extraction capacity, while securing long-term organic waste substrate contracts ahead of anaerobic digestion facility competition. Entrant pressure from automated rearing technology licensors threatens margin compression in standard-grade meal; backward integration into egg breeding operations preserves quality consistency advantages. For New Entrants and Emerging Players: Launch via direct-to-aquafeed-mill distribution in Germany and Poland where substrate access advantages offset incumbent Dutch logistics proximity. Layer hen nutrition in France represents the most penetrable white-space segment, with post-molt recovery diets and omega-3 enriched egg programs lacking dedicated insect oil suppliers. Position around carbon accounting integration for EU Green Deal farm-to-fork reporting premiums. For Investors and Strategic Acquirers: The window for entry favors vertically integrated operators with EFSA-registered species portfolios and existing aquaculture offtake relationships. Acquisition targets should demonstrate captive substrate supply and automated climate control deployment. Watch for EFSA delegated acts expanding poultry inclusion rate ceilings as the inflection signal for poultry feed volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Direct contracting with Norwegian salmon producers displaces spot-market purchasing and locks volume commitments. |
| Backward Integration | In-house egg breeding and substrate processing secures quality consistency against protein profile variability risks. |
| Capacity Expansion | Automated vertical farming deployment in France and Germany compresses larval development cycles to 14 days. |
| Green Certification Program | Verified Scope 3 emissions reductions unlock EU Green Deal premium pricing tiers for feed ingredient sales. |
| Regulatory Approval Pathway | EFSA species registration and EU member-state harmonization accelerates market access for novel feed materials. |
Research Approach
Document review covered EFSA safety opinions, EU Commission delegated acts, and national feed safety authority filings, complemented by interviews with aquafeed formulation directors, poultry compounder procurement leads, and industrial insect farm operations managers. Secondary validation drew from customs trade data, Norwegian Food Safety Authority aquaculture feed registrations, and German Federal Office of Consumer Protection species approval timelines. Bottom-up facility capacity estimates and top-down feed inclusion rate projections were triangulated against direct sourcing relationship disclosures.
Output modeling produced volume and value trajectories across the projection horizon, with segmentation by larvae species, meal versus oil product form, aquaculture versus poultry versus pet food application, and direct sales versus wholesale distribution channel. CAGRs were derived from facility commissioning announcements, substrate supply contract durations, and regulatory approval pathway acceleration assumptions. Forecast inputs incorporated fishmeal price volatility indices and EU Green Deal carbon accounting implementation schedules.
Peruvian anchovy quota revisions, organic waste substrate competition from anaerobic digestion subsidies, and multi-jurisdiction species registration delays are the dominant revision risks for trajectory assumptions. Forecasts reflect documented regulatory timelines and disclosed offtake agreement structures. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Agricultural Adjuvants Market
Agricultural Biologicals
United States Animal Feed Additives Market
Agricultural Biologicals
North America Animal Feed Additives Market
Agricultural Biologicals
South America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Acetoin Natural Market
Agricultural Biologicals
Agricultural Biofungicides Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
Humic-Based Biostimulants Market
Agricultural Biologicals
Agricultural Activator Adjuvants Market
Agricultural Biologicals
North America Silage Inoculant Market
Agricultural Biologicals
Edible Fungus Market
Agricultural Biologicals
Latin America Animal Feed Additives Market
Agricultural Biologicals
Global Agri Natural Enemy Pest Control Market
Agricultural Biologicals
Animal Feed Additives Market
Agricultural Biologicals
North America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Baobab Market