
 Paraguay Grains Market | 2026-2036
Paraguay Grains Market Size, Share, and Industry Trends Forecast 2026-2036
Paraguay Grains Market Insights
Paraguayan soybean producers is repositioning export volumes toward higher-margin crushing rather than raw bean shipments. Cargill Paraguay S.R.L. leverages its Puerto Caacupé crushing complex to anchor value-added oil and meal output. Bunge Paraguay S.A. competes through backward integration into farmer financing and seed distribution networks. Louis Dreyfus Company Paraguay S.A. dominates the river logistics corridor connecting eastern farms to Argentine export terminals.
Paraguay grains comprise oilseeds, cereals, and pulses cultivated across subtropical and temperate agro-ecological zones, with soybeans typically achieving protein contents of 37-39% and corn averaging 14-15% moisture at harvest. The primary commercial purpose centers on supplying international protein meal demand, domestic food security, and regional livestock feed rations. Soybeans leads product type revenue due to crushing scale and export tax differentials versus Argentine and Brazilian origins. Animal feed end users represents the fastest-growing demand pool as Brazilian integrators source Paraguayan corn and soybean meal to bypass domestic price volatility. Premium and non-GMO quality grades capture concentrated margin pools as European and Japanese buyers enforce strict origin verification protocols.
Paraguay's national grain quality regulator, SENAVE, enforces phytosanitary certificates and GMO traceability standards that determine market access eligibility for European and Asian buyers. The country's adherence to Mercosur technical standards and bilateral SPS agreements with the EU and China conditions export corridor viability. Stakeholders must monitor evolving EU deforestation-free supply chain regulations and their impact on Paraguayan farm-level traceability investments.
Market Dynamics
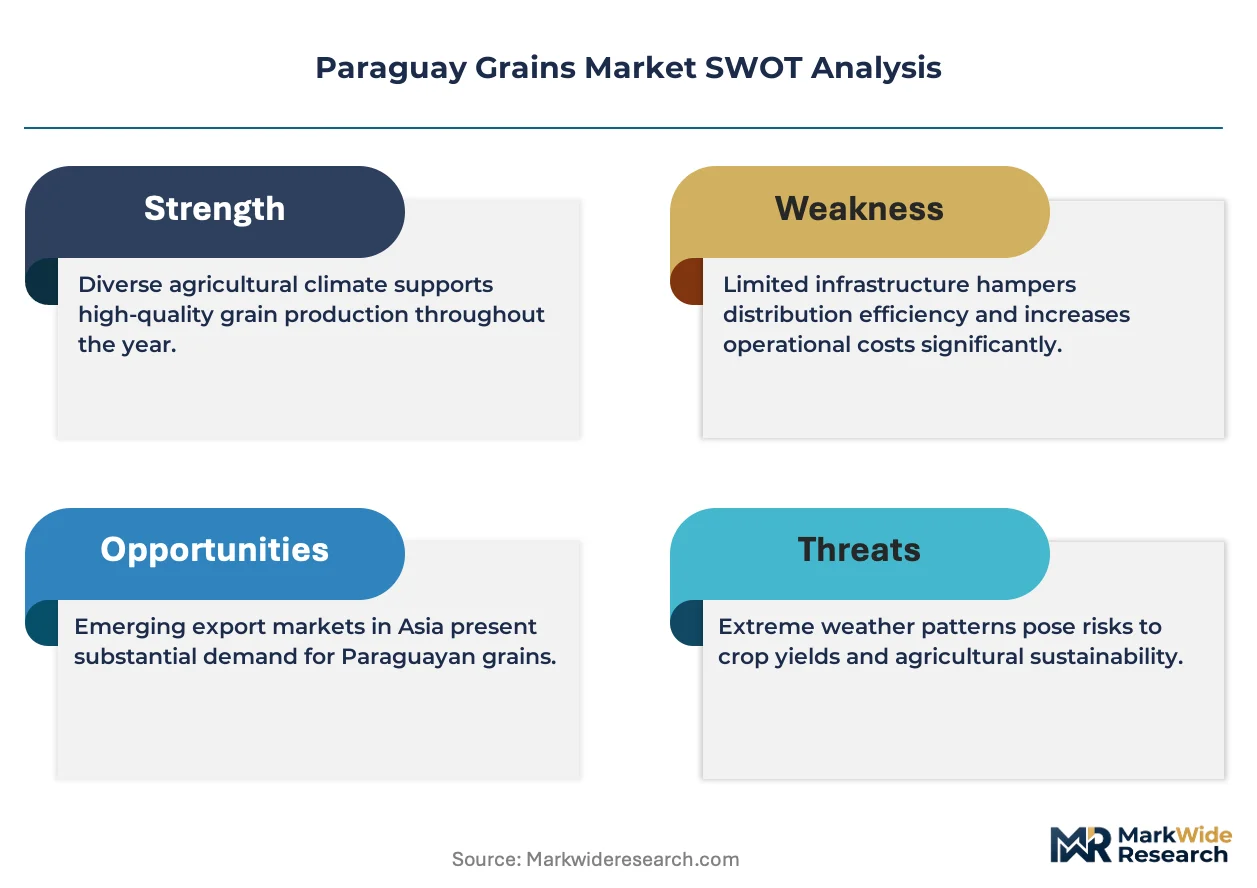
Paraguayan grain flows are pivoting from raw commodity exports toward value-added crushing as Brazilian and Argentine buyers demand processed meal and oil rather than whole beans, tightening logistics requirements around Alto Paraná's river terminals.
Growth Catalysts
- EU Deforestation-Free Regulation:SENAVE's traceability protocols align with Brussels' supply chain mandates, unlocking premium non-GMO access for European feed compounders.
- Brazilian Integrator Demand:Poultry and swine producers in Mato Grosso do Sul source Paraguayan corn and soybean meal to arbitrage domestic price spikes.
- No-Till Technology Spread:Precision planting systems reduce soil erosion and input costs across eastern departments, expanding cultivable acreage.
Market Restraints
- River Logistics Bottlenecks:Low water levels on the Paraguay-Paraná waterway strand barges, forcing costlier truck hauls to Argentine ports.
- Seed Input Concentration:Proprietary genetics from multinational suppliers dominate planting stock, limiting farmer bargaining power.
- Argentine Export Tax Arbitrage:Buenos Aires' variable levy structures periodically invert Paraguay's price advantage in regional markets.
Strategic Opportunities
- Japanese Food-Grade Soy:Identity-preserved non-GMO shipments to Yokohama crushers command quality premiums above commodity benchmarks.
- Domestic Biofuel Mandate:Paraguay's biodiesel blending requirements create captive demand for soybean oil currently exported.
- Digital Grain Receipts:Blockchain-based warehouse certificates could reduce financing costs and collateral risk for smallholder producers.
Industry Challenges
- Certification Timeline Compression:SENAVE's phytosanitary approval windows lag harvest peaks, causing demurrage at river elevators.
- Crushing Capacity Mismatch:Existing plants run below optimal scale during low-yield seasons, straining unit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paraguay Grains Market |
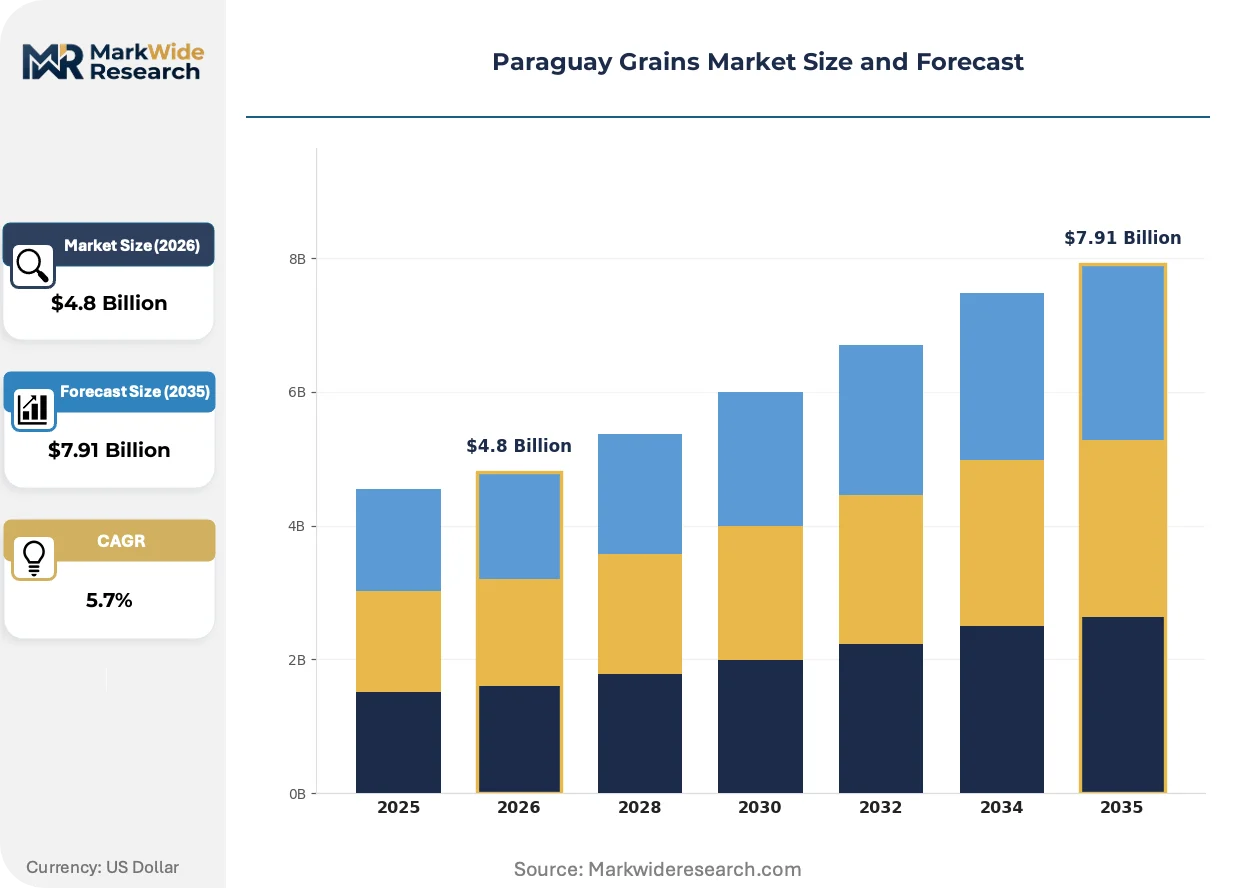
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soybeans, Corn, Wheat, Rice End User: Food Processing, Animal Feed, Export, Retail Distribution Channel: Direct Sales, Wholesale, Online, Cooperative Quality Grade: Premium, Standard, Organic, Non-GMO |
| Companies Covered | Cargill Paraguay S.R.L., ADM Paraguay S.R.L., Bunge Paraguay S.A., Louis Dreyfus Company Paraguay S.A., Copagra S.A., ContiParaguay S.A., Agroganadera Itapúa S.A., Agrofértil S.A., Cooperativa Colonias Unidas Agropecuaria e Industrial, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paraguay Grains Market Trends and Innovations
Digital traceability and precision agriculture are converging to transform how Paraguayan grains qualify for premium export tiers, while regulatory pressure from Brussels and Tokyo tightens origin verification standards.
Variable-rate seeding and prescription fertilizer application is rewriting productivity benchmarks across the Alto Paraná and Itapúa departments. Medium-scale cooperatives are adopting these platforms fastest, consolidating 200-hectare blocks into precision-managed units. The technology is compressing yield variance between early adopters and traditional broadcast methods, widening the gap in loan access and insurance pricing.
SENAVE's implementation of EU-aligned deforestation-free supply chain documentation is reshaping farm-level record-keeping requirements. The regulator now mandates GPS polygon mapping of cultivation areas for export eligibility. Smallholders in Caaguazú and San Pedro face the steepest compliance burden, driving consolidation toward larger managed estates with dedicated administrative staff.
Japanese trading houses are bypassing traditional Argentine brokers to contract directly with Paraguayan crushing cooperatives, shortening the supply chain by one intermediation layer. This disintermediation concentrates volume risk on origin processors but secures preferred delivery slots at Yokohama and Kobe. The pattern is most pronounced in non-GMO soybean meal contracts for aquaculture feed.
Paraguay Grains Market Segmentation
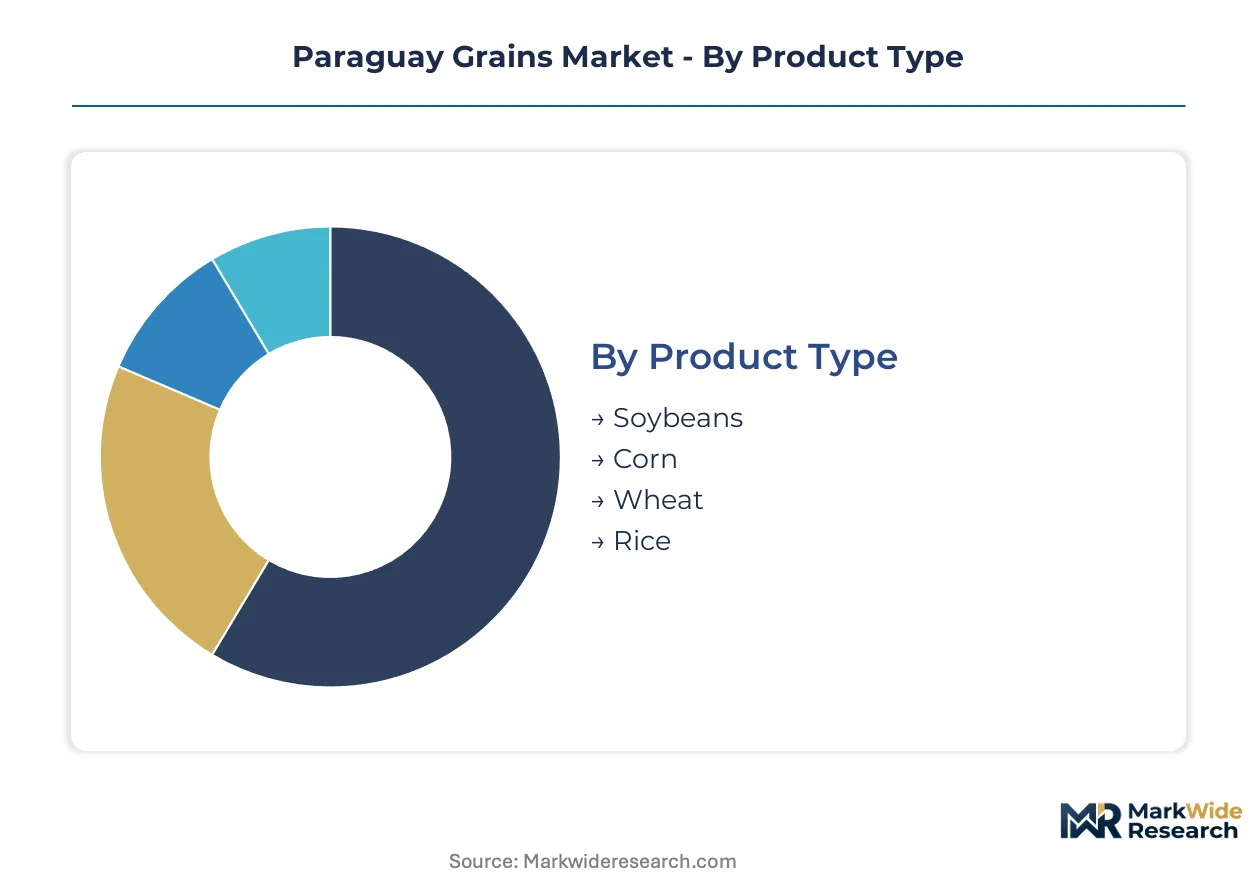
Paraguay's grain market segmentation reflects the country's dual role as a regional crushing hub and premium non-GMO supplier. Distinct buyer requirements across product types, quality grades, and distribution channels determine access to European, Japanese, and Brazilian markets.
Product Type:
Protein content and oil yield specifications differentiate commercial viability across Paraguay's four core grain categories.
- Soybeans:Protein contents of 37-39% position Paraguayan beans above Argentine benchmarks for crushing efficiency. Demand concentrates in Alto Paraná crushing complexes supplying Brazilian poultry integrators in Mato Grosso do Sul, driven by tax differentials versus domestic Brazilian origin.
- Corn:Harvest moisture of 14-15% reduces drying costs and preserves test weight for export. Animal feed compounders in southern Brazil source Paraguayan corn during domestic price spikes, leveraging river logistics through the Paraguay-Paraná waterway.
- Wheat:Limited cultivation in eastern departments serves domestic milling requirements for bread and pasta production.
- Rice:Subtropical varieties in the Alto Paraná and Itapúa departments supply domestic food security needs with minimal export orientation.
Mature deployment sits with soybeans. Newer deployment is concentrated in corn as Brazilian integrators deepen cross-border procurement.
End User:
Customer sophistication and certification requirements fragment Paraguay's grain demand into four distinct commercial channels.
- Animal Feed:Brazilian swine and poultry producers in Mato Grosso do Sul and Paraná states source Paraguayan soybean meal and corn to arbitrage domestic price volatility. SENAVE's phytosanitary certificates align with Mercosur standards for seamless cross-border movement.
- Export:Japanese trading houses contract directly with Paraguayan crushing cooperatives for identity-preserved non-GMO soybean meal, bypassing traditional Argentine intermediaries to secure preferred delivery slots at Yokohama and Kobe.
- Food Processing:Domestic millers in Asunción and Ciudad del Este process wheat and rice for local consumption.
- Retail:Packaged grains for household consumption move through supermarket chains and municipal markets.
Volume concentration sits with export channels. Margin expansion is concentrated in animal feed as Brazilian integrators accept premium pricing for supply security.
Distribution Channel:
Logistics infrastructure and buyer scale determine channel selection across Paraguay's fragmented farm structure.
- Direct Sales:Large crushing complexes operated by multinational agribusinesses contract directly with 500+ hectare farms for identity-preserved shipments, reducing intermediation costs and enabling real-time quality verification.
- Cooperative:Medium-scale producers in Caaguazú and San Pedro consolidate through regional cooperatives to access river terminals and shared storage infrastructure, spreading fixed costs across member volumes.
- Wholesale:Independent traders aggregate smallholder production for bulk export through Argentine port terminals.
- Online:Emerging digital platforms connect farmers with domestic processors for spot market transactions.
Established infrastructure sits with cooperative channels. Digital adoption is expanding most quickly in direct sales as large farms deploy blockchain-based warehouse receipts.
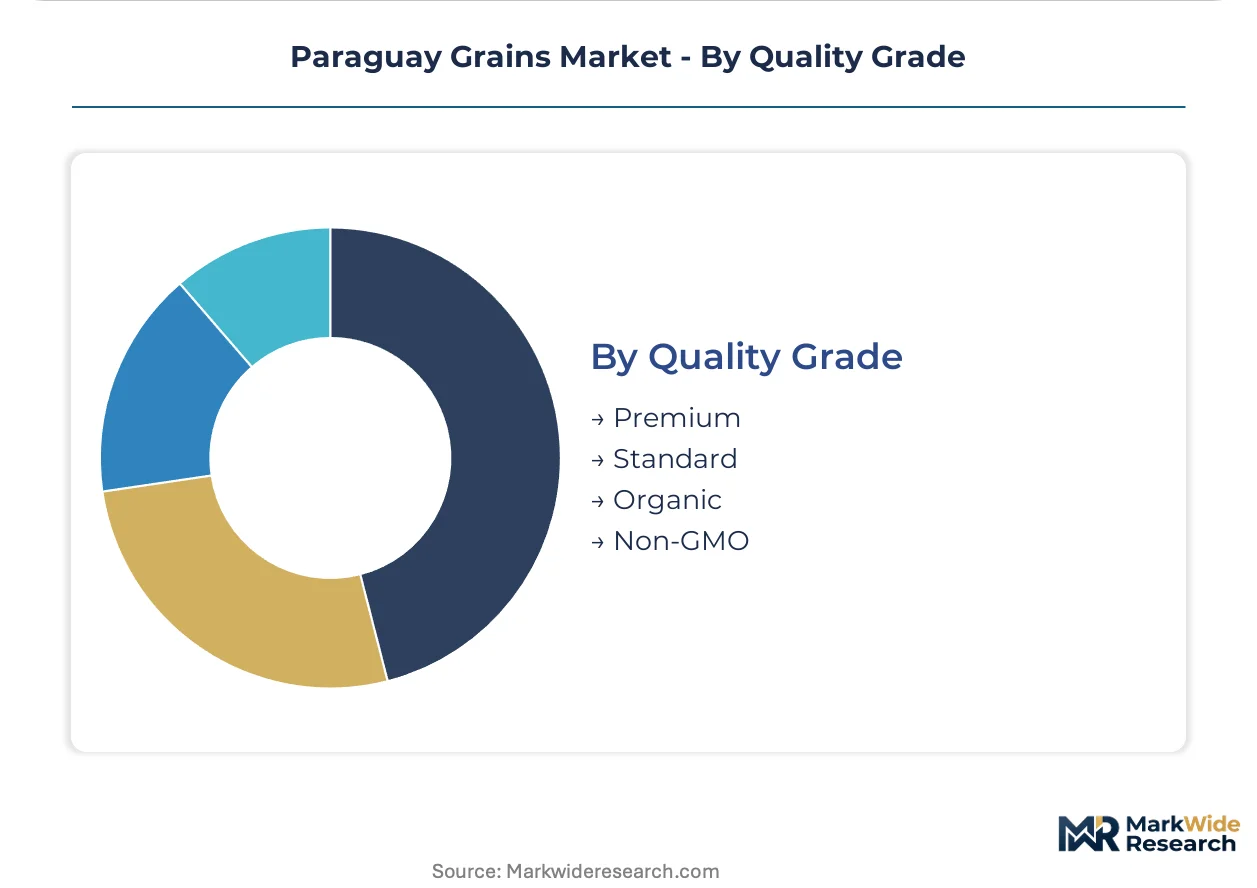
Quality Grade:
Certification tiers determine market access eligibility and price realization across export destinations.
- Non-GMO:Identity-preserved production with GPS polygon mapping satisfies EU deforestation-free regulations and Japanese food-grade protocols. European feed compounders pay premiums above commodity benchmarks for verified origin documentation.
- Premium:Elevated protein specifications and moisture controls target specialized crushers in Yokohama and Kobe for aquaculture feed applications.
- Standard:Commodity grades serve Mercosur regional trade and domestic processing without certification premiums.
- Organic:Limited acreage under conversion targets niche European health food markets with stringent input restrictions.
Certification maturity sits with standard grades. Regulatory-driven expansion is climbing the fastest in non-GMO as SENAVE mandates GPS traceability for export eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Alto Paraná department anchors Paraguay's grain production, where subtropical soils and riverine logistics concentrate soybean and corn cultivation. Eastern departments leverage the Paraguay-Paraná waterway for cost-competitive export access to Brazilian and Argentine buyers.
Alto Paraná
Crushing complexes along the Paraná River process soybeans into meal and oil for Brazilian poultry integrators in Mato Grosso do Sul. SENAVE's phytosanitary certification protocols align with Mercosur standards for seamless cross-border movement. Ciudad del Este hosts the densest clustering of river terminals and grain elevators, with capacity expansions targeting Brazilian feed demand.
Itapúa
Medium-scale cooperatives in Itapúa adopt precision agriculture platforms fastest, consolidating 200-hectare blocks into technology-managed units. The department's adherence to SENAVE's GPS polygon mapping requirements enables non-GMO export eligibility for European compounders. Encarnación serves as the primary collection point for identity-preserved shipments to Japanese crushers.
Caaguazú
Smallholder consolidation accelerates in Caaguazú as compliance burdens from EU deforestation-free regulations drive administrative scale requirements. The national grain quality regulator's traceability mandates reshape farm-level record-keeping, favoring larger managed estates. Coronel Oviedo functions as the administrative hub for cooperative aggregation and shared storage infrastructure.
San Pedro
Traditional broadcast methods persist in San Pedro, widening yield variance gaps with precision-adopting departments and compressing loan access for smallholders. SENAVE's certification timeline compression causes demurrage at river elevators during harvest peaks. The department's limited crushing infrastructure forces reliance on truck hauls to Alto Paraná processing facilities.
Truck-dependent logistics in San Pedro strain unit economics when low water levels on the Paraguay-Paraná waterway divert barge traffic. The department's producers face steepest compliance costs for GPS mapping and origin verification protocols. Regional cooperatives invest in digital grain receipt platforms to reduce financing costs for member producers.
Paraguay Grains Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital traceability and cooperative consolidation to capture premium non-GMO margins. The market structures around three archetypes: multinational crushing complexes with backward integration into farmer financing, domestic cooperatives aggregating medium-scale volumes, and river logistics specialists controlling terminal access. Capacity expansion and strategic partnerships dominate competitive moves, with players securing preferred delivery slots at Brazilian and Japanese destinations.
Among multinational operators, Cargill Paraguay S.R.L., Bunge Paraguay S.A., and Louis Dreyfus Company Paraguay S.A. exemplify the integrated crushing-and-logistics archetype, leveraging river terminal control to anchor value-added output. These entities represent the scale-driven tier where processing capacity and export corridor access determine competitive position. Domestic cooperatives such as Cooperativa Colonias Unidas Agropecuaria e Industrial occupy the aggregation tier, consolidating member volumes to meet minimum efficient scale for premium certification programs.
| Leading Market Players |
|---|
| Cargill Paraguay S.R.L. |
| ADM Paraguay S.R.L. |
| Bunge Paraguay S.A. |
| Louis Dreyfus Company Paraguay S.A. |
| Copagra S.A. |
| ContiParaguay S.A. |
| Agroganadera Itapúa S.A. |
| Agrofértil S.A. |
| Cooperativa Colonias Unidas Agropecuaria e Industrial |
| Others |
Pricing and Supply Chain Analysis
EU deforestation-free regulations gate both qualified supply and premium-tier pricing access, forcing Paraguayan producers to absorb GPS mapping and certification costs to maintain European market eligibility while Brazilian integrators arbitrage regional price differentials for standard grades.
Pricing Analysis
Certification-bundled pricing separates traceable non-GMO shipments from commodity grades, with SENAVE-compliant GPS polygon documentation commanding premiums from European and Japanese buyers while standard Mercosur grades compete on spot market arbitrage against Argentine and Brazilian origins. Price differentiation hinges on quality grade and origin verification level, with identity-preserved lots capturing margin pools above commodity benchmarks. Pricing pressure stems from Argentine export tax volatility that periodically inverts Paraguay's regional advantage. Brazilian poultry integrators in Mato Grosso do Sul exhibit highest price sensitivity due to feed cost exposure, while Japanese trading houses show lowest sensitivity for aquaculture-grade meal contracts.
Supply Chain Analysis
Reverse-logistics flows are minimal in grain markets, though crushing cooperatives in Itapúa and Caaguazú repurpose damaged lots for domestic biodiesel feedstock rather than export channels. Supply concentrates in Paraguay, Brazil, and Argentina as the Southern Cone crushing triangle, with Alto Paraná river terminals serving as the logistics anchor. Raw material dependencies center on proprietary soybean genetics from multinational seed suppliers, phosphate fertilizers imported through Brazilian ports, and diesel for truck hauls during low-water barge seasons. Supply chain risk rests on Paraguay-Paraná waterway level volatility that forces costlier truck diversion to Argentine export terminals. Distribution runs through river terminal aggregation, multinational crushing complexes, and cooperative consolidation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paraguay's grains sector is consolidating as EU regulatory compliance costs force administrative scale requirements that marginalize smallholders without cooperative backing or dedicated estate management.
For Market Incumbents: Acquire river terminal capacity in Alto Paraná to lock in export corridor access before Brazilian integrators deepen backward integration into Paraguayan crushing. Cargill and Bunge should expand farmer financing networks in Caaguazú and San Pedro to secure volume commitments against emerging cooperative competitors. SENAVE's tightening certification timelines threaten margin compression for operators without dedicated compliance staff.
For New Entrants and Emerging Players: Blockchain-based warehouse receipt platforms offer a technology-first wedge to reduce collateral costs for smallholder producers excluded from traditional trade finance. Target San Pedro's underserved cooperative aggregation layer where digital adoption lags and financing spreads remain wide. Partner with regional crushing cooperatives rather than competing against multinational terminal control.
For Investors and Strategic Acquirers: Japanese trading house direct contracting with Paraguayan cooperatives is the leading indicator that premium non-GMO supply chains are shortening and origin-processor margins are stabilizing. The five-to-ten year viability window favors mid-scale cooperatives with established SENAVE compliance infrastructure and GPS-mapped member estates. Monitor SENAVE certification approval velocity during harvest peaks as an early signal of operational bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farmer Financing | Bunge's seed distribution networks lock in planting decisions and volume commitments before harvest. |
| River Terminal Capacity Expansion | Louis Dreyfus controls Paraguay-Paraná logistics corridors connecting eastern farms to Argentine ports. |
| Digital Grain Receipt Platform Launch | Blockchain certificates reduce collateral risk for Caaguazú cooperatives excluded from traditional banking. |
| Non-GMO Certification Investment | SENAVE's GPS polygon mandates enable European compounder access under deforestation-free regulations. |
| Direct Japanese Trading House Contracts | Yokohama and Kobe delivery slots bypass Argentine intermediary margins for aquaculture meal. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with crushing complex operations managers, cooperative board members, SENAVE compliance officers, and Brazilian poultry integrator procurement leads. Secondary sources included Mercosur technical standard documents, EU deforestation-free regulation implementation guidance, Paraguayan customs export statistics, and bilateral SPS agreement texts. Bottom-up volume estimates from departmental production surveys were triangulated against top-down export corridor throughput data.
Data-stream reconciliation across multiple grain flow tracking sources informed the analytical framework. Segmentation dimensions modeled include product type, quality grade certification tier, end-user channel, and distribution channel structure across the projection horizon. CAGRs were derived from trend extrapolation of crushing capacity utilization, export corridor expansion timelines, and regulatory compliance adoption curves. Forecast inputs incorporated SENAVE certification velocity assumptions and Brazilian integrator cross-border procurement intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended Paraguay-Paraná drought conditions or abrupt Argentine export tax regime shifts. Practitioners should monitor SENAVE approval backlog metrics during February-March harvest peaks and Brazilian domestic corn price spikes for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Masa Corn Products Market
Grains
Africa Wheat Flour Market
Grains
Europe Rice Market
Grains
Colombia Grains Market
Grains
Green Pea Grits Market
Grains
Oat Bran Market
Grains
United States Maize Market
Grains
South American Maize Market
Grains
Wild Rice Market
Grains
Wheat Bran Market
Grains
Cultured Wheat Market
Grains
United States Gluten-Free Oats Market
Grains
Organic Oats Market
Grains
White Beans Market
Grains
Africa Wheat Protein Market
Grains
Europe Maize Market